
 Sodium Hydroxide Market | 2026-2036
Sodium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hydroxide Market Analysis
ISO 9001:2015 quality management certification is reorganizing supplier eligibility for industrial chemical procurement contracts across European and Asian markets. Olin Corporation leverages integrated chlor-alkali production to sustain feedstock cost advantages in North American distribution. Tata Chemicals anchors its position through captive salt reserves and coastal manufacturing scale in Gujarat. INEOS Group Limited competes via specialized membrane cell technology and pipeline-connected logistics across northwest Europe.
Sodium hydroxide, commonly designated caustic soda, constitutes an inorganic base with the chemical formula NaOH and typical commercial concentrations ranging from 50% liquid solution to 98% solid forms; manufacturers produce it primarily through chlor-alkali electrolysis of brine, yielding chlorine gas as a critical co-product for PVC and water treatment supply chains. The liquid product type dominates volume flows due to lower handling costs and direct pipeline delivery to pulp mills and petroleum refineries, while pharmaceutical grade commands premium pricing driven by USP and EP purity mandates. End use industry segmentation reveals pulp and paper as the mature demand anchor, whereas pharmaceutical applications generate disproportionate margin contribution per ton sold.
EPA effluent limitation guidelines and REACH chemical registration requirements in the United States and European Union respectively constrain mercury and asbestos diaphragm cell operations, accelerating capital redeployment toward membrane and ion-exchange technologies. China's MEE enforces stricter chlor-alkali energy intensity standards that reshape capacity licensing in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between membrane cell incentives and carbon border adjustment mechanisms to calibrate technology investment timelines and geographic sourcing strategies.
Market Dynamics
Membrane cell technology upgrades are compressing legacy mercury and diaphragm capacity as regulators enforce stricter effluent standards, forcing producers to redeploy capital toward energy-efficient electrolysis or exit concentrated supply regions entirely.
Growth Catalysts
- Pulp and paper bleaching expansion:Rising demand for high-purity cellulose in packaging and specialty grades drives volume requirements for 50% liquid caustic soda delivered via direct pipeline to integrated mills.
- REACH chemical registration:Stricter substance evaluation protocols in the European Union accelerate phase-out of asbestos diaphragm operations, creating replacement demand for membrane cell output certified to higher purity tiers.
- Chlor-alkali co-product economics:PVC and water treatment supply chains absorb chlorine gas output from integrated facilities, improving overall plant economics and sustaining capacity utilization across coastal manufacturing clusters in China and India.
Market Restraints
- Energy cost volatility:Electrolysis operations remain exposed to electricity price swings, particularly in jurisdictions with carbon border adjustment mechanisms affecting German and Chinese producers.
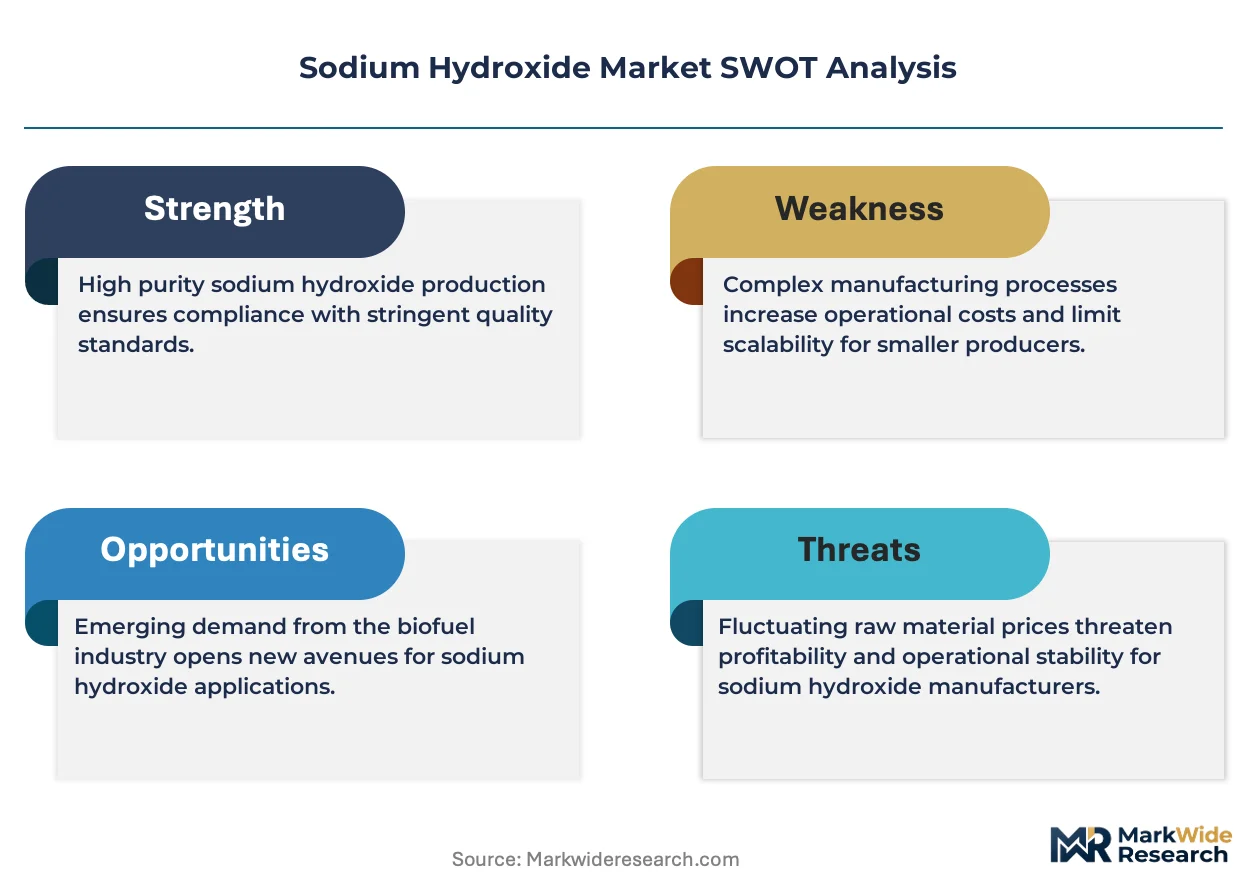
- Supply concentration risk:Membrane cell technology licensing concentrates among specialized equipment providers, limiting technology access for mid-scale operators in emerging manufacturing regions.
- Caustic potash substitution:Potassium hydroxide competes in pharmaceutical and food-grade applications where potassium ion presence is functionally preferred over sodium.
Strategic Opportunities
- Pharmaceutical grade premiumization:USP and EP certification mandates create pricing stratification opportunities for producers capable of meeting heavy metal and impurity specifications below 10 ppm thresholds.
- Wastewater treatment regulatory tailwinds:EPA effluent limitation guidelines and China's MEE energy intensity standards force industrial users toward higher-purity caustic for pH adjustment and heavy metal precipitation.
- Digital distribution platforms:Bulk chemical procurement marketplaces are emerging as alternative channels for spot volume transactions, particularly for mid-sized paper mills and regional refineries.
Industry Challenges
- Membrane cell engineering talent scarcity:Specialized expertise in ion-exchange membrane maintenance and cell room optimization remains concentrated among veteran technicians approaching retirement.
- ISO 9001:2015 certification timelines:Supplier eligibility restructuring for industrial chemical procurement contracts requires 12-18 month quality management system implementations.
- Legacy brine purification integration:Upgrading existing salt dissolution and purification infrastructure to meet membrane cell feedstock specifications demands significant capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hydroxide Market |
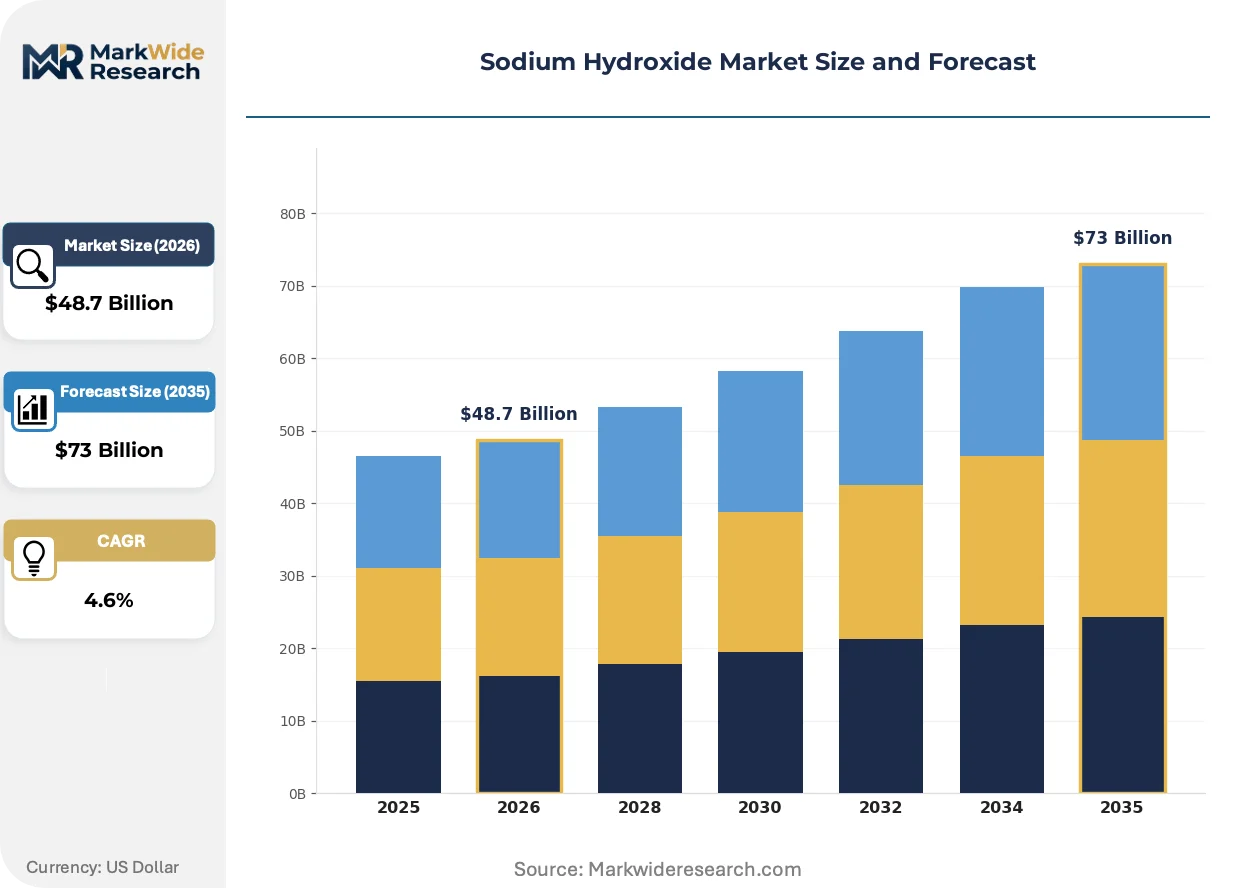
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Liquid, Pellets, Powder End Use Industry: Pulp & Paper, Textiles, Chemicals, Pharmaceuticals Packaging Type: Drums, Bags, Containers, Bulk Grade: Technical, Food, Pharmaceutical, Industrial |
| Companies Covered | Tata Chemicals, Formosa Plastics Corporation, Olin Corporation, INEOS Group Limited, BASF SE, Dow Inc., Occidental Chemical Corporation, Solvay, Westlake Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hydroxide Market Emerging Trajectories
Electrochemical process intensification and digital process control systems are compressing unit production costs while regulatory mandates force technology substitution across legacy installed bases.
Membrane cell technology with nano-structured electrode coatings is bifurcating the installed base between high-efficiency producers achieving sub-2,100 kWh per ton and legacy operators facing stranded asset risk. Pulp and paper conglomerates in Scandinavia and the US Pacific Northwest are prioritizing long-term supply agreements with certified low-carbon intensity suppliers. This technology divide is compressing margins for diaphragm and mercury cell operators unable to fund conversion capex.
EPA effluent limitation guidelines under the Clean Water Act are forcing mercury cell closures in chlor-alkali corridors along the US Gulf Coast. The industrial consequence is regional supply tightness for 50% liquid caustic in Texas and Louisiana petrochemical clusters. Affected segments are responding by extending rail and barge supply radius from membrane cell facilities in Appalachia and the Midwest.
Direct pipeline delivery contracts are displacing traditional tank car procurement for integrated pulp mills and petroleum refineries. This channel shift concentrates volume with producers possessing coastal or riverine logistics infrastructure. The transformation is most visible in China's Shandong and Jiangsu provinces, where state-owned chlor-alkali operators are consolidating regional distribution networks.
Sodium Hydroxide Market Segmentation
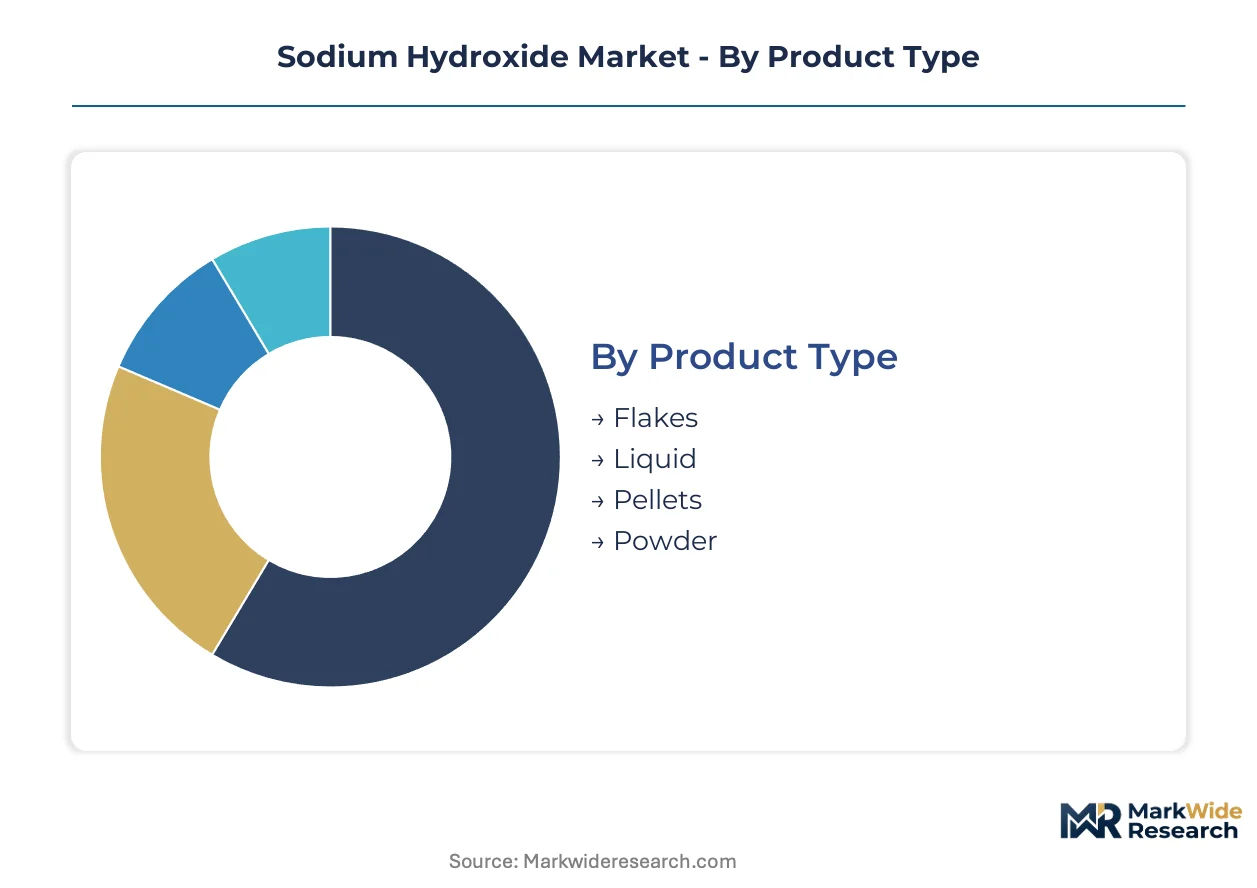
Caustic soda flows through distinct channel configurations shaped by physical form, purity requirements, and delivery scale. Each segment carries specific logistics constraints and margin profiles that determine competitive positioning across regional supply networks.
Product Type:
Liquid dominates pipeline deliveries to integrated mills, while solid forms serve dispersed industrial users through packaged distribution channels.
- Liquid:A 50% aqueous solution delivered via direct pipeline or rail tank car to pulp mills and petroleum refineries. Demand concentrates in China's Shandong province and the US Gulf Coast, where chlor-alkali plants anchor coastal manufacturing clusters and EPA effluent rules force mercury cell conversions.
- Flakes:Solid caustic formed through evaporative crystallization and flaking, typically 98% purity. Applications cluster in small-scale chemical processing and water treatment facilities across Germany's industrial Rhine corridor, driven by REACH registration requirements for higher-purity process chemicals.
- Pellets:Compressed spherical forms optimized for controlled dissolution in batch processes. Pharmaceutical compounders in India prefer this format for precise dosing in active pharmaceutical ingredient synthesis.
- Powder:Finely ground solid requiring moisture-resistant packaging for shelf stability. Textile processors in Gujarat's dyeing clusters utilize powder forms for caustic mercerization of cotton fibers.
Liquid dominates installed base. Flakes and pellets are where expansion concentrates as quality certification requirements proliferate.
End Use Industry:
Cost tier stratification separates commodity volume applications from premium-margin specialty segments.
- Pulp & Paper:The mature demand anchor consuming 50% liquid via direct pipeline for wood chip digestion and bleach chemical regeneration. Integrated mills in Finland and Sweden prioritize long-term supply agreements with low-carbon certified producers.
- Pharmaceuticals:USP and EP grade material commanding premium pricing for active pharmaceutical ingredient synthesis and pH adjustment in sterile manufacturing. Heavy metal specifications below 10 ppm threshold create supply scarcity.
- Chemicals:Intermediate consumption for sodium salts, detergents, and synthetic fiber precursors. German chemical parks along the Rhine maintain pipeline-connected supply from membrane cell facilities.
- Textiles:Caustic mercerization of cotton and synthetic fiber processing. India's Tamil Nadu and Maharashtra textile belts drive regional demand concentration.
Pulp & Paper dominates installed base. Pharmaceuticals is where expansion concentrates.
Packaging Type:
Volume scale and handling automation determine packaging selection across customer tiers.
- Bulk:Tank truck and rail car deliveries for integrated chemical processors and refineries. Coastal chlor-alkali facilities in Jiangsu province leverage riverine logistics for bulk distribution.
- Drums:Standard 200-liter steel or HDPE containers for mid-scale industrial users. REACH compliance documentation accompanies each drum shipment in European markets.
- Bags:Multi-layer laminated sacks for solid forms in textile and small chemical processing. India's BIS certification marks appear on export-grade bagged product.
- Containers:Intermediate bulk containers and totes for pharmaceutical and food-grade applications requiring contamination control.
Bulk dominates installed base. Drums and specialized containers are where expansion concentrates.
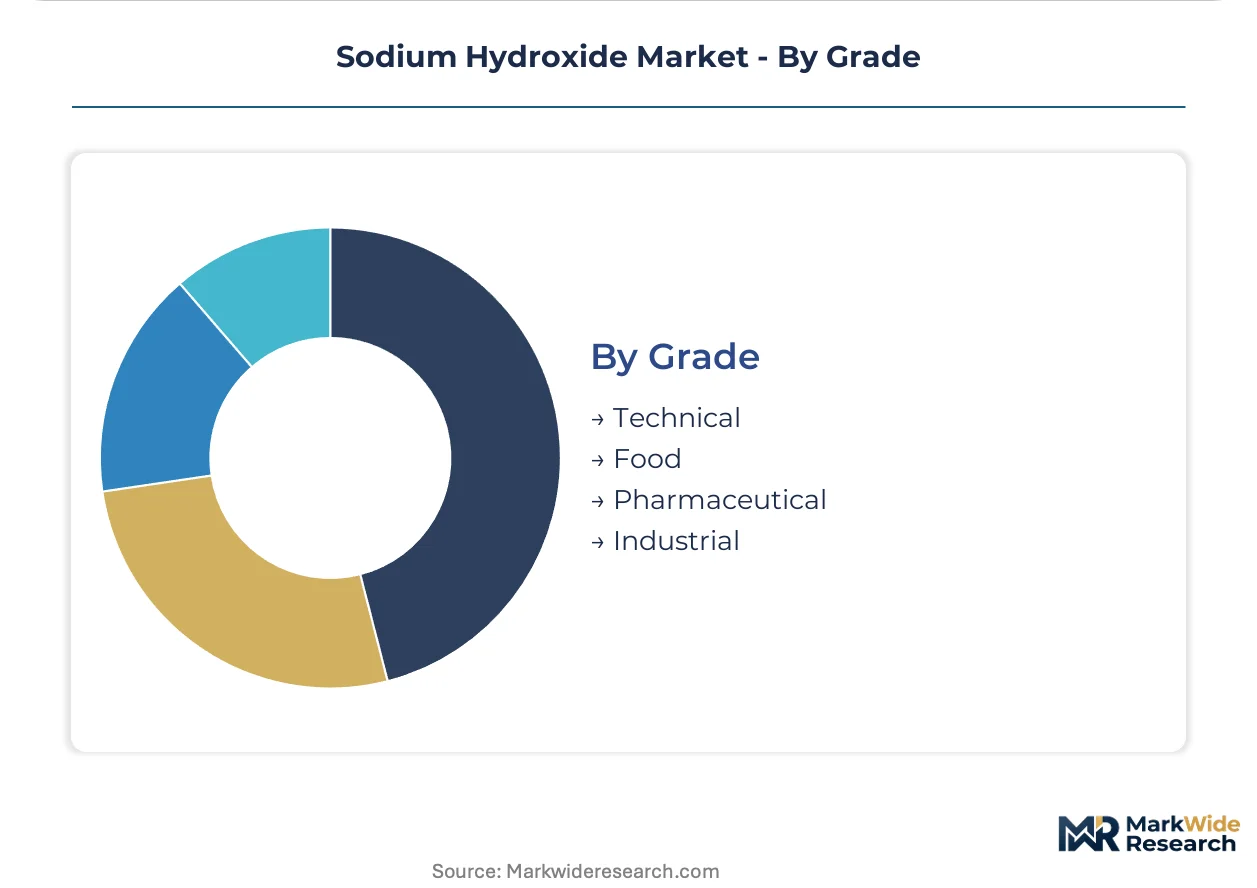
Grade:
Application maturity separates established industrial specifications from emerging certification tiers.
- Industrial:Standard technical grade for pulp processing, petroleum refining, and general chemical synthesis. Membrane cell output increasingly displaces diaphragm production in this category.
- Pharmaceutical:USP and EP compliant material with documented impurity profiles and batch traceability. CDSCO in India and FDA in the United States enforce divergent inspection protocols.
- Food:FCC grade for food processing, peeling, and pH adjustment. FSSAI registration requirements in India create compliance barriers for imported material.
- Technical:Lower-purity specification for wastewater treatment and neutralization applications where heavy metal content is less critical.
Industrial dominates installed base. Pharmaceutical and Food grades are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan port complex anchors Asia-Pacific caustic soda throughput, handling membrane cell output from Jiangsu and Shandong chlor-alkali corridors for re-export to Southeast Asian textile and paper processors.
China
Pulp mill digestion and PVC precursor synthesis absorb volume from membrane cell expansions in Shandong province. MEE energy intensity standards force mercury cell closures in older Jiangsu facilities. Qingdao's coastal chlor-alkali cluster now supplies pipeline-connected refineries across the Bohai Rim.
Germany
Rhine chemical parks demand pharmaceutical-grade flakes for sodium salt synthesis and pH adjustment protocols. REACH substance evaluation accelerates asbestos diaphragm phase-outs at Ludwigshafen and Leverkusen sites. BASF's membrane cell integration at Ludwigshafen anchors northwest European supply.
United States
Gulf Coast petrochemical clusters consume 50% liquid caustic for petroleum refining and ethylene dichloride production. EPA effluent limitation guidelines force mercury cell retirements in Louisiana and Texas. Appalachian membrane cell capacity now rail-supplies Texas refineries facing regional tightness.
India
Gujarat's textile mercerization and pharmaceutical API synthesis drive pellet and flake demand. CDSCO inspection protocols for USP-grade material concentrate supply among Gujarat and Maharashtra producers. Tata Chemicals' Mithapur facility leverages captive salt reserves for coastal manufacturing scale.
Sodium Hydroxide Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and feedstock integration dimensions. The structure concentrates around integrated chlor-alkali operators with captive salt or pipeline logistics, while mid-scale diaphragm cell owners face stranded asset pressure. Three archetypes dominate: membrane cell technology licensors, coastal integrated producers with salt reserves, and regional distributors with rail-tank car fleets. Competitive moves center on M&A consolidation of distressed diaphragm capacity and strategic partnerships for membrane technology access.
Within the integrated coastal producer tier, Tata Chemicals and Olin Corporation exemplify feedstock-anchored positioning, while INEOS Group Limited occupies a position among northwest European membrane cell operators with pipeline-connected logistics infrastructure.
| Leading Market Players |
|---|
| Tata Chemicals |
| Formosa Plastics Corporation |
| Olin Corporation |
| INEOS Group Limited |
| BASF SE |
| Dow Inc. |
| Occidental Chemical Corporation |
| Solvay |
| Westlake Corporation |
| Others |
Supply Flow & Price Mechanics
Thirty-to-forty-five-day inventory cycles at coastal membrane cell facilities in China and Germany compress working capital exposure while amplifying pricing leverage for producers with direct pipeline access to pulp mills and refineries. This tight inventory band concentrates margin capture with integrated operators possessing captive salt reserves and riverine logistics infrastructure.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, industrial, and technical grades separates membrane cell output certified to USP and EP standards from commodity 50% liquid and lower-purity wastewater treatment material. Price differentiation hinges on heavy metal impurity thresholds below 10 ppm and ISO 9001:2015 quality management certification status. Cost compression in industrial-grade spot markets intensifies as Appalachian membrane cell capacity rail-supplies Texas Gulf Coast refineries facing regional tightness from mercury cell closures. Pharmaceutical compounders exhibit lowest price sensitivity due to batch traceability requirements and regulatory audit burdens, while textile mercerization operators in Gujarat demonstrate highest elasticity to delivered cost fluctuations.
Supply Chain Analysis
Just-in-time pipeline delivery dominates procurement preferences for integrated pulp mills and petroleum refineries, while pharmaceutical compounders maintain strategic stockpiles of USP-grade pellets to buffer CDSCO inspection delays. Geographic supply concentration centers on China's Shandong and Jiangsu provinces, Germany's Rhine chemical corridor, and the US Gulf Coast petrochemical cluster. Raw material dependencies draw from captive salt reserves, electricity supply contracts, and specialized ion-exchange membrane inventories. Single-source vulnerability permeates membrane cell technology licensing, where equipment providers constrain access for mid-scale operators. Distribution runs through direct pipeline connections for bulk liquid, rail-tank car networks for regional supply, and drum-container channels for pharmaceutical and food-grade solid forms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium hydroxide demand enters an early-cycle expansion phase as membrane cell technology upgrades and REACH-driven asbestos diaphragm phase-outs create replacement demand for certified higher-purity output across European and Asian manufacturing clusters.
For Market Incumbents: Fortify membrane cell feedstock integration through captive salt reserve acquisitions or long-term brine supply agreements in Gujarat and Shandong provinces. Accelerate ISO 9001:2015 certification timelines to maintain supplier eligibility as European procurement contracts restructure quality management requirements. Prioritize pipeline-connected logistics infrastructure to defend against rail-tank car distributors encroaching on integrated mill supply relationships. For New Entrants and Emerging Players: Digital distribution platform underinvestment by established chlor-alkali operators creates entry space for bulk chemical procurement marketplaces targeting mid-sized paper mills and regional refineries with spot volume transactions. Target pharmaceutical-grade pellet production in India where CDSCO inspection protocols concentrate supply scarcity among Gujarat and Maharashtra producers. Pursue toll-manufacturing arrangements with stranded diaphragm cell owners seeking membrane technology access without capital redeployment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core chlor-alkali assets in northwest Europe and coastal China. Five-to-ten-year viability favors membrane cell operators with pipeline logistics and pharmaceutical-grade certification capabilities over legacy mercury and diaphragm capacity facing regulatory obsolescence. Monitor EPA effluent limitation guideline enforcement timelines and China's MEE energy intensity standard implementation as inflection indicators for stranded asset risk realization.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Technology Licensing | Specialized ion-exchange membrane access determines competitive positioning for mid-scale operators in Shandong province. |
| Backward Integration into Salt Reserves | Captive brine supply anchors feedstock cost advantages for coastal chlor-alkali manufacturing clusters in Gujarat. |
| Pharmaceutical Grade Certification Investment | USP and EP compliance opens premium pricing tiers for heavy metal specifications below 10 ppm thresholds. |
| Long-term Pipeline Supply Agreement | Direct delivery contracts lock in volume with integrated pulp mills and refineries across Scandinavia and the US Pacific Northwest. |
| Digital Distribution Platform Launch | Spot transaction marketplaces penetrate mid-sized paper mill procurement previously served by traditional tank car distributors. |
Methodological Framework
Desk research of customs and trade flow databases, chlor-alkali industry association reports, and regulatory filings with EPA and ECHA preceded structured interviews with plant managers at membrane cell facilities, procurement leads at downstream pulp and petroleum refineries, distribution channel partners, and technical R&D directors specializing in electrochemical process intensification. Primary fieldwork combined with secondary validation from SEC 10-K disclosures and energy intensity filings with China's MEE enabled bottom-up capacity modeling and top-down demand triangulation across end-use segments.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub shaped the analytical framework over the projection horizon. CAGRs derived from electrolysis capacity expansion schedules, pulp mill digestion demand curves, and PVC precursor synthesis growth trajectories. Model inputs incorporated membrane cell technology adoption rates, mercury cell closure timelines under EPA effluent guidelines, and pharmaceutical-grade certification penetration patterns.
Underlying assumptions cover regulatory enforcement consistency for mercury cell phase-outs, electricity price stability in carbon border adjustment jurisdictions, and membrane technology licensing availability, with deviation risk concentrated in energy cost volatility and single-source equipment provider constraints. Revision becomes warranted when EPA or MEE enforcement intensity crosses thresholds accelerating stranded asset recognition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
Barium Nitrate Market