
 United States Calcium Carbonate Market | 2026-2036
United States Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Calcium Carbonate Market Analytics
EPA particulate matter regulations under the Clean Air Act is pivoting calcium carbonate buyers toward micronized and coated grades that reduce dust generation during handling. Imerys leverages vertically integrated quarry-to-distribution networks across the Southeast to sustain supply security for paper and plastics customers. Minerals Technologies Inc. anchors its position through precipitated calcium carbonate technology leadership, while Omya AG competes via specialized coating capabilities for high-performance polymer applications.
Calcium carbonate is a naturally occurring mineral with the chemical formula CaCO3, typically processed to purity levels between 95% and 99.9% depending on end-use requirements, and functions primarily as a functional filler, processing aid, and cost-reducing extender across industrial formulations. Ground calcium carbonate occupies the largest volume share due to its lower energy intensity and broad availability from domestic limestone deposits, though precipitated calcium carbonate commands premium positioning in plastics and food-grade applications where particle size distribution and surface area specifications are stringent. The filler application segment dominates value capture given its integration into polypropylene and PVC compounding for automotive interior and construction profiles, while pH regulator demand in water treatment and food processing represents a concentrated margin pool with specialized certification requirements.
FDA food additive regulations under 21 CFR 184.1409, EPA National Ambient Air Quality Standards for PM2.5, and OSHA permissible exposure limits for respirable crystalline silica collectively shape product specifications, facility permitting, and worker protection protocols across the value chain. State-level environmental review processes in Pennsylvania, Ohio, and Kentucky further constrain greenfield quarry development, tightening long-term supply availability for high-volume industrial grades. Stakeholders must monitor evolving EPA coal ash regulations and emerging state carbon accounting mandates that could redirect calcium carbonate sourcing toward synthetic and recovered CO2-based production pathways.
Market Dynamics
EPA industrial emissions standards and OSHA silica exposure limits are compressing permissible operating envelopes for calcium carbonate producers, forcing capital deployment toward dust suppression systems and micronized processing lines that reduce respirable particulate generation.
Growth Catalysts
- Automotive lightweighting mandates:CAFE standards are accelerating precipitated calcium carbonate purchases for polypropylene interior components that reduce vehicle curb weight.
- Water infrastructure reinvestment:The Bipartisan Infrastructure Law is channeling federal funds toward municipal pH regulation systems that consume high-purity calcium carbonate for drinking water treatment.
- Plastics compounding cluster expansion:Gulf Coast petrochemical corridor investments are creating captive demand for surface-coated filler grades tailored to extrusion-grade polymer specifications.
Market Restraints
- Limestone quarry permitting delays:State environmental review processes in Pennsylvania, Ohio, and Kentucky are extending greenfield development timelines to 7-10 years.
- Natural gas price volatility:Precipitated calcium carbonate production depends on calcination energy inputs that fluctuate with Henry Hub pricing.
- Ground calcium carbonate purity ceilings:Mined material cannot achieve the sub-micron particle size distribution required for optical brightening applications.
Strategic Opportunities
- Carbon capture utilization pathways:Synthetic calcium carbonate production from industrial CO2 streams qualifies for Section 45Q tax credits under the Inflation Reduction Act.
- Food-grade certification expansion:FDA 21 CFR 184.1409 compliance investments open margin-rich pharmaceutical and nutraceutical excipient markets.
- Ohio River Valley logistics integration:Barge-accessible processing facilities can serve Midwest paper mills with 40% lower freight costs than rail-dependent competitors.
Industry Challenges
- Process control engineering shortage:Precipitated calcium carbonate operations require specialized talent in particle engineering and surface chemistry that domestic universities underproduce.
- Multi-jurisdictional air quality compliance:Facilities spanning state lines must reconcile divergent Pennsylvania DEP, Ohio EPA, and Kentucky DNR permitting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Calcium Carbonate Market |
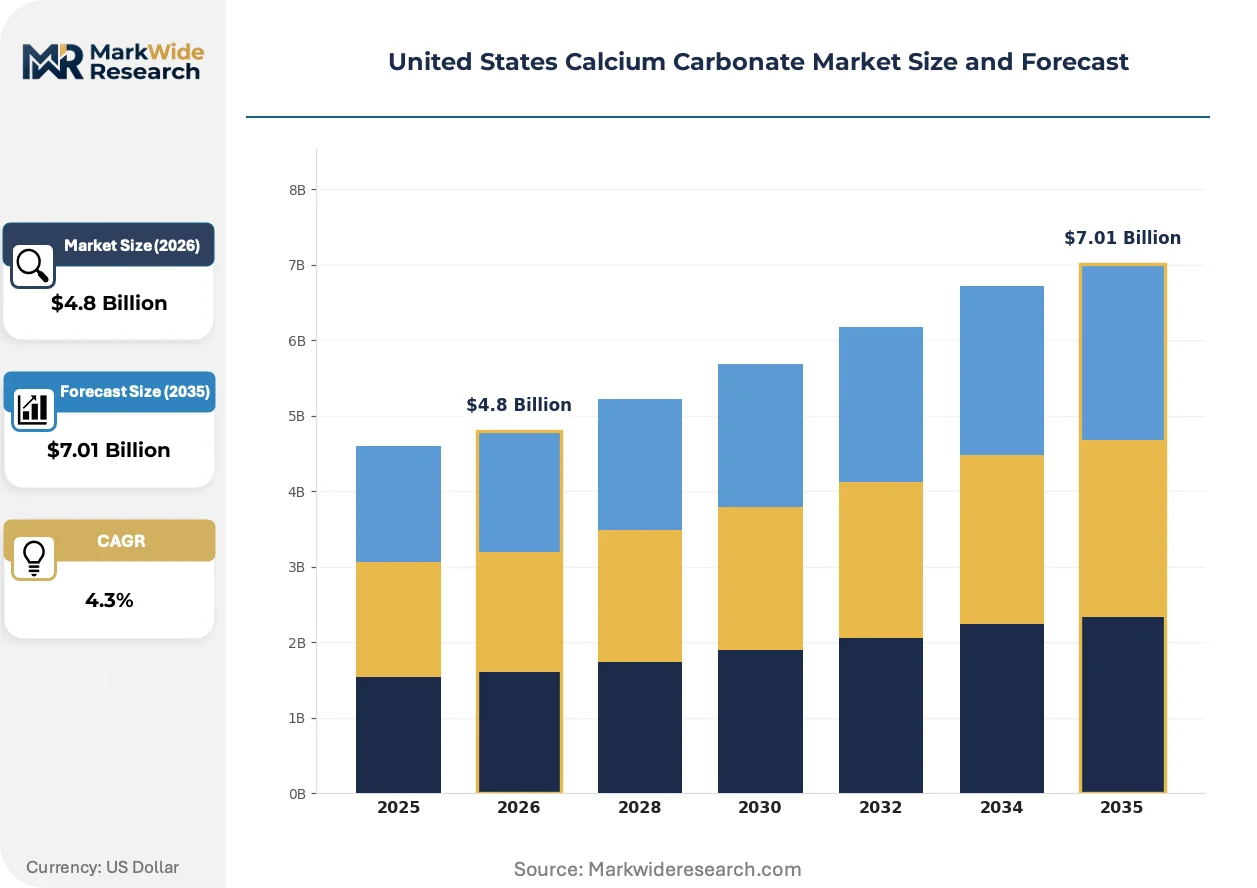
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.01 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
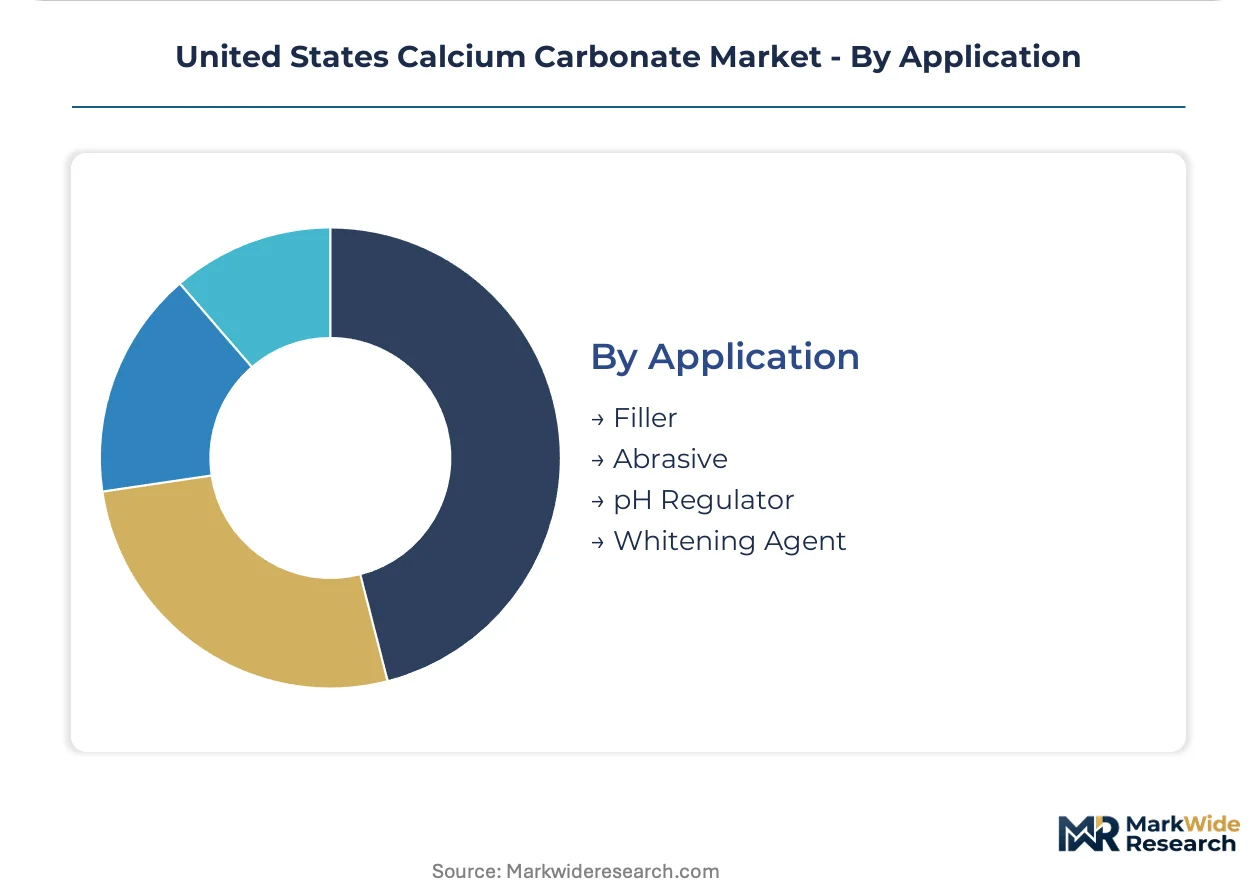
| Segmentation | Product Type: Ground Calcium Carbonate, Precipitated Calcium Carbonate, Coated Calcium Carbonate, Micronized Calcium Carbonate End Use Industry: Plastics, Paints, Paper, Food & Beverage Grade: High Purity, Food Grade, Industrial Grade, Ultra-Fine Application: Filler, Abrasive, pH Regulator, Whitening Agent |
| Companies Covered | Imerys, Minerals Technologies Inc., Omya AG, Mississippi Lime Company, Lhoist, Carmeuse, J.M. Huber Corporation, GLC Minerals, Greer Limestone Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Calcium Carbonate Market Evolving Landscape
Digital process control systems and regulatory compliance automation are redefining competitive differentiation in calcium carbonate manufacturing, compressing cost structures for early adopters while raising barriers for legacy operators.
Continuous precipitation reactor technology is automating particle size distribution control in precipitated calcium carbonate production. Automotive plastics compounders are adopting these systems to secure tighter specification windows for headliner and dashboard applications. This automation is compressing batch-to-batch variability penalties that previously eroded filler value capture.
EPA National Ambient Air Quality Standards for PM2.5 are tightening fugitive dust limits at mining and processing facilities. Industrial operators must install real-time particulate monitoring and automated suppression systems to maintain Title V operating permits. Surface-coated ground calcium carbonate grades are capturing share in paper and plastics as handlers seek lower-dust alternatives.
Direct mill-to-plant supply contracts are displacing distributor intermediaries in high-volume filler procurement. Plastics compounders along the Gulf Coast are negotiating multi-year toll processing agreements that guarantee specification consistency and volume allocation. This channel consolidation is most visible in polypropylene automotive interior supply chains serving Tennessee and Alabama assembly plants.
United States Calcium Carbonate Market Segmentation
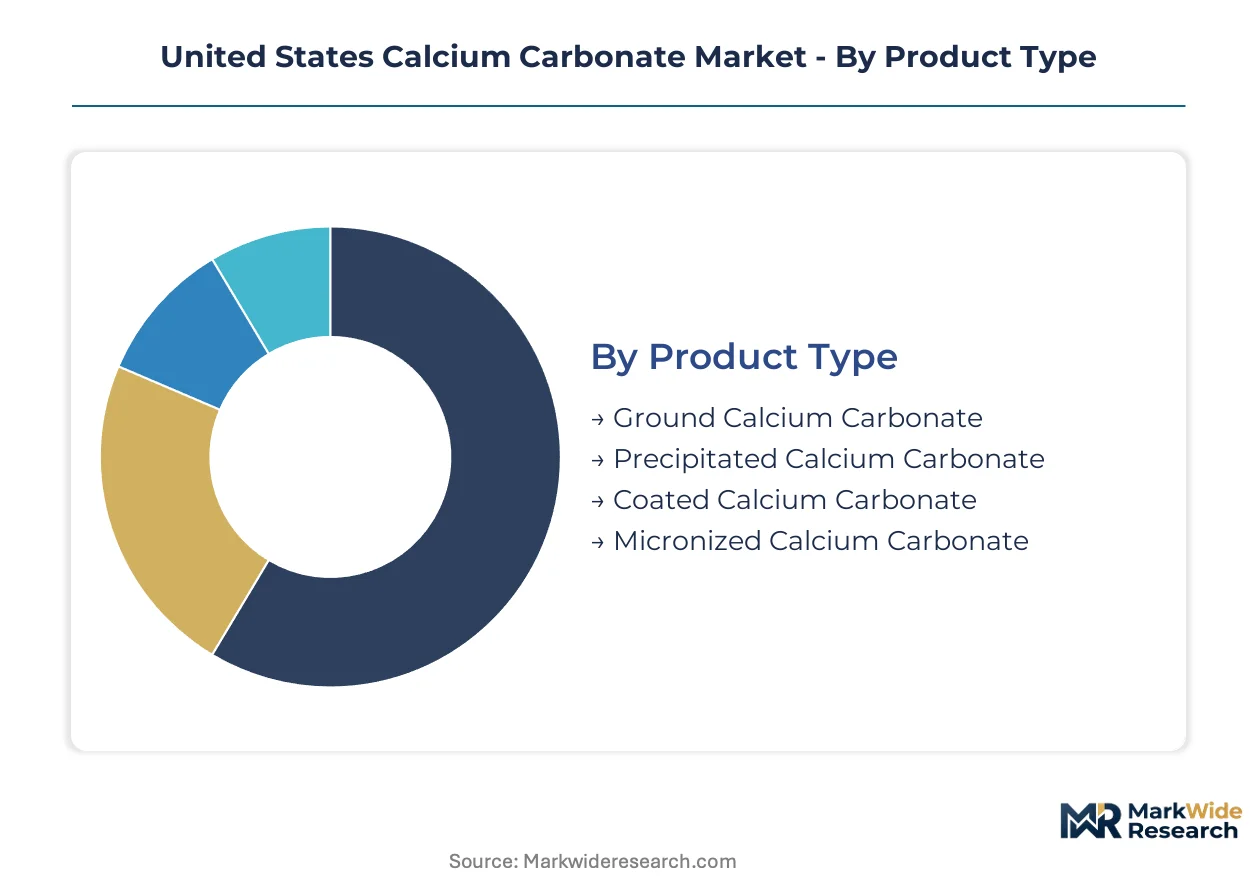
Calcium carbonate specifications diverge sharply across end-use requirements, with particle size distribution, surface treatment, and purity thresholds determining pricing tiers and customer switching costs. Producers must align processing investments with the technical demands of automotive plastics, food safety certification, or optical brightening applications.
Product Type:
Particle engineering technology separates commodity supply from premium positioning.
- Ground Calcium Carbonate:Mechanical grinding of limestone yields particles between 1 and 50 microns with moderate brightness. Demand concentrates in Ohio River Valley paper mills and Midwest construction profiles where freight cost minimization outweighs specification intensity. EPA PM2.5 enforcement is accelerating surface-coated variants that reduce handling dust.
- Precipitated Calcium Carbonate:Controlled precipitation chemistry achieves sub-micron particle sizes with narrow distribution curves and high specific surface area. Automotive interior polypropylene compounders in Tennessee and Alabama specify these grades for dimensional stability in thin-wall molding applications.
- Coated Calcium Carbonate:Surface modification with stearic acid or proprietary coupling agents improves polymer matrix dispersion and hydrophobicity.
- Micronized Calcium Carbonate:Jet milling or classifier milling produces ultra-fine particles below 5 microns for high-performance coatings and sealants.
Ground calcium carbonate leads on scale; precipitated calcium carbonate leads on momentum.
End Use Industry:
Customer concentration patterns dictate logistics infrastructure and technical service intensity.
- Plastics:Polypropylene and PVC compounding for automotive interiors, construction profiles, and packaging films consumes surface-treated filler grades. Gulf Coast petrochemical corridor expansion is creating captive demand for just-in-time delivery contracts with specification guarantees.
- Paints:Titanium dioxide extension and rheology control in architectural and industrial coatings requires controlled particle size and oil absorption indices.
- Paper:Coated groundwood and uncoated freesheet mills in the Southeast and Great Lakes regions specify brightness and particle distribution for opacity and printability.
- Food & Beverage:FDA 21 CFR 184.1409 compliance for pH adjustment, anti-caking, and fortification demands dedicated processing lines with allergen controls and batch traceability.
Plastics commands the steepest expansion trajectory; paper retains the largest volume foundation.
Grade:
Certification tiering creates margin stratification that separates commodity producers from specialty suppliers.
- High Purity:Acid-insoluble content below 0.5% and heavy metal limits stricter than standard industrial specifications serve pharmaceutical excipient and premium polymer applications.
- Food Grade:Microbiological testing, allergen segregation, and FDA food additive compliance enable nutraceutical tablets, beverage fortification, and processed food applications with 3-5x commodity pricing multiples.
- Industrial Grade:Standard brightness and purity levels satisfy construction, agriculture, and bulk chemical processing where cost minimization dominates procurement.
- Ultra-Fine:Particle sizes below 1 micron with tight distribution coefficients address optical brightening, barrier films, and advanced composites where performance premiums justify processing complexity.
Industrial grade leads on scale; food grade leads on margin expansion.
Application:
Functional role determines formulation integration depth and customer technical support requirements.
- Filler:Volume extension in plastics, rubber, and paper compounds reduces raw material costs while maintaining mechanical properties. Automotive lightweighting mandates are accelerating precipitated grade adoption for density reduction in interior components.
- Abrasive:Controlled hardness and particle angularity in toothpaste, cleaning compounds, and industrial polishing applications.
- pH Regulator:Municipal water treatment plants and industrial wastewater systems consume high-purity grades for neutralization, with Bipartisan Infrastructure Law funding expanding Midwest and Southeast utility procurement.
- Whitening Agent:High brightness and fine particle size scatter light in paper coatings, paints, and plastics where optical performance is specified.
Filler leads on scale; pH regulator leads on policy-driven momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone quarrying expertise concentrates in the Ohio River Valley, where multi-generational mining workforces anchor domestic supply chains for paper, plastics, and water treatment customers.
Ohio River Valley
Paper mill clusters in Kentucky and Ohio purchase ground calcium carbonate for coated groundwood production. EPA National Ambient Air Quality Standards for PM2.5 constrain quarry expansion permits. Pittsburgh-to-Cincinnati processing corridors leverage barge logistics to serve Great Lakes papermakers with freight cost advantages.
Gulf Coast Petrochemical Corridor
Polypropylene compounding for automotive interiors drives precipitated calcium carbonate demand from Tennessee and Alabama assembly plants. OSHA silica exposure limits require micronized processing investments at Texas and Louisiana facilities. Houston-area toll processors negotiate multi-year supply contracts with specification guarantees.
Southeast Limestone Belt
Construction profile extruders in Georgia and Florida consume surface-coated filler grades for PVC applications. State environmental review processes in Pennsylvania and Kentucky extend greenfield quarry timelines. Imerys operates vertically integrated quarry-to-distribution networks across Virginia and North Carolina.
Midwest Water Treatment Hubs
Municipal pH regulation systems in Illinois and Michigan consume high-purity calcium carbonate for drinking water compliance. Bipartisan Infrastructure Law funding accelerates procurement from dedicated food-grade processing lines. Chicago-area distributors serve regional utilities with batch traceability documentation.
Mountain West Mining Districts
Industrial-grade limestone for agriculture and bulk chemicals originates from Colorado and Utah deposits. Natural gas price volatility affects calcination economics for precipitated grade production. Denver-based processors supply western construction markets with lower-brightness industrial specifications.
United States Calcium Carbonate Market Competitive Landscape
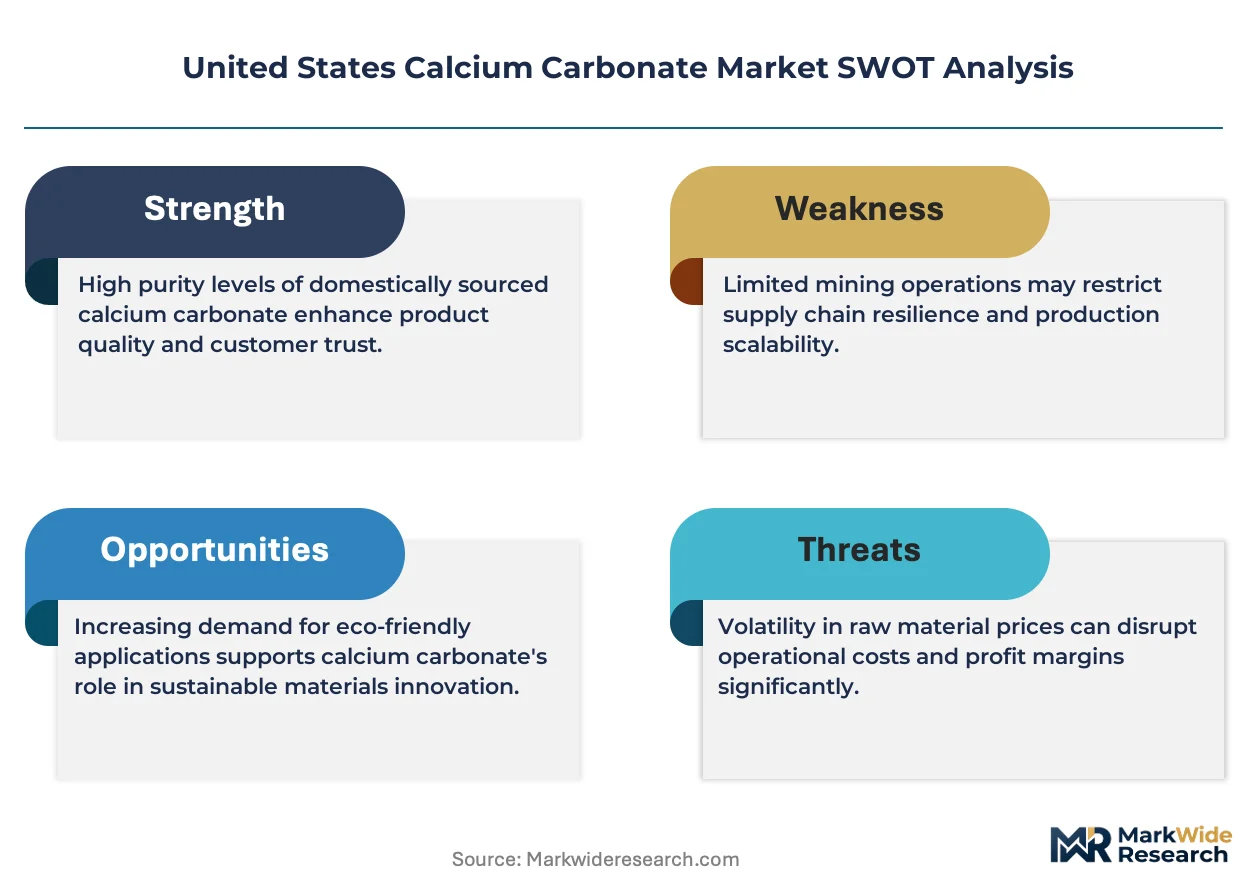
Capital-heavy producers compete with asset-light designers across distinct technology tiers in the United States calcium carbonate market. Vertically integrated quarry operators dominate ground calcium carbonate volume through captive limestone reserves and barge-accessible processing infrastructure. Precipitated calcium carbonate specialists anchor premium positioning via controlled precipitation chemistry and particle engineering capabilities. Surface modification specialists capture margin in polymer compounding through proprietary coating formulations. Competitive dynamics center on multi-year toll processing agreements and food-grade certification investments that lock in automotive and pharmaceutical customers.
Among integrated multi-national suppliers, Imerys, Minerals Technologies Inc., and Omya AG exemplify contrasting strategic archetypes. Imerys occupies a position anchored in quarry ownership and Southeast distribution density. Minerals Technologies Inc. represents technology-led positioning through precipitated calcium carbonate process control. Omya AG sits within specialized coating capabilities for high-performance polymer applications. These three structures illustrate how capital deployment, technical specialization, and geographic coverage define competitive differentiation in domestic filler markets.
| Leading Market Players |
|---|
| Imerys |
| Minerals Technologies Inc. |
| Omya AG |
| Mississippi Lime Company |
| Lhoist |
| Carmeuse |
| J.M. Huber Corporation |
| GLC Minerals |
| Greer Limestone Company |
| Others |
Value Network & Pricing Analysis
Family-owned limestone operators in Pennsylvania and Kentucky anchor supply discipline through generational quarry ownership, translating captive mineral reserves into pricing power that resists spot-market volatility while funding micronized processing investments demanded by automotive compounders.
Pricing Analysis
Bundled toll-processing contracts dominate precipitated calcium carbonate procurement, while unbundled spot purchases persist for industrial-grade ground material. Three-tier pricing structure across food-grade, high-purity, and industrial specifications separates FDA-certified pharmaceutical excipients from construction filler, with certification investments commanding 3-5x commodity multiples. Cost compression in standard industrial grades intensifies because barge-accessible Ohio River Valley processors undercut rail-dependent competitors on delivered cost. Water treatment utilities exhibit highest price sensitivity due to municipal budget constraints, while automotive Tier 1 suppliers prioritize specification consistency over unit cost.
Supply Chain Analysis
Reverse-logistics flows are negligible in calcium carbonate given the mineral's single-use nature, though spent processing water recycling and quarry overburden reclamation are tightening environmental compliance. Supply concentrates in the United States through domestic limestone deposits in Ohio, Kentucky, and Pennsylvania, with limited import dependency for ultra-high-purity specialty grades. Raw material sourcing draws from Paleozoic limestone formations, natural gas for calcination energy, and proprietary coating chemistries. Single-source vulnerability runs through the Ohio River Valley barge corridor where flooding periodically disrupts paper mill deliveries. Distribution runs through direct mill-to-plant contracts for high-volume plastics compounders, with regional distributors serving fragmented construction and agriculture customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in United States calcium carbonate rests on food-grade certification premiums and automated precipitation technology that compresses batch-to-batch variability penalties.
For Market Incumbents: Deploy continuous precipitation reactor automation to tighten particle size distribution windows for Tennessee and Alabama automotive interior compounders. Consolidate quarry positions in Kentucky and Ohio ahead of EPA PM2.5 permitting constraints that will strand undeveloped reserves. Channel control through captive barge terminals defends against rail-dependent entrants in Great Lakes paper markets. For New Entrants and Emerging Players: Launch via synthetic calcium carbonate production from industrial CO2 streams, qualifying for Section 45Q tax credits under the Inflation Reduction Act. Target carbon capture utilization partnerships with Gulf Coast petrochemical operators seeking Scope 3 reduction pathways. Food-grade pH regulator supply to Midwest municipal utilities offers the most penetrable white space given Bipartisan Infrastructure Law funding acceleration and incumbent capacity constraints. For Investors and Strategic Acquirers: Specialty chemical conglomerates with polymer compounding footprints are the most active acquirer in this space, seeking backward integration into filler supply. Five-to-ten year viability favors processors with FDA 21 CFR 184.1409 compliance and precipitated calcium carbonate technology leadership over pure-play quarry operators. Monitor EPA coal ash regulation evolution as a signal for synthetic calcium carbonate demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive limestone reserves in Kentucky and Ohio secure supply against EPA permitting delays. |
| Food-Grade Certification Investment | FDA 21 CFR 184.1409 compliance opens pharmaceutical excipient markets with premium pricing multiples. |
| Continuous Precipitation Reactor Deployment | Automated particle engineering reduces batch-to-batch variability penalties in automotive polypropylene supply. |
| Carbon Capture Utilization Pathway | Synthetic production from industrial CO2 streams qualifies for Section 45Q tax credit monetization. |
| Barge-Accessible Processing Expansion | Ohio River Valley terminals deliver 40% freight cost advantage over rail-dependent Great Lakes competitors. |
Research Methodology
Direct dialogue with plant managers at precipitated calcium carbonate facilities, procurement leads at Gulf Coast polypropylene compounders, distribution channel partners serving Midwest paper mills, and technical R&D directors at surface modification specialists grounded qualitative findings. Secondary validation drew from EPA enforcement databases, SEC 10-K filings of listed specialty chemical producers, Ohio River Valley customs and barge traffic data, and OSHA silica exposure compliance records. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated to cross-check volume assumptions.
Segment-level value outputs across product type, end-use industry, grade certification, and application functional role were generated through the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating automotive lightweighting mandates, Bipartisan Infrastructure Law water treatment funding trajectories, and plastics compounding cluster expansion patterns. Henry Hub natural gas price volatility and EPA PM2.5 enforcement intensity served as scenario-weighting inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged quarry permitting moratoria or accelerated carbon accounting mandates. Practitioners should monitor EPA coal ash regulation finalization and Ohio River Valley flood frequency for early signals of supply disruption or synthetic calcium carbonate demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
US Trona Market