
 Biobased Polypropylene PP Size Market | 2026-2036
Biobased Polypropylene PP Size Market Size, Share, and Industry Trends Forecast 2026-2036
Biobased Polypropylene PP Size Market Insights
Automotive OEM procurement for interior and under-hood components is consolidating around Tier 1 suppliers with verified biobased feedstock certificates. Braskem leverages its sugarcane-derived ethanol-to-propylene pathway to anchor supply contracts with European automakers. Mitsui Chemicals sustains technical leadership in high-heat random copolymer grades for injection molding applications. Neste competes through renewable naphtha partnerships that extend its reach into Asian packaging markets.
Biobased polypropylene denotes propylene polymer derived from non-fossil feedstocks such as plant oils, agricultural residues, or bio-naphtha, with identical molecular structure to conventional PP and melt flow indices ranging from 2 to 50 g/10min for process compatibility. It serves industrial buyers seeking drop-in replacements that maintain existing tooling and recycling infrastructure while reducing scope 3 emissions. Packaging materials leads application demand as brand owners enforce minimum biobased content thresholds in flexible films and rigid containers. Automotive components represents the fastest-expanding segment as lightweighting requirements intersect with carbon accounting rules. Homopolymer grades occupy the dominant share of volume owing to their stiffness and clarity balance in thin-wall injection molding.
The EU Green Deal and REACH frameworks mandate mass-balance certification for biobased content claims, compelling producers to adopt ISCC PLUS chain-of-custody standards. The EPA in the United States administers renewable fuel pathway approvals that influence bio-naphtha pricing and refinery offtake economics. Stakeholders must monitor feedstock cost volatility relative to fossil propylene and verify that certification schemes align with downstream customer audit requirements.
Market Dynamics
Automotive OEMs in Germany are embedding biobased content mandates into multi-year supplier contracts, forcing Tier 1 injection molders to secure ISCC PLUS-certified feedstock or lose platform access.
Growth Catalysts
- EU Green Deal mass-balance rules:REACH sustainability criteria now require verifiable chain-of-custody documentation, compelling packaging converters to source certified biobased grades for retailer compliance.
- Automotive lightweighting mandates:Under-hood and interior component specifications increasingly specify biopolymer content to meet fleet emissions accounting rules.
- Sugarcane ethanol-to-propylene pathways:Brazilian feedstock infrastructure is expanding fermentation capacity to supply European polymer producers with drop-in bio-naphtha.
Market Restraints
- Feedstock cost volatility:Agricultural commodity prices for corn and sugarcane swing independently of fossil propylene, compressing margin predictability for compounders.
- Refinery offtake concentration:Bio-naphtha supply clusters in Rotterdam and Antwerp, creating single-point vulnerability for Northern European processors.
- Melt flow index limitations:Current biobased random copolymer grades struggle to match the high-flow characteristics required for thin-wall food container molding.
Strategic Opportunities
- Underpenetrated Japanese automotive:METI carbon-neutral vehicle targets have not yet translated to biopolymer procurement clauses, leaving first-mover space for certified suppliers.
- Flexible film food packaging:Brand owner minimum biobased thresholds are tightening fastest in fresh produce and ready-meal segments.
- Pyrolysis-to-naphtha convergence:Chemical recycling infrastructure is merging with bio-naphtha supply pools, enabling hybrid feedstock claims.
Industry Challenges
- ISCC PLUS audit timelines:Certification backlogs stretch 8-14 months, delaying contract execution for converters facing retailer deadlines.
- Legacy tooling compatibility:Process engineers must revalidate injection parameters when switching from fossil to biobased grades with slightly different shear response.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobased Polypropylene PP Size Market |
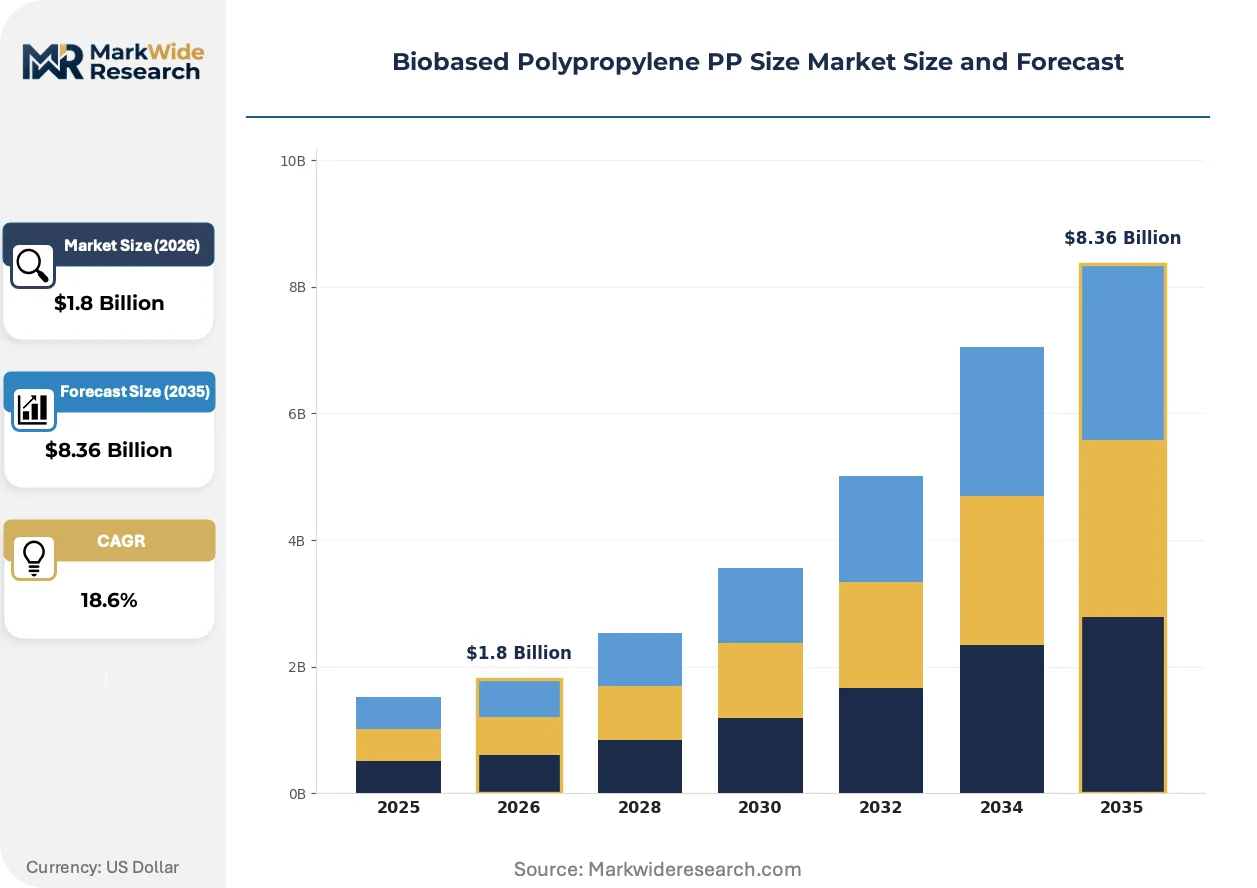
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Random Copolymer, Block Copolymer, Impact Copolymer Application: Packaging Materials, Automotive Components, Consumer Goods, Electrical Appliances, Construction Materials End User Industry: Agriculture Technology, Household Products, Electronics Manufacturing, Infrastructure Development Packaging Type: Bulk Bags, Jumbo Bags, Totes, Pallet Bags |
| Companies Covered | Braskem, LyondellBasell Industries Holdings, Mitsui Chemicals, SABIC, Borealis, TotalEnergies, Neste, FKuR Kunststoff, Citroniq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobased Polypropylene PP Size Market Trends and Innovations
Mass-balance accounting systems are rewiring how polymer producers contract with agricultural feedstock suppliers and petrochemical refiners simultaneously.
Advanced fermentation pathways for propylene precursors are expanding into commercial-scale production. Braskem and Neste have commissioned integrated biorefinery complexes that convert sugarcane bagasse and waste oils into polymer-grade bio-naphtha. European automakers are qualifying these outputs for interior trim applications at accelerated 18-month cycles. The technology is expanding into Asian packaging markets where brand owners face Scope 3 disclosure pressure.
REACH mass-balance certification requirements under the EU Green Deal are tightening documentation standards for biobased content claims. ECHA now mandates third-party verification for every supply chain node from feedstock cultivation to pellet distribution. German automotive OEMs have integrated these audit requirements into supplier quality agreements. Packaging converters in France and Italy are consolidating procurement around traders with pre-certified inventory pools.
Retailer sustainability scorecards are compressing converter switching cycles from annual to quarterly reviews. Lidl and Carrefour now enforce minimum biobased thresholds in private-label flexible films, forcing compounders to maintain dual-certified fossil and biobased grade inventories. Tier 2 molders in Spain and Poland report margin pressure from this inventory duplication. The shift is most visible in fresh produce packaging where shelf-life performance must match conventional PP while meeting content mandates.
Biobased Polypropylene PP Size Market Segmentation
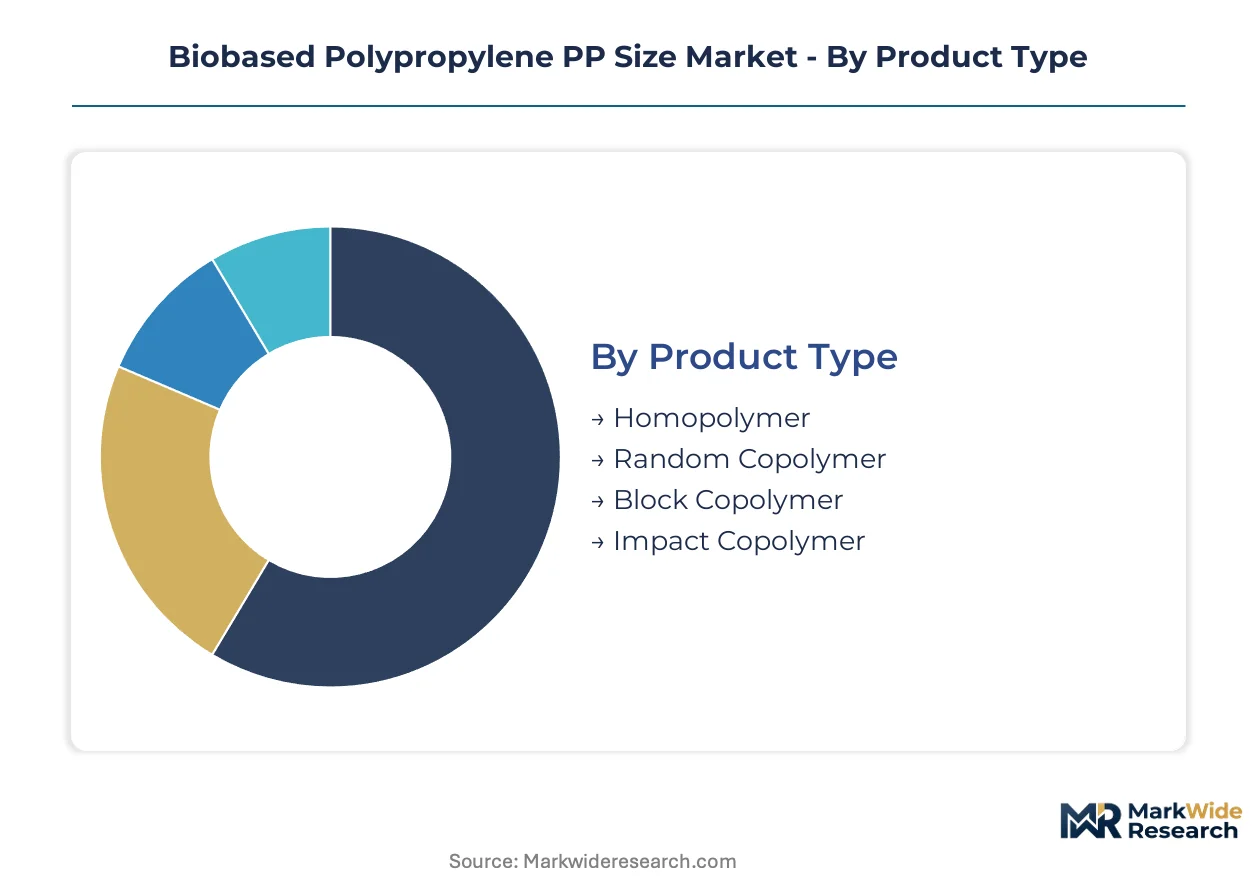
Segmentation in biobased polypropylene reveals how certification requirements and tooling compatibility split procurement patterns across converter tiers. Technical specifications diverge sharply between drop-in homopolymer grades and higher-value copolymers requiring process revalidation.
Product Type:
Production capacity clusters around fermentation-derived homopolymer grades with established mass-balance certification, while advanced copolymer variants remain concentrated with Mitsui Chemicals and Braskem's technical service networks.
- Homopolymer:Stiffness and clarity balance suits thin-wall injection molding for food containers and caps. German automotive Tier 1 suppliers specify this grade for non-structural interior trim where ISCC PLUS documentation satisfies OEM audit requirements.
- Random Copolymer:High-heat resistance and optical clarity target medical packaging and transparent consumer goods. Mitsui Chemicals dominates technical qualification programs for this segment across Japanese and European electronics packaging converters.
- Block Copolymer:Balanced stiffness-toughness profile serves appliance housings requiring drop-in replacement compatibility with existing fossil PP tooling.
- Impact Copolymer:Superior low-temperature ductility targets automotive bumper cores and cold-chain packaging where ethylene content enhances durability.
Homopolymer absorbs the bulk of installed capacity; random copolymer is expanding most quickly.
Application:
Cost tier differentiation separates commodity packaging converters operating on thin margins from automotive suppliers capturing carbon accounting premiums through multi-year contracts.
- Packaging Materials:Flexible films and rigid containers for fresh produce and ready-meals dominate volume. Lidl and Carrefour procurement mandates force quarterly inventory rotations between certified biobased and fossil grades.
- Automotive Components:Under-hood and interior specifications now embed biopolymer content targets. BMW and Volkswagen supplier contracts in Germany require verified feedstock certificates for platform access.
- Consumer Goods:Durable housewares and furniture components leverage biobased claims for retail differentiation without performance compromise.
- Electrical Appliances:Flame-retardant compounded grades serve small appliance housings where UL certification paths remain under development.
- Construction Materials:Geotextiles and pipe fittings exploit UV stability in agricultural and civil engineering applications.
Packaging materials command the widest converter base; automotive components show the steepest expansion trajectory.
End User Industry:
Customer type fragmentation splits between agricultural buyers prioritizing cost parity and electronics manufacturers demanding full supply chain disclosure for Scope 3 reporting.
- Agriculture Technology:Mulch films and crop protection fabrics require UV-stabilized grades with certified biodegradation pathways in soil contact applications.
- Household Products:Storage containers and cleaning tool housings leverage biobased labeling for shelf placement advantages in European retail.
- Electronics Manufacturing:Precision molding tolerances and ESD properties drive qualification cycles with Sony and Panasonic procurement teams in Japan.
- Infrastructure Development:Geosynthetics and drainage systems specify long-term durability where fossil PP cost advantages persist.
Agriculture technology consumes the highest volume tonnage; electronics manufacturing is gaining share fastest.
Packaging Type:
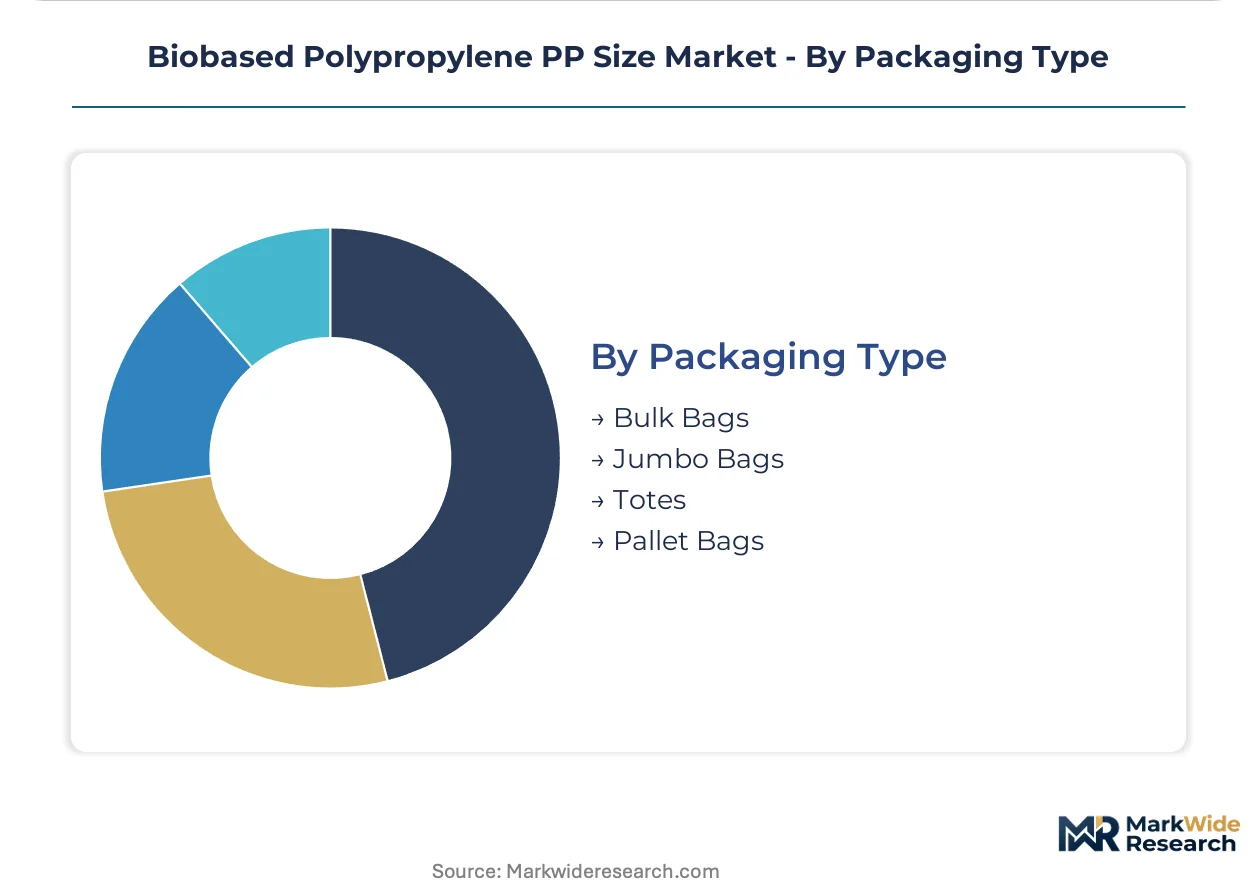
Volume scale determines converter equipment investment, with bulk formats amortizing certification costs across larger production runs than small-lot specialty bags.
- Bulk Bags:FIBC formats for chemicals and food ingredients require UN certification compatibility that biobased grades now achieve through Braskem's drop-in validation.
- Jumbo Bags:Agricultural commodity transport exploits tear resistance where homopolymer stiffness advantages reduce material gauge.
- Totes:Intermediate bulk containers for liquids demand FDA compliance pathways that remain limited for biobased random copolymer grades.
- Pallet Bags:Stretch hood and shrink wrap applications prioritize cling and puncture resistance where bio-naphtha feedstock consistency affects lot-to-lot variability.
Bulk bags anchor current converter capacity; totes are climbing the fastest as chemical logistics operators adopt mass-balance certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs embed the most aggressive biobased content mandates into supplier contracts, while Brazilian feedstock infrastructure and Dutch refining clusters anchor upstream supply. Certification backlogs and port concentration create bottlenecks that reshape procurement geography.
Germany
BMW and Volkswagen procurement teams enforce ISCC PLUS documentation for platform access across interior and under-hood components. The EU Green Deal mass-balance rules through ECHA mandate third-party verification at every supply chain node. The Ruhr industrial corridor hosts Tier 1 injection molders consolidating procurement around pre-certified inventory pools.
Brazil
Sugarcane ethanol-to-propylene pathways supply European polymer producers with drop-in bio-naphtha at scale. Fermentation capacity expansion in São Paulo state responds to German automaker demand for verified feedstock certificates. Braskem's integrated biorefinery complexes anchor supply contracts through mass-balance certified output.
Netherlands
Rotterdam and Antwerp clusters concentrate bio-naphtha refining capacity for Northern European processors. REACH compliance documentation requirements force traders to maintain dual-certified fossil and biobased grade inventories. The port infrastructure creates single-point vulnerability that compounders mitigate through quarterly inventory rotations.
Japan
METI carbon-neutral vehicle targets have not yet translated to biopolymer procurement clauses, leaving first-mover space for certified suppliers. Sony and Panasonic procurement teams drive qualification cycles for precision molding tolerances in electronics packaging. The Kanto region around Tokyo hosts technical qualification programs for high-heat random copolymer grades.
United States
EPA renewable fuel pathway approvals influence bio-naphtha pricing and refinery offtake economics for domestic compounders. Lidl and Carrefour procurement mandates for North American operations enforce minimum biobased thresholds in private-label flexible films. The Gulf Coast petrochemical corridor integrates bio-naphtha supply pools with chemical recycling infrastructure.
Biobased Polypropylene PP Size Market Competitive Landscape
Brazilian producers anchor the fermentation-derived feedstock tier; European specialists hold mass-balance certification and refinery partnership positions. The vendor base splits between integrated agricultural-polymer conglomerates and petrochemical incumbents retrofitting naphtha crackers. Three archetypes dominate: sugarcane-ethanol pathway operators, renewable naphtha traders, and technical-grade compounders. Capacity expansion and ISCC PLUS certification acquisition constitute the primary competitive moves as retailers compress converter switching cycles.
Within the integrated agricultural-polymer tier, Braskem exemplifies the sugarcane-ethanol-to-propylene pathway model. Mitsui Chemicals occupies a position among technical-grade specialists serving high-heat random copolymer demand. Neste represents the renewable naphtha trading archetype through partnerships extending into Asian packaging markets.
| Leading Market Players |
|---|
| Braskem |
| LyondellBasell Industries Holdings |
| Mitsui Chemicals |
| SABIC |
| Borealis |
| TotalEnergies |
| Neste |
| FKuR Kunststoff |
| Citroniq |
| Others |
Pricing and Supply Chain Analysis
Sugarcane ethanol benchmark prices in São Paulo state cascade through fermentation-to-propylene pathways, splitting procurement costs between mass-balance-certified biobased grades and conventional fossil propylene. This feedstock volatility compresses converter margins while EU Green Deal certification requirements add audit-cost premiums that Tier 1 automotive suppliers absorb more readily than thin-margin packaging compounders.
Pricing Analysis
Volume-scale homopolymer grades trade at commodity spot-equivalent levels, while high-heat random copolymer variants command certification-linked premiums from automotive OEMs. Price differentiation rests on ISCC PLUS documentation tier and melt-flow index performance grade. Pricing pressure stems from agricultural commodity swings independent of naphtha benchmarks, squeezing compounders without long-term offtake hedges. Packaging converters show highest price sensitivity due to retailer quarterly switching mandates; automotive Tier 1 suppliers exhibit lowest sensitivity through multi-year carbon accounting contracts.
Supply Chain Analysis
EU Green Deal local-content provisions and REACH mass-balance rules are reshaping sourcing toward verified Brazilian ethanol and Dutch-German refining corridors. Geographic supply concentrates in Brazil for fermentation feedstock, the Netherlands for bio-naphtha refining, and Germany for automotive compounding. Raw material dependencies include sugarcane bagasse, waste oils, and polymer-grade bio-naphtha. Single-point vulnerability clusters around Rotterdam-Antwerp port infrastructure, exposing Northern European processors to logistics disruption. Distribution runs through mass-balance-certified traders maintaining dual fossil-biobased inventories for converter compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a feedstock-transition phase where sugarcane-ethanol-to-propylene pathways displace fossil naphtha cracking, with certification infrastructure determining competitive survival.
For Market Incumbents: Deepen backward integration into São Paulo fermentation capacity to lock feedstock cost predictability against sugar price volatility. Secure ISCC PLUS certification pre-emptively for all pellet grades before ECHA audit backlogs stretch beyond 14 months, defending platform access against emerging bio-naphtha traders. For New Entrants and Emerging Players: Begin with Japanese automotive electronics packaging, where METI carbon-neutral targets have not yet triggered biopolymer procurement clauses. Target high-heat random copolymer qualification programs for Sony and Panasonic supply chains, using technical service partnerships as the go-to-market wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor mass-balance-certified compounders in the Netherlands-Ruhr corridor with stranded fossil PP assets convertible to bio-naphtha blending. Long-term viability hinges on hybrid feedstock flexibility combining pyrolysis and fermentation pathways. Watch for ISCC PLUS certification timeline compression as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Braskem's São Paulo biorefinery complexes anchor supply security against agricultural price swings. |
| ISCC PLUS Certification Acquisition | ECHA mass-balance mandates through EU Green Deal create 8-14 month audit backlogs for unprepared compounders. |
| Hybrid Feedstock Blending Capability | Pyrolysis-to-naphtha convergence enables dual certified-bio and recycled-content claims for packaging converters. |
| Technical Service Network Expansion | Mitsui Chemicals dominates Japanese electronics packaging through high-heat random copolymer qualification programs. |
| Long-term Automotive Supply Agreements | BMW and Volkswagen contracts embed biopolymer content targets with verified certificate requirements. |
Research Methodology
Multi-period observation of sugarcane ethanol pricing spreads, ISCC PLUS certification timelines, and automotive OEM procurement clauses anchored the trend analysis, supplemented by interviews with polymer plant managers, Tier 1 automotive procurement leads, packaging converter technical directors, and renewable naphtha traders. Secondary validation drew from customs trade data, ECHA regulatory filings, SEC chemical sector disclosures, and European bioplastics association production statistics. Bottom-up grade-level volume estimates triangulated against top-down regional demand aggregates.
Segment-weighting across product type, application, and end-use industry dimensions drove the analytical framework, with homopolymer and random copolymer grades receiving distinct elasticity assumptions. CAGRs derived from feedstock cost trajectory modeling and OEM contract penetration curves. Forecast inputs included Brazilian fermentation capacity expansion schedules and REACH enforcement intensity indices.
Underlying measurement precision varies by segment; automotive components carry tighter precision due to disclosed OEM contract volumes, while flexible film packaging estimates reflect broader converter survey dispersion. Forecasts reflect documented assumptions on certification adoption rates and sugarcane yield trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Global Resin Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Polyetherketone Market