
 Industrial Exhaust Fan Market | 2026-2036
Industrial Exhaust Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Exhaust Fan Market Analytics
Composite resin materials is broadening design possibilities for industrial exhaust fan impellers and housings. Greenheck Fan Corporation leverages captive manufacturing of corrosion-resistant polymer components to sustain margin pools in chemical processing applications. Howden Group anchors its position through specialized alloy fabrication capabilities for high-temperature exhaust streams. Twin City Fan & Blower competes aggressively on configurable direct-drive platforms for warehousing and distribution centers.
An industrial exhaust fan is a mechanical ventilation device engineered to remove contaminated air, fumes, heat, or particulate matter from enclosed industrial environments, typically operating at static pressures between 0.5 and 12 inches water gauge and flow rates exceeding 10,000 cubic feet per minute depending on application scale. Centrifugal fans dominate heavy manufacturing duty cycles where high static pressure resistance proves essential, while axial fans lead in agricultural and light warehousing applications prioritizing volume throughput at lower system resistance. Smart control mechanisms represent the fastest-expanding installation category as facility managers integrate variable frequency drives with building automation protocols to reduce energy consumption during non-peak ventilation periods.
OSHA ventilation standards mandate minimum air exchange rates in hazardous industrial environments, directly shaping product specification requirements for US-based manufacturers and importers. EPA emissions enforcement for volatile organic compounds and particulate matter forces end users toward higher-efficiency exhaust systems with integrated filtration stages. The EU F-Gas Regulation and REACH chemical compliance frameworks constrain material selection for fans deployed in European pharmaceutical and food processing facilities. Stakeholders must weigh regional certification burdens against total cost of ownership when specifying platform architectures for multinational facility rollouts.
Market Dynamics
Composite blade materials are compressing replacement cycles and forcing incumbent fabricators to retool production lines around polymer injection molding, fundamentally altering cost structures and supplier qualification timelines across heavy-duty industrial ventilation.
Growth Catalysts
- OSHA ventilation mandates:Tightening air exchange requirements in US chemical processing facilities are compelling facility retrofits and driving specification upgrades toward higher-static-pressure centrifugal platforms.
- Composite resin adoption:Corrosion-resistant polymer impellers are extending operational lifespans in fume-laden environments, reducing total cost of ownership calculations for plant engineers specifying new installations.
- Yangtze River Delta manufacturing corridor:Concentrated industrial expansion across Jiangsu and Zhejiang provinces is generating concentrated demand for large-scale exhaust infrastructure in electronics and automotive component plants.
Market Restraints
- Specialized alloy input costs:Nickel and cobalt price volatility directly pressures margins for fabricators serving high-temperature exhaust applications above 400°C operating thresholds.
- Supply concentration in precision bearing assemblies:German and Japanese specialty suppliers control critical subcomponent availability, creating vulnerability for tier-two fan assemblers without captive machining.
- REACH chemical compliance:European coating and sealant material restrictions are forcing reformulation of corrosion-resistant surface treatments, extending product development cycles.
Strategic Opportunities
- Smart building integration:Variable frequency drive convergence with BACnet and Modbus protocols is opening specification pathways in greenfield logistics facilities pursuing LEED certification.
- EU F-Gas Regulation phase-down:Refrigerant containment mandates in cold storage and food processing are driving demand for sealed exhaust systems with integrated leak detection.
- India pharmaceutical manufacturing:CDSCO cleanroom requirements and export-oriented production growth are creating demand for HEPA-integrated exhaust platforms in Hyderabad and Ahmedabad clusters.
Industry Challenges
- Aerodynamic simulation expertise:Computational fluid dynamics competency gaps among regional system integrators are delaying optimized fan selection for complex ductwork configurations.
- Multi-certification timelines:Simaneous UL, ATEX, and IECEx qualification requirements for hazardous location deployment are extending product launch schedules by 8-14 months.
- Legacy motor integration:Retrofit installations face mechanical compatibility constraints when mating modern high-efficiency impellers with existing NEMA frame sizes and shaft configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Exhaust Fan Market |
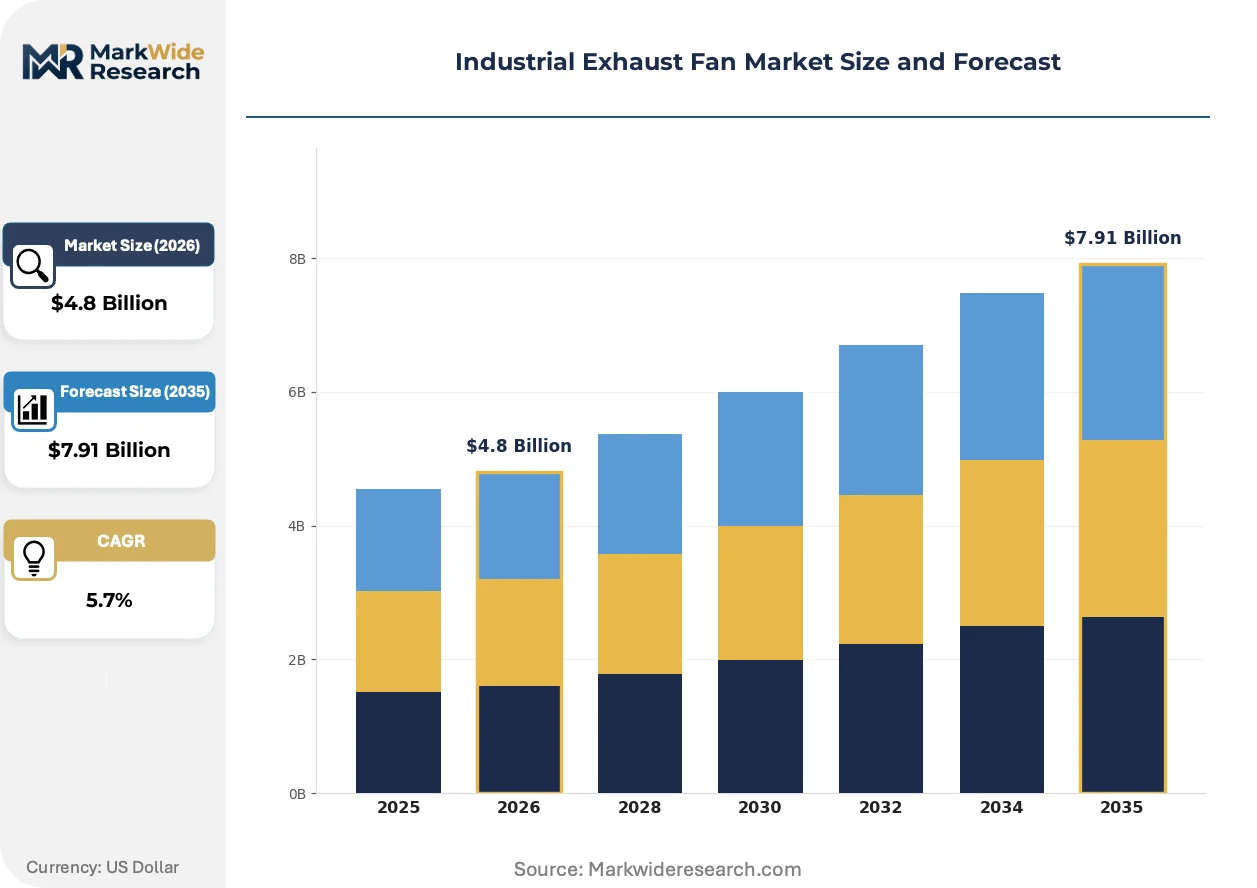
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Mixed Flow Fans, Blowers End User: Manufacturing, Warehousing, Agriculture, Automotive Installation Type: Roof-mounted, Wall-mounted, Ducted, Portable Control Mechanism: Manual, Automatic, Variable Speed, Smart Control |
| Companies Covered | Greenheck Fan Corporation, Twin City Fan & Blower, Howden Group, Systemair, Loren Cook Company, Johnson Controls International plc, ebm-papst, Soler & Palau, Ventmeca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Exhaust Fan Market Evolving Landscape
Active magnetic bearing systems are eliminating mechanical contact in high-speed impeller applications, while predictive maintenance algorithms embedded in drive controllers are compressing service intervals and reshaping aftermarket revenue models.
Direct-drive permanent magnet motors are electrifying traditional belt-and-pulley transmission architectures in centrifugal exhaust platforms. Food processing and pharmaceutical facilities are specifying these configurations to eliminate lubrication contamination risks and reduce acoustic signatures below 75 dB. The technology is electrifying competitive positioning by enabling manufacturers to capture premium pricing for maintenance-reduced platforms while compressing aftermarket belt and bearing replacement revenues.
EPA emissions enforcement for volatile organic compounds is tightening stack monitoring requirements across US chemical and coating operations. Facilities must now demonstrate continuous compliance through integrated exhaust stream measurement rather than periodic manual testing. Petrochemical complexes along the Texas and Louisiana Gulf Coast are responding by specifying fans with built-in sampling ports and corrosion-resistant materials compatible with continuous analyzer exposure.
Energy service company contracting is displacing traditional capital purchase models for large-scale ventilation infrastructure. Industrial facilities in Germany and the Netherlands are engaging Siemens Energy and Engie on performance-guaranteed exhaust system upgrades where payments tie to verified airflow and energy reduction outcomes. This model is most visible in carbon-intensive process industries facing EU ETS compliance cost pressures and seeking off-balance-sheet treatment for efficiency investments.
Industrial Exhaust Fan Market Segmentation
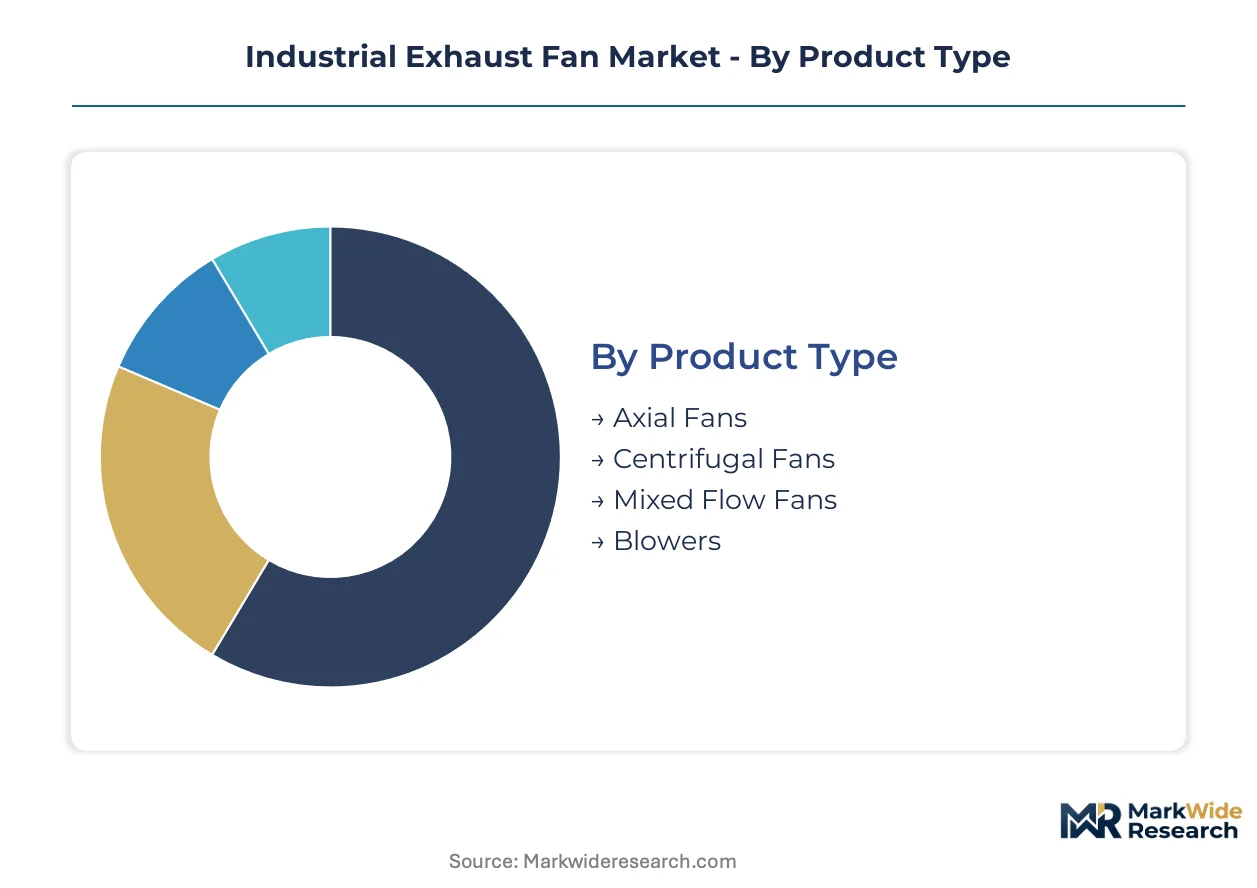
Industrial exhaust fan procurement varies sharply by operational context. Standalone units dominate heavy manufacturing where dedicated ventilation lines serve single processes. Embedded systems integrate with building automation in warehousing and distribution facilities where centralized control reduces energy overhead.
Product Type:
Standalone centrifugal platforms anchor chemical processing and high-temperature applications. Embedded axial configurations integrate into HVAC backbone systems for agricultural and light industrial facilities where space constraints favor compact mounting.
- Axial Fans:Propeller-style impellers move high air volumes against minimal static resistance. Poultry operations in Iowa and grain storage facilities across the US Midwest specify these for continuous ventilation cycles where energy efficiency trumps pressure capability.
- Centrifugal Fans:Radial blade configurations generate static pressures exceeding 12 inches water gauge. US Gulf Coast petrochemical complexes deploy these for fume extraction under OSHA Process Safety Management mandates where ductwork complexity demands pressure head.
- Mixed Flow Fans:Hybrid geometries blend axial throughput with centrifugal pressure generation. Semiconductor cleanrooms in China's Jiangsu province specify these for laminar airflow maintenance where both volume and directional control matter.
- Blowers:Positive-displacement or high-speed impeller designs for concentrated point-source extraction. Automotive paint booths in Mexico's Bajío region deploy these for overspray capture where localized velocity profiles prove critical.
Volume placements concentrate in centrifugal platforms; the faster expansion belongs to mixed flow configurations climbing fastest in electronics manufacturing.
End User:
Cost tier stratification separates specification behavior across end-use categories. Capital-intensive process industries accept premium pricing for corrosion-resistant materials and extended warranties. Volume-driven sectors prioritize first-cost minimization and standardized maintenance protocols.
- Manufacturing:Chemical processing, metal fabrication, and electronics assembly operations require continuous exhaust duty. US OSHA ventilation mandates and EPA emissions enforcement drive specification toward higher-efficiency platforms with integrated monitoring capabilities.
- Warehousing:Distribution centers and logistics facilities prioritize intermittent ventilation for heat and contaminant purging. LEED-certified greenfield developments in Germany and the Netherlands specify smart-controlled systems with BACnet integration for energy optimization.
- Agriculture:Livestock confinement and crop storage operations demand corrosion-resistant construction for ammonia-laden environments. Iowa and Nebraska pork production facilities specify fiberglass-reinforced polymer housings to withstand organic acid exposure.
- Automotive:Paint application, welding, and battery assembly lines require explosion-rated configurations. Mexico's Querétaro and Guanajuato assembly plants specify ATEX-compliant centrifugal units for solvent vapor zones under NOM-027-STPS-2008 workplace safety standards.
Revenue concentration sits with manufacturing end users; steepest expansion trajectory belongs to automotive electrification-driven battery plant construction.
Installation Type:
Application context determines mounting architecture. Roof installations dominate new construction where structural loading accommodates distributed weight. Retrofit environments often force wall-mounted or portable solutions where existing infrastructure constrains modification scope.
- Roof-mounted:Upblast and downblast configurations exhaust directly to atmosphere without ductwork penetration. US commercial warehousing developments specify these for minimized installation cost and maintenance access from exterior.
- Wall-mounted:Sidewall propeller units serve agricultural buildings and light manufacturing where roof structural capacity limits loading. China's Yangtze River Delta electronics plants deploy these for supplementary ventilation in expansion wings.
- Ducted:Inline centrifugal or axial configurations integrate with extended duct networks. Pharmaceutical facilities in India's Hyderabad cluster specify these for HEPA-filtered exhaust streams under CDSCO cleanroom requirements.
- Portable:Self-contained units with flexible ducting for temporary or emergency ventilation. US construction and remediation contractors deploy these for confined space entry compliance under OSHA 1910.146 permit-required space regulations.
Placement volume clusters in roof-mounted systems; portable configurations gain share fastest in disaster recovery and temporary manufacturing surge capacity.
Control Mechanism:
Customer sophistication separates manual from automated specification. Small and mid-size facilities often retain manual switching for first-cost containment. Large-scale operations with energy management mandates specify integrated control architectures.
- Manual:On/off switching or multi-speed selectors without external system integration. Small agricultural operations and legacy manufacturing facilities specify these where capital constraints limit automation investment.
- Automatic:Timer-based or sensor-triggered activation for scheduled or demand-responsive operation. Germany's industrial Mittelstand deploys these for compliance with Energieeffizienzgesetz energy audit requirements.
- Variable Speed:Variable frequency drive modulation for partial-load efficiency. US food processing plants specify these to match ventilation rates to production scheduling and reduce peak demand charges.
- Smart Control:BACnet, Modbus, or proprietary protocol integration with building automation systems. Netherlands logistics facilities pursuing BREEAM certification deploy these for real-time airflow optimization and predictive maintenance scheduling.
Shipment volume concentrates in variable speed drives; smart control platforms climb fastest in greenfield European industrial construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate electronics manufacturing demand for corrosion-resistant exhaust infrastructure. OSHA ventilation mandates tighten across US Gulf Coast chemical processing corridors. EU F-Gas Regulation phase-downs reshape cold storage specifications in Germany and the Netherlands.
United States
Petrochemical complexes along the Texas and Louisiana Gulf Coast drive specification upgrades for high-static-pressure centrifugal platforms. EPA emissions enforcement mandates continuous stack monitoring for volatile organic compounds. Houston-area facilities deploy fans with integrated sampling ports and corrosion-resistant alloys compatible with analyzer exposure.
China
Jiangsu and Zhejiang provinces in the Yangtze River Delta generate concentrated demand for large-scale exhaust systems in semiconductor and automotive component plants. GB standards for industrial ventilation tighten compliance requirements for electronics manufacturing. Suzhou and Wuxi industrial parks specify mixed-flow configurations for laminar airflow maintenance in cleanroom environments.
Germany
Ruhr industrial belt facilities pursue Energieeffizienzgesetz compliance through performance-guaranteed ventilation upgrades. EU ETS carbon pricing pressures drive energy service company contracting models. Dortmund and Duisburg chemical plants engage Siemens Energy on outcome-based exhaust system retrofits with verified airflow optimization.
India
Hyderabad and Ahmedabad pharmaceutical clusters expand HEPA-integrated exhaust capacity under CDSCO cleanroom requirements. PLI scheme incentives accelerate export-oriented production growth. Telangana's Genome Valley biotech corridor specifies ducted inline configurations for filtered exhaust streams in active pharmaceutical ingredient manufacturing.
Mexico
Querétaro and Guanajuato automotive assembly plants specify ATEX-compliant centrifugal units for solvent vapor zones. NOM-027-STPS-2008 workplace safety standards mandate explosion-rated configurations in paint application areas. Bajío region battery plant construction drives demand for sealed exhaust systems with integrated leak detection.
Industrial Exhaust Fan Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in chemical processing and fragmented competition in agricultural ventilation. Tier-one fabricators anchor premium specification through captive alloy fabrication and polymer injection molding capabilities. Mid-scale regional assemblers compete on configurable platforms for warehousing and distribution. Dominant competitive moves include backward integration into precision bearing supply and strategic partnerships for smart control protocol integration.
Among US-based ventilation specialists, Greenheck Fan Corporation exemplifies the captive manufacturing archetype through in-house production of corrosion-resistant polymer components. Twin City Fan & Blower occupies a position within the configurable platform tier, while Howden Group represents specialized alloy fabrication capabilities for high-temperature exhaust applications. European fabricators Systemair and ebm-papst sit within the energy-efficient drive integration segment, with Soler & Palau anchoring Mediterranean market presence through regional distribution density.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| Twin City Fan & Blower |
| Howden Group |
| Systemair |
| Loren Cook Company |
| Johnson Controls International plc |
| ebm-papst |
| Soler & Palau |
| Ventmeca |
| Others |
Value Network & Pricing Analysis
Petrochemical procurement teams along the US Gulf Coast anchor pricing power through multi-year framework agreements that compress spot-market premiums for corrosion-resistant centrifugal platforms. This buyer concentration forces fabricators to absorb nickel and cobalt volatility through contract escalation clauses rather than pass-through mechanisms.
Pricing Analysis
Short lead-time premiums of 15-25 percent separate expedited deliveries from standard-cycle procurement in heavy-duty industrial ventilation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and aftermarket service bundling. Pricing pressure stems from composite resin substitution eroding steel-blade margins in chemical processing applications. Small agricultural operations exhibit highest price sensitivity, while pharmaceutical cleanroom specifications tolerate premium positioning for HEPA-integrated ducted systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Yangtze River Delta electronics plants, while authorized distributor networks serve fragmented agricultural and warehousing accounts. Manufacturing concentrates in China, Germany, and the United States for finished assembly, with precision bearing subcomponents sourced from Japan and German specialty suppliers. Raw material dependencies center on nickel alloys for high-temperature applications, glass-reinforced polymers for corrosion resistance, and rare-earth magnets for direct-drive motors. Single-source vulnerability in precision bearing assemblies creates procurement risk for tier-two assemblers lacking captive machining capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alloy fabrication capacity constraints prop pricing resilience across high-temperature exhaust applications above 400°C operating thresholds. This supply bottleneck sustains margin pools for incumbent fabricators with captive metallurgy capabilities.
For Market Incumbents: To counter composite resin substitution threatening traditional steel-blade revenue pools, secure backward integration into polymer injection molding or deepen captive alloy fabrication for extreme-temperature specifications. Prioritize ATEX and IECEx certification investments to extend qualification timelines that deter regional assemblers from hazardous-location penetration. For New Entrants and Emerging Players: Enter via portable exhaust configurations for disaster recovery and temporary manufacturing surge capacity, where established brands maintain minimal presence. Target India's pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad for HEPA-integrated platform specifications under CDSCO cleanroom mandates. Pursue energy service company partnerships for performance-guaranteed contracting models displacing capital purchase paradigms. For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with smart control protocol integration capabilities and established BACnet or Modbus certification pathways. Long-term viability hinges on predictive maintenance algorithm development and aftermarket revenue capture from magnetic bearing systems. Monitor EPA emissions enforcement intensity as the inflection signal for continuous monitoring infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Molding | Greenheck Fan Corporation's captive corrosion-resistant component production sustains margin pools in chemical processing. |
| Smart Control Protocol Certification | BACnet and Modbus integration opens specification pathways in Netherlands logistics facilities pursuing BREEAM certification. |
| Specialized Alloy Fabrication Capacity | Howden Group anchors high-temperature exhaust positioning through in-house metallurgy for petrochemical Gulf Coast demand. |
| Energy Service Company Partnership | Siemens Energy contracting models in Germany's Ruhr belt displace traditional capital purchase paradigms under EU ETS pressure. |
| Multi-Certification Investment | Simultaneous UL, ATEX, and IECEx qualification extends product launch timelines that protect incumbent positioning in hazardous locations. |
Research Methodology
Multi-period observation of OSHA enforcement patterns, EPA emissions mandate implementation timelines, and Yangtze River Delta industrial park expansion rates anchored the trend analysis, supplemented by interviews with plant engineers, OEM procurement teams, aftermarket service directors, and energy management consultants. Secondary validation drew from customs trade data, SEC 10-K filings of listed ventilation specialists, ACC industry reports, and GB standards documentation. Bottom-up installation volume estimates triangulated against top-down manufacturing capacity assessments across the analysis window.
Segment-weighting approaches distributed value and volume projections across product type, end-use vertical, installation architecture, and control mechanism dimensions. CAGRs were derived from regression analysis of historical shipment patterns against regulatory mandate implementation schedules and industrial construction permit data. Forecast inputs incorporated composite resin adoption curves, smart building integration penetration rates, and regional certification burden differentials.
Revisions become necessary when nickel and cobalt price volatility exceeds historical bands, REACH chemical compliance frameworks expand restricted substance lists, or precision bearing supply disruptions extend lead times beyond contractual escalation thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Hydronic Control Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Cold Insulation Market
HVAC Systems
Ductless HVAC System Market