
 Industrial Hood Ventilation Market | 2026-2036
Industrial Hood Ventilation Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hood Ventilation Market Foresight
Preventive maintenance contracts and software-enabled airflow monitoring is rebalancing how buyers evaluate total cost of ownership over equipment life cycles. Greenheck Fan Corporation leverages its captive distribution network to sustain aftermarket revenue streams across North American foodservice accounts. CaptiveAire Systems anchors its competitive position through specialized fabrication capabilities in stainless steel hood assemblies. Halton Group differentiates through advanced kitchen ventilation technologies that integrate fire suppression with demand-controlled ventilation.
An industrial hood ventilation system comprises a canopy structure, grease filters, exhaust fans, and ductwork engineered to capture, contain, and remove airborne contaminants, heat, and combustion byproducts from commercial and industrial processes, typically rated for airflow capacities from 1,000 to 50,000 cubic feet per minute depending on cooking load or chemical exposure. Wall-mounted configurations dominate volume sales in retrofit applications where existing kitchen layouts constrain ceiling infrastructure, while island hoods command premium positioning in open-concept restaurant designs requiring 360-degree capture efficiency. Active filtration technology represents the fastest-expanding segment as operators seek to reduce external ducting requirements and comply with evolving municipal discharge regulations.
The National Fire Protection Association mandates grease extraction efficiency standards through NFPA 96, while the American Society of Heating, Refrigerating and Air-Conditioning Engineers establishes minimum ventilation rates via ASHRAE Standard 154, and the U.S. Environmental Protection Agency enforces emissions thresholds for commercial cooking operations under Clean Air Act provisions. These overlapping requirements compel end users to prioritize certified equipment with documented test data rather than lowest-first-cost alternatives. Stakeholders must monitor emerging local ordinances restricting natural gas infrastructure, as electrification mandates could fundamentally alter hood thermal load calculations and fan sizing protocols.
Market Dynamics
Active filtration technology is compressing replacement cycles as commercial kitchen operators abandon passive grease capture systems to meet stricter municipal discharge ordinances and reduce external ducting footprints. This shift is rebalancing capital allocation toward software-enabled airflow monitoring and predictive maintenance platforms.
Growth Catalysts
- NFPA 96 Compliance Mandates:Fire safety code enforcement in the United States compels restaurant chains to upgrade exhaust systems with certified grease extraction efficiency, accelerating equipment replacement beyond natural depreciation schedules.
- Electrification Infrastructure:Natural gas restriction ordinances in California, New York, and Massachusetts are forcing recalculation of thermal load profiles, driving demand for hood systems engineered around induction and electric cooking equipment.
- Demand-Controlled Ventilation:Integration of variable-speed exhaust with occupancy sensors cuts energy consumption by modulating airflow to actual cooking load rather than peak design capacity.
Market Restraints
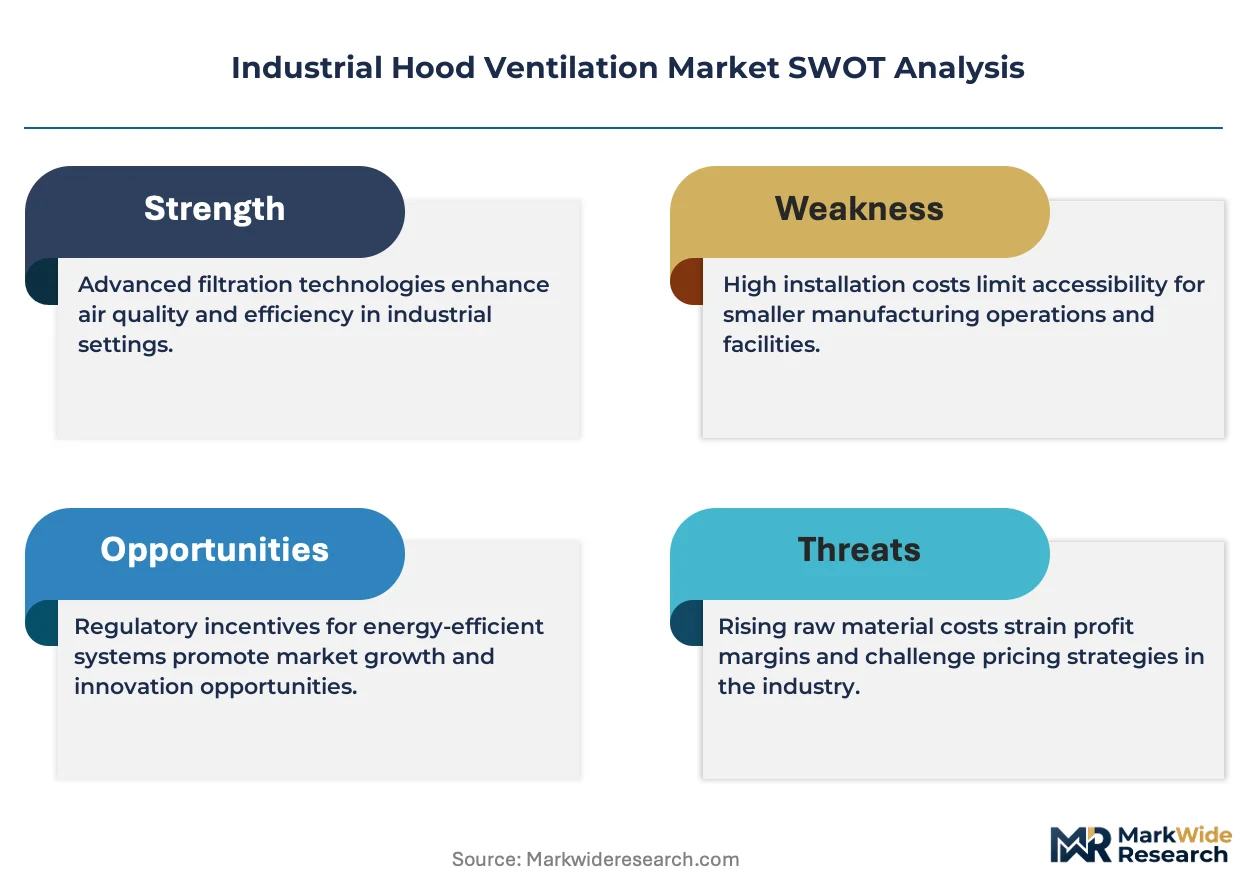
- Stainless Steel Input Volatility:Grade 304 and 316 sheet metal pricing fluctuates with nickel and chromium commodity markets, compressing fabrication margins for hood assembly specialists.
- Certified Installer Scarcity:NFPA 96 and ASHRAE 154 compliance requires licensed fire suppression technicians and sheet metal contractors, creating installation bottlenecks in secondary metropolitan markets.
- Electrostatic Precipitator Maintenance Burden:Active filtration cells demand weekly cleaning protocols and specialized wastewater handling, raising lifecycle operating costs above passive filter alternatives.
Strategic Opportunities
- Ghost Kitchen Concentrations:Delivery-only foodservice facilities in urban cores require compact, high-turnover ventilation solutions with minimal external ducting, favoring recirculating active filtration configurations.
- Utility Rebate Programs:Energy-efficiency incentives from Con Edison, PG&E, and Southern California Edison subsidize demand-controlled ventilation retrofits, lowering customer acquisition costs for system integrators.
- Cloud Kitchen Platforms:Reef Kitchens, CloudKitchens, and similar operators standardize ventilation specifications across multi-tenant facilities, creating volume procurement channels for pre-engineered hood packages.
Industry Challenges
- Controls Integration Complexity:BACnet and Modbus interoperability between hood controllers, building management systems, and fire suppression panels requires specialized commissioning expertise that general HVAC contractors rarely possess.
- ASHRAE 154-2016 Testing Documentation:Third-party certification of capture and containment performance adds six to twelve weeks to project timelines, delaying revenue recognition for equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hood Ventilation Market |
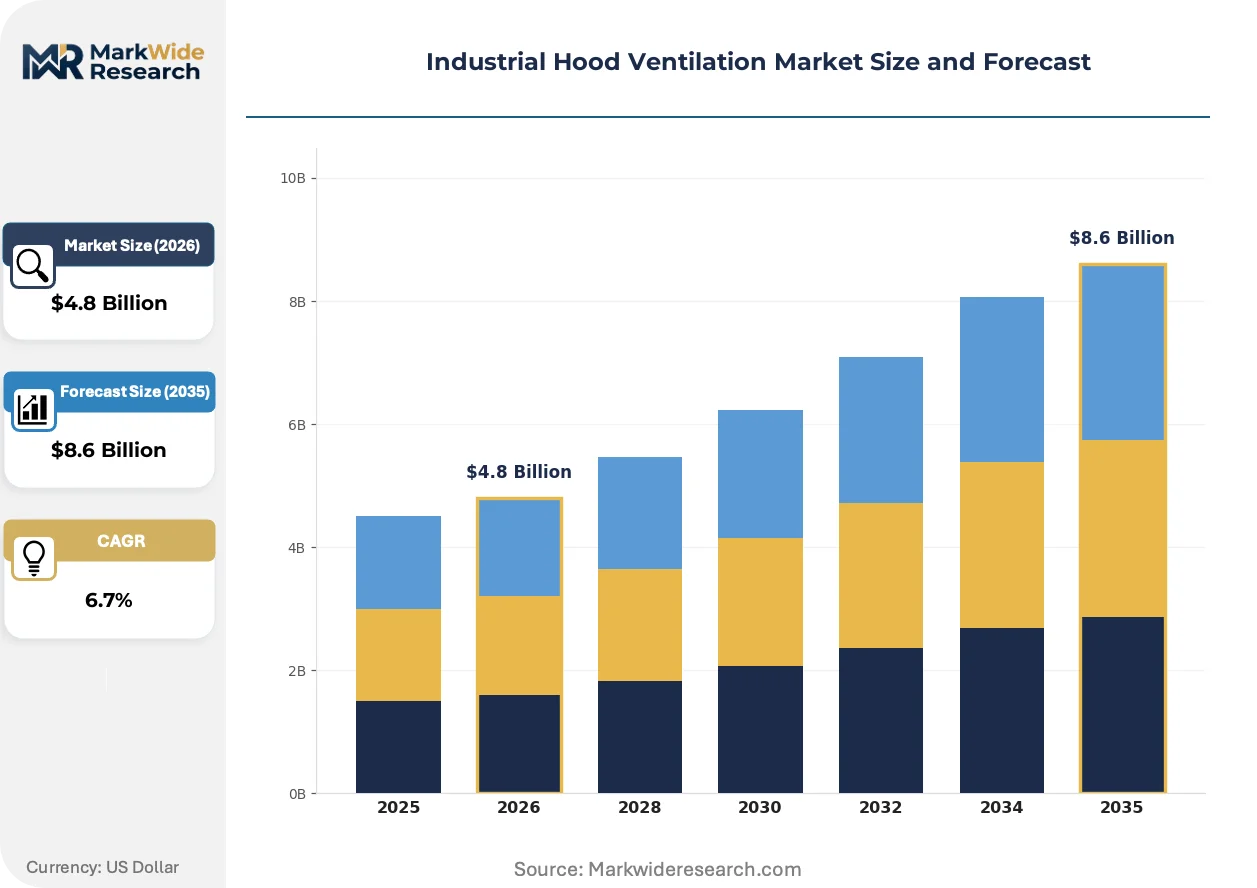
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Ceiling-Mounted, Island, Downdraft Installation Type: New Installation, Replacement, Retrofit, Modular End User: Restaurants, Laboratories, Manufacturing Plants, Supermarkets Technology: Active Filtration, Passive Filtration, Recirculating Ventilation, Exhaust System |
| Companies Covered | Greenheck Fan Corporation, CaptiveAire Systems, Halton Group, Johnson Controls, Honeywell International Inc., Systemair AB, Daikin Industries, FläktGroup, Fantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hood Ventilation Market Shifts & Advancements
Software-defined airflow management is displacing static mechanical controls as the primary value proposition in commercial kitchen ventilation. This transition favors suppliers with embedded systems capabilities over pure fabrication specialists.
Ultraviolet-C germicidal irradiation is expanding into exhaust plenum applications to reduce grease accumulation and fire risk. High-volume institutional cafeterias in hospital and university settings are piloting UVC-integrated hood systems to extend duct cleaning intervals. This technology is expanding into markets previously served solely by passive filtration, compressing the addressable base for conventional grease baffle manufacturers.
The U.S. Environmental Protection Agency enforces commercial cooking emissions under Clean Air Act provisions, with regional administrators targeting charbroiler and frying operations in ozone non-attainment zones. This regulatory pressure forces chain operators to document particulate matter controls in environmental impact statements. Quick-service restaurants in the Los Angeles and Houston metropolitan areas now specify hood-mounted emissions monitoring as standard procurement criteria.
Buyer evaluation criteria have migrated from first-cost minimization to total cost of ownership modeling across ten-year operational horizons. Foodservice procurement teams now require energy modeling, maintenance scheduling, and end-of-life disposal cost projections from shortlisted vendors. This behavioral shift is most visible among contract foodservice management companies such as Aramark, Compass Group, and Sodexo, which standardize lifecycle analysis across their North American facility portfolios.
Industrial Hood Ventilation Market Segmentation
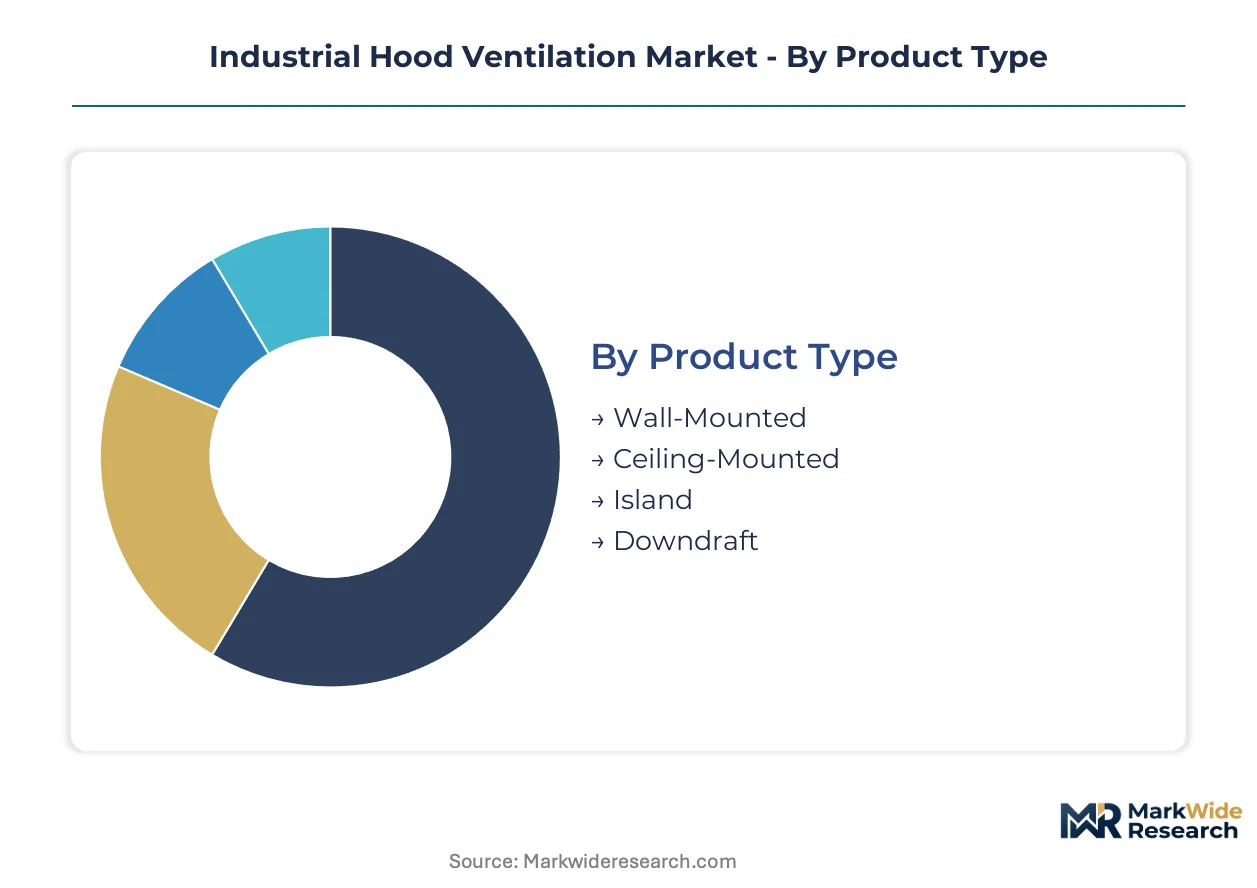
Segmentation in industrial hood ventilation reveals how specification requirements diverge across cooking intensity, regulatory exposure, and facility lifecycle stage. Procurement patterns cluster around compliance-driven replacement cycles versus greenfield capacity expansion, with technology choice increasingly dictated by municipal discharge ordinances rather than first-cost optimization.
Product Type:
Customization intensity spans from standardized wall-mounted units for constrained retrofits to architecturally integrated island configurations requiring bespoke fabrication.
- Wall-Mounted:These configurations anchor to vertical surfaces with integrated grease capture chambers and single-sided airflow capture. Demand concentrates in United States urban retrofit markets where existing ceiling infrastructure cannot support suspended loads, driven by NFPA 96 compliance mandates forcing exhaust system upgrades in aging restaurant stock.
- Island:Suspended canopy structures engineered for 360-degree capture efficiency dominate open-concept kitchen designs. Premium positioning in high-visibility restaurant concepts across California and New York commands specification of demand-controlled ventilation integration to offset elevated energy consumption from continuous perimeter airflow.
- Ceiling-Mounted:Flush integration with architectural soffits serves institutional cafeterias requiring unobstructed sightlines.
- Downdraft:Counter-level exhaust capture eliminates overhead canopy requirements for demonstration cooking stations and front-of-house exhibition kitchens.
Most installed capacity flows through Wall-Mounted configurations. Expansion is steepest in Island systems as open-kitchen restaurant concepts proliferate.
Installation Type:
Project velocity and margin structure shift dramatically across new construction versus existing facility modification, with regulatory inspection requirements lengthening timelines disproportionately for replacement work.
- New Installation:Greenfield projects allow optimized duct routing and fan sizing from architectural inception. United States restaurant chain rollouts in Texas and Florida concentrate procurement volume, with electrification mandates in California and New York forcing recalculation of thermal load profiles for induction-compatible hood specifications.
- Replacement:Equipment swap-outs triggered by NFPA 96 enforcement or insurance-mandated fire safety upgrades. Demand clusters in legacy independent restaurants across Midwestern and Southeastern states where depreciation schedules have exceeded actual equipment life, constrained by certified installer scarcity extending project timelines.
- Retrofit:Modifications to existing ductwork and capture geometry accommodate menu changes or cooking equipment replacement without full system replacement.
- Modular:Pre-engineered packaged units with standardized dimensions reduce field fabrication for cloud kitchen platforms and ghost kitchen facilities.
Replacement commands the largest revenue share by volume. Modular installations are climbing the fastest as delivery-only foodservice operators standardize specifications across multi-tenant facilities.
End User:
Contaminant chemistry and duty cycle intensity create distinct specification requirements across cooking, research, and production environments.
- Restaurants:Grease-laden vapor capture and fire suppression integration dominate specification criteria. Full-service and quick-service chains across the United States drive compliance-driven procurement, with Los Angeles and Houston metropolitan areas mandating hood-mounted emissions monitoring for particulate matter documentation.
- Laboratories:Chemical fume containment and corrosion-resistant construction take precedence over thermal management. Research institutions specify stainless steel 316 construction for acid vapor exposure, with demand concentrating in pharmaceutical and biotechnology clusters.
- Manufacturing Plants:Process-specific contaminant extraction for welding, solvent handling, or powder coating operations.
- Supermarkets:Combined cooking and refrigeration heat load management for prepared food sections.
Restaurants absorb the majority of unit shipments. Laboratories show the steepest specification escalation as research facility construction accelerates.
Technology:
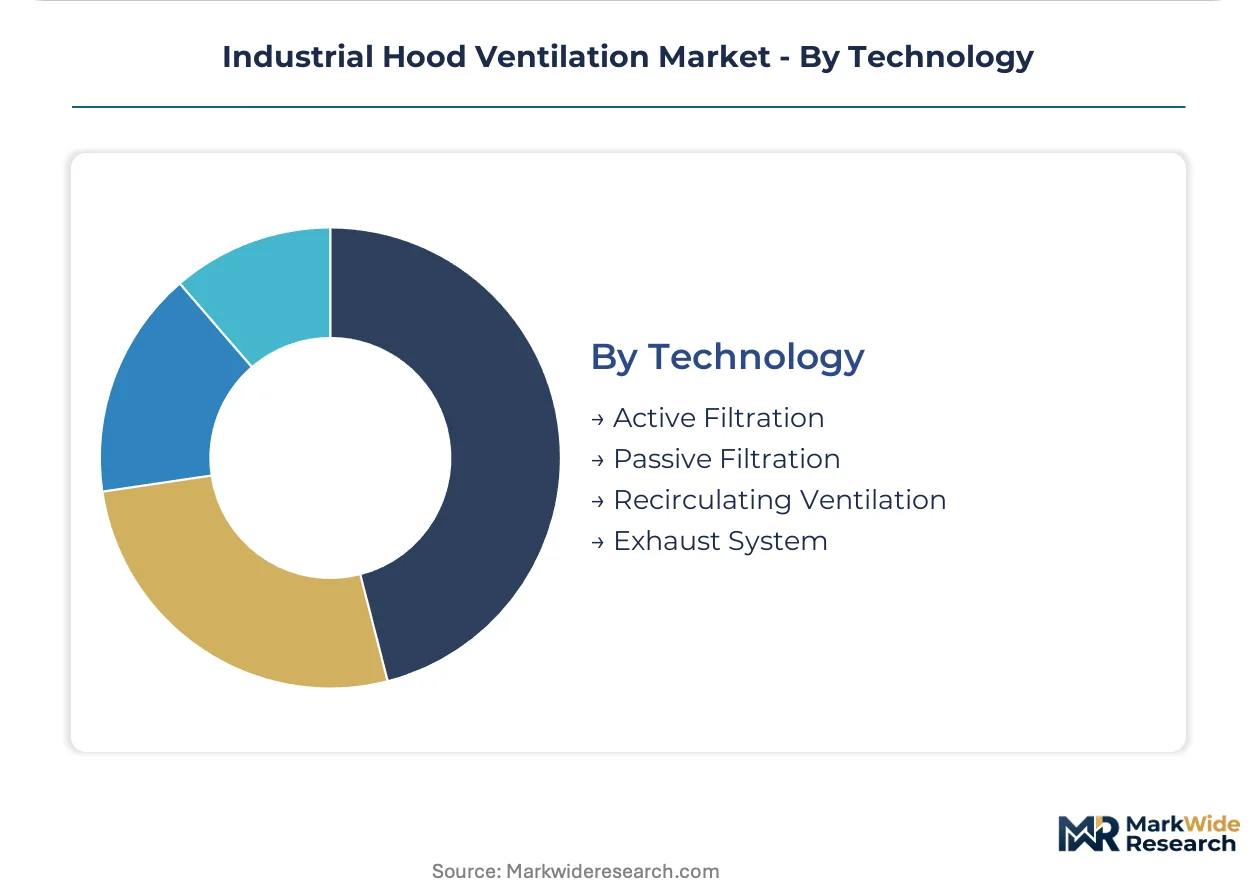
Active versus passive filtration represents the fundamental technology fork, with capital allocation shifting toward systems that reduce external ducting requirements and enable recirculating configurations.
- Active Filtration:Electrostatic precipitation and multi-stage mechanical filtration enable internal air discharge without external ductwork. Ghost kitchen operators in United States urban cores favor these systems to minimize building envelope penetrations, though weekly cleaning protocols and specialized wastewater handling raise lifecycle operating costs above passive alternatives.
- Passive Filtration:Stainless steel baffle filters rely on gravity and airflow velocity for grease separation. Dominates replacement demand in existing facilities with established duct infrastructure, particularly in secondary metropolitan markets where installer scarcity delays active filtration commissioning.
- Recirculating Ventilation:Self-contained systems with integrated filtration and air return for facilities lacking external discharge options.
- Exhaust System:Traditional ducted configurations with external fan discharge to atmosphere.
Passive Filtration retains the largest installed base. Active Filtration is gaining share fastest as municipal discharge ordinances tighten and external ducting restrictions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates compliance-driven procurement volume while Germany advances active filtration adoption through municipal discharge mandates, illustrating how regulatory stringency varies across developed markets.
United States
NFPA 96 enforcement and ASHRAE Standard 154 ventilation guidelines compel restaurant chain exhaust system upgrades. The EPA enforces commercial cooking emissions under Clean Air Act provisions, with regional administrators targeting charbroiler operations in ozone non-attainment zones. Los Angeles and Houston metropolitan areas now mandate hood-mounted emissions monitoring as standard procurement criteria.
Germany
REACH compliance and EU Green Deal decarbonization targets accelerate demand-controlled ventilation retrofits in institutional foodservice. The country's national environmental regulator enforces strict municipal discharge ordinances for commercial kitchen effluent. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate fabrication capacity for stainless steel hood assemblies serving central European markets.
China
Rapid urbanization and foodservice sector expansion drive hood ventilation installation in commercial kitchen infrastructure. GB standards and MIIT industrial guidelines establish minimum efficiency requirements for commercial cooking exhaust systems. Yangtze River Delta and Pearl River Delta manufacturing hubs supply standardized wall-mounted configurations for domestic and export markets.
Japan
METI energy efficiency programs subsidize demand-controlled ventilation integration in high-turnover restaurant concepts. JIS standards govern commercial kitchen ventilation equipment certification and performance testing. Kanto and Kansai metropolitan areas concentrate ghost kitchen facility development requiring compact active filtration solutions.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance pathways for equipment suppliers serving British and EU markets. The country's national fire safety regulator maintains grease extraction standards aligned with NFPA 96 principles. London and Southeast England concentrate contract foodservice management company procurement for standardized ventilation specifications.
Industrial Hood Ventilation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fabrication-focused entities dominating replacement volume while technology-integrated suppliers capture greenfield specification. The vendor base organizes into three tiers: captive distribution networks sustaining aftermarket revenue, specialized stainless steel fabricators with bespoke capabilities, and diversified HVAC conglomerates leveraging controls integration expertise. Consolidation pressure is mounting as software-defined airflow management displaces static mechanical controls. Strategic moves center on backward integration into stainless steel supply chains and technology licensing for demand-controlled ventilation algorithms.
Among North American specialists, Greenheck Fan Corporation and CaptiveAire Systems exemplify contrasting archetypes. Greenheck leverages its captive distribution infrastructure to anchor aftermarket service relationships across foodservice accounts. CaptiveAire occupies a position as a fabrication-centric supplier with specialized stainless steel hood assembly capabilities. Halton Group represents the technology-integrated tier, differentiating through advanced kitchen ventilation systems that merge fire suppression with demand-controlled ventilation protocols.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| CaptiveAire Systems |
| Halton Group |
| Johnson Controls |
| Honeywell International Inc. |
| Systemair AB |
| Daikin Industries |
| FläktGroup |
| Fantech |
| Others |
Supply & Pricing Matrix
Electrification mandates in California and New York gate qualified supply and premium-tier pricing access by forcing recalculation of thermal load profiles for induction-compatible hood specifications, while stainless steel input volatility compresses fabrication margins across all tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standardized wall-mounted configurations. Three-tier pricing structure across premium, standard, and economy levels separates demand-controlled ventilation integration from basic passive filtration and bare-bones replacement units. Cost compression in the economy tier is intensifying because of nickel and chromium commodity swings. Independent restaurants in secondary metropolitan markets exhibit highest price sensitivity, while contract foodservice management companies prioritize lifecycle cost modeling over first-cost minimization.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and Georgia anchor hub-and-spoke patterns for North American aftermarket parts fulfillment. Manufacturing concentrates in the United States, China, and Germany, with stainless steel 304 and 316 sheet metal drawing from South African chromium and Indonesian nickel supply. Single-source vulnerability in electrostatic precipitator cell production creates bottleneck risk for active filtration configurations. Distribution runs through captive dealer networks for branded specialists and direct-to-contractor channels for fabrication-centric suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined airflow management creates margin-expansion potential as buyers shift evaluation criteria toward ten-year total cost of ownership models, displacing pure price competition.
For Market Incumbents: Lock in aftermarket revenue streams through preventive maintenance contracts and software-enabled airflow monitoring platforms. Backward integration into stainless steel supply chains defends fabrication margins against nickel volatility, while certification investment in ASHRAE 154-2016 testing documentation accelerates project velocity against emerging controls-integrator competitors. For New Entrants and Emerging Players: NFPA 96 compliance mandates in the United States open a window for specialized commissioning expertise in BACnet and Modbus interoperability, where general HVAC contractors lack capability. Ghost kitchen facilities in urban cores present the most penetrable segment, with recirculating active filtration configurations requiring minimal external ducting expertise as the specific go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional sheet metal fabricators with NFPA 96-certified installation capabilities because certified technician scarcity creates local moats. The five-to-ten-year viability window favors targets with captive distribution infrastructure over pure manufacturing plays. Watch utility rebate program expansion from Con Edison, PG&E, and Southern California Edison as the inflection indicator for demand-controlled ventilation penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Captive supply of Grade 304 and 316 sheet metal buffers margin compression from nickel volatility. |
| Demand-Controlled Ventilation Platform Development | Software-defined airflow management displaces static mechanical controls as the primary value proposition. |
| Preventive Maintenance Contract Expansion | Recurring revenue streams from foodservice accounts rebalance customer lifetime value calculations. |
| Active Filtration Technology Licensing | Electrostatic precipitation IP enables recirculating configurations for ghost kitchen operators. |
| Utility Rebate Program Partnership | Con Edison and PG&E incentives lower customer acquisition costs for energy-efficient retrofits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with commercial kitchen operators, fire suppression technicians, sheet metal contractors, and foodservice procurement directors with secondary validation from NFPA 96 documentation, ASHRAE Standard 154 test data, EPA Clean Air Act enforcement records, and utility rebate program filings. Bottom-up equipment shipment analysis and top-down construction spending triangulation anchored market sizing.
Historical reference periods established baseline penetration rates for active versus passive filtration technologies across the projection horizon. Segmentation modeling captured product type, installation category, end-user vertical, and technology tier dimensions. CAGRs derived from equipment replacement cycle compression, electrification mandate rollout timelines, and municipal discharge ordinance adoption curves. Forecast inputs included stainless steel commodity price trajectories and certified installer pipeline expansion.
Revisions become necessary when electrification mandates accelerate beyond modeled adoption curves or when nickel and chromium price spikes exceed historical volatility bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Roof Vents Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Freeze and Thaw Systems Market