
 Malaysia Building Thermal Insulation Material Market | 2026-2036
Malaysia Building Thermal Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Building Thermal Insulation Material Market Outlook
Green building certification-grade thermal performance is redrawing competitive dynamics in Malaysia's insulation sector. Rockwool International A/S anchors its position through mineral wool specialization suited to tropical humidity and fire-safety specifications. Kingspan Group leverages its rigid insulation manufacturing scale to serve commercial facade projects across Penang and Johor. Saint-Gobain differentiates through integrated glass wool and gypsum systems that simplify contractor procurement.
Malaysia building thermal insulation material encompasses engineered barriers designed to reduce conductive heat flow, typically quantified by thermal conductivity values ranging from 0.022 to 0.040 W/m·K depending on core chemistry, and manufactured through foaming, melting-spinning, or extrusion processes to stabilize indoor temperatures in tropical climates. These materials primarily serve to lower air-conditioning energy loads in commercial and residential envelopes where cooling dominates operational expenditure. Rigid insulation and spray foam command expanding share in high-performance commercial envelopes where space constraints and airtightness targets intensify. Mineral wool and polyurethane segments split along fire-resistance versus thermal-efficiency priorities, with margin pools concentrating in specification-grade polyurethane systems for industrial cold-chain facilities.
BIS-equivalent standards through Malaysia's Department of Standards Malaysia (DSM), CIDB's construction quality assessments, and Green Building Index criteria collectively mandate minimum thermal resistance values and material traceability for public projects. Compliance with these frameworks shapes product certification costs and factory audit schedules for both domestic producers and importers. Stakeholders must monitor how impending alignment with ASEAN harmonized standards reshapes test protocol equivalency and cross-border material acceptance.
Market Dynamics
Malaysia's Green Building Index certification mandates and CIDB energy efficiency codes are compressing specification timelines, forcing insulation suppliers to pre-certify products before project tendering rather than retrofitting compliance post-award.
Growth Catalysts
- Green Building Index certification:Mandatory thermal performance thresholds for new commercial developments in Kuala Lumpur and Penang are accelerating specification-grade mineral wool and polyurethane procurement from domestic distributors.
- Industrial zone expansion:Mega infrastructure corridors in the Klang Valley are driving bulk material offtake for cold-chain facilities requiring high-R-value rigid insulation systems.
- Polyurethane spray foam:Airtightness targets in high-rise envelopes are displacing conventional batt insulation with applied foam systems that eliminate thermal bridging at structural joints.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane core chemistry depends on MDI and polyol inputs priced against regional naphtha benchmarks, compressing margin stability for domestic blenders.
- Import concentration:Premium-grade glass wool and specialty foams concentrate in supply chains routed through Singaporean distribution hubs, exposing projects to port congestion risk.
- Fire-resistance trade-offs:High-efficiency polyurethane systems face substitution pressure from mineral wool in vertical shafts and egress corridors where BS 476 fire ratings are mandatory.
Strategic Opportunities
- Johor Bahru corridor:Underpenetrated industrial construction in Iskandar Malaysia presents white space for cold-storage insulation specialists targeting food logistics hubs.
- Integrated facade systems:Convergence of rigid insulation with prefabricated curtain wall modules allows suppliers to capture value upstream from pure material sales.
- CIDB Green Card incentives:Contractor accreditation bonuses for sustainable material specification create a procurement channel that rewards certified thermal performance documentation.
Industry Challenges
- Certification timeline compression:DSM-equivalent testing protocols for imported materials extend factory audit schedules by eight to twelve weeks, delaying project mobilization.
- Applicator skill scarcity:Spray foam installation quality depends on certified technician density that lags demand growth in secondary cities like Ipoh and Malacca.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Building Thermal Insulation Material Market |
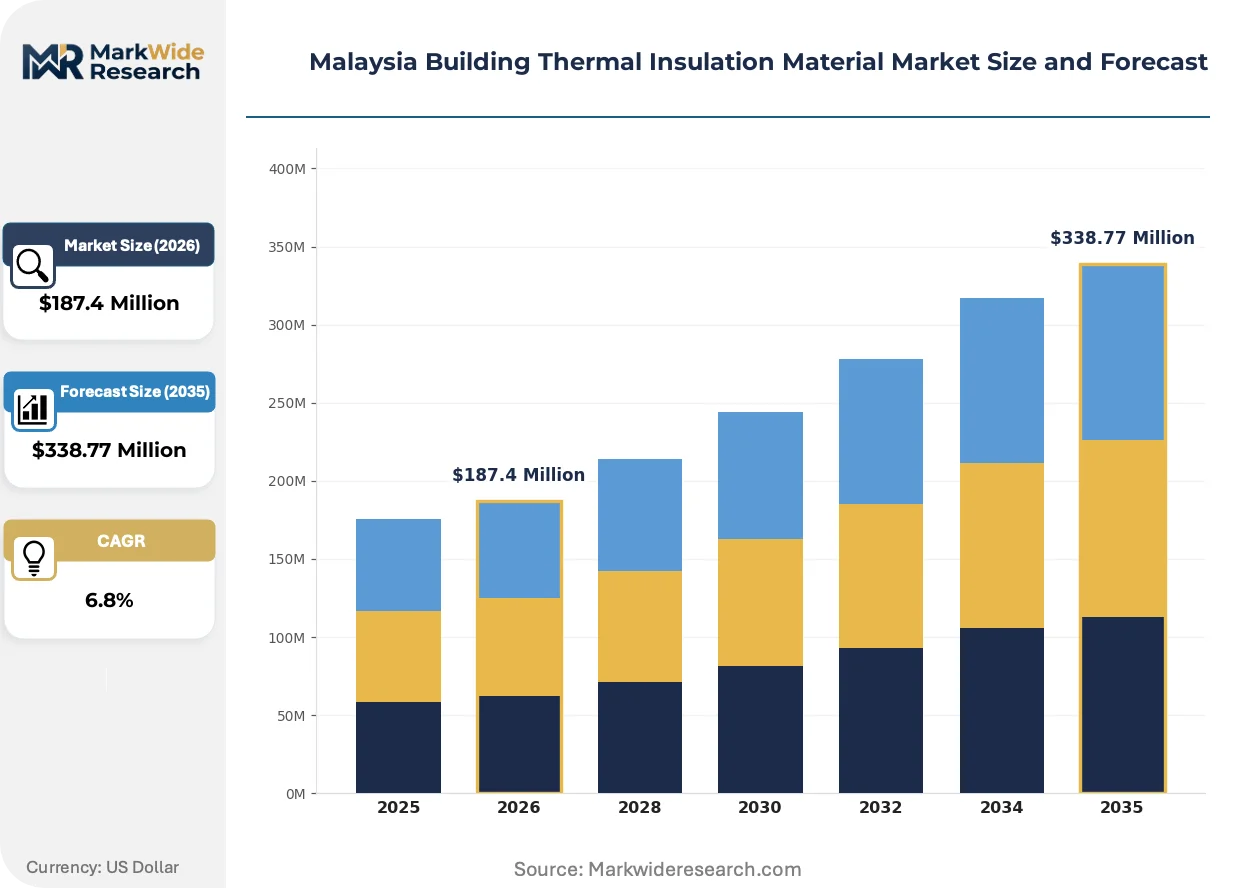
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Board, Batts, Spray Foam, Rigid Insulation Application: Exterior Walls, Roofs, Floors, HVAC Systems Material: Polyurethane, Polystyrene, Fiberglass, Mineral Wool End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Recticel Group, GAF Materials LLC, Rockwool International A/S, Owens Corning, URSA Insulation, BASF SE, Johns Manville, Saint-Gobain, Kingspan Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Building Thermal Insulation Material Market Strategic Shifts
Vacuum insulation panels and aerogel composites are penetrating high-value building envelopes where space constraints override cost sensitivity, while digital specification tools compress the material selection cycle for consulting engineers.
Aerogel-enhanced blanket systems are miniaturizing thermal protection layers in retrofitted heritage structures across Georgetown and Kuala Lumpur's colonial core, where conservation guidelines prohibit envelope thickening. Conservation architects specify these silica-based materials at three to five times conventional insulation cost to preserve floor-to-ceiling dimensions. The technology is miniaturizing the physical footprint of high-performance envelopes, enabling R-values previously requiring 150mm mineral wool in sub-40mm assemblies.
Malaysia's Department of Standards Malaysia is aligning thermal resistance test protocols with ASEAN harmonized standards, creating equivalency recognition for Singaporean and Thai certification bodies. This regulatory convergence reduces duplicate testing costs for regional suppliers but imposes new documentation burdens on Chinese imports lacking ASEAN-accredited laboratory reports. Johor-based distributors with cross-border warehousing capabilities are capturing share from direct-import channels by pre-positioning certified inventory.
Engineering consultants are unbundling material specification from turnkey contractor procurement, creating direct relationships with insulation manufacturers for performance-guaranteed envelope design. This disintermediation compresses distributor margins in commercial high-rise segments while rewarding technical service capabilities. Penang's design-build firms are most exposed to this shift, as developer clients increasingly retain independent envelope consultants through Green Building Index registration processes.
Malaysia Building Thermal Insulation Material Market Segmentation
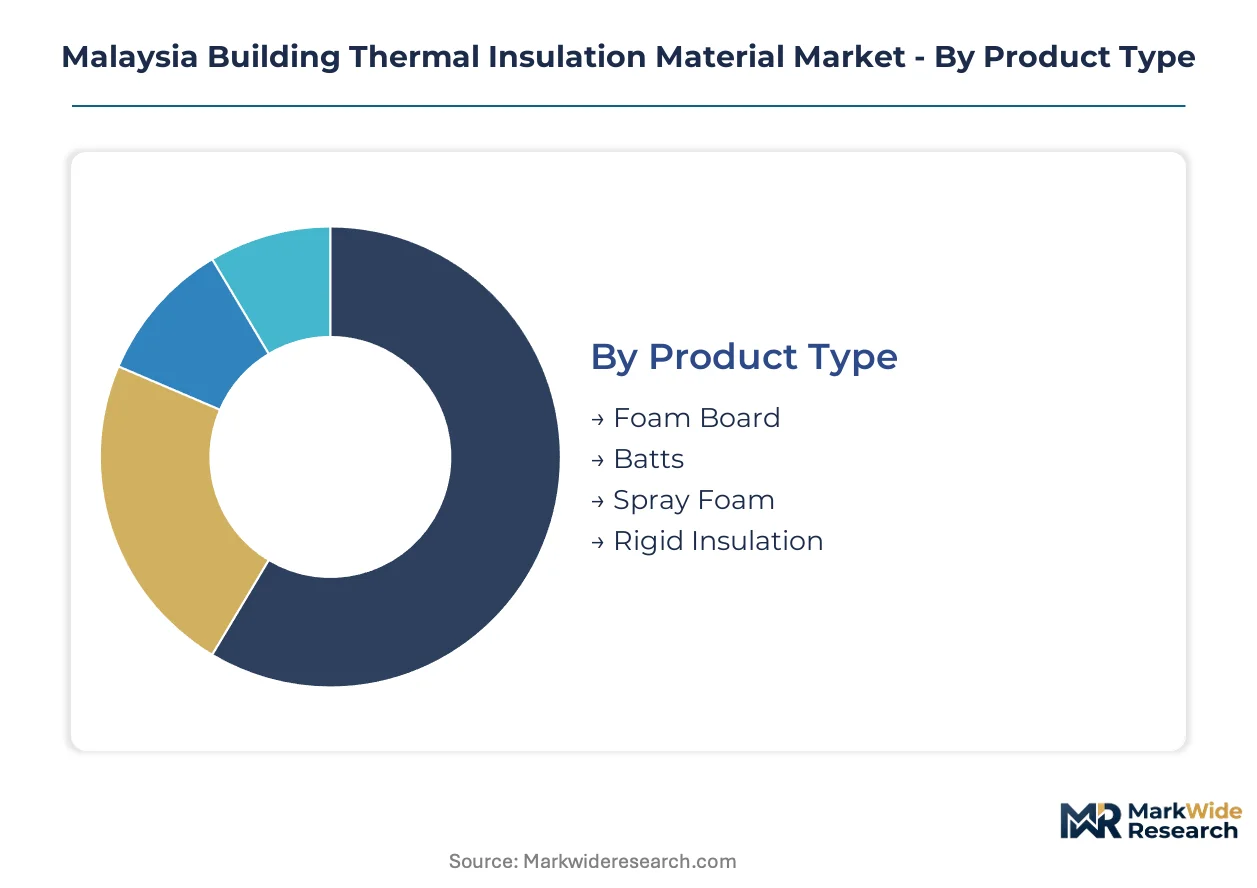
Malaysia's tropical climate and Green Building Index mandates create distinct procurement patterns across insulation formats. Specification-grade products flow through certified distributor networks, while commodity grades concentrate in project-direct channels serving volume construction.
Product Type:
Distributor stocking patterns split between specification-grade rigid systems and contractor-direct spray foam, with inventory turns varying sharply by format complexity.
- Foam Board:Extruded polystyrene and polyiso cores dominate commercial facade specifications across Kuala Lumpur high-rises. Klang Valley distributors maintain 30-45 day inventory cycles for standard dimensions, with custom thicknesses routed through Singaporean hubs.
- Spray Foam:Closed-cell polyurethane systems command premium positioning in airtightness-critical envelopes. Penang and Johor applicator networks are expanding technician certification to match developer demand for continuous insulation layers.
- Batts:Glass and mineral wool rolls serve residential pitched-roof segments through hardware retail channels. CIDB Green Card contractors specify certified thermal resistance values for public housing projects.
- Rigid Insulation:High-compressive-strength boards target cold-chain flooring and industrial envelope applications. Iskandar Malaysia logistics hubs are driving specification of moisture-resistant facings.
By volume, Foam Board leads. By growth pace, Spray Foam is expanding most quickly.
Application:
End-use concentration varies by building typology, with commercial envelopes demanding multi-layer systems and residential projects optimizing for installation speed.
- Exterior Walls:Curtain wall cavities and rainscreen assemblies specify rigid insulation with fire-rated facings. Georgetown heritage retrofits are accelerating demand for thin-profile vacuum panels where floor space is constrained.
- Roofs:Inverted membrane assemblies with extruded polystyrene dominate flat-roof commercial stock. Industrial zone expansions in Shah Alam require high-R-value systems for process cooling efficiency.
- Floors:Ground-contact and suspended slab applications favor moisture-resistant foam boards. Cold-storage facilities in Johor Bahru specify load-bearing insulation for rack-supported mezzanines.
- HVAC Systems:Ductwork and equipment insulation concentrates in glass wool and elastomeric foam. Green Building Index-registered projects mandate thermal bridging mitigation at pipe penetration points.
Exterior Walls capture the largest material tonnage. HVAC Systems show the steepest specification-grade margin expansion.
Material:
Feedstock exposure and fire-performance trade-offs segment supplier portfolios between petrochemical-based and inorganic mineral systems.
- Polyurethane:Spray and rigid board formats deliver the highest thermal resistance per unit thickness. MDI price volatility compresses blender margins, driving long-term supply contracts with regional polyol distributors.
- Polystyrene:Expanded and extruded grades serve cost-optimized residential and commercial applications. Fire-retardant additives are tightening under Department of Standards Malaysia protocol alignment with ASEAN standards.
- Fiberglass:Melt-spun glass wool dominates batt and loose-fill segments. Malaysian manufacturing capacity concentrates in Johor with imported boron and silica feedstocks.
- Mineral Wool:Basalt and slag-based fibers command fire-critical vertical shafts and industrial envelopes. Rockwool International's domestic production anchors supply security for BS 476-rated specifications.
Polystyrene leads by installed square meters. Polyurethane claims the highest value per thermal unit delivered.
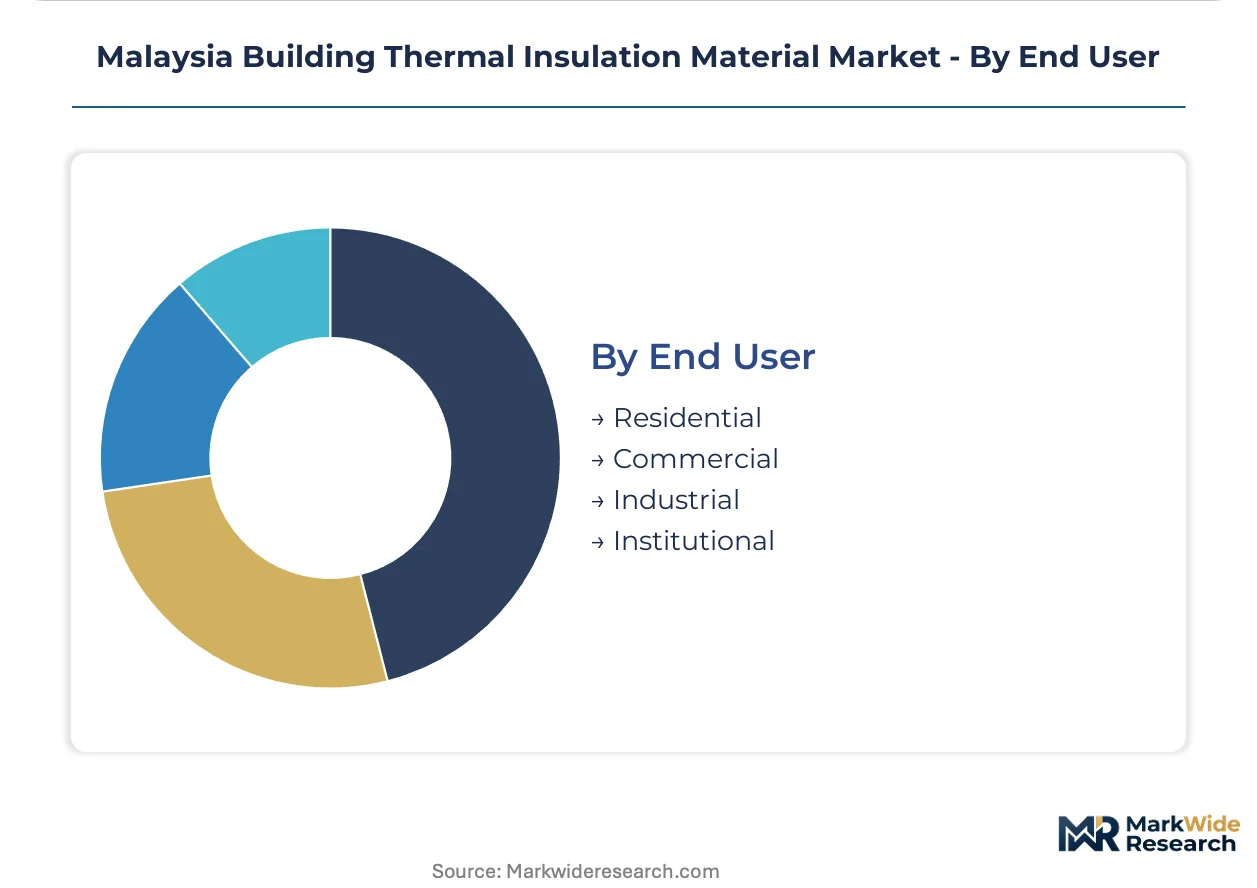
End User:
Procurement sophistication escalates from residential retail channels to institutional tender processes with embedded performance guarantees.
- Commercial:High-rise offices and retail complexes specify through Green Building Index-registered consultants. Kuala Lumpur's TRX and Bandar Malaysia developments are consolidating envelope design under performance-contracting arrangements.
- Industrial:Cold-chain, pharmaceutical, and electronics manufacturing demand precision thermal control. Penang's Batu Kawan industrial park is expanding specification-grade rigid insulation offtake for cleanroom envelopes.
- Residential:Single-family and high-rise apartments prioritize installed cost over thermal performance. Developer bulk procurement concentrates in Klang Valley greenfield townships.
- Institutional:Hospitals, universities, and government facilities mandate CIDB-certified materials with full traceability. Public Works Department projects require DSM-equivalent test documentation for imported products.
Commercial segment leads by project value. Industrial applications are climbing the fastest on cold-chain infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Material supply for Malaysia's insulation sector concentrates in Johor Bahru's manufacturing corridor and Singaporean distribution hubs serving the Klang Valley. Regional procurement patterns split between domestic mineral wool production and imported polyurethane systems routed through ASEAN trade channels.
Klang Valley
Commercial high-rise construction in Kuala Lumpur and Petaling Jaya drives specification-grade rigid insulation procurement. The Ministry of Housing's energy efficiency codes mandate minimum thermal resistance values for new developments. The Tun Razak Exchange and Bandar Malaysia mega-projects are consolidating envelope design under performance-contracting arrangements with certified distributors.
Penang
Industrial zone expansion in Batu Kawan and Bayan Lepas accelerates demand for cold-chain facility insulation. Green Building Index certification requirements tighten thermal performance thresholds for pharmaceutical manufacturing envelopes. Georgetown heritage retrofits specify vacuum insulation panels where conservation guidelines prohibit structural modifications.
Johor Bahru
Iskandar Malaysia logistics hubs drive bulk material offtake for food processing and electronics manufacturing facilities. CIDB Green Card incentives reward contractors specifying certified thermal performance documentation. Pasir Gudang industrial zones anchor domestic mineral wool production serving fire-rated vertical shaft specifications.
Singapore
Premium-grade glass wool and specialty foam imports concentrate in distribution chains routed through Singaporean ports. ASEAN harmonized standards alignment creates equivalency recognition for Singaporean certification bodies. Port congestion risks expose Klang Valley projects to delivery delays during peak construction windows.
Malaysia Building Thermal Insulation Material Market Competitive Environment
Concentration sits with multinational material specialists and domestic distributors holding Green Building Index pre-certification. The market structure tiers between specification-grade suppliers serving commercial high-rises and commodity distributors targeting residential volume construction. Two strategic archetypes dominate: mineral wool specialists leveraging fire-safety credentials and polyurethane blenders optimizing thermal efficiency per unit thickness. Competitive moves center on pre-certification investments compressing tender timelines and cross-border warehousing capabilities reducing import lead times.
Among European-headquartered specialists, Rockwool International A/S and Saint-Gobain exemplify the mineral wool archetype with tropical humidity-resistant formulations. Kingspan Group occupies a position on the rigid insulation vector serving commercial facade projects. These three anchors illustrate how fire-performance specialization and manufacturing scale split competitive positioning in specification-grade procurement channels.
| Leading Market Players |
|---|
| Recticel Group |
| GAF Materials LLC |
| Rockwool International A/S |
| Owens Corning |
| URSA Insulation |
| BASF SE |
| Johns Manville |
| Saint-Gobain |
| Kingspan Group |
| Others |
Value Chain & Pricing Dynamics
Mineral wool substitution for polyurethane in fire-rated vertical shafts is redrawing procurement geography across Malaysia's insulation sector, compressing margins for petrochemical-dependent blenders while elevating pricing power for domestic basalt-fiber producers in Johor's Pasir Gudang corridor.
Pricing Analysis
Green Building Index certification dictates the pricing tier structure across Malaysia's thermal insulation market. Three-tier pricing structure across specification-grade, certified-standard, and commodity-economy levels separates Green Building Index-registered projects from CIDB-compliant public housing and unregulated residential volume construction. Cost compression in polyurethane spray foam is intensifying because MDI and polyol feedstock volatility erodes blender margins against fixed-price mineral wool contracts. Residential developers in Klang Valley greenfield townships exhibit the highest price sensitivity, while pharmaceutical manufacturers in Penang's Batu Kawan industrial park prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
Port congestion at Singapore's PSA terminals and container availability constraints on the China-Singapore-Klang Valley trade lane are extending lead times for premium-grade glass wool and specialty polyurethane systems. Geographic supply concentration centers on Malaysia's domestic mineral wool production, Singaporean distribution hubs for imported foams, and Chinese manufacturing for polystyrene feedstocks. Raw material dependencies rest on regional naphtha benchmarks for polyurethane chemistry, imported borosilicate glass for fiberglass production, and slag from Penang's steel processing for mineral wool. Single-source vulnerability concentrates in MDI supply chains routed through Singaporean petrochemical traders. Distribution runs through certified distributor networks for specification-grade products and project-direct channels for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's building thermal insulation material market sits in a cyclical recovery phase anchored to infrastructure investment cycles in the Klang Valley and Iskandar Malaysia corridors.
For Market Incumbents: Compound defensive positioning through backward integration into MDI and polyol supply contracts with Singaporean petrochemical distributors, insulating margin stability against feedstock volatility. Expand certified technician training academies in Ipoh and Malacca to capture spray foam installation quality premiums before regional competitors replicate competency density. Mineral wool specialists should deepen fire-safety certification portfolios as polyurethane faces substitution pressure in vertical shaft applications. For New Entrants and Emerging Players: Green Building Index certification fast-tracking through pre-positioned DSM-equivalent test documentation opens tender participation for Johor Bahru cold-chain logistics hubs where incumbent coverage remains thin. Target underpenetrated industrial construction in Iskandar Malaysia's food processing zones with rigid insulation systems optimized for moisture-resistant flooring specifications. Establish cross-border warehousing in Singapore to compress delivery timelines against direct-import competitors exposed to port congestion. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors distributors with integrated certification capabilities and regional warehousing footprints. Long-term viability hinges on exposure to specification-grade procurement channels rather than commodity residential volume. Acquisition targets should demonstrate Green Building Index pre-certification density and established relationships with independent envelope consultants. Monitor CIDB Green Card incentive expansion as an inflection indicator for sustainable material procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | MDI and polyol supply contracts with Singaporean distributors insulate polyurethane blenders from regional naphtha volatility. |
| Certified Technician Training Academy Expansion | Spray foam installation quality depends on technician density that lags demand growth in secondary Malaysian cities. |
| Cross-Border Warehousing in Singapore | Pre-positioned inventory captures share from direct-import channels exposed to PSA terminal congestion risks. |
| Green Building Index Pre-Certification Investment | Pre-certified products compress tender timelines against competitors requiring eight-to-twelve-week factory audit schedules. |
| Integrated Facade System Development | Convergence with prefabricated curtain wall modules allows upstream value capture from pure material sales. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of DSM technical standards, CIDB construction quality assessments, Green Building Index certification databases, and ASEAN harmonized standards documentation. Primary interviews engaged envelope consultants specifying for TRX and Bandar Malaysia developments, procurement directors at Klang Valley commercial contractors, plant managers at Johor mineral wool production facilities, and distribution channel partners in Penang and Singapore. Secondary validation drew from Department of Standards Malaysia protocol alignments, customs and trade flow data, and construction project development databases. Bottom-up volume estimates triangulated against top-down market sizing from certified distributor network coverage.
Segmentation dimensions modeled span product type, application, material chemistry, and end-user procurement sophistication across the analysis window. Value projections incorporate thermal conductivity performance tiers, fire-resistance rating requirements, and certification cost burdens. CAGRs were derived from installer capacity expansion rates, green building registration trajectories, and industrial zone development pipelines. Forecast inputs include MDI price volatility assumptions and ASEAN standards harmonization timelines.
Decision-makers should treat outputs as directional under assumptions of continued Green Building Index mandate enforcement and stable ASEAN trade lane access; material deviation would warrant model refresh. Specific risks that could revise projections include abrupt petrochemical feedstock price spikes, port congestion extending beyond Singaporean hubs, or delays in ASEAN standards equivalency recognition. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Marine HVAC Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Residential Hydronic Underfloor Heating Market