
 Global HVAC Controls Market | 2026-2036
Global HVAC Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Global HVAC Controls Market Outlook
Aftermarket service revenue is rewriting margin capture across the Global HVAC Controls Market. Johnson Controls International plc leverages its direct channel presence to sustain recurring commissioning contracts. Schneider Electric SE anchors its profitability through software-enabled predictive maintenance subscriptions. Siemens AG competes by extending digital twin integration from design through operational phases.
HVAC controls encompass electromechanical and electronic devices that regulate temperature, humidity, airflow, and refrigerant pressure through programmable logic, typically operating across 24V AC or low-voltage DC signal ranges with BACnet, Modbus, or LonWorks communication protocols. These systems serve primarily to optimize energy consumption, maintain indoor environmental quality, and extend mechanical equipment life in conditioned spaces. Smart technology segments now command the fastest expansion as cloud-connected controllers enable real-time optimization and utility demand-response participation. Wireless deployments are displacing wired infrastructure in retrofit applications where conduit replacement proves cost-prohibitive. Sensors represent a concentrated margin pool as multi-parameter indoor air quality units integrate CO2, VOC, and particulate detection into single hardware platforms.
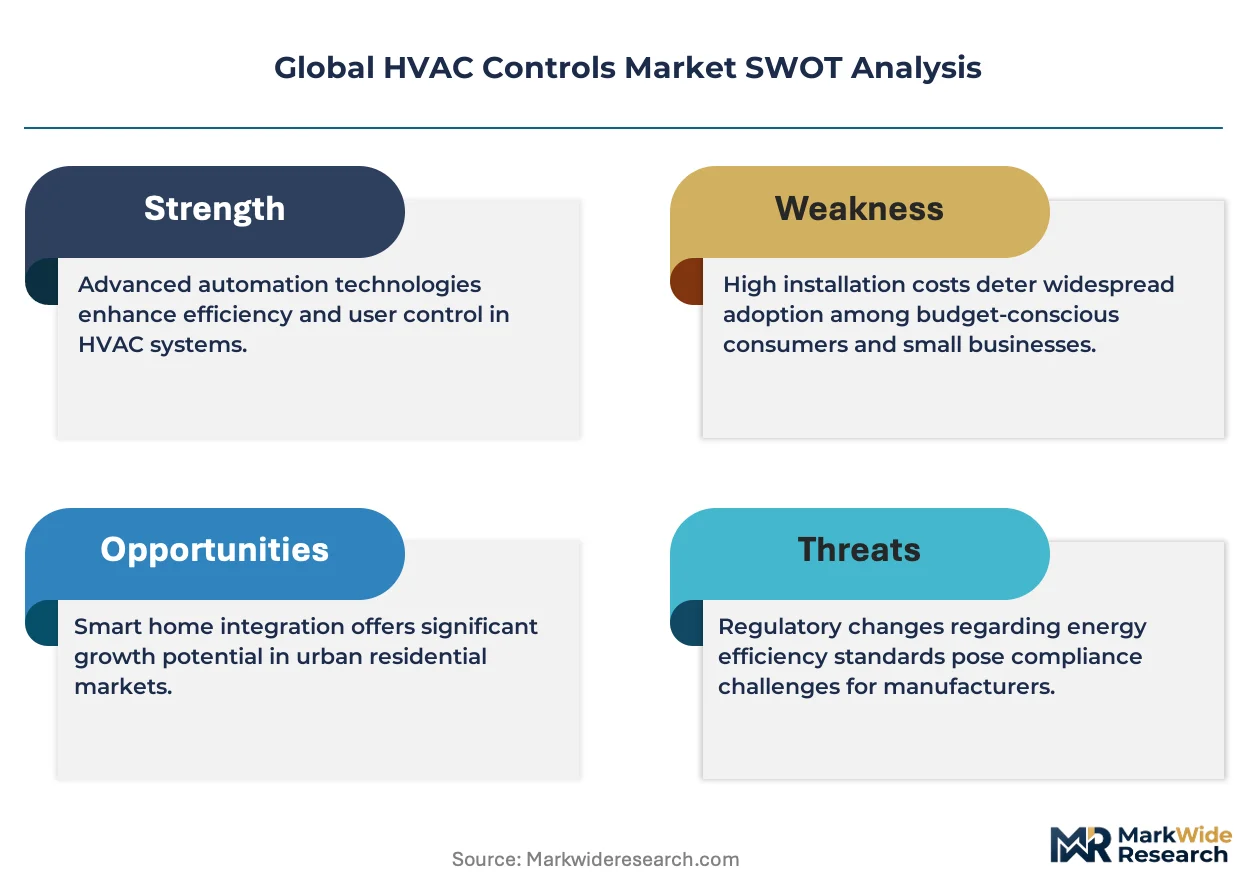
The US Department of Energy enforces minimum efficiency standards through FERC-aligned regional grid operators, while the EU Green Deal and F-Gas Regulation compel refrigerant transition planning that reshapes control system specifications across European installations. China's MIIT publishes GB standards for building energy management systems that dictate interoperability requirements for imported controllers. Stakeholders must monitor evolving cybersecurity mandates for operational technology networks as regulatory bodies in multiple jurisdictions draft certification requirements for connected building infrastructure.
Market Dynamics
Wireless BACnet protocols and edge-computing sensors are displacing legacy wired architectures across commercial and institutional installations. Building operators in Germany and Singapore face tightening energy performance mandates that accelerate control system refresh cycles.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation compel refrigerant transition planning that reshapes control system specifications across European installations.
- Smart thermostat deployments:Commercial building operators in Germany and Singapore are expanding smart thermostat deployments under tightening energy performance mandates.
- Retrofit corridors:Demand concentrates in retrofit-intensive urban corridors across the United States, Japan, and the United Arab Emirates.
Market Restraints
- Copper and semiconductor input costs:Volatility in copper pricing and semiconductor availability compresses hardware margins for controller manufacturers.
- Legacy system interoperability:Technical limitations in bridging proprietary legacy protocols with open standards delay upgrade timelines in existing buildings.
- Cybersecurity certification friction:Evolving cybersecurity mandates for operational technology networks create regulatory friction as multiple jurisdictions draft certification requirements.
Strategic Opportunities
- India's building energy codes:Underpenetrated Indian commercial real estate offers white space as BIS and CEA strengthen enforcement of building energy management standards.
- Digital twin convergence:Technology convergence between building information modeling and real-time operational data creates new service revenue streams.
- Predictive maintenance subscriptions:Software-enabled service contracts represent a channel innovation displacing traditional break-fix service models.
Industry Challenges
- BACnet/IP certification timelines:Extended testing and certification cycles for cybersecurity-hardened controllers delay product launches.
- Legacy integration complexity:Integration complexity with pneumatic and proprietary legacy systems consumes disproportionate engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HVAC Controls Market |
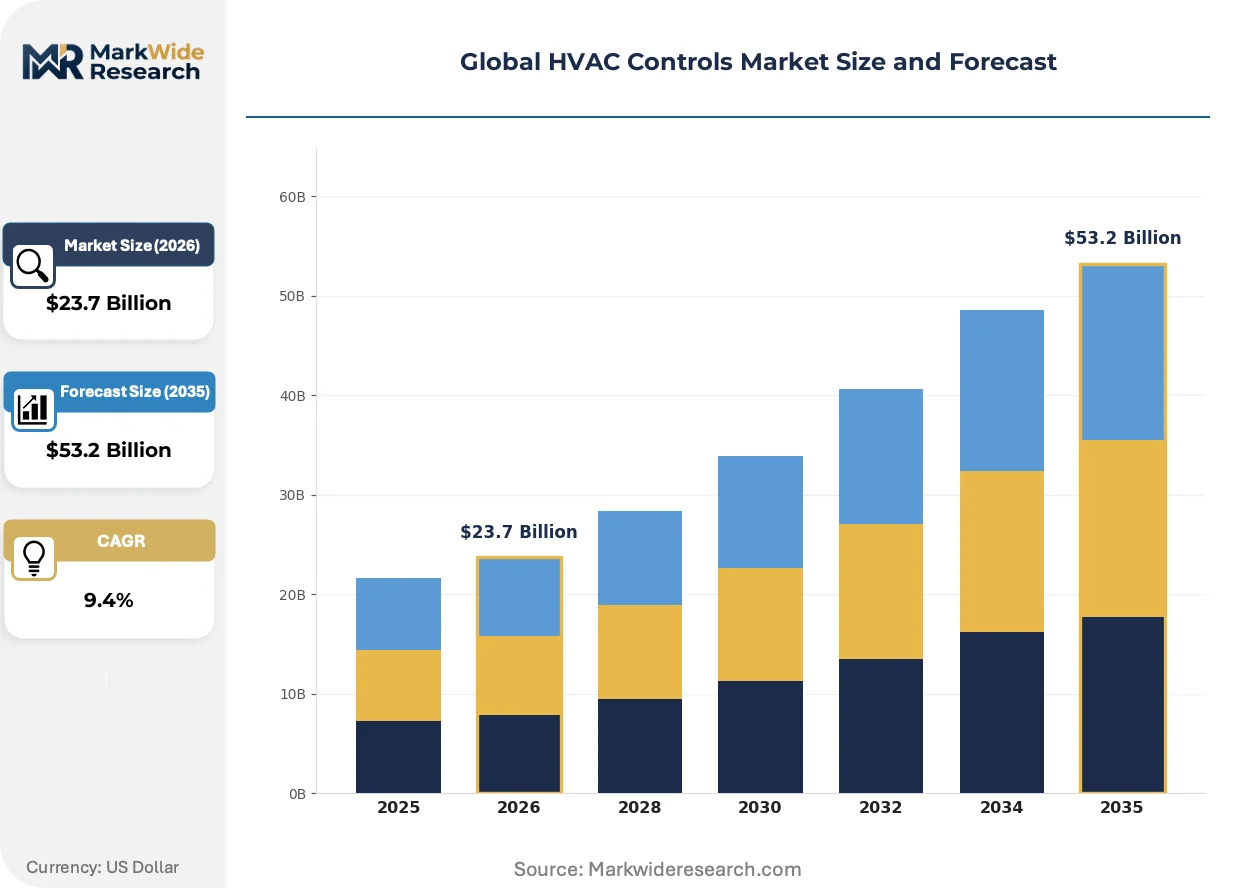
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Sensors, Actuators, Controllers Technology: Wireless, Wired, Smart, Analog End User: Commercial Buildings, Industrial Facilities, Residential Homes, Educational Institutions Application: Heating, Ventilation, Air Conditioning, Refrigeration |
| Companies Covered | Siemens AG, ABB Ltd, Johnson Controls International plc, Trane Technologies, Carrier Global Corporation, Honeywell International Inc., Emerson Electric Co., Delta Controls Inc., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HVAC Controls Market Strategic Shifts
Cloud-connected controllers and multi-parameter sensors are compressing the traditional separation between HVAC hardware and building management software. The market is witnessing rapid convergence of operational technology and information technology stacks.
Edge-computing sensor platforms is hybridizing data processing architectures by distributing analytics load away from central servers. Large commercial landlords in the United States are adopting these platforms to reduce latency in demand-response events. This hybridization is compressing the value capture of traditional building automation system gateways.
The EU F-Gas Regulation is forcing refrigerant transition planning that mandates leak detection and monitoring capabilities in control system specifications. Equipment manufacturers must redesign sensor suites to accommodate new refrigerant chemistries. European commercial refrigeration and chiller segments are responding by accelerating replacement of fixed-gas detectors with connected multi-refrigerant units.
Buying patterns among facility managers are compressing specification cycles as energy performance contracting displaces capital procurement. Third-party energy service companies are capturing decision authority previously held by mechanical contractors. This shift is most visible in German and Singaporean commercial office markets where performance guarantees dominate new construction.
Global HVAC Controls Market Segmentation
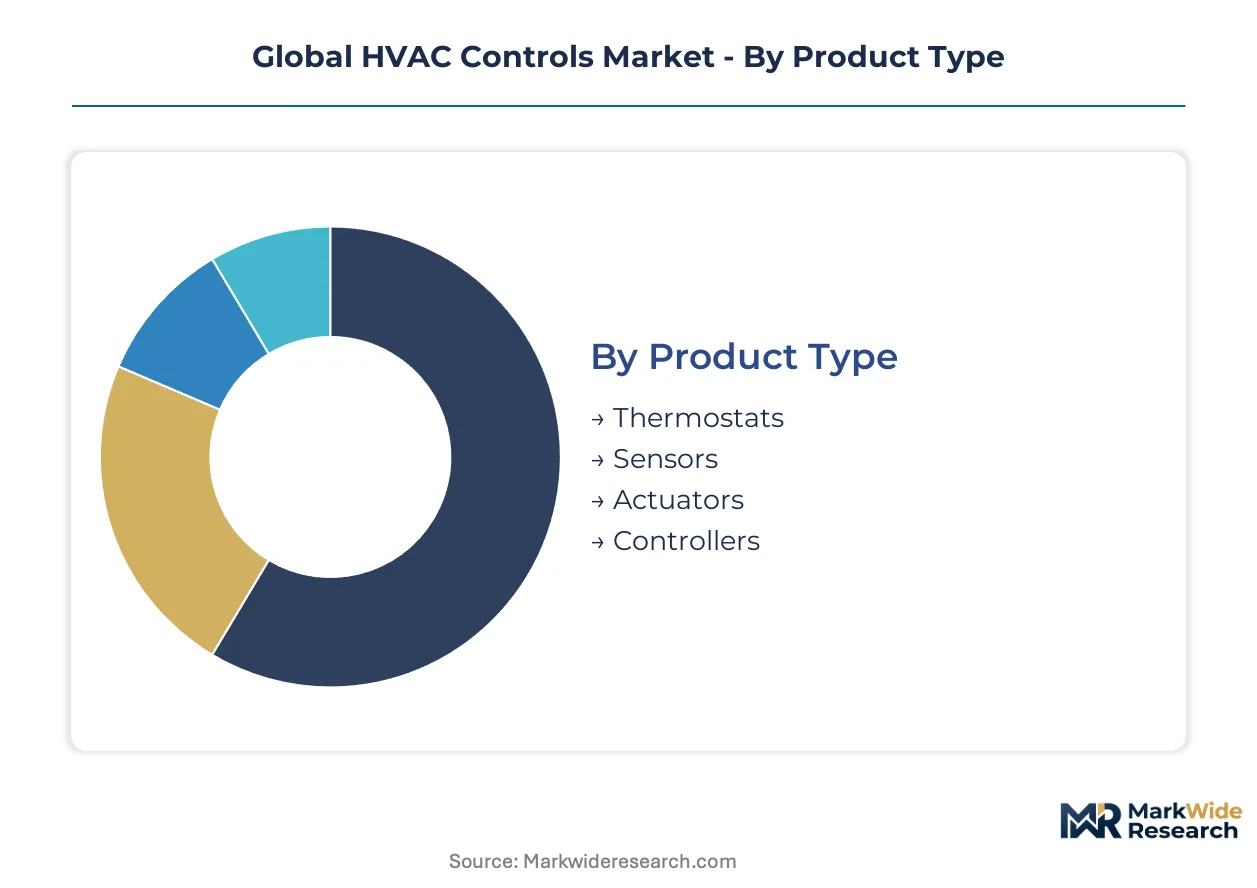
HVAC controls manufacturers engineer product portfolios around distinct margin architectures. After-sales service intensity varies sharply across product categories, with controllers demanding sustained commissioning support while sensors generate recurring calibration revenue. Technology and end-user segmentation further stratifies profitability through software subscription attach rates and retrofit cycle frequencies.
Product Type:
Controllers and sensors command the highest after-sales service intensity as building operators seek continuous optimization and predictive maintenance contracts.
- Controllers:Programmable logic devices orchestrate multi-zone temperature, humidity, and pressure regulation through BACnet, Modbus, or LonWorks protocols. Demand concentrates in German and Singaporean commercial offices where energy performance contracting mandates drive replacement cycles. These units anchor recurring commissioning revenue streams for system integrators.
- Sensors:Multi-parameter indoor air quality units integrate CO2, VOC, and particulate detection with refrigerant leak monitoring for F-Gas compliance. Japanese and UAE retrofit corridors show accelerating procurement of wireless edge-computing sensor platforms that compress traditional gateway value capture.
- Thermostats:Electromechanical and electronic temperature regulation devices span programmable, smart, and basic configurations.
- Actuators:Motorized valve and damper positioning components translate control signals into mechanical airflow adjustments.
Controllers hold the largest share; momentum sits with sensors.
Technology:
Cost tier stratification separates premium smart systems from economy analog installations, with wireless deployments commanding retrofit premiums.
- Smart:Cloud-connected controllers enable real-time optimization, utility demand-response participation, and digital twin integration. US commercial landlords adopt these platforms most aggressively to reduce latency in grid events.
- Wireless:BACnet/IP and proprietary radio protocols displace wired infrastructure where conduit replacement proves cost-prohibitive. German building operators under EU Green Deal mandates favor wireless retrofit paths to avoid facade disruption.
- Wired:Traditional 24V AC and low-voltage DC signal architectures persist in new construction with integrated conduit pathways.
- Analog:Basic electromechanical control devices serve cost-sensitive residential and small commercial applications.
Smart technology commands premium pricing; wireless is expanding most quickly.
End User:
Customer type determines procurement authority structure, with commercial buildings shifting toward energy service company intermediation.
- Commercial Buildings:Office, retail, and hospitality facilities drive specification cycles as third-party energy service companies capture decision authority previously held by mechanical contractors. This shift dominates German and Singaporean markets where performance guarantees structure new construction.
- Industrial Facilities:Manufacturing and process environments demand ruggedized controllers with extended temperature ranges and washdown ratings.
- Residential Homes:Single-family and multi-family dwellings favor DIY-installable smart thermostats with utility rebate eligibility.
- Educational Institutions:K-12 and university campuses prioritize interoperability with legacy pneumatic systems and extended warranty terms.
Commercial buildings represent the deepest revenue pool; industrial facilities show the steepest expansion trajectory.
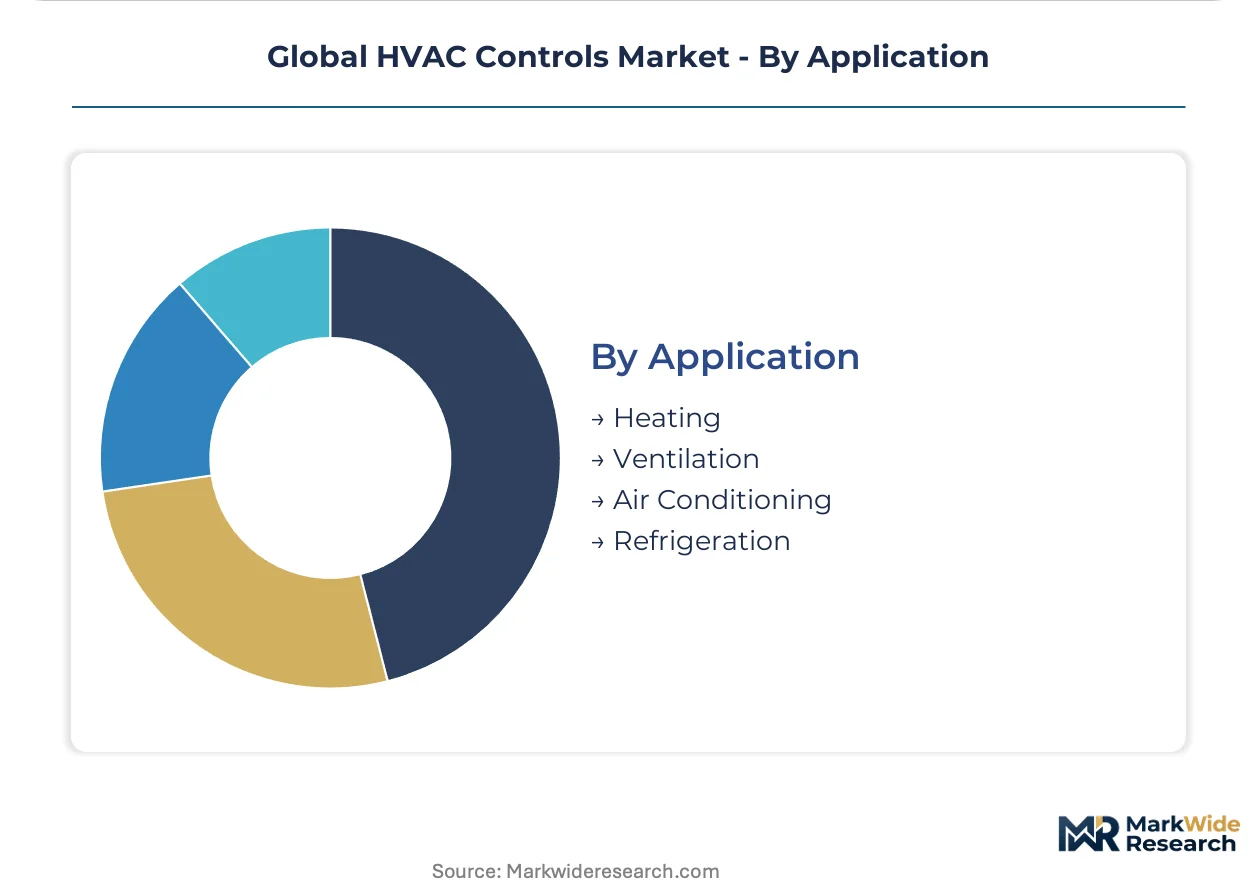
Application:
Application segmentation tracks refrigerant transition pressures and ventilation code evolution across jurisdictions.
- Air Conditioning:Chiller and packaged unit controls face redesign pressure from EU F-Gas Regulation mandates for leak detection and new refrigerant chemistry accommodation.
- Ventilation:Demand-controlled ventilation systems with CO2 sensing dominate post-pandemic indoor air quality upgrades in US and Japanese commercial corridors.
- Heating:Boiler and heat pump regulation devices integrate with district heating networks in Northern European installations.
- Refrigeration:Commercial refrigeration controls accelerate replacement of fixed-gas detectors with connected multi-refrigerant units under European regulatory pressure.
Air conditioning maintains the largest installed base; ventilation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller manufacturing clusters in Germany, the United States, and Japan concentrate supply capacity for premium BACnet/IP systems. Demand-side procurement concentrates in retrofit-intensive urban corridors where energy performance mandates accelerate replacement cycles.
United States
Commercial landlords in New York, Chicago, and Los Angeles deploy edge-computing sensor platforms to reduce latency in FERC-aligned demand-response events. The US Department of Energy enforces minimum efficiency standards through regional grid operators that reshape control specifications. Retrofit demand concentrates in Sun Belt metros where aging infrastructure meets utility rebate programs.
Germany
Building operators in Berlin, Munich, and Hamburg favor wireless BACnet retrofit paths to avoid facade disruption under EU Green Deal mandates. The F-Gas Regulation compels refrigerant transition planning that mandates leak detection capabilities in new controller specifications. Energy performance contracting dominates procurement in the Rhine-Ruhr and Frankfurt corridors.
Japan
Tokyo and Osaka building managers accelerate procurement of multi-parameter indoor air quality sensors for post-pandemic ventilation upgrades. METI publishes efficiency standards that dictate interoperability requirements for imported controllers. Retrofit activity concentrates in the Greater Tokyo Area where aging commercial stock faces 2030 carbon neutrality deadlines.
Singapore
Commercial office developers in the CBD and Jurong Lake District expand smart thermostat deployments under tightening energy performance mandates. The Building and Construction Authority enforces Green Mark standards that accelerate control system refresh cycles. Demand concentrates in new mixed-use developments where performance guarantees structure procurement.
United Arab Emirates
Facility managers in Dubai and Abu Dhabi prioritize wireless sensor platforms for existing building retrofits where conduit replacement proves cost-prohibitive. MOHAP and local energy regulators draft certification requirements for connected building infrastructure. Procurement authority shifts toward energy service companies in the Emirates' commercial real estate sector.
Global HVAC Controls Market Competitive Environment
Diversified industrial conglomerates and specialized building automation firms split the market across technology tiers. Siemens AG, Johnson Controls International plc, and Schneider Electric SE anchor the premium tier through integrated hardware-software portfolios. Mid-scale specialists occupy retrofit-focused niches with wireless-first architectures. Dominant competitive moves include strategic partnerships for digital twin integration and geographic expansion into underpenetrated Asian markets.
Within the diversified conglomerate tier, Siemens AG and ABB Ltd exemplify European-origin players with captive industrial automation expertise. Honeywell International Inc. and Carrier Global Corporation anchor the US-based contingent, while Schneider Electric SE occupies a position bridging European engineering heritage with aggressive digital service expansion. Johnson Controls International plc represents the building-focused pure-play archetype, competing through direct channel presence and recurring commissioning contracts. Trane Technologies and Emerson Electric Co. sit within the climate-systems-integrated tier, leveraging equipment manufacturing scale to bundle control offerings.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Johnson Controls International plc |
| Trane Technologies |
| Carrier Global Corporation |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Delta Controls Inc. |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
Semiconductor fabrication concentration in Taiwan and South Korea feeds directly into controller margin architecture, with foundry capacity allocation determining tier availability for BACnet/IP-certified processors. Copper smelter output from Chile and Indonesian nickel processing for battery-backed wireless sensors further concentrate input cost volatility in premium hardware tiers.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European installations by mandating leak detection capabilities that stratify hardware into certified and non-certified bands. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-compliant multi-refrigerant sensor suites from basic fixed-gas detectors. Pricing pressure stems from copper and semiconductor input volatility that compresses hardware margins for controller manufacturers. Small commercial retrofit buyers exhibit highest price sensitivity, while German energy performance contractors under Green Deal mandates absorb premium tiers for compliance assurance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for edge-computing sensor platforms that draw from Shenzhen assembly clusters. Controller manufacturing rests on German, Japanese, and US-based precision machining for BACnet/IP gateway housings, with Taiwanese semiconductor foundries feeding processor demand. Single-source vulnerability concentrates in MEMS sensor die supply from specific East Asian vendors. Distribution runs through system integrator channels in retrofit corridors and direct OEM supply for new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global HVAC Controls Market sits in early-cycle expansion as post-pandemic ventilation upgrades and EU refrigerant transition mandates accelerate replacement timelines across commercial building stock.
For Market Incumbents: Pre-empt wireless-first specialists by acquiring edge-computing sensor platforms before they capture German and UAE retrofit corridors. Deepen backward integration into semiconductor procurement to buffer foundry allocation volatility. Lock long-term commissioning contracts with Singaporean commercial developers before energy service companies consolidate decision authority. For New Entrants and Emerging Players: Mid-market commercial buildings in India's underpenetrated Tier-2 cities represent the most penetrable entry point for wireless BACnet controllers ahead of BIS enforcement strengthening. Japanese Greater Tokyo Area aging stock facing 2030 carbon deadlines offers second-mover retrofit opportunity. Partner with local system integrators rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward software-enabled predictive maintenance platforms with recurring revenue visibility across the analysis window. Acquisition archetypes include wireless sensor specialists with F-Gas-certified hardware portfolios and digital twin integration capabilities. Monitor EU cybersecurity certification timeline announcements as inflection signals for product launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration Partnership | Siemens AG extends design-to-operations data continuity for German commercial landlords. |
| Predictive Maintenance Platform Launch | Schneider Electric SE anchors recurring subscription revenue displacing break-fix models. |
| Wireless BACnet Certification Investment | Johnson Controls International plc accelerates product launches ahead of cybersecurity mandates. |
| Edge-Computing Sensor Acquisition | Mid-scale specialists capture Japanese retrofit demand for multi-parameter IAQ units. |
| Indian Market Channel Expansion | Direct presence builds before BIS and CEA strengthen building energy code enforcement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU regulatory databases, and customs trade records. Interviews with building automation system integrators, facility managers at commercial landlords, OEM procurement leads, and energy service company executives provided demand-side validation. Secondary sources include FERC efficiency standard filings, EU Green Deal implementation documents, and METI efficiency guideline publications. Bottom-up sensor and controller shipment analysis triangulates against top-down building stock replacement modeling.
Forecast inputs span product type segmentation by controller, sensor, thermostat, and actuator categories; technology tiers across smart, wireless, wired, and analog architectures; and end-user splits between commercial buildings, industrial facilities, residential homes, and educational institutions. CAGRs derive from replacement cycle frequency analysis under regulatory mandate acceleration scenarios. Specific inputs include EU F-Gas Regulation compliance deadlines and US utility rebate program funding trajectories.
Practitioners should monitor semiconductor foundry allocation shifts and copper price volatility for early signals of hardware margin compression. Forecasts reflect assumptions of steady regulatory enforcement without abrupt mandate delays. Material shifts in EU cybersecurity certification timelines or US FERC standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Platform Lifts Market