
 Global Door Closers Market | 2026-2036
Global Door Closers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Door Closers Market Analysis
The EU Green Deal is broadening specification mandates for energy-efficient building hardware across European commercial construction. Allegion leverages its vertical integration into electronic access control to capture premium electromechanical door closer demand. Dormakaba Group anchors its position through specialized channel partnerships with European hospital and airport infrastructure contractors. ASSA ABLOY competes on manufacturing scale, sustaining cost leadership across standard hydraulic and spring product lines.
A door closer is a mechanical or electromechanical device installed at the hinge side or top of a door to control closing speed and ensure positive latching, typically operating through hydraulic fluid damping, pneumatic pressure, or spring tension mechanisms rated for cycle counts exceeding one million operations. Its primary purpose is to maintain fire compartmentation, manage energy loss through controlled door operation, and satisfy accessibility requirements in public buildings. Hydraulic door closers occupy the largest installed base due to proven reliability in high-traffic commercial environments, while electromechanical variants represent the fastest-expanding margin pool as smart building integration requirements intensify. Surface mounted installation dominates retrofit activity, though concealed systems command premium positioning in institutional and hospitality interiors where aesthetics constrain visible hardware.
The US Food and Drug Administration and Department of Justice enforce accessibility standards affecting door closer force and speed in healthcare and public facilities, while the EU Construction Products Regulation mandates CE marking and fire resistance testing for hardware deployed in commercial buildings. China's Ministry of Housing and Urban-Rural Development enforces GB standards for fire door assemblies, shaping product certification requirements for market entry. Stakeholders must monitor evolving interoperability standards between door closers and building management systems as electrification of building envelopes accelerates specification complexity.
Market Dynamics
Electrification of building envelopes is compressing specification cycles as electromechanical door closers displace hydraulic systems in smart building retrofits across commercial real estate portfolios.
Growth Catalysts
- EU Green Deal energy mandates:Tighter building energy codes across Germany, France, and Italy are mandating thermally efficient hardware replacements in existing commercial stock.
- Healthcare construction:Hospital infrastructure contractors in the United States are specifying low-energy door closers to satisfy FDA-enforced accessibility standards in patient care facilities.
- Fire safety upgrade cycles:China's GB standards enforcement is accelerating replacement demand for certified fire door assemblies in high-rise residential and office towers.
Market Restraints
- Raw material volatility:Zinc and aluminum price swings compress margins for die-cast closer body manufacturers dependent on spot market sourcing.
- Supply concentration:Precision hydraulic valve production concentrates among Taiwanese and German component specialists, creating single-source vulnerability.
- Electromechanical substitution complexity:Pneumatic door closers face technical displacement as building management system integration becomes mandatory in premium specifications.
Strategic Opportunities
- India building modernization:BIS certification requirements and urban hospital expansion create specification white space for electromechanical systems in Mumbai and Delhi construction corridors.
- Airport infrastructure:Concealed door closer demand is rising in Middle Eastern aviation hubs where aesthetic constraints intersect with high-cycle durability requirements.
- CSRD disclosure mandates:European corporate sustainability reporting is forcing facility managers to document embodied carbon in hardware procurement, favoring suppliers with verified lifecycle data.
Industry Challenges
- Electromechanical integration complexity:Door closer OEMs lack embedded software engineering capacity to satisfy BACnet and Modbus interoperability requirements from smart building integrators.
- Fire certification timeline compression:CE marking and UL testing backlogs extend product launch cycles by eight to fourteen months, delaying revenue recognition on new electromechanical platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Door Closers Market |
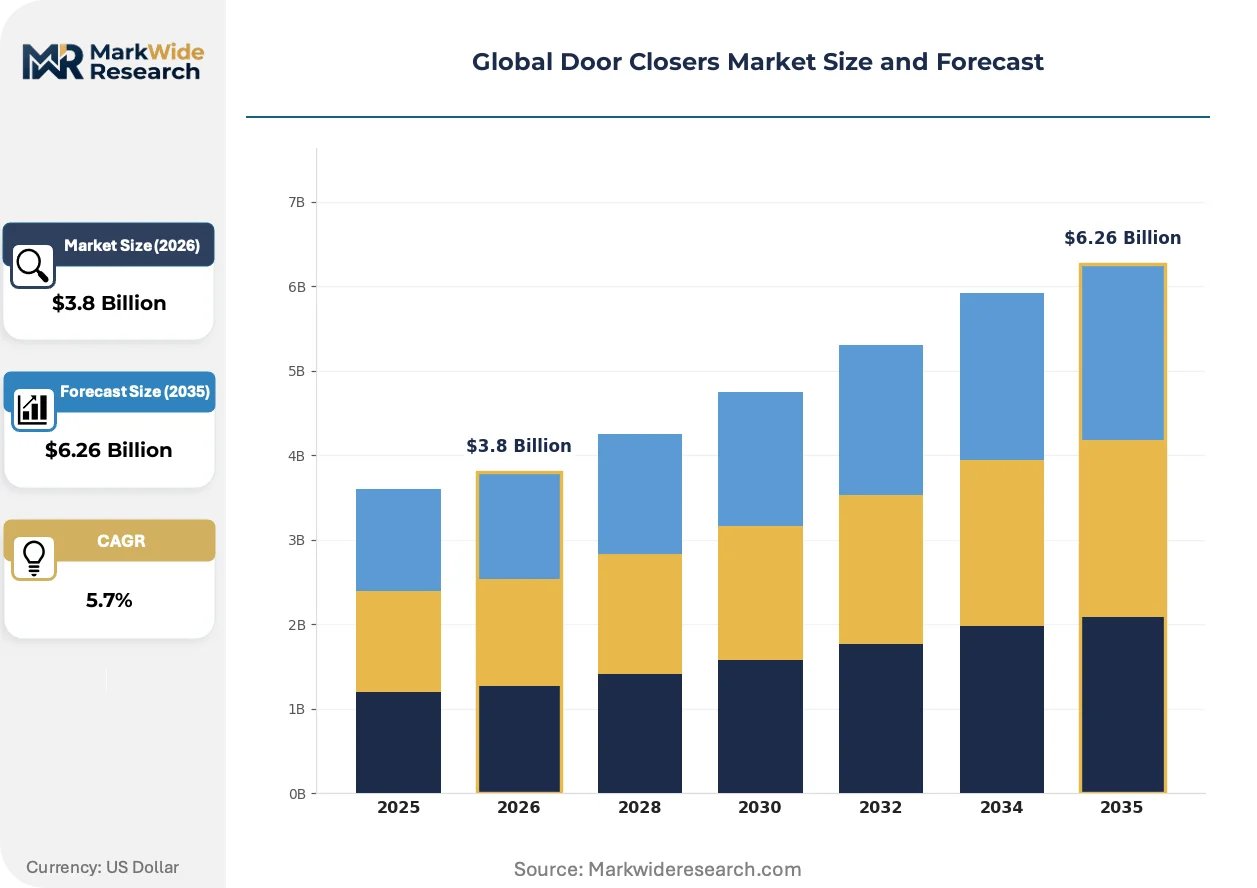
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electromechanical, Spring Installation Type: Surface Mounted, Concealed, Overhead, Floor Spring Application: Residential, Commercial, Institutional, Industrial Material: Aluminum, Stainless Steel, Brass, Plastic |
| Companies Covered | Allegion, Dormakaba Group, ASSA ABLOY, GEZE, Ryobi, Hafele, Stanley Black and Decker, Hager, Oude, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Door Closers Market Emerging Trajectories
Building electrification is fusing hardware with digital infrastructure. Specification professionals now evaluate door closers as networked edge devices rather than isolated mechanical components, forcing product architecture redesigns across the supply base.
Electromechanical door closers with integrated position sensing and network connectivity are converging with building management systems to enable real-time fire compartmentation monitoring and predictive maintenance scheduling. Large commercial real estate operators in Germany and the United States are deploying these systems in Class-A office portfolios. This convergence is compressing the addressable market for standalone hydraulic units while expanding service revenue pools for connected hardware providers.
REACH restrictions on persistent organic pollutants are forcing reformulation of hydraulic damping fluids used in conventional door closers, with ECHA enforcement tightening compliance verification across EU member states. Manufacturers serving the European market are accelerating qualification of bio-based synthetic alternatives. The regulatory pressure falls most heavily on economy-tier product lines where fluid cost represents a higher share of bill-of-materials.
Facility management procurement teams are consolidating vendor relationships and demanding extended warranty terms with predictive maintenance clauses for electromechanical installations. This behavior is displacing transactional distributor relationships with direct OEM partnerships in the United States healthcare and education verticals. The shift is most visible in California and Texas where large hospital systems and university districts are centralizing capital equipment purchasing.
Global Door Closers Market Segmentation
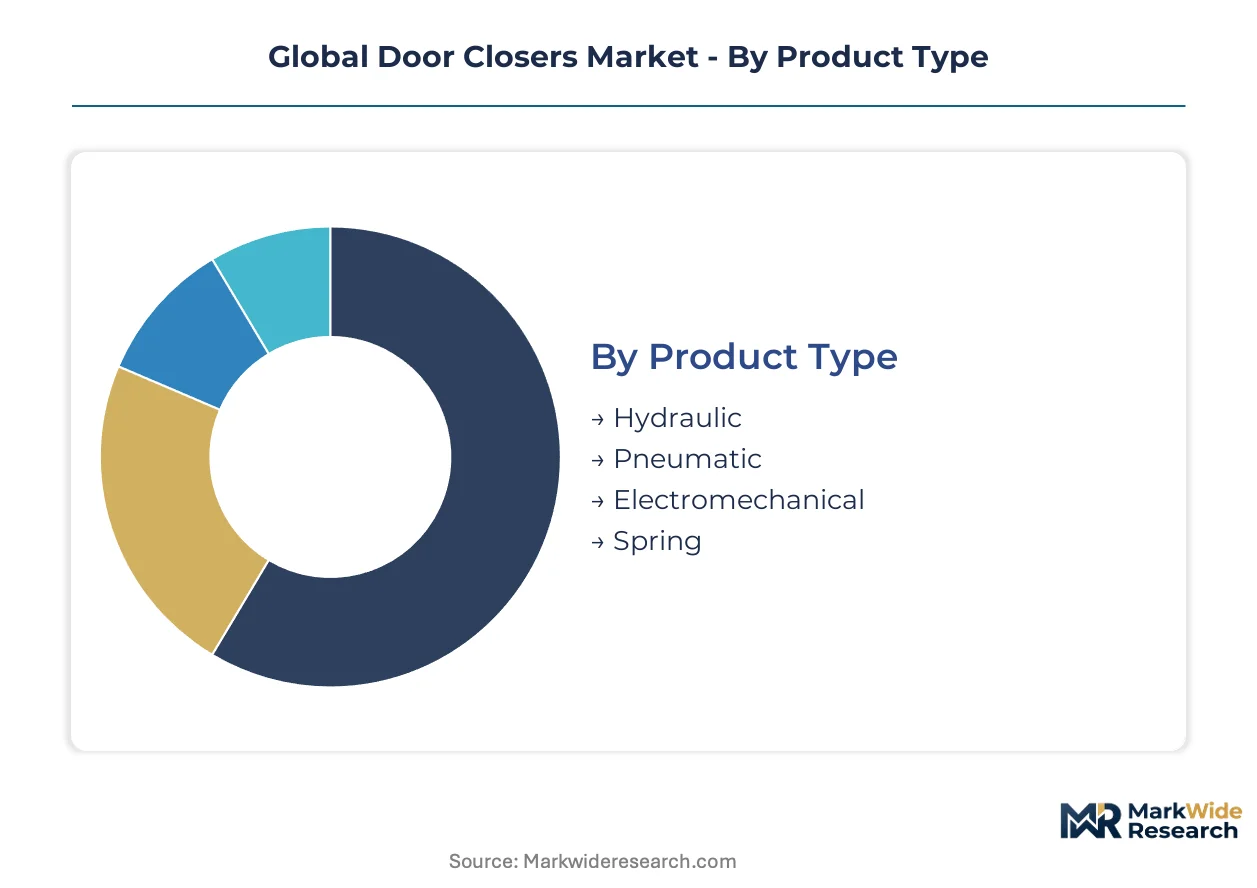
Door closer procurement decisions split across technical performance requirements, aesthetic constraints, and lifecycle cost calculations. Specification professionals weight installation geometry, traffic intensity, and building management system integration differently across verticals.
Product Type:
Buyers prioritize cycle durability and maintenance burden when selecting closing mechanisms for high-traffic environments.
- Hydraulic:Fluid-damped systems with adjustable latching speed control dominate commercial retrofit specifications. Hospital infrastructure contractors in the United States specify these for patient care corridors where ADA-compliant opening force limits are mandatory.
- Electromechanical:Motor-driven units with position sensing and BACnet connectivity command premium positioning. German Class-A office developers deploy these for real-time fire compartmentation monitoring and predictive maintenance scheduling.
- Pneumatic:Air-pressure systems serve light-duty residential and low-traffic institutional applications where cost sensitivity outweighs precision control requirements.
- Spring:Tension-based mechanisms occupy economy-tier positioning for basic residential and small commercial installations with minimal cycle count demands.
Hydraulic systems lead on installed base scale; electromechanical variants lead on specification momentum.
Installation Type:
Architectural visibility constraints and substrate conditions determine mounting geometry selection across new construction and retrofit projects.
- Surface Mounted:Exposed bracket systems attach directly to door and frame faces. These dominate North American commercial retrofit activity where minimal demolition preserves existing millwork.
- Concealed:Hidden mechanism installations recess into door leaves or transom headers. Middle Eastern aviation hubs specify these for premium passenger-facing zones where hardware visibility conflicts with interior design standards.
- Overhead:Header-mounted configurations distribute load across structural framing for heavy-duty industrial and institutional doors.
- Floor Spring:Pivot-based systems embed in concrete substrates for center-pivot and offset-pivot door configurations in high-end hospitality and retail storefronts.
Surface mounted installations lead on volume; concealed systems lead on margin expansion.
Application:
Traffic intensity, fire safety tier, and accessibility compliance stringency segment demand across building types.
- Commercial:Office towers, retail centers, and mixed-use developments drive specification of medium-duty and heavy-duty closers with hold-open and delayed-action features. EU Green Deal energy mandates accelerate replacement of outdated hardware in German and French commercial stock.
- Institutional:Healthcare facilities, educational campuses, and government buildings require certified fire-rated assemblies with documented lifecycle performance. China's GB standards enforcement drives replacement demand in high-rise hospital towers.
- Residential:Multi-family housing and single-family construction specify economy-grade hydraulic and spring mechanisms with basic latching control.
- Industrial:Manufacturing plants and warehousing facilities deploy heavy-duty overhead and floor-spring configurations for high-cycle loading dock and interior partition doors.
Commercial applications lead on specification value; institutional verticals lead on compliance-driven replacement velocity.
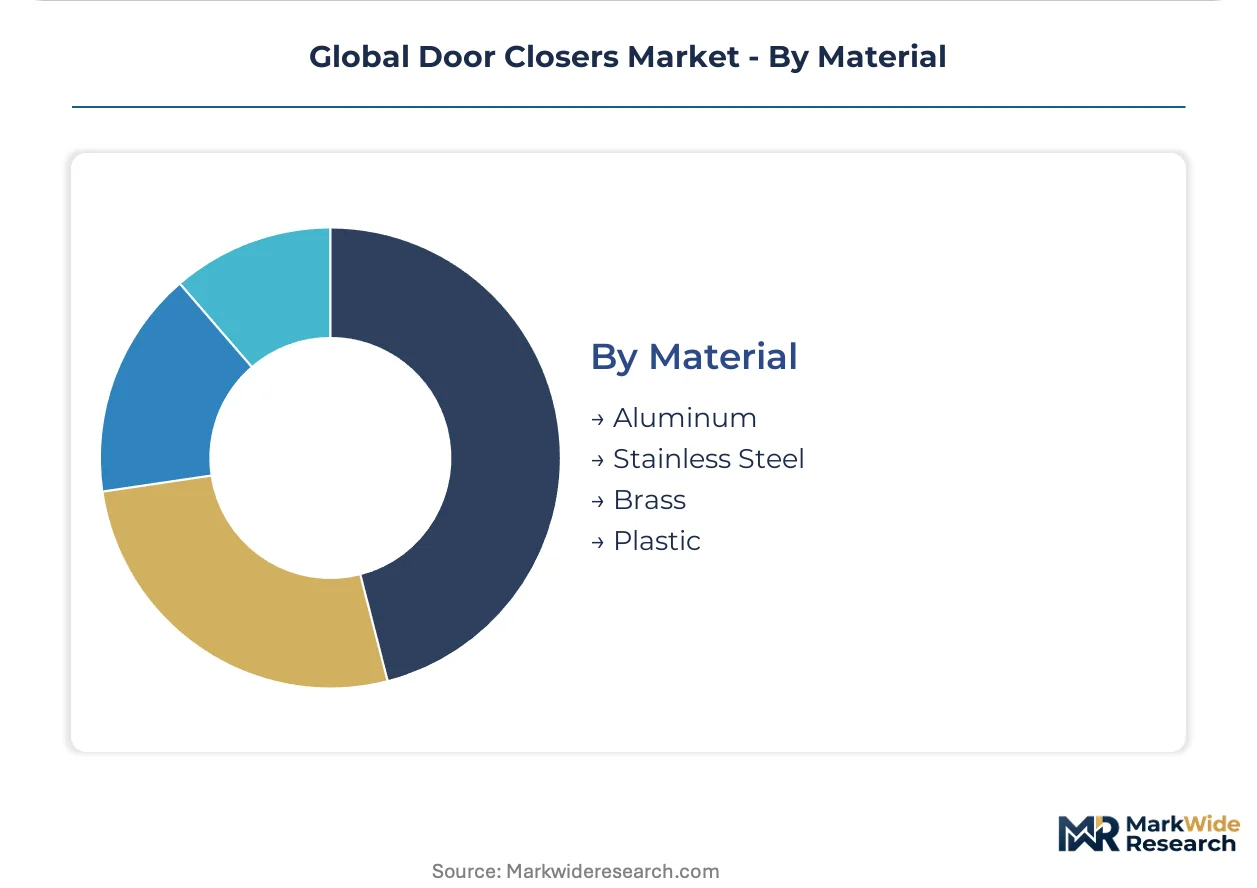
Material:
Corrosion resistance, die-cast precision, and surface finish requirements differentiate material selection across climate zones and aesthetic specifications.
- Aluminum:Die-cast alloy bodies balance weight, machinability, and cost for standard commercial product lines. Raw material price volatility compresses margins for manufacturers dependent on spot market sourcing.
- Stainless Steel:Corrosion-resistant grades serve coastal, healthcare, and food processing environments where sanitization protocols and salt exposure degrade standard finishes.
- Brass:Decorative bronze and brass finishes command premium positioning in historic restoration and luxury hospitality interiors where material authenticity is specified.
- Plastic:Glass-reinforced polymer components reduce weight and cost in light-duty residential and economy commercial applications with minimal durability requirements.
Aluminum leads on production volume; stainless steel leads on specification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Door closer manufacturing first achieved industrial scale in Germany during the post-war reconstruction era, with hydraulic damping technology spreading from European engineering centers to North American and Asian markets through the late twentieth century.
Germany
Class-A office developers in Frankfurt and Munich specify electromechanical door closers with BACnet connectivity for real-time fire compartmentation monitoring. The EU Green Deal mandates thermally efficient hardware replacements across existing commercial stock, accelerating specification velocity. The Rhine-Ruhr industrial corridor hosts precision hydraulic valve specialists supplying componentry to domestic and export markets.
United States
Hospital infrastructure contractors specify low-energy door closers to satisfy FDA-enforced accessibility standards in patient care facilities across Texas and California. Large healthcare systems in these states centralize capital equipment purchasing, displacing transactional distributor relationships with direct OEM partnerships. The Southeast construction corridor drives commercial retrofit activity for surface-mounted installations.
China
GB standards enforcement by the Ministry of Housing and Urban-Rural Development accelerates replacement demand for certified fire door assemblies in high-rise residential towers. Urban hospital expansion in Shanghai and Beijing creates specification white space for electromechanical systems. The Yangtze River Delta concentration of die-cast manufacturing supplies closer bodies to domestic and export markets.
India
BIS certification requirements and urban hospital expansion in Mumbai and Delhi create specification opportunities for imported electromechanical platforms. Healthcare construction in these corridors drives demand for fire-rated assemblies with documented lifecycle performance. The National Building Code adoption across state jurisdictions tightens hardware compliance verification.
United Arab Emirates
Middle Eastern aviation hubs in Dubai and Abu Dhabi specify concealed door closers where aesthetic constraints intersect with high-cycle durability requirements. Premium hospitality and commercial developments deploy floor-spring configurations for center-pivot door arrangements. MOHAP facility standards shape procurement specifications for healthcare infrastructure.
Global Door Closers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across electromechanical integration capability and fire certification depth. The vendor base stratifies between multinational hardware conglomerates with captive electronic access control divisions, specialized European engineering houses with deep channel partnerships, and Asian fabricators competing on die-cast scale. Three archetypes dominate: vertically integrated building technology platforms, precision hydraulic component specialists, and volume-driven standard product manufacturers. Competitive moves concentrate on M&A for electronic access control capability and strategic partnerships with hospital and airport infrastructure contractors.
Within the multinational platform tier, Allegion and ASSA ABLOY represent vertically integrated building technology architectures with captive supply of electronic access control systems. Dormakaba Group exemplifies the European engineering house archetype, anchoring position through specialized channel relationships with institutional infrastructure contractors. These three companies occupy positions across premium electromechanical and standard hydraulic product lines, with geographic origin and corporate structure reflecting their respective market entry paths.
| Leading Market Players |
|---|
| Allegion |
| Dormakaba Group |
| ASSA ABLOY |
| GEZE |
| Ryobi |
| Hafele |
| Stanley Black and Decker |
| Hager |
| Oude |
| Others |
Supply Flow & Price Mechanics
Large healthcare systems in Texas and California centralize capital equipment purchasing, compressing distributor margins and forcing direct OEM partnerships that stratify pricing across certification tiers rather than volume brackets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electromechanical systems with BACnet connectivity from hydraulic units with CE marking from basic spring mechanisms. Price differentiation hinges on fire certification depth and smart building integration capability. Cost compression in economy-tier hydraulic lines is intensifying because REACH-mandated fluid reformulation raises bill-of-materials exposure. Healthcare procurement teams exhibit lowest price sensitivity due to regulatory compliance mandates, while residential developers in emerging markets remain most cost-conscious.
Supply Chain Analysis
Domestic-content requirements in India's BIS certification regime and China's GB standards enforcement are reshaping sourcing patterns for foreign OEMs seeking market access. Manufacturing gravity centers on Germany for precision hydraulic valve production, China for die-cast aluminum body fabrication, and Taiwan for electronic control module assembly. Raw material supply draws from zinc spot markets, aluminum smelters, and bio-based synthetic fluid developers. Single-source vulnerability concentrates in German and Taiwanese precision component specialists. Distribution runs through specialized architectural hardware distributors in developed markets and direct contractor relationships in healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal compounds specification velocity through mandated hardware replacement cycles, transforming regulatory compliance into a recurring revenue driver for certified suppliers.
For Market Incumbents: Deepen captive electronic access control capability to defend electromechanical margins against pure-play smart building entrants. Accelerate CE marking and UL testing pipeline investments to compress fire certification timelines that currently delay revenue recognition. Prioritize backward integration into precision hydraulic valve production to reduce single-source exposure from Taiwanese and German component specialists. For New Entrants and Emerging Players: Mid-tier hospital infrastructure contractors in India's Mumbai-Delhi corridor represent the most penetrable buyer archetype, as BIS certification requirements create specification white space for compliant electromechanical platforms. Target airport infrastructure procurement in Middle Eastern aviation hubs where concealed system demand outstrips established supply relationships. Lead with lifecycle cost documentation and predictive maintenance bundling to displace transactional distributor incumbents. For Investors and Strategic Acquirers: Electronic access control conglomerates are the most active acquirer in this space, consolidating electromechanical door closer capability to complete smart building platform architectures. Long-term viability favors targets with verified fire certification depth and embedded software engineering capacity for BACnet interoperability. Watch for GB standards enforcement intensity in China as the inflection signal for replacement demand acceleration in high-rise residential towers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Valve Production | Reduces single-source dependency on Taiwanese and German component specialists. |
| Smart Building Platform Integration | Captures premium positioning as BACnet connectivity becomes mandatory in Class-A specifications. |
| Fire Certification Pipeline Expansion | Compresses CE marking and UL testing backlogs that delay electromechanical platform launches. |
| Direct Healthcare System Partnerships | Displaces transactional distributors as Texas and California hospital networks centralize procurement. |
| Bio-Based Hydraulic Fluid Qualification | Satisfies REACH restrictions while defending economy-tier margin positions against reformulation costs. |
Methodological Framework
Multiple input streams — specification interviews with architectural hardware distributors, technical discussions with hospital infrastructure contractors, and regulatory compliance consultations with fire certification laboratories — were reconciled against customs trade data, EU Construction Products Regulation filings, and SEC disclosures from listed building technology conglomerates. Bottom-up product-level volume estimates and top-down construction spend allocation models were triangulated to derive market sizing.
Data-stream reconciliation across the projection horizon applied segmentation by product type, installation geometry, application vertical, and regional regulatory cluster. CAGRs were computed from modeled replacement cycles and new construction penetration assumptions. Forecast inputs incorporated EU Green Deal implementation timelines, China's GB standards enforcement patterns, and healthcare facility modernization budgets across state-level jurisdictions.
Underlying measurement precision varies by segment; electromechanical and concealed installation categories carry tighter precision than economy-tier spring mechanisms due to specification visibility. Forecasts reflect assumptions about regulatory enforcement intensity and raw material price stability that could shift with commodity volatility or certification timeline changes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building Automation System Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
AEC Market
Building Automation Systems
Building Management System Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Automated Daylight Harvesting Systems Market