
 Smart Window Film Market | 2026-2036
Smart Window Film Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Window Film Market Insights
Architectural specification channels are being redrawn as smart window film is reshaping how glazing contractors and energy consultants bundle dynamic shading into retrofit proposals. 3M Company leverages its optical film heritage to dominate commercial retrofit channels, while Eastman Chemical Company anchors high-volume automotive glazing partnerships through its performance films division. Saint-Gobain competes by extending its building materials distribution network into integrated facade solutions that pair smart film with structural glass.
Smart window film comprises multilayer polymer or ceramic composites that modulate light transmission through thermochromic, electrochromic, or suspended particle device mechanisms, typically switching between transparent and opaque states within seconds under electrical or thermal stimulus. Electrochromic films incorporate tungsten oxide layers that darken via lithium ion intercalation, delivering precise solar heat gain coefficients for commercial facades. Suspended Particle Devices command premium positioning in automotive glazing and luxury residential applications where instant switching speed matters, while Polymer Dispersed Liquid Crystal occupies niche privacy-glass segments in healthcare and corporate interiors where opacity rather than thermal control drives specification.
Building energy codes enforced by the EU through the Energy Performance of Buildings Directive and by California through Title 24 now explicitly credit dynamic glazing toward compliance, creating regulatory pull for certified smart film installations. The EPA Energy Star program and comparable national frameworks in Japan and South Korea further shape product testing protocols and market access requirements. Stakeholders must monitor how upcoming amendments to these standards treat retrofit versus new-construction eligibility, as this distinction will determine which installation type segments capture the next wave of specification volume.
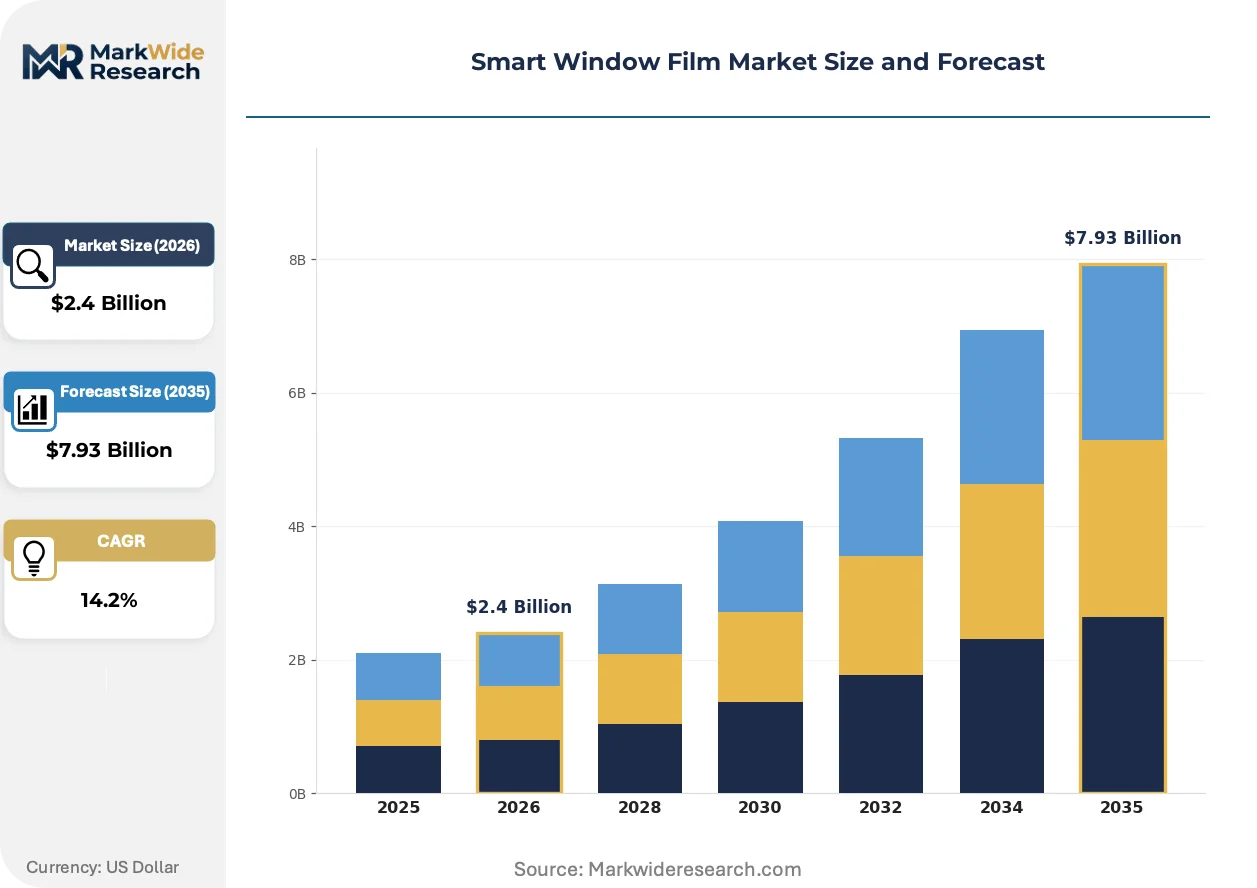
Market Dynamics
Building energy codes in California, Germany, and Japan are forcing commercial operators to treat dynamic glazing as a compliance instrument rather than an amenity, compressing specification cycles and bundling smart film into facade retrofit contracts.
Growth Catalysts
- California Title 24:The state's building energy standards now award compliance credits for electrochromic installations, pulling smart film into commercial retrofit specifications.
- Automotive glazing:Luxury vehicle manufacturers are integrating SPD films for instant tint switching, creating premium demand separate from building applications.
- Tungsten oxide electrochromics:Precise lithium-ion intercalation delivers tunable solar heat gain coefficients that satisfy tightening facade performance thresholds.
Market Restraints
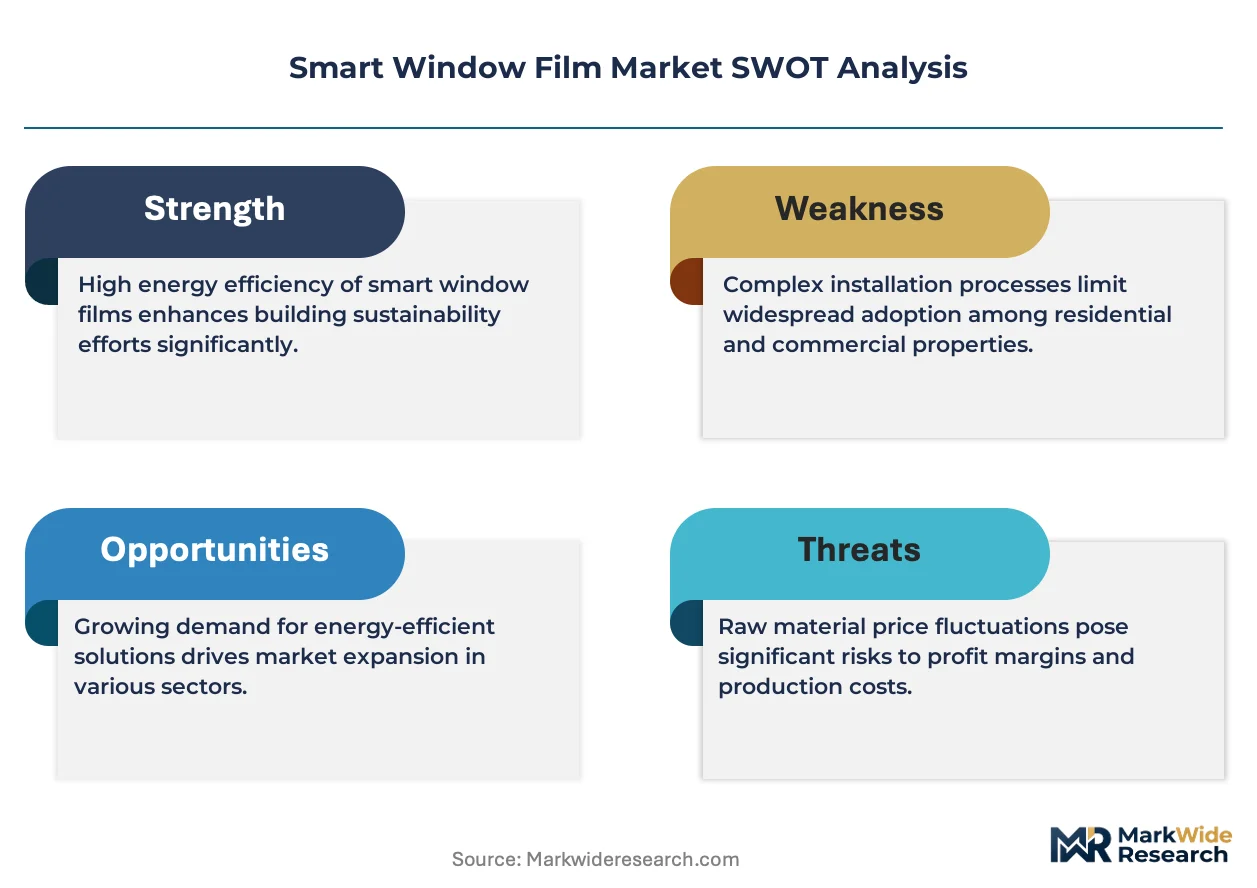
- Indium tin oxide supply:Transparent conductive layer costs fluctuate with concentrated mining operations, pressuring film manufacturer margins.
- Installation skill scarcity:Qualified glazing contractors capable of integrating switchable films with building management systems remain limited in secondary markets.
- Polymer dispersed liquid crystal limitations:PDLC films lack thermal modulation capability, restricting their addressable market to privacy applications and excluding energy-code-driven specifications.
Strategic Opportunities
- South Korea green building incentives:National certification frameworks now reward dynamic solar control, opening specification channels in a previously underpenetrated construction market.
- Healthcare privacy glass:PDLC installations in patient rooms and surgical suites create recurring replacement demand independent of energy retrofit cycles.
- Electrochromic-SPD convergence:Hybrid films combining precise thermal control with rapid switching are enabling new automotive sunroof and aircraft cabin applications.
Industry Challenges
- BMS integration complexity:Smart film control systems must interface with legacy building automation protocols, extending commissioning timelines and requiring specialized systems integrators.
- Certification fragmentation:Divergent testing protocols across the EPA Energy Star program, EU CE marking requirements, and Japan's JIS standards force manufacturers to maintain multiple product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Window Film Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.93 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermochromic, Photochromic, Electrochromic, Suspended Particle Devices, Polymer Dispersed Liquid Crystal Application: Commercial Buildings, Residential Properties, Automotive Glazing, Public Infrastructure, Marine Vessels Installation Type: Retrofit, OEM Installation, New Construction, Replacement Projects, Temporary Solutions End User Industry: Office Facilities, Housing Developments, Vehicle Manufacturers, Transit Authorities, Boat Builders |
| Companies Covered | 3M Company, Eastman Chemical Company, Saint-Gobain, Avery Dennison Corporation, Lintec Corporation, Polytronix, Inc., Smart Films International, Gentex Corporation, View, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Window Film Market Trends and Innovations
Smart window film is digitizing how buildings manage solar load, shifting control from static hardware to software-defined facades that respond to real-time conditions and utility pricing signals.
Electrochromic tungsten oxide stacks are digitizing facade performance by enabling continuous tint adjustment through building management system integration. Commercial developers in Germany and California are specifying these systems to automate compliance with dynamic utility rate structures. The technology is digitizing the traditional glazing procurement model from commodity glass purchase to long-term energy service contracting.
REACH restrictions on hazardous substances in construction materials are forcing reformulation of liquid crystal and suspended particle suspensions. Film manufacturers are accelerating substitution of legacy solvents with water-based alternatives to maintain EU market access. Automotive OEMs are responding by pre-qualifying compliant suppliers for next-generation vehicle programs.
Facility managers are unbundling smart film commissioning from general contractor scope, engaging directly with specialized controls integrators to retain operational flexibility. This pattern concentrates in Class A office assets in New York, London, and Tokyo where lease structures pass energy costs to tenants. The shift is compressing traditional glazing contractor influence over specification decisions.
Smart Window Film Market Segmentation
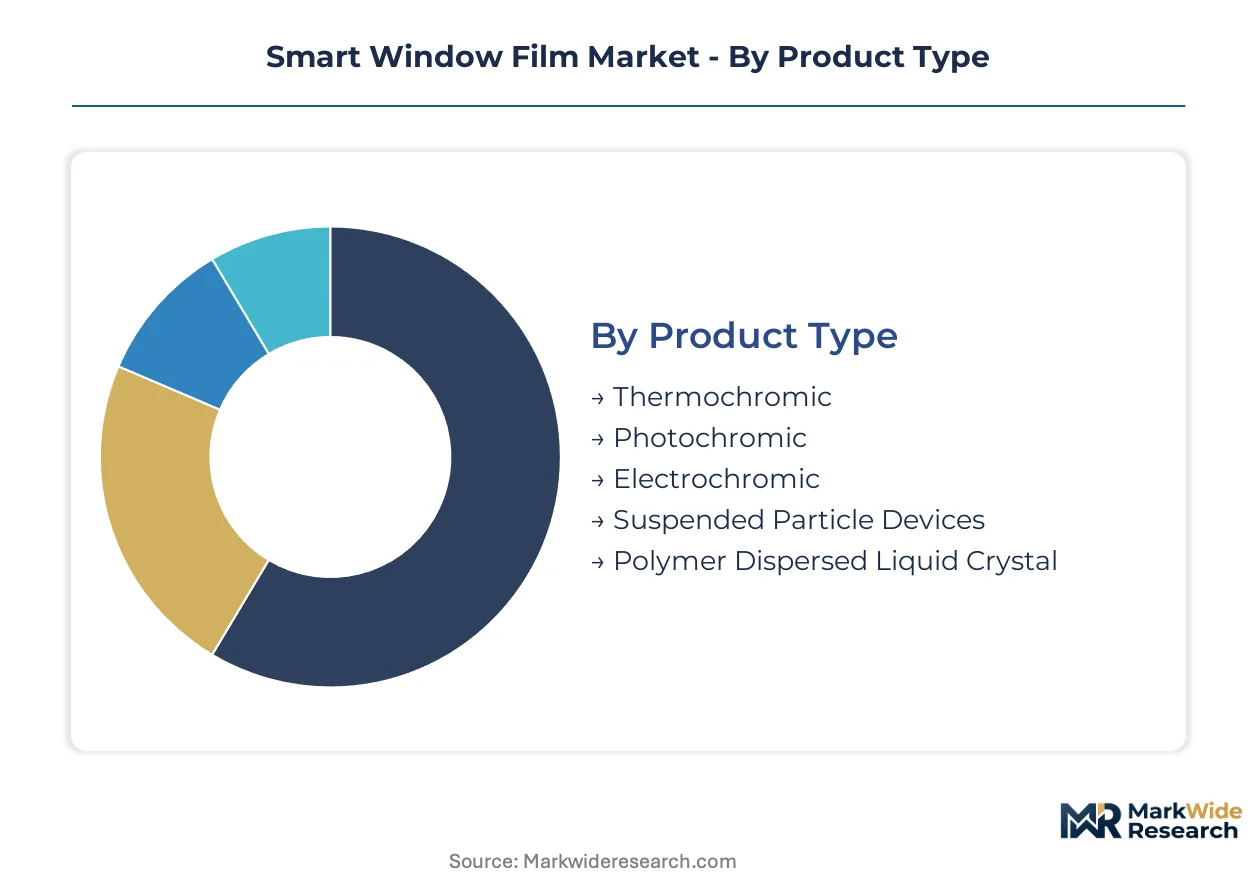
Smart window film technology fragments across multiple functional dimensions, with product chemistry determining thermal performance limits and installation type governing market access in retrofit versus new-build channels. Understanding how these segments intersect reveals where specification power concentrates and which customer types drive margin.
Product Type:
Mature electrochromic and SPD technologies anchor commercial revenue, while emerging thermochromic and photochromic variants target cost-sensitive volume applications.
- Electrochromic:Tungsten oxide layers modulate light transmission through lithium-ion intercalation, delivering precise solar heat gain coefficients demanded by California Title 24 compliance projects. Demand concentrates in Class A office retrofits across Germany, the United States, and Japan where energy codes credit dynamic glazing.
- Suspended Particle Devices:Rod-shaped particles suspended in liquid align under electrical field to switch between transparent and opaque states within milliseconds. Luxury automotive manufacturers in Germany and Japan specify SPD for sunroof applications where instant tint response commands premium pricing.
- Thermochromic:Vanadium dioxide coatings transition automatically with temperature, eliminating control system costs for residential applications in climate-variable regions.
- Photochromic:Silver halide crystals darken under UV exposure, finding niche adoption in marine vessel glazing where electrical infrastructure is limited.
- Polymer Dispersed Liquid Crystal:Liquid crystal droplets embedded in polymer matrix scatter light when de-energized, serving privacy-glass segments in healthcare and corporate interiors where opacity rather than thermal control drives specification.
Electrochromic retains volume leadership; thermochromic holds the steepest expansion curve.
Application:
Cost tier stratification separates premium facade retrofits from standardized automotive glazing and economy-tier residential installations.
- Commercial Buildings:Curtain wall and skylight retrofits dominate specification volume, with building operators bundling smart film into energy service contracts to meet EU Energy Performance of Buildings Directive thresholds. Germany and California account for the densest project pipelines.
- Automotive Glazing:OEM sunroof and side-window programs in Germany and Japan integrate SPD films as standard equipment on luxury segments, with tier-one suppliers qualifying hybrid electrochromic-SPD stacks for next-generation vehicle platforms.
- Residential Properties:High-net-worth homeowners in Tokyo and London specify electrochromic glazing for primary residences, while thermochromic alternatives penetrate mass-market housing in climate-extreme US states.
- Public Infrastructure:Transit authorities in Japan and South Korea deploy switchable glazing in rail stations and airport terminals to manage solar load without mechanical shading.
- Marine Vessels:Yacht builders in Italy and the Netherlands specify SPD films for saloon windows where weight reduction and instant privacy outweigh cost premiums.
Commercial buildings retain volume leadership; automotive glazing holds the steepest expansion curve.
Installation Type:
Customer type divides between owner-operated assets seeking operational control and developer-led projects optimizing first-cost versus lifecycle value.
- Retrofit:Existing commercial facade upgrades generate the highest-margin installations, with facility managers in New York, London, and Tokyo engaging specialized controls integrators directly to retain BMS flexibility outside general contractor scope.
- New Construction:Integrated facade packages pair smart film with structural glass, with German and Japanese developers specifying electrochromic systems from design phase to capture green building certification credits.
- OEM Installation:Automotive and marine manufacturers pre-qualify film suppliers during platform development, locking in multi-year volume commitments.
- Replacement Projects:Healthcare facilities replace PDLC privacy glass on accelerated cycles, creating recurring demand independent of energy retrofit cycles.
- Temporary Solutions:Event venues and retail pop-ups deploy removable film installations for seasonal solar control.
Retrofit retains volume leadership; new construction holds the steepest expansion curve.
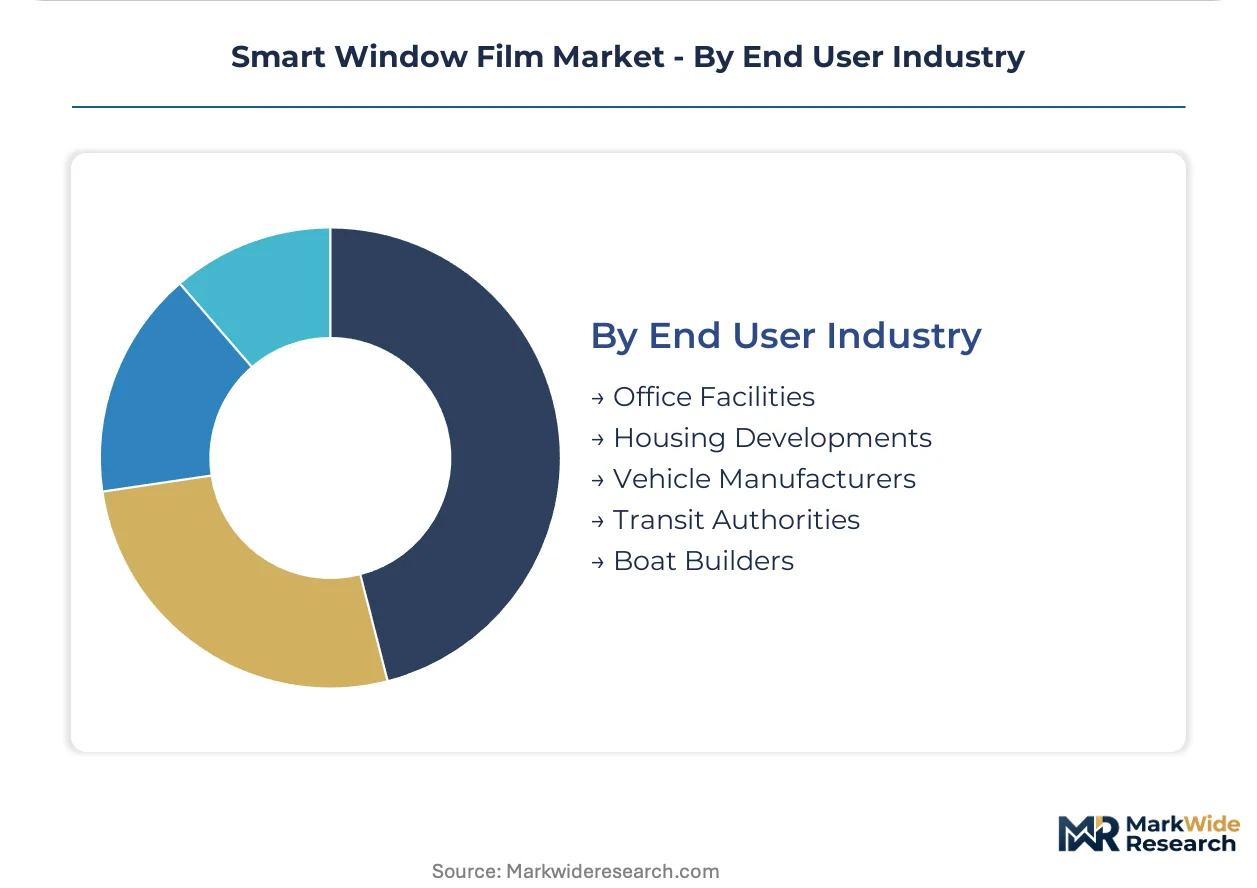
End User Industry:
Margin concentration tracks regulatory exposure, with code-driven office facilities and vehicle manufacturers commanding premium pricing over discretionary housing and marine segments.
- Office Facilities:Class A landlords in California and Germany treat dynamic glazing as compliance infrastructure, bundling electrochromic specification into lease structures that pass energy costs to tenants.
- Vehicle Manufacturers:German and Japanese OEMs integrate smart film at platform level, with sunroof programs driving standardization of SPD and hybrid electrochromic technologies.
- Housing Developments:Master-planned communities in Japan and South Korea specify thermochromic glazing to meet national green building incentives without premium electrical infrastructure.
- Transit Authorities:Rail operators in Tokyo and Seoul pilot switchable platform screen doors and station glazing to reduce cooling loads.
- Boat Builders:Superyacht yards in the Netherlands specify marine-grade SPD for weight-critical applications.
Office facilities retain volume leadership; vehicle manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cargo throughput anchors European smart film distribution networks, while Japan's Shinkansen rail corridors concentrate transit-oriented glazing demand. These infrastructure assets channel specification activity toward code-compliant metropolitan clusters.
United States
California Title 24 mandates dynamic glazing credits for commercial retrofits, pulling electrochromic specification into Los Angeles and San Francisco facade contracts. The EPA Energy Star program shapes product testing protocols for multi-state deployment. New York facility managers engage specialized controls integrators directly, bypassing general contractor scope to retain building management system flexibility.
Germany
The EU Energy Performance of Buildings Directive compresses specification cycles for Frankfurt and Berlin office retrofits. ECHA REACH restrictions force reformulation of liquid crystal suspensions with water-based alternatives. Bavarian automotive OEMs pre-qualify SPD film suppliers for next-generation sunroof platforms, locking in multi-year volume commitments.
Japan
METI green building incentives reward dynamic solar control in Tokyo commercial assets. JIS standards govern product certification for domestic and export markets. Osaka-based rail operators pilot switchable platform screen doors to reduce station cooling loads without mechanical shading infrastructure.
South Korea
National certification frameworks now credit dynamic glazing toward compliance, opening specification channels in Seoul construction markets previously underpenetrated by smart film. MFDS-equivalent building regulators align testing protocols with Japanese standards. Busan-Ulsan automotive clusters integrate hybrid electrochromic-SPD stacks for premium vehicle programs.
United Kingdom
London Class A landlords bundle electrochromic specification into lease structures passing energy costs to tenants. The UK's national building regulations increasingly reference dynamic solar control for facade compliance. Manchester and Birmingham retrofit pipelines concentrate specification volume outside the capital's premium tier.
Smart Window Film Market Competitive Landscape
On the supply side, the industry is tiered between diversified materials conglomerates and specialized film fabricators. Chemical heritage companies leverage optical coating expertise to anchor commercial retrofit channels. Technology specialists command premium positioning in automotive and aerospace applications where switching speed determines specification. Dominant competitive moves include strategic partnerships with glazing contractors and geographic expansion through regional distributor networks.
Among diversified materials conglomerates, 3M Company and Eastman Chemical Company exemplify archetypes leveraging polymer science heritage to dominate volume channels. Saint-Gobain occupies a position bridging building materials distribution with integrated facade solutions. These three anchors represent contrasting strategic postures: optical film specialization, performance chemicals verticality, and construction systems integration.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| Saint-Gobain |
| Avery Dennison Corporation |
| Lintec Corporation |
| Polytronix, Inc. |
| Smart Films International |
| Gentex Corporation |
| View, Inc. |
| Others |
Pricing and Supply Chain Analysis
Indium tin oxide mining concentration in Bolivia and Australia funnels transparent conductive layer costs directly into film manufacturer margin structures, concentrating pricing power with upstream chemical processors while glazing contractors downstream absorb installation skill premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electrochromic facade systems from SPD automotive glazing and thermochromic residential films. Certification grade under EU CE marking and California Title 24 compliance tiers drives price differentiation alongside volume scale for multi-project facility managers. Cost compression in standard-tier electrochromic films is intensifying because REACH-compliant solvent reformulation adds manufacturing overhead. Healthcare PDLC privacy applications show least price sensitivity due to replacement cycle independence from energy retrofit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for tungsten oxide precursor chemicals and liquid crystal suspensions. Manufacturing concentrates in Germany, Japan, and South Korea for precision coating equipment and optical film substrates. Raw material dependencies span lithium carbonate for electrochromic intercalation, indium tin oxide for transparent conductors, and specialized polymer resins for multilayer lamination. Distribution runs through building materials distributors for commercial retrofit channels and Tier 1 automotive suppliers for OEM glazing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart window film market is emerging from a cyclical trough as commercial construction retrofit pipelines refill following energy code enforcement delays. Building energy code amendment cycles in California and Germany provide the demand cadence.
For Market Incumbents: Build certification moats around EU CE marking and EPA Energy Star protocols to lock out emerging Asian competitors. Deepen backward integration into tungsten oxide precursor supply through captive offtake agreements with Bolivian mining operations. Channel control through direct facility manager relationships in New York and London Class A office assets counters general contractor disintermediation threats. For New Entrants and Emerging Players: Establish a beachhead in South Korean green building incentive programs where specification channels remain underpenetrated by Western incumbents. Target thermochromic residential retrofits in climate-extreme US states where electrical infrastructure limitations favor passive switching technologies. Pursue healthcare PDLC replacement contracts through specialized medical equipment distributors rather than architectural specification channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrochromic technology specialists seeking exit liquidity after patent cliff approaches. Five-to-ten year viability hinges on hybrid electrochromic-SPD convergence platforms capturing automotive sunroof standardization. Monitor JIS standards harmonization with South Korean MFDS-equivalent protocols as inflection indicator for pan-Asian market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Supply | Captive lithium-ion intercalation chemistry sourcing secures electrochromic film margin pools against commodity volatility. |
| Hybrid Electrochromic-SPD Platform Development | Combined thermal precision and millisecond switching opens aircraft cabin and premium automotive sunroof specifications. |
| REACH-Compliant Solvent Reformulation | Water-based liquid crystal suspension chemistry preserves EU market access under ECHA hazardous substance restrictions. |
| Direct Facility Manager Engagement | Bypassing general contractor scope in New York and London Class A assets retains building management system integration control. |
| South Korean Certification Alignment | MFDS-equivalent building regulator protocol harmonization unlocks Seoul construction market specification channels. |
Research Methodology
Operator-level perspectives from glazing contractors, facility managers, energy consultants, and building automation integrators anchored the qualitative base. Primary interviews combined with secondary validation against SEC 10-K filings from diversified materials conglomerates, ECHA REACH compliance databases, and EU Energy Performance of Buildings Directive implementation reports. Customs and trade data from Germany, Japan, and South Korea provided import volume triangulation against bottom-up project pipeline estimates.
Scenario-bracketing framed the analytical approach across the analysis window, modeling technology type, installation channel, and end-use industry segments alongside regional regulatory cluster adoption curves. CAGRs derived from installed base growth rates and replacement cycle frequencies, with electrochromic lithium-ion intercalation efficiency improvements and SPD particle alignment speed advances as key technology trajectory inputs.
Sensitivities concentrate around building energy code amendment timelines and indium tin oxide supply disruptions. Forecasts reflect assumptions about retrofit versus new-construction eligibility distinctions in incentive programs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building Management System Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Escalator Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Smart Building Solutions Market