
 Dumbwaiter Lifts Market | 2026-2036
Dumbwaiter Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Dumbwaiter Lifts Market Foresight
Commercial kitchen demand is hardening as restaurateurs prioritize vertical material transport to reduce server travel time and floor congestion. Otis Elevator Company leverages its service network density to capture replacement cycles in North American hospitality corridors. Schindler Group anchors its position through modular installation capabilities that shorten downtime in active restaurant environments. Kone Corporation differentiates via digital monitoring integration that tracks lift cycles and predicts maintenance intervals.
Dumbwaiter lifts are compact vertical transportation systems typically rated for loads between 50 and 500 pounds, designed to move goods between floors through a dedicated shaftway using electric traction or winding drum drive mechanisms. Their primary commercial purpose centers on segregating personnel and material flows to improve operational efficiency and reduce workplace injury exposure in high-traffic buildings. Electric dumbwaiters command the largest installed base due to reliability advantages over manual alternatives, though pneumatic variants are gaining traction in clean-environment applications such as hospital pharmacies where contamination control matters. Custom installation projects carry margin premiums relative to modular counterparts, reflecting the engineering complexity of retrofitting heritage structures with non-standard floor heights.
ASME A17.1 in the United States and the EU Machinery Directive govern dumbwaiter safety standards, with both frameworks tightening requirements for door interlocks and emergency braking systems that extend product development cycles. Japan's METI building equipment codes impose additional seismic resilience testing that filters out lower-tier suppliers from that market. Stakeholders must monitor evolving accessibility regulations that could blur the functional boundary between dumbwaiters and passenger lifts, potentially triggering reclassification and more stringent inspection protocols.
Market Dynamics
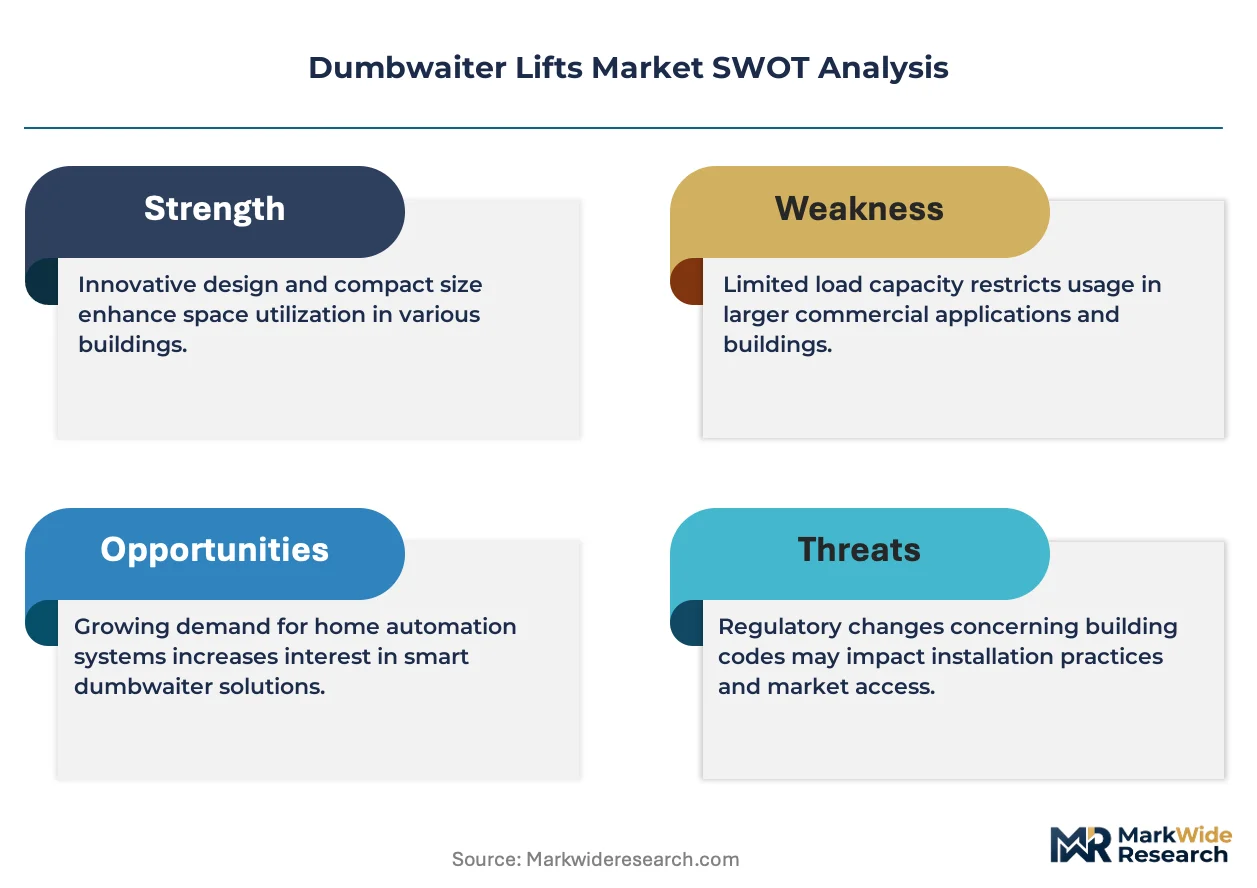
Labor efficiency mandates across mid-scale restaurant chains are hardening demand for vertical material transport systems, while ASME A17.1 and EU Machinery Directive compliance extensions stretch product development cycles for manufacturers.
Growth Catalysts
- Commercial kitchen automation:Mid-scale restaurant chains deploy dumbwaiters to reduce server travel time and floor congestion, compressing table turnaround intervals during peak service windows.
- EU Machinery Directive enforcement:Tightened door interlock and emergency braking requirements are filtering out non-compliant suppliers, consolidating procurement toward certified vendors in German and French hospitality markets.
- Aging building stock renovation:Heritage structure retrofits in Japan, Germany, and the United States create installation demand for compact shaftway solutions adapted to non-standard floor heights.
Market Restraints
- Steel and copper input volatility:Winding drum drive mechanisms and electric traction systems face margin pressure from commodity price swings, compressing OEM profitability on standard-configuration units.
- Supplier concentration in precision gearing:Japanese and German specialty manufacturers control high-torque reduction gear supply, exposing dumbwaiter assemblers to lead time extension risks.
- Passenger lift substitution threat:Accessibility regulation expansions in multiple jurisdictions blur functional boundaries, potentially triggering reclassification of larger-capacity dumbwaiters into more stringent inspection protocols.
Strategic Opportunities
- Hospital pharmacy pneumatic systems:Clean-environment contamination control requirements in Japanese and German healthcare facilities drive specification of sealed pneumatic variants over conventional electric traction.
- Digital monitoring convergence:IoT cycle-tracking and predictive maintenance algorithms create service revenue attachment opportunities beyond hardware installation.
- Modular installation channel innovation:Pre-fabricated shaftway systems reduce active-site downtime, opening mid-market restaurant segments previously blocked by operational disruption concerns.
Industry Challenges
- Seismic certification complexity:Japan's METI building equipment codes impose additional resilience testing that extends product qualification timelines and excludes lower-tier engineering capabilities.
- Heritage retrofit integration friction:Non-standard floor heights and structural constraints in aged buildings demand custom engineering, stretching project delivery schedules and compressing margin realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dumbwaiter Lifts Market |
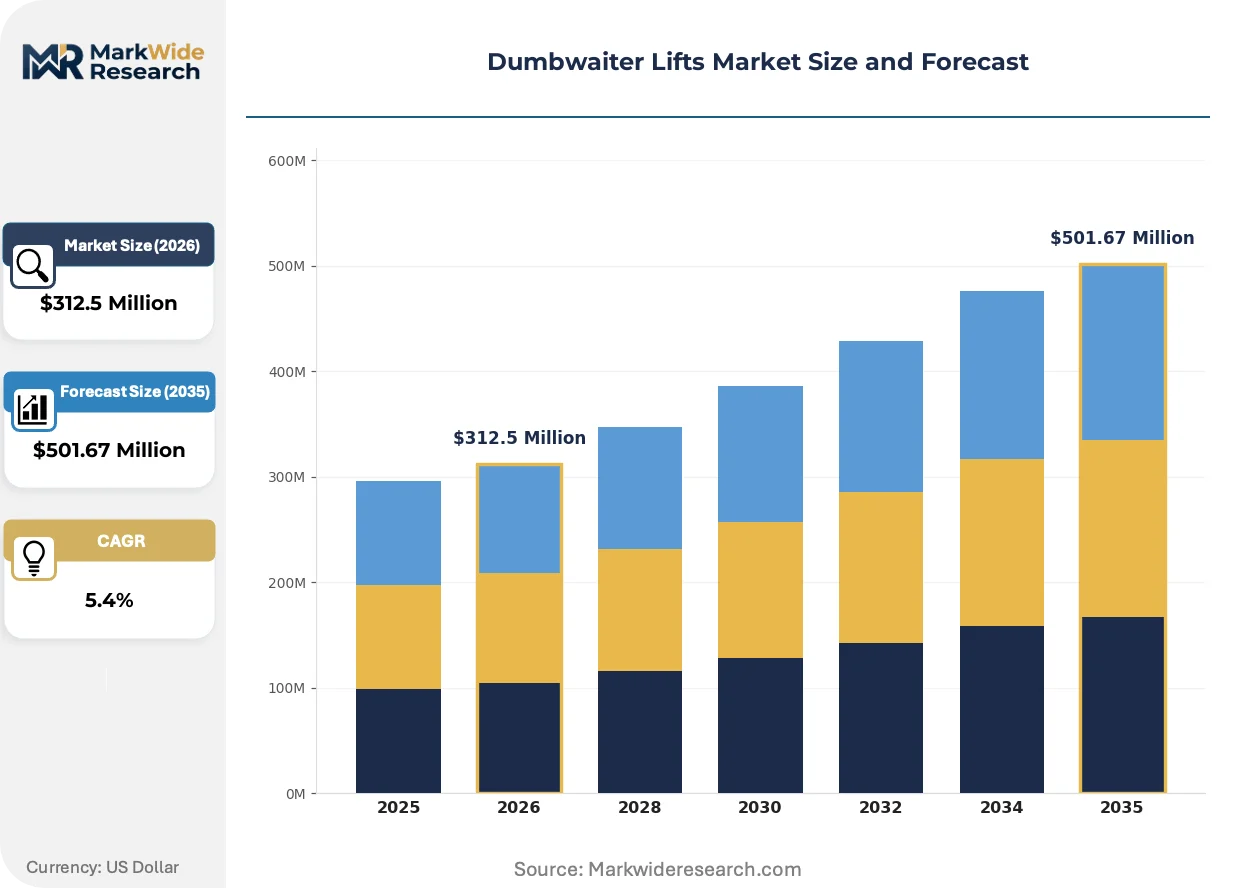
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Dumbwaiters, Electric Dumbwaiters, Manual Dumbwaiters, Pneumatic Dumbwaiters Application: Residential Use, Commercial Kitchens, Hospitals, Libraries Installation Type: In-Building, Independent Structure, Custom Installation, Modular Installation End User: Restaurateurs, Facility Managers, Homeowners, Library Administrators |
| Companies Covered | Otis Elevator Company, Schindler Group, Thyssenkrupp AG, Kone Corporation, Mitsubishi Electric Corporation, Stannah Lifts Holdings Ltd, Waupaca Elevator Company, Hitachi Ltd, Matot, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dumbwaiter Lifts Market Shifts & Advancements
Digital monitoring integration and clean-environment pneumatic alternatives are actively reshaping product architecture and service attachment models across commercial and healthcare verticals.
IoT-enabled cycle tracking is absorbing maintenance scheduling from calendar-based to condition-based intervals. Hospital chains and large restaurant groups deploy sensor networks that log lift cycles, motor temperature, and door operation frequency. This data stream is absorbing service contract pricing toward outcome metrics rather than fixed fees, compressing traditional break-fix revenue pools.
REACH substance restrictions and F-Gas Regulation phase-downs in Europe are forcing lubricant and hydraulic fluid reformulation in electric traction systems. Manufacturers must qualify alternative chemistries that maintain torque transmission efficiency across temperature ranges. German OEMs face the steepest compliance burden given their installed base density in food-service applications with strict contamination protocols.
Buying committees at multi-unit restaurant operators now specify lifecycle cost rather than upfront capital expenditure, unbundling after-sales service from initial equipment procurement. Third-party service aggregators capture maintenance contracts that OEMs previously held captive, particularly in United States hospitality corridors where independent installer networks remain fragmented. This shift is most visible in California and Texas markets with high chain restaurant penetration and aggressive facilities cost benchmarking.
Dumbwaiter Lifts Market Segmentation
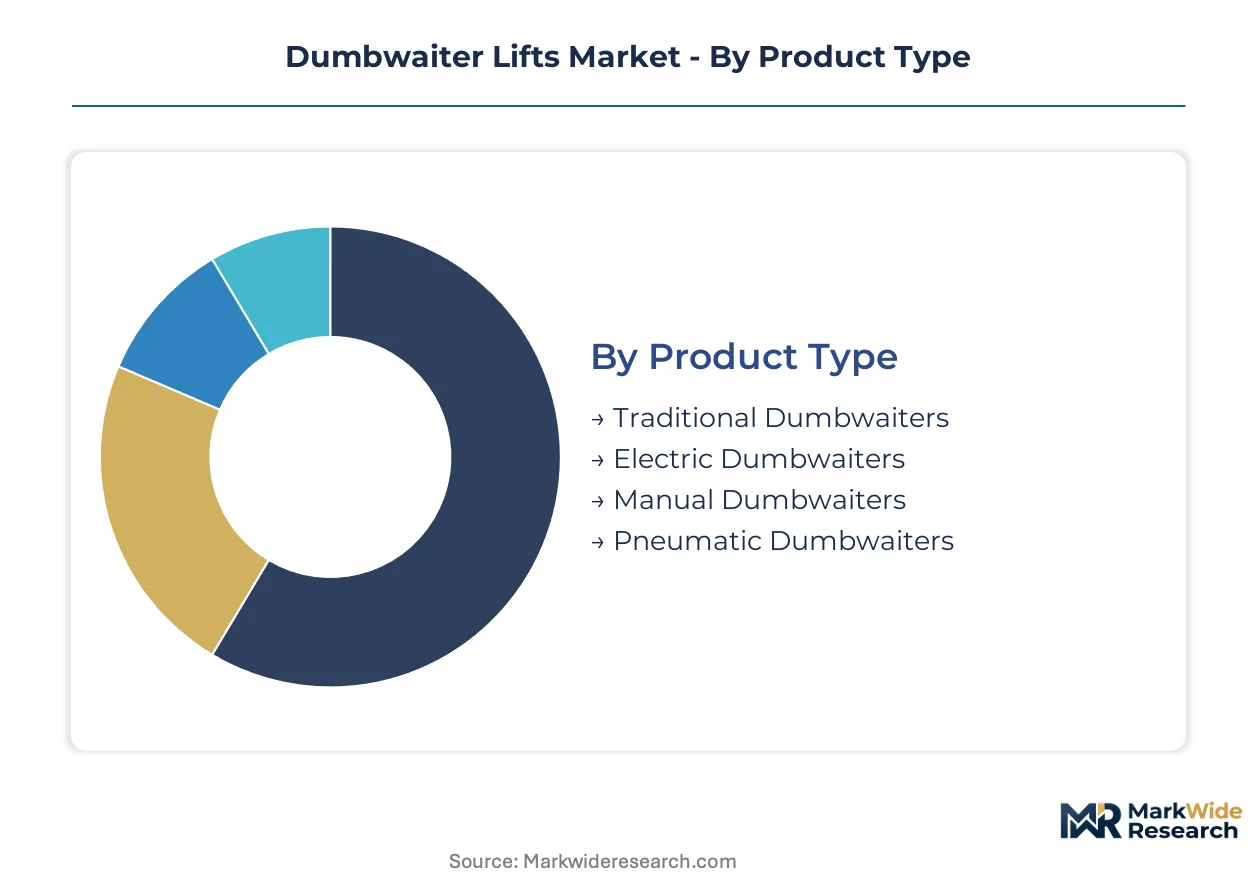
Product architecture in the Dumbwaiter Lifts Market fragments across drive mechanisms, installation constraints, and end-user procurement sophistication. Segmentation reveals where engineering complexity concentrates margin capture and where standardization enables volume scaling.
Product Type:
Supply concentration in precision gearing and motor assemblies favors established electric traction platforms over emerging alternatives.
- Electric Dumbwaiters:Traction or winding drum drive mechanisms rated for 50-500 pound loads dominate commercial specifications. Mid-scale restaurant chains in the United States specify these for kitchen-to-server circulation paths where reliability compresses maintenance downtime.
- Pneumatic Dumbwaiters:Sealed pressure-differential systems eliminate contamination risk in Japanese and German hospital pharmacy environments. METI building equipment codes and EU Machinery Directive cleanroom protocols accelerate specification where electric motor particulate is prohibited.
- Traditional Dumbwaiters:Rope-and-pulley manual systems persist in heritage building retrofits where electrical infrastructure is restricted.
- Manual Dumbwaiters:Counterweight-assisted units serve low-frequency residential applications with minimal cycle demand.
Today's leader: Electric Dumbwaiters. Tomorrow's challenger: Pneumatic Dumbwaiters.
Application:
Cost tier stratification separates specification-intensive healthcare deployments from price-sensitive residential installations.
- Commercial Kitchens:Labor efficiency mandates across United States mid-scale restaurant chains harden demand for vertical material transport. These installations prioritize cycle speed and door interlock reliability over upfront capital expenditure.
- Hospitals:Contamination control protocols in Japanese and German healthcare facilities specify pneumatic or sealed electric variants. ASME A17.1 and EU Machinery Directive compliance filters procurement toward certified vendors with documented emergency braking validation.
- Residential Use:Homeowners in aging building stock renovations favor compact shaftway footprints adapted to non-standard floor heights.
- Libraries:Book transport between stacks and circulation desks drives moderate-capacity specifications with low cycle frequency.
Commercial Kitchens anchor current volume. Hospital applications are climbing the fastest on regulatory tailwinds.
Installation Type:
Customer type fragmentation separates turnkey modular buyers from engineering-intensive custom project stakeholders.
- Modular Installation:Pre-fabricated shaftway systems reduce active-site downtime, opening mid-market restaurant segments previously blocked by operational disruption concerns. German and United States hospitality corridors show strongest uptake where chain operators benchmark facilities costs aggressively.
- Custom Installation:Heritage structure retrofits in Japan and Germany demand adaptation to non-standard floor heights and structural constraints. These projects carry margin premiums reflecting engineering complexity and extended delivery schedules.
- In-Building:New construction integration allows optimized shaftway placement during architectural design phase.
- Independent Structure:External shaftway additions serve buildings where internal vertical circulation is physically constrained.
Modular Installation is gaining share fastest. Custom Installation retains margin leadership.
End User:
Procurement sophistication varies sharply across stakeholder technical capacity and lifecycle cost visibility.
- Restaurateurs:Multi-unit operators in California and Texas markets now specify lifecycle cost rather than upfront capital expenditure. Third-party service aggregators capture maintenance contracts that OEMs previously held captive.
- Facility Managers:Hospital and institutional buyers deploy IoT-enabled cycle tracking to shift maintenance scheduling from calendar-based to condition-based intervals.
- Homeowners:Individual residential purchasers prioritize compact footprint and aesthetic integration over predictive maintenance capabilities.
- Library Administrators:Municipal procurement processes favor standardized specifications with extended warranty terms.
Restaurateurs drive volume scaling. Facility Managers are expanding most quickly on digital monitoring convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as compliance cost differentials widen between jurisdictions with stringent safety codes and those with lighter enforcement regimes.
United States
Mid-scale restaurant chains in California and Texas drive replacement demand as labor efficiency mandates intensify vertical transport investment. ASME A17.1 safety code enforcement filters procurement toward certified vendors with documented emergency braking validation. The Pacific Northwest hospitality corridor concentrates retrofit activity where aging building stock renovations intersect with aggressive facilities cost benchmarking.
Germany
Heritage structure retrofits in Bavaria and North Rhine-Westphalia create installation demand for compact shaftway solutions adapted to non-standard floor heights. EU Machinery Directive tightened door interlock requirements are consolidating procurement toward compliant vendors in food-service applications. The Stuttgart industrial cluster anchors precision gearing supply that feeds dumbwaiter assemblers across Central Europe.
Japan
Hospital pharmacy contamination control protocols in Tokyo and Osaka accelerate specification of sealed pneumatic variants over conventional electric traction. METI building equipment codes impose additional seismic resilience testing that filters out lower-tier suppliers from this market. The Nagoya manufacturing belt concentrates specialty reduction gear production that exposes assemblers to lead time extension risks.
United Kingdom
Commercial kitchen automation across London and Southeast England hardens demand for modular installation systems that reduce active-site downtime. REACH substance restrictions and F-Gas Regulation phase-downs force lubricant reformulation in electric traction systems. The Midlands engineering base retains custom fabrication capabilities for heritage building adaptations with constrained shaftway dimensions.
India
Rising hospitality sector investment in Maharashtra and Karnataka creates specification demand for cost-optimized electric traction units in mid-market restaurant segments. The country's national building equipment regulator is aligning certification frameworks with ISO safety standards, compressing qualification timelines for imported systems. The Delhi-NCR corridor concentrates facilities management procurement for multi-unit restaurant operators benchmarking lifecycle costs.
Dumbwaiter Lifts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated leadership in premium certification-intensive markets and fragmentation in price-sensitive residential applications. Tier-one elevator conglomerates leverage service network density to capture replacement cycles, while regional fabricators compete on custom engineering for heritage retrofits. Two strategic archetypes dominate: integrated vertical transport providers with captive maintenance revenue, and modular system specialists with pre-fabricated shaftway capabilities. M&A activity concentrates on digital monitoring technology acquisition, while capacity expansion targets pneumatic production lines for healthcare clean-environment specifications.
Among diversified elevator conglomerates, Otis Elevator Company and Schindler Group exemplify the integrated-service archetype with established North American and European hospitality corridor presence. Kone Corporation occupies a position within the digital convergence tier, representing predictive maintenance platform development. These three anchors illustrate how certification compliance and IoT integration are separating viable competitors from price-pressured assemblers dependent on commodity drive mechanisms.
| Leading Market Players |
|---|
| Otis Elevator Company |
| Schindler Group |
| Thyssenkrupp AG |
| Kone Corporation |
| Mitsubishi Electric Corporation |
| Stannah Lifts Holdings Ltd |
| Waupaca Elevator Company |
| Hitachi Ltd |
| Matot, Inc. |
| Others |
Supply & Pricing Matrix
Captive in-house production of precision reduction gears anchors pricing power for Japanese and German OEMs, while outsourced motor assembly exposes mid-tier assemblers to commodity volatility. This integration choice separates vendors who command lifecycle service premiums from those competing on upfront capital expenditure alone.
Pricing Analysis
Distributor margins in North American hospitality corridors compress as multi-unit restaurant operators consolidate procurement through third-party facilities aggregators. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels tracks ASME A17.1 validation tiers. Cost compression in the economy tier intensifies because steel and copper input volatility erodes assembler profitability. Price sensitivity concentrates among independent restaurant operators in Texas and California markets, while hospital pharmacy buyers in Japan and Germany prioritize contamination control over capital outlay.
Supply Chain Analysis
Dual-sourcing requirements for high-torque reduction gears mandate Japanese and German specialty manufacturer qualification, extending lead times for assemblers seeking supply security. Precision gearing production concentrates in Japan, Germany, and select United States industrial clusters. Winding drum mechanisms and electric traction motors draw from copper winding suppliers and steel fabricators in these same geographies. Single-source vulnerability in seismic-certified component supply exposes assemblers to METI qualification bottlenecks. Distribution runs through OEM captive service networks in premium segments and independent installer channels in residential applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dumbwaiter Lifts Market reads as a late-cycle quality story where specification demand hardens toward certified, digitally monitored systems. Labor efficiency mandates across mid-scale restaurant chains accelerate this shift toward premium lifecycle-cost procurement.
For Market Incumbents: Deepen captive maintenance revenue through IoT-enabled predictive service contracts that absorb break-fix revenue pools. Fortify seismic certification capabilities to defend Japanese hospital pharmacy positions against pneumatic specialists. Priority investment targets modular shaftway pre-fabrication to compress active-site downtime for restaurant chain accounts. For New Entrants and Emerging Players: Independent installer networks in United States hospitality corridors offer white-space entry where OEM service density remains fragmented. Target mid-market restaurant segments in Texas and California through facilities management aggregator partnerships. Specification engineering support for heritage retrofit projects opens margin premiums unavailable in standard-configuration volume plays. For Investors and Strategic Acquirers: Roll-up economics work for regional pneumatic specialists because contamination control protocols in Japanese and German healthcare facilities are consolidating procurement toward certified clean-environment vendors. Five-to-ten year viability favors acquisition targets with documented METI seismic validation and existing hospital pharmacy reference installations. Watch for accessibility regulation expansions that reclassify larger-capacity units into passenger lift inspection protocols as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | IoT cycle-tracking shifts service pricing toward outcome metrics in United States restaurant chains. |
| Seismic Certification Investment | METI compliance filters lower-tier suppliers from Japanese hospital pharmacy specifications. |
| Modular Shaftway Pre-fabrication | Reduced active-site downtime opens mid-market restaurant segments previously blocked by disruption concerns. |
| Pneumatic Production Line Expansion | Sealed pressure-differential systems capture German and Japanese healthcare cleanroom demand. |
| Heritage Retrofit Engineering Capability | Custom adaptation to non-standard floor heights commands margin premiums in Bavaria and North Rhine-Westphalia. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from elevator OEM procurement directors, restaurant facilities managers, hospital biomedical engineers, and independent installer network operators. Secondary validation drew from ASME A17.1 code revision filings, EU Machinery Directive enforcement bulletins, METI building equipment certification databases, and hospitality sector capital expenditure disclosures. Bottom-up installation demand estimates and top-down equipment production data were triangulated for segment-level consistency.
Segment-weighting across drive mechanism type, installation constraint category, and end-user procurement sophistication anchored the analytical framework. Modeled dimensions included electric traction versus pneumatic architecture, modular versus custom installation, and commercial kitchen versus hospital versus residential application. CAGRs were derived from installed base replacement cycles and new construction penetration curves. Forecast inputs incorporated steel and copper price trajectory assumptions alongside regulatory compliance timeline shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to accessibility regulation reclassification risks and seismic code amendment schedules. Deviation in EU Machinery Directive enforcement intensity or METI qualification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Escalator Market
Building Automation Systems
Automated Daylight Harvesting Systems Market