
 Escalator Market | 2026-2036
Escalator Market Size, Share, and Industry Trends Forecast 2026-2036
Escalator Market Analysis
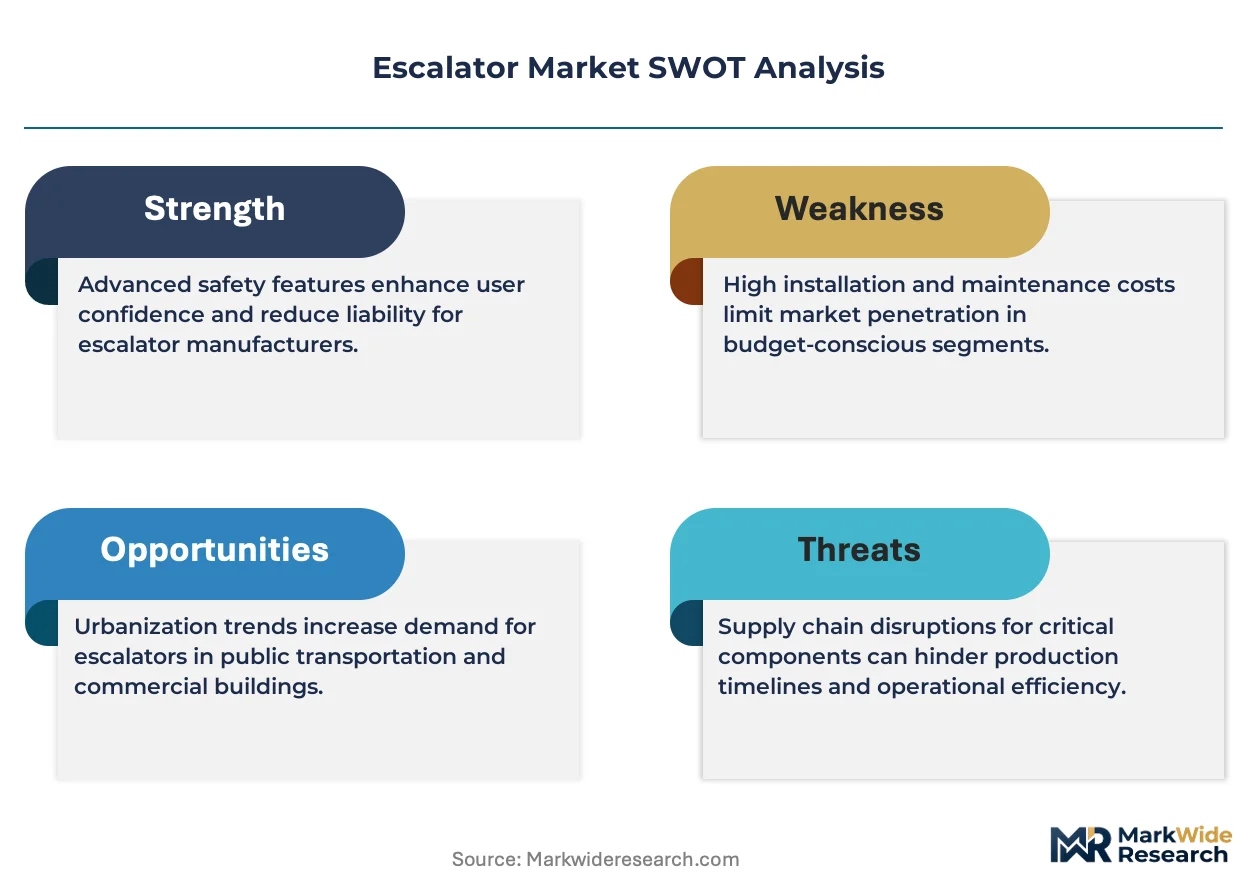
The EU Green Deal is broadening sustainability requirements for public infrastructure procurement across European transit hubs. TK Elevator GmbH leverages its German engineering base to dominate premium commercial installations in Frankfurt and Munich. Hyundai Elevator Co. Ltd anchors its position through captive supply of core drive systems from its Changwon manufacturing complex. Otis Worldwide Corporation sustains global service density through predictive maintenance platforms that reduce urban downtime.
An escalator is a continuously moving staircase comprising linked steps on a circulating track, typically driven by an electric motor at speeds between 0.5 and 0.75 meters per second, designed to transport pedestrians between building floors or transit levels. Commercial escalators lead product type demand as shopping complexes and transport terminals require bidirectional flow capacity with load ratings exceeding 9,000 passengers per hour. Heavy-duty escalators represent the fastest-growing product category due to airport expansion projects requiring extended rise heights and continuous operation cycles. Predictive maintenance captures expanding margin pools as sensor-based vibration analysis shifts service contracts from reactive to outcome-based models.
The EU Machinery Directive and CE marking requirements shape product compliance costs for escalator manufacturers serving European markets. China's SAMR enforces GB 16899 safety standards that mandate brake system redundancy and skirt deflection limits on new installations. India's BIS certification for vertical transportation equipment creates market access barriers that favor established multinationals with local testing partnerships. Stakeholders must monitor how evolving fire safety codes for deep metro stations reshape step material specifications and emergency stop protocols.
Market Dynamics
Metro rail authorities in China, Germany, and India are accelerating heavy-duty escalator procurement as deep-tunnel station designs demand extended rise heights and continuous-duty drive systems.
Growth Catalysts
- High-speed rail station construction:China's expanding network of intercity terminals requires bidirectional escalator banks with passenger throughput exceeding 9,000 per hour.
- EU F-Gas Regulation:Climate-controlled escalator environments in Frankfurt and Munich transit hubs must transition refrigerants, triggering equipment replacement cycles.
- Predictive maintenance platforms:Sensor-based vibration analysis is automating service scheduling and compressing urban downtime incidents.
Market Restraints
- Steel and copper price volatility:Step chain assemblies and motor windings face input cost swings that compress OEM margins on fixed-price transit contracts.
- Drive system supply concentration:Premium helical gearboxes and permanent magnet motors concentrate among German and Japanese component specialists.
- Deep metro fire safety codes:Emergency ventilation and step material specifications in London and Paris are extending project approval timelines.
Strategic Opportunities
- India's BIS certification pathway:Vertical transportation equipment standards favor multinationals with local testing partnerships, creating protected market access.
- Airport expansion wave:Middle Eastern and Southeast Asian aviation hubs require heavy-duty units with 15-meter rise heights and 20-hour daily operation cycles.
- EU Green Deal procurement mandates:Sustainability criteria in public infrastructure tenders are elevating lifecycle assessment scores over first-cost bidding.
Industry Challenges
- Mechatronics technician shortage:Drive system calibration and brake redundancy testing require specialized skills scarce in emerging market installation teams.
- GB 16899 compliance timeline:China's SAMR brake system redundancy mandates are forcing design revalidation for existing platform portfolios.
- Legacy controller integration:Digital retrofit kits face protocol incompatibility with 1990s-era relay logic systems in aging European metro networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Escalator Market |
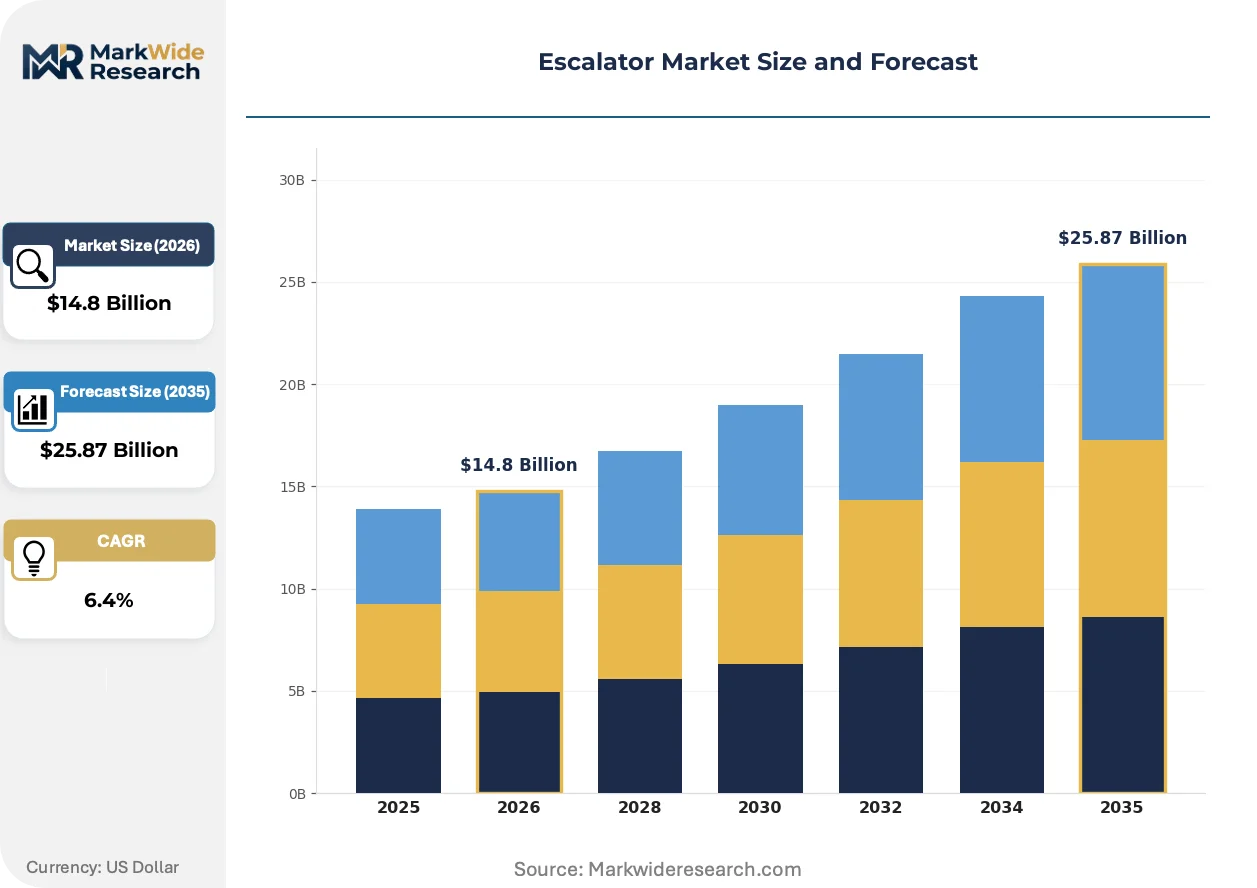
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Escalators, Residential Escalators, Heavy-Duty Escalators, Portable Escalators Installation Type: Indoor Installation, Outdoor Installation, Permanent Installation, Temporary Installation End User: Retail Outlets, Airports, Hospitals, Office Buildings Maintenance Type: Preventive Maintenance, Corrective Maintenance, Predictive Maintenance, Emergency Maintenance |
| Companies Covered | TK Elevator GmbH, Hyundai Elevator Co. Ltd, Otis Worldwide Corporation, Mitsubishi Electric Corporation, Toshiba Corporation, Schindler Group, Fujitec Co. Ltd, SJEC Corporation, KONE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Escalator Market Emerging Trajectories
Digital condition monitoring and regenerative drive technology are compressing total cost of ownership calculations for transit authorities evaluating 30-year asset lifecycles.
Machine vision step-detect systems are automating foreign object identification and emergency stop triggering. Tokyo Metro and Singapore's LTA are piloting camera arrays that map step surface integrity in real-time. This capability is automating maintenance dispatch decisions and reducing manual inspection labor.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in climate-controlled escalator environments. Hydrocarbon and CO2 alternatives require redesigned compressor architectures and safety ventilation systems. Heavy-duty commercial installations in Germany and France face the steepest retrofit obligations.
Lifecycle service contracts are displacing transactional maintenance arrangements. Transit authorities in Madrid and Milan now specify availability guarantees with penalty clauses. This purchasing pattern compresses vendor selection toward integrated manufacturers with captive spare parts logistics.
Escalator Market Segmentation
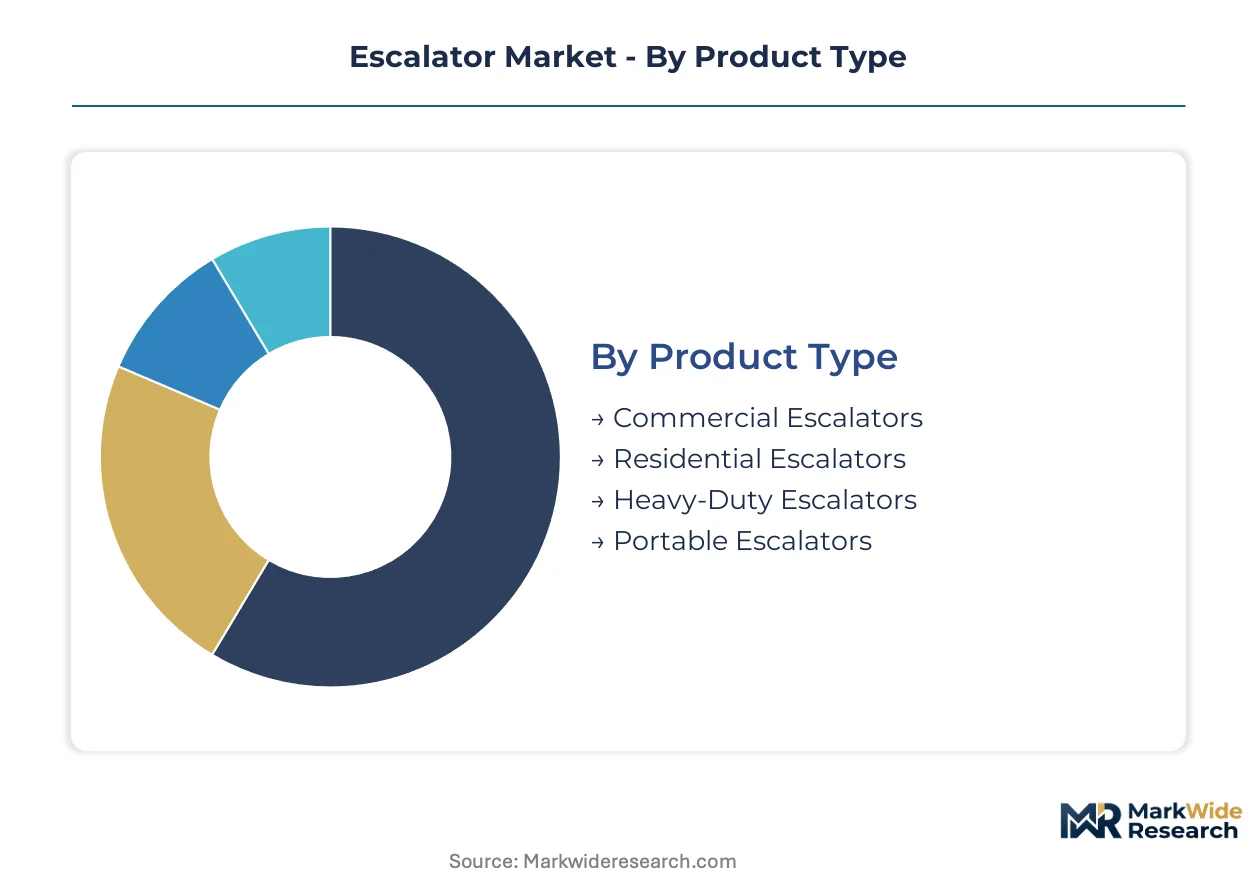
Escalator procurement patterns diverge sharply between high-throughput transit infrastructure and lower-duty commercial environments. Specification requirements for step chain durability, drive system redundancy, and climate protection vary dramatically across installation contexts and end-use intensity.
Product Type:
Volume concentration sits with standardized commercial units, while premium engineering margins concentrate in specialized heavy-duty configurations.
- Commercial Escalators:These units handle bidirectional passenger flows in shopping complexes and transport terminals with load ratings exceeding 9,000 passengers per hour. Demand concentrates in China's high-speed rail station construction where TK Elevator and Otis compete for terminal infrastructure contracts.
- Heavy-Duty Escalators:Extended rise heights up to 15 meters and continuous-duty drive systems characterize airport and deep metro applications. Middle Eastern and Southeast Asian aviation hubs are driving procurement for units with 20-hour daily operation cycles and enhanced brake redundancy.
- Residential Escalators:Compact designs with reduced step width and lower speed ratings serve luxury housing developments and assisted living facilities.
- Portable Escalators:Modular truss designs enable rapid deployment for temporary events and construction site access.
Mature deployment sits with commercial escalators in established retail corridors. Newer deployment is concentrated in heavy-duty units for deep-tunnel metro systems.
Installation Type:
Environmental exposure determines specification tiers, with climate-controlled indoor installations commanding standard pricing and weatherized outdoor units requiring premium engineering.
- Indoor Installation:Climate-controlled environments in Frankfurt and Munich transit hubs dominate this segment. EU F-Gas Regulation compliance is forcing refrigerant transitions in escalator machine rooms, triggering replacement cycles.
- Outdoor Installation:Weatherized truss enclosures, heated step chains, and sealed drive systems withstand temperature extremes and precipitation exposure.
- Permanent Installation:Fixed infrastructure with 30-year asset lifecycles requires lifecycle service contracts with availability guarantees.
- Temporary Installation:Modular anchoring systems and rapid commissioning protocols serve construction phases and event venues.
Permanent installations anchor service revenue streams through long-term maintenance agreements. Temporary deployment is expanding most quickly in modular transit construction projects.
End User:
Throughput intensity and operating hours create distinct specification bands across verticals.
- Airports:Extended rise heights and continuous operation cycles demand heavy-duty drive systems with redundant braking. Singapore's LTA and Tokyo Metro are piloting machine vision step-detect systems for automated maintenance dispatch.
- Retail Outlets:Bidirectional flow capacity with moderate duty cycles characterizes shopping complex installations.
- Hospitals:Low-speed configurations with enhanced handrail sanitation and emergency stop accessibility serve patient transport needs.
- Office Buildings:Standard commercial specifications with peak-load capacity for morning and evening commuter surges.
Retail outlets represent established volume deployment. Airports are gaining share fastest through global aviation hub expansion.
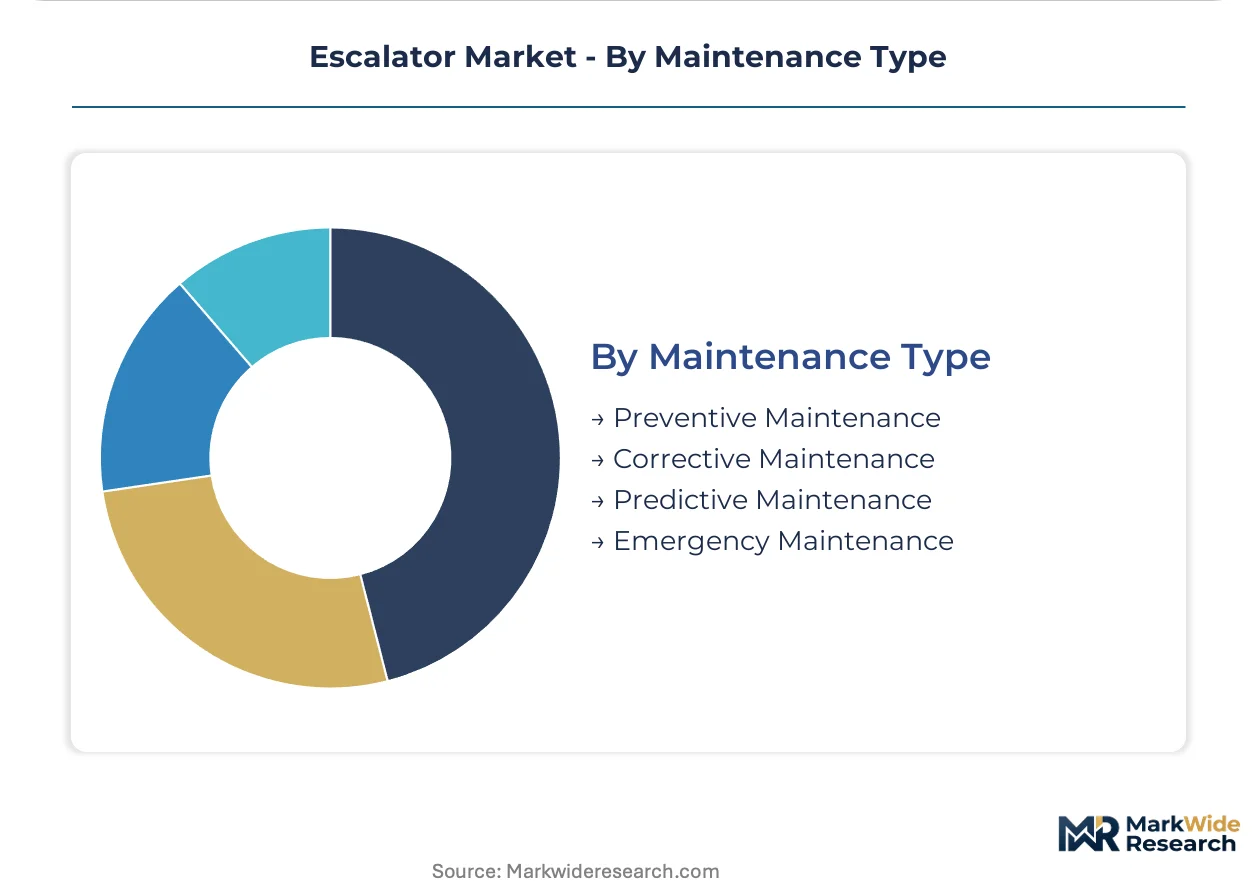
Maintenance Type:
Service contract economics are shifting from transactional repairs to outcome-based availability models.
- Predictive Maintenance:Sensor-based vibration analysis and digital condition monitoring automate service scheduling. Madrid and Milan transit authorities now specify availability guarantees with penalty clauses, compressing vendor selection toward integrated manufacturers.
- Preventive Maintenance:Scheduled component replacement based on cycle counts and calendar intervals.
- Corrective Maintenance:Reactive repair dispatch following failure events.
- Emergency Maintenance:24-hour response protocols for safety-critical failures and entrapment incidents.
Preventive maintenance remains the baseline service model. Predictive platforms are displacing reactive arrangements in premium transit contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's high-speed rail corridor drives the heaviest concentration of heavy-duty escalator procurement worldwide, with China's SAMR enforcing GB 16899 safety standards that mandate brake system redundancy across all new installations.
China
High-speed rail station construction in Beijing, Shanghai, and Guangzhou requires bidirectional escalator banks with passenger throughput exceeding 9,000 per hour. SAMR's GB 16899 standards enforce skirt deflection limits and emergency stop protocols that extend design revalidation timelines. The Yangtze River Delta cluster anchors domestic manufacturing capacity for step chain assemblies and drive systems.
Germany
Frankfurt and Munich transit hubs are accelerating equipment replacement cycles under EU F-Gas Regulation phase-down schedules for climate-controlled escalator environments. The EU Machinery Directive and CE marking requirements shape compliance costs for manufacturers serving European markets. Baden-Württemberg's engineering corridor concentrates premium helical gearbox production for heavy-duty applications.
United States
Airport expansion projects in Atlanta, Dallas-Fort Worth, and Denver drive demand for extended rise heights and continuous-duty drive systems. FAA coordination with transit authorities influences fire safety specifications for deep metro stations. The Southeast manufacturing belt hosts assembly operations for standardized commercial units serving retail and office verticals.
India
Metro rail authorities in Delhi, Mumbai, and Bangalore are procuring heavy-duty units for deep-tunnel station designs requiring 15-meter rise capabilities. BIS certification for vertical transportation equipment creates market access barriers favoring multinationals with local testing partnerships. Maharashtra's industrial corridor is developing component sourcing networks for step chain and motor assemblies.
Japan
Tokyo Metro pilots machine vision step-detect systems that automate foreign object identification and emergency stop triggering. METI efficiency standards drive regenerative drive technology adoption in high-throughput installations. The Kanto region's precision manufacturing base supplies permanent magnet motors and sensor arrays for predictive maintenance platforms.
Escalator Market Vendor Landscape
The competitive structure tilts toward integrated manufacturers with captive service networks and backward integration into core drive systems. Consolidation pressure concentrates among premium-tier suppliers capable of delivering 30-year lifecycle contracts with availability guarantees. Three archetypes dominate: German-engineered premium specialists, Korean-Japanese integrated conglomerates with captive component supply, and scale-driven maintenance platform operators. Geographic expansion through local certification partnerships and vertical integration into predictive maintenance software represent the dominant competitive vectors.
Within the German-engineered tier, TK Elevator GmbH exemplifies premium commercial positioning through European transit hub dominance. Among Asia-Pacific integrated manufacturers, Hyundai Elevator Co. Ltd and Mitsubishi Electric Corporation occupy positions anchored by captive supply of core drive systems from dedicated manufacturing complexes. Otis Worldwide Corporation sits within the scale-driven maintenance platform archetype, leveraging predictive service density to compress urban downtime incidents across diversified geographic footprints.
| Leading Market Players |
|---|
| TK Elevator GmbH |
| Hyundai Elevator Co. Ltd |
| Otis Worldwide Corporation |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Schindler Group |
| Fujitec Co. Ltd |
| SJEC Corporation |
| KONE Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Japan anchor premium-tier supply, translating engineering heritage into pricing discipline that resists commoditization pressure from Chinese scale manufacturers. Their captive production of helical gearboxes and permanent magnet motors insulates margin pools while transit authorities in Frankfurt and Munich negotiate lifecycle contracts with availability guarantees.
Pricing Analysis
Value-based pricing anchored to uptime guarantees dominates heavy-duty transit contracts, with availability penalties replacing fixed-fee structures. Premium-mid-economy pricing differentiation tracks certification tier and brake redundancy specifications under China's GB 16899 and EU Machinery Directive. Pricing pressure stems from steel and copper volatility compressing OEM margins on fixed-price rail station contracts. Municipal buyers in India and Southeast Asia exhibit highest price sensitivity, while airport authorities in the Middle East prioritize performance over first-cost bidding.
Supply Chain Analysis
Dual-sourcing requirements from metro rail authorities in China, Germany, and India mandate qualified secondary suppliers for step chain assemblies and drive control systems. Manufacturing concentrates in China, Germany, and South Korea for heavy-duty components. Supply chains draw from specialty steel mills in Baden-Württemberg, copper winding facilities in the Yangtze River Delta, and precision gear producers in Changwon. Single-source vulnerability persists for permanent magnet motors and sensor arrays. Distribution runs through captive service networks with regional spare parts hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as lifecycle service contracts with penalty clauses force sub-scale maintenance providers into exit or acquisition. The EU Green Deal's sustainability procurement mandates favor integrated manufacturers with certified carbon accounting.
For Market Incumbents: Extend predictive maintenance platform coverage to compress urban downtime incidents below competitor thresholds. Deepen backward integration into step chain and brake system production to secure margin pools against steel price volatility. Capture GB 16899 compliance leadership in China through early design revalidation investments. For New Entrants and Emerging Players: Digital-channel routes through retrofit controller kits offer lower-friction entry than new installation competition. Target India's BIS certification pathway by partnering with Maharashtra-based testing facilities for market access. Focus on modular portable escalator deployment for temporary transit construction phases in Southeast Asia. For Investors and Strategic Acquirers: Distressed-cycle entries favor maintenance platform operators with dense urban service footprints in legacy European metro networks. Five-to-ten year viability hinges on predictive software monetization and spare parts logistics integration. Monitor SAMR enforcement timelines for GB 16899 brake redundancy mandates as inflection signal for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Expansion | Sensor-based vibration analysis automates service scheduling for Madrid and Milan transit authorities. |
| Regenerative Drive Technology Adoption | METI efficiency standards in Japan accelerate energy recovery system deployment in high-throughput installations. |
| GB 16899 Compliance Investment | Brake redundancy revalidation secures platform access across China's high-speed rail station construction pipeline. |
| Local Testing Partnership Formation | BIS certification pathways in India create protected market access for multinationals with Maharashtra-based facilities. |
| F-Gas Regulation Retrofit Capability | Hydrocarbon and CO2 compressor architectures capture replacement cycles in Frankfurt and Munich climate-controlled environments. |
Methodological Framework
Independent corroboration across escalator OEM technical directors, metro rail procurement officers, and aftermarket service heads underwrites the qualitative findings. Primary interviews with maintenance platform operators and component specialists in Germany, China, and Japan informed supply chain concentration assessments. Secondary validation drew from SAMR regulatory filings, EU Machinery Directive compliance databases, customs trade records for step chain assemblies, and SEC disclosures from listed vertical transportation equipment manufacturers. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects. The analytical framework models segmentation by product type, installation environment, end-use intensity, and maintenance contract structure. CAGRs were derived from infrastructure pipeline tracking and replacement cycle analysis. Escalator-specific inputs include high-speed rail station construction schedules, airport expansion timelines, and F-Gas Regulation phase-down compliance deadlines.
Inputs from regulatory filings and OEM technical documentation were available through the study window; gaps in real-time transit authority procurement data introduce uncertainty bands around near-term volume estimates. Deviation in China's infrastructure stimulus intensity or EU Green Deal enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Building Automation and Control System Market