
 Energy Storage System (ESS) Battery Market | 2026-2036
Energy Storage System (ESS) Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Storage System (ESS) Battery Market Insights
China's gigafactory corridor is reshaping cost curves for ESS battery supply. CATL leverages vertical integration from cathode materials to containerized systems, sustaining price competitiveness across utility-scale tenders. BYD anchors its position through proprietary lithium iron phosphate cell chemistry and captive demand from its renewable project pipeline. Tesla differentiates via software-integrated Powerpack and Megapack architectures that optimize grid dispatch algorithms.
An energy storage system battery is an electrochemical device engineered for repeated charge-discharge cycles at scales from residential kilowatt-hours to utility-scale gigawatt-hours, typically employing lithium iron phosphate or nickel manganese cobalt oxide cathodes with graphite anodes in prismatic or cylindrical formats, designed to buffer electricity supply against demand fluctuations and renewable generation variability. Lithium-ion chemistry dominates installed capacity due to energy density advantages and declining cell costs, while flow battery technology occupies niche applications requiring extended discharge duration beyond four hours. Utility-scale deployment represents the fastest-expanding application segment as independent power producers and grid operators procure multi-hundred-megawatt installations, whereas residential systems compete on backup power reliability and solar self-consumption economics.
The US Federal Energy Regulatory Commission's Order 841 mandates wholesale market access for storage resources, while China's National Energy Administration enforces grid-side storage quotas for renewable project interconnection. The EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds that condition market access for imported cells. Stakeholders must monitor evolving chemistry-specific safety standards and local content requirements that determine project economics and supplier qualification.
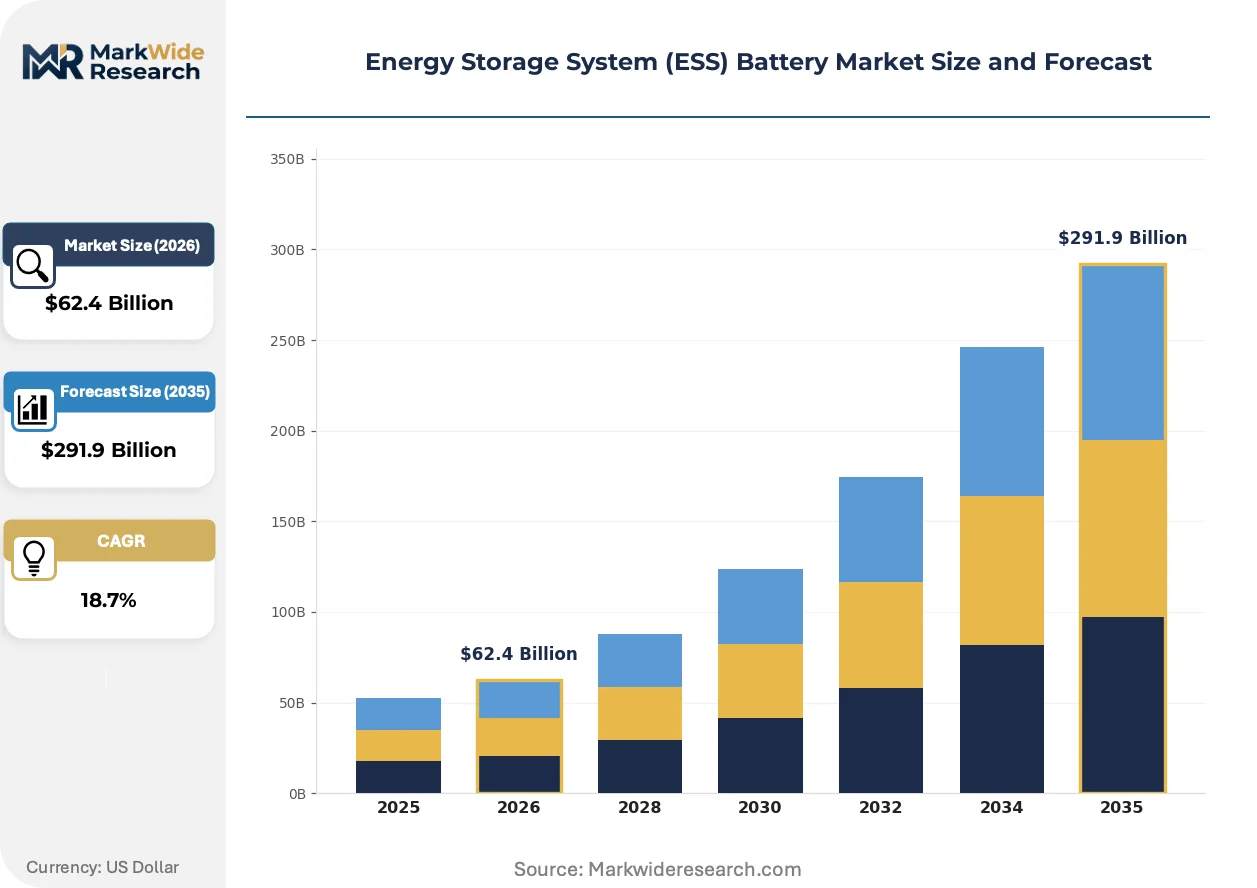
Market Dynamics
Utility-scale procurement of lithium-ion battery banks is compressing project development timelines as grid operators in Texas and California accelerate capacity additions to manage renewable intermittency.
Growth Catalysts
- US IRA standalone storage tax credit:The Inflation Reduction Act's investment tax credit redirects capital toward domestic cell and system manufacturing, lowering levelized cost of storage for independent power producers.
- China's grid-side storage quotas:The National Energy Administration mandates energy storage for renewable project interconnection, creating captive demand in Jiangsu and Guangdong provinces.
- Lithium iron phosphate chemistry maturation:Cell-level cost declines and cycle life improvements enable four-hour duration systems to compete on economics with peaker plants.
Market Restraints
- Upstream lithium concentration:Spodumene and brine processing capacity concentrates in Australia and Chile, exposing cell manufacturers to feedstock price volatility.
- Four-hour duration ceiling:Lithium-ion chemistry faces technical limitations for multi-day storage applications, ceding longer-duration tenders to vanadium flow alternatives.
- EU Battery Regulation carbon thresholds:The European Union's carbon footprint disclosure and recycled content mandates create compliance friction for imported cells.
Strategic Opportunities
- India's renewable-plus-storage tenders:The Solar Energy Corporation of India and state discoms are bundling storage with solar and wind auctions, opening procurement channels for system integrators.
- Behind-the-meter commercial aggregation:Virtual power plant software converges with distributed battery assets, enabling demand response revenue stacking for C&I customers.
- Second-life automotive batteries:Retired electric vehicle packs from passenger and commercial fleets offer lower-cost stationary storage for backup power applications.
Industry Challenges
- NFPA 855 fire code compliance:Local jurisdictions impose varying installation spacing and suppression requirements, extending project permitting timelines.
- Power conversion system integration:Containerized battery banks require specialized inverters and energy management software, complicating EPC contractor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage System (ESS) Battery Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $291.9 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Flow Battery Capacity: 10 kWh, 50 kWh, 100 kWh, 250 kWh Application: Residential, Commercial, Industrial, Utility-scale Deployment Model: On-grid, Off-grid, Hybrid, Containerized |
| Companies Covered | Tesla, LG Energy Solution, Samsung SDI, BYD, CATL, Panasonic, Fluence, ESS Inc., Sungrow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage System (ESS) Battery Market Trends and Innovations
Digital twin modeling and predictive analytics are reshaping how asset owners optimize battery dispatch and degradation management across utility-scale portfolios.
Solid-state electrolyte research is digitizing cell monitoring architectures. Automotive and stationary manufacturers are embedding fiber-optic sensors and edge computing modules into pouch and prismatic formats. This convergence is digitizing warranty underwriting and enabling real-time state-of-health pricing in secondary markets.
China's MIIT battery passport requirements are forcing supply chain disclosure across cathode material provenance. The regulation mandates blockchain-traceable documentation from mining through cell assembly. European importers are responding by qualifying alternative suppliers in Indonesia and the Democratic Republic of Congo.
Independent power producers are consolidating procurement through multi-year framework agreements rather than project-specific tenders. This channel compression favors system integrators with balance-sheet capacity to carry inventory. The shift is most visible in ERCOT and CAISO interconnection queues, where developers pre-commit to technology platforms before site control.
Energy Storage System (ESS) Battery Market Segmentation
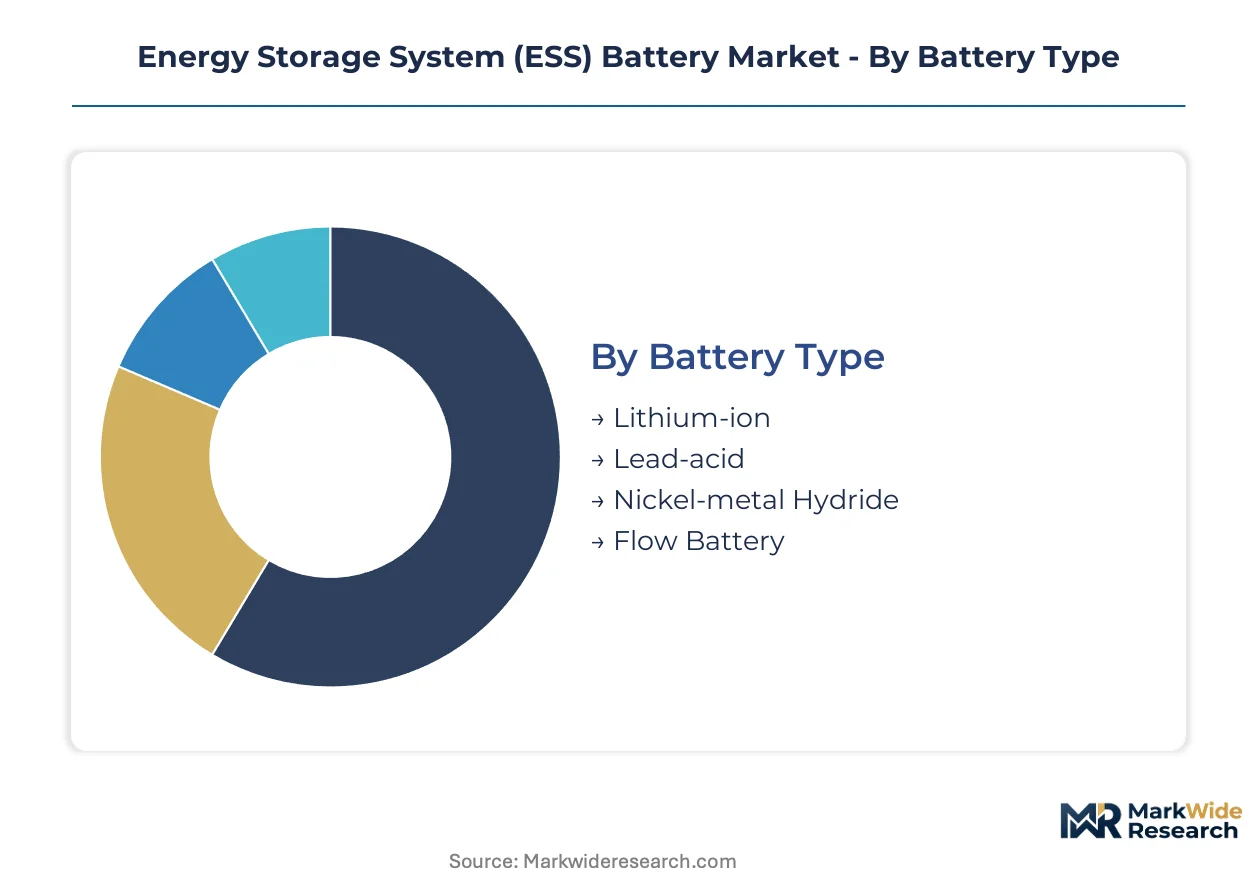
Segmentation in the ESS battery market reveals how chemistry choices, scale configurations, and deployment contexts reshape procurement patterns and supplier economics. Each dimension carries distinct margin profiles, regulatory exposure, and integration complexity that determine competitive positioning.
Battery Type:
Mature electrochemies dominate installed capacity while emerging alternatives carve duration-specific niches.
- Lithium-ion:Cells employ lithium iron phosphate or nickel manganese cobalt oxide cathodes with graphite anodes, achieving energy densities above 150 Wh/kg. Utility-scale procurement in Texas and California concentrates here due to four-hour duration economics and established supply chains from Jiangsu and Guangdong production clusters.
- Flow Battery:Vanadium redox systems separate energy and power scaling through liquid electrolyte tanks, enabling discharge durations beyond eight hours. Demand clusters in Germany and Australia where grid operators tender multi-day storage for seasonal renewable shifting.
- Lead-acid:Mature flooded and valve-regulated designs serve backup power in telecom and rural electrification with lower capital cost but limited cycle life.
- Nickel-metal Hydride:Rare earth hydride anodes deliver moderate energy density for niche industrial applications requiring wide temperature tolerance.
Lithium-ion retains volume leadership; flow battery holds the steepest expansion curve for duration-extended tenders.
Capacity:
Scale tiers map directly to customer sophistication and procurement channel structure.
- 100 kWh:Commercial and light industrial installations balance footprint constraints with peak shaving economics. California's SGIP incentive program drives adoption among C&I customers seeking demand charge management.
- 250 kWh:Containerized configurations serve microgrids and small utility substations with modular expansion paths. ERCOT interconnection queues show rising pre-commitment to this scale for distributed resource aggregation.
- 10 kWh:Wall-mounted residential units pair with rooftop solar for self-consumption optimization in Germany and Australia.
- 50 kWh:Small commercial buildings and agricultural operations deploy this midpoint for backup power and time-of-use arbitrage.
100 kWh systems anchor current procurement volume; 250 kWh configurations are climbing the fastest as virtual power plant aggregation expands.
Application:
End-use contexts determine fire code compliance, warranty terms, and software integration requirements.
- Utility-scale:Grid-connected installations from 100 MW to multi-gigawatt complexes buffer renewable intermittency and provide ancillary services. FERC Order 841 mandates wholesale market access, reshaping developer economics in CAISO and ERCOT territories.
- Residential:Behind-the-meter systems compete on backup reliability and solar self-consumption economics. Australia's NEM regions and Germany's EEG framework drive deployment through tariff structures.
- Commercial:Peak shaving and demand response revenue stacking motivate C&I procurement with shorter payback horizons than residential.
- Industrial:Manufacturing facilities prioritize power quality and uninterrupted production over energy arbitrage, demanding higher reliability tiers.
Utility-scale commands the dominant share of megawatt-hour additions; residential is gaining share fastest as distributed energy resource management platforms mature.
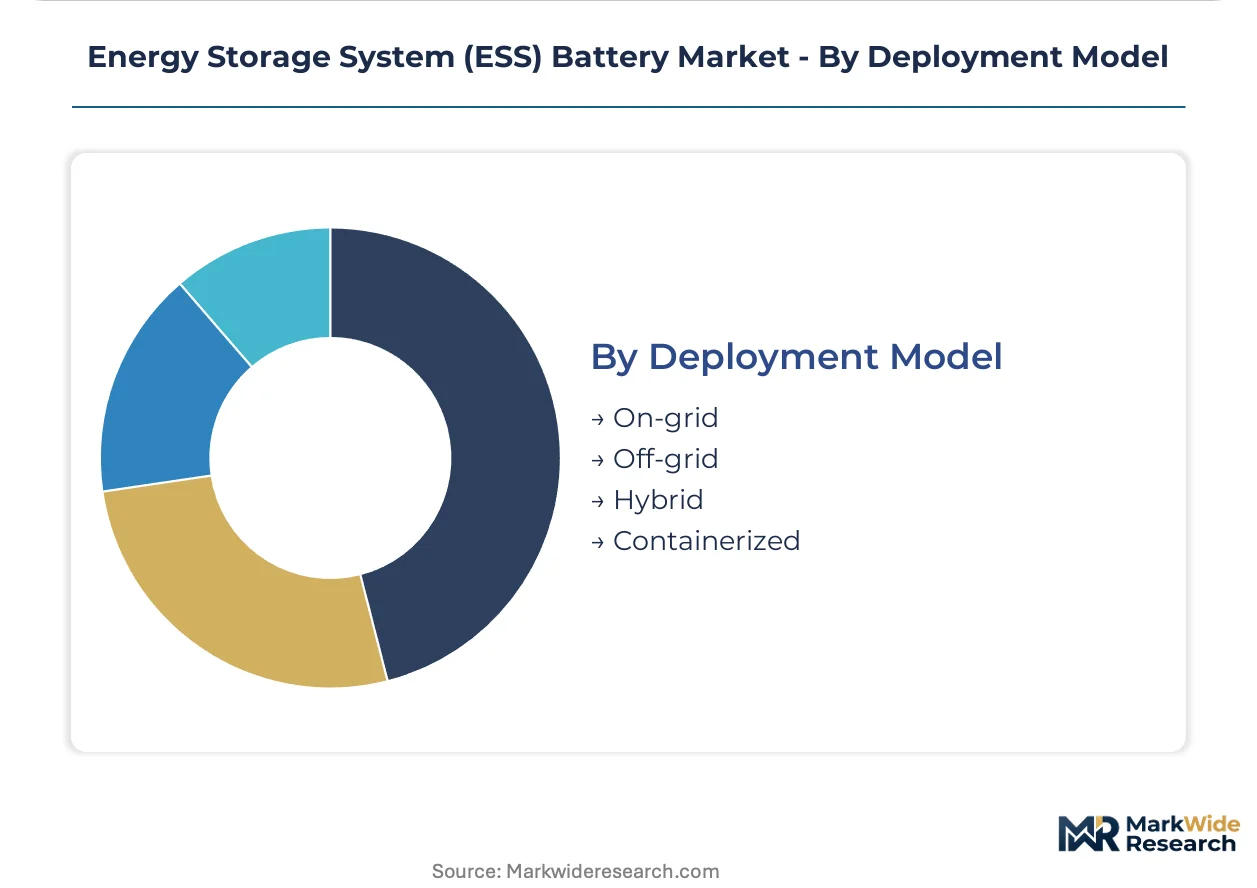
Deployment Model:
Grid integration architecture determines inverter specifications, permitting complexity, and operational revenue streams.
- Containerized:Factory-integrated battery banks with thermal management and power conversion systems compress field installation timelines. China's integrated cell-to-system production clusters achieve cost advantages through standardized 20-foot and 40-foot formats.
- Hybrid:Co-located solar-plus-storage configurations share interconnection infrastructure and capture investment tax credit stacking in the US.
- On-grid:Direct utility interconnection enables frequency regulation and capacity market participation with strict cybersecurity protocols.
- Off-grid:Islanded microgrids serve remote mining operations and rural electrification with diesel displacement economics.
Containerized systems lead procurement volume; hybrid deployments show the steepest trajectory as solar-plus-storage tenders proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell and system manufacturing clusters in Jiangsu and Guangdong provinces anchor supply-side capacity. Texas and California utilities are accelerating procurement timelines. Germany's carbon border adjustments are conditioning import access for Asian producers.
United States
ERCOT and CAISO interconnection queues show multi-gigawatt battery additions as grid operators manage solar and wind intermittency. FERC Order 841 mandates wholesale market participation for storage resources. Texas developers pre-commit to containerized lithium-ion platforms before securing site control.
China
Jiangsu and Guangdong provinces drive integrated cell-to-system production with captive cathode material supply. MIIT battery passport requirements enforce blockchain-traceable documentation from mining through assembly. CATL and BYD anchor manufacturing clusters achieving cost advantages in utility-scale tenders.
Germany
Grid operators tender multi-day storage for seasonal renewable shifting, creating demand clusters for duration-extended technologies. EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds. Industrial buyers in Bavaria and North Rhine-Westphalia qualify suppliers against compliance mandates.
India
Solar Energy Corporation of India bundles storage with solar and wind auctions, opening procurement channels for system integrators. Central Electricity Authority mandates grid-side storage quotas for renewable project interconnection. Gujarat and Karnataka states host emerging assembly operations serving domestic tenders.
Australia
NEM regions drive residential deployment through tariff structures optimizing solar self-consumption. National electricity rules enable distributed battery aggregation into virtual power plants. Queensland and New South Wales host utility-scale installations buffering coal plant retirements.
Energy Storage System (ESS) Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell and material production. The vendor base separates into consolidated cell manufacturers with captive demand, independent system integrators with software differentiation, and project developers with offtake relationships. Two strategic archetypes dominate: vertically integrated conglomerates controlling cathode-to-container supply chains, and pure-play integrators bundling third-party cells with power conversion and energy management. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure lithium feedstock and inverter supply.
Among the named players, Tesla and BYD exemplify platform integrators with proprietary system architectures, while CATL represents the upstream cell specialist archetype with downstream extension into containerized solutions. LG Energy Solution and Samsung SDI occupy positions bridging component supply and system integration. These five anchors illustrate how competitive positioning stratifies across the value chain, with each archetype defending margin through distinct control points—software dispatch algorithms, captive renewable project pipelines, or integrated manufacturing scale.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| Samsung SDI |
| BYD |
| CATL |
| Panasonic |
| Fluence |
| ESS Inc. |
| Sungrow |
| Others |
Pricing and Supply Chain Analysis
Australian and Chilean spodumene and brine processing capacity concentrates feedstock pricing power with cathode material producers in Jiangsu and Guangdong, compressing margin pools for system integrators downstream while rewarding captive lithium sourcing.
Pricing Analysis
The US IRA standalone storage tax credit dictates the pricing tier structure across utility-scale tenders, separating ITC-eligible domestic content from imported standard-tier systems and premium software-integrated architectures. Price differentiation rests on certification grade—UL 9540A fire safety validation commands premiums over baseline IEC compliance—and volume scale through multi-year framework agreements. Cost compression in containerized lithium-ion systems is intensifying because CATL and BYD are achieving integrated cell-to-system production advantages. Independent power producers show highest price sensitivity through pre-commitment to technology platforms before site control, while grid operators with mandated storage quotas exhibit lowest sensitivity.
Supply Chain Analysis
Export controls on advanced battery manufacturing equipment limit technology transfer to emerging production hubs, concentrating cell supply in China, South Korea, and Japan. Raw material dependencies center on lithium carbonate from Australian hard-rock and Chilean brine operations, plus cobalt feedstock from the Democratic Republic of Congo. Single-source vulnerability runs through China's dominance of cathode active material processing. Distribution runs through EPC contractors with specialized power conversion system integration capabilities and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ESS battery market tracks a cyclical recovery anchored to utility-scale procurement waves following renewable interconnection mandates, with capital deployment accelerating through FERC Order 841 market access reforms.
For Market Incumbents: Insulate margin pools by securing captive lithium offtake from Australian spodumene and Chilean brine operations, while investing in NFPA 855-compliant fire suppression systems to preempt permitting delays that threaten project timelines against emerging system integrators with software-integrated dispatch algorithms.
For New Entrants and Emerging Players: Build out virtual power plant aggregation capabilities targeting California's SGIP-incentivized C&I segment, where behind-the-meter 100 kWh deployments offer the most penetrable entry point through demand response revenue stacking without competing directly on utility-scale lithium-ion tenders.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent power producers holding interconnection queue positions in ERCOT and CAISO territories. Long-term viability hinges on offtake contract duration and technology platform standardization. Watch for inflection when grid operators tender multi-day duration requirements that favor vanadium flow battery alternatives over lithium-ion economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | CATL's lithium iron phosphate chemistry control sustains cost advantages in Jiangsu utility tenders. |
| Multi-Year Framework Agreements | ERCOT developers pre-commit to Tesla Megapack platforms before securing interconnection site control. |
| Virtual Power Plant Software Integration | Sunrun and Enphase aggregation platforms enable CAISO demand response revenue stacking for C&I assets. |
| Second-Life Battery Sourcing | Retired EV packs from Tesla and BYD fleets lower stationary storage capital costs for backup power. |
| EU Battery Regulation Compliance | Carbon footprint disclosure mandates force Asian producers to qualify alternative cobalt suppliers in Indonesia. |
Research Methodology
The analysis maps lithium-ion, flow battery, and emerging solid-state chemistries, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators across primary interviews with secondary triangulation against EIA capacity data, FERC interconnection filings, IEA storage outlooks, and MIIT battery passport disclosures. Bottom-up project-level aggregation and top-down regulatory scenario modeling converge through iterative stakeholder feedback.
Assumption sets held lithium carbonate price trajectories and IRA domestic content thresholds fixed while varying renewable penetration rates and grid operator procurement timelines across the analysis window. Segmentation dimensions modeled include battery chemistry type, capacity tier, application context, and deployment architecture. CAGRs derive from installed capacity buildout curves tempered by supply chain constraint functions and interconnection queue processing rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated conglomerates with captive lithium mining assets would shift outcomes. Material shifts in US trade policy toward Chinese cell imports or breakthroughs in solid-state electrolyte manufacturing economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
US Energy Storage Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Energy Storage Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
North America Energy Storage Market
Battery Management System
Automotive Energy Storage System Market