
 Battery Management System (BMS) Market | 2026-2036
Battery Management System (BMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Management System (BMS) Market Insights
Multi-source procurement of BMS semiconductor cores is shifting toward vertically integrated module suppliers. Analog Devices, Inc. sustains technology leadership in precision voltage sensing ICs for high-cell-count packs. Texas Instruments dominates integrated battery monitor and protector chipsets with embedded cell balancing. Sensata Technologies, Inc. leverages its automotive heritage to anchor high-reliability BMS assembly for OEM qualification cycles.
A battery management system comprises hardware and firmware that measure individual cell voltages, temperatures, and state-of-charge to prevent thermal runaway and optimize cycle life across lithium-ion, lead-acid, and solid-state chemistries. Its primary purpose is safeguarding energy storage assets while maximizing usable capacity and discharge rates in electric vehicles, grid storage, and industrial equipment. Modular BMS architectures lead in aftermarket and retrofit applications where scalability matters, while distributed BMS topologies are capturing share in premium electric vehicle platforms requiring cell-level granularity. Solid-state technology segments command attention from R&D budgets despite lithium-ion's current production dominance, as solid-state cells demand fundamentally different monitoring protocols.
The EU Battery Regulation and CE marking requirements under the EU Green Deal are mandating passport-ready traceability and state-of-health disclosure across battery lifecycles. China's SAMR enforces GB standards for battery safety testing that directly shape BMS fault-response thresholds and diagnostic depth. India's BIS certification for battery systems is tightening import compliance, forcing BMS suppliers to adapt firmware for local thermal and grid conditions. Stakeholders must monitor which regulatory jurisdictions will next mandate predictive failure algorithms versus passive monitoring, as this distinction will split R&D investment and product roadmaps.
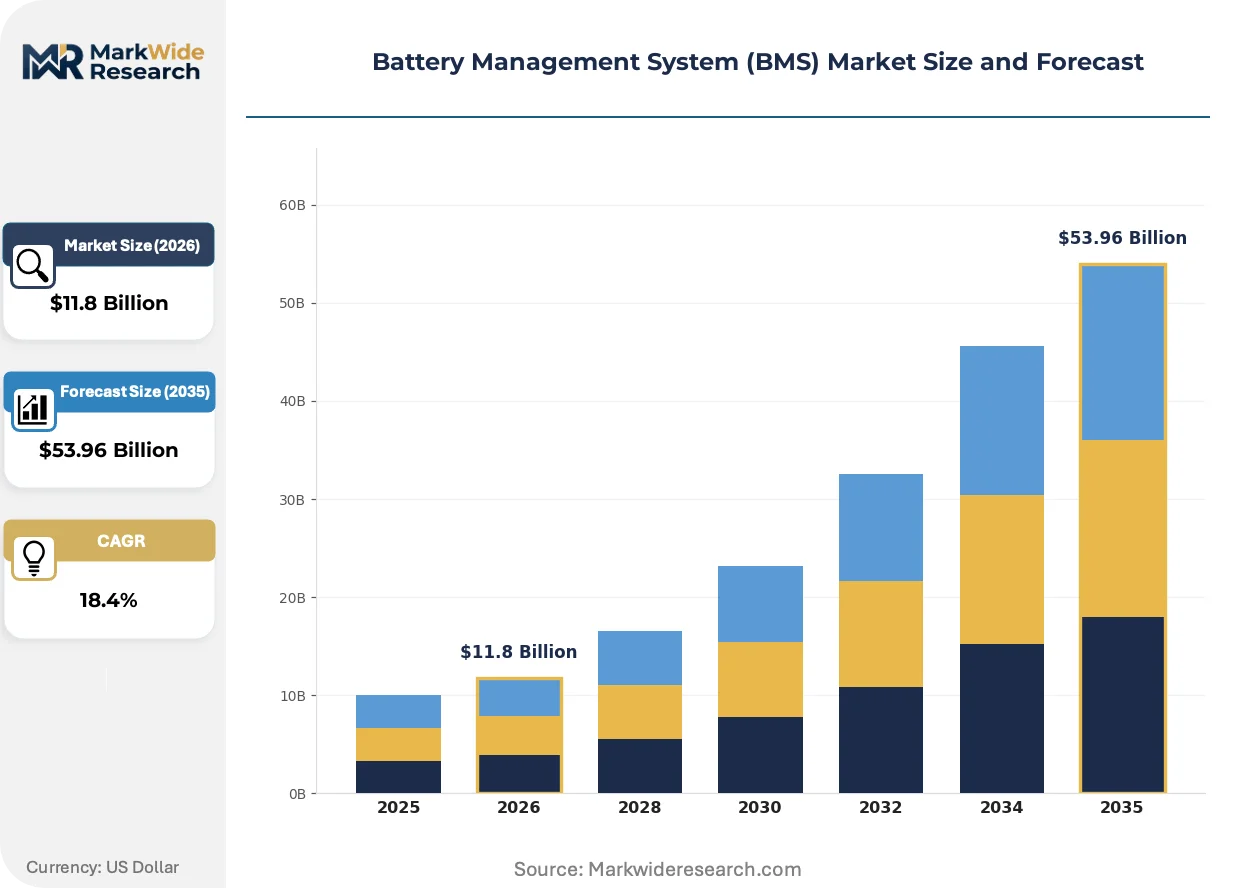
Market Dynamics
Cell-level monitoring granularity is tightening as electric vehicle platforms scale toward 800-volt architectures, forcing semiconductor suppliers to recalibrate voltage sensing precision and thermal modeling firmware across distributed BMS topologies.
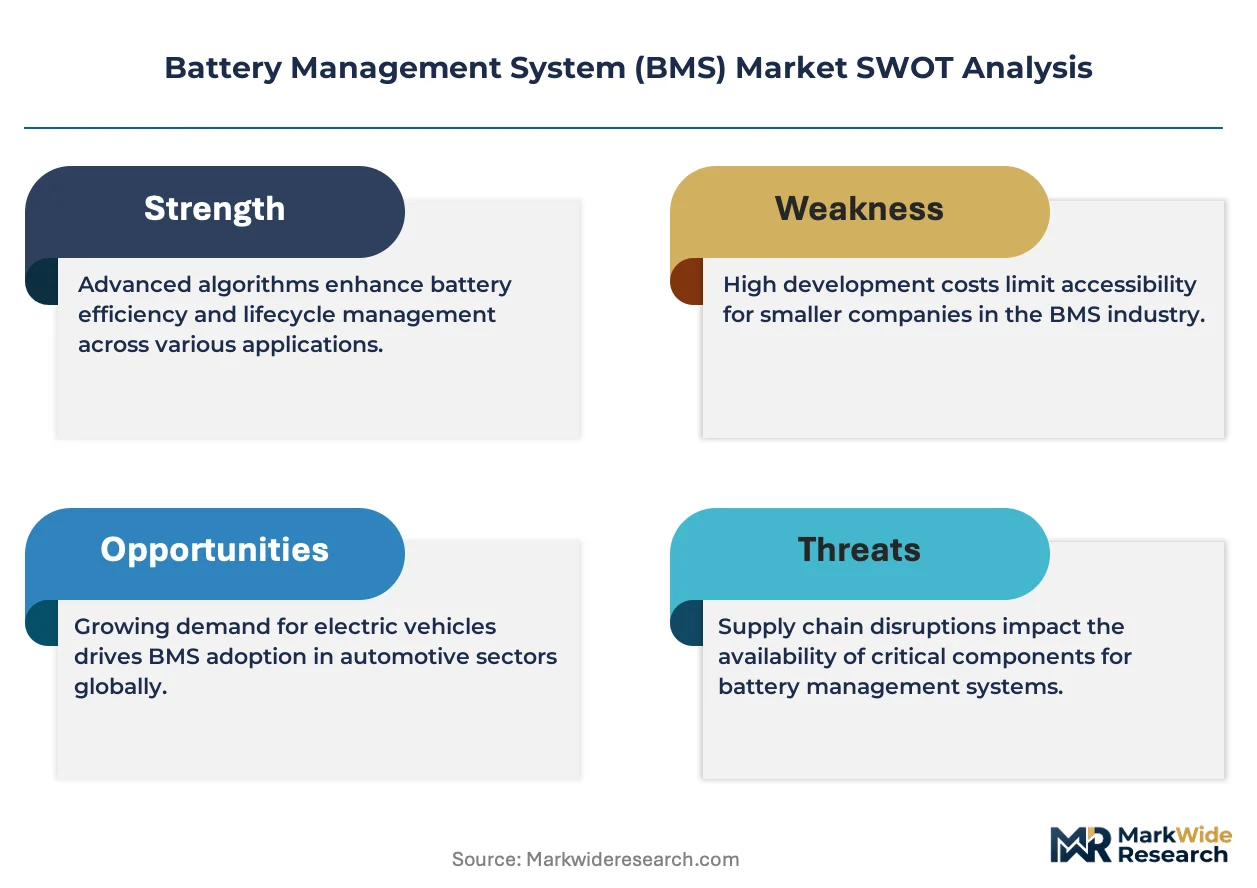
Growth Catalysts
- EU Battery Regulation passport mandates:Lifecycle traceability requirements under the EU Green Deal are compelling BMS firmware upgrades for state-of-health disclosure and second-life tracking across stationary storage and automotive applications.
- Solid-state chemistry transition:Emerging solid-state cell architectures demand fundamentally different monitoring protocols for lithium-metal anode stability, opening module-level redesign cycles for next-generation pack integrators.
- Grid-scale storage procurement:Utility-scale battery installations in Germany, South Korea, and California are scaling BMS procurement for multi-megawatt containerized systems requiring predictive thermal runaway containment.
Market Restraints
- Silicon carbide MOSFET supply concentration:High-voltage switching components for BMS power stages face supply bottlenecks concentrated among Japanese and German substrate manufacturers, constraining module production scaling.
- Firmware validation timelines:Automotive OEM qualification cycles for ASIL-D functional safety certification extend 18-24 months, freezing algorithm updates and delaying feature deployment.
- Copper and nickel price volatility:Cell interconnect materials and thermal management hardware face input cost swings that compress assembly margins for tier-two BMS suppliers.
Strategic Opportunities
- India BIS certification adaptation:Localized firmware for tropical thermal profiles and grid instability conditions creates first-mover positioning as domestic battery assembly scales under PLI scheme incentives.
- Second-life stationary integration:Retired EV battery packs with degraded capacity require BMS reconfiguration for grid buffering applications, opening aftermarket software and hardware retrofit demand.
- Wireless cell monitoring convergence:Elimination of wire harnesses through RF-based voltage sensing is reducing pack weight and assembly labor for premium electric vehicle platforms.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for functional safety and predictive diagnostics faces recruitment gaps across automotive electronics hubs in Stuttgart, Seoul, and Detroit.
- Multi-chemistry calibration complexity:BMS platforms must support simultaneous lithium-ion, LFP, and solid-state cell profiles without hardware swaps, multiplying validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Management System (BMS) Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $53.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular BMS, Centralized BMS, Distributed BMS, Standalone BMS Technology: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Application: Electric Vehicles, Renewable Energy, Consumer Electronics, Industrial Equipment End User: Automotive OEMs, Energy Providers, Electronics Manufacturers, Aerospace |
| Companies Covered | Sensata Technologies, Inc., Skyworks Solutions, Inc., Ewert Energy Systems, Inc, KPM Power Inc, Munich Electrification GmbH, STAFL Systems, LLC., Analog Devices, Inc., Texas Instruments, Nuvation Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Management System (BMS) Market Trends and Innovations
Artificial intelligence inference at the edge is compressing fault-detection latency from seconds to milliseconds, rewriting how thermal runaway prediction integrates with vehicle safety systems and grid control protocols.
Machine learning-based state-of-charge estimation is rewriting accuracy benchmarks for high-nickel cathode chemistries. Tier-one suppliers are embedding neural network accelerators directly into battery monitor ICs. This architecture is collapsing the historical separation between sensing hardware and predictive analytics layers.
China's GB standards for battery safety testing are mandating granular fault-response thresholds that exceed prior international baselines. SAMR enforcement is pushing foreign BMS suppliers to establish local firmware development centers. Domestic pack assemblers are accelerating compliance timelines to capture NEV subsidy windows.
Automotive OEMs are consolidating BMS procurement under long-term platform contracts rather than cell-supplier-mediated arrangements. Direct semiconductor sourcing is displacing tiered module purchasing in premium electric vehicle programs. This restructuring is most pronounced in Germany's automotive corridor where Volkswagen, BMW, and Mercedes-Benz have established captive BMS engineering centers.
Battery Management System (BMS) Market Segmentation
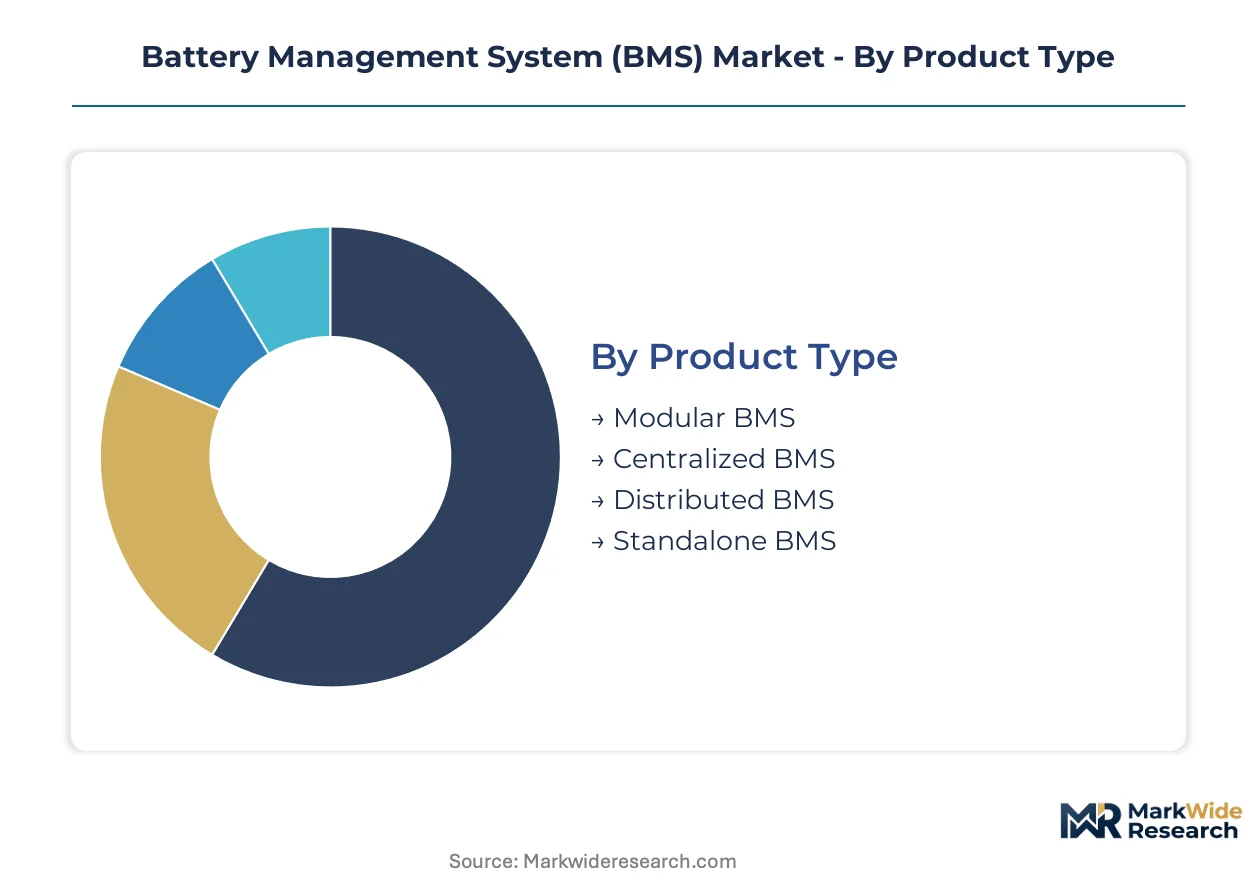
BMS procurement patterns diverge sharply across topology designs, cell chemistries, and end-use verticals. Semiconductor sourcing strategies and firmware qualification timelines reshape how suppliers prioritize segment exposure.
Product Type:
Module suppliers concentrate assembly capacity around architectures that match OEM qualification cycles and pack integration labor.
- Modular BMS:Stackable slave boards with master controller communication suit aftermarket retrofits and scalable energy storage. Demand clusters in Germany's grid-scale procurement and India's emerging battery assembly corridors under PLI incentives.
- Centralized BMS:Single control unit managing all cell strings through wired harnesses dominates lead-acid forklift and industrial equipment segments. Cost-sensitive applications in India's material handling sector favor this topology for firmware simplicity.
- Distributed BMS:Cell monitoring units positioned directly at each module enable 800-volt EV architectures with reduced wiring weight. Premium electric vehicle platforms in California and South Korea specify this topology for thermal granularity.
- Standalone BMS:Self-contained units with integrated protection circuits serve low-voltage consumer and light industrial applications. Electronics manufacturers in Shenzhen and Taipei source these for power tool and e-bike battery packs.
Centralized BMS absorbs the bulk of installed capacity; distributed BMS is expanding most quickly.
Technology:
Cell chemistry dictates voltage sensing precision, thermal modeling protocols, and semiconductor component selection across BMS platforms.
- Lithium-ion:NMC and NCA cathode configurations require millivolt-accurate voltage tracking and predictive thermal runaway algorithms. Automotive OEMs in Stuttgart and Seoul specify these BMS variants for 700+ kilometer range platforms.
- Lead-acid:Simpler state-of-charge estimation with temperature-compensated charging suits stationary backup and motive power applications. India's telecom tower operators and material handling fleets sustain demand for cost-optimized monitoring hardware.
- Nickel-metal Hydride:Memory effect management and trickle charge protocols persist in hybrid vehicle legacy platforms. Toyota's continued hybrid production in Japan and Kentucky sustains niche BMS procurement.
- Solid-state:Lithium-metal anode stability monitoring demands fundamentally different impedance spectroscopy and pressure sensing integration. R&D contracts from Germany's automotive corridor and South Korea's battery industrial zone drive prototype volumes.
Lithium-ion BMS commands current production volumes; solid-state configurations are climbing the fastest.
Application:
End-use thermal profiles and duty cycles fragment BMS firmware roadmaps across mobility, stationary, and portable segments.
- Electric Vehicles:ASIL-D functional safety certification and 10-15 year cycle life optimization drive semiconductor content. California's EV manufacturing cluster and Germany's premium automotive corridor concentrate procurement for 800-volt platforms.
- Renewable Energy:Grid-tied inverters and multi-megawatt containerized storage require predictive state-of-health algorithms for second-life economics. Utility procurement in Germany and South Korea scales BMS demand for frequency regulation services.
- Consumer Electronics:Compact footprint and minimal quiescent current prioritize integration with power management ICs. Shenzhen's electronics manufacturing ecosystem sources these for smartphone, laptop, and wearable battery packs.
- Industrial Equipment:Harsh environment sealing and CAN bus integration serve construction, mining, and agricultural machinery. OEMs in Illinois and Bavaria specify these for electrified heavy equipment platforms.
Electric vehicle applications dominate current semiconductor consumption; renewable energy storage is gaining share fastest.
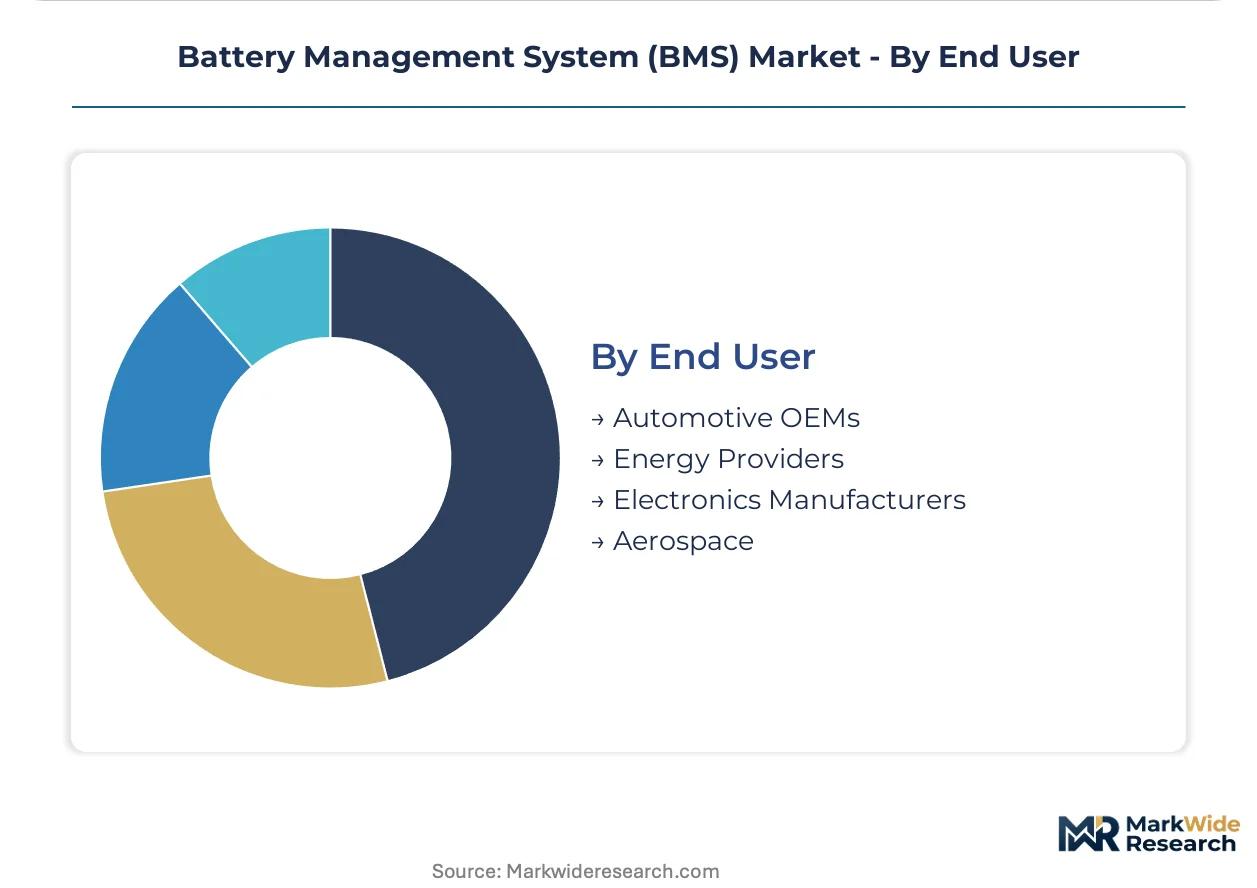
End User:
Customer procurement sophistication spans captive engineering centers, utility technical specifications, and contract manufacturer BOM optimization.
- Automotive OEMs:Direct semiconductor sourcing and long-term platform contracts displace tiered module purchasing. Volkswagen, BMW, and Mercedes-Benz have established captive BMS engineering centers in Germany's automotive corridor.
- Energy Providers:Technical specifications for grid stability and fire safety drive module-level procurement for containerized storage. Germany's transmission system operators and South Korea's KEPCO affiliate utilities shape supplier qualification.
- Electronics Manufacturers:Cost-optimized BOM targets and rapid product cycles favor turnkey BMS module sourcing from Asian integrators. Foxconn, BYD Electronics, and Salcomp anchor procurement in Shenzhen and Vietnam.
- Aerospace:DO-178C software certification and radiation-hardened component requirements constrain supplier pools. Boeing's satellite programs and Airbus defense divisions sustain niche demand in Seattle and Toulouse.
Automotive OEMs absorb the bulk of engineering-intensive BMS development; energy providers are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Chile's Atacama Desert and cobalt supply chains from the Democratic Republic of Congo shape raw-material dependencies for BMS semiconductor fabrication. Cell manufacturing clusters in China, Germany, South Korea, and the United States concentrate demand for precision voltage sensing and thermal management firmware.
Germany
Automotive OEMs in Stuttgart and Munich are scaling 800-volt EV platform production, driving procurement for distributed BMS topologies. The EU Battery Regulation mandates passport-ready traceability and state-of-health disclosure across battery lifecycles. Bavaria's battery industrial corridor hosts captive engineering centers from Volkswagen, BMW, and Mercedes-Benz that directly source semiconductor cores.
China
NEV subsidy windows and domestic pack assembly expansion under dual carbon goals accelerate BMS firmware localization. SAMR enforces GB standards for battery safety testing that exceed prior international baselines for fault-response thresholds. Shenzhen and Shanghai anchor module production for consumer electronics and grid-scale storage integrators.
South Korea
Battery cell manufacturers in Gyeonggi Province and Ulsan are verticalizing BMS engineering to secure supply chain control. KEPCO-affiliated utilities specify technical requirements for multi-megawatt containerized storage systems. Seoul's semiconductor design houses embed neural network accelerators into battery monitor ICs for high-nickel cathode chemistries.
United States
California's EV manufacturing cluster and Texas grid-scale storage procurement drive demand for predictive thermal runaway containment algorithms. The Inflation Reduction Act domestic content provisions reshape semiconductor sourcing strategies for pack integrators. Detroit's automotive electronics hubs face embedded systems talent scarcity for ASIL-D functional safety certification.
India
PLI scheme incentives for domestic battery assembly create first-mover positioning for BMS suppliers adapting firmware to tropical thermal profiles. BIS certification tightens import compliance, forcing module suppliers to recalibrate diagnostic depth for grid instability conditions. Tamil Nadu and Gujarat's emerging cell manufacturing corridors concentrate procurement from Asian integrators.
Battery Management System (BMS) Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one automotive electronics suppliers scale module assembly lines to match OEM platform contracts. The vendor base organizes around three strategic archetypes: semiconductor specialists with precision sensing IP, automotive heritage suppliers leveraging qualification relationships, and battery engineering boutiques serving retrofit and aftermarket segments. M&A activity and strategic partnerships concentrate among firms seeking to bridge firmware development with cell-level hardware integration.
Within the semiconductor specialist tier, Analog Devices, Inc. and Texas Instruments occupy positions defined by voltage sensing precision and integrated protector chipsets respectively. Sensata Technologies, Inc. exemplifies the automotive heritage archetype through its anchoring of high-reliability BMS assembly for OEM qualification cycles. These three firms collectively represent the competitive vectors shaping procurement consolidation under direct semiconductor sourcing arrangements.
| Leading Market Players |
|---|
| Sensata Technologies, Inc. |
| Skyworks Solutions, Inc. |
| Ewert Energy Systems, Inc |
| KPM Power Inc |
| Munich Electrification GmbH |
| STAFL Systems, LLC. |
| Analog Devices, Inc. |
| Texas Instruments |
| Nuvation Energy |
| Others |
Pricing and Supply Chain Analysis
Copper and nickel price volatility on the London Metal Exchange cascades through BMS assembly economics, compressing margins for tier-two suppliers while concentrating pricing power with semiconductor specialists who have locked in long-term substrate offtake. Warranty bundling and firmware upgrade subscriptions increasingly separate premium module suppliers from commodity hardware vendors.
Pricing Analysis
Warranty coverage and predictive diagnostic service bundles now define pricing tiers rather than hardware specifications alone. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification depth and firmware customization scope. Cost compression in economy-tier centralized BMS is intensifying because Indian contract manufacturers are optimizing BOM targets for material handling fleets. Electronics manufacturers in Shenzhen exhibit highest price sensitivity; automotive OEMs in Stuttgart and Seoul absorb premium pricing for distributed architectures with embedded neural network accelerators.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, BMW, and Mercedes-Benz captive engineering centers, displacing tiered module purchasing. Silicon carbide MOSFET fabrication concentrates in Japan and Germany; precision voltage sensing ICs draw from Analog Devices' Massachusetts fabs and Texas Instruments' Dallas facilities. Single-source vulnerability in ceramic substrate supply from Japanese manufacturers threatens production scaling for 800-volt architectures. Distribution runs through automotive electronics distributors in Stuttgart, Seoul, and Detroit for ASIL-D qualified components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate bottlenecks prop pricing power for qualified suppliers while constraining tier-two expansion. Capacity scarcity in functional safety-certified firmware engineering reinforces incumbent positioning.
For Market Incumbents: Lock in multi-year platform contracts with automotive OEMs before captive engineering centers expand in-house BMS design. Secure backward integration into ceramic substrate supply through Japanese supplier partnerships. Solid-state chemistry R&D contracts from South Korea's battery industrial zone represent the priority capability gap to defend against. For New Entrants and Emerging Players: India's PLI scheme incentives open a window for firmware localization targeting tropical thermal profiles and grid instability conditions. Tamil Nadu and Gujarat's emerging cell manufacturing corridors offer the most penetrable geography for first-mover positioning. Second-life stationary integration for retired EV packs provides a software-only entry path with minimal hardware capital requirements. For Investors and Strategic Acquirers: The window for entry favors automotive heritage suppliers with existing ASIL-D qualification relationships and dormant capacity in Bavaria or Michigan. Acquisition targets should demonstrate embedded systems talent density and active SAMR or BIS certification pipelines. Watch for inflection when China's NEV subsidy windows tighten and force consolidation among domestic pack assemblers unable to fund firmware localization.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Automotive OEMs in Germany's Stuttgart corridor mandate functional safety depth for platform qualification. |
| Silicon Carbide Substrate Partnership | Japanese ceramic substrate supply anchors high-voltage switching performance for 800-volt architectures. |
| Firmware Localization Center | SAMR enforcement in China and BIS certification in India require regional engineering presence. |
| Second-Life Software Platform | Retired EV battery packs with degraded capacity require BMS reconfiguration for grid buffering economics. |
| Wireless Cell Monitoring Development | RF-based voltage sensing eliminates wire harness weight for premium California and South Korea EV platforms. |
Research Methodology
Independent corroboration across BMS platform engineers, semiconductor procurement leads at Tier 1 automotive suppliers, and grid-scale storage EPC contractors underwrites the qualitative findings. Primary fieldwork engaged firmware development directors, ASIL-D functional safety auditors, and cell manufacturing operations heads across Germany, South Korea, China, and the United States. Secondary validation drew from SAMR GB standard filings, EU Battery Regulation technical documentation, SEC 10-K semiconductor segment disclosures, and IHS Markit vehicle production databases. Bottom-up cell count modeling and top-down OEM platform contract aggregation triangulate market sizing.
Comparable historical periods spanning lithium-ion pack scaling and solid-state prototype deployment anchor the projection horizon. The analytical framework segments by topology architecture, cell chemistry, end-use vertical, and customer procurement sophistication. CAGRs derive from semiconductor content per pack trajectories, OEM platform rollout schedules, and utility storage procurement pipelines. Forecast inputs include 800-volt architecture adoption curves, second-life stationary integration economics, and wireless cell monitoring convergence timelines.
Caveats apply where silicon carbide substrate supply disruptions, embedded systems talent scarcity in Detroit and Stuttgart, or regulatory acceleration of predictive failure algorithm mandates could materially shift the outlook. Forecasts reflect documented assumptions regarding OEM captive engineering center expansion and NEV subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
North America Energy Storage Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Battery Management Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Energy Storage Market