
 Smart Battery Maintainer Market | 2026-2036
Smart Battery Maintainer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Battery Maintainer Market Insights
Modular accessory bundling is shifting how buyers evaluate smart battery maintainers, with retailers now pairing desulfator units with trickle chargers in single SKUs. CTEK leverages its Nordic engineering heritage to dominate premium automotive channels. NOCO differentiates through ruggedized industrial housings that extend into marine and powersport segments. Battery Tender anchors the North American aftermarket through deep retail penetration and brand recognition among motorcycle enthusiasts.
A smart battery maintainer is an intelligent charging device that monitors battery voltage, temperature, and internal resistance to deliver precisely conditioned current without overcharging, typically operating between 0.75 and 5 amps with multi-stage charging algorithms. Its primary purpose is to preserve battery capacity during extended storage periods while preventing sulfation in lead-acid cells and balancing charge states in lithium-ion packs. Smart chargers now lead product type revenue as microprocessor-controlled units displace basic trickle chargers in both consumer and professional channels. The marine end-user segment shows the fastest trajectory as boat owners adopt solar-integrated maintainers for off-season storage. Lead-acid technology still occupies the largest installed base, though Li-ion compatibility commands premium positioning across personal vehicle and UPS applications.
The EPA governs charger efficiency standards under ENERGY STAR specifications, while the EU F-Gas Regulation and CE marking requirements shape export compliance for North American manufacturers. California's CEC Title 20 mandates minimum efficiency thresholds that effectively filter lower-tier imports from the state's substantial addressable base. Stakeholders must monitor evolving battery chemistry standards and regional efficiency mandates to maintain product registration and channel access.
Market Dynamics
Fleet electrification is forcing automotive service centers to retool their battery management protocols, creating sustained pull for intelligent charging infrastructure that can handle mixed chemistry portfolios without manual intervention.
Growth Catalysts
- EPA ENERGY STAR Specifications:Minimum efficiency thresholds for battery charging systems are filtering low-performance imports from the US market, elevating demand for certified smart maintainers that meet federal performance benchmarks.
- Marine Storage Applications:Boat owners operating in cold-climate regions require off-season battery preservation solutions, driving adoption of solar-integrated maintainers that operate independently of shore power.
- Lithium-Ion Compatibility:Advanced microprocessor-controlled units capable of balancing Li-ion charge states are commanding premium positioning as personal vehicle and UPS applications diversify beyond lead-acid chemistry.
Market Restraints
- Semiconductor Component Volatility:Microprocessor and sensor chip supply constraints create input cost instability for manufacturers assembling multi-stage charging algorithms.
- China Supply Concentration:Printed circuit board and power semiconductor fabrication clusters in East Asia expose North American and European brands to single-source geographic risk.
- Basic Trickle Charger Substitution:Low-cost conventional chargers without intelligent monitoring capabilities retain price-sensitive segments in developing markets and casual consumer channels.
Strategic Opportunities
- German Automotive Aftermarket:Premium vehicle density and stringent TÜV inspection standards create demand for professional-grade maintainers with diagnostic connectivity features.
- California SB 1215 Compliance:The state's evolving battery disposal and efficiency mandates are reshaping product registration requirements, favoring manufacturers with pre-certified SKU portfolios.
- Solar-Trickle Convergence:Integration of photovoltaic input management with traditional maintainer functions opens off-grid applications in recreational vehicle and marine verticals.
Industry Challenges
- Firmware Certification Timelines:Multi-stage charging algorithm validation for UL and CE marking extends product launch cycles by 8-14 months, compressing first-mover windows.
- Legacy System Integration:Backward compatibility requirements with existing 12V lead-acid infrastructure complicate Li-ion feature development and SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Battery Maintainer Market |
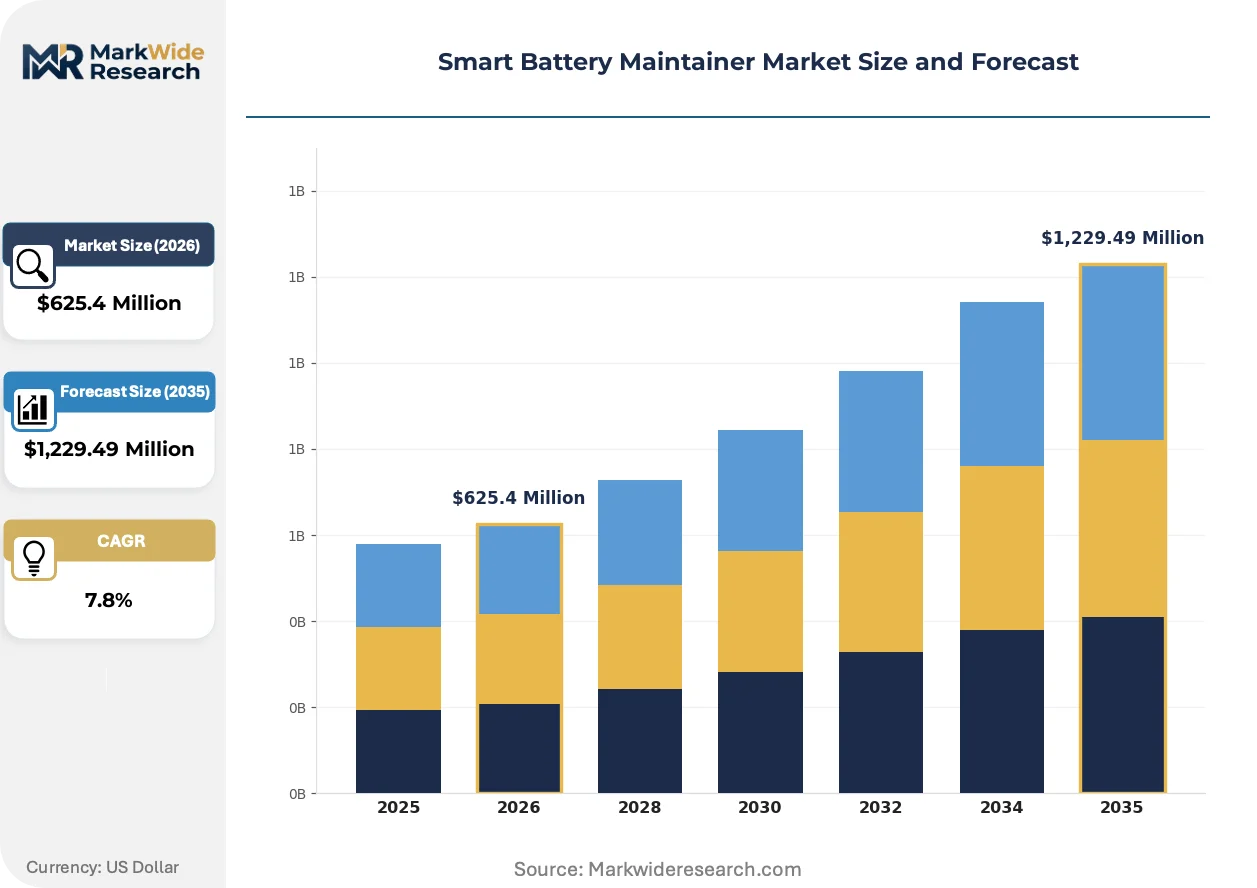
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,229.49 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trickle Chargers, Smart Chargers, Desulfators, Battery Conditioners End User: Automotive, Marine, Aviation, Industrial Technology: Li-ion, Lead Acid, NiMH, Solar Application: Personal Vehicles, Boats, Motorcycles, UPS |
| Companies Covered | Delta-Q Technologies, CTEK, NOCO, Battery Tender, Accutronics Ltd, Analytic Systems, Associated Equipment, Schumacher Electric Corporation, ProMariner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Battery Maintainer Market Trends and Innovations
Microprocessor architecture is redefining competitive differentiation as manufacturers race to embed diagnostic intelligence that extends beyond voltage monitoring into predictive failure detection and remote fleet management.
Bluetooth-enabled battery monitoring is decentralizing how service centers manage vehicle fleets. Automotive technicians now receive real-time state-of-charge data on mobile devices, eliminating physical bay inspections. This connectivity layer is compressing maintenance labor costs and enabling proactive battery replacement scheduling before seasonal demand spikes.
The EU F-Gas Regulation is tightening compliance requirements for refrigerant-based thermal management systems integrated into high-amplitude chargers. Manufacturers exporting from North America must redesign heat dissipation architectures to eliminate fluorinated gas dependencies. Professional-grade units destined for German and French channels face the most stringent redesign timelines.
Direct-to-consumer channels are fragmenting traditional aftermarket distribution. Powersport and marine enthusiasts now research charging specifications through manufacturer websites before purchasing, reducing reliance on retail counter staff for technical guidance. This behavior shift concentrates in United States and Canadian markets where e-commerce penetration in automotive accessories exceeds brick-and-mortar growth rates.
Smart Battery Maintainer Market Segmentation
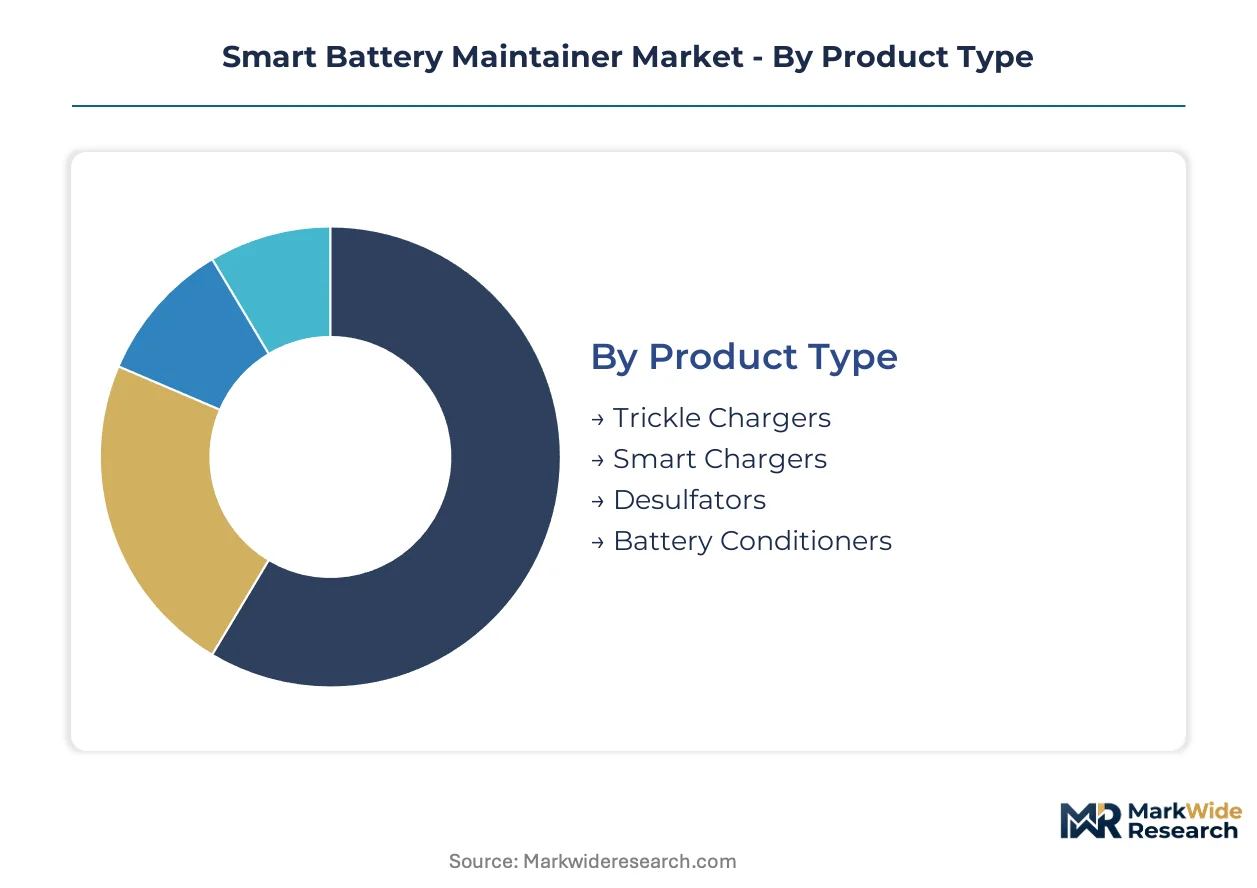
Smart battery maintainer procurement patterns diverge sharply across use cases. Fleet operators prioritize chemistry-agnostic platforms, while recreational buyers emphasize portability and solar compatibility. Understanding these segment boundaries clarifies where R&D budgets and channel investments generate returns.
Product Type:
Capital intensity peaks with smart chargers requiring microprocessor architecture and multi-stage algorithm validation, while desulfators and basic trickle units demand lighter firmware investment.
- Smart Chargers:Microprocessor-controlled units with voltage, temperature, and internal resistance monitoring deliver precisely conditioned current between 0.75 and 5 amps. Automotive service centers in Germany and the United States deploy these for mixed-chemistry fleet portfolios where manual intervention is uneconomical.
- Trickle Chargers:Conventional constant-voltage units without intelligent monitoring retain price-sensitive segments in developing markets. Basic units face substitution pressure as ENERGY STAR thresholds filter low-efficiency imports from California and federal procurement channels.
- Desulfators:High-frequency pulse units reverse crystalline sulfate buildup in lead-acid cells through resonant frequency disruption.
- Battery Conditioners:Hybrid devices combining maintenance charging with diagnostic cycling extend functional lifespan in seasonal storage applications.
Smart chargers absorb the bulk of installed capacity; desulfators are expanding most quickly as modular bundling with trickle units gains retail traction.
End User:
Application environment dictates housing durability, connectivity requirements, and certification complexity, with marine and aviation segments imposing the most severe compliance burdens.
- Automotive:Passenger vehicle and fleet maintenance applications dominate volume, with service centers requiring UL-listed units for bay liability coverage. EPA ENERGY STAR certification functions as a de facto entry requirement for United States commercial procurement.
- Marine:Off-season boat storage in cold-climate regions drives demand for solar-integrated maintainers that operate without shore power. Salt-resistant housings and IP67 ratings command premium positioning in Nordic and Great Lakes markets.
- Aviation:Ground support equipment for general aviation requires DO-160 environmental testing and specialized connector standards.
- Industrial:Forklift and stationary backup systems prioritize throughput over portability, favoring rack-mounted units with remote monitoring capabilities.
Automotive absorbs the bulk of installed capacity; marine is climbing the fastest as solar-trickle convergence opens off-grid applications.
Technology:
Chemistry compatibility determines firmware architecture complexity and semiconductor content, with lithium-ion platforms requiring cell-balancing circuits absent from lead-acid designs.
- Lead Acid:Flooded, AGM, and gel cell variants retain the largest installed base across automotive and industrial verticals. Desulfation algorithms and temperature-compensated voltage curves address sulfation risk during extended storage periods.
- Li-ion:Lithium iron phosphate and lithium-ion polymer packs demand precise charge-state balancing and thermal runaway prevention. Personal vehicle and UPS applications in Germany and California command premium positioning for chemistry-agnostic units.
- NiMH:Nickel-metal hydride compatibility persists in legacy hybrid vehicle fleets and specialty industrial equipment.
- Solar:Photovoltaic input management with maximum power point tracking enables standalone operation in remote marine and recreational vehicle deployments.
Lead acid absorbs the bulk of installed capacity; solar is gaining share fastest as photovoltaic cost curves improve standalone economics.
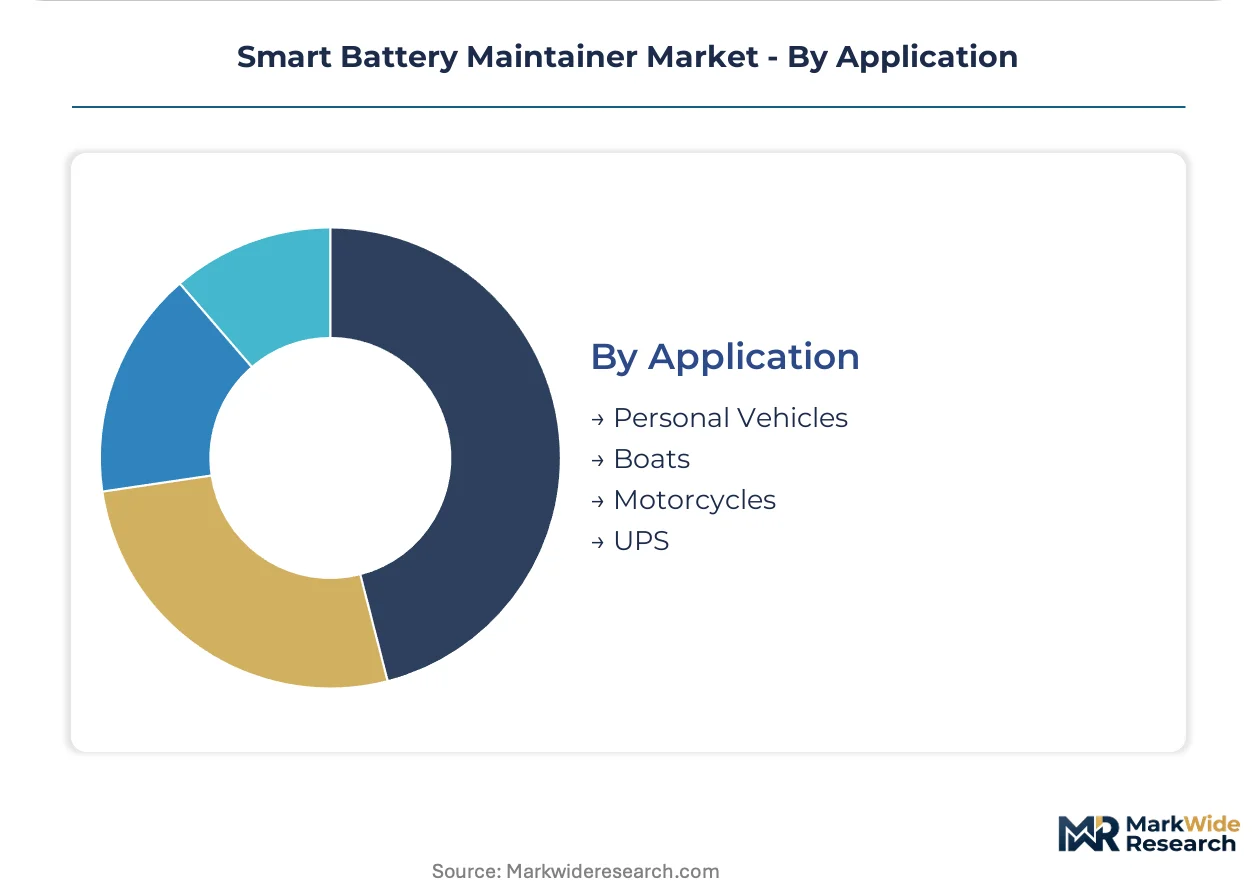
Application:
Storage duration and access to grid power separate applications, with motorcycles and boats requiring seasonal solutions unlike continuously connected UPS systems.
- Personal Vehicles:Passenger cars and light trucks in cold-storage regions sustain replacement cycles for maintainers with temperature-compensated charging. California's CEC Title 20 efficiency mandates filter lower-tier imports from the state's substantial addressable base.
- Boats:Off-season layup periods of 4-6 months in northern climates create concentrated demand for solar-integrated units. Bluetooth-enabled monitoring eliminates physical inspection requirements for owners storing vessels at remote marinas.
- Motorcycles:Seasonal riders with limited electrical knowledge favor plug-and-forget units with automatic desulfation cycles.
- UPS:Uninterruptible power supply maintenance prioritizes continuous float charging with alarm integration for data center and healthcare facility backup systems.
Personal vehicles absorb the bulk of installed capacity; boats are expanding most quickly as solar integration penetrates recreational marine channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Dongguan concentrate printed circuit board fabrication for smart charger microprocessors, drawing component suppliers into clustered logistics corridors that reduce inbound freight costs for maintainer assemblers.
United States
Automotive service centers in Michigan and Ohio deploy intelligent charging infrastructure for mixed-chemistry fleet portfolios as electrification accelerates. EPA ENERGY STAR specifications filter low-efficiency imports from federal procurement channels. The Detroit-Warren-Dearborn metro anchors professional-grade demand through dense collision repair and dealership service bay networks.
Germany
Premium vehicle density in Bavaria and Baden-Württemberg sustains demand for diagnostic-connected maintainers meeting TÜV inspection standards. The EU F-Gas Regulation forces redesign of thermal management systems in high-amplitude chargers. Stuttgart's automotive engineering cluster drives firmware development for cell-balancing algorithms in lithium-compatible units.
China
Domestic EV fleet expansion in Shanghai and Guangdong province creates pull for chemistry-agnostic charging platforms. GB standards and MIIT efficiency mandates shape product registration for local manufacturers. The Yangtze River Delta electronics corridor supplies power semiconductors and sensor chips to regional charger assemblers.
Japan
Legacy hybrid vehicle fleets in Aichi and Kanagawa prefectures sustain nickel-metal hydride compatible maintainer demand alongside lithium-ion transitions. METI efficiency guidelines and JIS standards govern product certification for domestic channels. The Nagoya industrial zone concentrates precision electronics manufacturing for automotive-grade charging components.
Smart Battery Maintainer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning bands. The vendor base organizes around three strategic archetypes: Nordic engineering houses leveraging cold-climate credibility, North American aftermarket brands with retail channel depth, and industrial electronics conglomerates with captive component supply. Consolidation pressure concentrates in the mid-tier as efficiency certification costs filter sub-scale competitors. Geographic expansion and strategic partnerships dominate competitive moves, with European brands seeking California CEC pre-certification and Asian fabricators pursuing German TÜV alignment.
Among Nordic-origin specialists, CTEK exemplifies the premium engineering archetype through its association with cold-climate automotive heritage. NOCO and Battery Tender anchor the North American aftermarket tier, with the former representing ruggedized industrial positioning and the latter occupying deep retail penetration channels. These three names illustrate how brand geography and channel strategy segment competitive space without requiring overlapping feature claims.
| Leading Market Players |
|---|
| Delta-Q Technologies |
| CTEK |
| NOCO |
| Battery Tender |
| Accutronics Ltd |
| Analytic Systems |
| Associated Equipment |
| Schumacher Electric Corporation |
| ProMariner |
| Others |
Pricing and Supply Chain Analysis
California's CEC Title 20 efficiency mandates are filtering low-performance imports from the state's procurement channels, forcing manufacturers to absorb semiconductor certification costs or surrender price-competitive positioning in the premium automotive aftermarket.
Pricing Analysis
Short lead-time premiums for UL-certified microprocessor units separate urgent fleet procurement from standard inventory cycles in German and US automotive service channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ENERGY STAR certification grade and Bluetooth connectivity features. Cost compression in economy-tier trickle chargers is intensifying because basic units without intelligent monitoring face substitution pressure. Fleet operators show least price sensitivity; casual motorcycle enthusiasts in developing markets show most.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and refurbished desulfator modules concentrate refurbishment activity in Shenzhen corridor facilities serving North American aftermarket distributors. Printed circuit board fabrication clusters in China, Taiwan, and South Korea supply microprocessors and sensor chips to regional charger assemblers. Semiconductor input dependency creates single-source vulnerability when East Asian foundry capacity tightens. Distribution runs through automotive aftermarket distributors and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microprocessor foundry capacity constraints in East Asia are propping pricing for certified intelligent units, creating supply-constrained conditions that favor manufacturers with pre-qualified component pipelines.
For Market Incumbents: Hedge against semiconductor volatility by securing multi-year foundry agreements with TSMC or Samsung analog chip lines. Defend margin position by deepening backward integration into power semiconductor design rather than sourcing generic controller chips. Prioritize California CEC pre-certification to maintain channel access as efficiency thresholds tighten. For New Entrants and Emerging Players: Direct-to-consumer marine channels offer penetrable white-space as boat owners research solar-integrated specifications online before purchase. Target Nordic cold-climate storage applications where salt-resistant IP67 housings command premium positioning. Launch through specialty powersport e-commerce platforms with technical content marketing rather than retail counter presence. For Investors and Strategic Acquirers: The window for entry favors firmware-agnostic hardware platforms capable of chemistry-switching between lead-acid and lithium-ion protocols. Long-term viability rests on acquiring specialists with validated multi-stage charging algorithms already through UL and CE marking timelines. Monitor EPA ENERGY STAR specification updates as inflection signals for import filtration intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductor Design | Captive controller chip supply insulates CTEK and NOCO from foundry allocation shocks. |
| Solar-Trickle Convergence Product Launch | Photovoltaic input management opens off-grid marine applications in Great Lakes and Nordic markets. |
| California CEC Pre-Certification Investment | Pre-qualified SKUs maintain channel access as Title 20 efficiency thresholds filter imports. |
| Bluetooth-Enabled Fleet Monitoring Platform | Real-time state-of-charge data compresses automotive service center labor costs and enables proactive replacement. |
| German TÜV Diagnostic Connectivity Partnership | Inspection-standard alignment secures premium positioning in Bavaria and Baden-Württemberg automotive clusters. |
Research Methodology
Independent corroboration across automotive service center procurement directors, marine dealership operations managers, and electronics manufacturing executives underwrites the qualitative findings in this study. Primary interviews with fleet maintenance supervisors, aftermarket distributor category buyers, and power semiconductor sourcing leads combined with secondary validation from EPA ENERGY STAR certification databases, EU F-Gas Regulation filings, and California CEC Title 20 efficiency standards. Bottom-up unit shipment estimates and top-down value aggregation triangulate market sizing across product type, end user, and technology segments.
Comparable-period anchoring to historical replacement cycles in cold-climate storage applications grounded the forecast window across the analysis window. Segmentation modeling incorporated product architecture, chemistry compatibility, application environment, and regional regulatory cluster dimensions. CAGRs derived from trend-line extrapolation of fleet electrification penetration and solar-integrated maintainer adoption curves. Industry-specific inputs included automotive service bay density metrics and marine vessel registration patterns by climate zone.
The model holds under stable semiconductor supply conditions and sustained EPA efficiency enforcement; deviation in foundry allocation crises or regulatory suspension would shift volume projections. Forecasts reflect documented assumptions about fleet electrification pace and ENERGY STAR specification evolution. Practitioners should monitor MIIT efficiency mandate updates in China and EU F-Gas Regulation enforcement timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Battery Management Market
Battery Management System
North America Battery Management System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
North America Energy Storage Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
Battery Management System (BMS) Market
Battery Management System
US Energy Storage Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
India Stationary Battery Energy Storage System Market