
 Electric Vehicle Battery Management System Market | 2026-2036
Electric Vehicle Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Management System Market Analysis
Commercial truck electrification is hardening as the fastest-expanding application vertical for battery management systems. Tesla sustains integrated hardware-software control across its commercial and passenger platforms. CATL dominates cell-to-pack architectures that embed management intelligence at the module level. Robert Bosch competes through thermal runaway detection systems calibrated for heavy-duty cycle profiles.
An Electric Vehicle Battery Management System is an electronic controller that monitors cell voltage, temperature, and state-of-charge within traction battery packs, typically operating across voltage ranges from 48V to 800V and communicating via CAN or wireless protocols to powertrain controllers. Its primary purpose is to optimize battery performance, prevent thermal events, and extend cycle life under variable load conditions. Modular systems lead in aftermarket retrofit applications where legacy platforms require scalable upgrade paths, while integrated systems capture margin pools in OEM new-vehicle programs where space and weight constraints are tightest. Distributed architectures are gaining traction in commercial buses and trucks where pack segmentation across long wheelbases demands localized cell monitoring nodes.
FDA-equivalent automotive safety protocols in the United States flow through NHTSA defect investigations and EPA emissions compliance pathways that indirectly validate battery system integrity. EMA-aligned frameworks in Europe, specifically the EU Battery Regulation and CE marking requirements, mandate carbon footprint disclosure and recycled content thresholds that reshape supplier qualification criteria. Stakeholders must monitor how China's GB standards evolution and SAMR certification timelines synchronize with solid-state technology maturation to determine next-generation platform investment sequencing.
Market Dynamics
Cell-to-pack architecture compression is eliminating redundant module housings and redistributing thermal management intelligence across battery enclosures. This structural shift forces suppliers to recalibrate sensing node density and firmware architectures.
Growth Catalysts
- Commercial truck fleet electrification:Heavy-duty operators are mandating real-time state-of-health telemetry to protect residual value in leased assets across extended duty cycles.
- EU Battery Regulation recycled content mandates:Cell passport traceability requirements are accelerating investment in embedded monitoring systems that track material provenance from mine to vehicle.
- 800V platform proliferation:High-voltage architectures demand precision cell balancing algorithms that legacy 400V systems cannot support, creating upgrade imperatives.
Market Restraints
- Semiconductor supply concentration:Automotive-grade AEC-Q100 qualified microcontrollers face allocation constraints from concentrated foundry capacity in East Asian manufacturing clusters.
- Cell chemistry heterogeneity:Proliferation of LFP, NMC, and sodium-ion formats forces redundant firmware development and fragments economies of scale.
- NHTSA defect investigation exposure:Thermal event liability is concentrating in OEMs, pressuring tier-one suppliers to absorb warranty risk in contract negotiations.
Strategic Opportunities
- Second-life stationary storage:Retired automotive packs require repurposed BMS firmware to manage degraded cell populations in grid-buffer applications.
- Wireless cell monitoring:Elimination of harness wiring reduces pack weight and assembly labor, with adoption concentrating in premium passenger platforms.
- India PLI scheme localization:Domestic cell manufacturing incentives are creating demand for indigenous BMS design and calibration capabilities.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise is concentrated among a limited pool of specialists, constraining program velocity.
- Legacy vehicle retrofit integration:CAN protocol fragmentation across model years complicates aftermarket BMS deployment in aging hybrid fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Management System Market |
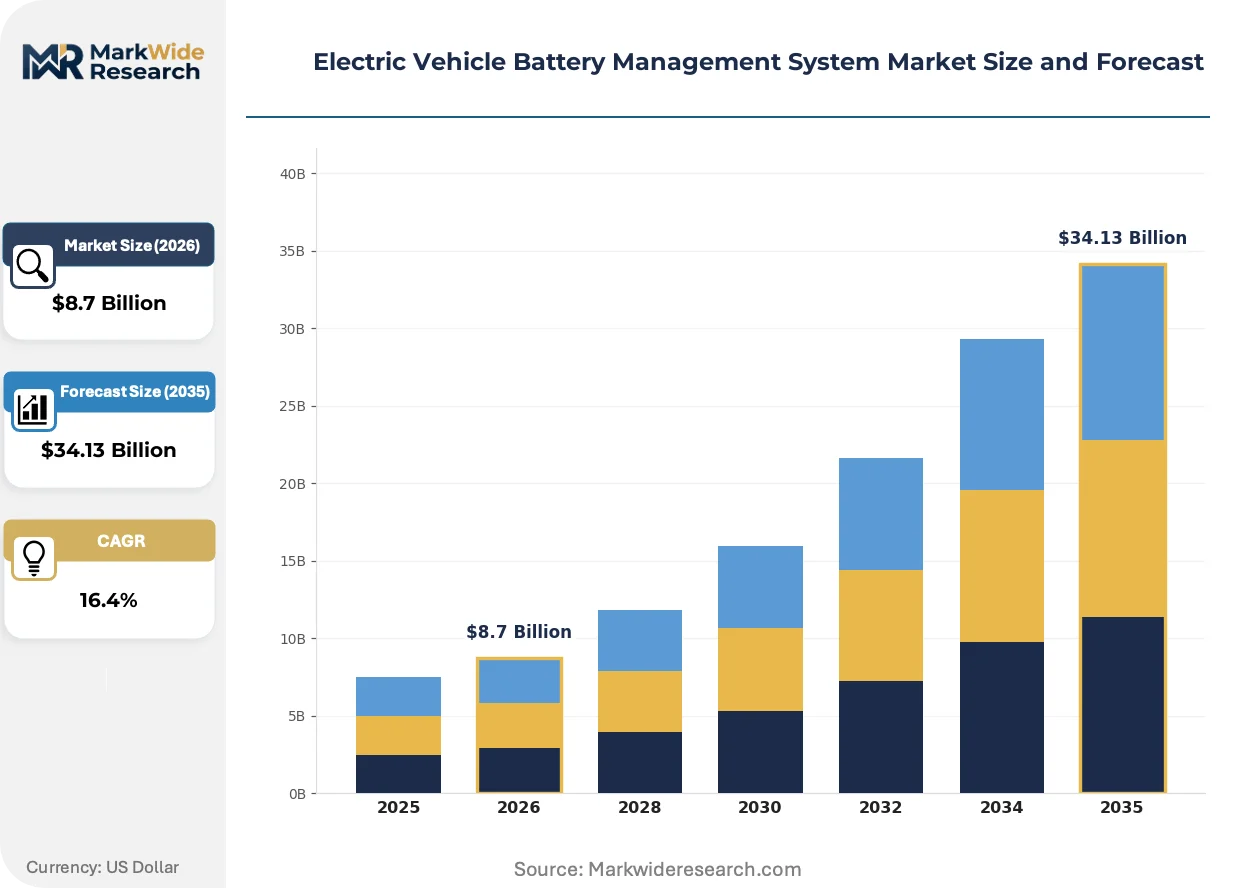
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Integrated Systems, Centralized Systems, Distributed Systems End User: OEMs, Fleet Operators, Aftermarket Providers, Research Institutions Technology: Li-ion, Solid State, Nickel Metal Hydride, Lead Acid Application: Passenger Vehicles, Commercial Trucks, Buses, Two-Wheelers |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), Tesla, Vishay Intertechnology, Texas Instruments, LG Chem, Analog Devices, Continental AG, STMicroelectronics, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Management System Market Emerging Trajectories
Intelligence migration from centralized controllers to distributed edge nodes is compressing response latency for thermal anomaly detection. This architectural inversion demands new validation protocols and supplier capability profiles.
Silicon carbide power semiconductors are rewriting thermal management strategies by enabling higher switching frequencies that reduce passive component sizing. Commercial bus manufacturers are adopting these devices fastest, driven by space constraints in double-decker configurations. The resulting packaging density is compressing cooling system volumes and enabling flatter battery enclosures.
China's GB/T standards evolution for solid-state cell interfaces is forcing premature obsolescence of incumbent sensing architectures. Domestic OEMs are accelerating validation timelines to synchronize with SAMR certification windows. Foreign suppliers must maintain parallel development tracks to avoid exclusion from platform sourcing decisions.
Fleet operators are consolidating procurement authority into centralized technical centers that specify BMS performance requirements directly, bypassing traditional tier-one intermediaries. This disintermediation concentrates purchasing power among logistics giants and municipal transit authorities. Germany's commercial leasing market exhibits this pattern most acutely, with operating lease providers dictating data access and predictive maintenance terms.
Electric Vehicle Battery Management System Market Segmentation
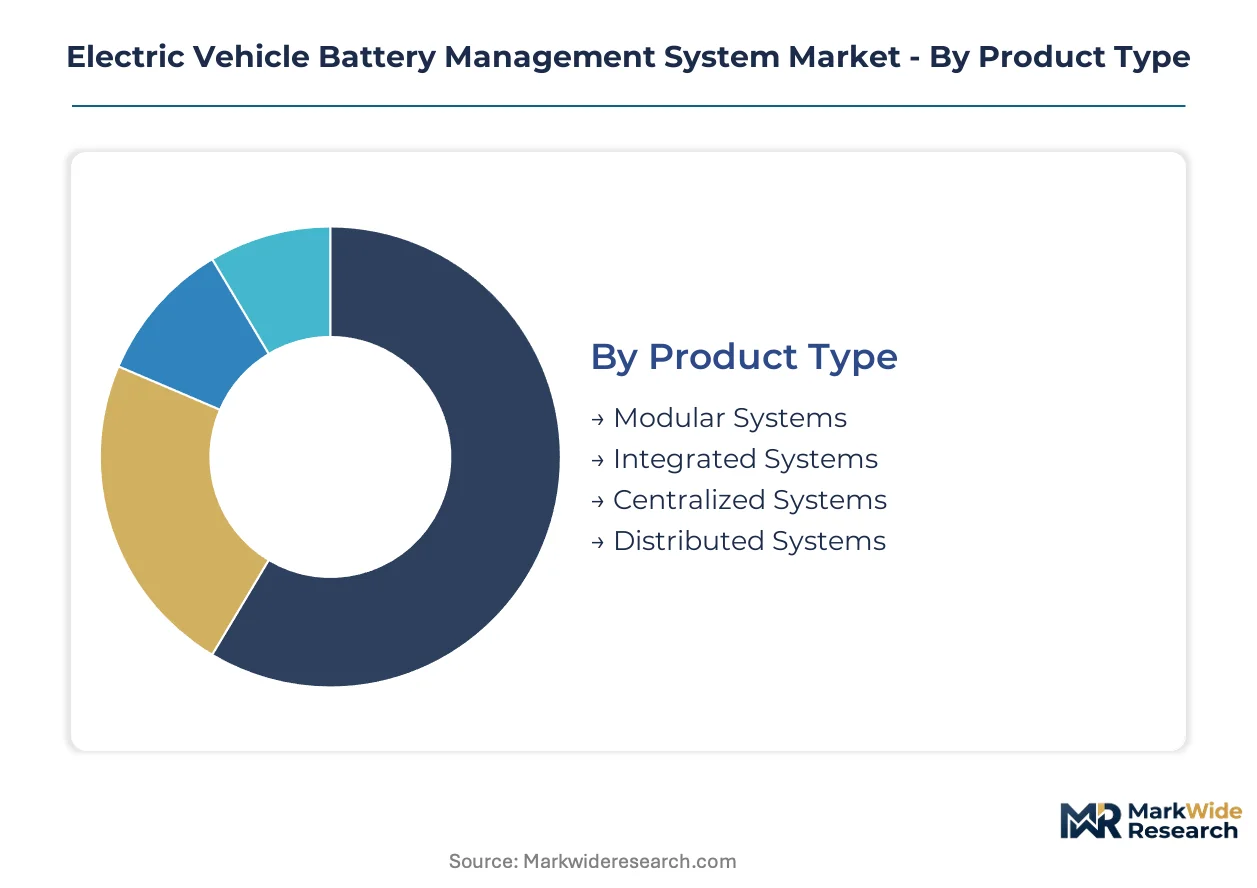
Segmentation in the Electric Vehicle Battery Management System market reveals how certification burdens, thermal management requirements, and integration complexity vary across product architectures and end-use applications. Suppliers must align development roadmaps with the specific validation protocols each segment demands.
Product Type:
ISO 26262 ASIL-D functional safety certification applies universally, yet testing scope expands dramatically for architectures handling higher node counts across distributed topologies.
- Integrated Systems:These embed management intelligence directly into cell-to-pack architectures with consolidated sensing and control circuitry. Passenger vehicle OEMs in Germany concentrate procurement here, driven by space constraints and the need to minimize wiring harness mass in premium platforms. NHTSA defect investigation exposure concentrates liability risk, forcing redundant validation cycles.
- Distributed Systems:Localized monitoring nodes communicate via CAN or wireless protocols across segmented pack enclosures. Commercial truck and bus manufacturers in the United States adopt these most aggressively, as wheelbase extension demands cell supervision at multiple physical locations. The architecture complicates electromagnetic compatibility certification under FCC Part 15 for wireless variants.
- Modular Systems:Scalable hardware-software units designed for aftermarket retrofit applications where legacy platforms require upgrade paths without full pack replacement.
- Centralized Systems:Single-controller architectures with consolidated sensing harnesses, dominant in earlier-generation hybrid vehicles now facing obsolescence pressure from 800V platform proliferation.
Leading the category by volume: Integrated Systems. Growing fastest: Distributed Systems.
End User:
Contractual liability allocation diverges sharply across buyer types, with fleet operators now extracting predictive maintenance data rights that reshape supplier margin structures.
- Fleet Operators:Heavy-duty logistics and municipal transit authorities are consolidating procurement authority into centralized technical centers that specify performance requirements directly. Germany's commercial leasing market exhibits this pattern acutely, with operating lease providers dictating state-of-health telemetry access to protect residual value in leased assets across extended duty cycles.
- OEMs:Integrated hardware-software control captures margin pools in new-vehicle programs where space and weight constraints are tightest. Tesla sustains proprietary architectures across commercial and passenger platforms, while tier-one suppliers absorb escalating warranty risk in contract negotiations.
- Aftermarket Providers:Service networks and independent installers serving aging hybrid fleets where CAN protocol fragmentation complicates deployment.
- Research Institutions:Universities and national laboratories validating next-generation cell chemistries and solid-state interfaces under SAMR and NMPA certification timelines.
Volume concentrates with OEMs. Procurement disintermediation is accelerating fastest among Fleet Operators.
Technology:
Firmware development redundancy fragments economies of scale as chemistry heterogeneity forces parallel validation tracks.
- Li-ion:LFP and NMC variants dominate current production, with LFP gaining share in commercial applications where cycle life outweighs energy density requirements. China's GB standards evolution and NMPA battery safety mandates tighten cell-level accountability for these chemistries.
- Solid State:Next-generation architectures with ceramic or sulfide electrolytes are forcing premature obsolescence of incumbent sensing architectures. Domestic OEMs in China accelerate validation timelines to synchronize with SAMR certification windows.
- Nickel Metal Hydride:Legacy chemistry persisting in select hybrid applications with established BMS firmware bases.
- Lead Acid:Auxiliary power applications in commercial vehicles where cost minimization overrides performance optimization.
Li-ion commands current volume. Solid State carries the steepest expansion trajectory.
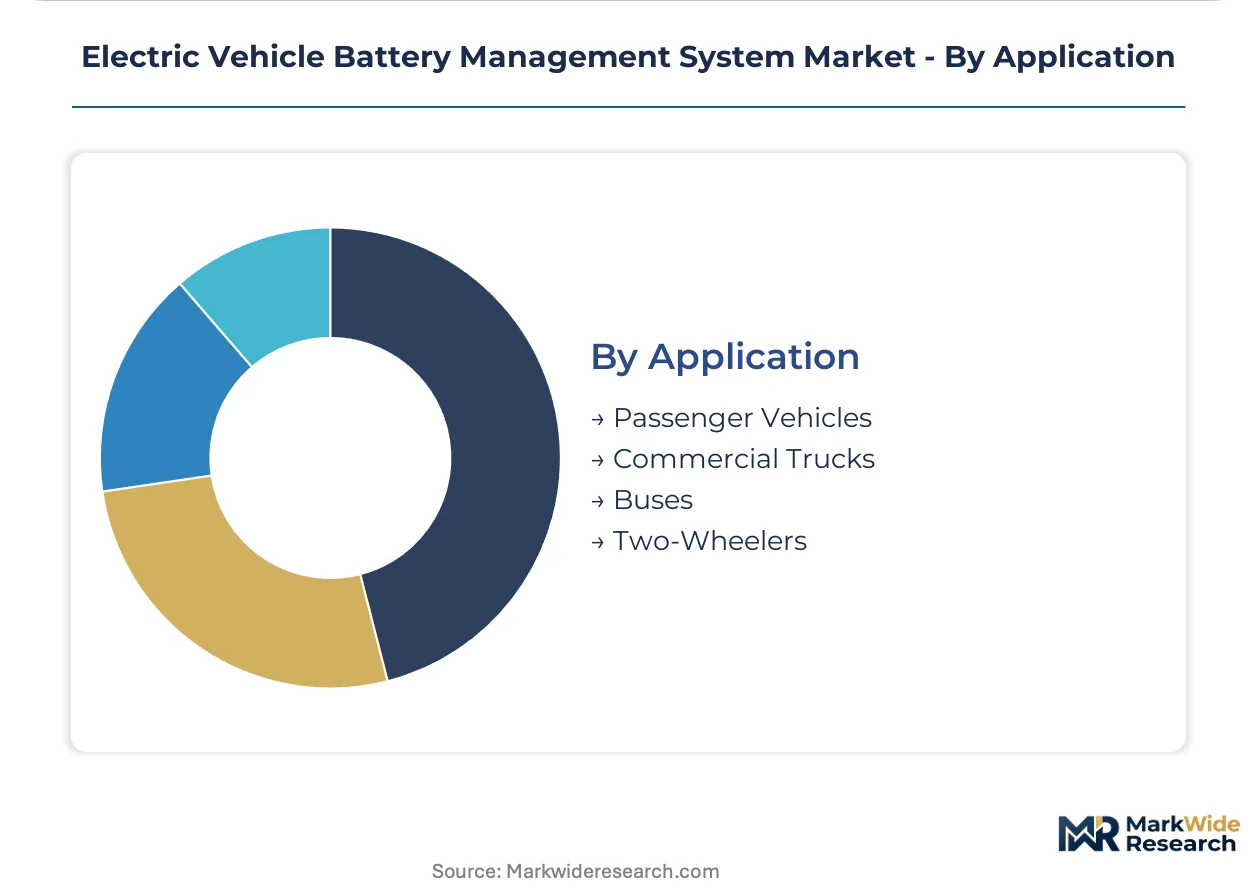
Application:
Thermal runaway detection calibration varies by duty cycle severity, with heavy-duty profiles demanding specialized algorithm development.
- Commercial Trucks:Heavy-duty operators mandate real-time state-of-health telemetry to protect residual value in leased assets. Robert Bosch competes through thermal runaway detection systems calibrated specifically for these cycle profiles. The EU Battery Regulation's recycled content mandates accelerate investment in embedded monitoring systems that track material provenance.
- Passenger Vehicles:Electrification corridors spanning Germany, China, and the United States concentrate demand here. 800V platform proliferation demands precision cell balancing algorithms that legacy 400V systems cannot support.
- Buses:Double-decker configurations in European cities drive silicon carbide adoption for space-constrained thermal management.
- Two-Wheelers:Cost-optimized BMS implementations for emerging market mobility, with India's PLI scheme localization creating demand for indigenous design capabilities.
Passenger Vehicles lead by volume. Commercial Trucks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate cell-to-pack manufacturing, drawing BMS suppliers into clustered development corridors alongside CATL and domestic OEMs.
China
NMPA battery safety mandates and SAMR certification timelines accelerate validation programs for solid-state interfaces. GB standards evolution forces premature obsolescence of incumbent sensing architectures. Domestic OEMs in the Yangtze River Delta and Pearl River Delta compress development cycles to capture platform sourcing decisions.
Germany
Commercial leasing providers dictate state-of-health telemetry terms to protect residual value in electrified truck fleets. EU Battery Regulation recycled content mandates and CE marking requirements reshape supplier qualification criteria. Industrial clusters in Bavaria and Baden-Württemberg host integrated system development for premium passenger platforms.
United States
Heavy-duty logistics operators mandate real-time battery monitoring across extended duty cycles. NHTSA defect investigation exposure concentrates thermal event liability, forcing redundant validation protocols. Development activity clusters in Michigan and California, where commercial truck electrification programs intersect with passenger vehicle corridors.
India
Domestic cell manufacturing incentives under the PLI scheme create demand for indigenous BMS design capabilities. Central Electricity Authority and BIS standards evolution shapes certification requirements for two-wheeler and commercial applications. Tamil Nadu and Gujarat industrial corridors attract calibration capability investments.
South Korea
LG Chem and domestic semiconductor suppliers drive precision cell balancing algorithm development for 800V architectures. MFDS-aligned safety protocols and METI-coordinated standards influence regional certification approaches. Seoul Capital Area and Busan-Ulsan manufacturing belts concentrate high-voltage platform engineering.
Electric Vehicle Battery Management System Market Vendor Landscape
Top-tier vendors anchor integrated hardware-software control, while tier-one suppliers absorb escalating warranty risk in contract negotiations. The structure stratifies across captive OEM architectures, independent semiconductor specialists, and tier-one system integrators. Archetypes include cell-to-pack embedded intelligence providers, thermal runaway detection specialists, and wireless monitoring technology developers. Dominant competitive moves encompass strategic partnerships for solid-state validation and geographic expansion into India PLI scheme corridors.
Within the captive OEM tier, Tesla sustains proprietary architectures across commercial and passenger platforms. Among tier-one system integrators, Robert Bosch occupies a position calibrated for heavy-duty cycle profiles. Contemporary Amperex Technology Co. Limited anchors the cell-to-pack embedded intelligence segment. These three exemplify how competitive positioning fragments across integration depth, application specialization, and geographic certification focus.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| Tesla |
| Vishay Intertechnology |
| Texas Instruments |
| LG Chem |
| Analog Devices |
| Continental AG |
| STMicroelectronics |
| Robert Bosch |
| Others |
Supply Flow & Price Mechanics
The EU Battery Regulation's recycled content mandates and carbon footprint disclosure requirements gate qualified supply access for tier-one BMS suppliers while simultaneously compressing premium-tier pricing power for uncertified competitors. Buyers in Germany's commercial leasing market now embed material provenance tracking as a contractual prerequisite, forcing price stratification between compliant and non-compliant sourcing tiers.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to automotive-grade AEC-Q100 qualified microcontrollers facing allocation constraints from concentrated foundry capacity in East Asian manufacturing clusters. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation driven by ISO 26262 ASIL-D certification grade and volume scale commitments. Cost compression in modular aftermarket systems is intensifying because CAN protocol fragmentation forces redundant firmware development across aging hybrid fleet retrofits. Fleet operators exhibit the highest price sensitivity due to residual value protection requirements, while premium passenger OEMs in Germany prioritize space-constrained integrated architectures with minimal cost elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tesla and CATL, while tier-one system integrators like Robert Bosch maintain parallel distribution through commercial truck fleet procurement centers. Geographic supply concentration centers on China for cell-to-pack manufacturing, South Korea for LG Chem's precision balancing algorithms, and Taiwan for semiconductor foundry capacity. Raw material dependencies include lithium carbonate from South American salares, nickel sulfate from Indonesian processing facilities, and copper foil for current collectors. Single-source vulnerability in automotive-grade microcontroller supply from East Asian manufacturing clusters poses structural risk. Distribution runs through consolidated technical centers at logistics giants and municipal transit authorities that bypass traditional tier-one intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
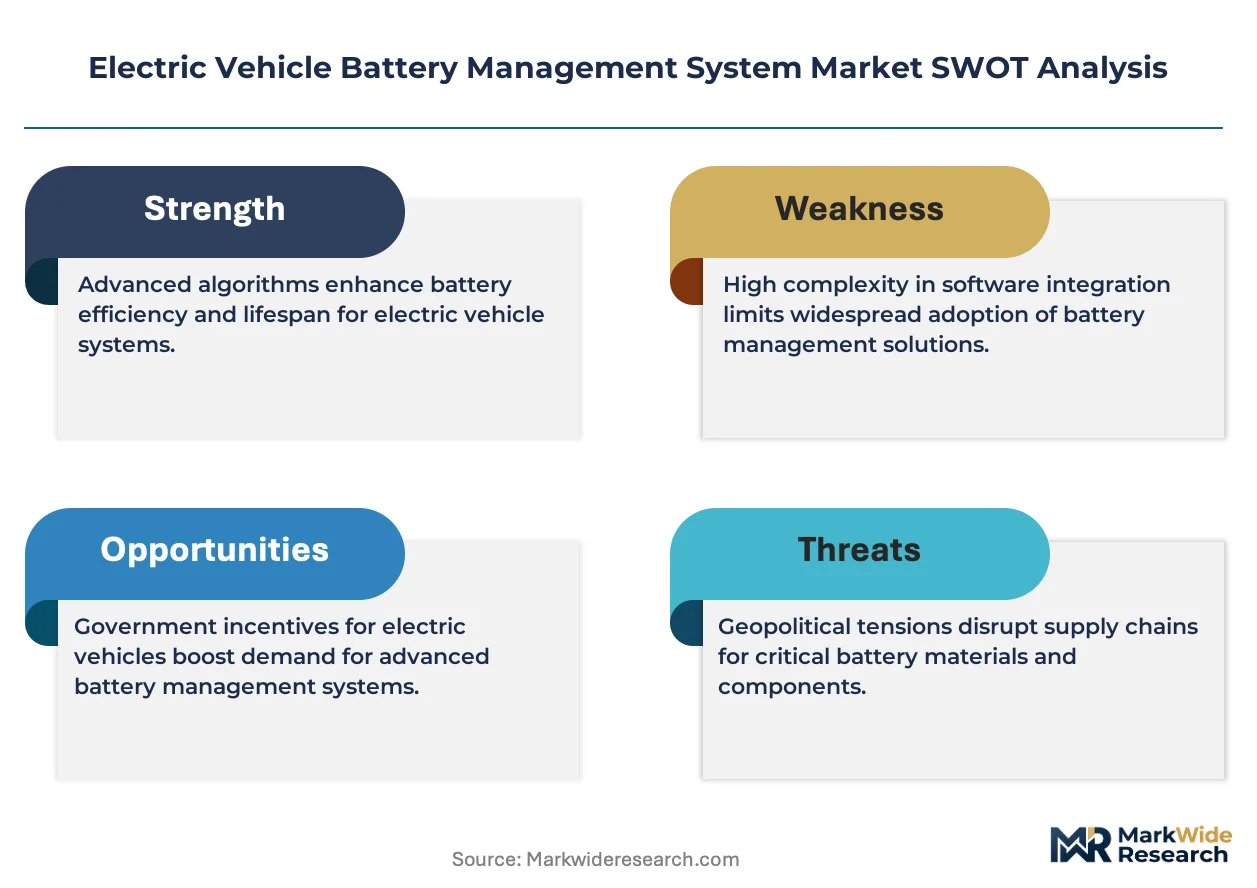
The Electric Vehicle Battery Management System market sits in a technology-transition phase as solid-state cell architectures with ceramic electrolytes displace incumbent lithium-ion sensing platforms. This displacement forces parallel validation tracks and premature obsolescence risk for suppliers anchored to legacy chemistries.
For Market Incumbents: Acquire solid-state validation capabilities and embedded wireless monitoring IP to defend against disintermediation by fleet operator procurement centers. CATL's cell-to-pack dominance and Tesla's proprietary integration threaten tier-one margin pools. Backward integration into semiconductor design or captive foundry partnerships in South Korea and Taiwan reduces AEC-Q100 allocation vulnerability. For New Entrants and Emerging Players: Fleet operator technical centers represent the most penetrable channel partner type for bypassing established tier-one relationships. India's PLI scheme corridors offer white-space demand for indigenous BMS calibration capabilities serving two-wheeler and commercial applications. Second-life stationary storage repurposing for degraded automotive packs provides a software-defined entry point with lower certification barriers. For Investors and Strategic Acquirers: SAMR solid-state certification timeline announcements are the leading indicator that platform sourcing decisions will concentrate among domestic Chinese OEMs within the next development cycle. Long-term viability favors suppliers with parallel GB standards and NMPA validation tracks. Target acquisition archetypes include thermal runaway detection specialists with heavy-duty cycle calibration and wireless cell monitoring developers with FCC Part 15 clearance. Watch for NHTSA defect investigation escalations as thermal event liability concentration signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Investment | Eliminates redundant module housings and redistributes thermal management intelligence across CATL's consolidated enclosures. |
| 800V Platform Standardization | Demands precision cell balancing algorithms that legacy 400V systems cannot support, forcing upgrade imperatives. |
| Solid-State Validation Partnership | Synchronizes development timelines with SAMR certification windows to avoid exclusion from Chinese OEM sourcing. |
| Wireless Monitoring Technology Deployment | Reduces pack weight and assembly labor, with adoption concentrating in premium passenger platforms. |
| India PLI Localization Buildout | Creates indigenous BMS design capabilities serving Tamil Nadu and Gujarat industrial corridors. |
Methodological Framework
Multi-period observation of NMPA battery safety mandate implementation, EU Battery Regulation recycled content thresholds, and SAMR certification timeline compression anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and fleet operator technical center directors. Secondary validation drew from NHTSA defect investigation filings, EPA emissions compliance pathways, GB standards evolution documents, and vehicle production databases. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices modeled relationships between propulsion architecture voltage tiers, vehicle class duty cycle severity, content per vehicle node counts, OEM integration depth preferences, and regional production cluster concentrations across the projection horizon. CAGRs were derived from segment-level growth trajectory analysis. Industry-specific forecast inputs included 800V platform proliferation rates and solid-state cell chemistry commercialization timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, semiconductor supply disruptions beyond current allocation constraints, and breakthrough cell chemistries that obviate existing sensing architectures. Forecasts reflect assumptions regarding GB standards synchronization with solid-state maturation and NHTSA liability allocation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
India Stationary Battery Energy Storage System Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
Global Power Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
EV Battery Management Market
Battery Management System
Energy Storage Systems Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
Renewable Battery Storage Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
US Energy Storage Market