
 Asia-Pacific Battery Energy Storage System Market | 2026-2036
Asia-Pacific Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Battery Energy Storage System Market Outlook
The capability gap between vertically integrated cell manufacturers and pure-play system integrators is collapsing. BYD Company Limited leverages its captive lithium iron phosphate cell production to undercut rivals on module cost. Samsung SDI Co Ltd anchors its position through proprietary prismatic cell chemistry optimized for high-cycle utility applications. Contemporary Amperex Technology Co. Ltd dominates cylindrical and prismatic supply to third-party integrators across the region.
A battery energy storage system comprises electrochemical cells packaged with power conversion, thermal management, and control systems to absorb and discharge electricity on command. Lithium-ion configurations now account for the bulk of installed capacity due to energy density thresholds above 250 Wh/kg and declining cell costs. Grid-tied technology leads deployment scale as utilities favor direct interconnection with transmission infrastructure. Virtual power plant architecture represents the fastest-expanding segment, aggregating distributed assets into dispatchable capacity pools that compete with centralized peaking plants.
China's MIIT enforces GB standards on battery safety and cycle life that determine market access for domestic and imported systems. South Korea's KATS and Japan's METI coordinate technical harmonization through aligned JIS and KC certification pathways, reducing friction for Korean and Japanese suppliers. Stakeholders must track how India's BIS adoption of IEC 62619 and CEA grid codes reshape procurement criteria for utility-scale tenders.
Market Dynamics
The collapse of capability gaps between cell manufacturers and system integrators is redrawing competitive boundaries across the Asia-Pacific battery energy storage system market. China's MIIT mandates on energy density and cycle life now function as de facto market access gates, compressing margins for pure-play integrators while rewarding captive cell production.
Growth Catalysts
- MIIT GB Standard Enforcement:China's tightened safety and performance thresholds for lithium-ion cells are accelerating replacement cycles in utility-scale installations. Grid operators in eastern China must now procure only certified systems.
- Virtual Power Plant Aggregation:Distributed asset pooling is displacing centralized peaking capacity across South Korea and Japan. METI-aligned utilities are contracting aggregated storage pools for frequency regulation services.
- Southeast Asia Utility Procurement:State-owned power companies in Thailand, Vietnam, and the Philippines are tendering grid-scale storage to manage renewable intermittency. Procurement volumes concentrate where transmission infrastructure intersects solar and wind zones.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings compress module margins for non-integrated system builders. Cell producers with captive lithium supply chains maintain cost advantages during input spikes.
- Prismatic Cell Supply Concentration:Korean and Japanese producers control high-cycle prismatic output for utility applications. Third-party integrators face allocation constraints during demand surges.
- Grid Code Harmonization Gaps:India's CEA technical standards diverge from IEC 62619 baselines adopted by BIS. Foreign suppliers must duplicate certification efforts for Indian utility tenders.
Strategic Opportunities
- India Utility-Scale Tenders:Underpenetrated state distribution companies are issuing multi-gigawatt-hour storage mandates. CEA grid code finalization will unlock procurement at scale for compliant suppliers.
- Iron-Air Hybrid Convergence:Long-duration chemistries are pairing with lithium-ion front-ends to extend discharge windows. Australian and Japanese pilot projects are validating hybrid architectures for seasonal shifting.
- Direct Developer Channel Models:Bypassing traditional EPC contractors, cell producers are contracting directly with renewable developers. This channel compression captures margin previously allocated to system integrators.
Industry Challenges
- Thermal Management Engineering Scarcity:Battery system designers with liquid cooling expertise command premium compensation. Korean and Japanese producers are poaching talent from automotive thermal teams.
- Multi-Certification Timeline Compression:Simultaneous BIS, KC, and JIS testing extends product launch cycles. Suppliers must parallel-track documentation to meet tender deadlines.
- Legacy SCADA Integration Friction:Utility control rooms operate decades-old dispatch software. New storage assets require protocol translators that introduce latency and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Battery Energy Storage System Market |
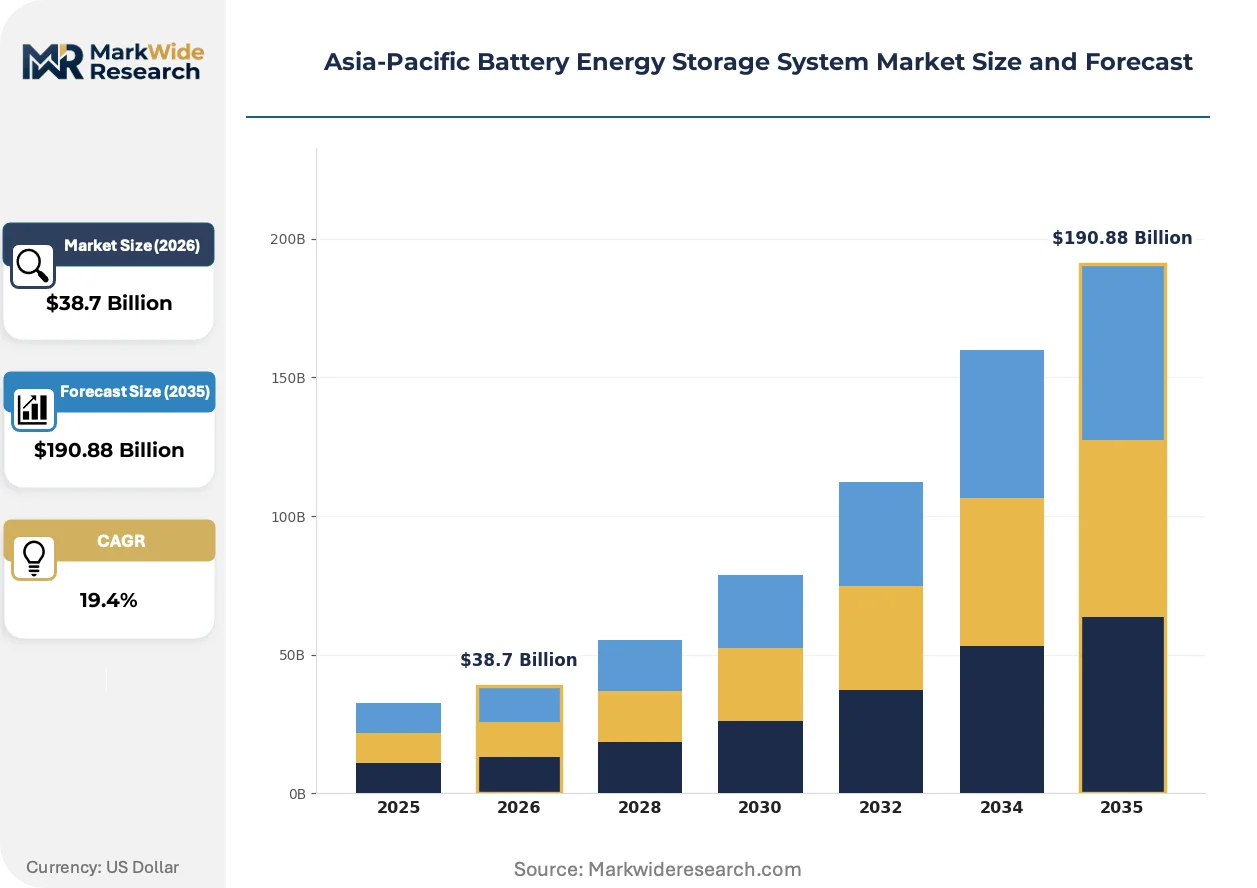
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow, Nickel-cadmium Use Case: Renewable Integration, Peak Shaving, Frequency Regulation, Backup Power End User: Utilities, Commercial, Residential, Industrial Technology: Grid-tied, Off-grid, Hybrid, Virtual Power Plant |
| Companies Covered | Samsung SDI Co Ltd, Toshiba Corporation, BYD Company Limited, Hitachi, NEC, LG Chem, Panasonic Corporation, Tesla Inc., Contemporary Amperex Technology Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Battery Energy Storage System Market Strategic Shifts
Sodium-ion cell chemistry is advancing from pilot to commercial scale, threatening to undercut lithium iron phosphate in stationary applications where energy density matters less than cycle cost. This chemistry rotation coincides with regulatory pressure on supply chain provenance and buyer demands for procurement flexibility.
Sodium-ion technology is fragmenting the low-cost stationary storage segment. Chinese producers are scaling 160 Wh/kg cells for grid-tied installations where weight and volume constraints are minimal. Utility procurement teams in Jiangsu and Shandong are piloting sodium-ion buffers for renewable smoothing, compressing the addressable market for lithium iron phosphate in price-sensitive tenders.
Japan's METI has aligned JIS C 8715-2 with IEC 62619 to accelerate Korean supplier access. This harmonization reduces retesting burdens for Samsung SDI and LG Energy Solution. Indian regulators are observing this bilateral coordination as BIS finalizes its own adoption roadmap, with CEA technical committees referencing the Japan-Korea precedent.
Aggregators are unbundling storage assets from long-term offtake contracts. Virtual power plant operators in South Korea now offer merchant exposure to battery owners, replacing decade-long utility leases. This risk transfer model concentrates in the KPX market where real-time price signals reward flexible dispatch.
Asia-Pacific Battery Energy Storage System Market Segmentation
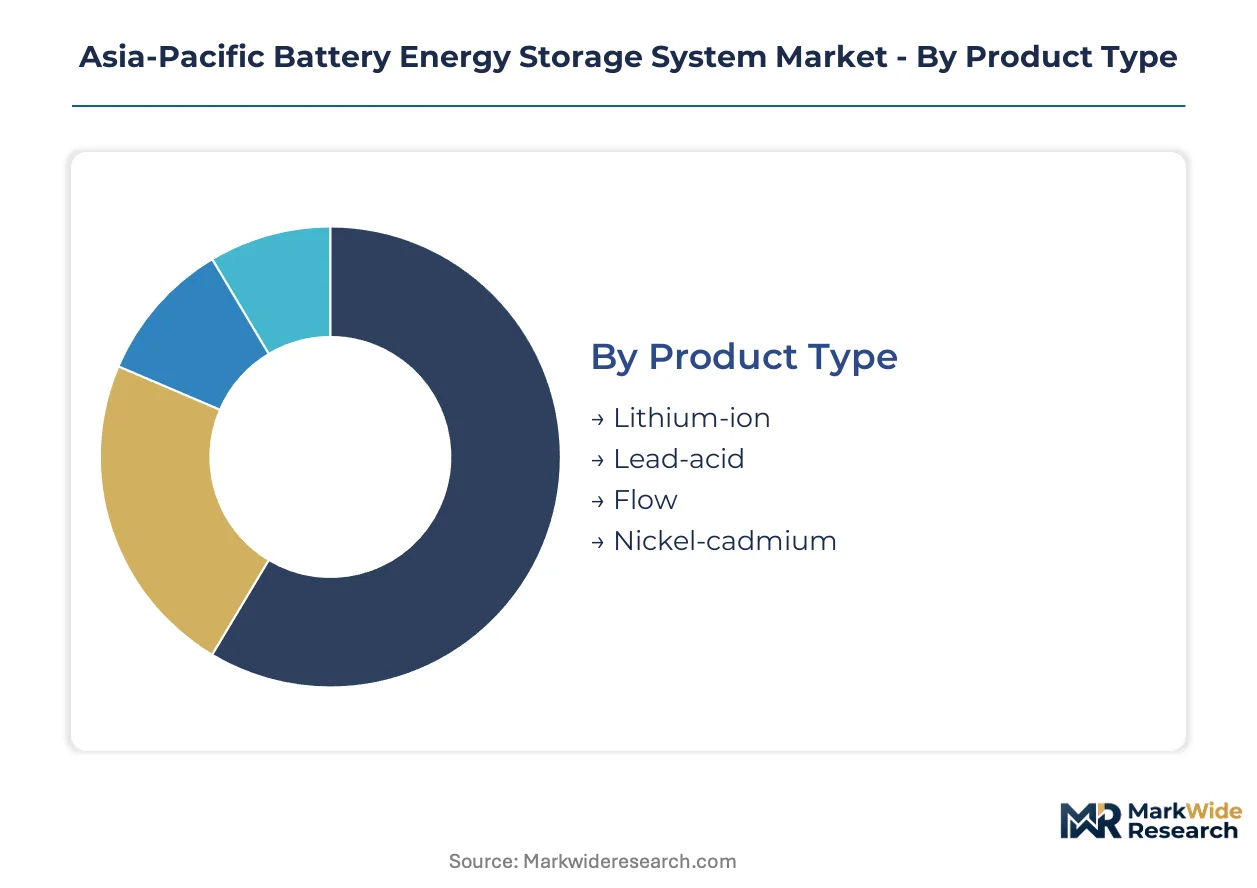
Segmentation in the Asia-Pacific battery energy storage system market reveals where substitution pressures and regulatory thresholds reshape procurement patterns. Technology transitions and certification requirements fragment addressable demand across chemistry types, grid architectures, and end-use applications.
Product Type:
Sodium-ion chemistries are mounting the strongest substitution threat against established lithium-ion configurations in price-sensitive stationary applications across eastern China and India.
- Lithium-ion:Dominant electrochemical configuration utilizing lithium iron phosphate and nickel-manganese-cobalt cathodes with energy density thresholds above 250 Wh/kg. Procurement concentrates in South Korean utility tenders where MIIT-aligned safety standards and high-cycle requirements favor certified lithium-ion systems from integrated cell producers.
- Lead-acid:Mature flooded and valve-regulated designs with lower upfront capital requirements but constrained cycle life below 1500 cycles. Demand persists in Indian commercial backup applications where BIS certification timelines and cost sensitivity delay lithium-ion adoption in tier-2 cities.
- Flow:Vanadium and zinc-bromine redox systems offering 8-12 hour discharge duration for seasonal shifting. Pilot deployments validate hybrid pairing with lithium-ion front-ends in Australian and Japanese long-duration projects.
- Nickel-cadmium:Rugged alkaline chemistry with extreme temperature tolerance. Niche demand survives in Southeast Asian industrial microgrids where ambient thermal stress exceeds lithium-ion operating envelopes.
Lithium-ion retains volume leadership; flow batteries hold the steepest expansion curve for multi-hour discharge applications.
Use Case:
Application-driven segmentation tracks where revenue pools concentrate based on grid code maturity and tariff structures across the region.
- Renewable Integration:Buffer storage co-located with solar and wind assets to smooth intermittency and firm dispatch schedules. Procurement volumes cluster in Vietnam and Thailand where state-owned utilities tender grid-scale systems at transmission substations intersecting renewable zones.
- Peak Shaving:Discharge during demand spikes to reduce capacity charges and defer transmission upgrades. Commercial and industrial facilities in Japan's KPX market deploy behind-the-meter systems to exploit time-of-use arbitrage.
- Frequency Regulation:Rapid-response discharge to maintain grid frequency within operational bands. Aggregated virtual power plant pools in South Korea contract with Korea Power Exchange for ancillary services.
- Backup Power:Uninterruptible supply during grid outages for critical infrastructure. Hospitals and data centers across the Philippines specify nickel-cadmium or lead-acid systems where maintenance capabilities limit lithium-ion adoption.
Renewable integration commands the largest procurement volumes; frequency regulation offers the most attractive merchant revenue streams.
End User:
Customer-type segmentation exposes diverging procurement sophistication and contract structures across the demand base.
- Utilities:State-owned transmission and distribution companies issuing multi-gigawatt-hour tenders with decade-long offtake agreements. Procurement in India accelerates as CEA finalizes grid codes enabling utility-scale deployment.
- Commercial:Retail, logistics, and manufacturing facilities seeking behind-the-meter peak shaving and backup. Japanese commercial estates favor grid-tied lithium-ion systems with JIS C 8715-2 certification.
- Residential:Single-family and multi-unit dwellings with rooftop solar pairing. South Korean apartment complexes aggregate distributed assets into virtual power plant pools contracted to KEPCO.
- Industrial:Heavy manufacturing and process industries with high power quality requirements. Steel and chemical plants in eastern China procure MIIT-certified systems for power reliability.
Utilities dominate absolute capacity deployment; commercial segments exhibit the most rapid adoption acceleration.
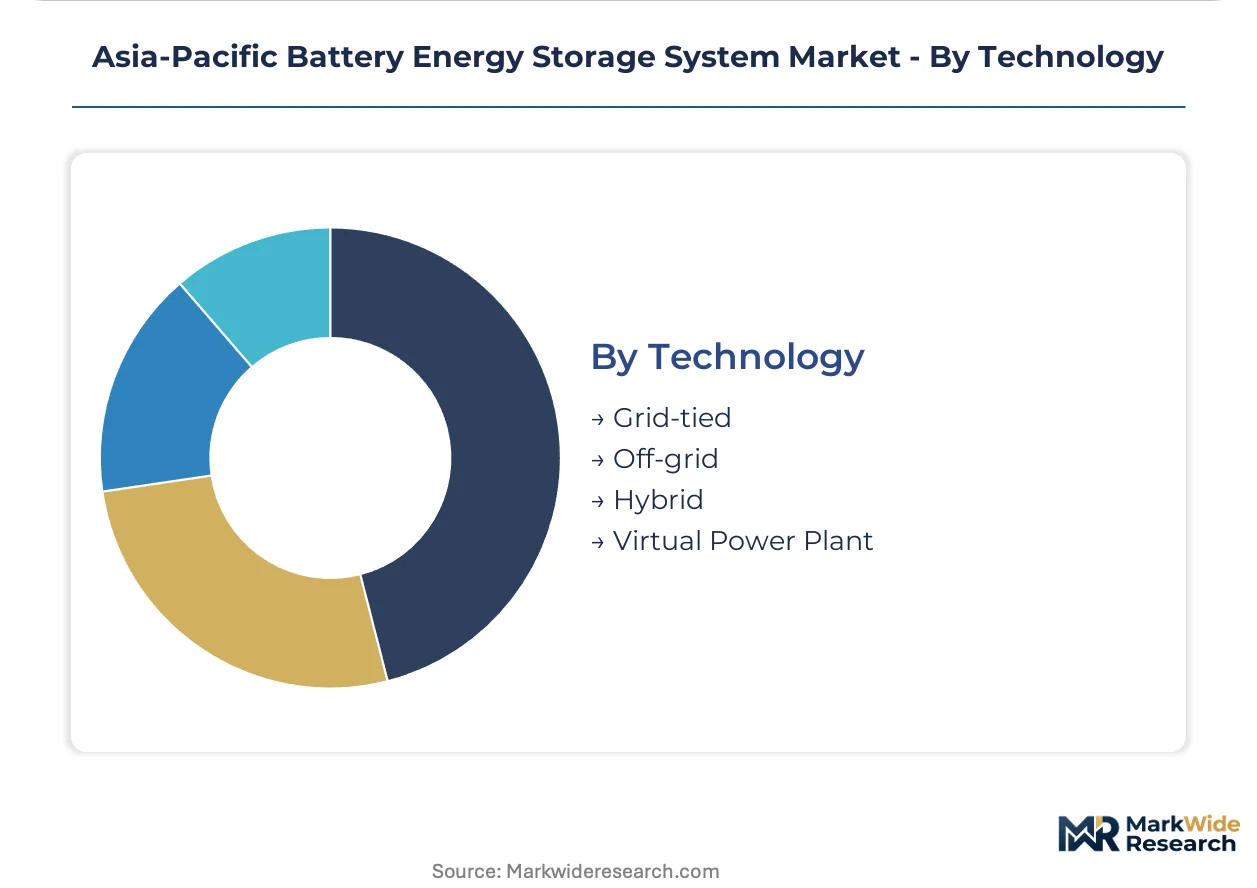
Technology:
System architecture segmentation tracks how interconnection standards and control protocols reshape competitive positioning.
- Grid-tied:Direct interconnection with transmission or distribution infrastructure enabling wholesale market participation. Dominates utility procurement in China, South Korea, and Japan where grid codes mandate centralized dispatch capability.
- Off-grid:Islanded operation for remote communities and industrial sites without reliable grid access. Southeast Asian mining operations and Philippine island municipalities deploy hybrid solar-storage microgrids.
- Hybrid:Combined renewable generation and storage with shared power conversion and control systems. Australian and Japanese pilots validate lithium-ion and iron-air hybrid configurations for seasonal shifting.
- Virtual Power Plant:Aggregated distributed assets dispatched as unified capacity pools through centralized control platforms. South Korean aggregators unbundle storage from long-term leases, offering merchant exposure to battery owners in KPX real-time markets.
Grid-tied systems anchor current deployment scale; virtual power plant architecture is gaining share fastest as aggregation platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Japanese cell producers while Chinese system integrators compete on procurement volume. This asymmetry shapes procurement patterns across the region.
China
MIIT GB standards on energy density and cycle life gate market access for utility-scale tenders. Eastern provinces Jiangsu and Shandong pilot sodium-ion buffers for renewable smoothing, compressing lithium iron phosphate margins in price-sensitive bids.
Japan
METI-aligned utilities contract aggregated storage pools for frequency regulation services. JIS C 8715-2 harmonization with IEC 62619 reduces retesting burdens for Korean suppliers accessing the market.
South Korea
Korea Power Exchange real-time markets reward flexible dispatch from virtual power plant aggregators. Samsung SDI and LG Energy Solution anchor prismatic cell supply for high-cycle utility applications.
India
CEA grid code finalization will unlock multi-gigawatt-hour procurement at scale for compliant suppliers. State distribution companies in Maharashtra and Gujarat issue underpenetrated storage mandates.
Australia
Long-duration pilots validate lithium-ion and iron-air hybrid architectures for seasonal shifting. Western Australian mining operations deploy hybrid solar-storage microgrids where grid access remains unreliable.
Asia-Pacific Battery Energy Storage System Market Competitive Environment
Concentration sits with vertically integrated cell manufacturers possessing captive lithium supply chains. The vendor base splits between integrated producers controlling cell chemistry and pure-play system integrators assembling third-party modules. Two archetypes dominate: Korean and Japanese prismatic specialists, and Chinese LFP-integrated conglomerates. Competitive moves center on backward integration into lithium refining and direct developer channel compression bypassing traditional EPC contractors.
Among Korean producers, Samsung SDI Co Ltd and LG Chem exemplify the prismatic chemistry archetype for high-cycle utility applications. BYD Company Limited represents the Chinese integrated model with captive lithium iron phosphate production. Contemporary Amperex Technology Co. Ltd occupies a position as cylindrical and prismatic supplier to third-party integrators across the region.
| Leading Market Players |
|---|
| Samsung SDI Co Ltd |
| Toshiba Corporation |
| BYD Company Limited |
| Hitachi |
| NEC |
| LG Chem |
| Panasonic Corporation |
| Tesla Inc. |
| Contemporary Amperex Technology Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Sodium-ion chemistry substitution for lithium iron phosphate in eastern China's Jiangsu and Shandong utility tenders simultaneously redistributes cell manufacturing geography toward inland cathode precursor facilities and compresses module pricing economics for non-integrated system builders.
Pricing Analysis
Configured-to-order pricing for MIIT-certified utility systems commands a 15-25% premium over standard catalog offerings from pure-play integrators. Pricing stratifies across premium MIIT-GB certified, standard KC/JIS compliant, and economy-grade lead-acid replacement tiers. Cost compression in the standard tier is intensifying because BYD and CATL are direct-contracting renewable developers, bypassing EPC markups. State-owned utilities in China and Thailand exhibit the highest price sensitivity due to tender-based procurement, while Japanese commercial estates pay premiums for JIS C 8715-2 certification and localized after-sales support.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and prismatic cell inventory dominates procurement behavior among Korean and Japanese producers facing allocation constraints during demand surges. Cell production concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Chinese Hunan and Fujian provinces. The supply chain rests on spodumene concentrate from Australia, cobalt hydroxide from the DRC, and nickel matte from Indonesia. Single-source vulnerability sits with Korean producers' dependence on Chinese-separated lithium hydroxide. Distribution runs through direct developer channels that are displacing traditional EPC contractor networks across Southeast Asian utility markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in underpenetrated Indian state distribution companies and Australian long-duration hybrid pilots, where demand-side shifts toward merchant-exposed virtual power plant aggregation create niche entry points for non-integrated specialists.
For Market Incumbents: Consolidate through captive lithium refining investments in Australia and Chile to offset carbonate volatility squeezing module margins. Acquire sodium-ion pilot producers in China before chemistry rotation accelerates. MIIT certification timelines function as the critical lever for locking in eastern China utility procurement.
For New Entrants and Emerging Players: Differentiate on iron-air hybrid system integration for Australian and Japanese seasonal shifting applications where lithium-ion front-end pairing commands technical credibility. Target Indian state distribution company tenders in Maharashtra and Gujarat as the most penetrable geography. Pursue direct developer channel contracts bypassing EPC intermediaries to capture margin compression.
For Investors and Strategic Acquirers: The market sits at a certification-concentration phase that favors vertically integrated cell producers with captive lithium supply chains and multi-standard testing capabilities. Long-term viability hinges on backward integration into cathode precursor production. The signal to watch is BIS adoption of IEC 62619 alignment, which would unlock Indian procurement scale and revalue compliant supplier archetypes.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | GB standard compliance gates utility-scale access in Jiangsu and Shandong procurement. |
| Direct Developer Channel Buildout | Bypassing EPC contractors captures margin previously allocated to system integrators. |
| Lithium Refining Backward Integration | Captive supply chains insulate module margins from carbonate price spikes. |
| Sodium-Ion Pilot Scale-Up | 160 Wh/kg cell production threatens LFP economics in stationary applications. |
| Virtual Power Plant Platform Development | KPX real-time market access enables merchant revenue streams for aggregated storage. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators across China, South Korea, Japan, and India, and refined through secondary validation against MIIT GB standard filings, CEA technical committee records, KPX market data, and IEA energy storage deployment statistics. Bottom-up project pipeline aggregation was triangulated against top-down capacity forecasts.
Variance decomposition across chemistry type, use case, end user, and technology architecture shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs incorporated lithium carbonate price scenario curves and regulatory adoption timelines for BIS, KC, and JIS certification alignment.
Forecasts assume regulatory continuity in MIIT GB enforcement, METI-METI harmonization, and CEA grid code finalization; material policy shifts would require re-modeling. Revision becomes warranted when sodium-ion chemistry cost parity crosses lithium iron phosphate thresholds in utility tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Battery Systems for Electric Vehicle Market
Battery Management System
Energy Storage Systems Market
Battery Management System
North America Energy Storage Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Battery Management Market
Battery Management System
US Energy Storage Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Automotive Energy Storage System Market