
 North America Lithium-Ion Battery Market | 2026-2036
North America Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium-Ion Battery Market Outlook
Automotive-grade cell qualification is collapsing the gap between premium and mass-market battery supply. Tesla leverages its Nevada gigafactory to anchor cylindrical cell production for its vehicle lineup. Panasonic Corporation sustains its joint-venture manufacturing scale in North America, while LG Energy Solution competes through dedicated pouch-cell capacity serving Detroit automakers.
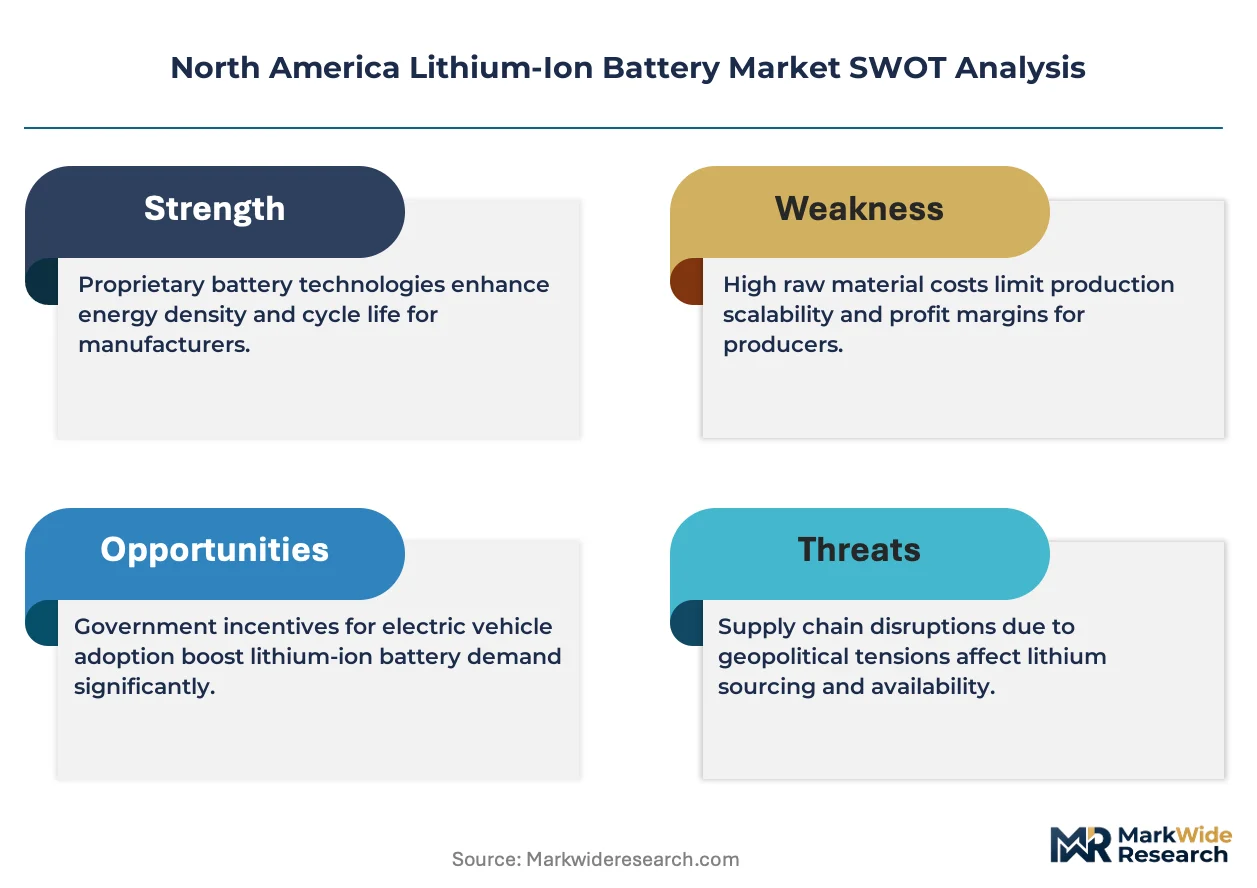
A lithium-ion battery is an electrochemical storage device using intercalated lithium compounds in the positive electrode and typically graphite in the negative electrode, with energy densities ranging from 150 to 300 watt-hours per kilogram depending on cathode chemistry. Its primary commercial purpose is to store and discharge electrical energy through reversible lithium-ion movement between electrodes during charge and discharge cycles. Electric Vehicle batteries occupy the dominant value pool given OEM procurement scale, while LFP technology is gaining structural share in grid storage applications where cycle life and thermal stability outweigh energy density requirements. Consumer Electronics represents a mature, price-sensitive segment where margin compression limits new entrants.
The Inflation Reduction Act and NHTSA safety standards jointly reshape domestic content thresholds and cell testing protocols for vehicles sold in the United States. EPA tailpipe regulations and state-level zero-emission mandates in California and New York accelerate fleet electrification timelines and battery procurement obligations. Stakeholders must monitor cathode chemistry patent landscapes and raw material offtake agreements as the decisive variables for cost position and supply security.
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are forcing cell manufacturers to reconfigure cathode supply chains around North American mineral processing capacity.
Growth Catalysts
- IRA Production Tax Credits:The Inflation Reduction Act's $35 per kilowatt-hour credit for U.S.-manufactured cells is pulling gigafactory investment toward Michigan, Ohio, and Tennessee.
- Grid Storage Procurement:Utility-scale battery installations are accelerating across Texas and California as intermittent renewable penetration requires four-hour duration storage.
- LFP Chemistry Maturation:Lithium iron phosphate cathodes are displacing nickel-cobalt formulations in commercial vehicles where thermal stability outweighs energy density requirements.
Market Restraints
- Spodumene Concentration:Hard-rock lithium feedstock relies on Australian and Canadian mine output, creating geographic vulnerability for U.S. cell plants.
- Graphite Dependence:Synthetic and natural anode material remains concentrated in Chinese processing facilities, complicating IRA origin compliance.
- Electrolyte Salt Bottleneck:Lithium hexafluorophosphate purification capacity is structurally limited in North America, constraining cell output scaling.
Strategic Opportunities
- Mexican Cathode Precursor Sourcing:Sonora and Baja California are attracting lithium hydroxide conversion investments to satisfy U.S.-Mexico-Canada Agreement rules of origin.
- Second-Life Battery Aggregation:Retired electric vehicle packs are creating a distributed storage resource for commercial and industrial peak-shaving applications.
- Solid-State Pilot Lines:Sulfide-based electrolyte manufacturing is attracting Department of Energy loan guarantees for pre-commercial production in the U.S. Northeast.
Industry Challenges
- Cell Formation Capacity Scarcity:The electrochemical aging process requires weeks of controlled cycling, creating a manufacturing bottleneck that limits output velocity regardless of electrode coating speed.
- UN 38.3 Certification Backlogs:Lithium-ion shipping classification testing faces laboratory queue delays, extending product launch timelines for new cell formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium-Ion Battery Market |
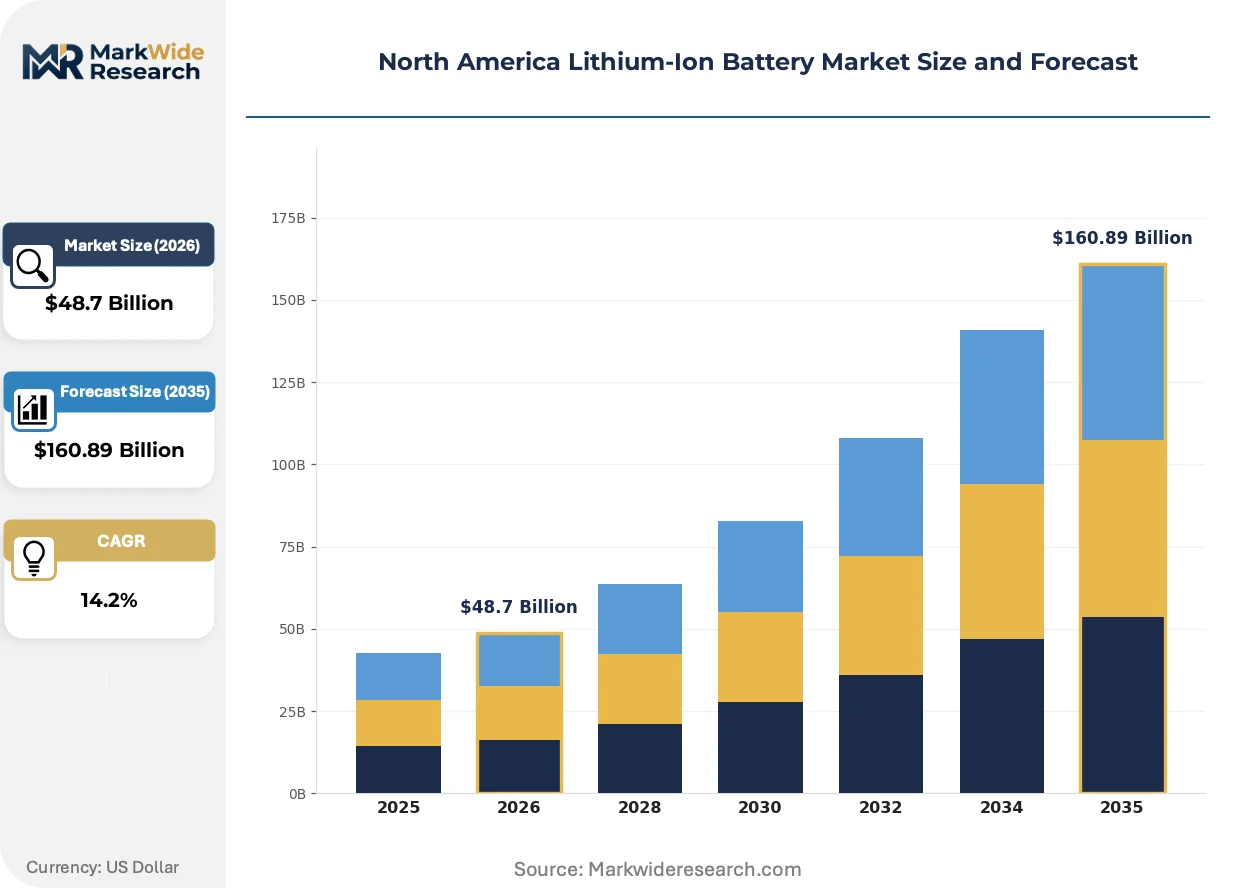
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Electric Vehicle, Aerospace Technology: LFP, NMC, NCA, LMO End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Application: Grid Storage, Power Tools, Electric Bicycles, Drones |
| Companies Covered | Tesla, Panasonic Corporation, LG Energy Solution, Samsung SDI, Contemporary Amperex Technology (CATL), BYD, SK On, Northvolt, Duracell Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium-Ion Battery Market Strategic Shifts
Cell manufacturing is splitting between high-nickel chemistries for automotive range extension and iron-based formulations for cost-sensitive stationary applications.
Lithium metal anode technology is bifurcating development pathways. Silicon Valley startups pursue solid-state architectures for aviation and defense applications where energy density above 400 watt-hours per kilogram justifies premium pricing. Concurrently, incumbent manufacturers are integrating thin lithium foils into conventional liquid electrolyte designs for drone and satellite markets. This dual-track development is compressing the timeline for commercial solid-state deployment while sustaining liquid electrolyte process investments.
EPA tailpipe regulations are tightening fleet-average carbon intensity mandates through 2032. Automakers must electrify light-truck segments previously dominated by internal combustion engines, expanding battery pack size requirements. The commercial vehicle segment faces the steepest compliance burden, driving demand for heavy-duty cell architectures with enhanced thermal management.
Fleet operators are consolidating procurement through direct cell supplier relationships rather than relying on vehicle OEM battery warranties. Large logistics companies in California and New York are negotiating volume offtake agreements with cell manufacturers for dedicated commercial vehicle production. This disintermediation is compressing margin pools for traditional automotive tier-one suppliers and accelerating vertical integration by end-users.
North America Lithium-Ion Battery Market Segmentation
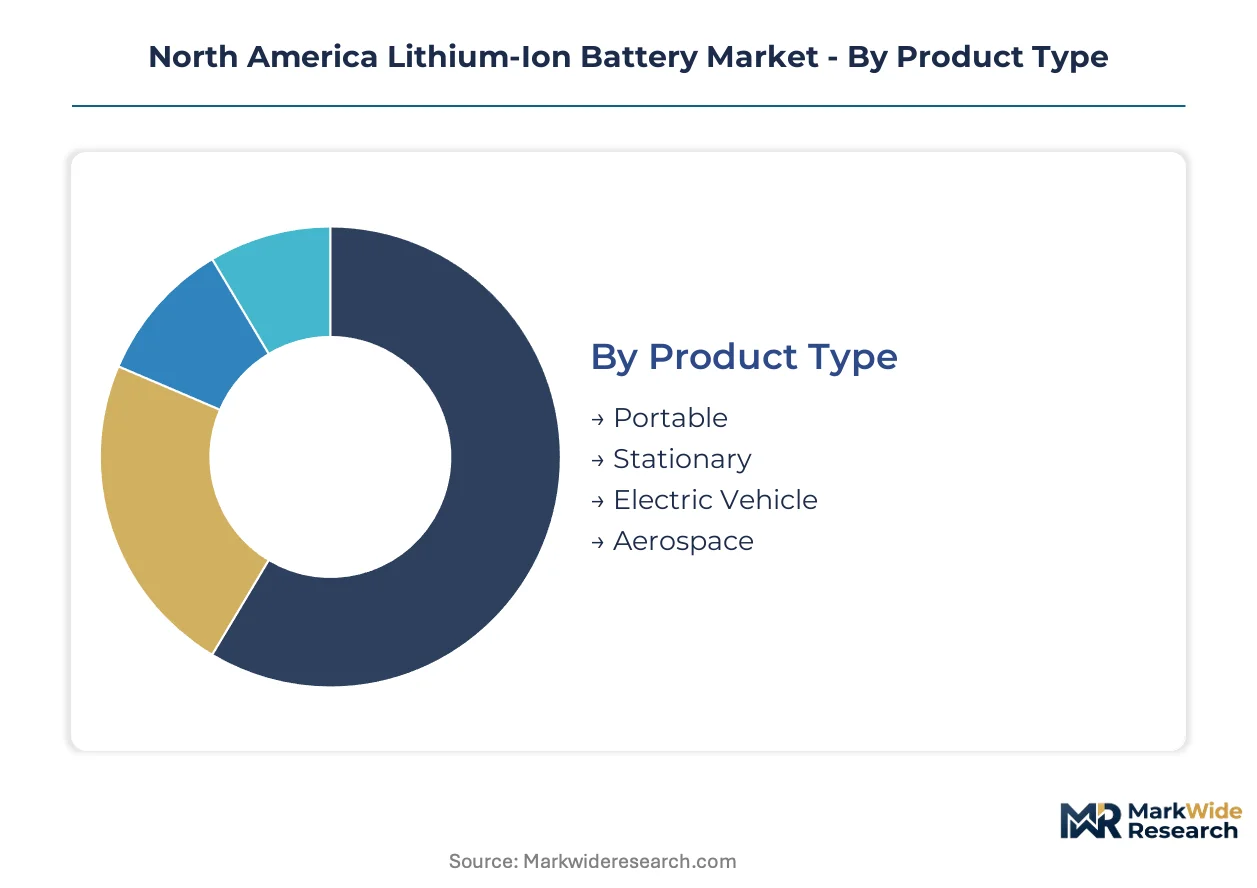
Segmentation in the North America lithium-ion battery market reveals how procurement channels bifurcate between automotive OEM direct contracts and distributor-mediated industrial sales. Understanding these flow patterns exposes where margin pools concentrate and where supply bottlenecks threaten fulfillment.
Product Type:
Channel structure varies sharply across product categories, with automotive-grade cells moving through dedicated OEM supply agreements while portable and stationary batteries flow through electrical distributors and EPC contractors.
- Portable:Compact cylindrical and pouch cells power cordless tools, medical devices, and personal electronics. California and Texas distribution centers handle the highest throughput volumes for contractor-grade tool batteries.
- Stationary:Rack-mounted battery systems serve commercial peak-shaving and residential backup power applications. Utility procurement desks in Michigan and Ohio are consolidating orders for multi-megawatt containerized installations.
- Electric Vehicle:Prismatic and cylindrical cells integrate into battery packs through tier-one automotive suppliers. Detroit automakers in Michigan anchor the dominant procurement channel for this segment.
- Aerospace:Specialized high-discharge cells meet FAA certification requirements for auxiliary power units and electric propulsion prototypes. Defense contractors in California and Washington state drive classified procurement volumes.
By volume, Electric Vehicle leads. By growth pace, Stationary is expanding most quickly.
Technology:
Cost tiers separate these chemistries, with nickel-cobalt formulations commanding premium pricing for range-critical applications while iron-based alternatives capture price-sensitive grid storage contracts.
- LFP:Lithium iron phosphate cathodes deliver thermal stability and extended cycle life at moderate energy density. Texas utility-scale installations and California commercial fleets are displacing nickel-cobalt alternatives where safety margins outweigh range requirements.
- NMC:Nickel-manganese-cobalt layered oxides optimize energy density for automotive range extension. Michigan and Ohio cell plants are scaling high-nickel variants to satisfy Detroit OEM procurement specifications.
- NCA:Nickel-cobalt-aluminum formulations serve premium electric vehicle segments requiring maximum gravimetric energy density. Nevada manufacturing lines supply cylindrical NCA cells for performance-oriented vehicle platforms.
- LMO:Lithium manganese oxide cathodes occupy niche applications in power tools and medical devices where cost and safety balance against moderate energy needs. Industrial distributors across the U.S. Midwest stock LMO cells for replacement battery markets.
By manufacturing scale, NMC dominates current output. By share gain trajectory, LFP is climbing the fastest.
End User:
Customer type determines contract structure, with automotive buyers negotiating multi-year offtake agreements while industrial and renewable energy purchasers favor project-based procurement with EPC wrap guarantees.
- Consumer Electronics:Mature demand for smartphones, laptops, and wearables flows through established Asian contract manufacturers. Margin compression in this segment limits North American cell plant participation.
- Automotive:Light-duty and commercial vehicle electrification drives the dominant value pool in North American battery demand. IRA production tax credits are pulling cell manufacturing investment toward Michigan, Ohio, and Tennessee to serve Detroit OEM supply chains.
- Industrial:Forklift fleets, material handling equipment, and stationary backup systems create steady replacement demand. California warehouse operators are consolidating procurement through direct cell supplier relationships rather than equipment OEM intermediaries.
- Renewable Energy:Solar-plus-storage and standalone grid batteries require four-hour duration systems for renewable firming. Texas ERCOT market participants and California IOU procurement programs are accelerating utility-scale installations.
By revenue concentration, Automotive leads. By contract velocity, Renewable Energy is gaining share fastest.
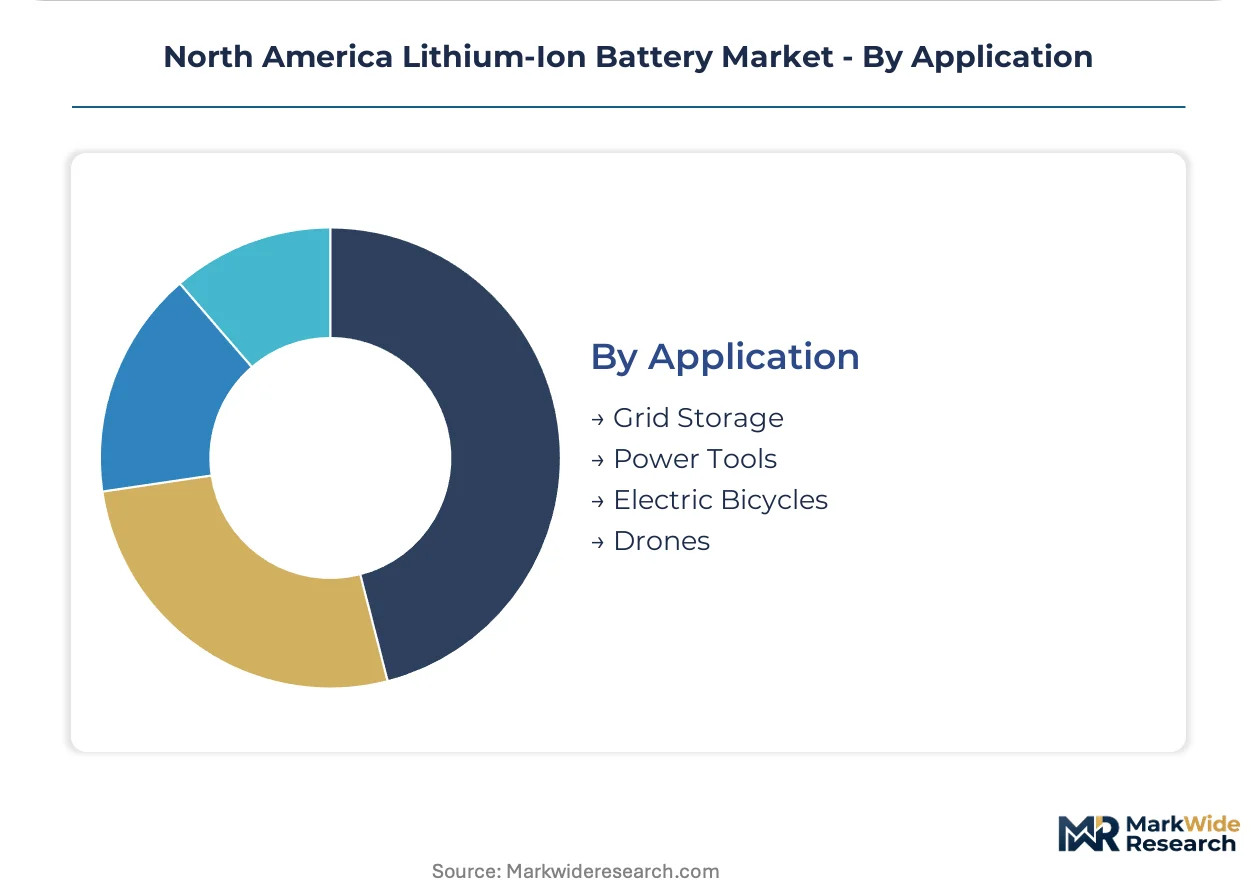
Application:
Maturity stages differentiate these use cases, with power tools representing established replacement markets while grid storage and drone applications exhibit steepest expansion trajectories.
- Grid Storage:Utility-scale and commercial battery installations provide frequency regulation, peak shaving, and renewable firming. Texas and California interconnection queues are backing up with multi-gigawatt storage proposals awaiting transmission study completion.
- Power Tools:Cordless construction and manufacturing equipment relies on cylindrical cell packs through established distributor channels. The Home Depot and Lowe's distribution networks handle substantial volumes of replacement battery sales.
- Electric Bicycles:Aftermarket conversion kits and OEM-integrated systems serve urban mobility and recreational markets. New York City delivery fleet electrification is creating concentrated demand for high-cycle-life battery packs.
- Drones:Commercial inspection, agricultural spraying, and defense applications require high-discharge pouch and cylindrical cells. FAA Part 107 certification expansion is enabling beyond-visual-line-of-sight operations that extend flight duration requirements.
By installed base, Power Tools leads. By expansion trajectory, Grid Storage is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian lithium hydroxide flows to U.S. gigafactories under USMCA rules of origin, while Mexican cathode precursor plants supply Nevada and Texas cell lines. This trilateral trade corridor concentrates investment along the Great Lakes and border manufacturing zones.
United States
Michigan and Ohio anchor Detroit OEM procurement with dedicated cell plants scaling NMC output for light-duty electrification. EPA tailpipe regulations through 2032 mandate fleet-average carbon intensity reductions that expand battery pack size requirements. Tesla's Nevada gigafactory supplies cylindrical cells for automotive and energy storage applications.
Canada
Quebec and Ontario hard-rock lithium mines feed U.S. hydroxide conversion plants under IRA critical mineral sourcing rules. Natural Resources Canada funding accelerates spodumene concentrate capacity to reduce Australian import dependence. Vancouver and Toronto host venture capital flows for battery material startups.
Mexico
Sonora lithium clay deposits attract hydroxide conversion investments to satisfy USMCA domestic content thresholds. Baja California cathode precursor plants position to serve California and Texas gigafactory demand. Mexican manufacturing wages compress electrode coating costs versus U.S. equivalents.
North America Lithium-Ion Battery Market Competitive Environment
Listed leaders compete with private specialists across capital access and technology licensing dimensions. The market structure concentrates around vertically integrated automotive OEMs and dedicated cell manufacturers with tier-one supplier relationships. Three archetypes dominate: captive producers serving single OEM demand, independent suppliers multi-sourcing to Detroit and European automakers, and commodity specialists in LFP chemistry for grid storage. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with joint-venture structures proliferating to share capital burden.
Within the captive production tier, Tesla exemplifies vertical integration from cell to vehicle. Panasonic Corporation and LG Energy Solution occupy independent supplier positions, multi-sourcing cylindrical and pouch formats respectively. These three anchors demonstrate how scale and OEM relationship depth separate sustainable market presence from marginal competitors.
| Leading Market Players |
|---|
| Tesla |
| Panasonic Corporation |
| LG Energy Solution |
| Samsung SDI |
| Contemporary Amperex Technology (CATL) |
| BYD |
| SK On |
| Northvolt |
| Duracell Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Detroit automakers and Michigan cell plants lock in cathode supply access while establishing price visibility across volatile lithium hydroxide markets. These agreements transfer volume risk from manufacturers to OEM procurement desks, compressing spot-market liquidity for automotive-grade cells.
Pricing Analysis
Current-generation NMC cells command premium positioning against prior-generation LMO alternatives and pre-commercial solid-state prototypes. Three-tier pricing structure across premium high-nickel automotive, standard LFP grid storage, and economy portable electronics levels reflects cathode metal intensity and certification grade differentiation. Pricing pressure stems from IRA domestic content bonuses that subsidize U.S. manufacturing but expose non-compliant imports to margin compression. Renewable energy developers exhibit highest price sensitivity due to project finance constraints, while defense contractors absorb premium tiers for FAA-certified aerospace cells.
Supply Chain Analysis
Strategic stockpile preferences dominate cathode precursor procurement as manufacturers buffer against Australian spodumene concentrate volatility and Chinese graphite processing bottlenecks. Raw material flows draw from Chilean brine operations, Canadian hard-rock mines, and Chinese synthetic anode facilities. Single-source vulnerability concentrates in lithium hexafluorophosphate electrolyte salt, where North American purification capacity remains structurally limited. Distribution runs through dedicated OEM supply agreements for automotive volumes and EPC contractor channels for utility-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation is shifting buyer power toward direct cell manufacturer relationships, bypassing traditional automotive tier-one intermediaries. This disintermediation fragments legacy supply chain margin pools and rewards vertically integrated cell-to-pack producers.
For Market Incumbents: Secure cathode chemistry patent positions against LFP displacement in commercial vehicle segments. Lock in Quebec and Ontario lithium hydroxide offtake under USMCA rules to defend IRA tax credit eligibility. Add cell formation capacity in Tennessee and Ohio to eliminate the electrochemical aging bottleneck constraining output velocity regardless of electrode coating investments. For New Entrants and Emerging Players: Lead with second-life battery aggregation platforms targeting California commercial and industrial peak-shaving applications. Mexican cathode precursor plants in Sonora offer the most penetrable geography for USMCA-compliant supply chain insertion. Pursue direct relationships with Texas ERCOT market participants for grid storage procurement bypassing established EPC intermediaries. For Investors and Strategic Acquirers: Solid-state electrolyte specialists with Department of Energy loan guarantee backing represent the priority acquisition archetype for pre-commercial manufacturing scale. Long-term viability hinges on sulfide-based electrolyte pilot line execution and aviation certification timelines. Watch FAA Part 33 electric propulsion certification progress as the inflection signal for lithium metal anode commercial readiness.| Strategic Initiative | Industry Significance |
|---|---|
| IRA-Compliant Supply Chain Reconfiguration | Reshapes cathode precursor flows toward Mexican conversion plants and Canadian hard-rock mines. |
| LFP Capacity Expansion | Captures Texas and California utility-scale procurement displacing nickel-cobalt alternatives. |
| Second-Life Battery Aggregation Platform | Creates distributed storage resource from retired Detroit OEM electric vehicle packs. |
| Solid-State Pilot Line Investment | Attracts DOE loan guarantees for sulfide-based electrolyte pre-commercial production. |
| Direct Fleet Operator Relationships | Bypasses tier-one suppliers for California and New York commercial vehicle electrification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with OEM procurement directors, cell plant operations managers, EPC contractor project developers, and utility storage planning officers. Secondary validation drew from EPA tailpipe regulation filings, FERC interconnection queue data, IRA critical mineral guidance documents, and USMCA rules of origin determinations. Bottom-up cell production capacity tallies triangulated against top-down automotive electrification mandates.
Across the analysis window, volume and value outputs reflect segmentation modeling by cathode chemistry, end-user contract structure, and regional production cluster. CAGRs were derived from production capacity buildout schedules and OEM offtake agreement volumes. Forecast inputs incorporated NHTSA safety standard evolution and state-level zero-emission mandate acceleration.
The analysis sits within stated boundaries; outcomes outside sustained IRA tax credit continuity or USMCA trade corridor stability would require recalibration. Forecasts reflect documented assumptions regarding lithium hydroxide conversion capacity scaling and cathode precursor plant commissioning timelines. Supply chain disruption from UN 38.3 certification backlogs or spodumene concentrate export restrictions represents material revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market