
 Automotive Pressure Plate Market | 2026-2036
Automotive Pressure Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pressure Plate Market Outlook
The automotive pressure plate market is recalibrating around a widening performance gap between premium diaphragm-type assemblies and commodity single-plate designs for emerging-market light commercial vehicles. Raicam Clutch leverages its European manufacturing base to sustain high-margin supply contracts with premium passenger car OEMs. BorgWarner anchors its position through backward integration into friction material compounding, while Valeo competes aggressively on modular clutch-kit bundling across multiple vehicle platforms.
An automotive pressure plate is a spring-loaded friction device, typically fabricated from heat-treated steel or aluminum castings with a friction surface diameter between 180 mm and 430 mm, that engages and disengages engine torque transmission to the gearbox through axial clamping force against the clutch disc. Its primary industrial purpose is to modulate power flow in manual and automated manual transmissions across on-highway and off-highway vehicles. Diaphragm-type products now dominate OEM fitment for passenger vehicles due to their self-adjusting clamp load and compact packaging, while multi-plate configurations command the fastest growth trajectory in high-torque commercial and off-road applications where heat dissipation requirements are severe. Aftermarket providers represent a concentrated margin pool for steel-construction replacements, particularly in regions with aging vehicle parc and limited dealer network penetration.
NHTSA brake and transmission safety standards, EPA fuel economy regulations, and Euro 7 emissions frameworks collectively shape product specifications by mandating reduced driveline mass and tighter particulate thresholds that pressure plate designs must accommodate through material substitution. China's MIIT enforces GB standards on clutch assembly durability that directly gate market access for imported components. Stakeholders must monitor how automated manual transmission penetration and electrification timelines alter replacement-cycle economics for friction-based clutch systems.
Market Dynamics
Automated manual transmission penetration and electrification timelines are compressing replacement-cycle economics for friction-based clutch systems, forcing suppliers to recalibrate portfolio exposure between ICE service parts and emerging e-axle thermal management components.
Growth Catalysts
- Euro 7 particulate thresholds:OEMs in Germany and Italy are sourcing lighter aluminum-cast pressure plates to meet mass reduction mandates for passenger car drivelines.
- India's commercial vehicle parc:Fleet operators in Maharashtra and Gujarat are driving aftermarket volume for heavy-duty diaphragm-type replacements as average vehicle age exceeds 12 years.
- Carbon-ceramic friction compounding:Advanced material formulations are extending service intervals in high-torque applications across Brazilian mining and agricultural equipment sectors.
Market Restraints
- Heat-treated steel input volatility:Scrap metal price fluctuations in China's Hebei province are compressing margin structures for cast-iron pressure plate manufacturers.
- Single-supplier concentration:Diaphragm spring forming capacity clusters among three European tool-and-die houses, creating procurement bottlenecks for tier-two assemblers.
- Electrification substitution:Battery electric commercial vehicle platforms are eliminating mechanical clutch assemblies entirely from powertrain architectures.
Strategic Opportunities
- Thailand's pickup truck hub:Japanese OEM transplant factories around Bangkok present captive supply opportunities for modular clutch-kit bundling.
- EPA Phase 2 vocational vehicle standards:Stricter fuel economy rules are incentivizing multi-plate configurations for Class 8 trucks operating in stop-and-go urban delivery cycles.
- Digital aftermarket channels:Independent repair networks in Mexico are adopting platform-based procurement for standardized replacement pressure plates, bypassing traditional distributor markups.
Industry Challenges
- Heat-treatment process certification:NADCAP accreditation timelines for new steel suppliers stretch 18-24 months, delaying qualification for aerospace-adjacent friction material partners.
- Legacy AMT integration complexity:Automated manual transmission control software requires recalibrated clamp load profiles that pressure plate suppliers must validate against proprietary OEM actuator specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pressure Plate Market |
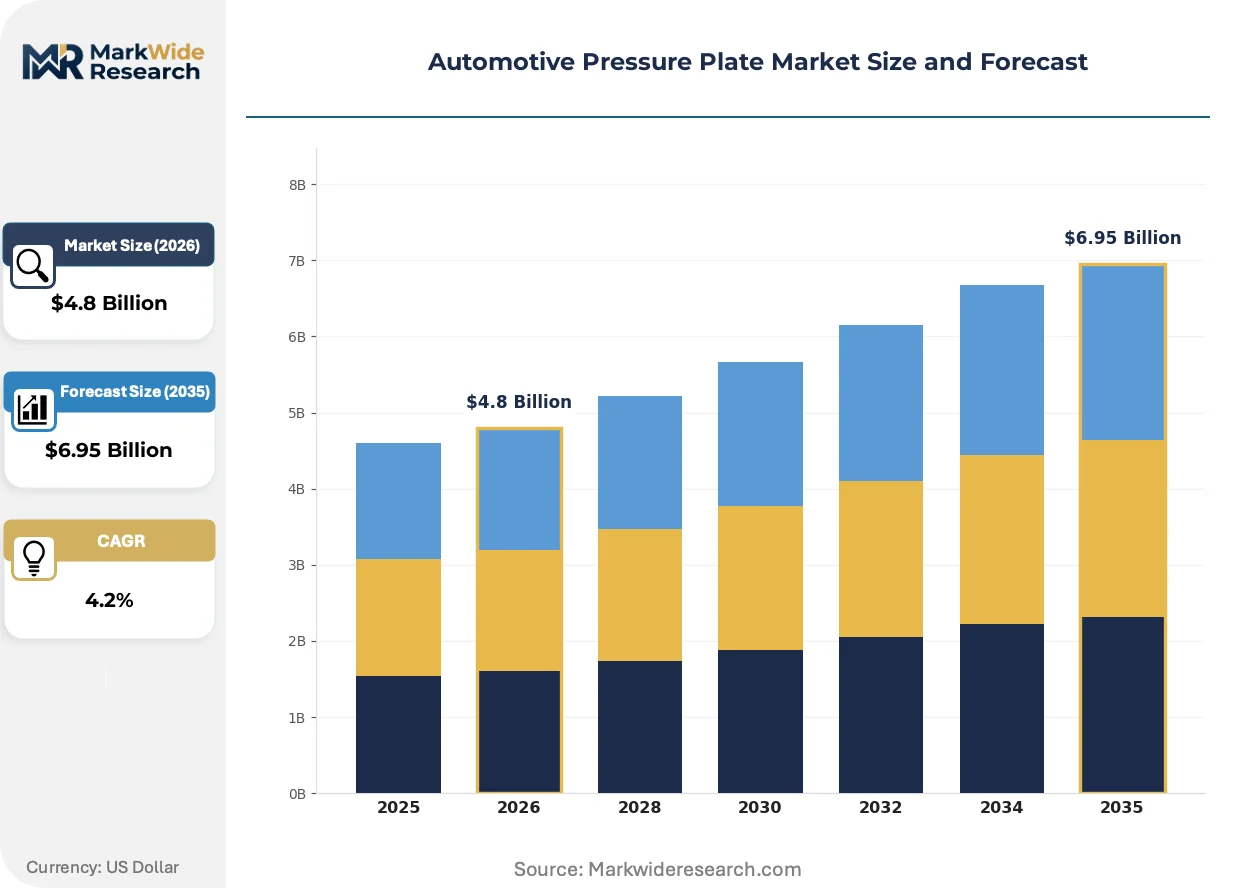
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Plate, Multi Plate, Diaphragm Type, Pull Type Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Off-Road Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Distributors Material: Aluminum, Steel, Composite, Carbon Fiber |
| Companies Covered | Raicam Clutch, Aisin Seiki, MACAS Automotive, ZF Friedrichshafen, Valeo, Setco Automotive, Hebei Tengda Auto Parts, BorgWarner, ANAND Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pressure Plate Market Strategic Shifts
Material science advances and regulatory mass mandates are converging to reshape pressure plate architecture, with friction surface engineering and thermal management emerging as the primary vectors of product differentiation.
Carbon-fiber-reinforced ceramic matrix composites are unifying heat dissipation and weight reduction in a single friction surface layer. High-performance passenger car OEMs in southern Germany are specifying these materials for dual-clutch transmission variants. This convergence is unifying what were previously separate thermal and mechanical engineering disciplines within tier-one supplier R&D organizations.
China's MIIT GB standards on clutch assembly durability are mandating 1.2 million cycle minimums for commercial vehicle applications. Domestic assemblers around Baoding are redesigning diaphragm spring geometries to accommodate these thresholds. The regulation is most acutely affecting medium-duty truck platforms where local suppliers previously optimized for lower cycle counts.
Fleet maintenance departments are consolidating brake and transmission service intervals to minimize vehicle downtime. Large logistics operators in São Paulo's urban distribution corridors are negotiating bundled clutch replacement contracts with independent service chains. This pattern is most visible in Brazil's e-commerce delivery sector where vehicle utilization rates exceed 18 hours daily.
Automotive Pressure Plate Market Segmentation
Pressure plate procurement decisions hinge on divergent certification burdens across product architectures and end-use channels. Segment boundaries map directly to which stakeholders bear NADCAP heat-treatment accreditation, MIIT GB cycle-testing, or OEM proprietary validation protocols.
Product Type:
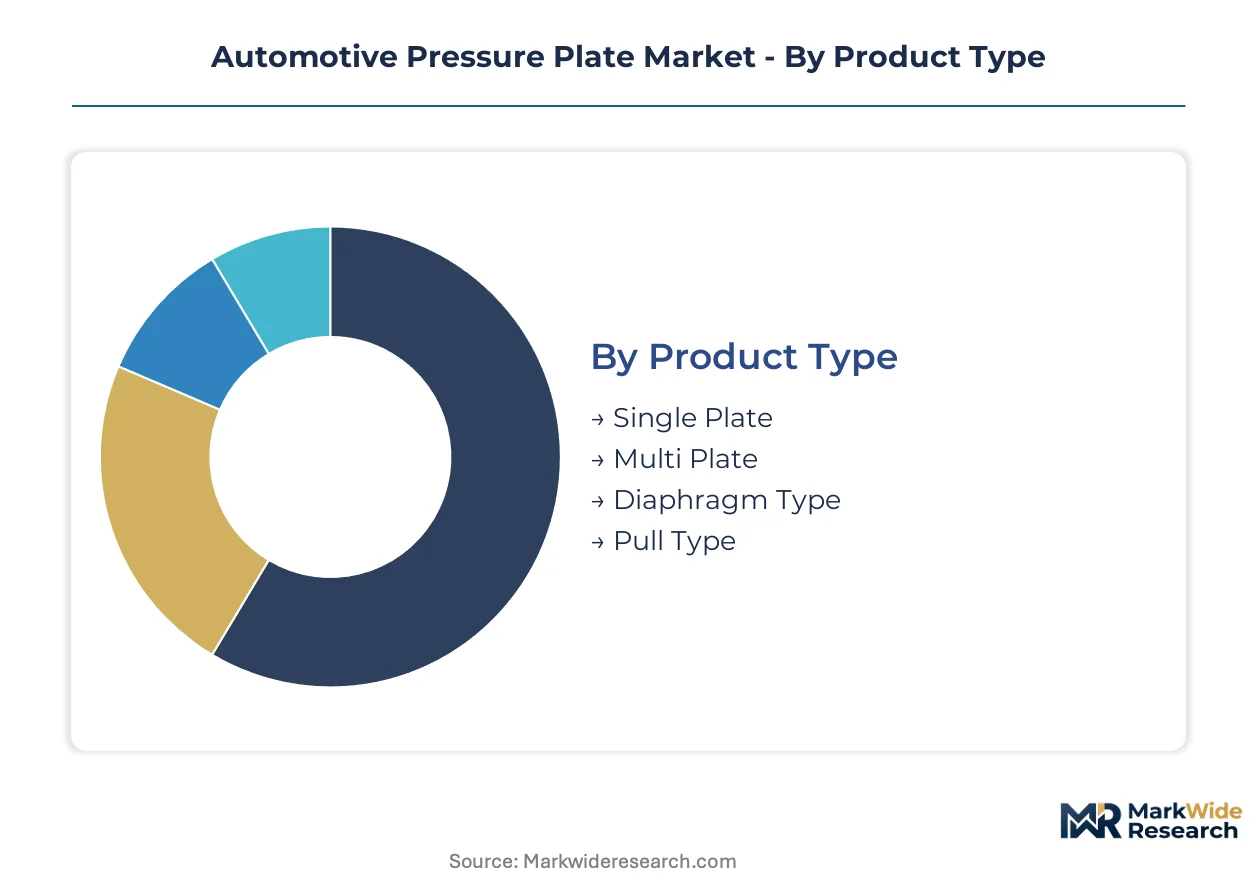
Diaphragm-type and multi-plate configurations carry the heaviest certification loads, with NADCAP heat-treatment and OEM-specific clamp-load validation creating multi-year qualification timelines for new entrants.
- Diaphragm Type:Self-adjusting spring-loaded designs fabricated from heat-treated steel with segmented friction surfaces. German and Italian passenger car OEMs specify these for dual-clutch transmissions under Euro 7 mass reduction mandates, requiring aluminum-cast variants to undergo proprietary thermal cycling validation.
- Multi Plate:Stacked friction disc arrangements enabling superior heat dissipation through expanded surface area. Brazilian mining equipment operators and Class 8 vocational truck fleets in the US specify these for stop-and-go cycles under EPA Phase 2 standards, with carbon-ceramic compounding extending service intervals.
- Single Plate:Concentric friction surface designs dominating emerging-market light commercial vehicle fitment.
- Pull Type:Actuation-mechanism variants optimized for compact packaging in front-wheel-drive architectures.
Leading the category by volume: Diaphragm Type. Growing fastest: Multi Plate.
Application:
Cost tiers separate passenger vehicle precision engineering from commercial vehicle durability economics, with off-road applications commanding premium material specifications.
- Commercial Vehicles:Heavy-duty diaphragm-type assemblies for medium and heavy trucks face China's MIIT-mandated 1.2 million cycle minimums. Fleet operators in Maharashtra and Gujarat drive aftermarket replacement volume as vehicle age exceeds 12 years, with bundled service contracts consolidating brake and transmission intervals.
- Passenger Vehicles:Aluminum-cast pressure plates with carbon-fiber-reinforced ceramic friction surfaces specified by southern German OEMs for dual-clutch variants. Mass reduction targets under Euro 7 push material substitution toward aerospace-adjacent suppliers requiring 18-24 month NADCAP accreditation.
- Motorcycles:Compact single-plate designs optimized for wet-clutch applications in high-revving powertrains.
- Off-Road Vehicles:Severe-duty multi-plate configurations for agricultural and construction equipment operating in abrasive environments.
Highest margin concentration: Passenger Vehicles. Steepest expansion trajectory: Commercial Vehicles in aftermarket channels.
End User:
Customer type determines whether procurement flows through captive OEM supply agreements or fragmented independent service networks.
- OEMs:Direct supply relationships with tier-one integrators specifying modular clutch-kit bundling across multiple vehicle platforms. Japanese transplant factories around Bangkok present captive opportunities for standardized kit configurations.
- Aftermarket Providers:Independent repair networks in Mexico adopting platform-based procurement, bypassing traditional distributor markups for steel-construction replacements.
- Vehicle Assemblers:Domestic medium-duty truck builders around Baoding and Chongqing sourcing diaphragm-type plates under GB durability standards.
- Distributors:Traditional wholesale channels serving aging vehicle parc in regions with limited dealer network penetration.
Dominant procurement volume: OEMs. Fastest channel shift: Aftermarket Providers via digital platforms.
Material:
Supply concentration for specialized inputs creates procurement bottlenecks, with carbon fiber and advanced composites requiring aerospace-adjacent supplier relationships.
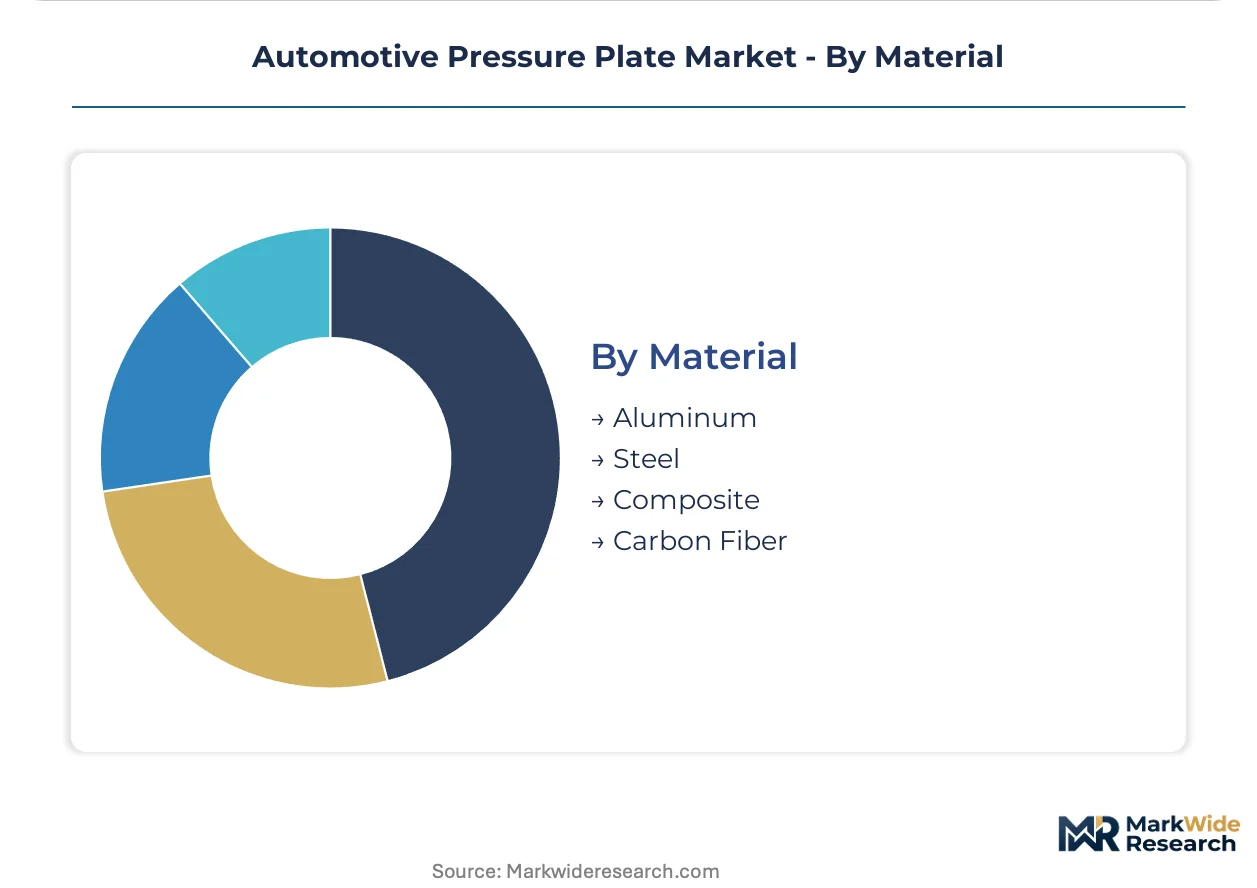
- Steel:Heat-treated carbon and alloy grades dominating diaphragm spring and pressure ring fabrication. Scrap metal price volatility in China's Hebei province compresses margin structures for cast-iron manufacturers.
- Aluminum:Cast and forged variants specified for mass-critical passenger car applications under Euro 7 mandates, with foundry capacity clustering in European automotive supply basins.
- Composite:Glass-fiber and aramid-reinforced formulations for cost-optimized emerging-market applications.
- Carbon Fiber:Ceramic matrix composites unifying heat dissipation and weight reduction in unified friction surface layers for high-performance dual-clutch variants.
Widest application base: Steel. Gaining share fastest: Carbon Fiber in premium passenger car segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baoding and Chongqing anchor commercial vehicle pressure plate procurement in China's medium-duty truck corridor, while India's Maharashtra-Gujarat belt drives aftermarket replacement volume for aging heavy-duty fleets.
China
Domestic assemblers around Baoding source diaphragm-type plates under MIIT's GB durability standards mandating 1.2 million cycle minimums. Local manufacturers redesign spring geometries to meet these thresholds. Chongqing's commercial vehicle hub concentrates procurement for medium-duty platforms serving domestic logistics networks.
India
Fleet operators in Maharashtra and Gujarat extend replacement cycles for heavy-duty clutch assemblies as average vehicle age exceeds 12 years. BIS certification requirements gate imported component access. The Pune-Nashik corridor hosts independent service chains negotiating bundled brake-transmission maintenance contracts.
Germany
Southern German OEMs specify aluminum-cast pressure plates with carbon-fiber-reinforced ceramic friction surfaces for dual-clutch variants. KBA type-approval processes enforce Euro 7 mass reduction mandates. Stuttgart's automotive supply basin concentrates foundry capacity for aerospace-adjacent material qualification.
Brazil
Mining equipment operators in Minas Gerais specify carbon-ceramic friction compounding for extended service intervals in high-torque applications. ANVISA environmental compliance overlaps with EPA Phase 2 alignment for export-oriented manufacturers. São Paulo's urban distribution corridors consolidate fleet maintenance through independent service networks.
United States
Class 8 vocational truck fleets adopt multi-plate configurations under EPA Phase 2 fuel economy standards for stop-and-go urban delivery. NHTSA brake-transmission safety standards shape clamp-load validation protocols. Michigan's automotive supply corridor anchors tier-one integrator relationships with modular clutch-kit specifications.
Automotive Pressure Plate Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification and thermal cycling validation burdens. The vendor base stratifies into three tiers: European specialists with NADCAP-accredited heat-treatment capabilities, Asian scale fabricators serving domestic OEM captive demand, and regional aftermarket assemblers sourcing standardized steel constructions. Strategic differentiation flows through backward integration into friction material compounding and modular clutch-kit bundling across multiple vehicle platforms.
Within the European specialist tier, Raicam Clutch and ZF Friedrichshafen occupy positions defined by proximity to southern German OEM specification centers. BorgWarner exemplifies the integrated material-compounding archetype among US-headquartered tier-one suppliers. Valeo represents the modular-kit bundling strategy across multiple platform relationships. Aisin Seiki anchors Japanese transplant supply relationships in Thailand's pickup truck manufacturing corridor.
| Leading Market Players |
|---|
| Raicam Clutch |
| Aisin Seiki |
| MACAS Automotive |
| ZF Friedrichshafen |
| Valeo |
| Setco Automotive |
| Hebei Tengda Auto Parts |
| BorgWarner |
| ANAND Group |
| Others |
Value Chain & Pricing Dynamics
Carbon-ceramic friction compounding adoption simultaneously compresses per-unit manufacturing economics and concentrates procurement leverage among aerospace-adjacent material suppliers with NADCAP accreditation. This dual effect reshapes margin structures across diaphragm-type and multi-plate product tiers as OEMs prioritize thermal performance over commodity steel constructions.
Pricing Analysis
Service-interval extension anchors value-based pricing for carbon-ceramic formulations in Brazilian mining and US Class 8 vocational fleets. Three-tier pricing structure across premium certified, standard OEM-specified, and economy aftermarket levels differentiates by NADCAP heat-treatment tier and MIIT GB cycle certification. Cost compression in steel-construction commodity tiers intensifies due to scrap metal volatility in China's Hebei province. Fleet operators in India's Maharashtra-Gujarat corridor exhibit highest price sensitivity, while southern German OEMs purchasing aluminum-cast dual-clutch variants show lowest sensitivity to material premiums.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Bangkok, and Detroit anchor hub-and-spoke patterns for modular clutch-kit bundling to OEM assembly plants. Manufacturing concentration clusters in Germany, China, and Thailand, with foundry capacity for aluminum-cast variants tethered to European automotive supply basins. Heat-treated steel, carbon-fiber ceramic matrices, and diaphragm spring forgings constitute critical input dependencies. Single-source vulnerability pervades diaphragm spring forming capacity concentrated among three European tool-and-die houses. Distribution runs through captive OEM supply agreements for tier-one integrators and platform-based digital channels for Mexican aftermarket providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over friction material compounding and heat-treatment accreditation determines margin capture. Players are pursuing upstream captive supply of carbon-ceramic inputs to escape procurement bottlenecks.
For Market Incumbents: Acquire NADCAP-accredited heat-treatment facilities to secure qualification timelines for aerospace-adjacent friction material partnerships. Consolidate diaphragm spring forming capacity through selective tool-and-die house acquisitions, countering single-supplier concentration risk. Electrification substitution threatens long-term clutch assembly demand, necessitating parallel investment in e-axle thermal management component portfolios. For New Entrants and Emerging Players: Launch via platform-based digital procurement targeting Mexico's independent repair networks, bypassing traditional distributor markups. White-space concentrates in carbon-ceramic aftermarket formulations for Brazilian mining equipment and India's aging commercial vehicle parc. Go-to-market leverage rests on modular clutch-kit bundling contracts with Japanese OEM transplant factories in Thailand's pickup truck corridor. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to tier-one automotive suppliers seeking backward integration into friction material compounding. Long-term viability across the analysis window hinges on portfolio exposure split between ICE service parts and electrification-adjacent thermal management. Acquisition target archetype: European specialists with NADCAP accreditation and existing southern German OEM relationships. Monitor EPA Phase 2 vocational vehicle standard enforcement as inflection indicator for multi-plate configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Friction Material Compounding | BorgWarner's captive supply of carbon-ceramic formulations insulates margin structures from aerospace-adjacent supplier bottlenecks. |
| Modular Clutch-Kit Bundling Expansion | Valeo's platform-spanning kit configurations capture economies of scope across multiple OEM vehicle architectures. |
| NADCAP Heat-Treatment Accreditation Investment | Raicam Clutch's certified European manufacturing base sustains premium supply contracts with KBA type-approval requirements. |
| Digital Aftermarket Platform Development | Independent Mexican repair networks adopting platform procurement bypass traditional distributor markups for steel-construction replacements. |
| Multi-Plate Configuration Capacity Addition | EPA Phase 2 vocational standards incentivize heat-dissipating stacked disc arrangements for Class 8 stop-and-go urban delivery cycles. |
Study Parameters
Independent corroboration across OEM platform engineering directors, tier-one supplier procurement leads, aftermarket distributor operations heads, and heat-treatment facility quality managers underwrites the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and NADCAP accreditation records. Bottom-up triangulation of segment-level demand patterns with top-down macroeconomic drivers ensures internal consistency across volume and value estimates.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions span product architecture, vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derive from fitted growth curves calibrated to historical replacement-cycle economics and regulatory phase-in schedules. Forecast inputs incorporate automated manual transmission penetration trajectories and electrification substitution timelines for friction-based clutch systems.
Electrification acceleration, scrap metal price volatility, and NADCAP accreditation delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding OEM platform standardization decisions and fleet operator maintenance interval consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Defroster Market