
 Global Automotive Gears Market | 2026-2036
Global Automotive Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Gears Market Intelligence
Consolidation among global vehicle platform purchasers is realigning the supply base for automotive gears, favoring suppliers with scale and broad technological capabilities. ZF Friedrichshafen AG leverages its extensive manufacturing footprint to serve multiple OEMs across continents. JTEKT Corporation specializes in high-precision gearing systems for key Japanese automotive clients. In contrast, American Axle & Manufacturing Holding, Inc. anchors its position in the North American commercial truck and SUV driveline segment.
Automotive gears are precision-engineered mechanical components that transmit torque and power within a vehicle's transmission, differential, and steering systems. These components are designed with specific tooth profiles, such as involute curves, to ensure smooth, low-noise operation under high load. Helical gears lead the product type category, valued for their quiet operation in modern passenger vehicle transmissions. While the passenger vehicle application constitutes the largest market by volume, gears for specialized off-road vehicles often command higher per-unit margins.
Regulatory frameworks, including US EPA fuel economy mandates and China's GB standards for vehicle components, compel innovation in lightweight materials and high-efficiency gear designs. European Union directives on vehicle lifecycle and material recycling also influence the selection of alloys and polymers used in gear manufacturing. Suppliers must now decide whether to invest in specialized production for electric vehicle transmissions or to optimize costs for the enduring internal combustion engine aftermarket.
Market Dynamics
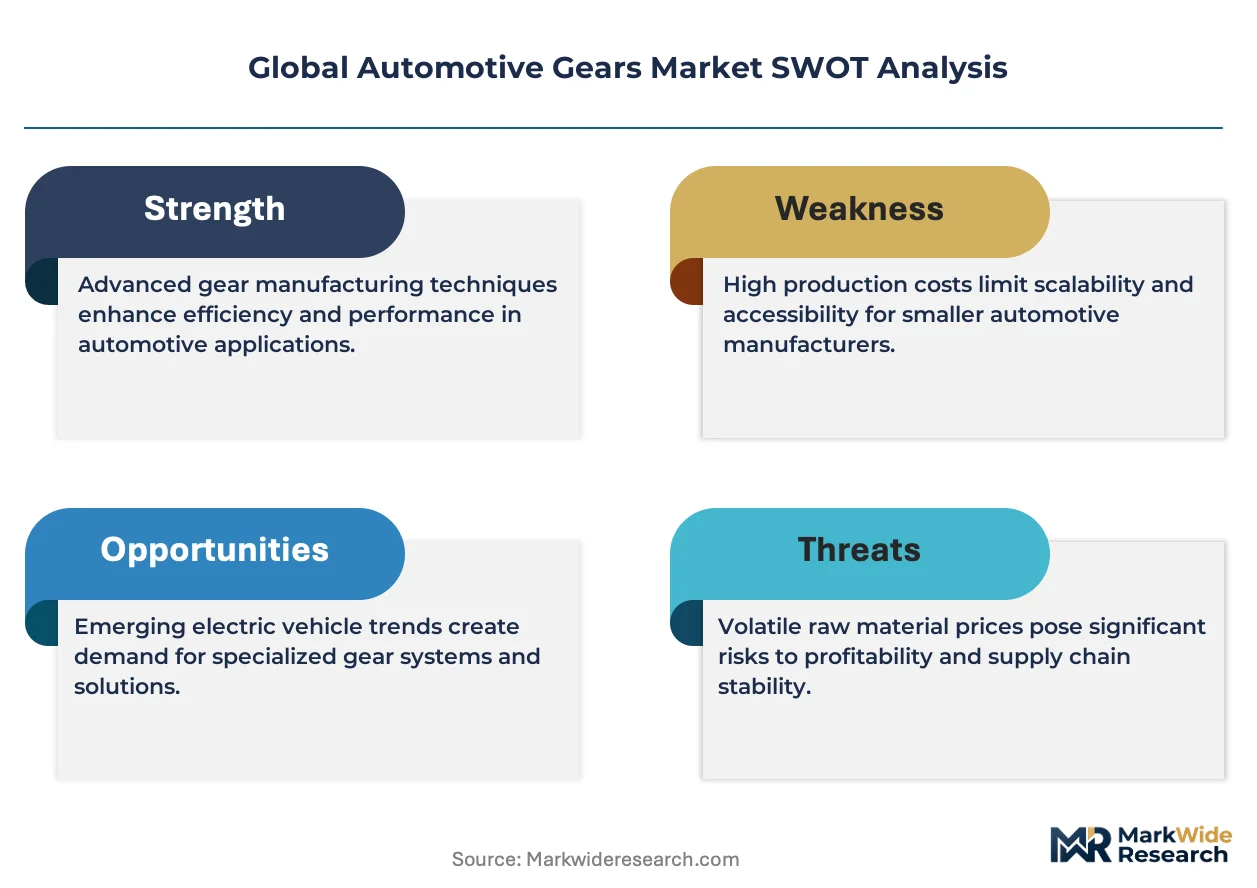
The automotive gears market is defined by the tension between developing specialized gears for high-torque electric vehicle powertrains and simultaneously optimizing cost and weight for internal combustion engine platforms to meet efficiency mandates from regulators.
Growth Catalysts
- EV Multi-Speed Transmissions:The development of two-speed or three-speed transmissions for electric vehicles to enhance range and performance creates demand for new, complex planetary gear sets not required in single-speed EVs.
- Chinese NEV Incentives:Government support for New Energy Vehicles in China directly stimulates domestic production and consumer adoption of EVs, increasing the regional volume demand for specialized electric powertrain gears.
- EU Green Deal Regulations:Stringent CO2 emission targets under the European Green Deal compel automakers to adopt every available efficiency technology, including lower-friction gear coatings and lightweight gear materials to reduce parasitic driveline losses.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of high-grade steel alloys, specialty polymers, and rare earth elements for magnets in e-axles create margin pressure and sourcing instability for gear manufacturers globally.
- NVH Performance Demands:The quiet operation of electric motors amplifies gear whine, imposing extreme Noise, Vibration, and Harshness requirements that necessitate costly precision grinding, advanced tooth profile modifications, and extensive testing.
- High Capital Expenditure:The significant investment required for advanced CNC gear hobbing, shaping, and grinding machines, along with metrology equipment, acts as a substantial barrier to entry and expansion for smaller suppliers.
Strategic Opportunities
- Gears for Urban Air Mobility:Emerging UAM and electric vertical take-off and landing (eVTOL) aircraft require extremely high power-density, lightweight, and reliable gearboxes, opening a new, high-margin niche for specialist gear manufacturers.
- Advanced Composite Gears:The maturation of carbon fiber-reinforced polymers and PEEK composites presents an opportunity to replace metal gears in lower-torque applications like steering systems and actuators, offering significant weight savings. *Aftermarket for Automated Manual Transmissions: In markets like India and Brazil, the growing parc of vehicles with automated manual transmissions (AMTs) creates a future service and replacement opportunity for clutch and gear actuator components.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of skilled gear design engineers, metallurgists, and CNC machine operators capable of working with the tight tolerances required for modern transmissions hampers production and innovation.
- EV Transmission Standardization:The lack of common standards for electric motor interfaces and e-axle form factors forces gear suppliers to create bespoke designs for each OEM, increasing engineering costs and limiting economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Gears Market |
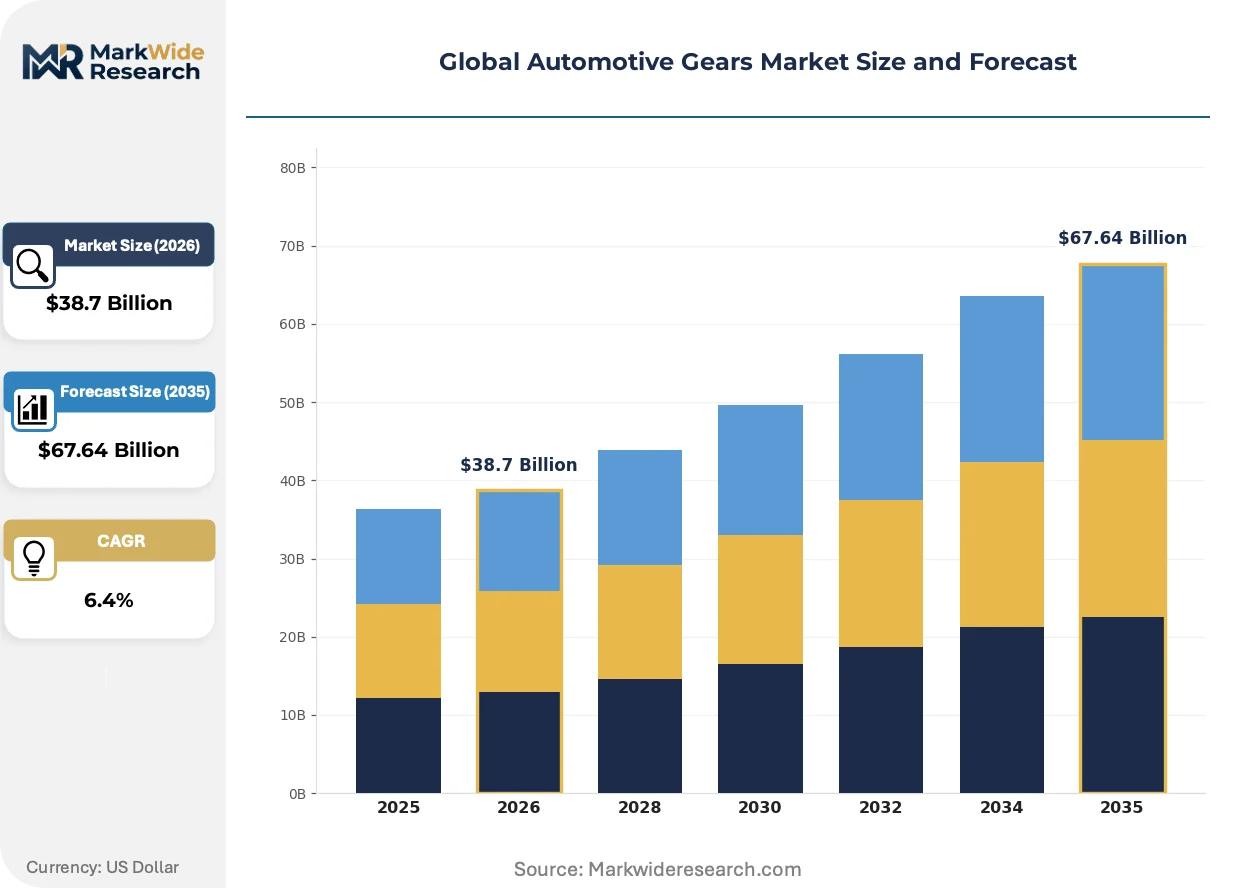
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spur Gears, Helical Gears, Bevel Gears, Worm Gears, Hypoid Gears Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-Road Vehicles, Construction Equipment Manufacturing Stage: Forged Gears, Cast Gears, Machined Gears, Sintered Gears, Cut Gears End User: OEMs, Aftermarket Suppliers, Tier-1 Vendors, Vehicle Assemblers |
| Companies Covered | American Axle & Manufacturing Holding, Inc., GKN PLC, Bharat Gears Ltd., JTEKT Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Showa Corporation, AmTech International, IMS Gear SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Gears Market Strategic Shifts & Innovations
Material science advancements are intersecting with digital twin and simulation technologies to accelerate the development of next-generation automotive gears. This combination allows for rapid virtual prototyping and optimization for both electric and combustion powertrain applications, reducing physical testing cycles.
Additive manufacturing, specifically selective laser melting of specialty steel alloys, produces complex and lightweight gear geometries that are difficult to achieve with traditional hobbing. Aerospace and motorsports are key early adopters, valuing the performance benefits over higher unit costs. This technology is expanding into high-performance passenger vehicle prototypes and specialized aftermarket components, enabling rapid design iteration.
European Union directives on vehicle lifecycle and material recyclability, such as the End-of-Life Vehicles directive, are influencing material selection for gears and related components. The regulations encourage the use of alloys and polymers that are easier to recycle and track, impacting long-term design choices. This affects suppliers by adding material traceability and lifecycle assessment requirements to their development process.
A shift toward platform-based vehicle development by major OEMs is altering purchasing patterns for gears. Instead of sourcing individual components, automakers increasingly procure complete modular driveline systems, including e-axles or hybrid transmission units, from Tier 1 suppliers. This trend is most visible in North America and Europe, favoring large-scale suppliers who can offer fully integrated and validated systems.
Global Automotive Gears Market Segmentation
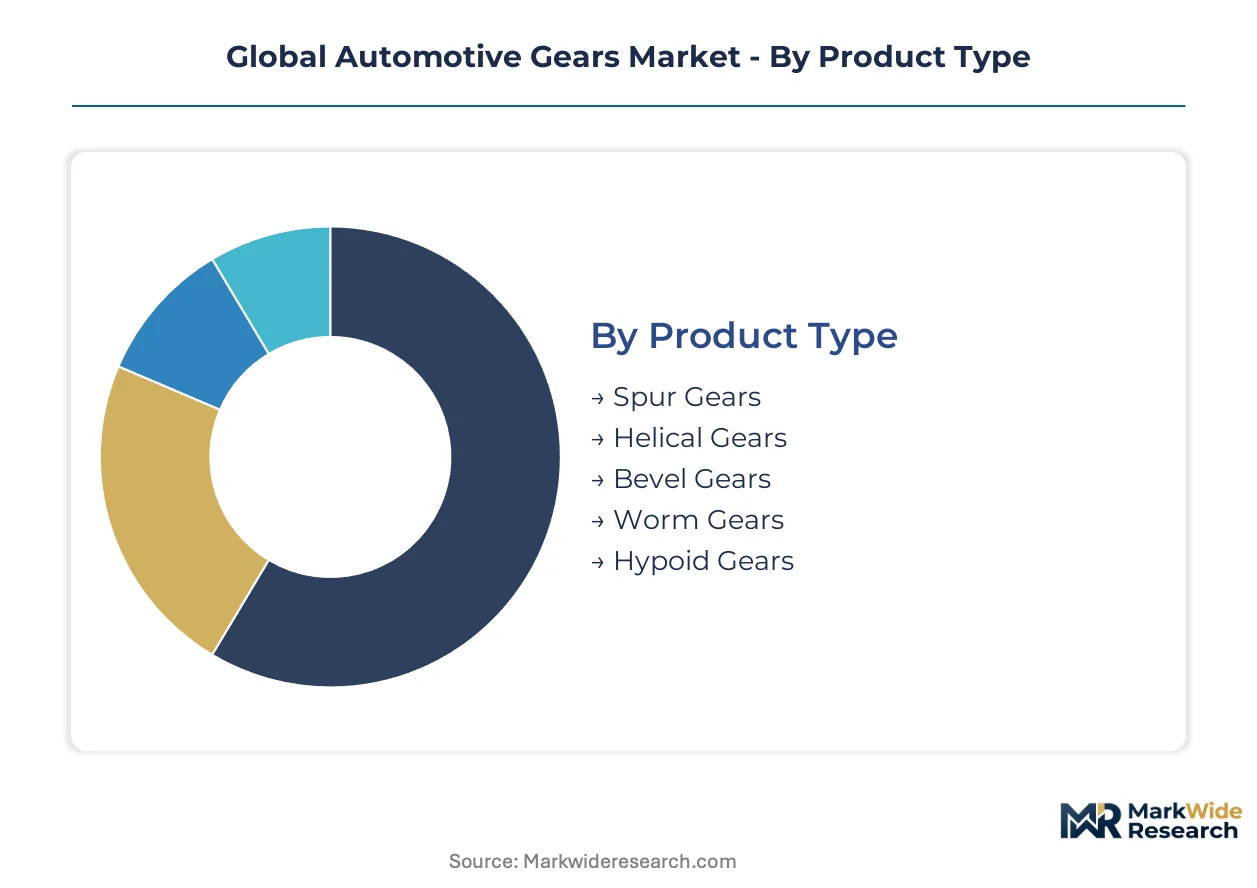
The automotive gears market segmentation provides a granular view of component demand across diverse vehicle types and manufacturing processes. Understanding these distinct segments helps manufacturers align production capabilities with specific market needs. This detailed breakdown reveals where innovation and investment are most critical for future growth.
Product Type:
The product type segment illustrates the spectrum from highly standardized mechanical components to specialized designs requiring significant customization for specific vehicle performance envelopes.
- Helical Gears:These gears feature teeth cut at an angle to the axis of rotation, enabling smoother, quieter operation and higher load-carrying capacity compared to spur gears. Demand is concentrated in modern passenger vehicle transmissions across Europe and Asia, driven by stringent Noise, Vibration, and Harshness (NVH) requirements.
- Spur Gears:Characterized by straight teeth parallel to the axis of rotation, spur gears are the simplest and most common type, offering high efficiency and ease of manufacture. Their widespread use in industrial machinery and simpler automotive applications, particularly in cost-sensitive markets like India, reflects their robust and straightforward design.
- Bevel Gears:These conical-shaped gears transmit power between intersecting shafts, commonly found in differentials and steering systems within commercial trucks.
- Worm Gears:Consisting of a worm (screw) and a worm wheel, these gears provide large speed reductions and high torque multiplication in steering mechanisms and industrial applications.
- Hypoid Gears:Similar to spiral bevel gears but with non-intersecting shafts, hypoid gears are essential for rear-wheel drive vehicle differentials, lowering the drive shaft for improved cabin space.
Leading the category by volume: Helical Gears. Growing fastest: Hypoid Gears, driven by specialized driveline needs in performance vehicles.
Application:
This application segment highlights the diverse volume requirements and performance specifications across various vehicle types, from high-volume passenger cars to specialized heavy-duty machinery.
- Passenger Vehicles:This segment encompasses gears used in transmissions, differentials, and steering systems of cars, SUVs, and light-duty trucks. Demand is substantial in China due to expansive domestic vehicle production and consumer preference for advanced driveline technologies.
- Off-Road Vehicles:Gears for these vehicles are engineered for extreme durability and high torque transfer under harsh conditions, including ATVs, UTVs, and agricultural machinery. Their specialized design and robust material requirements command higher per-unit margins compared to standard automotive gears.
- Commercial Trucks:This category includes heavy-duty gears designed for the demanding transmissions and differentials of large freight vehicles and buses, prioritizing longevity and load capacity.
- Two-Wheelers:Gears in this segment are primarily for motorcycles and scooters, focusing on compact design and efficient power delivery within constrained spaces.
- Construction Equipment:This segment requires exceptionally robust and large gears for excavators, loaders, and bulldozers, built to withstand immense forces and continuous heavy operation.
Passenger Vehicles represent the largest volume segment. Off-Road Vehicles are expanding most quickly due to increasing global infrastructure projects and recreational demand.
Manufacturing Stage:
The manufacturing stage segment reflects varying production complexities and associated cost structures, influencing the final margin profile of different gear types.
- Forged Gears:Produced by plastically deforming metal in its solid state, forged gears offer superior strength, ductility, and fatigue resistance due to optimized grain structure. They are critical for high-stress applications in heavy-duty commercial trucks and performance passenger vehicles where reliability is paramount.
- Machined Gears:These gears are precisely cut from solid stock using processes like hobbing, shaping, and grinding, allowing for intricate tooth profiles and tight tolerances. Their high precision is essential for electric vehicle powertrains to meet stringent Noise, Vibration, and Harshness (NVH) performance demands.
- Cast Gears:Formed by pouring molten metal into a mold, cast gears are cost-effective for large, less precise components found in agricultural machinery and some older vehicle models.
- Sintered Gears:Manufactured from metal powders pressed and heated below their melting point, these gears offer good dimensional accuracy and are suitable for complex, smaller components in actuators and steering systems.
- Cut Gears:This broad category includes gears where teeth are mechanically removed from a blank, often serving as an initial stage before further finishing for various automotive applications.
Forged Gears maintain a significant market share due to their strength. Machined Gears are gaining share fastest, driven by precision requirements in advanced transmissions.
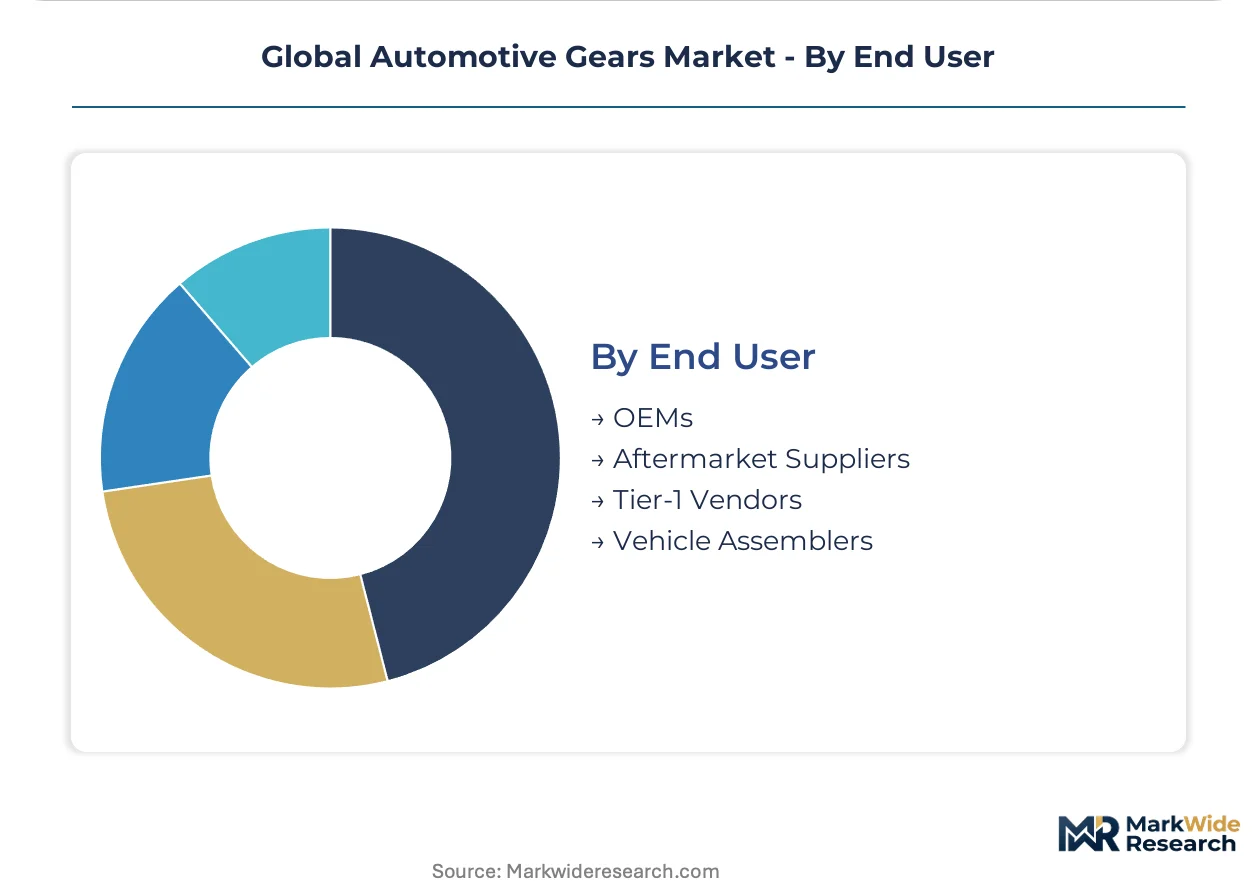
End User:
This end-user segment illustrates how supply concentration shifts between direct vehicle manufacturers and specialized component integrators within the automotive value chain.
- OEMs:Original Equipment Manufacturers directly integrate gears into new vehicle assemblies, including transmissions, differentials, and engine components. Their procurement patterns are increasingly favoring complete modular driveline systems from Tier 1 suppliers in North America and Europe.
- Tier-1 Vendors:These suppliers design and manufacture complex sub-assemblies, such as complete e-axles or hybrid transmission units, which they then supply to OEMs. Their role is expanding as automakers consolidate platforms and outsource integrated system development.
- Aftermarket Suppliers:This segment provides replacement gears and components for vehicle repairs and upgrades, serving independent workshops and service centers globally.
- Vehicle Assemblers:These entities primarily focus on the final assembly of vehicles, often sourcing pre-assembled gear systems or individual gears from various suppliers.
OEMs represent the largest purchasing volume for automotive gears. Tier-1 Vendors show the steepest expansion trajectory as they assume greater system integration responsibilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for automotive gears is evident across key manufacturing hubs globally. China's expansive domestic vehicle production significantly drives regional volume, especially for new energy vehicles. European and North American markets also contribute substantial demand, particularly for advanced driveline technologies.
China
China's robust electric vehicle market generates significant demand for specialized gears. Government incentives for New Energy Vehicles (NEVs) under its dual carbon goals accelerate this trend. The Yangtze River Delta region, with its numerous EV manufacturers, actively integrates advanced e-axle gear systems.
Germany
Germany's established automotive industry drives substantial demand for high-precision gears in luxury and performance vehicles. Stringent EU Green Deal regulations compel innovation in lightweight materials and high-efficiency designs. The Stuttgart automotive cluster actively develops advanced transmissions for both ICE and EV platforms.
United States
The United States market requires durable gears for its large commercial truck and SUV segments. US EPA fuel economy mandates push manufacturers toward more efficient driveline components. Detroit's industrial base focuses on developing robust gear sets for heavy-duty applications.
Japan
Japan's automotive sector demands high-quality, quiet-operation gears for its globally exported passenger vehicles. JIS standards ensure precision manufacturing and reliability across the supply chain. The Nagoya manufacturing cluster specializes in high-precision gearing systems for key Japanese OEMs.
India
India's growing vehicle parc, particularly in the two-wheeler and cost-sensitive passenger car segments, creates consistent gear demand. The PLI scheme for automotive components encourages domestic production and technological upgrades. Chennai's automotive hub sees increasing production of gears for automated manual transmissions.
Global Automotive Gears Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized high-torque electric vehicle applications. The market structure exhibits consolidation among Tier 1 suppliers capable of delivering integrated driveline systems. Strategic archetypes include global scale providers, regional specialists, and niche technology innovators. Many companies engage in M&A activities to expand technological capabilities and geographic reach.
Among global scale providers, ZF Friedrichshafen AG leverages its extensive manufacturing footprint to serve multiple OEMs across continents with broad technological capabilities. JTEKT Corporation exemplifies regional specialization, focusing on high-precision gearing systems tailored for key Japanese automotive clients and their unique performance envelopes. American Axle & Manufacturing Holding, Inc. anchors its position within the North American commercial truck and SUV driveline segment, providing robust solutions for heavy-duty applications. These companies collectively represent the diverse strategic approaches defining the automotive gears market.
| Leading Market Players |
|---|
| American Axle & Manufacturing Holding, Inc. |
| GKN PLC |
| Bharat Gears Ltd. |
| JTEKT Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Showa Corporation |
| AmTech International |
| IMS Gear SE & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Vertical integration into modular driveline systems by Tier-1 vendors anchors their supply position and grants significant pricing power for complex e-axle units. This shift reshapes traditional component procurement.
Pricing Analysis
Volume-driven passenger vehicle gears operate on tighter margins compared to specialized off-road vehicle gears, which command higher per-unit profits. The dominant pricing model is contract-based long-term offtake, with price differentiation driven by customization levels for EV powertrains and specific certification requirements. Pricing pressure stems from raw material price volatility, particularly for high-grade steel alloys. Passenger vehicle OEMs exhibit high price sensitivity, while off-road vehicle manufacturers prioritize durability and performance.
Supply Chain Analysis
Dual-sourcing requirements from major OEMs mitigate risk and ensure supply continuity for critical automotive gears. Geographic supply concentrates in manufacturing hubs like China, Germany, and Japan, drawing from global sources of high-grade steel alloys and specialty polymers. Commodity price volatility for these inputs presents a structural supply chain risk. Distribution runs primarily direct to OEMs and Tier-1 vendors, who then integrate components into larger systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive gears market is navigating a significant technology-transition phase, as specialized gears for high-torque electric vehicle powertrains displace traditional internal combustion engine components. This shift demands new manufacturing capabilities.
For Market Incumbents: Deploy capacity addition in EV gear manufacturing to meet rising demand for multi-speed transmissions. Incumbents should invest in advanced CNC gear hobbing and grinding machines to meet stringent NVH requirements for electric powertrains. Acquiring niche EV gear specialists can accelerate technological integration and counter emerging entrants with focused solutions. R&D into advanced composite gears offers a long-term advantage against material cost volatility.
For New Entrants and Emerging Players: EU Green Deal Regulations in Europe open a window for new entrants specializing in lightweight, high-efficiency gear designs. Target emerging niches like Urban Air Mobility (UAM) and eVTOL aircraft, which require extremely high power-density gearboxes. Advanced composite gears for lower-torque steering systems also represent a penetrable segment. A focused go-to-market angle emphasizes specialist production for performance benefits over mass volume.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by large Tier-1 suppliers seeking to bolster their electric vehicle driveline capabilities. Long-term viability remains strong for specialized EV gear manufacturers over the next decade, driven by sustained electrification trends. Target acquisition archetypes include firms with proprietary electric powertrain gear technology or advanced material expertise. The signal to watch is OEM platform standardization for e-axle components, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs consolidate component designs, favoring large suppliers capable of integrated systems. |
| Advanced Material R&D | Develop lightweight composites for efficiency and performance gains in electric powertrains. |
| EV Gear Capacity Expansion | Increase production lines for multi-speed electric vehicle transmissions to meet electrification demand. |
| Strategic Niche Acquisition | Acquire specialists in Urban Air Mobility or high-precision EV components to diversify portfolios. |
| Digital Twin Integration | Implement virtual prototyping to accelerate gear design and testing cycles, reducing development costs. |
Research Approach
Multi-period observation of vehicle production volumes, EV adoption rates, and material science advancements anchored the trend analysis. Primary research involved discussions with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and metallurgists. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs/trade data, and technical journals. This approach facilitated bottom-up and top-down triangulation.
Segment-weighting approach informed the market sizing and projection across the analysis window. The analytical framework incorporated regression analysis and scenario modeling to forecast market evolution. Segmentation dimensions modeled included product type, application, manufacturing stage, end user, and propulsion architecture. Compound Annual Growth Rates were derived from a weighted average of individual segment growth rates, utilizing inputs like EV sales forecasts and raw material cost projections.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing in gear production would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and economic growth over the projection horizon. Deviation in raw material price fluctuations or EV transmission standardization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive V-Belts Market
Automotive Components
Automotive Resonator Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Hubcaps Market