
 Automotive Instrument Cluster Market | 2026-2036
Automotive Instrument Cluster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Instrument Cluster Market Analysis
Modular cockpit bundling is expanding as OEMs consolidate instrument clusters, infotainment screens, and head-up displays into unified digital cockpit platforms. Visteon Corporation leverages its integrated SmartCore architecture to supply scalable domain controllers across multiple vehicle programs. Continental AG sustains broad manufacturing scale across TFT LCD and OLED cluster variants for both premium and mass-market platforms. Denso Corporation anchors its position through deep relationships with Toyota and hybrid-electric vehicle cockpit specialization in Japan and North America.
An automotive instrument cluster is the driver-facing information display assembly that presents vehicle speed, engine status, navigation prompts, and safety warnings through analog gauges, digital screens, or hybrid configurations. The unit typically incorporates a 10-12 inch TFT LCD or OLED panel driven by a dedicated graphics controller, housed in a thermally managed bezel assembly rated for automotive temperature extremes. Digital clusters now dominate new vehicle programs because they enable software-defined customization and over-the-air updates. Hybrid clusters retain relevance in cost-sensitive commercial vehicle segments where analog reliability persists. Head-up displays represent the fastest-growing feature category as safety regulations mandate eyes-forward information presentation.
The US NHTSA enforces Federal Motor Vehicle Safety Standard 101 for driver information readability and warning lamp protocols. The EU Green Deal and CSRD disclosure rules pressure suppliers to document embedded carbon in cluster electronics and display manufacturing. Japan's METI promotes domestic semiconductor and display supply chain resilience through targeted industrial policy. Stakeholders must monitor how software liability frameworks evolve as clusters transition from hardware-defined to software-updatable platforms.
Market Dynamics
Digital cockpit consolidation is compressing standalone instrument cluster margins as OEMs demand unified domain controllers spanning displays, HUDs, and infotainment. NHTSA and Euro NCAP safety disclosure mandates are accelerating hardware-software integration timelines.
Growth Catalysts
- NHTSA FMVSS 101:Federal readability standards for driver information displays mandate high-contrast digital interfaces, pushing analog-to-digital conversion across US vehicle programs.
- Head-up display convergence:Safety regulations requiring eyes-forward information presentation are bundling HUD modules with instrument clusters in premium and mass-market platforms.
- Software-defined vehicle architectures:Over-the-air update capabilities enable post-sale feature monetization, transforming clusters from fixed hardware into upgradable service platforms.
Market Restraints
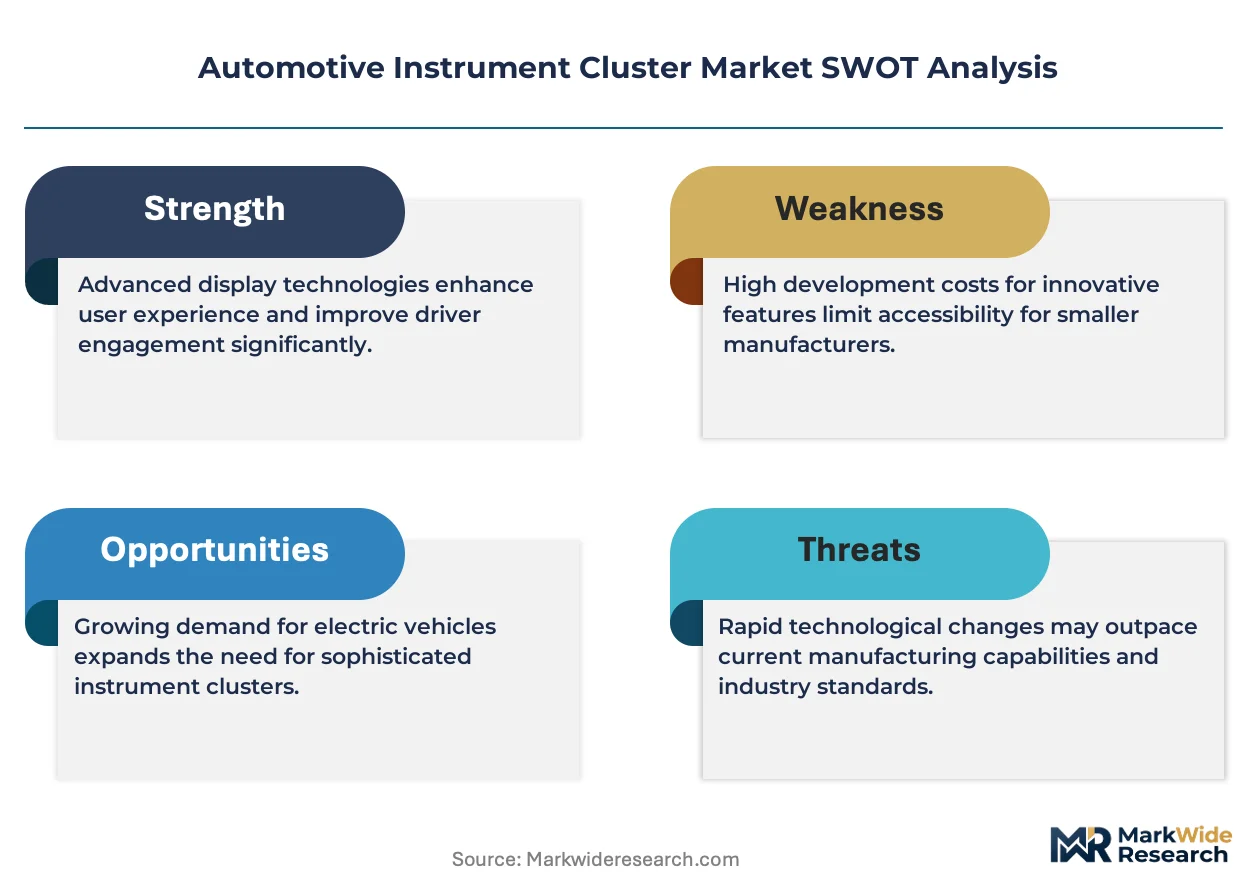
- AMOLED panel supply concentration:Korean and Chinese display manufacturers control high-grade automotive OLED capacity, creating input bottlenecks for curved cluster designs.
- Semiconductor lithography costs:Advanced graphics controllers require sub-7nm fabrication nodes with capital-intensive foundry commitments, elevating breakeven volumes.
- Functional safety certification friction:ISO 26262 ASIL-B compliance for safety-critical cluster software extends development cycles and locks in supplier relationships.
Strategic Opportunities
- Commercial vehicle hybrid clusters:Cost-sensitive trucking and construction equipment segments retain analog-digital hybrid demand where reliability outweighs customization.
- EU CSRD carbon disclosure:Embedded emissions reporting requirements favor suppliers with documented low-carbon display manufacturing and semiconductor sourcing.
- AR-HUD integration:Augmented reality head-up displays converging with instrument clusters create new content monetization channels for navigation and hazard alerts.
Industry Challenges
- Automotive UX software talent scarcity:Real-time graphics programming and functional safety engineering skills concentrate at tier-one suppliers and major OEM captive centers.
- Legacy vehicle electrical architecture integration:Domain controller migration requires backward compatibility with CAN and LIN bus systems in multi-year platform cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Instrument Cluster Market |
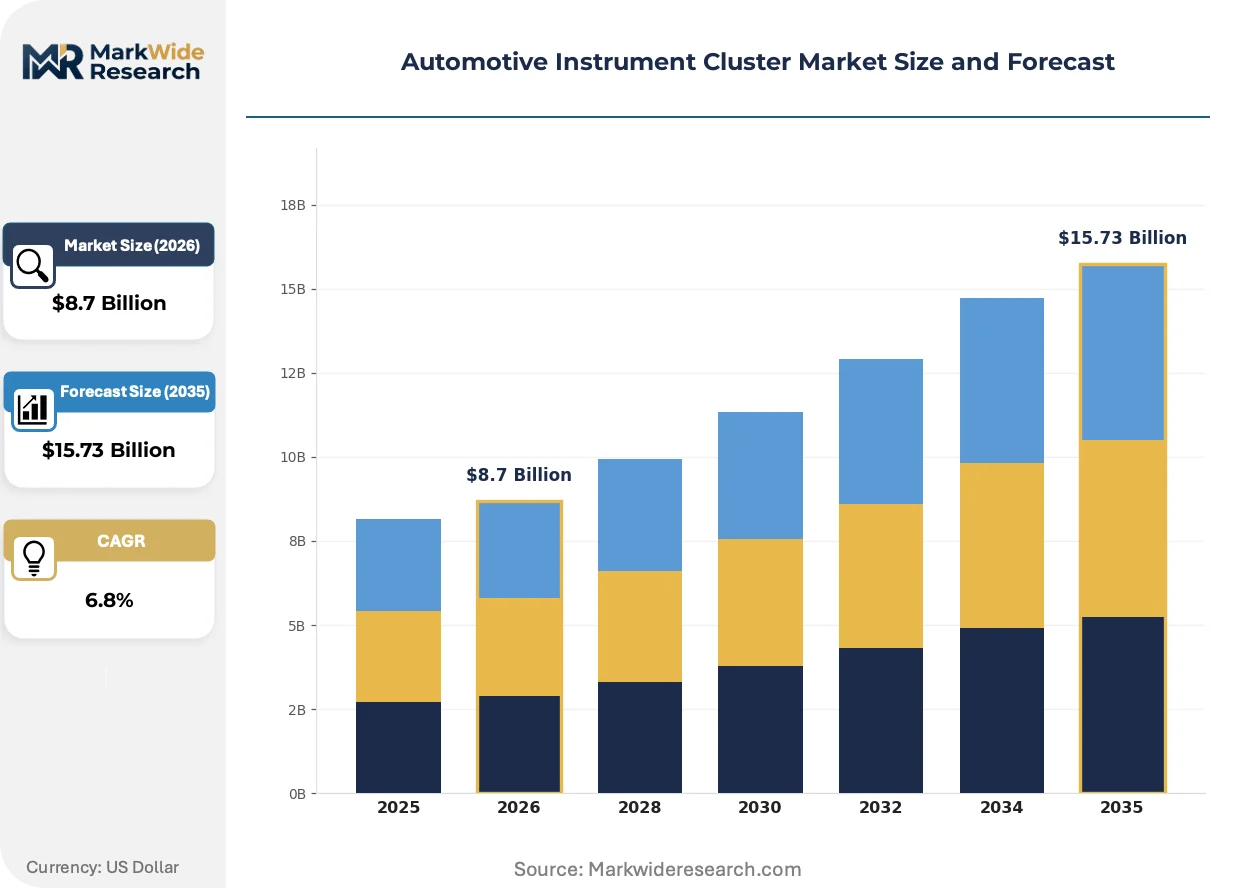
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Clusters, Digital Clusters, Hybrid Clusters, Head-Up Displays Technology: TFT LCD, OLED, LED, LCD End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Feature: Navigation System, Connectivity, Customization, Safety Alerts |
| Companies Covered | Visteon Corporation, Yazaki Corporation, Continental AG, Aisin Seiki Co., Ltd., Panasonic Corporation, Denso Corporation, Nippon Seiki Co., Ltd., Magneti Marelli S.p.A., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Instrument Cluster Market Emerging Trajectories
Three forces are restructuring how instrument clusters deliver value: display technology convergence with infotainment, regulatory pressure for integrated safety alerts, and procurement models favoring bundled cockpit domain controllers over discrete components.
MicroLED display technology is integrating high-brightness, low-latency visualization for direct sunlight readability in premium electric vehicles. German and Japanese OEMs are piloting curved microLED clusters with pixel-level dimming for augmented reality overlays. This technology is integrating safety-critical information with entertainment content on unified screens, compressing the traditional separation between instrument clusters and center-stack displays.
Euro NCAP's 2026 safety rating protocols mandate direct driver monitoring and distraction warnings, forcing cluster-HUD integration for compliance. European suppliers are accelerating development of unified graphics pipelines that render identical hazard alerts across multiple display surfaces. Premium EV platforms in Germany and Scandinavia are first movers, with mass-market adoption following regulatory phase-in schedules.
Fleet procurement of digital cockpits is consolidating specification authority at OEM central purchasing departments, displacing decentralized brand-level component sourcing. Tier-one suppliers now negotiate multi-program domain controller contracts spanning instrument clusters, infotainment, and HUDs. This concentration is most visible in North American and European OEMs with standardized global vehicle architectures.
Automotive Instrument Cluster Market Segmentation
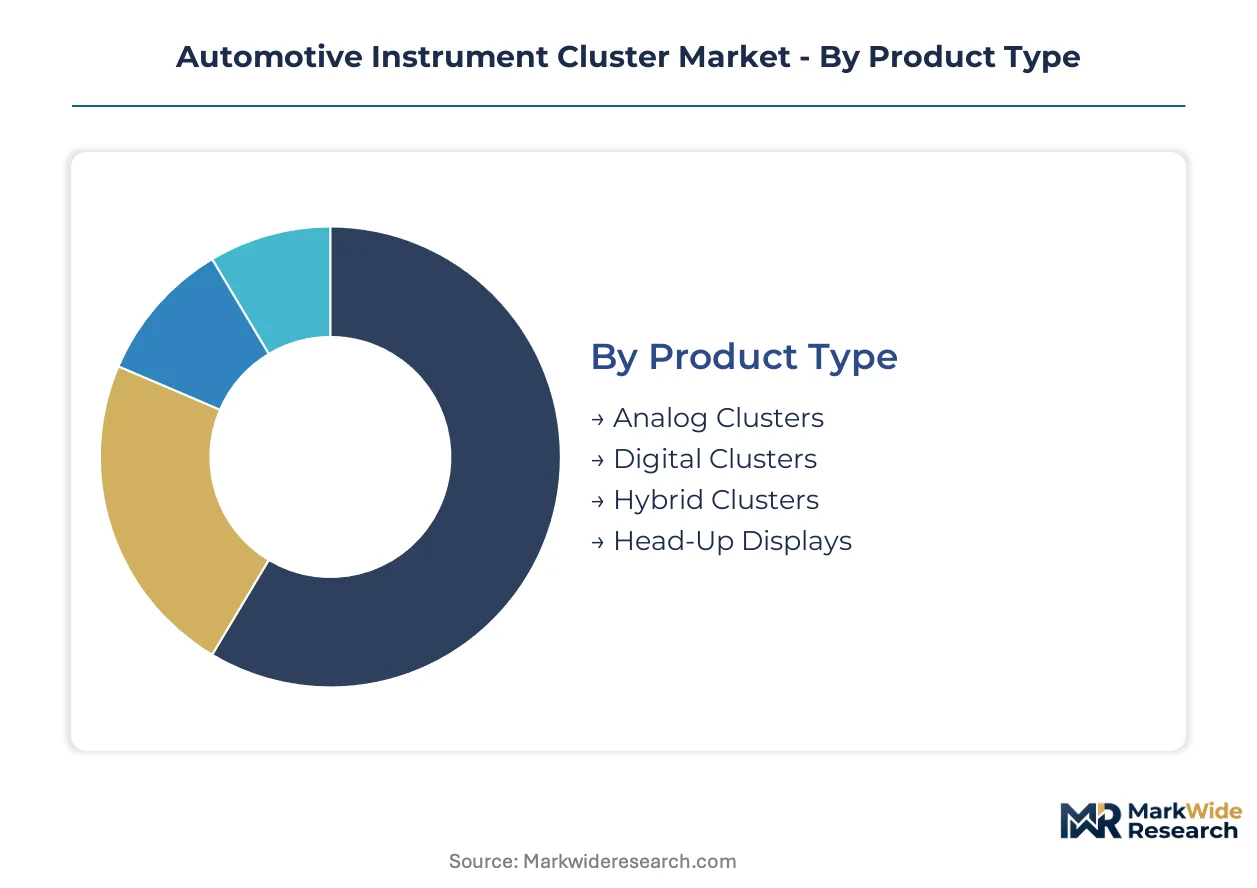
Segmentation in the automotive instrument cluster market reveals how upgrade cycles, platform consolidation, and regulatory mandates reshape procurement priorities across vehicle programs. Understanding these dimensions exposes where suppliers can capture value as digital cockpit architectures displace discrete component sourcing.
Product Type:
Replacement cycles for instrument clusters accelerate as OEMs redesign vehicle interiors around unified digital experiences, compressing the timeline between analog legacy and full digital adoption.
- Digital Clusters:Full TFT LCD or OLED displays replace mechanical gauges with software-rendered instruments, enabling over-the-air updates and customizable layouts. Electric vehicle platforms in Germany, Japan, and the United States concentrate demand as these OEMs eliminate analog heritage entirely.
- Hybrid Clusters:Analog-digital combinations retain mechanical speedometers or tachometers alongside embedded screens, serving cost-sensitive segments where gauge reliability outweighs customization needs. Commercial vehicle manufacturers in China and India specify these configurations for durability in harsh operating environments.
- Analog Clusters:Pure mechanical gauge assemblies persist in entry-level vehicles and certain developing markets where semiconductor supply constraints elevate digital costs prohibitively.
- Head-Up Displays:Windshield-projected information systems represent the fastest-climbing segment as NHTSA and Euro NCAP safety mandates require eyes-forward hazard presentation.
Digital Clusters sits at the top of the volume ranking, with Head-Up Displays climbing the fastest.
Technology:
Cost tier differentiation across display technologies determines which suppliers capture premium versus mass-market platform wins, with panel sourcing strategies locked years ahead of production.
- TFT LCD:Thin-film transistor liquid crystal displays dominate mass-market instrument clusters with mature supply chains, automotive temperature ratings, and cost structures below OLED alternatives. Korean and Chinese panel manufacturers supply the majority of global capacity for this technology tier.
- OLED:Organic light-emitting diode panels enable curved surfaces, pixel-level dimming, and superior contrast ratios for premium electric vehicle cockpits. German OEMs specify these for flagship sedan and SUV programs where display differentiation commands price premiums.
- LED:Light-emitting diode backlighting enhances conventional LCD readability while reducing power consumption compared to cold cathode fluorescent alternatives.
- LCD:Standard liquid crystal display technology without active matrix addressing serves entry-level clusters where cost minimization overrides performance specifications.
TFT LCD maintains the largest installed base, though OLED is expanding most quickly in premium vehicle segments.
End User:
Application-specific requirements for information presentation, environmental durability, and connectivity integration fragment demand across vehicle categories with distinct procurement authority structures.
- Passenger Vehicles:Light-duty automobiles and SUVs drive standardization toward large-format digital clusters with integrated infotainment and head-up display convergence. Japanese and German OEMs lead specification complexity for these platforms.
- Electric Vehicles:Battery-electric platforms eliminate internal combustion gauges entirely, enabling radical cockpit redesigns with unified screen architectures spanning instrument panel to center stack. Chinese EV manufacturers accelerate this transition fastest through domestic display supply chain integration.
- Commercial Vehicles:Heavy trucks, buses, and construction equipment prioritize gauge legibility under vibration, temperature extremes, and direct sunlight exposure over aesthetic customization.
- Two-Wheelers:Motorcycles and scooters utilize compact cluster formats with simplified information architecture, often integrating smartphone mirroring for navigation in premium segments.
Passenger Vehicles occupies the highest volume position, while Electric Vehicles demonstrates the steepest expansion trajectory.
Feature:
Customer type preferences for connectivity and safety integration determine which feature bundles command pricing power versus commoditization in consolidated cockpit procurement.
- Safety Alerts:Integrated collision warnings, lane departure notifications, and driver monitoring displays respond directly to NHTSA FMVSS 101 and Euro NCAP rating protocols. European suppliers embed these capabilities into unified graphics pipelines rendering identical alerts across cluster and head-up display surfaces.
- Navigation System:Turn-by-turn direction presentation within the instrument cluster reduces driver distraction compared to center-stack glances. Premium German and Japanese platforms specify this as standard equipment.
- Connectivity:Smartphone integration, over-the-air update capability, and cloud-based service access transform clusters into software-defined platforms with post-sale monetization potential.
- Customization:User-selectable gauge layouts, themes, and information prioritization enable personalization without hardware changes.
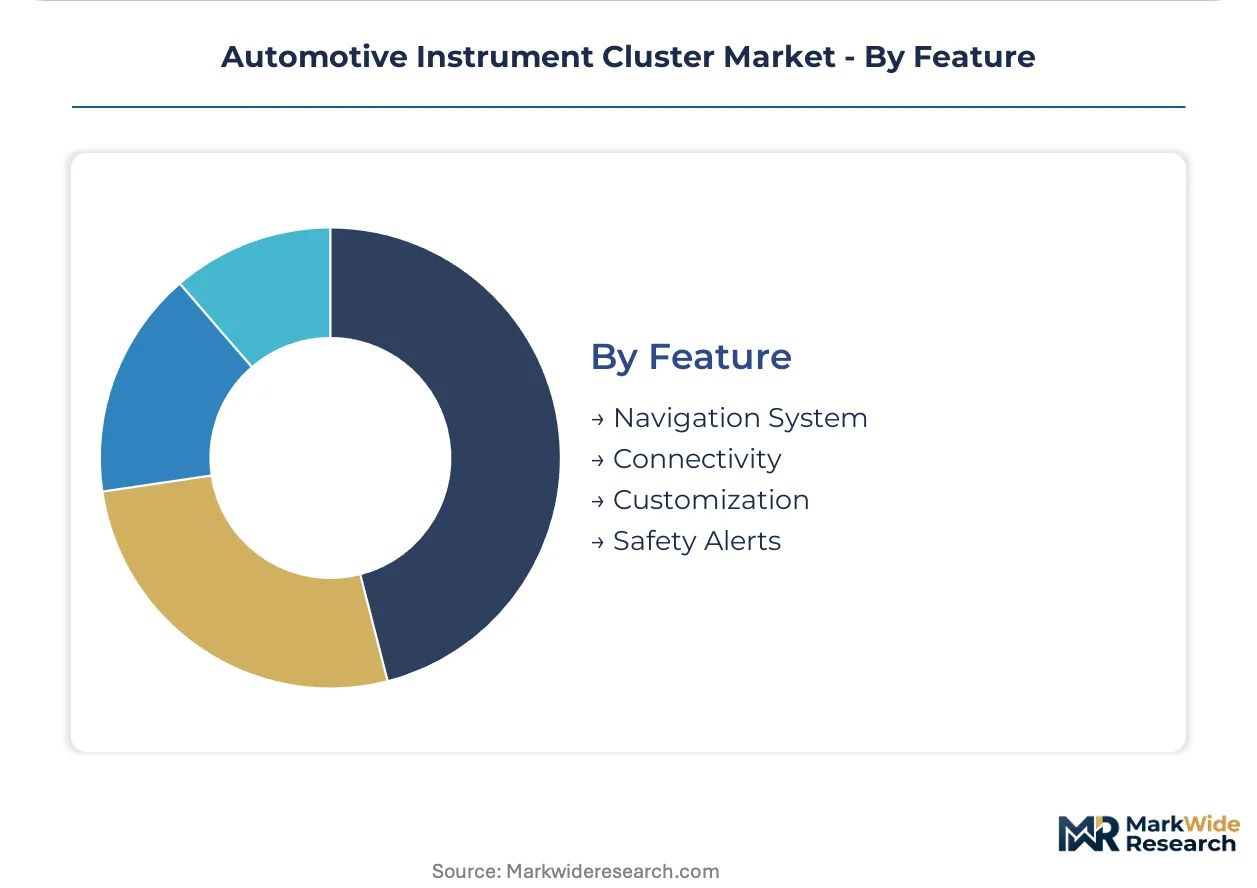
Safety Alerts leads feature adoption by regulatory mandate, with Connectivity gaining share fastest through software-defined vehicle architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive instrument cluster manufacturing during the post-war industrial expansion, establishing Stuttgart and Munich as cockpit electronics engineering centers that later seeded tier-one supplier networks across Europe and Asia.
China
Domestic EV manufacturers in Shenzhen and Shanghai drive demand for fully digital cockpit systems with integrated head-up displays. The MIIT enforces GB standards for vehicle display readability and electromagnetic compatibility. Yangtze River Delta manufacturing clusters around Suzhou and Ningbo now supply TFT LCD and OLED panels for both local OEMs and export programs.
Germany
Premium OEMs in Munich and Stuttgart specify curved OLED clusters with augmented reality HUD convergence for flagship electric platforms. The KBA enforces UNECE regulations on driver information presentation and functional safety. Baden-Württemberg's supplier corridor from Böblingen to Karlsruhe concentrates domain controller R&D and graphics software engineering.
Japan
Hybrid-electric vehicle programs from Toyota City and Hiroshima sustain demand for specialized cluster architectures balancing analog reliability with digital integration. METI promotes domestic semiconductor and display supply chain resilience through targeted industrial policy. Kansai manufacturing clusters around Osaka and Kyoto maintain captive production of automotive-grade graphics controllers.
United States
Detroit-based OEMs and Silicon Valley EV entrants consolidate procurement of unified digital cockpit platforms spanning instrument clusters, infotainment, and HUDs. NHTSA FMVSS 101 mandates high-contrast digital interfaces with standardized warning lamp protocols. Michigan's automotive corridor from Detroit to Grand Rapids anchors tier-one supplier engineering centers serving North American vehicle programs.
South Korea
Display manufacturers in Suwon and Gumi control high-grade automotive OLED capacity, creating input concentration for curved cluster designs across global OEMs. The MFDS coordinates with automotive regulators on embedded electronics safety standards. Seoul Capital Area engineering centers develop microLED and advanced TFT technologies for next-generation cockpit applications.
Automotive Instrument Cluster Market Vendor Landscape
Premium-margin players sit above commodity-margin players across display technology tiers and software integration depth. The market structures into consolidated tier-one domain controller suppliers and specialized cluster component manufacturers serving cost-sensitive segments. Three archetypes dominate: integrated cockpit platform providers, display panel specialists with automotive qualification, and legacy gauge assemblers pivoting toward digital hybrid systems. Competitive moves center on multi-program domain controller contracts and strategic partnerships for AR-HUD content pipelines.
Within the integrated platform tier, Visteon Corporation and Continental AG exemplify scalable architecture suppliers spanning multiple vehicle programs. Denso Corporation anchors the hybrid-electric specialization segment through captive relationships with Japanese OEMs. Robert Bosch GmbH occupies a position bridging component supply and systems integration across European and North American markets.
| Leading Market Players |
|---|
| Visteon Corporation |
| Yazaki Corporation |
| Continental AG |
| Aisin Seiki Co., Ltd. |
| Panasonic Corporation |
| Denso Corporation |
| Nippon Seiki Co., Ltd. |
| Magneti Marelli S.p.A. |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Fleet procurement consolidation at OEM central purchasing departments forces tier-one suppliers to absorb volume-scaling risks while committing to multi-year domain controller contracts, compressing component-level margins and elevating importance of captive semiconductor sourcing for cost control.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by display technology grade and functional safety certification tier. Premium OLED clusters with ASIL-B compliance command substantial premiums over mass-market TFT LCD alternatives. Cost compression in standard-tier TFT LCD modules is intensifying because Korean and Chinese panel manufacturers compete aggressively for automotive qualification slots. Commercial vehicle OEMs exhibit highest price sensitivity, while German premium EV manufacturers prioritize differentiation over unit cost.
Supply Chain Analysis
Domestic-content mandates in China, Japan, and South Korea are reshaping sourcing patterns for automotive-grade graphics controllers and display panels. Manufacturing concentrates in China's Yangtze River Delta, South Korea's Seoul Capital Area, and Japan's Kansai corridor. Semiconductor lithography for advanced cluster controllers draws from Taiwan and South Korea foundries. Single-source vulnerability for sub-7nm fabrication nodes creates supply chain risk. Distribution runs through tier-one domain controller suppliers who bundle clusters with HUD and infotainment modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as OEM procurement shifts toward unified digital cockpit platforms with integrated AR-HUD capabilities and software-defined update architectures.
For Market Incumbents:Cement domain controller platform dominance by securing multi-program contracts spanning instrument clusters, infotainment, and HUDs. Deepen backward integration into automotive-grade semiconductor sourcing to defend margins against Korean and Chinese display panel supply concentration. Prioritize ASIL-B functional safety certification investment as regulatory mandates accelerate.
For New Entrants and Emerging Players:Commercial vehicle hybrid cluster specialists represent the most penetrable white-space target, as cost-sensitive trucking and construction equipment segments retain analog-digital demand where reliability outweighs customization. Target Chinese domestic EV manufacturers with localized TFT LCD sourcing partnerships as an entry angle.
For Investors and Strategic Acquirers:Asymmetric upside sits with tier-two display panel specialists possessing automotive OLED qualification and existing relationships with German premium OEMs. Long-term viability centers on software-defined vehicle architectures transforming clusters into upgradable service platforms. Watch for AR-HUD content pipeline partnerships as inflection indicator for platform consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unifies instrument cluster, infotainment, and HUD architectures across multiple vehicle programs for OEMs. |
| Software-Defined Vehicle Investment | Enables over-the-air feature monetization transforming hardware into recurring revenue streams. |
| Geographic Manufacturing Footprint | Positions suppliers near China, Germany, and Japan production clusters to meet local-content requirements. |
| Backward Integration into Semiconductors | Reduces dependency on Taiwan and South Korea foundries for advanced graphics controller supply. |
| AR-HUD Content Partnership | Creates navigation and hazard alert monetization channels converging with instrument cluster displays. |
Methodological Framework
Coverage spans China, Germany, Japan, South Korea, and the United States, with primary inputs from each market. The research combines structured interviews with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS filings, and Euro NCAP safety protocols. Bottom-up modeling of content per vehicle and platform-level bill-of-materials triangulates against top-down market sizing from regional production forecasts.
Granularity-level modeling disaggregates volume and value across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from segment-level growth trajectory analysis incorporating electric vehicle platform ramp schedules and regulatory mandate phase-in timelines across the projection horizon. Forecast inputs include semiconductor supply constraints, display technology transition curves, and software-defined vehicle adoption patterns.
Revisions become necessary when semiconductor lithography capacity expansions, trade policy shifts, or safety regulation accelerations materialize differently than modeled. Forecasts reflect documented assumptions about OLED panel yield improvements and domain controller consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Door Module Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Asia Pacific Automotive Actuators Market