
 China Automotive Actuators Market | 2026-2036
China Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Actuators Market Outlook
New energy vehicle powertrain architectures is shifting actuator procurement toward electromechanical solutions with higher precision demands. Robert Bosch GmbH leverages its localized engineering centers in China to sustain development of integrated brake-actuator modules for domestic EV platforms. Denso Corporation anchors its competitive position through captive motor-manufacturing capacity serving steering and thermal management actuators. Zhejiang Asia-Pacific Mechanical & Electronic Co Ltd specializes in pneumatic brake actuators and dominates aftermarket channels across eastern provinces.
Automotive actuators are electromechanical or fluid-powered devices that convert energy into controlled mechanical motion to modulate vehicle subsystems, typically operating with positional accuracy within fractions of a millimeter and response times under 50 milliseconds for safety-critical functions. Their primary purpose is to execute real-time commands from electronic control units in powertrain, chassis, and thermal systems without direct human intervention. Linear actuators lead volume demand in transmission and engine management where precise displacement control governs shift quality and emissions performance, while electromechanical technology is displacing hydraulic alternatives in brake-by-wire and steer-by-wire architectures due to energy efficiency and packaging advantages. OEMs capture the dominant value share as vehicle manufacturers internalize actuator specification authority and qualify suppliers against platform-specific durability protocols.
MIIT establishes mandatory fuel consumption and new energy vehicle credit quotas that force actuator efficiency improvements in thermal and powertrain systems. NMPA enforces homologation standards for braking and steering actuators under GB protocol requirements that govern market access for replacement and original equipment. GB standards administered by SAMR define electromagnetic compatibility and environmental testing benchmarks that electromechanical actuator designs must satisfy for type approval. Stakeholders must monitor how dual carbon goals tighten material sourcing requirements and whether domestic semiconductor availability constrains smart actuator controller supply.
Market Dynamics
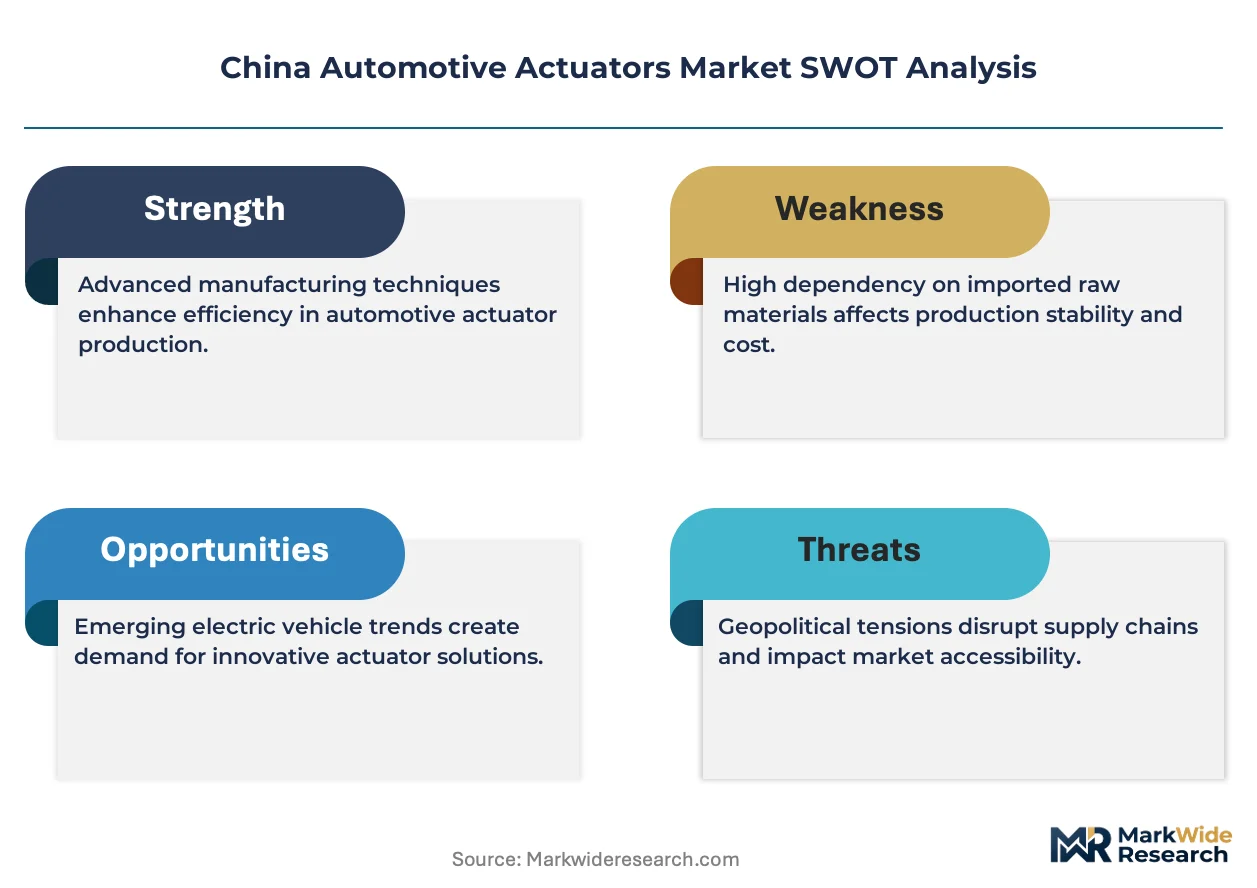
Electromechanical actuator architectures are displacing hydraulic systems across brake-by-wire and steer-by-wire platforms as domestic OEMs accelerate xEV platform rollouts to satisfy MIIT credit mandates. This technology transition concentrates procurement authority with vehicle manufacturers who now specify integrated module designs rather than discrete component sourcing.
Growth Catalysts
- MIIT NEV Credit Quotas:Mandatory production thresholds for new energy vehicles compel automakers to source precision electromechanical actuators for thermal management and regenerative braking systems.
- Yangtze River Delta Clustering:Co-location of Tier-1 suppliers with assembly plants in Shanghai, Jiangsu, and Zhejiang provinces compresses logistics costs and accelerates design iteration cycles.
- Brake-by-Wire Proliferation:The elimination of hydraulic fluid circuits in favor of electromechanical solutions reduces vehicle weight and enables integration with autonomous emergency braking protocols.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium and dysprosium supply concentration in processing facilities creates input cost volatility for high-torque motor cores used in steering actuators.
- GB Standard Compliance Burden:SAMR-administered electromagnetic compatibility and environmental testing protocols extend type-approval timelines for imported actuator controller designs.
- Hydraulic System Incumbency:Existing service infrastructure and technician familiarity with fluid-based brake systems slows fleet replacement cycles in commercial vehicle segments.
Strategic Opportunities
- Western China Manufacturing Bases:Chongqing and Chengdu automotive hubs offer underutilized capacity for actuator assembly plants serving interior provinces with lower labor and land costs.
- Dual Carbon Policy Alignment:MEE emissions reduction frameworks reward suppliers with verified low-carbon material sourcing, creating preference windows for domestic rare earth processors.
- Smart Actuator Convergence:Integration of position sensors and edge-computing controllers enables predictive maintenance contracts that extend supplier revenue streams beyond hardware sales.
Industry Challenges
- Embedded Software Certification:ISO 26262 functional safety validation for actuator control algorithms demands specialized automotive software engineers in short supply across domestic engineering centers.
- Semiconductor Controller Availability:Smart actuator deployment depends on consistent supply of automotive-grade microcontrollers where domestic foundry capacity remains constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Actuators Market |
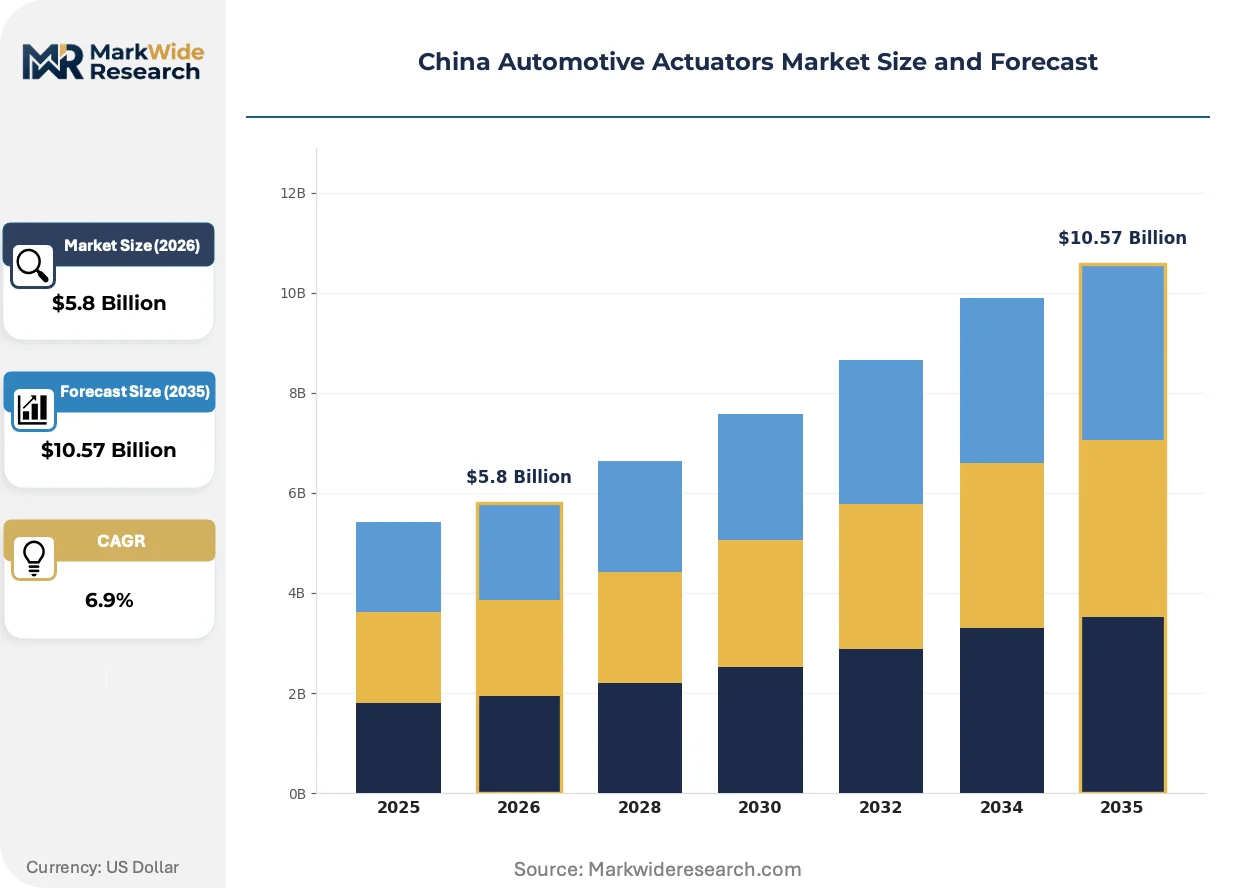
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.57 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
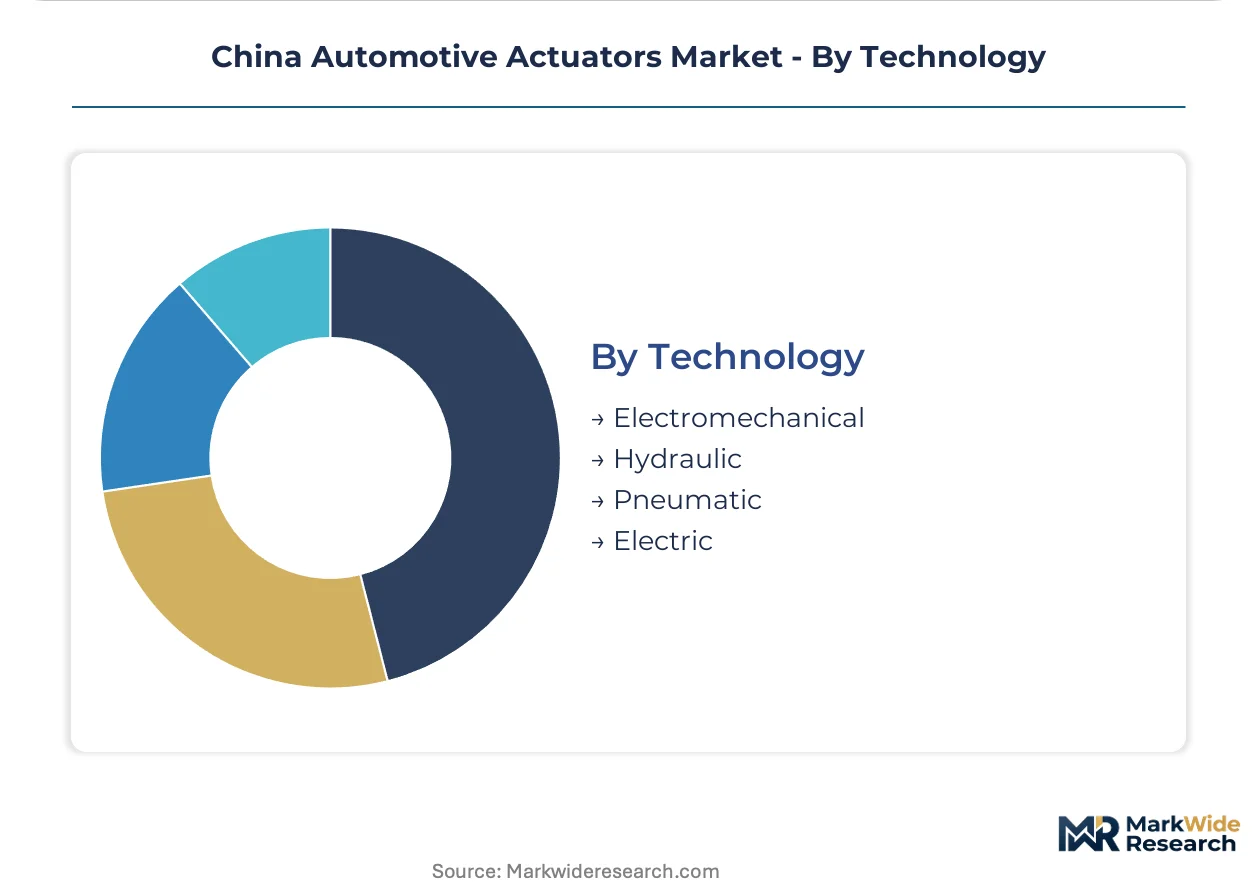
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Pneumatic Actuators, Hydraulic Actuators Application: Engine Control, Transmission Control, Brake Systems, Steering Systems End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: Electromechanical, Hydraulic, Pneumatic, Electric |
| Companies Covered | Mitsubishi Electric Corporation, Hitachi Ltd, Robert Bosch GmbH, Shanghai Hugong Auto-Electric Co Ltd, BorgWarner Inc, Denso Corporation, Nidec Corporation, Zhejiang Asia-Pacific Mechanical & Electronic Co Ltd, Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Actuators Market Strategic Shifts
Actuator technology trajectories center on electromechanical precision improvements and control system integration as vehicle architectures consolidate distributed functions into domain controllers. These shifts compress supplier margins while elevating specification authority toward OEM engineering centers.
Integrated brake-actuator modules combining motor, gearbox, and control electronics in sealed housings are expanding into domestic EV platforms from multiple OEMs. These consolidated designs eliminate hydraulic lines and vacuum boosters entirely. BYD and NIO have qualified such modules for volume production. The technology is expanding into commercial vehicle applications where maintenance interval extension drives fleet operator preference.
NMPA enforcement of GB protocol homologation standards for braking and steering actuators tightens electromagnetic compatibility and environmental stress testing requirements. The industrial consequence accelerates localization of controller firmware development to satisfy type-approval documentation in Mandarin. Passenger vehicle platforms with autonomous driving capability are most affected, with suppliers establishing dedicated compliance engineering teams in Shanghai.
Automakers now specify actuator performance through outcome-based durability protocols rather than component-level specifications. Tier-1 suppliers assume integration risk for complete mechatronic subsystems. This pattern concentrates in the Yangtze River Delta where OEM technical centers maintain daily engineering coordination with actuator manufacturers.
China Automotive Actuators Market Segmentation
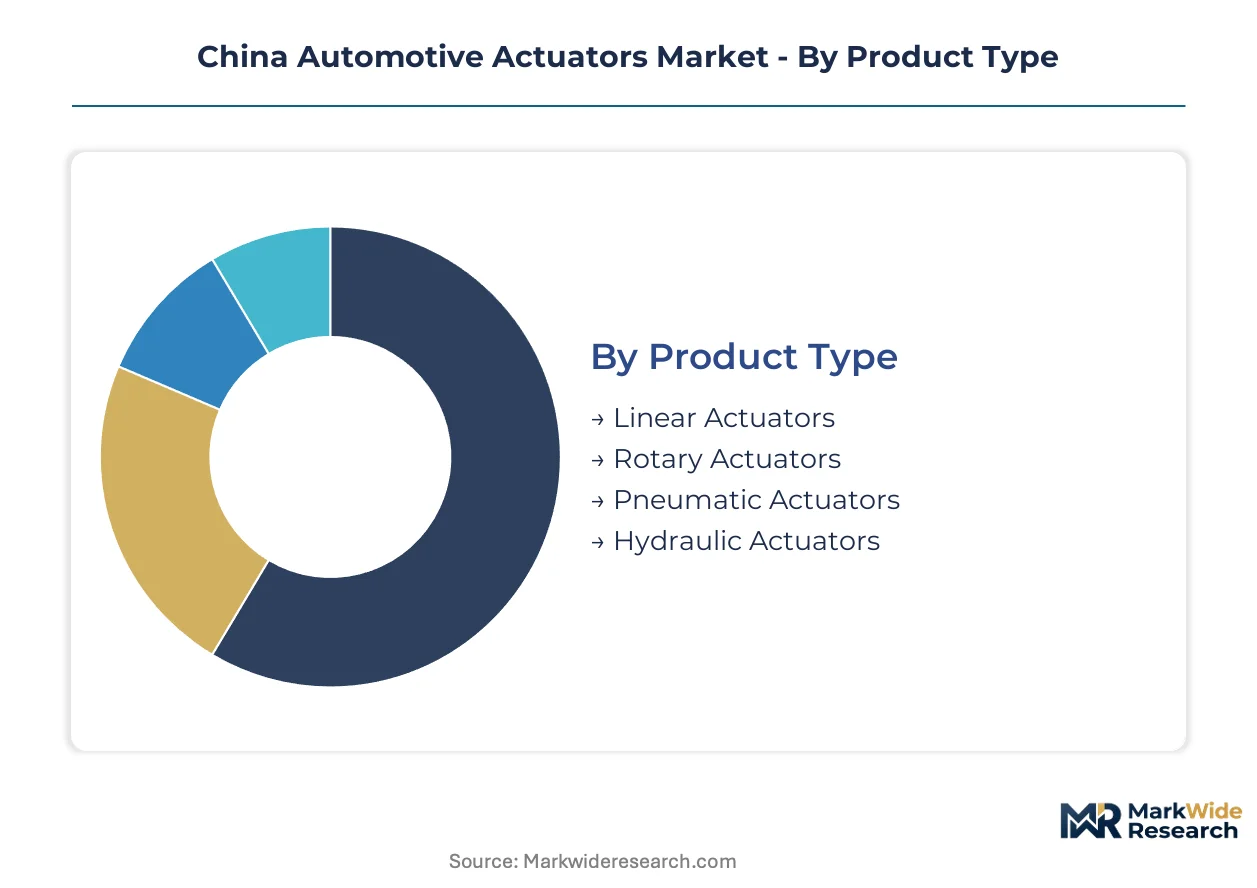
Actuator procurement patterns in China diverge sharply between integrated powertrain modules and standalone chassis components, with MIIT efficiency mandates and NMPA safety protocols creating distinct specification pathways across each segment cluster. Understanding these divides reveals where supplier margins concentrate and which technology transitions threaten incumbent positions.
Product Type:
Standalone actuators serve discrete replacement markets while embedded designs merge into consolidated mechatronic modules, altering supplier economics across each category.
- Linear Actuators:Electromechanical screw and ball-screw mechanisms deliver precise displacement control for transmission shift forks and throttle bodies. Demand concentrates in Yangtze River Delta transmission plants where Geely and SAIC specify sub-millimeter positional accuracy for dual-clutch architectures. MIIT fuel-economy mandates force continuous refinement of actuation speed and energy consumption.
- Rotary Actuators:Brushless DC motor-driven rotary stages manage valve timing and exhaust gas recirculation with angular resolution below 0.1 degrees. Sichuan and Chongqing engine manufacturing hubs drive procurement volume as domestic OEMs localize powertrain production away from coastal clusters.
- Pneumatic Actuators:Compressed air systems dominate commercial vehicle brake applications and clutch actuation where cost sensitivity outweighs precision requirements.
- Hydraulic Actuators:Fluid-power cylinders persist in heavy-duty steering and suspension systems despite electromechanical displacement in passenger vehicles.
Linear actuators lead volumes today; rotary actuators are gaining share fastest.
Application:
Cost tiers separate safety-critical chassis functions from powertrain efficiency systems, with brake and steering commanding premium pricing against engine and transmission components.
- Brake Systems:Electromechanical brake-by-wire modules integrate motor, gearbox, and controller in sealed housings that eliminate hydraulic circuits entirely. BYD and NIO have qualified domestic designs for volume EV production, with NMPA GB homologation standards mandating electromagnetic compatibility validation that extends development timelines.
- Steering Systems:Rack-drive electromechanical power steering delivers torque assist with fail-operational redundancy required for autonomous driving capability. Shanghai-based engineering centers coordinate daily with Tier-1 suppliers on durability protocol compliance.
- Engine Control:Throttle and variable valve timing actuators face margin compression as ICE vehicle production plateaus under MIIT NEV credit quotas.
- Transmission Control:Shift-by-wire actuators support dual-clutch and dedicated hybrid transmission architectures in Geely and Great Wall Motor platforms.
Brake systems capture the highest unit margins; steering systems are climbing the fastest.
End User:
Volume concentration tilts toward captive OEM supply chains versus fragmented aftermarket channels, with specification authority residing in vehicle manufacturer engineering centers.
- OEMs:Vehicle manufacturers internalize actuator specification authority and qualify suppliers against platform-specific durability protocols spanning thermal cycling, vibration, and corrosion resistance. Direct procurement relationships dominate electromechanical brake and steering modules where system integration risk concentrates.
- Tier-1 Suppliers:Bosch, Denso, and domestic specialists like Zhejiang Asia-Pacific Mechanical assume subsystem integration responsibility and manage Tier-2 component sourcing. These intermediaries capture value through mechatronic design and firmware development capabilities.
- Aftermarket Providers:Independent distributors serve replacement demand for hydraulic brake and pneumatic systems in commercial vehicle fleets across eastern provinces.
- Dealerships:Authorized service channels handle warranty-related actuator replacement with OEM-mandated parts sourcing.
OEMs dominate value capture today; Tier-1 suppliers are expanding their role fastest.
Technology:
Supply concentration for rare earth magnets and semiconductor controllers constrains electromechanical expansion while hydraulic incumbency resists in commercial vehicle segments.
- Electromechanical:Brushless DC motors with neodymium-dysprosium magnet cores deliver precise position control for brake-by-wire and steer-by-wire platforms. Domestic rare earth processing concentration in Jiangxi and Inner Mongolia creates input cost volatility that suppliers hedge through long-term offtake agreements.
- Electric:Solenoid and stepper motor actuators serve thermal management and auxiliary systems with lower torque requirements than primary motion control functions.
- Hydraulic:Fluid-power systems retain installed base in heavy commercial vehicles where service infrastructure and technician familiarity slow technology transition.
- Pneumatic:Compressed air technology persists in cost-sensitive commercial brake applications and industrial vehicle segments.
Electromechanical systems lead investment today; electric actuators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta actuator demand concentrates in Shanghai, Jiangsu, and Zhejiang provinces where Tier-1 suppliers co-locate with vehicle assembly plants. MIIT fuel-economy mandates and NMPA safety certifications tighten performance thresholds across this cluster. Domestic OEMs expand xEV lineups, pulling electromechanical actuator procurement upward.
Shanghai-Jiangsu-Zhejiang Cluster
Electromechanical brake-by-wire and steer-by-wire modules dominate procurement as BYD and NIO qualify integrated designs for volume EV production. NMPA GB homologation standards mandate electromagnetic compatibility validation that extends development timelines. Shanghai-based engineering centers coordinate daily with Tier-1 suppliers on durability protocol compliance and firmware localization.
Sichuan-Chongqing Hub
Rotary actuator demand for valve timing and exhaust gas recirculation systems concentrates in engine manufacturing facilities localizing powertrain production. MIIT NEV credit quotas redirect investment toward hybrid-compatible actuator architectures. Chongqing automotive hubs offer underutilized capacity for actuator assembly plants serving interior provinces.
Beijing-Tianjin-Hebei Corridor
Thermal management actuator procurement aligns with dual carbon policy frameworks rewarding verified low-carbon material sourcing. SAMR-administered GB standards define electromagnetic compatibility benchmarks for electromechanical designs. Beijing technical centers focus on smart actuator convergence integrating position sensors and edge-computing controllers.
Shandong Peninsula
Pneumatic brake actuator aftermarket channels serve commercial vehicle fleets across eastern provinces with cost-sensitive replacement demand. MEE emissions reduction frameworks tighten material sourcing requirements for domestic rare earth processors. Qingdao and Yantai manufacturing bases supply hydraulic system components where service infrastructure slows technology transition.
Western China
Chengdu manufacturing expansion targets lower labor and land costs for actuator assembly serving interior province demand. Domestic semiconductor availability constraints limit smart actuator controller deployment in this region. Jiangxi and Inner Mongolia rare earth processing concentration creates input cost volatility that suppliers hedge through long-term offtake agreements.
China Automotive Actuators Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers establish localized engineering centers to satisfy NMPA type-approval documentation requirements. The vendor base organizes around three strategic archetypes: integrated mechatronic module specialists, captive motor manufacturers, and pneumatic brake aftermarket incumbents. Geographic clustering in the Yangtze River Delta compresses logistics costs while accelerating design iteration cycles. M&A activity concentrates on firmware development capabilities and rare earth magnet supply security.
Among Japanese-origin diversified industrial groups, Mitsubishi Electric Corporation and Hitachi Ltd occupy positions emphasizing electromechanical precision and control system integration. Robert Bosch GmbH anchors the European multinational tier through localized engineering centers serving domestic EV platforms. Denso Corporation exemplifies captive motor-manufacturing capacity serving steering and thermal management applications. Zhejiang Asia-Pacific Mechanical & Electronic Co Ltd represents the domestic specialist archetype focused on pneumatic brake systems and aftermarket channel dominance across eastern provinces.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Robert Bosch GmbH |
| Shanghai Hugong Auto-Electric Co Ltd |
| BorgWarner Inc |
| Denso Corporation |
| Nidec Corporation |
| Zhejiang Asia-Pacific Mechanical & Electronic Co Ltd |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Neodymium-dysprosium magnet cores flow from Jiangxi and Inner Mongolia processing facilities through three-tier pricing structures across premium, standard, and economy levels, with rare earth cost volatility compressing margins at the electromechanical module tier while pneumatic brake alternatives retain cost advantage in commercial vehicle channels.
Pricing Analysis
Distributor margins for aftermarket pneumatic actuators in eastern provinces absorb 15-25 point markups over OEM-direct electromechanical modules. Price differentiation separates NMPA GB-certified brake-by-wire systems from uncertified economy-tier alternatives. Cost compression in standard-tier rotary actuators is intensifying because domestic OEMs consolidate specification authority. Commercial vehicle fleet operators exhibit highest price sensitivity; autonomous-capable passenger vehicle OEMs show least.
Supply Chain Analysis
Remanufacturing flows for hydraulic brake components circulate through Shandong Peninsula service depots, feeding cost-sensitive replacement demand. Manufacturing concentrates in China, Japan, and Germany for precision electromechanical modules. Raw material dependencies center on neodymium-dysprosium magnets, automotive-grade microcontrollers, and specialty steel alloys. Single-source vulnerability in domestic semiconductor foundry capacity threatens smart actuator controller deployment. Distribution runs through Yangtze River Delta co-located Tier-1 supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT NEV credit quotas compound regulatory demand for precision electromechanical actuators, with mandatory production thresholds forcing technology transitions across domestic OEM platforms.
For Market Incumbents: To counter rare earth magnet cost volatility, secure long-term offtake agreements with Jiangxi and Inner Mongolia processors. Add captive motor-manufacturing capacity in Sichuan-Chongqing hubs to hedge coastal cluster concentration risk. NMPA GB homologation timeline extensions threaten imported controller designs; localize firmware development in Shanghai engineering centers. For New Entrants and Emerging Players: The premium-economy price-point gap in smart actuator convergence creates entry opportunity for edge-computing controller specialists. Western China manufacturing bases in Chengdu offer underutilized assembly capacity with lower labor and land costs. Target thermal management actuator segments where MIIT fuel-economy mandates force continuous refinement but incumbent concentration remains lower than brake and steering. For Investors and Strategic Acquirers: Roll-up economics work for domestic pneumatic brake aftermarket specialists because channel fragmentation across eastern provinces prevents scale efficiency. Five-to-ten year viability hinges on electromechanical displacement pace in commercial vehicles. Watch Jiangxi rare earth processing policy shifts as inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Rare Earth Offtake Agreement | Secures neodymium-dysprosium supply from Jiangxi processors against price volatility. |
| Shanghai Firmware Localization Center | Accelerates NMPA GB homologation timelines for smart actuator controller designs. |
| Chengdu Assembly Plant Expansion | Captures lower labor and land costs for interior province demand serving. |
| Integrated Brake-Actuator Module Qualification | Meets BYD and NIO platform specifications for volume EV production. |
| Edge-Computing Controller Development | Enables predictive maintenance contracts extending supplier revenue streams. |
Study Parameters
Multiple input streams — OEM platform engineering interviews, Tier-1 supplier procurement discussions, aftermarket distributor channel assessments, and NMPA regulatory filing analysis — were reconciled against vehicle production databases and MIIT policy documentation. Primary engagement with actuator R&D directors, OEM durability protocol managers, and thermal system procurement leads supplemented secondary validation through SAMR GB standard publications, customs trade records, and IHS Markit registration data. Bottom-up segment sizing and top-down market reconciliation triangulated volume estimates.
Historical production trajectories were cross-referenced against panel input from Tier-1 engineering centers to anchor projection assumptions across the analysis window. Segmentation modeling spanned product type, application, technology, and regional production cluster dimensions. CAGRs were derived from fitted growth curves applied to technology transition rates and regulatory mandate compliance timelines. Electromechanical displacement pace in brake-by-wire platforms and domestic rare earth processing capacity expansion served as key forecast inputs.
Caveats apply where semiconductor controller availability constraints or dual carbon policy material sourcing restrictions could materially shift the outlook. Forecasts reflect assumptions regarding MIIT NEV credit quota enforcement consistency and NMPA GB standard implementation timelines. Periodic stress-testing of base assumptions against Jiangxi rare earth policy developments and domestic foundry capacity buildout is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Global Automotive Mats Market