
 France Automotive Hydraulic Actuators Market | 2026-2036
France Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Hydraulic Actuators Market Foresight
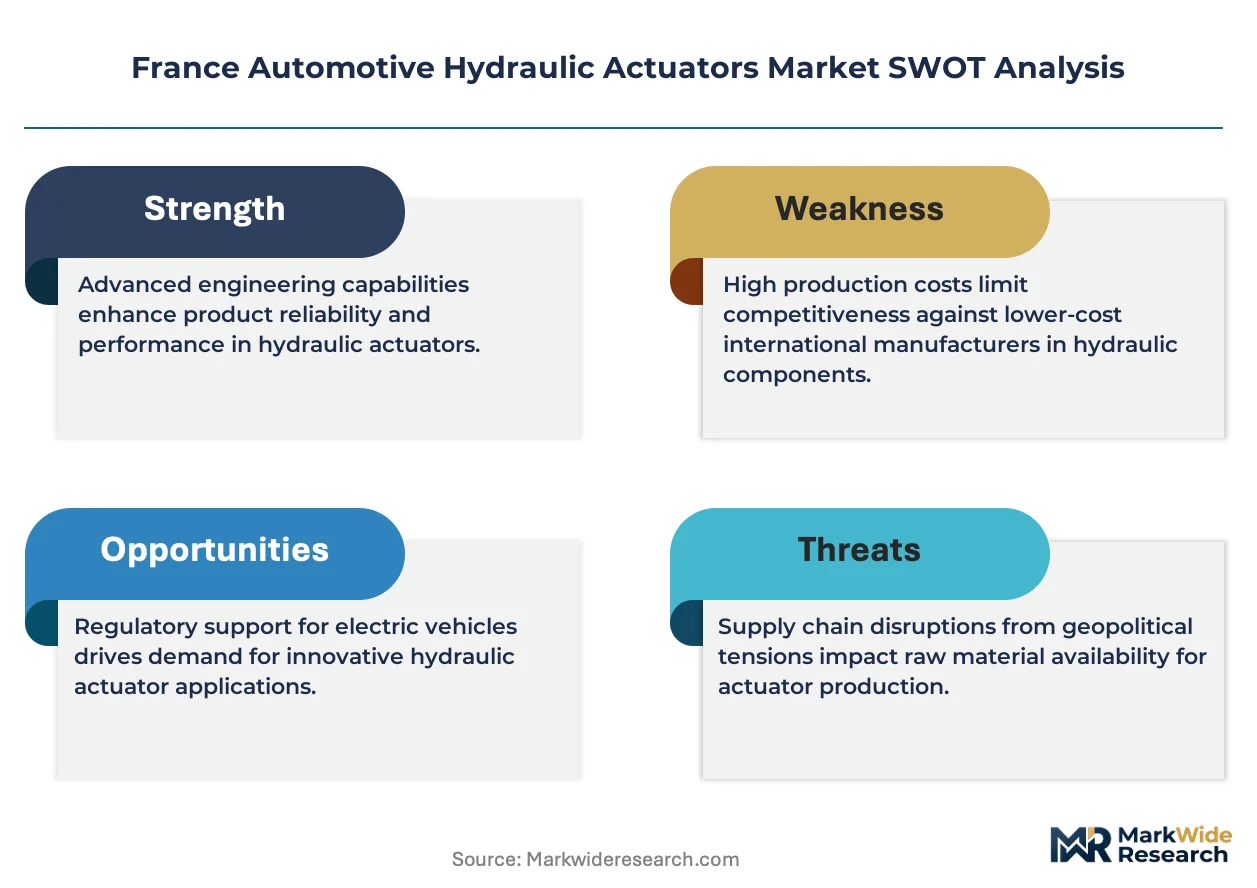
A shortage of precision fluid-power engineers is reorganizing how French suppliers staff their R&D centers and production lines. Continental AG sustains its position through captive testing facilities near Toulouse, while Robert Bosch GmbH leverages its Strasbourg engineering base to develop brake-system actuators for domestic OEMs. Sonceboz SA anchors its niche in proportional valve actuators for hybrid transmissions, competing directly with BorgWarner Inc's broader powertrain portfolio.
France automotive hydraulic actuators convert pressurized fluid energy into linear or rotary mechanical motion, typically operating at system pressures between 70 and 350 bar to control vehicle subsystems with millisecond response times. Their primary purpose is to deliver high force-to-weight actuation in safety-critical chassis and powertrain functions where electromagnetic alternatives lack torque density. Linear actuators dominate brake and steering applications due to their direct-force output and established fault-tolerance architectures, while servo actuators represent the fastest-growing technology category as drive-by-wire platforms replace mechanical linkages. Electro-hydraulic systems command the margin pool in premium vehicle segments, whereas fully hydraulic architectures retain cost advantages in commercial vehicle and heavy-duty applications where power demands exceed electric actuator limits.
France's national automotive regulator enforces type-approval standards aligned with EU MDR and CE marking requirements for hydraulic safety components, while ECHA's REACH framework restricts certain seal and coating chemistries used in actuator assemblies. The EU F-Gas Regulation pressures manufacturers to reformulate hydraulic fluids and redesign sealing systems to reduce greenhouse gas intensity across the vehicle lifecycle. Stakeholders must monitor how France's implementation of the EU AI Act intersects with autonomous braking and steering actuation algorithms, as software-validation requirements could reshape supplier qualification timelines and testing cost structures.
Market Dynamics
Fleet electrification across France is compressing development cycles for electro-hydraulic brake actuators, forcing Tier-1 suppliers to recalibrate R&D staffing and fluid-power architectures simultaneously.
Growth Catalysts
- EU F-Gas Regulation:France's national low-carbon mobility framework mandates reduced greenhouse gas intensity in hydraulic fluids, accelerating reformulation investments by domestic seal and coating suppliers.
- Paris-Saclay automotive cluster:Concentrated OEM procurement activity around this research corridor generates localized demand spikes for precision servo actuators in drive-by-wire platforms.
- Electro-hydraulic brake actuators:French OEMs expanding electric vehicle lineups require these components for regenerative braking integration, pulling volume from traditional hydraulic architectures.
Market Restraints
- Precision fluid-power engineer scarcity:French technical universities produce insufficient graduates with hybrid electromechanical-hydraulic expertise, inflating recruitment costs for R&D centers in Toulouse and Strasbourg.
- REACH-compliant seal chemistry constraints:ECHA restrictions on certain elastomer formulations limit supplier options for high-pressure actuator assemblies, compressing margin pools on legacy product lines.
- Electromagnetic actuator torque density improvements:Advances in motor-inverter integration threaten hydraulic solutions in sub-150 bar applications, displacing volume in light passenger segments.
Strategic Opportunities
- Rhône-Alpes manufacturing corridor expansion:Tier-1 suppliers co-locating with commercial vehicle assembly plants can capture heavy-duty actuator demand exceeding electric actuator power limits.
- EU AI Act software-validation requirements:Autonomous braking and steering algorithm mandates create qualification service revenue for suppliers with captive testing infrastructure.
- Hydraulic fluid recyclability mandates:France's implementation of circular economy principles in automotive supply chains rewards suppliers with closed-loop fluid recovery systems.
Industry Challenges
- Millisecond response time certification:ANSM and EU MDR-aligned type-approval standards for safety-critical chassis components extend validation timelines, delaying product launches.
- Legacy mechanical linkage integration:Drive-by-wire platforms require backward-compatible hydraulic architectures during transition periods, complicating production line configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Hydraulic Actuators Market |
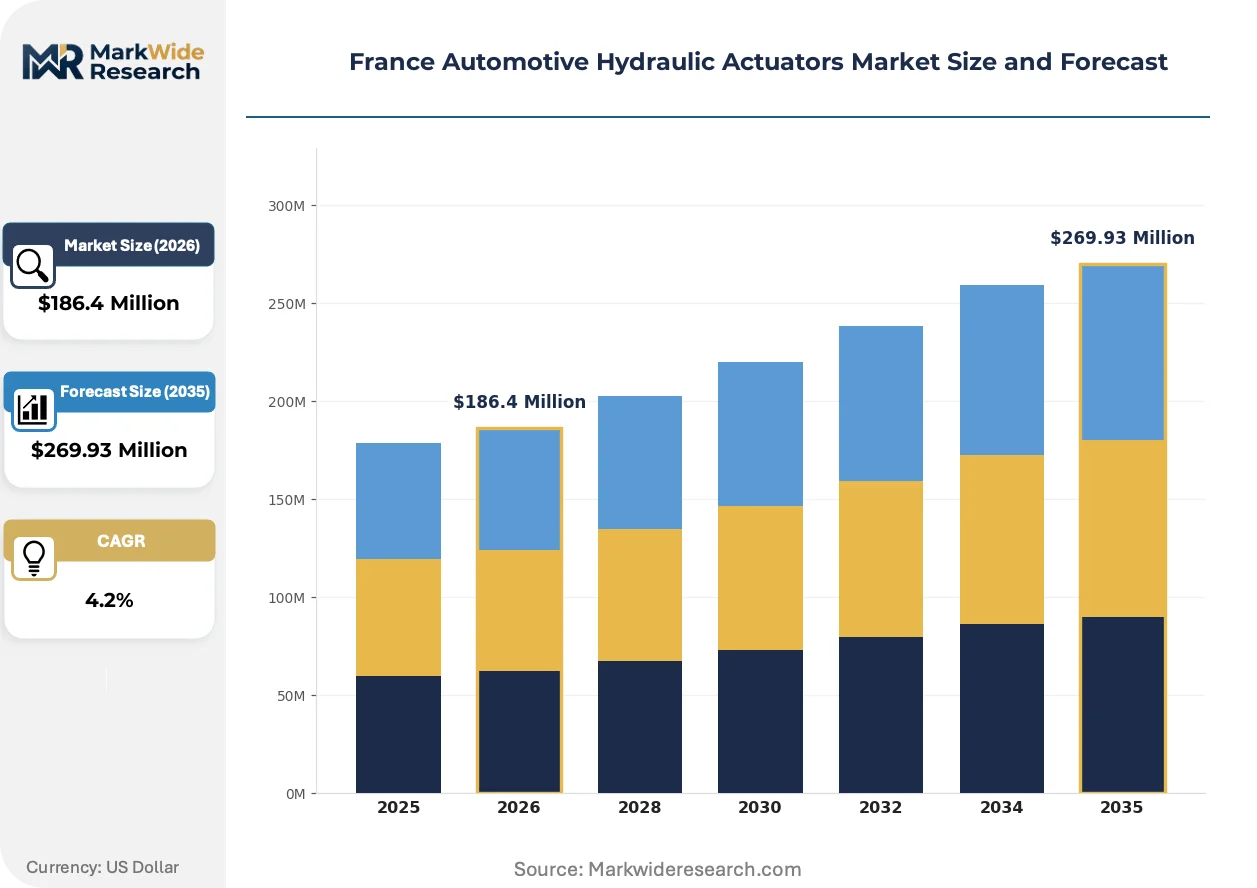
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $269.93 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Servo Actuators, Proportional Actuators Technology: Electro-Hydraulic, Hydro-Mechanical, Fully Hydraulic, Hybrid Hydraulic Application: Power Steering Systems, Brake Systems, Suspension Systems, Transmission Control End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Wabco Holdings Inc, Denso Corporation, Sonceboz SA, Hella KGaA Hueck & Co, Johnson Electric, BorgWarner Inc, CTS Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Hydraulic Actuators Market Shifts & Advancements
Actuator technology trajectories in France are diverging between premium electro-hydraulic integration and cost-optimized fully hydraulic retention, with regulatory chemistry mandates forcing parallel development tracks.
Proportional valve architectures for hybrid transmissions are fragmenting the servo actuator category. Sonceboz SA and competing specialists are deploying these components for seamless torque handoff between electric and combustion powertrains. French OEMs adopting 48V mild-hybrid systems are pulling adoption curves forward, compressing the addressable market for conventional on-off valve designs.
France's national automotive regulator enforces type-approval standards aligned with EU MDR and CE marking requirements. ECHA's REACH framework restricts specific seal and coating chemistries, compelling reformulation of elastomer compounds in actuator assemblies. The Rhône-Alpes manufacturing corridor bears the highest compliance cost concentration due to its density of hydraulic component production.
French OEM procurement of brake-system actuators is consolidating around electro-hydraulic platforms as fleet electrification accelerates. Tier-1 suppliers with captive testing facilities near Toulouse capture preferential qualification slots, displacing competitors dependent on third-party validation. This pattern concentrates sourcing decisions within the Paris-Saclay automotive cluster, compressing supplier diversity in safety-critical chassis procurement.
France Automotive Hydraulic Actuators Market Segmentation
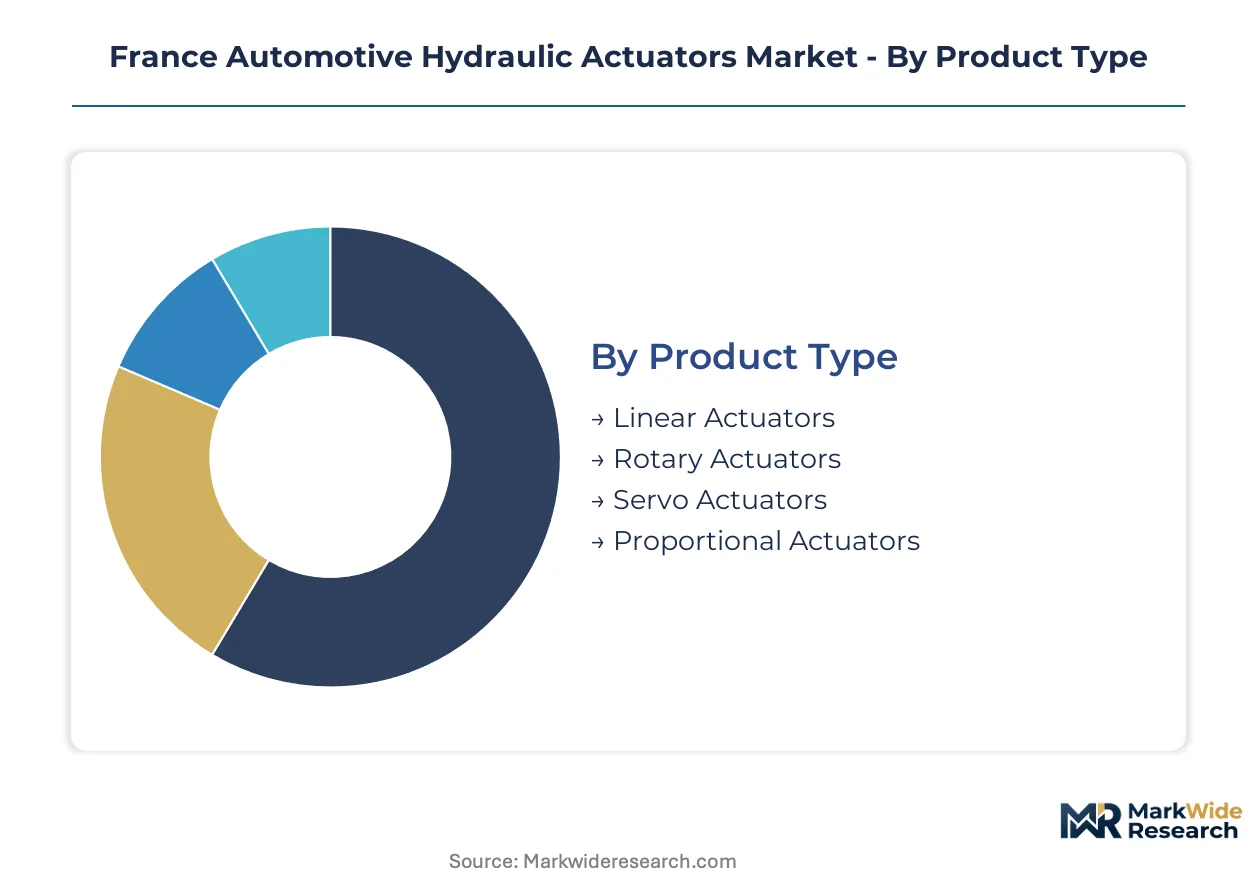
Segmentation in France's automotive hydraulic actuators market reveals how procurement channels, technology maturity, and regulatory pressure intersect. Distinct buyer behaviors across OEMs, Tier-1 suppliers, and aftermarket channels reshape volume distribution and margin capture for each product category.
Product Type:
Channel flow varies sharply: linear actuators move primarily through captive Tier-1 supply agreements to vehicle assemblers, while servo and proportional types concentrate in direct OEM procurement for drive-by-wire development programs.
- Linear Actuators:These devices convert hydraulic pressure into straight-line mechanical force through piston-cylinder architectures, typically rated for 200-350 bar operating pressures. Demand clusters around brake caliper and clutch release applications in the Rhône-Alpes manufacturing corridor, where heavy-duty vehicle assembly plants require fault-tolerant force transmission. ECHA REACH compliance costs for high-pressure seal formulations compress margins on legacy production lines.
- Servo Actuators:Closed-loop position control systems integrate proportional valves with feedback sensors for sub-millimeter accuracy. French OEM procurement for steer-by-wire platforms concentrates around the Paris-Saclay automotive cluster, pulling volume from mechanical alternatives as the EU AI Act tightens software-validation requirements for autonomous chassis functions.
- Rotary Actuators:Vane and gear-type designs deliver torque output for transmission selector mechanisms and throttle control.
- Proportional Actuators:Variable-flow valve systems enable smooth pressure modulation for hybrid transmission torque blending.
By volume, linear actuators lead. By growth pace, servo actuators are gaining share fastest.
Technology:
Cost tier stratification separates premium electro-hydraulic integration from commodity fully hydraulic retention, with hybrid architectures capturing mid-tier positioning for fleet electrification transitions.
- Electro-Hydraulic:Systems combining electric motor control with hydraulic power amplification dominate regenerative braking integration for French electric vehicle platforms. ANSM type-approval timelines for safety-critical chassis components extend validation cycles, favoring suppliers with captive testing infrastructure near Toulouse.
- Fully Hydraulic:Conventional pump-valve-cylinder architectures retain cost advantages in commercial vehicle applications exceeding 250 bar pressure demands. The Rhône-Alpes corridor sustains production concentration for heavy-duty lineups where electric actuator torque density falls short.
- Hydro-Mechanical:Mechanical feedback linkages with hydraulic assist persist in economy passenger segments.
- Hybrid Hydraulic:Dual-mode systems switch between electric and hydraulic power sources based on load conditions.
Electro-hydraulic systems command the premium tier. Hybrid hydraulic architectures are expanding most quickly as OEMs bridge electrification transitions.
Application:
Customer type fragmentation separates safety-critical chassis functions requiring ANSM certification from powertrain applications governed by EU MDR-aligned quality standards.
- Brake Systems:Electro-hydraulic actuation enables regenerative energy recovery while maintaining mechanical backup for fail-safe operation. French OEM procurement concentrates in the Paris-Saclay cluster for electric vehicle platform integration, where millisecond response certification under EU MDR extends supplier qualification timelines.
- Power Steering Systems:Rack-and-pinion hydraulic assist persists in commercial vehicle segments, with demand anchored in the Rhône-Alpes corridor where heavy-duty assembly plants require high steering torque capacity.
- Suspension Systems:Active damping actuators adjust ride height and stiffness in real-time.
- Transmission Control:Clutch and gear selector actuation manages torque transfer in automated manual and dual-clutch architectures.
Brake systems generate the highest unit values. Suspension systems are climbing the fastest as premium OEMs adopt active chassis technology.
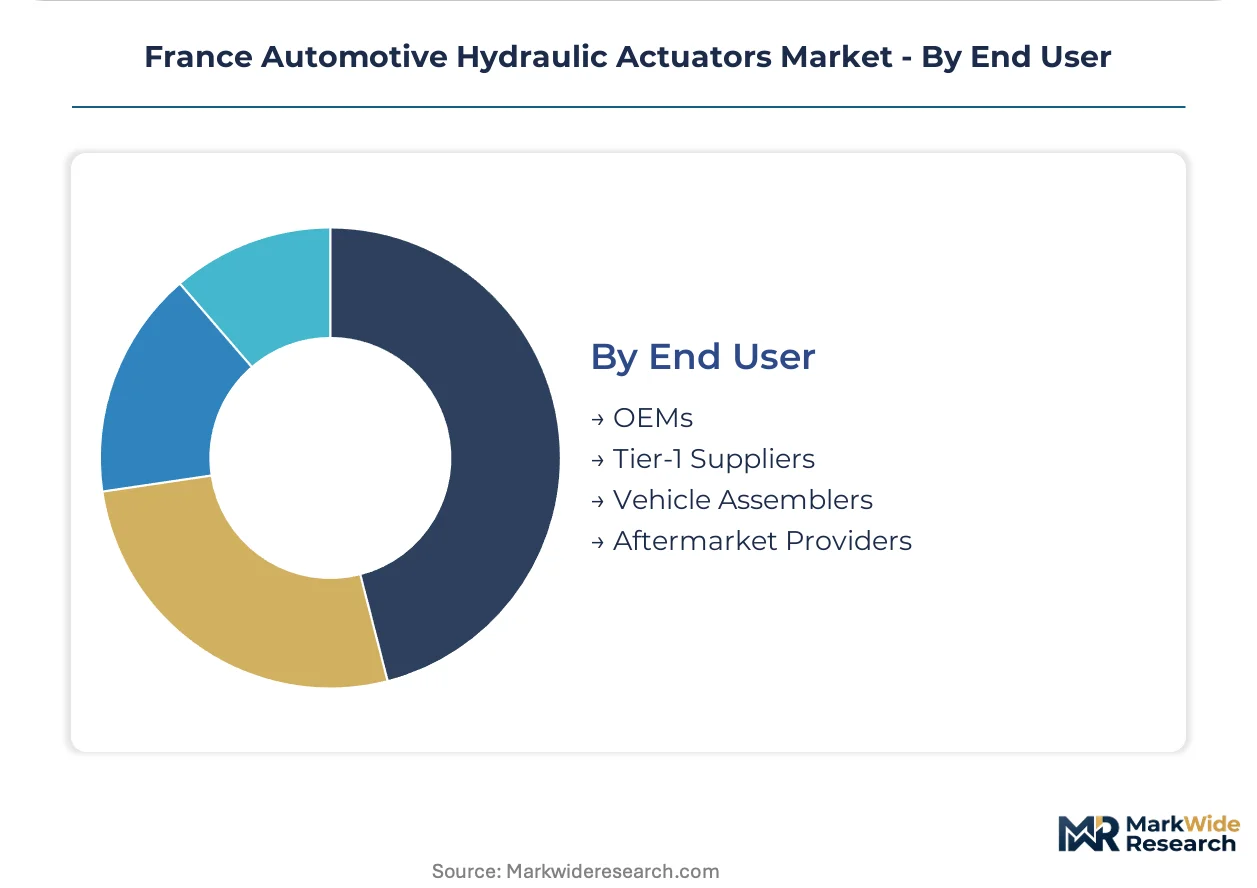
End User:
Supply concentration shapes access patterns: Tier-1 suppliers with co-located production capture OEM direct contracts, while aftermarket providers serve legacy fleet maintenance through independent distribution networks.
- OEMs:Direct procurement of electro-hydraulic brake and steering actuators for electric vehicle platforms concentrates in the Paris-Saclay automotive cluster. France's national low-carbon mobility framework mandates greenhouse gas intensity reductions that reshape hydraulic fluid specifications and supplier qualification criteria.
- Tier-1 Suppliers:Captive production of linear actuators for brake and transmission applications clusters in the Rhône-Alpes manufacturing corridor. ECHA REACH restrictions on seal chemistry formulations force reformulation investments that disadvantage smaller competitors.
- Vehicle Assemblers:Final integration of hydraulic subsystems into complete vehicle architectures.
- Aftermarket Providers:Replacement part distribution for legacy hydraulic systems in existing vehicle fleets.
Tier-1 suppliers dominate production volume. OEMs are driving the steepest expansion trajectory through direct procurement of electrified chassis systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM and ECHA REACH regulations anchor France's automotive hydraulic actuator governance, with sub-regional clusters responding to distinct electrification timelines and industrial specialization patterns.
Île-de-France
Paris-Saclay automotive cluster procurement concentrates electro-hydraulic brake actuator demand for electric vehicle platforms. France's national low-carbon mobility framework mandates greenhouse gas intensity reductions in hydraulic fluids. OEM engineering centers in this region pull volume from traditional hydraulic architectures as regenerative braking integration accelerates.
Auvergne-Rhône-Alpes
Heavy-duty commercial vehicle assembly sustains fully hydraulic actuator demand exceeding 250 bar pressure ratings. The EU F-Gas Regulation pressures manufacturers to reformulate sealing systems for reduced lifecycle emissions. Tier-1 suppliers co-locate production with Stellantis and Renault commercial plants in Lyon-Grenoble corridor, capturing cost advantages in torque-dense applications.
Provence-Alpes-Côte d'Azur
Maritime and defense adjacent manufacturing diversifies actuator demand beyond passenger automotive. ECHA REACH restrictions on seal chemistry formulations force reformulation investments among specialty suppliers. Toulouse-area captive testing facilities serve ANSM type-approval requirements for safety-critical chassis components.
Hauts-de-France
Legacy automotive supplier networks transition hydraulic component production toward electrification-compatible architectures. France's implementation of EU AI Act software-validation requirements reshapes supplier qualification timelines for autonomous braking systems. Lille-Roubaix manufacturing belt concentrates aftermarket distribution for existing hydraulic fleets.
Nouvelle-Aquitaine
Aerospace supply chain spillover creates precision machining capacity transferable to automotive actuator components. Circular economy principles in automotive supply chains reward closed-loop fluid recovery system investments. Bordeaux-Toulouse corridor hosts emerging suppliers targeting REACH-compliant elastomer formulation gaps.
France Automotive Hydraulic Actuators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive testing infrastructure and direct OEM relationships determining access to premium procurement channels. Continental AG and Robert Bosch GmbH anchor the upper tier through co-located engineering and validation assets. Mid-scale specialists compete on proportional valve architectures for hybrid transmission applications. Consolidation pressures concentrate around electro-hydraulic brake system qualification slots, while backward integration into seal chemistry production emerges as a margin defense mechanism.
Within the integrated tier, Continental AG and Robert Bosch GmbH exemplify captive infrastructure strategies, with testing facilities anchoring preferential access to Paris-Saclay OEM engineering centers. Sonceboz SA occupies a specialist position in proportional valve actuation, representing the mid-tier archetype competing through hybrid transmission torque-blending expertise. These three entities collectively illustrate how vertical integration depth, geographic proximity to decision-making clusters, and regulatory compliance infrastructure partition competitive access across France's automotive hydraulic actuator procurement landscape.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Wabco Holdings Inc |
| Denso Corporation |
| Sonceboz SA |
| Hella KGaA Hueck & Co |
| Johnson Electric |
| BorgWarner Inc |
| CTS Corporation |
| Others |
Supply & Pricing Matrix
Eighteen-week lead times for REACH-compliant elastomer compounds concentrate pricing power among seal chemistry suppliers with captive formulation labs, compressing margins for actuator assemblers lacking backward integration into polymer production. This inventory pressure stratifies procurement costs across the Paris-Saclay and Rhône-Alpes clusters, where OEM direct contracts command premium positioning against aftermarket channels.
Pricing Analysis
Electro-hydraulic brake actuators trade at 40-60 percent premiums over fully hydraulic equivalents in the Paris-Saclay corridor, with ANSM certification grade and regenerative braking integration complexity driving price differentiation. Cost compression in standard linear actuator tiers intensifies as Tier-1 suppliers consolidate volume around captive testing facilities. Aftermarket providers serving legacy fleets exhibit highest price sensitivity, while OEM platform engineering teams prioritize millisecond-response certification over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision valve and sensor production for French electro-hydraulic systems, with China supplying machined aluminum castings and steel piston rods. The supply chain draws from specialty polymer producers in Belgium and the Netherlands for REACH-compliant seal formulations. Single-source vulnerability concentrates in high-pressure proportional valve spools, where two European specialists control precision grinding capacity. Distribution runs through Tier-1 supplier hubs co-located with Stellantis and Renault assembly plants, with aftermarket channels feeding through independent distributors in the Lille-Roubaix belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's automotive hydraulic actuator market sits at a platform-economics inflection where drive-by-wire architectures are decoupling hardware procurement from software validation services, creating new interoperability revenue pools around EU AI Act compliance infrastructure.
For Market Incumbents: Fortify captive testing infrastructure near Toulouse to capture preferential ANSM qualification slots as software-validation timelines extend. Deepen backward integration into REACH-compliant elastomer formulation to defend margin position against seal chemistry cost inflation. Electromagnetic actuator torque density improvements in sub-150 bar applications threaten volume retention in light passenger segments. For New Entrants and Emerging Players: Lead with closed-loop fluid recovery systems targeting France's circular economy mandates in hydraulic fluid recyclability. The Rhône-Alpes heavy-duty corridor offers most penetrable white space, where 250-plus bar pressure demands exceed electric actuator limits. Position through direct OEM engineering partnerships for 48V mild-hybrid transmission torque-blending applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electro-hydraulic brake system qualification as ANSM type-approval timelines lengthen. Long-term viability over the next decade hinges on software-validation service attach rates rather than hardware shipment volumes. Acquire specialists with captive polymer formulation labs and Toulouse-area testing assets. Watch for EU AI Act implementation deadlines as inflection signals for qualification service pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Facility Expansion | ANSM qualification slots near Toulouse concentrate preferential OEM access for brake-system actuators. |
| REACH-Compliant Seal Chemistry Integration | In-house elastomer formulation defends margins against ECHA restriction-driven input cost volatility. |
| Software-Validation Service Development | EU AI Act autonomous braking mandates create recurring revenue streams alongside hardware sales. |
| Rhône-Alpes Manufacturing Footprint | Co-location with Stellantis and Renault commercial plants captures heavy-duty actuator demand. |
| Closed-Loop Fluid Recovery Systems | France's circular economy principles reward suppliers with lifecycle fluid management capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, ECHA REACH substance restrictions, and EU F-Gas Regulation implementation guidance. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and ANSM regulatory affairs specialists informed demand-side validation. Bottom-up actuator shipment estimates triangulated against top-down French vehicle assembly projections across the analysis window.
Segmentation dimensions modeled span product type, technology architecture, application function, and end-user channel across vehicle class, propulsion architecture, and regional production cluster. CAGRs derived from regression analysis of historical procurement patterns and electrification transition timelines. Forecast inputs incorporated OEM electrification platform rollouts, ECHA restriction amendment schedules, and EU AI Act software-validation requirement phasing.
Forecasts assume regulatory continuity in EU REACH, F-Gas, and AI Act implementation; material policy shifts in seal chemistry restrictions or autonomous vehicle liability frameworks would require re-modeling. Recalibration cycles align with material shifts in fleet electrification penetration, ANSM type-approval procedural updates, and electromagnetic actuator torque density benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Automotive Steel Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Automotive Electric Drivetrain Components Market