
 Automotive HVAC Ducts Market | 2026-2036
Automotive HVAC Ducts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive HVAC Ducts Market Outlook
Buyer concentration among electric vehicle OEMs is expanding as legacy automakers and dedicated EV producers consolidate supplier rosters for thermal management systems. Hanon Systems leverages its integrated climate solutions portfolio to anchor contracts with premium EV platforms. MAHLE GmbH sustains engineering intensity across aluminum and composite duct architectures for hybrid powertrains. Denso Corporation competes through in-house production of blowers, compressors, and ducting modules that reduce interface complexity for vehicle assemblers.
Automotive HVAC ducts are engineered air distribution channels, typically blow-molded from polypropylene or thermoformed from aluminum sheet, designed to route conditioned air from climate units to cabin zones with specified pressure drop and acoustic targets. Plastic ducts dominate passenger vehicle applications due to weight savings and corrosion resistance, while aluminum retains share in commercial vehicles where thermal durability and fire resistance command priority. Electric vehicle applications represent the fastest-growing segment as battery thermal management demands additional cooling loops and cabin conditioning circuits that multiply duct count per vehicle.
The EPA enforces Corporate Average Fuel Economy standards that penalize vehicle weight, pushing OEMs toward polymer-based duct solutions that trim mass versus metal alternatives. The EU F-Gas Regulation and REACH framework restrict refrigerant global warming potential and mandate material disclosure for plastic additives, compelling suppliers to reformulate compounds and validate new chemistries. Stakeholders must monitor how battery-electric platform architectures reshape duct routing complexity and whether thermal integration with battery cooling consolidates or fragments supplier tiers.
Market Dynamics
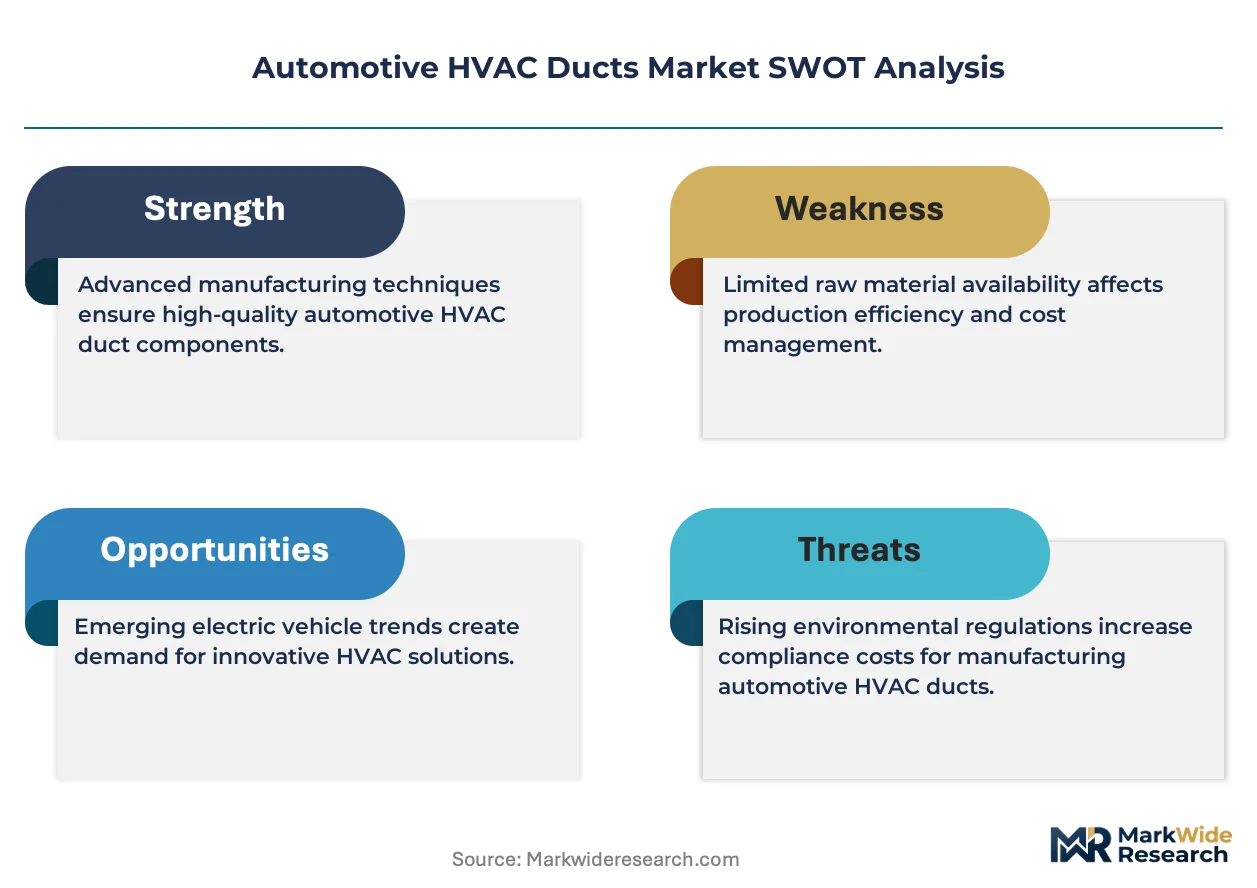
Electric vehicle platform architectures are multiplying cooling loop complexity per vehicle, forcing duct suppliers to engineer modular systems that bridge cabin climate control with battery thermal management circuits.
Growth Catalysts
- Battery-electric powertrain proliferation:Each EV carries separate conditioning circuits for cabin, battery, and power electronics, tripling duct count versus internal combustion architectures.
- EPA Corporate Average Fuel Economy standards:Weight-based penalties push OEMs toward polymer ducts that trim kilograms versus aluminum alternatives in passenger vehicle segments.
- China's dual carbon goals:Domestic EV production quotas accelerate procurement of lightweight thermal management components across NEV platforms.
Market Restraints
- Polypropylene resin price volatility:Propylene feedstock fluctuations compress margin buffers for blow-molded duct manufacturers locked into annual OEM contracts.
- REACH additive disclosure mandates:EU chemical registration requirements force reformulation of flame-retardant plastic compounds, extending validation timelines.
- Aluminum sheet substitution threat:Commercial vehicle segments retain metal duct preference for fire resistance, capping polymer penetration in heavy-duty applications.
Strategic Opportunities
- India PLI scheme for automotive components:Production-linked incentives attract duct manufacturing capacity to serve domestic EV assembly expansion.
- Thermal integration convergence:Heat pump and battery cooling circuit unification creates demand for multi-port distribution manifolds with integrated valves.
- Direct OEM supply contracts:Tier 1 suppliers bypass traditional HVAC system integrators to capture module-level procurement decisions on dedicated EV platforms.
Industry Challenges
- CAE simulation talent scarcity:Computational fluid dynamics expertise for pressure drop and acoustic optimization outpaces vocational training pipeline output.
- Multi-material bonding validation:Polymer-to-aluminum interface testing for hybrid duct architectures extends prototype-to-production cycles.
- Legacy tooling amortization:Existing blow-molding equipment for single-material ducts resists retooling for multi-layer barrier constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive HVAC Ducts Market |
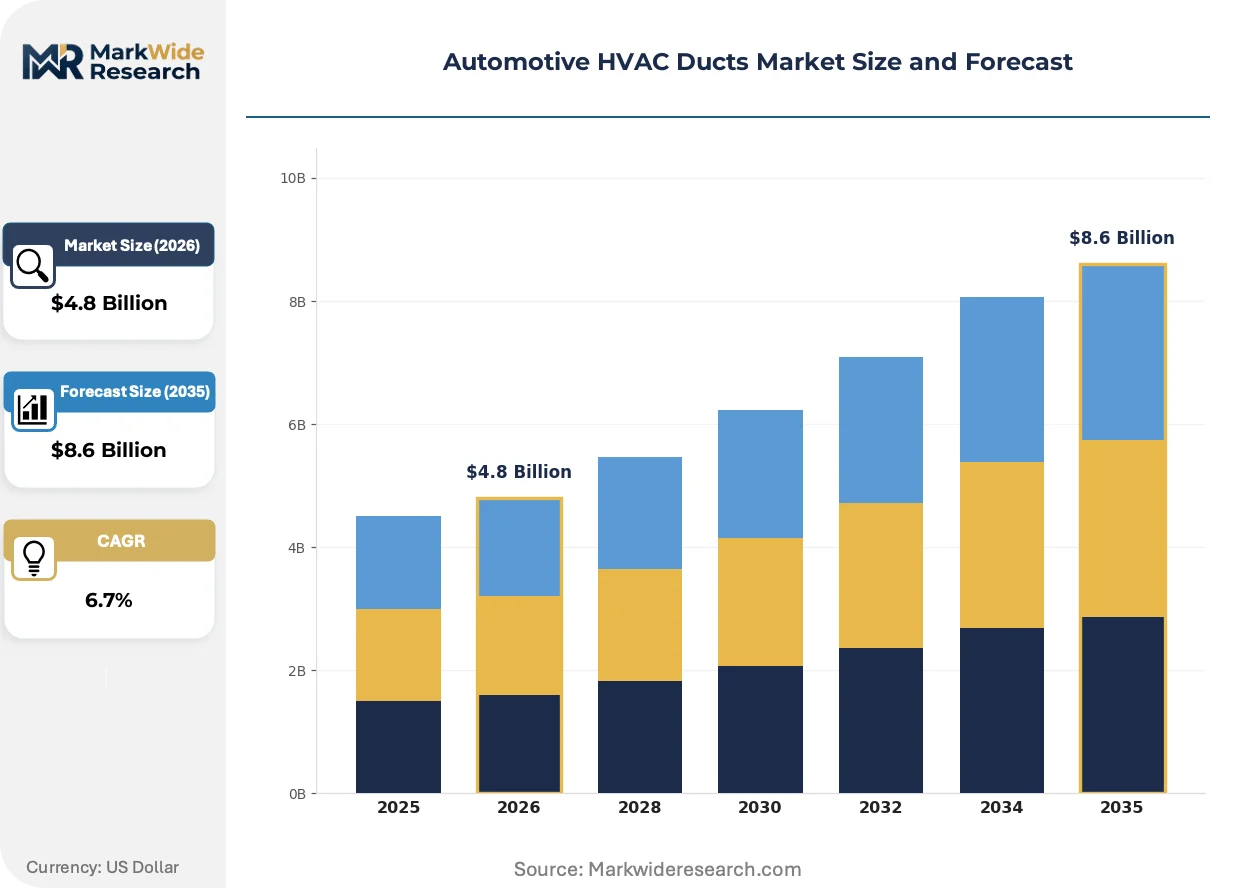
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Steel, Composite Product Design: Round, Rectangular, Oval, Custom End User: OEMs, Aftermarket, Tier-1 Suppliers, Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Others |
| Companies Covered | Hanon Systems, Sogefi Group, MAHLE GmbH, Kyoraku Co. Ltd, INOAC Corporation, Denso Corporation, MANN + HUMMEL Holding GmbH, Mergon International, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive HVAC Ducts Market Strategic Shifts
Material science advances and regulatory chemistry mandates are compressing traditional duct design cycles while enabling thermal management integration previously impractical with legacy architectures.
Multi-layer co-extruded barrier ducts are integrating ethylene vinyl alcohol interlayers to prevent refrigerant permeation through polypropylene walls. European EV platforms are adopting these constructions fastest, driven by F-Gas Regulation leakage thresholds. This material architecture is integrating battery cooling and cabin conditioning into single distribution modules, reducing part count and assembly labor.
The EU F-Gas Regulation is tightening refrigerant global warming potential limits, compelling suppliers to validate new barrier materials against alternative chemistries. OEMs must recertify entire thermal systems when switching refrigerants, creating specification lock-in for duct vendors who complete validation first. Premium EV segments in Germany and the Netherlands are absorbing these compliance costs fastest, while mass-market platforms delay transitions.
Consolidated supplier rosters are compressing procurement decisions toward module-level integrators capable of delivering complete thermal management circuits. Dedicated EV manufacturers are bypassing traditional Tier 2 duct specialists to source directly from climate system architects. This pattern concentrates most visibly in China, where vertical OEMs like BYD and NIO internalize thermal engineering and externalize only commodity extrusion.
Automotive HVAC Ducts Market Segmentation
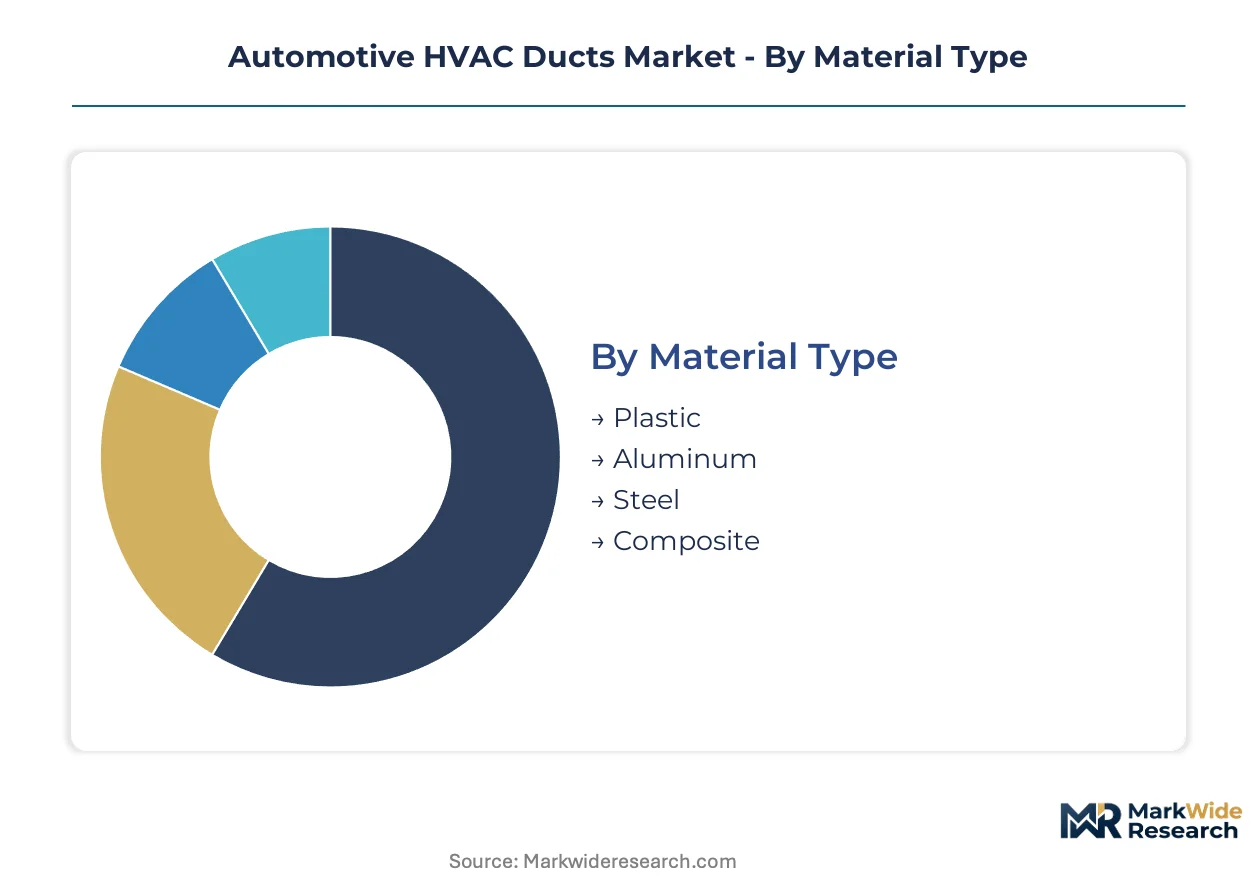
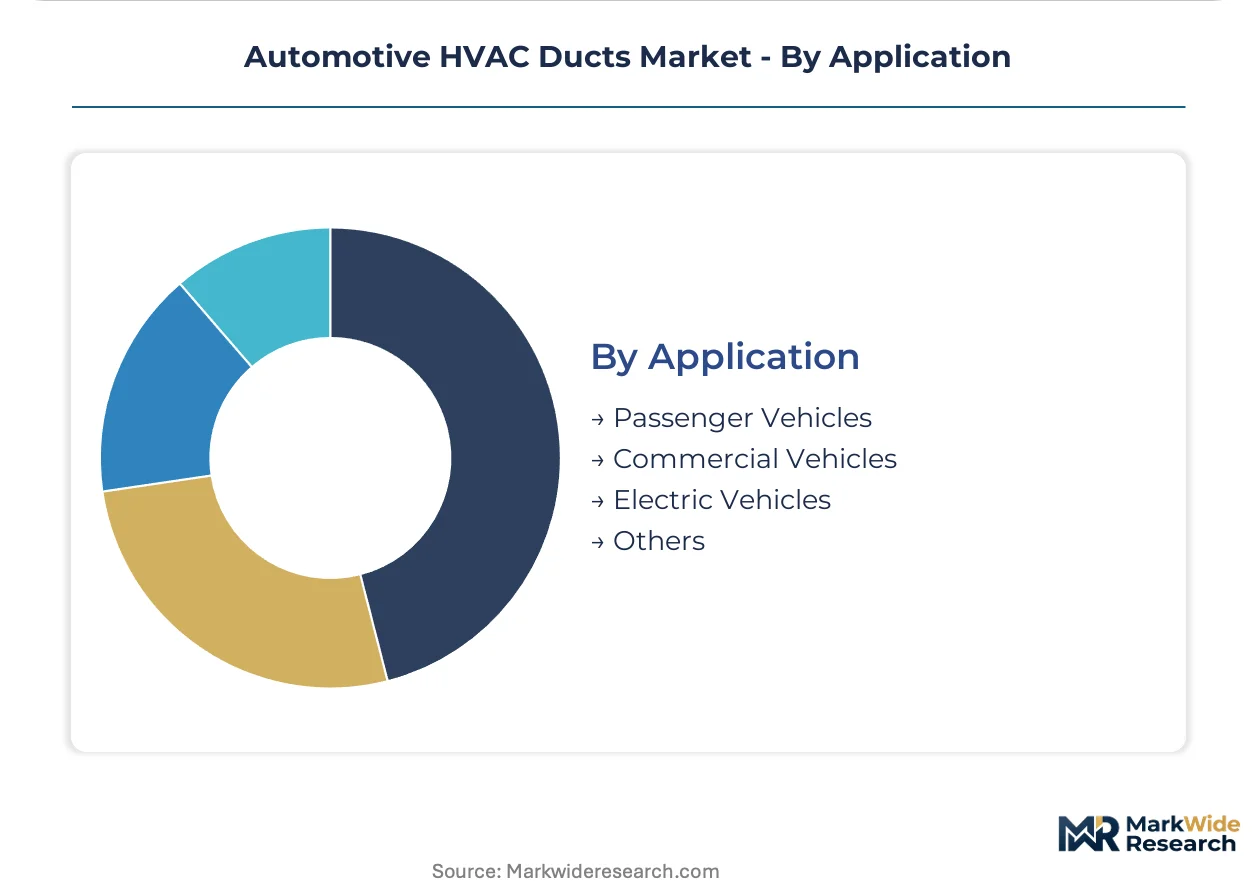
Segmentation in automotive HVAC ducts reflects divergent engineering priorities across thermal management architectures. Material selection and geometric design determine weight, permeation resistance, and routing flexibility in increasingly complex EV platforms. Procurement channels and vehicle applications further stratify supplier relationships and margin structures.
Material Type:
Standardization dominates commodity grades while specialized compounds command premium positioning for barrier performance and fire-rated applications.
- Plastic:Polypropylene blow-molded ducts deliver corrosion resistance and acoustic damping for passenger cabin distribution. OEMs in China and Germany specify these for battery-electric platforms where every kilogram affects range certification under EPA fuel-economy standards.
- Aluminum:Sheet-formed and welded aluminum architectures withstand elevated temperatures in commercial vehicle engine bays and battery cooling loops. Heavy-duty OEMs retain metal preference where fire resistance mandates override weight considerations.
- Steel:Galvanized steel ducts persist in legacy commercial vehicle platforms and aftermarket replacement channels.
- Composite:Glass-reinforced polymer and hybrid constructions bridge weight and thermal durability for hybrid powertrain applications.
Most installed capacity flows through Plastic. Expansion is steepest in Composite.
Product Design:
Volume manufacturing favors simple extrusions while integrated thermal modules demand complex geometries with embedded valve ports and sensor mounting points.
- Round:Circular cross-sections minimize pressure drop and simplify blow-molding tooling for high-volume passenger vehicle lines. These dominate standard cabin distribution where space constraints allow radial routing.
- Rectangular:Flat profiles maximize packaging efficiency beneath instrument panels and seat structures. EV platforms in the United States specify these for battery pack cooling circuits where height clearance is limited.
- Oval:Hybrid geometries balance flow efficiency with spatial constraints in compact vehicle architectures.
- Custom:Application-specific designs integrate multi-port manifolds, valve housings, and sensor bosses for unified thermal management modules.
Round geometries retain the largest production footprint. Custom designs are climbing the fastest as EV thermal integration advances.
End User:
Direct OEM relationships concentrate engineering control while aftermarket channels fragment across distributor networks and service chains.
- OEMs:Vehicle manufacturers specify duct architectures during platform development, locking in material and geometric standards for production runs. BYD and NIO internalize thermal engineering decisions while externalizing commodity extrusion.
- Aftermarket:Replacement ducts serve collision repair and aging vehicle refurbishment through independent distributors.
- Tier-1 Suppliers:Climate system integrators like Hanon Systems and MAHLE consolidate procurement decisions for legacy automaker platforms.
- Assemblers:Contract manufacturers execute final duct-to-HVAC unit assembly for OEMs with limited in-house thermal capacity.
OEM direct contracts capture the greatest engineering value. Aftermarket channels show the steepest volume expansion in aging vehicle populations.
Application:
Passenger vehicle standardization contrasts with commercial vehicle durability requirements and electric vehicle thermal complexity multiplication.
- Passenger Vehicles:Cabin-focused climate systems prioritize acoustic comfort and aesthetic integration. Polypropylene ducts dominate this segment where corrosion resistance and cost efficiency align with high-volume production economics.
- Electric Vehicles:Battery, power electronics, and cabin conditioning circuits triple duct count per vehicle versus internal combustion architectures. China's NEV production quotas accelerate procurement of lightweight thermal management components for these platforms.
- Commercial Vehicles:Engine proximity and fire safety regulations sustain aluminum and steel preferences in heavy-duty applications.
- Others:Specialty vehicle and off-highway equipment applications demand application-specific thermal routing solutions.
Passenger Vehicles maintain the largest installed base. Electric Vehicles are gaining share fastest as production lines scale across China, Germany, and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China scales EV thermal management capacity faster than Germany retools legacy combustion platforms, creating divergent procurement patterns for duct suppliers across both markets.
China
NEV production quotas under dual carbon goals multiply cooling circuit complexity per vehicle. MIIT mandates accelerate lightweight component adoption across battery-electric platforms. Shanghai and Shenzhen anchor manufacturing clusters where BYD and NIO internalize thermal engineering while externalizing commodity extrusion.
Germany
Premium EV segments absorb compliance costs for F-Gas Regulation refrigerant transitions fastest. KBA certification requirements lock in validated duct specifications for multi-year platform cycles. Stuttgart and Munich concentrate development engineering for integrated climate modules serving Volkswagen Group and BMW architectures.
United States
EPA Corporate Average Fuel Economy penalties push Detroit Three toward polymer duct solutions. IRA domestic content provisions reshape supplier qualification for battery-electric platforms. Michigan and Ohio retain tooling concentration despite southern state assembly migration.
Japan
Hybrid powertrain thermal architectures sustain demand for aluminum-composite hybrid duct constructions. METI efficiency standards pressure suppliers to reduce mass without sacrificing durability. Nagoya and Toyota City clusters specialize in precision-formed aluminum sheet for thermal durability applications.
India
PLI scheme for automotive components attracts blow-molding capacity to serve domestic EV assembly expansion. BIS quality mandates extend validation timelines for imported resin compounds. Tamil Nadu and Gujarat host emerging supplier parks adjacent to Tata Motors and Mahindra Electric production lines.
Automotive HVAC Ducts Market Competitive Environment
East Asian producers anchor the scale tier; European specialists hold premium integration positions. The market structures around three supplier archetypes: integrated climate system architects, modular duct specialists, and commodity extrusion contractors. Consolidation pressures intensify as OEM procurement shifts from component sourcing to thermal circuit procurement. Capacity expansion and backward integration into resin compounding represent dominant competitive vectors.
Among Korean fabricators, Hanon Systems occupies a position exemplifying integrated climate portfolio breadth. MAHLE GmbH anchors German engineering-intensive positioning across material architectures. Denso Corporation represents Japanese in-house production depth spanning blowers through distribution modules.
| Leading Market Players |
|---|
| Hanon Systems |
| Sogefi Group |
| MAHLE GmbH |
| Kyoraku Co. Ltd |
| INOAC Corporation |
| Denso Corporation |
| MANN + HUMMEL Holding GmbH |
| Mergon International |
| Valeo SA |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap compounders in Germany and Japan anchor resin supply for blow-molded ducts, translating feedstock cost discipline into stable contract pricing for OEM thermal platforms. Their long-tenured supplier relationships limit spot-market arbitrage, compressing margin volatility for duct manufacturers locked into annual vehicle program commitments.
Pricing Analysis
Capacity additions in China are reshaping price floors for polypropylene-based duct systems as domestic resin compounding scales to serve NEV production quotas. Three-tier pricing structure across premium, standard, and economy levels separates validated barrier-grade ducts for EU F-Gas compliance from commodity cabin distribution lines. Cost compression in standard-grade segments is intensifying because annual OEM contract structures prevent pass-through of propylene feedstock spikes. Mass-market EV platforms in China exhibit highest price sensitivity, while premium German OEMs absorb compliance premiums for multi-layer barrier constructions.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Japanese resin compounders who dominate flame-retardant polypropylene formulations for battery-thermal applications. Raw material flows draw from Saudi Arabian propylene feedstock, German additive packages, and Chinese masterbatch production. Tariff exposure on aluminum sheet imports threatens hybrid duct architectures for commercial vehicle segments. Distribution runs through Tier 1 climate system integrators who consolidate procurement decisions for legacy automaker platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards suppliers who capture thermal integration complexity as a margin-expansion vector, with battery-electric platform proliferation creating premium-tier specification pull-through.
For Market Incumbents: Anticipate specification lock-in from early F-Gas Regulation validation as a defensive moat against Chinese resin compounders entering European supply chains. Deepen backward integration into EVOH barrier film production to capture value migrating from commodity extrusion toward integrated thermal modules. Prioritize CAE simulation talent acquisition in Stuttgart and Shanghai engineering clusters before vocational pipeline shortages harden. For New Entrants and Emerging Players: Direct-to-OEM digital procurement portals offer the lowest-friction entry path for modular duct specialists bypassing legacy Tier 1 integrators. Target India's PLI scheme beneficiary OEMs—Tata Motors and Mahindra Electric—as the most penetrable demand pool with limited incumbent thermal engineering presence. Lead with rapid prototyping services for custom manifold geometries rather than competing on commodity round-duct volumes. For Investors and Strategic Acquirers: Climate system architects with battery-thermal validation completion are the most active acquirer in this space, consolidating module-level procurement decisions. Five-to-ten year viability hinges on heat-pump integration capabilities that unify cabin and battery cooling circuits. Watch for MIIT mandates expanding beyond NEV quotas into specific thermal component localization requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Material Validation | Early F-Gas Regulation compliance locks in multi-year OEM specification cycles for European EV platforms. |
| CAE Simulation Talent Acquisition | Computational fluid dynamics expertise scarcity in Stuttgart and Shanghai clusters commands premium compensation. |
| Backward Integration into Resin Compounding | In-house additive formulation shortens REACH disclosure timelines and protects margin from propylene volatility. |
| Direct OEM Supply Contracting | Bypassing Tier 1 climate integrators captures module-level procurement decisions on dedicated EV architectures. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract blow-molding capacity adjacent to Tata Motors and Mahindra Electric assembly lines. |
Study Parameters
Multiple input streams—primary interviews with OEM platform engineers and Tier 1 procurement leads, trade data reconciliation, and patent filing analysis—were reconciled to construct segment-level demand estimates. Stakeholder consultations encompassed thermal management directors at vehicle manufacturers, blow-molding equipment suppliers, and resin compounders across China, Germany, and the United States. Secondary validation drew from EPA fuel-economy certification databases, EU F-Gas Regulation implementation reports, and MIIT NEV production statistics. Bottom-up vehicle content modeling and top-down thermal system spending triangulation anchored value projections.
Data-stream reconciliation across material-grade splits, propulsion architecture transitions, and regional production clusters shaped the analytical framework across the analysis window. Segmentation dimensions modeled included vehicle class, thermal circuit complexity, and OEM tier positioning. CAGRs were derived from installed base turnover rates and content-per-vehicle expansion trajectories. Forecast inputs incorporated battery-electric platform ramp schedules, REACH additive disclosure timelines, and aluminum-polypropylene substitution elasticities in commercial vehicle segments.
The model assumes a particular technology adoption path; alternative pathways for heat-pump thermal integration would alter the outlook if battery cooling unification accelerates faster than projected. Forecasts reflect assumptions regarding NEV quota enforcement stringency, propylene feedstock price normalization, and F-Gas Regulation phase-down schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Emblem Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Drive System Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Automotive Bearing Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Headliners Market