
 Mrna Synthesis Raw Materials Market | 2026-2036
Mrna Synthesis Raw Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Mrna Synthesis Raw Materials Market Intelligence
Buyer concentration in the mRNA synthesis raw materials space is shifting as large pharmaceutical companies internalize supply chains while mid-tier biotechs proliferate as new customers. Thermo Fisher Scientific Inc. leverages its dual role as reagent supplier and CDMO to capture value across the production workflow. Merck KGaA anchors European supply through its nucleotide manufacturing base in Darmstadt. Yeasen Biotechnology (Shanghai) Co., Ltd. competes on cost-engineered enzymes for Asia-Pacific customers.
mRNA synthesis raw materials comprise the molecular inputs required for in vitro transcription, including nucleoside triphosphates, DNA templates, RNA polymerases, and capping enzymes that collectively determine yield, integrity, and immunogenicity of the final transcript. These materials must meet stringent purity grades, typically exceeding 99% for NTPs and requiring trace metal content below 10 ppm to prevent template degradation during polymerization. Enzymes dominate value capture within the product type segmentation due to manufacturing complexity and limited qualified suppliers. In vitro transcription leads the technology dimension by installed base, though enzymatic synthesis is gaining traction for its reduced downstream processing burden. Vaccine development remains the anchor application, while therapeutic applications for oncology and rare disease represent the fastest-growing demand pool.
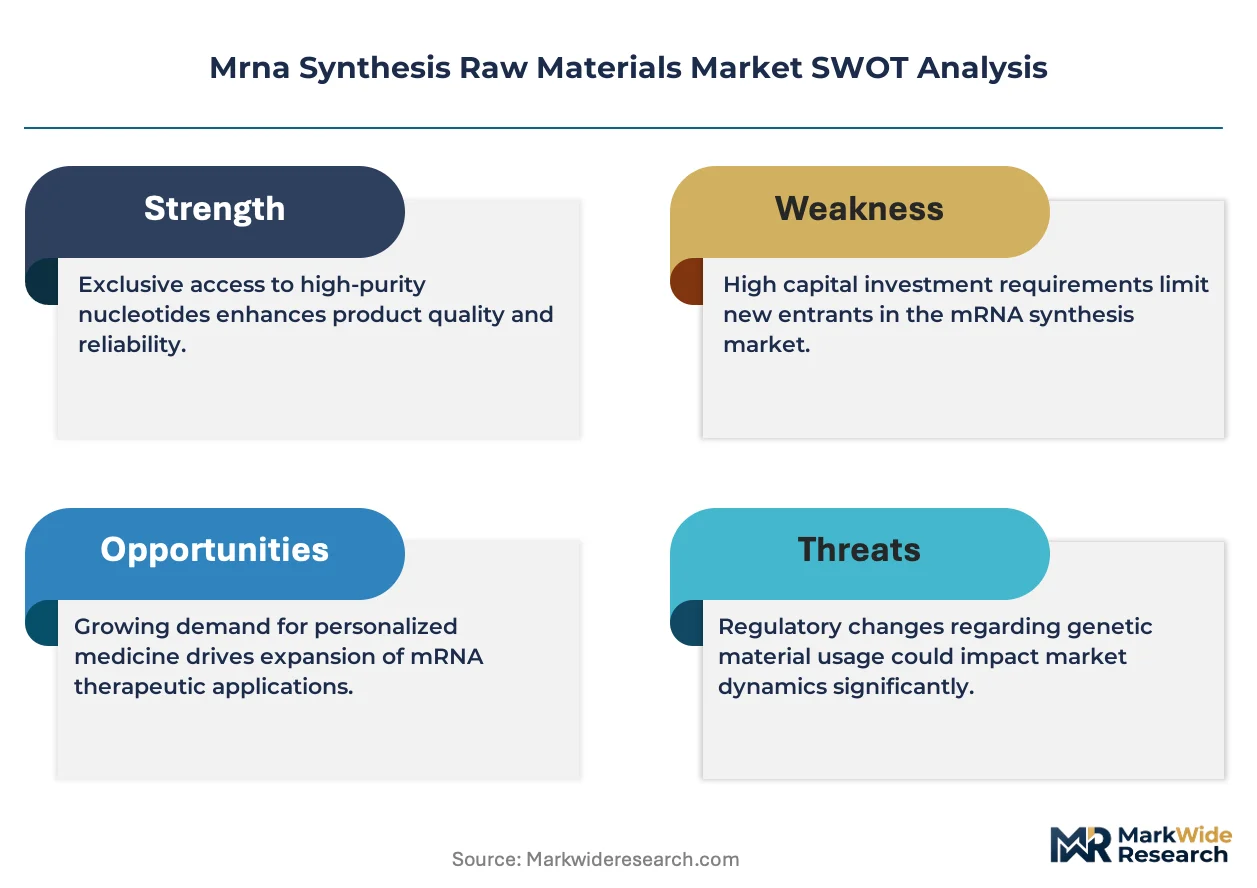
The FDA, EMA, and China's NMPA each impose distinct purity and documentation standards on mRNA raw materials, with the FDA's Chemistry, Manufacturing, and Controls guidance driving GMP-grade certification requirements that filter supplier eligibility. REACH and RoHS frameworks in Europe add chemical substance registration obligations for nucleotide importers, while China's GB standards mandate local testing protocols that extend qualification timelines. Stakeholders must monitor regulatory divergence across these jurisdictions to avoid supply interruptions as mRNA pipelines advance toward commercial scale.
Market Dynamics
Large pharmaceutical manufacturers are internalizing mRNA raw material supply chains while mid-tier biotechs proliferate as new customers, compressing traditional distributor margins and forcing suppliers to choose between captive partnerships or fragmented spot-market sales.
Growth Catalysts
- FDA Chemistry, Manufacturing, and Controls guidance:The tightened purity specifications for nucleic acid therapeutics are filtering supplier eligibility and accelerating GMP-grade certification investments among qualified manufacturers.
- Oncology therapeutic applications:Pipeline expansion into personalized cancer vaccines is diversifying demand beyond infectious disease prophylaxis into higher-margin therapeutic segments.
- Massachusetts and North Carolina biopharma clusters:Concentrated facility buildouts in these United States regions are creating localized demand spikes for modified nucleotides and capping enzymes.
Market Restraints
- Enzyme manufacturing complexity:Limited qualified suppliers for T7 RNA polymerase and capping enzymes concentrate supply risk among three to four dominant producers.
- Trace metal contamination thresholds:Sub-10 ppm requirements for NTPs necessitate specialized purification infrastructure that smaller suppliers cannot economically deploy.
- REACH chemical substance registration:European nucleotide importers face extended documentation timelines and testing costs that delay market entry.
Strategic Opportunities
- Enzymatic synthesis technology:Reduced downstream processing burden compared to in vitro transcription is attracting investment from process development teams seeking yield optimization.
- Rare disease therapeutic pipelines:Ultra-orphan indications with small patient populations favor mRNA's rapid manufacturing turnaround versus traditional biologics.
- China's GB standards local testing protocols:Domestic certification requirements create protected market space for regional suppliers capable of navigating extended qualification timelines.
Industry Challenges
- GMP-grade certification timelines:FDA facility inspections and documentation reviews for nucleotide manufacturing sites extend 18-24 months, constraining capacity expansion.
- Cross-jurisdictional regulatory divergence:Suppliers must maintain parallel quality systems for FDA, EMA, and NMPA requirements without harmonized standards.
- Specialized bioprocess engineering talent:Scarcity of professionals experienced in mRNA-specific enzymology and formulation science limits operational scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mrna Synthesis Raw Materials Market |
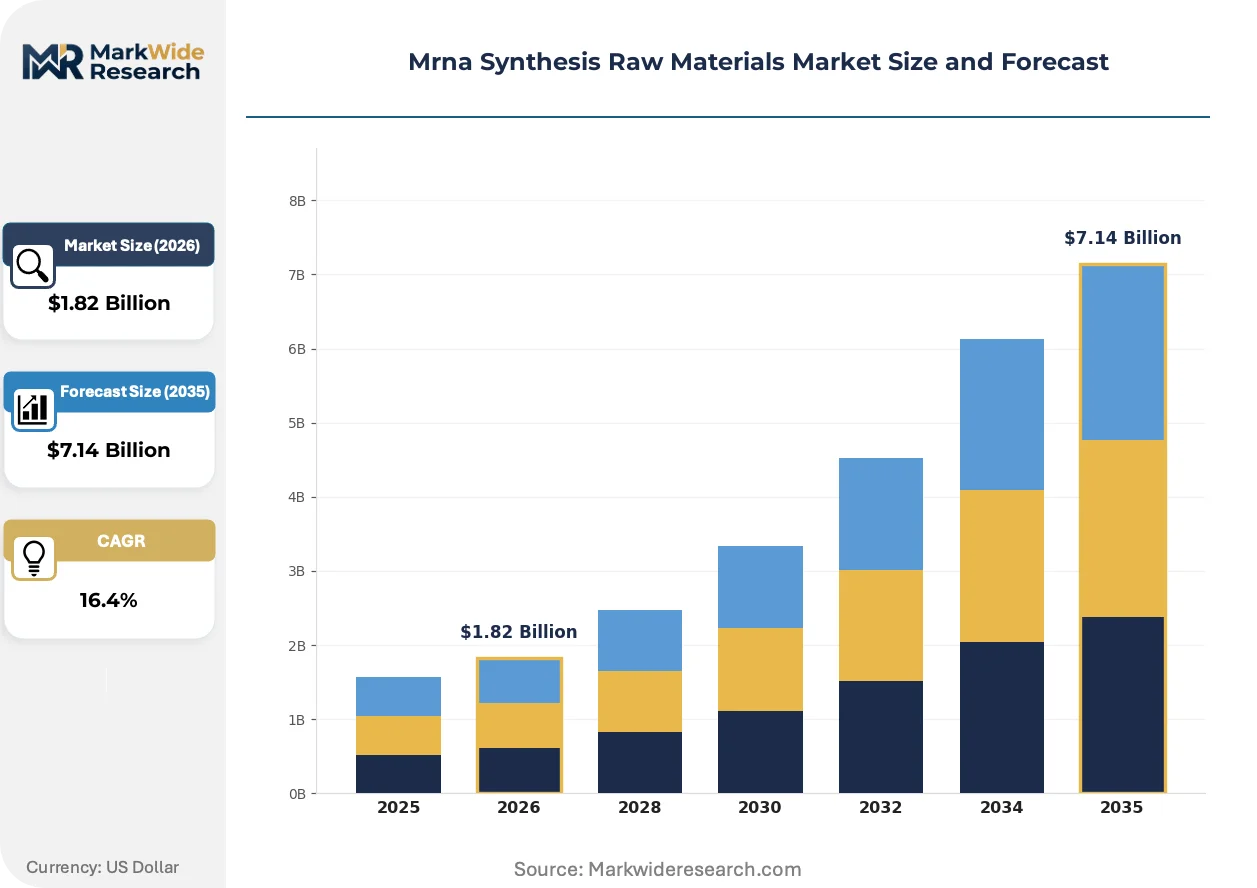
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $7.14 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleotides, Enzymes, Buffers, Reagents Technology: In Vitro Transcription, Cell-Free Synthesis, Enzymatic Synthesis, Chemical Synthesis Application: Vaccine Development, Therapeutic Applications, Diagnostic Tools, Gene Editing End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Labs |
| Companies Covered | Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., Merck KGaA, Jena Bioscience GmbH, Maravai LifeSciences, New England Biolabs, Yeasen Biotechnology (Shanghai) Co., Ltd., BOC Sciences, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mrna Synthesis Raw Materials Market Strategic Shifts & Innovations
Process intensification and regulatory harmonization pressures are converging to reshape how raw material suppliers configure their technical service offerings and geographic manufacturing footprints.
Enzymatic mRNA synthesis is electrifying process economics by eliminating chromatographic purification steps that dominate in vitro transcription workflows. Contract development and manufacturing organizations are piloting these systems for clinical-scale batches. The technology is compressing facility capital requirements and enabling distributed manufacturing models closer to patient populations.
REACH and RoHS frameworks in Europe are tightening chemical substance traceability obligations for nucleotide importers. Manufacturers must now document full supply chain provenance from base sugar through triphosphate activation. Suppliers serving the European market are responding by qualifying regional manufacturing assets in Germany and Switzerland to shorten documentation chains.
Buyer concentration among top-twenty pharmaceutical companies is consolidating procurement leverage while mid-tier biotechs fragment into numerous small-volume accounts. Traditional distributors are losing share to direct supplier relationships with large manufacturers. The United States exhibits this pattern most acutely, where Massachusetts-based innovators negotiate multi-year enzyme supply agreements bypassing intermediaries entirely.
Mrna Synthesis Raw Materials Market Segmentation
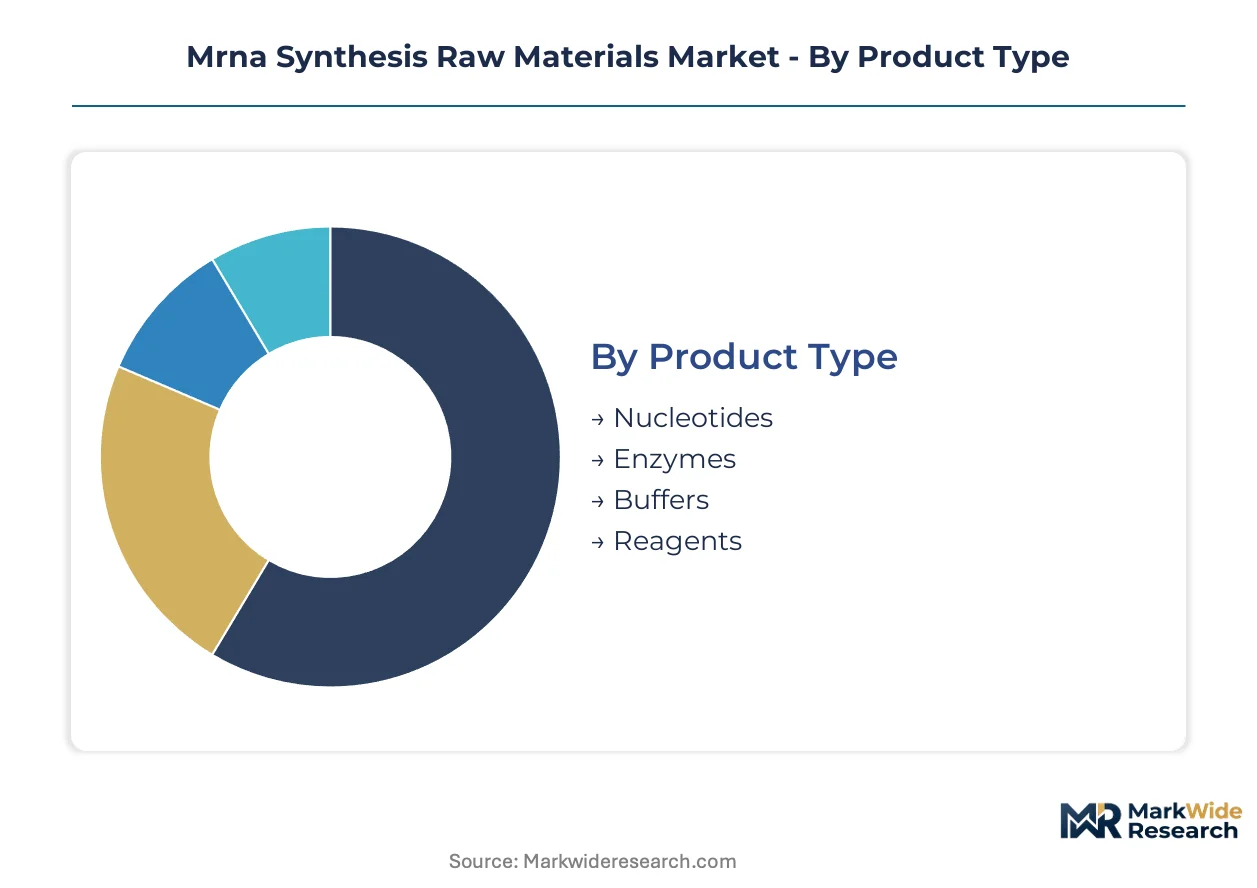
mRNA synthesis raw materials segment along four distinct dimensions that determine procurement patterns, technical specifications, and supplier relationships. Each category reflects how vaccine developers, therapeutic innovators, and research organizations prioritize purity grades, scale requirements, and regulatory documentation differently.
Product Type:
Standalone consumables dominate high-volume procurement while embedded system components require tighter integration with bioprocess workflows.
- Enzymes:T7 RNA polymerase and capping enzymes command premium pricing due to manufacturing complexity and limited qualified suppliers. Massachusetts-based vaccine developers negotiate multi-year supply agreements directly with manufacturers, bypassing distributors to secure GMP-grade certification documentation required by the FDA.
- Nucleotides:Modified nucleoside triphosphates must exceed 99% purity with trace metal content below 10 ppm to prevent template degradation during polymerization. North Carolina biopharma clusters are building captive purification capacity to reduce dependency on European importers facing REACH registration delays.
- Buffers:Formulated solutions for pH stabilization and ionic balance during transcription reactions.
- Reagents:Ancillary chemicals including DNase inhibitors, stabilizers, and quality control reference standards.
Enzymes lead volumes today; nucleotides are gaining share fastest as therapeutic applications diversify beyond infectious disease vaccines.
Technology:
Process maturity separates established platforms from emerging alternatives competing on downstream efficiency.
- In Vitro Transcription:The dominant installed base uses DNA templates and purified RNA polymerases in batch reactions. Contract development and manufacturing organizations in the United States rely on this proven approach for clinical-scale mRNA production, though chromatographic purification steps add facility capital requirements.
- Enzymatic Synthesis:Template-free systems eliminate DNA contamination risks and reduce purification burden. European process development teams are piloting these platforms for distributed manufacturing models closer to patient populations, compressing logistics complexity for personalized cancer vaccines.
- Cell-Free Synthesis:Lysate-based systems using crude cellular extracts rather than purified enzymes.
- Chemical Synthesis:Solid-phase oligonucleotide chemistry for short RNA sequences and modified constructs.
In vitro transcription anchors current capacity; enzymatic synthesis shows the steepest expansion trajectory as yield optimization becomes critical.
Application:
Regulatory pathway intensity varies sharply between prophylactic and therapeutic indications, reshaping material specification requirements.
- Vaccine Development:Infectious disease prophylaxis drove initial demand scaling for COVID-19 and influenza candidates. The FDA's Chemistry, Manufacturing, and Controls guidance tightened purity specifications specifically for this segment, filtering supplier eligibility and accelerating GMP-grade certification investments.
- Therapeutic Applications:Personalized cancer vaccines and rare disease treatments require smaller batch sizes with higher modification complexity. Oncology pipelines in Massachusetts favor rapid manufacturing turnaround versus traditional biologics, creating demand for flexible raw material supply structures.
- Diagnostic Tools:Reference standards and controls for molecular assay development.
- Gene Editing:Guide RNA and mRNA encoding nucleases for CRISPR-based therapies.
Vaccine development maintains volume leadership; therapeutic applications are climbing the fastest as margins attract supplier investment.
End User:
Procurement scale and technical service expectations diverge between integrated manufacturers and fragmented research consumers.
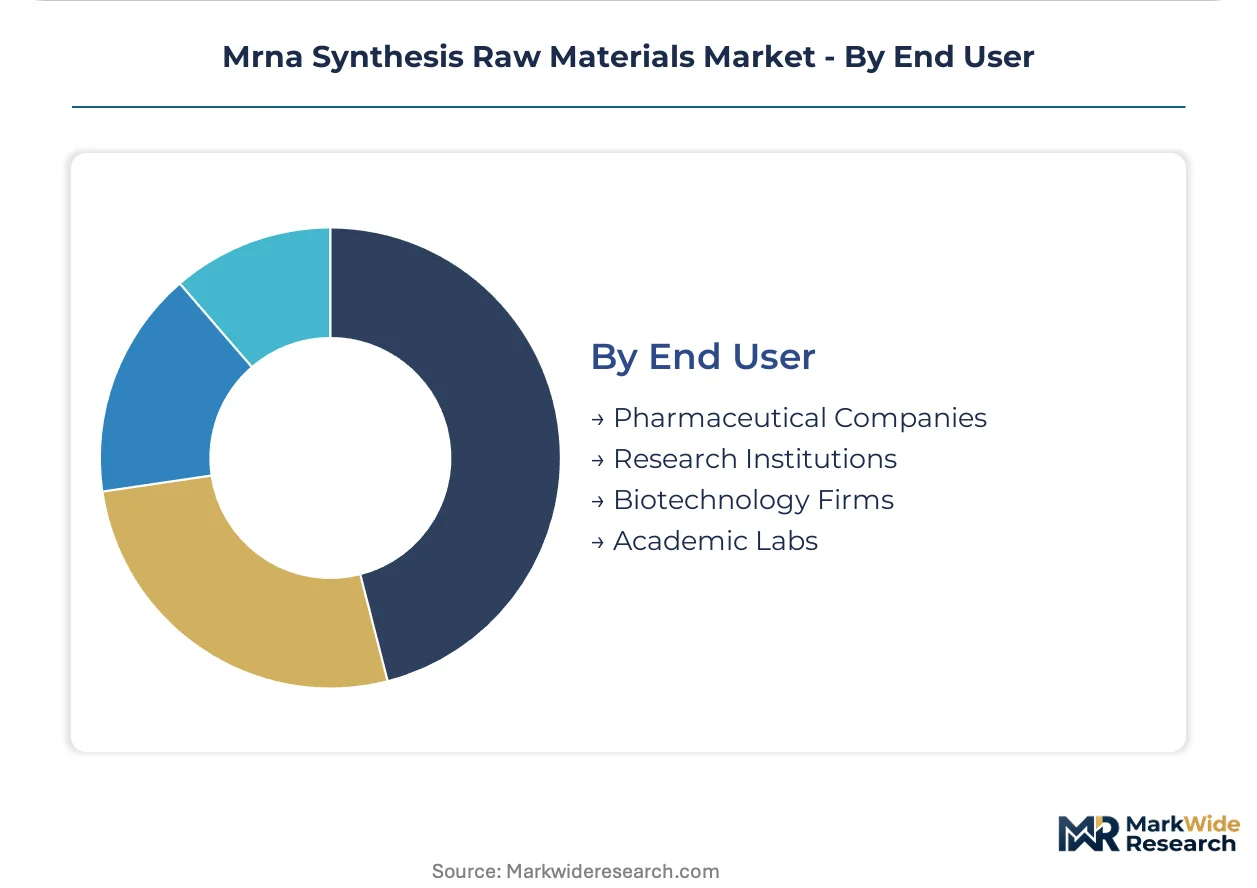
- Pharmaceutical Companies:Large manufacturers internalize supply chains through direct supplier relationships and captive raw material production. These buyers demand comprehensive regulatory documentation packages spanning FDA, EMA, and China's NMPA requirements without harmonized standards.
- Biotechnology Firms:Mid-tier innovators proliferate as new customers with fragmented spot-market purchasing patterns. North Carolina clusters host numerous venture-backed companies negotiating flexible supply terms as pipelines advance toward commercial scale.
- Research Institutions:National laboratories and contract research organizations with standardized reagent procurement.
- Academic Labs:University-based investigators with small-volume, catalog-based purchasing.
Pharmaceutical companies concentrate procurement leverage; biotechnology firms are expanding most quickly as new customer formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharma clusters command premium procurement volumes while Chinese suppliers compete on cost-engineered enzymes, revealing divergent regional strategies across the mRNA synthesis raw materials landscape.
United States
Massachusetts and North Carolina biopharma corridors drive concentrated demand for modified nucleotides and capping enzymes. FDA Chemistry, Manufacturing, and Controls guidance tightens purity specifications and accelerates GMP-grade certification requirements for domestic suppliers. Boston-Cambridge innovators negotiate multi-year enzyme supply agreements directly with manufacturers, bypassing traditional distribution channels entirely.
Germany
Darmstadt anchors European nucleotide manufacturing with specialized purification infrastructure serving continental vaccine developers. EMA documentation standards and REACH chemical substance registration obligations filter supplier eligibility and extend qualification timelines. German process development teams pilot enzymatic synthesis platforms for distributed manufacturing models closer to patient populations.
China
Shanghai-based enzyme specialists capture Asia-Pacific market share through cost-engineered production of T7 RNA polymerase. NMPA GB standards mandate local testing protocols that protect domestic suppliers from rapid import competition. Yangtze River Delta biotech clusters build captive mRNA manufacturing capacity to reduce dependency on Western nucleotide sources.
Switzerland
Swissmedic certification requirements attract premium-tier suppliers seeking European regulatory credibility without EMA jurisdictional complexity. Basel and Zurich biotech corridors concentrate demand for high-purity reagents in therapeutic oncology applications. Regional manufacturers qualify assets to shorten REACH documentation chains for nucleotide importers serving German and French markets.
United Kingdom
London-Oxford-Cambridge golden triangle sustains research-scale demand for clinical-grade raw materials in personalized cancer vaccine pipelines. Post-Brexit regulatory divergence from EMA standards complicates cross-border supply qualification for continental manufacturers. British biotechs negotiate flexible supply terms as mRNA pipelines advance toward commercial scale and MHRA licensing requirements.
Mrna Synthesis Raw Materials Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the mRNA synthesis raw materials space, creating a tiered structure where scale advantages clash with agility premiums. Three to four dominant producers concentrate supply of T7 RNA polymerase and capping enzymes due to manufacturing complexity barriers. Strategic archetypes include integrated life science conglomerates with dual re supplier-CDMO positioning, regional enzyme specialists competing on cost engineering, and nucleotide manufacturers with captive purification infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers race to secure GMP-grade certification ahead of pipeline commercialization.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. exemplifies dual-role positioning across reagent supply and contract manufacturing services. Merck KGaA anchors European supply architecture through its Darmstadt nucleotide manufacturing base. Yeasen Biotechnology (Shanghai) Co., Ltd. occupies a position within the Asia-Pacific cost-engineering specialist archetype, competing on enzyme production economics for regional customers navigating extended NMPA qualification timelines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| Merck KGaA |
| Jena Bioscience GmbH |
| Maravai LifeSciences |
| New England Biolabs |
| Yeasen Biotechnology (Shanghai) Co., Ltd. |
| BOC Sciences |
| Promega Corporation |
| Others |
Cost & Logistics Intelligence
GMP-grade certification ladders bifurcate the mRNA synthesis raw materials market into premium-validated tiers and research-grade commodities, with FDA-inspected manufacturers commanding threefold price multiples over catalog suppliers while simultaneously dictating supply chain topology through direct procurement relationships that bypass traditional distribution layers.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for European nucleotide supply as REACH-registered manufacturers absorb documentation costs into contract premiums. Three-tier pricing structure across GMP-certified, ISO-grade, and research-use levels separates pharmaceutical procurement from biotech spot purchasing. Pricing pressure stems from mid-tier biotechs consolidating volumes to match large manufacturer scale discounts. Academic labs exhibit highest price sensitivity; Massachusetts-based vaccine developers show least sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Specialized bioprocess engineering talent shortages in Darmstadt and Shanghai constrain enzyme manufacturing scale-up velocity. Supply concentrates in the United States, Germany, and China for T7 RNA polymerase and modified nucleoside triphosphates. Raw material dependencies draw from sugar phosphate feedstocks, recombinant protein expression systems, and chromatography resins. Single-source vulnerability concentrates among three dominant capping enzyme producers. Distribution runs through direct manufacturer relationships with large pharmaceutical accounts, with spot-market distributors serving fragmented biotech demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where NMPA qualification timelines in China create protected margin pools for domestic enzyme suppliers that Western competitors cannot access without eighteen-month certification delays.
For Market Incumbents: Acquire specialized purification infrastructure in nucleotide manufacturing to defend against mid-tier biotechs building captive capacity. Secure multi-year enzyme supply agreements with Massachusetts and North Carolina clusters before CDMOs internalize raw material production. FDA Chemistry, Manufacturing, and Controls guidance tightening represents the primary regulatory threat requiring accelerated GMP-grade certification investments.
For New Entrants and Emerging Players: Capture rare disease therapeutic pipelines where small-batch flexibility outweighs scale economics and incumbent pharmaceutical relationships carry less weight. Target Asia-Pacific biotechs navigating extended NMPA qualification timelines with cost-engineered enzyme offerings. Go-to-market through CDMO partnerships provides regulatory credibility without direct certification burden.
For Investors and Strategic Acquirers: Consolidation pressure builds where enzyme manufacturing complexity barriers protect three-to-four dominant producers from rapid capacity expansion. Five-to-ten year viability favors nucleotide manufacturers with captive purification assets over pure-play enzyme distributors. Signal to watch: FDA facility inspection queue lengths as inflection indicator for supply-constrained pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Grade Certification Investment | FDA facility inspections qualify suppliers for pharmaceutical procurement contracts exceeding research-grade margins. |
| Enzymatic Synthesis Technology Licensing | Template-free platforms reduce chromatographic purification burden for distributed manufacturing near patient populations. |
| Captive Nucleotide Purification Capacity | North Carolina clusters build in-house infrastructure to bypass REACH-registered European importer dependencies. |
| Multi-Year Direct Supply Agreements | Boston-Cambridge innovators bypass distributors entirely, compressing traditional channel margins. |
| Regional Manufacturing Footprint Expansion | Shanghai-based suppliers leverage NMPA GB standards to protect domestic market share from Western competitors. |
Research Approach
Direct dialogue with vaccine development executives, regulatory affairs leads at nucleotide manufacturers, CDMO procurement directors, and enzymology R&D specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA Chemistry, Manufacturing, and Controls guidance documents, EMA quality guidelines, NMPA GB standards filings, and clinical trial registration databases for mRNA therapeutic pipelines. Bottom-up and top-down triangulation cross-checked supplier capacity estimates against pharmaceutical procurement volume disclosures.
Bottom-up modeling aggregated nucleotide and enzyme demand by therapeutic application and end-user scale tier, while top-down analysis calibrated aggregate market expansion against biopharma facility investment announcements across the projection horizon. Segmentation dimensions included product type, technology platform, application indication, and end-user procurement scale. CAGRs were derived from fitted growth curves incorporating pipeline advancement rates and regulatory approval timelines. Industry-specific inputs captured GMP-grade certification lag times and enzymatic synthesis yield improvement trajectories.
Underlying measurement precision varies by segment; vaccine development applications carry tighter precision than emerging rare disease therapeutic categories due to disclosed procurement volumes. Forecasts reflect assumptions regarding regulatory harmonization progress and pipeline commercialization rates. Material deviation in FDA inspection throughput or NMPA qualification timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Global Dexamethasone Market