
 Magnesium Testing Reagents Market | 2026-2036
Magnesium Testing Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Testing Reagents Market Foresight
Automated wet-chemistry platforms is rewriting magnesium reagent deployment across clinical and industrial labs. Randox Laboratories leverages its integrated analyzer-reagent ecosystems to sustain high-throughput customer loyalty. Sigma-Aldrich Corporation anchors its position through deep catalog breadth spanning research-grade to diagnostic-grade formulations. DiaSys Diagnostic Systems specializes in liquid-stable reagent architectures that reduce cold-chain burden for mid-tier laboratories.
Magnesium testing reagents comprise calibrated chemical formulations—typically xylidyl blue, calmagite, or methylthymol blue complexes in buffered matrices—designed to quantify magnesium ion concentration via photometric endpoint detection, with sensitivity thresholds routinely reaching 0.1 mg/dL in serum matrices. These reagents serve primarily to diagnose hypomagnesemia and hypermagnesemia in renal, cardiac, and critical-care settings, while extending into environmental water hardness monitoring and agricultural soil nutrient profiling. Colorimetric reagents dominate routine clinical workflows due to their compatibility with open-channel chemistry analyzers and lower per-test cost structures. Liquid formulations are displacing lyophilized alternatives in high-volume settings where reconstitution time and technician variability erode throughput economics.
The FDA enforces Class I and Class II in vitro diagnostic controls over magnesium assay kits sold into U.S. clinical channels, while the EMA's In Vitro Diagnostic Regulation imposes escalating conformity requirements across European Economic Area member states. ISO 15189 accreditation standards for medical laboratories are tightening analytical traceability demands, forcing reagent vendors to tighten lot-to-lot consistency protocols. Stakeholders must monitor how evolving IVD regulatory convergence between FDA and EMA frameworks reshapes product registration timelines and manufacturing quality investments.
Market Dynamics
Automated wet-chemistry platforms are compressing reagent procurement cycles across hospital networks and reference laboratories, forcing vendors to bundle liquid-stable formulations with analyzer service contracts or risk displacement by integrated system suppliers.
Growth Catalysts
- IVDR Conformity Escalation:The EMA's In Vitro Diagnostic Regulation is accelerating consolidation among European reagent vendors unable to absorb Class B and C device certification costs, creating procurement advantages for ISO 13485-accredited suppliers.
- Renal Dialysis Expansion:End-stage renal disease patient volumes in Germany and Japan are magnifying magnesium monitoring frequency within nephrology protocols, driving recurring reagent consumption in hospital-based dialysis centers.
- Colorimetric Assay Standardization:Photometric endpoint detection using xylidyl blue complexes is hardening into the default methodology for open-channel chemistry analyzers, cementing supplier relationships with mid-tier clinical laboratories.
Market Restraints
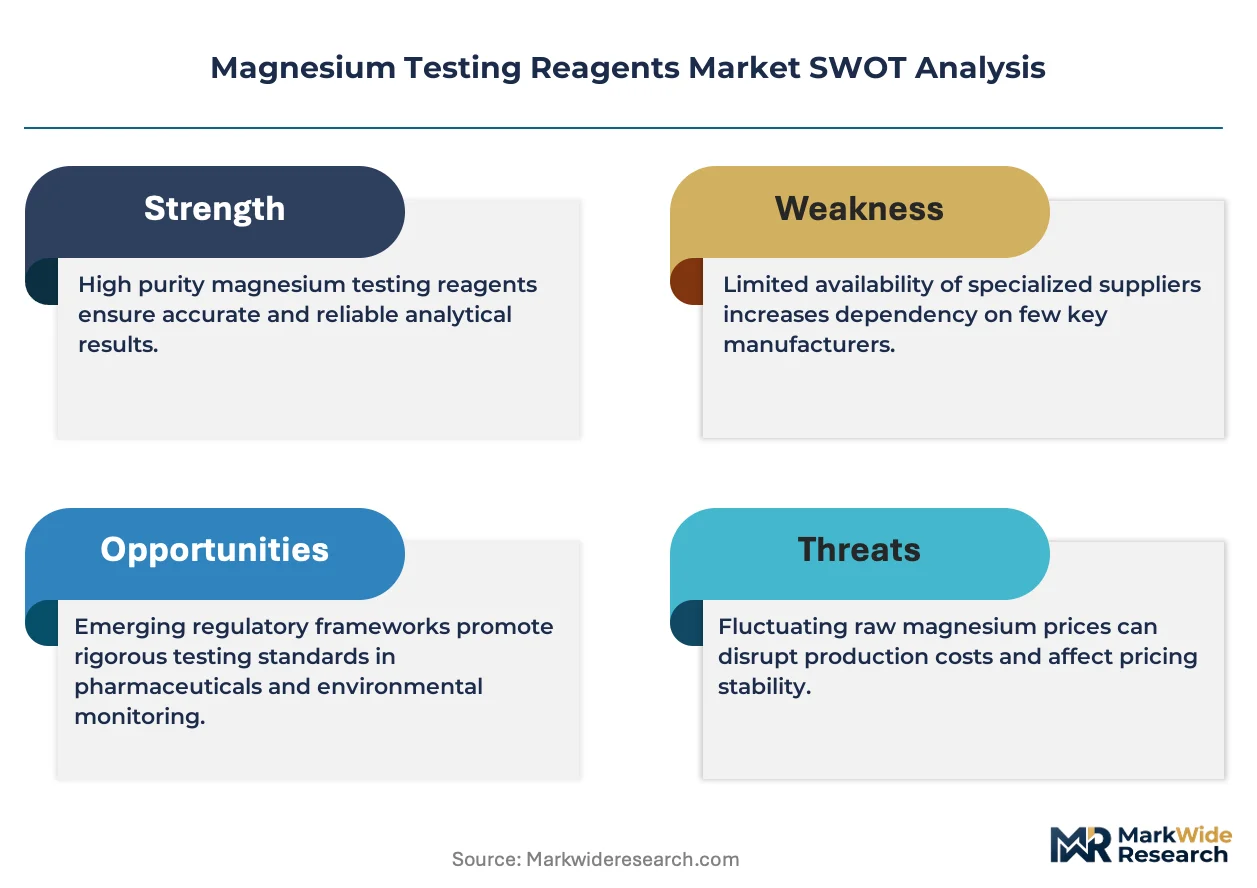
- Raw Material Concentration:Chromogenic indicator synthesis depends on specialized dye intermediates concentrated in Chinese chemical manufacturing zones, exposing reagent formulators to input cost volatility and supply interruption risk.
- Lyophilized Format Decline:Reconstitution time burdens and technician variability are structurally disadvantaging lyophilized reagent architectures, stranding capital investments in freeze-drying equipment among smaller regional suppliers.
- Analyzer Vendor Lock-in:Closed-system chemistry analyzers from dominant equipment manufacturers are capturing reagent decision-making authority, compressing margins for independent reagent producers unable to achieve OEM partnerships.
Strategic Opportunities
- Point-of-Care Penetration:Emergency departments and ambulatory surgical centers in the United States represent underpenetrated magnesium testing venues where cartridge-based assays could disperse testing beyond centralized laboratories.
- Agricultural Soil Profiling:Precision agriculture adoption in Japan is extending magnesium reagent applications from clinical diagnostics into environmental nutrient monitoring, opening volume contracts with agricultural extension services.
- ISO 15189 Traceability Mandates:Medical laboratory accreditation standards are tightening lot-to-lot consistency requirements, rewarding reagent vendors with embedded metrology capabilities and certified reference material programs.
Industry Challenges
- Regulatory Submission Expertise Scarcity:The FDA's 510(k) pathway for Class II IVD devices demands specialized regulatory affairs capacity that mid-size reagent manufacturers struggle to staff, elongating product registration timelines.
- Cold-Chain Infrastructure Reconfiguration:Liquid-stable reagent migration is forcing distributors to invest in temperature-controlled logistics networks, raising working capital requirements for regional supply partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Testing Reagents Market |
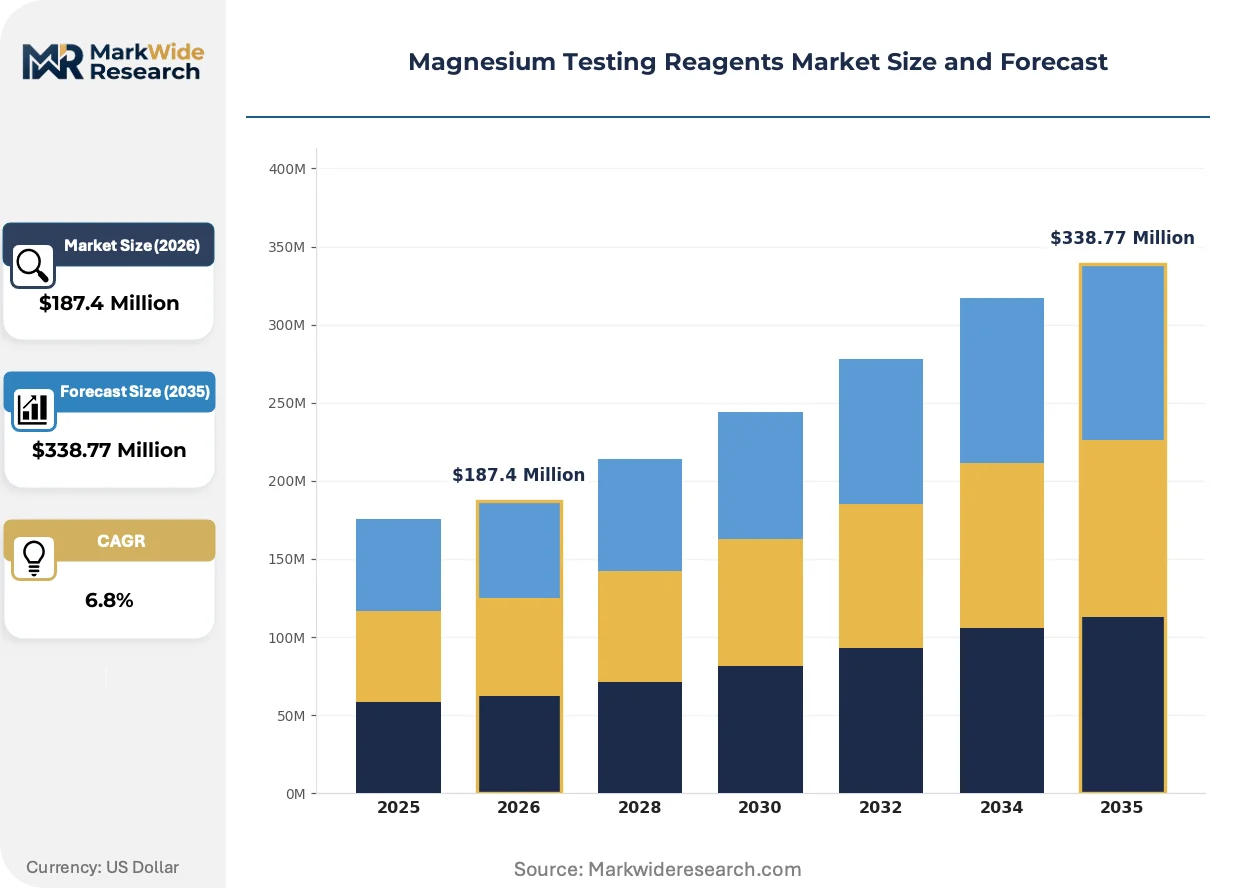
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colorimetric Reagents, Titrimetric Reagents, Spectrophotometric Reagents, Others End User: Research Laboratories, Pharmaceutical Companies, Environmental Monitoring, Food Industry Form: Liquid, Powder, Tablet, Solution Application: Clinical Testing, Water Quality Testing, Soil Analysis, Industrial Analysis |
| Companies Covered | Randox Laboratories, Sigma-Aldrich Corporation, Pointe Scientific Inc, Thomas Scientific, DiaSys Diagnostic Systems, Europiren B.V., Accurex Biomedical, Molychem, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Testing Reagents Market Shifts & Advancements
Reagent formulation architectures and distribution economics are undergoing parallel transformation as laboratories prioritize throughput reliability over per-unit cost minimization, reshaping vendor competitive priorities.
Liquid-stable magnesium reagent formulations are migrating from lyophilized alternatives in high-volume clinical settings. Hospital network laboratories with automated chemistry analyzers are adopting these formats to eliminate reconstitution variability and compress technician touch time. This migration is enabling reagent vendors to command premium pricing for convenience-optimized products while eroding the economic viability of traditional freeze-dried formats.
REACH chemical registration requirements in the European Union are tightening substance volume tracking and safety documentation obligations for chromogenic indicator manufacturers. Reagent formulators sourcing dye intermediates from non-EU suppliers face elevated compliance verification burdens and extended supplier qualification cycles. Mid-sized European clinical laboratories are responding by consolidating procurement around vendors with established REACH-compliant supply chains.
Service-unbundling is fragmenting traditional reagent supply relationships in the United States. Independent service organizations are separating analyzer maintenance from reagent procurement, allowing hospital laboratories to negotiate reagent contracts independently of equipment vendor arrangements. This pattern is most visible in multi-hospital health systems in the Midwest and Southeast regions where procurement centralization has matured.
Magnesium Testing Reagents Market Segmentation
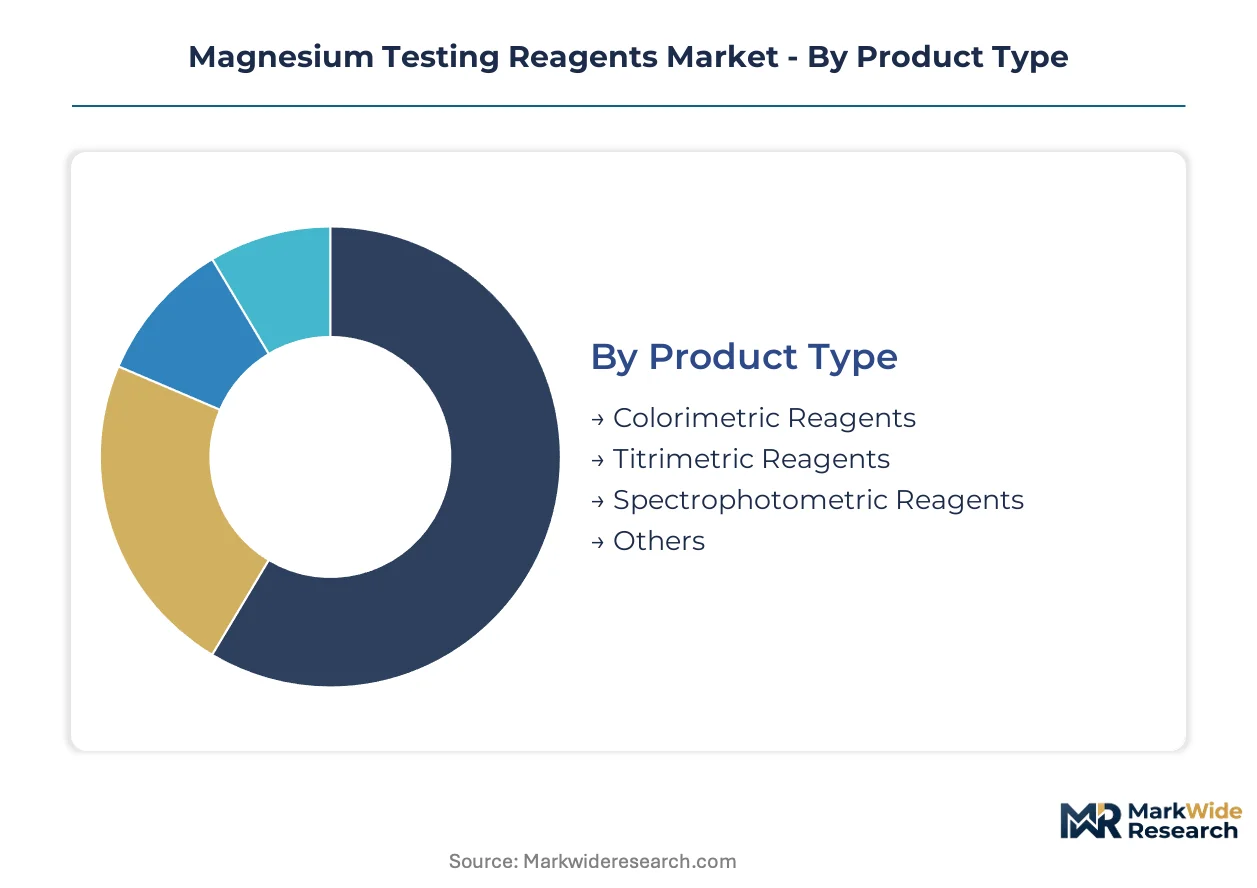
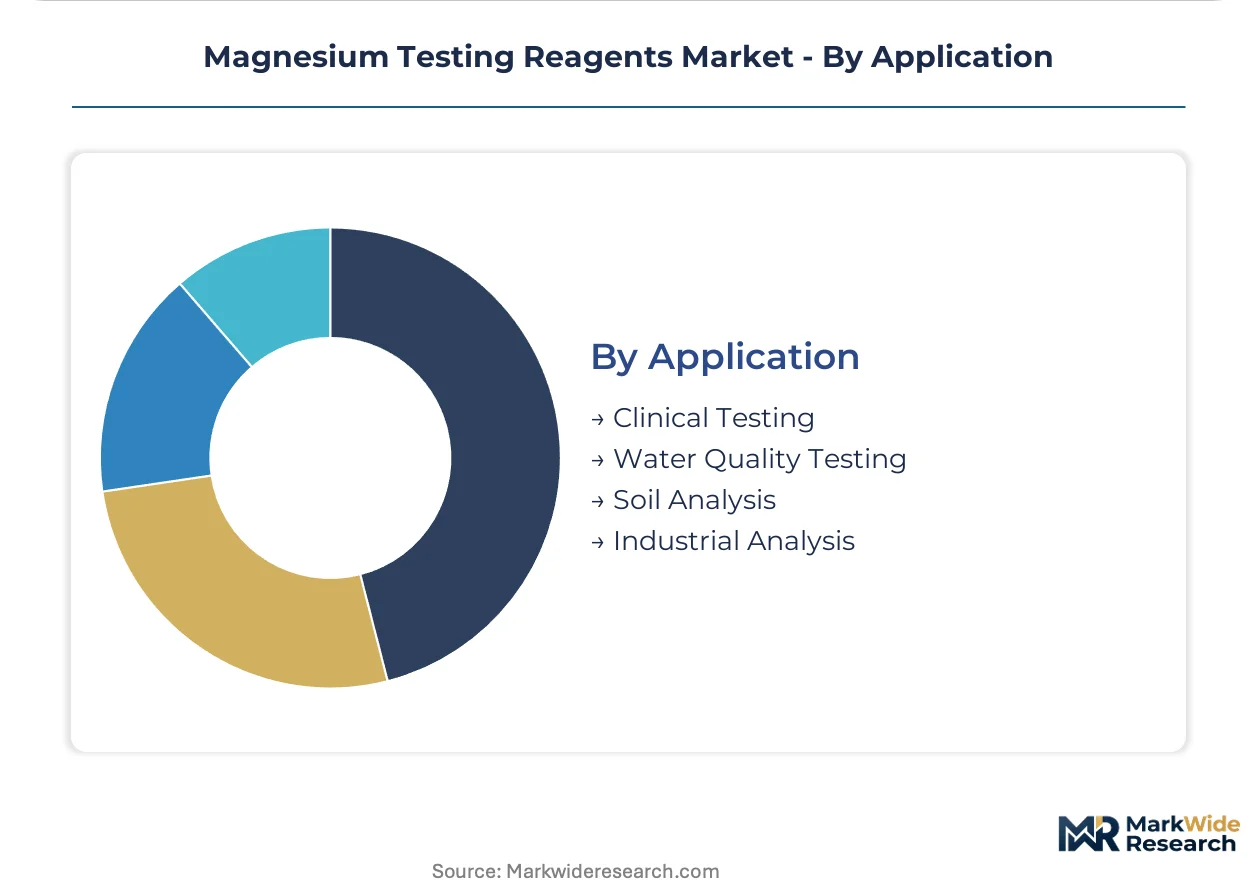
Magnesium testing reagents serve divergent analytical requirements across clinical diagnostics, environmental compliance, and industrial quality control. Segmentation reveals how formulation chemistry, physical format, and end-use environment dictate procurement priorities and supplier selection criteria.
Product Type:
Chromogenic detection chemistry spans photometric endpoint, volumetric titration, and atomic absorption methodologies, each calibrated to specific sensitivity thresholds and analyzer compatibility requirements.
- Colorimetric Reagents:Xylidyl blue and calmagite complexes in buffered matrices enable photometric quantification at 0.1 mg/dL sensitivity in serum. Hospital laboratories in the United States favor these formulations for open-channel chemistry analyzer compatibility and lower per-test economics.
- Titrimetric Reagents:EDTA-based chelometric solutions with metallochromic indicators support manual and semi-automated volumetric analysis. Water utilities in Germany specify these for hardness compliance monitoring under DVGW technical guidelines.
- Spectrophotometric Reagents:High-purity formulations for atomic absorption and ICP-MS calibration demand certified traceability to NIST reference materials.
- Others:Enzymatic and ion-selective electrode formulations address niche portable testing applications.
The dominant share belongs to colorimetric reagents, while titrimetric formulations are closing the gap fastest in environmental compliance segments.
End User:
Customer archetypes range from high-throughput clinical operators to dispersed field monitoring networks, each imposing distinct logistics and technical support demands on suppliers.
- Research Laboratories:Academic and government research facilities require reagent-grade formulations with batch-specific certificates of analysis and extended stability documentation. Procurement concentrates in Japan where METI-funded materials science programs sustain volume demand.
- Pharmaceutical Companies:GMP-compliant reagents for in-process control and finished product release testing require validated manufacturing records and audit trails. Quality control laboratories in Germany enforce ISO 17025 analytical standards.
- Environmental Monitoring:Regulatory compliance testing for surface water, wastewater, and drinking water mandates method-specific formulations.
- Food Industry:Nutritional labeling and quality assurance testing for fortified products and mineral water specifications.
Research laboratories command the largest procurement volumes, though pharmaceutical quality control is expanding most quickly as biologics manufacturing scales.
Form:
Physical presentation determines cold-chain requirements, shelf stability, and technician handling protocols across laboratory workflows.
- Liquid:Ready-to-use formulations in barcoded cartridges eliminate reconstitution variability. Automated chemistry analyzers in hospital networks are displacing lyophilized alternatives to compress technician touch time.
- Powder:Bulk lyophilized preparations for high-volume reconstitution retain cost advantages in resource-constrained settings.
- Tablet:Pre-weighed unit doses for field portability and educational laboratory instruction.
- Solution:Concentrated stock solutions requiring dilution for customized working concentrations.
Liquid formats dominate high-throughput clinical settings, while powder formulations retain footholds in emerging market reference laboratories.
Application:
Use-case environments span regulated clinical diagnostics to industrial process control, each with distinct performance validation and documentation requirements.
- Clinical Testing:Serum and plasma magnesium quantification for hypomagnesemia and hypermagnesemia diagnosis in renal, cardiac, and critical-care settings. Nephrology protocols in Japan mandate frequent monitoring for dialysis patients.
- Water Quality Testing:Hardness determination for drinking water compliance and boiler feedwater treatment. German municipal utilities enforce DVGW W 253 technical specifications.
- Soil Analysis:Agricultural nutrient profiling for precision fertilization recommendations.
- Industrial Analysis:Process control in chemical manufacturing and metallurgical quality assurance.
Clinical testing absorbs the dominant application share, with water quality testing gaining fastest as environmental enforcement tightens across European member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reagent manufacturers export liquid-stable formulations to hospital networks across Central Europe, while Japanese suppliers serve dialysis centers throughout East Asia. Trade corridors link specialized chromogenic indicator production in Switzerland to clinical laboratories in France and Italy.
United States
Hospital network consolidation in the Midwest and Southeast is centralizing reagent procurement decisions. The FDA's 510(k) pathway for Class II IVD devices shapes registration timelines for new entrants. The Boston-Cambridge corridor anchors metrology-focused vendors serving academic medical centers with certified reference material programs.
Germany
End-stage renal disease protocols in Bavaria and North Rhine-Westphalia drive recurring magnesium monitoring in dialysis centers. The EMA's In Vitro Diagnostic Regulation accelerates vendor consolidation among ISO 13485-accredited suppliers. The Rhine-Main cluster hosts reagent formulators with REACH-compliant dye intermediate supply chains.
Japan
Precision agriculture adoption in Hokkaido and Tohoku extends reagent applications into soil nutrient profiling. METI-funded materials science programs in Tsukuba sustain research-grade procurement volumes. The Kansai region's chemical manufacturing base supplies chromogenic indicators to domestic diagnostic formulators.
Switzerland
Swissmedic's device conformity requirements enforce stringent lot-to-lot consistency protocols. The Basel-Zurich corridor concentrates vendors with embedded metrology capabilities serving pharmaceutical quality control laboratories. Swiss reagent exporters leverage bilateral recognition agreements to access EU clinical channels.
United Kingdom
NHS procurement frameworks in England are consolidating reagent contracts around liquid-stable formats compatible with automated analyzers. The MHRA's post-Brexit IVD registration requirements reshape vendor market access strategies. The Cambridge-Oxford-London triangle anchors research-grade demand from university hospital networks.
Magnesium Testing Reagents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base organizes into three tiers: integrated analyzer-reagent ecosystems, independent reagent formulators, and regional distributors with cold-chain capabilities. Dominant competitive moves include analyzer service contract bundling and ISO 15189 accreditation investments that lock in laboratory relationships.
Within the integrated-system tier, Randox Laboratories and Roche Diagnostics occupy positions defined by analyzer-reagent bundling power. Sigma-Aldrich Corporation anchors the research-grade segment through catalog breadth spanning diagnostic-grade to analytical-grade formulations. DiaSys Diagnostic Systems exemplifies the liquid-stable specialist archetype, reducing cold-chain burden for mid-tier laboratories.
| Leading Market Players |
|---|
| Randox Laboratories |
| Sigma-Aldrich Corporation |
| Pointe Scientific Inc |
| Thomas Scientific |
| DiaSys Diagnostic Systems |
| Europiren B.V. |
| Accurex Biomedical |
| Molychem |
| Roche Diagnostics |
| Others |
Supply & Pricing Matrix
Chromogenic indicator synthesis concentrated in Chinese chemical manufacturing zones feeds directly into margin compression for mid-tier reagent formulators lacking captive dye intermediate supply. Liquid-stable formulation migration is redistributing value pools toward vendors with integrated analyzer partnerships and temperature-controlled logistics capabilities.
Pricing Analysis
Prior-generation lyophilized reagent pricing is collapsing against current-generation liquid-stable premiums, while next-generation cartridge-based point-of-care formats command substantial markups. Three-tier pricing structure across premium diagnostic-grade, standard clinical-grade, and economy research-grade levels reflects ISO 13485 certification status and NIST traceability documentation. Pricing pressure stems from analyzer vendor bundling power in consolidated US hospital networks. Academic research laboratories exhibit highest price sensitivity, while pharmaceutical quality control operations prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement relationships between European reagent distributors and mid-tier laboratory customers, straining working capital for regional supply partners. Manufacturing concentration spans China for dye intermediates, Germany for precision formulation, and Switzerland for metrology-grade reference materials. Raw material dependencies include xylidyl blue chromogens, EDTA chelators, and high-purity buffer salts. Single-source vulnerability around specialized dye synthesis exposes formulators to input cost volatility. Distribution runs through cold-chain-enabled regional distributors serving hospital networks and reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive dynamics as closed-system analyzer-reagent bundling locks in laboratory procurement relationships. Interoperability demands from ISO 15189 accreditation are favoring vendors with embedded metrology ecosystems over standalone reagent suppliers.
For Market Incumbents: Entrench analyzer-reagent bundling power through exclusive liquid-stable formulation supply agreements with dominant equipment manufacturers. Deepen ISO 13485 certification investments to accelerate IVDR conformity timelines and strand non-compliant regional competitors. The EMA's escalating Class B and C device requirements represent the primary regulatory threat to market position. For New Entrants and Emerging Players: Point-of-care emergency departments in the United States represent the most penetrable entry point for cartridge-based magnesium assays outside centralized laboratory control. Agricultural extension services in Japan's precision farming corridors offer volume contracts with lower regulatory barriers than clinical channels. Pursue service-unbundling relationships with independent service organizations separating analyzer maintenance from reagent procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed liquid-stable reagent specialists lacking analyzer OEM partnerships but holding REACH-compliant European supply chains. Five-to-ten year viability hinges on regulatory convergence between FDA and EMA frameworks favoring scaled compliance infrastructure. Watch for IVDR registration timeline elongation as the signal for accelerated vendor consolidation among ISO 13485-accredited suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Analyzer-Reagent Bundling Agreement | Locks hospital network procurement decisions and compresses independent reagent margins. |
| ISO 15189 Metrology Program | Certified reference material capabilities satisfy tightening lot-to-lot traceability mandates. |
| Liquid-Stable Format Conversion | Eliminates reconstitution variability and commands premium pricing in high-throughput settings. |
| REACH-Compliant Supply Chain | European dye intermediate sourcing avoids extended supplier qualification cycles. |
| Point-of-Care Cartridge Development | Extends testing beyond centralized laboratories into emergency and ambulatory venues. |
Research Methodology
A standing panel of clinical laboratory directors, reagent procurement managers at hospital networks, diagnostic analyzer service engineers, and regulatory affairs specialists at IVD manufacturers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with these stakeholders alongside trade data from customs records, FDA 510(k) filing databases, EMA IVDR submission trackers, and ISO 13485 accreditation registries. Bottom-up reagent volume estimates triangulated against top-down market sizing from analyzer installed base data.
Scenario-bracketing around regulatory timeline risk and raw material cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tiers, physical format categories, end-user archetypes, and regional regulatory clusters. CAGRs derived from weighted average growth rates across these segments, incorporating dialysis patient volume trajectories, precision agriculture adoption curves, and environmental compliance enforcement intensity as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth, chemical intermediate pricing, or trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory convergence pace and liquid-stable format adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
HPLC Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Paint Tester Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Hydrometer Market
Testing Equipment
Analytical Gel Permeation Chromatography Market