
 Cobalt Carbonate Market | 2026-2036
Cobalt Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Carbonate Market Analysis
Modular supply contracts for cobalt carbonate precursors is hardening buyer commitment structures in the battery materials sector. Huayou Cobalt leverages integrated refining assets in the Democratic Republic of Congo to secure feedstock continuity. Glencore anchors long-term offtake agreements with European cathode manufacturers through its trader-producer hybrid model. Umicore differentiates via closed-loop recycling capabilities that reduce virgin cobalt dependence.
Cobalt carbonate is a pink crystalline salt with the formula CoCO3, typically produced through precipitation from cobalt sulfate solutions using sodium carbonate; it serves primarily as a precursor for cobalt oxide and cobalt hydroxide in battery cathode manufacturing. The batteries segment dominates value capture as rechargeable battery applications absorb the majority of high-purity output, while the pigments segment occupies stable but slower-growing demand from ceramics and glass coloration. Chemical synthesis applications for cobalt carbonate catalysts compete for mid-grade material against thermal insulation uses in aerospace coatings.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape sourcing qualifications for cobalt carbonate entering European automotive supply chains. China's MIIT enforces GB standards for battery-grade purity that filter market access for imported material. Indonesia's downstream investment policies and the US IRA critical minerals provisions create divergent compliance pathways that stakeholders must reconcile when allocating capital between integrated mine-refine operations and merchant chemical processing.
Market Dynamics
The cobalt carbonate market operates under acute supply concentration pressure, with the Democratic Republic of Congo controlling the majority of mined cobalt and Indonesia rapidly consolidating downstream refining capacity through nickel-cobalt integrated processing hubs.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The regulation's escalating recycled cobalt thresholds force cathode manufacturers to secure certified carbonate streams, tightening qualification standards for battery-grade material entering European automotive supply chains.
- Indonesia's downstream investment policies:Indonesian government incentives attract Korean and Chinese chemical producers to construct hydrometallurgical facilities, expanding regional carbonate conversion capacity beyond traditional Chinese dominance.
- Lithium iron phosphate substitution limits:Mid-nickel and high-nickel cathode chemistries retain cobalt for thermal stability, preserving carbonate demand in premium electric vehicle battery segments where energy density remains non-negotiable.
Market Restraints
- Artisanal mining concentration in the DRC:Approximately seventy percent of global cobalt ore originates from a single country, exposing carbonate supply chains to geopolitical instability and ethical sourcing scrutiny from downstream automotive OEMs.
- Sulfuric acid and reagent cost volatility:Cobalt carbonate production depends on sulfuric acid for leaching and sodium carbonate for precipitation, with input cost swings compressing conversion margins for merchant chemical processors.
- Direct recycling technologies:Emerging black mass recovery methods threaten virgin carbonate demand by enabling cathode material regeneration without full chemical dissolution and re-precipitation cycles.
Strategic Opportunities
- US IRA critical minerals domestic content credits:The Inflation Reduction Act's tax incentives for North American battery supply chains create pull-through demand for carbonate converted within free-trade agreement countries, rewarding geographic diversification.
- Aerospace thermal insulation coatings:Cobalt carbonate-derived pigments for high-temperature ceramic coatings in turbine engines represent an underdeveloped application with stable offtake from defense and commercial aviation maintenance programs.
- Closed-loop industrial symbiosis:Integrated mine-refine operations that capture sulfur dioxide emissions for acid regeneration and recycle process water are automating cost structures that merchant processors cannot replicate.
Industry Challenges
- Battery-grade purity certification timelines:GB standards enforcement by China's MIIT and automotive OEM qualification protocols require eighteen-to-twenty-four month validation cycles for new carbonate supply sources, freezing out rapid market entry.
- Hydrometallurgical engineering talent scarcity:Solvent extraction circuit design and crystallization optimization expertise concentrates among a limited pool of specialists, constraining capacity expansion for junior chemical processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Carbonate Market |
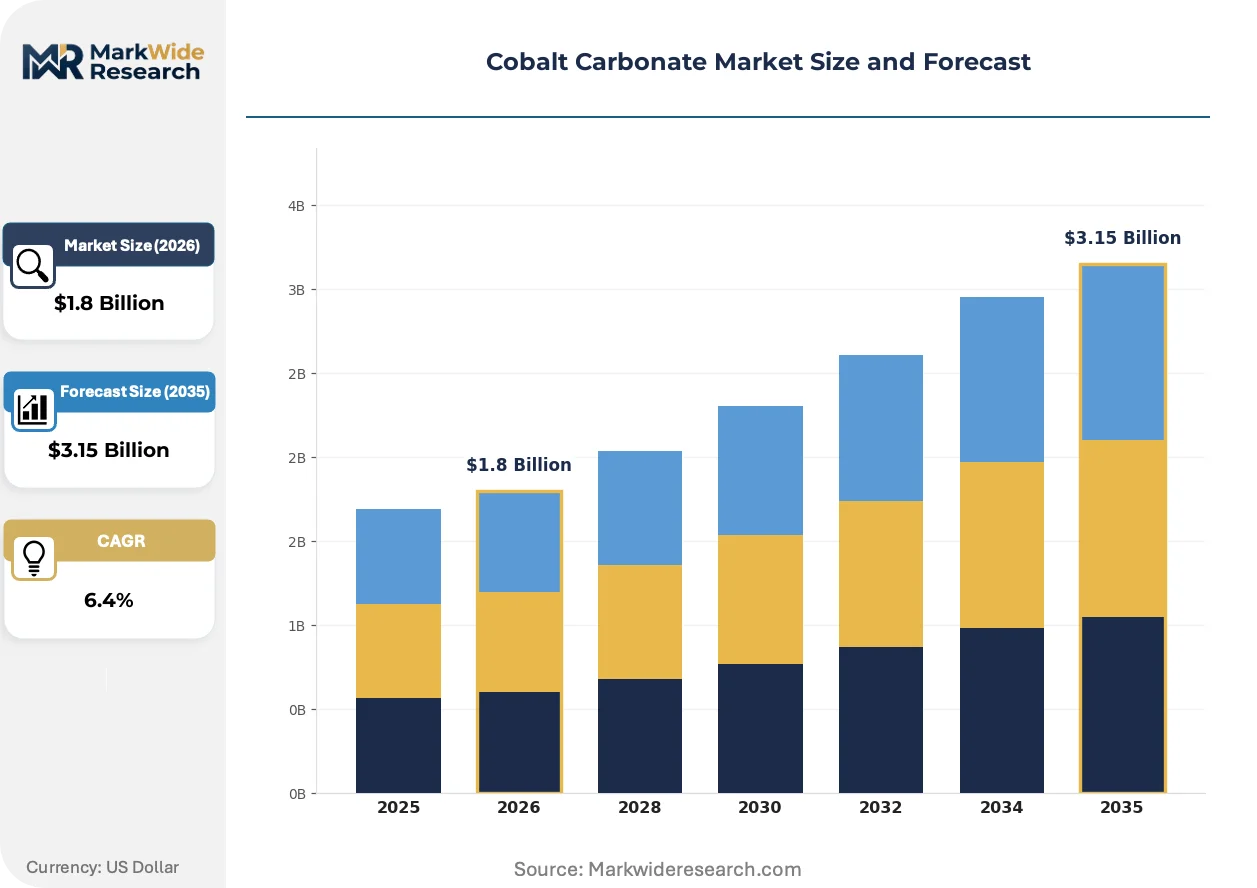
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Ceramics, Pigments, Catalysts End User: Aerospace, Electronics, Coatings, Automotive Application: Rechargeable Batteries, Thermal Insulation, Chemical Synthesis, Colorants Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Jinchuan Group International Resources Co. Ltd., Huayou Cobalt, Glencore, Sumitomo Metal Mining Co., Ltd., GEM Co., Ltd., China Molybdenum Co., Ltd., Eurasian Resources Group, Freeport-McMoRan Inc., Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Carbonate Market Emerging Trajectories
Continuous precipitation control systems and real-time purity monitoring are compressing the gap between battery-grade and technical-grade carbonate production, while regulatory carbon accounting is embedding emissions transparency into material passports.
Automated solvent extraction circuits with machine learning feedback loops are automating impurity rejection in cobalt sulfate purification stages. Korean cathode manufacturers deploy these systems to reduce batch-to-batch variation in carbonate precursor quality. The technology is automating quality assurance labor costs that previously required manual titration and ICP-MS verification at multiple production checkpoints.
China's dual carbon goals and GB standards enforcement by MIIT are tightening energy intensity caps on carbonate conversion facilities. Producers must document renewable electricity procurement and process heat recovery rates to maintain battery-grade certification eligibility. The policy is reshaping capital allocation toward integrated operations with captive power generation in Indonesia and the DRC.
Automotive OEMs now mandate supply chain due diligence documentation extending to artisanal mining origins, displacing anonymous spot market purchases. Tier-one cathode manufacturers respond by contracting directly with integrated traders possessing mine-site traceability systems. The behavioral shift concentrates procurement volume among qualified suppliers with blockchain-verified chain-of-custody capabilities, most visible in European and North American electric vehicle battery procurement tenders.
Cobalt Carbonate Market Segmentation
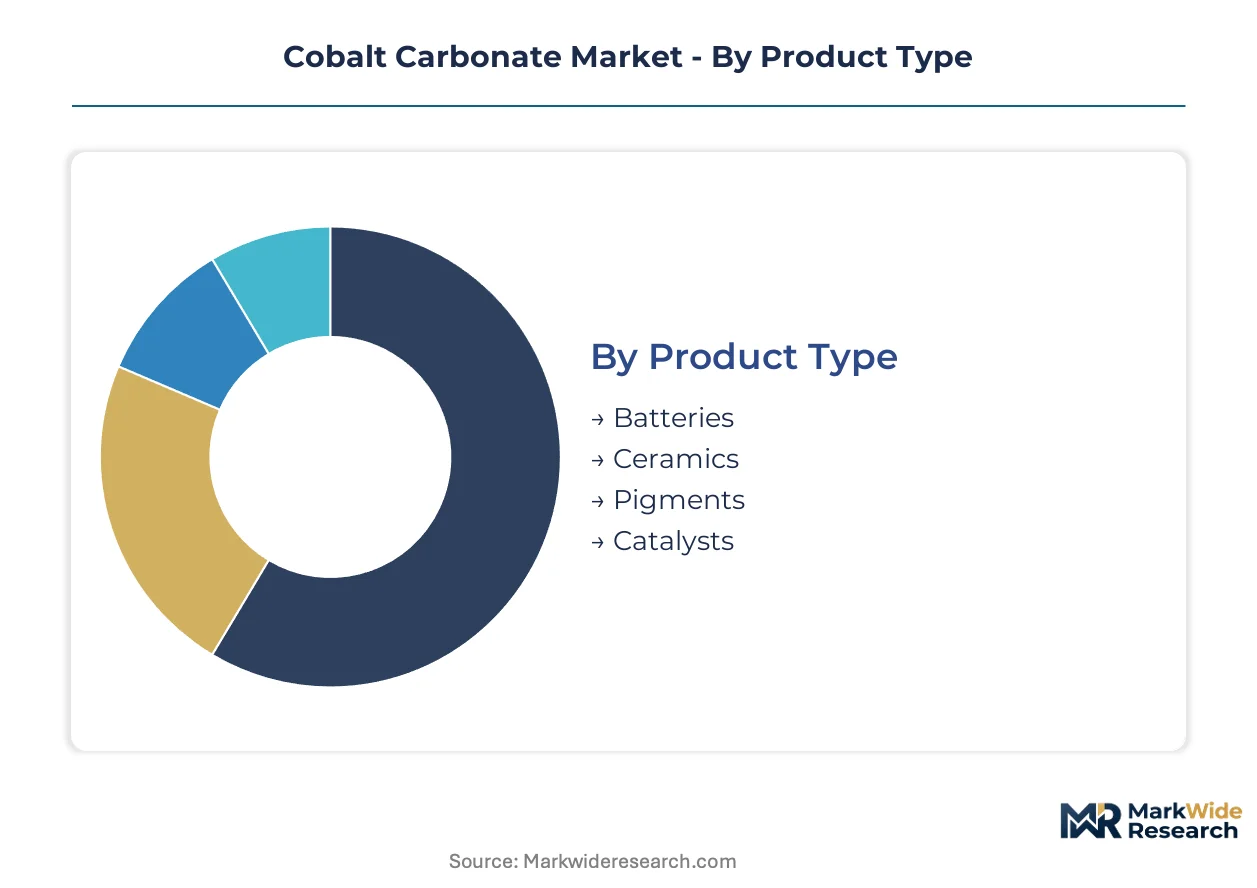
Segmentation in cobalt carbonate markets reveals how purity grades, end-use specifications, and channel structures fragment pricing power across the value chain. Battery-grade certification commands qualification premiums that technical-grade material cannot access, while direct sales relationships lock in cathode manufacturer offtake.
Product Type:
Capital intensity escalates steeply with purity thresholds, as battery-grade precipitation circuits require continuous crystallization control systems that technical-grade facilities omit.
- Batteries:High-purity cobalt carbonate with sub-50ppm iron and copper specifications serves as the precursor for cobalt oxide and cobalt hydroxide in lithium-ion cathodes. Korean and Chinese cathode manufacturers concentrate demand through long-term offtake contracts tied to GB standards compliance and automotive OEM qualification protocols. The segment absorbs the majority of hydrometallurgical conversion capacity expansion.
- Ceramics:Technical-grade material with moderate purity tolerances supplies glaze formulations and structural ceramic coloration. Italian and Spanish tile manufacturers maintain stable procurement from established European chemical distributors, with demand tied to construction cycle fluctuations rather than technology substitution risks.
- Pigments:Cobalt carbonate-derived blues and violets color glass, enamels, and artist materials. Demand concentrates in specialty coatings for high-temperature applications.
- Catalysts:Mid-grade material supports petrochemical oxidation processes and desulfurization applications. Refinery customers prioritize batch consistency over maximum purity.
Most installed capacity flows through Batteries. Expansion is steepest in Ceramics as Indonesian integrated operations capture technical-grade overflow.
End User:
Customer concentration patterns split between consolidated automotive OEM procurement desks and fragmented industrial buyers with limited volume leverage.
- Automotive:Electric vehicle manufacturers and their tier-one battery suppliers mandate supply chain due diligence documentation extending to mine-site origins. European OEMs enforce EU Battery Regulation recycled content thresholds through qualified supplier lists that exclude anonymous spot market sources. Procurement contracts now span five-to-seven year horizons with price-volume flexibility clauses.
- Electronics:Consumer electronics battery producers absorb mid-grade carbonate for power tool and portable device applications. Chinese contract manufacturers concentrate demand in Shenzhen and Dongguan manufacturing clusters, with sourcing decisions driven by MIIT GB standards enforcement rather than automotive-grade traceability requirements.
- Aerospace:Defense and commercial aviation maintenance programs purchase cobalt carbonate-derived thermal insulation coatings for turbine engine components. US Department of Defense procurement specifications favor domestic conversion sources qualifying under IRA domestic content provisions.
- Coatings:Industrial paint formulators use cobalt carbonate driers in alkyd resin systems. Demand tracks construction and marine maintenance cycles with limited growth momentum.
Automotive commands the dominant procurement volume. Electronics is gaining share fastest as energy storage applications proliferate beyond electric vehicles.
Application:
Application-level margins diverge based on qualification burden and substitution vulnerability.
- Rechargeable Batteries:Cathode precursor demand absorbs battery-grade output with non-negotiable purity specifications. Korean cathode manufacturers deploy automated solvent extraction with machine learning feedback loops to reduce batch-to-batch variation. The application ties directly to electric vehicle production schedules and mid-nickel cathode chemistry persistence against lithium iron phosphate substitution.
- Thermal Insulation:High-temperature ceramic coatings for aerospace and industrial furnaces utilize cobalt carbonate-derived pigments. Defense procurement programs in the US and European NATO members provide stable offtake with limited price elasticity.
- Chemical Synthesis:Cobalt carbonate serves as a reagent in organic oxidation reactions and specialty chemical production. Demand fragments across pharmaceutical and agrochemical intermediate manufacturers.
- Colorants:Glass, enamel, and ceramic coloration applications utilize technical-grade material with established formulation recipes. Italian and Spanish ceramic clusters maintain consistent procurement patterns.
Rechargeable Batteries anchors capacity utilization. Thermal Insulation shows the steepest expansion trajectory as aerospace original equipment manufacturers diversify coating suppliers.
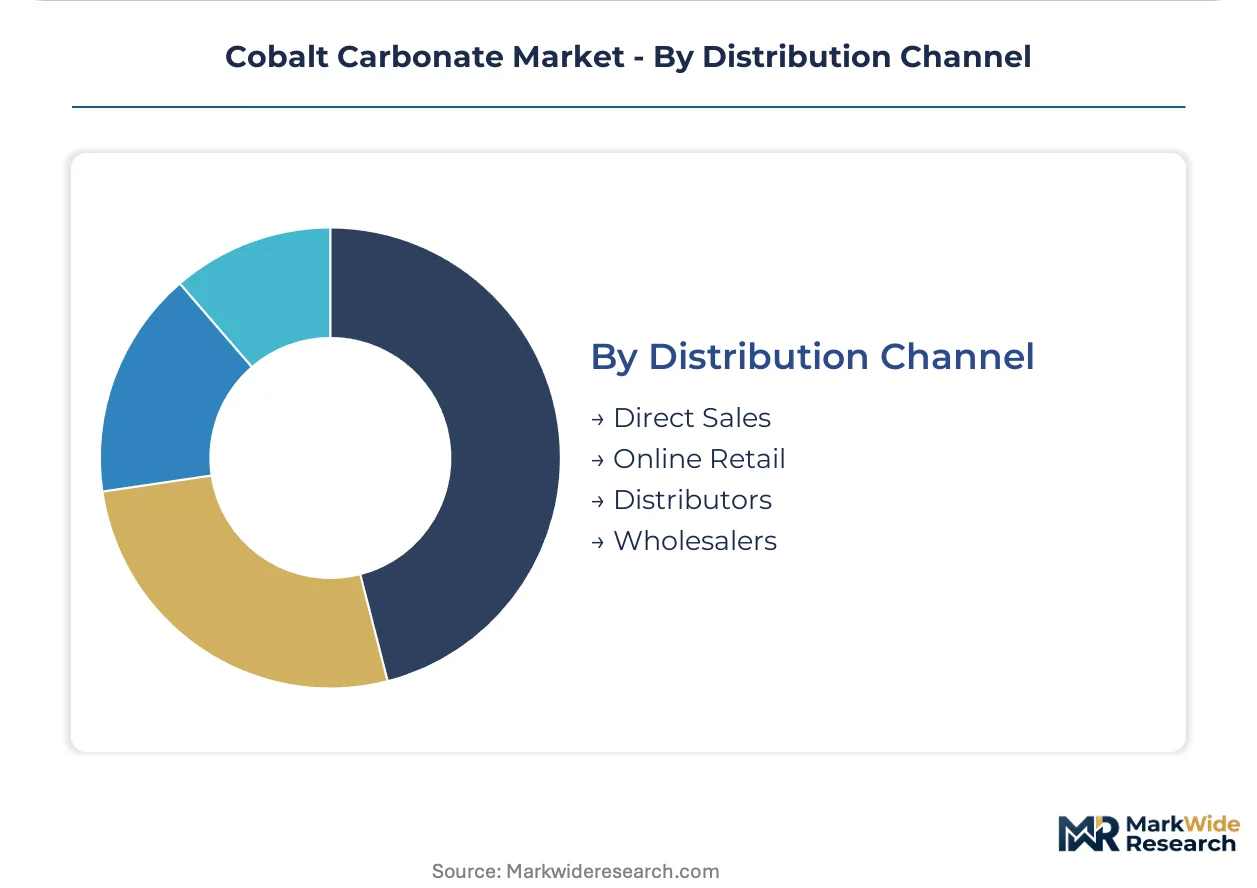
Distribution Channel:
Channel selection reflects customer scale, qualification requirements, and geographic proximity to conversion assets.
- Direct Sales:Integrated traders and chemical producers contract directly with tier-one cathode manufacturers and automotive OEMs. Huayou Cobalt and Glencore anchor procurement relationships through mine-site traceability systems and long-term offtake structures that bypass intermediary margin extraction.
- Distributors:Regional chemical distributors serve mid-tier ceramics, pigments, and catalyst customers with smaller lot sizes and less stringent certification requirements. European distributors maintain inventory positions in Rotterdam and Antwerp hub locations.
- Wholesalers:Bulk material aggregation serves technical-grade applications with standardized specifications and price-sensitive procurement behavior.
- Online Retail:Specialty chemical marketplaces accommodate research quantities and artisan ceramic producers with minimal volume requirements.
Direct Sales captures the dominant transaction value. Distributors are climbing fastest as Indonesian downstream capacity seeks qualified European and North American customer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cobalt carbonate industry traces its commercial scale to Belgian metallurgical refineries that pioneered hydrometallurgical cobalt recovery in the early twentieth century, establishing purity standards that persist in battery-grade specifications today. Contemporary production geography reflects this legacy while shifting toward integrated mine-refine operations in Central Africa and Southeast Asia.
Democratic Republic of Congo
Artisanal and industrial mining operations supply the majority of global cobalt ore feedstock. The country's national mining code imposes local content requirements and export licensing frameworks that shape downstream processor access. Kolwezi and Lubumbashi host concentrated refining infrastructure where Chinese chemical producers operate integrated leaching and precipitation circuits.
China
MIIT enforces GB standards for battery-grade purity that filter market access for imported cobalt carbonate material. The Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate cathode precursor production, with Zhejiang and Jiangsu provinces hosting the majority of hydrometallurgical conversion capacity serving Korean and domestic battery manufacturers.
Indonesia
Downstream investment policies attract Korean and Chinese chemical producers to construct nickel-cobalt integrated processing hubs in Morowali and Weda Bay. The government's industrial estate incentives and export restriction schedules on unprocessed ore accelerate regional carbonate conversion capacity expansion beyond traditional Chinese dominance.
Belgium
Closed-loop recycling capabilities at Hoboken and Olen facilities reduce virgin cobalt dependence for European cathode manufacturers. ECHA REACH registration requirements and the EU Battery Regulation's recycled content mandates reshape sourcing qualifications for carbonate entering automotive supply chains.
United States
IRA critical minerals domestic content credits create pull-through demand for carbonate converted within free-trade agreement countries. The Department of Defense procurement specifications for aerospace thermal insulation coatings favor domestic conversion sources, with limited merchant chemical processing capacity concentrated in legacy mining states.
Cobalt Carbonate Market Vendor Landscape
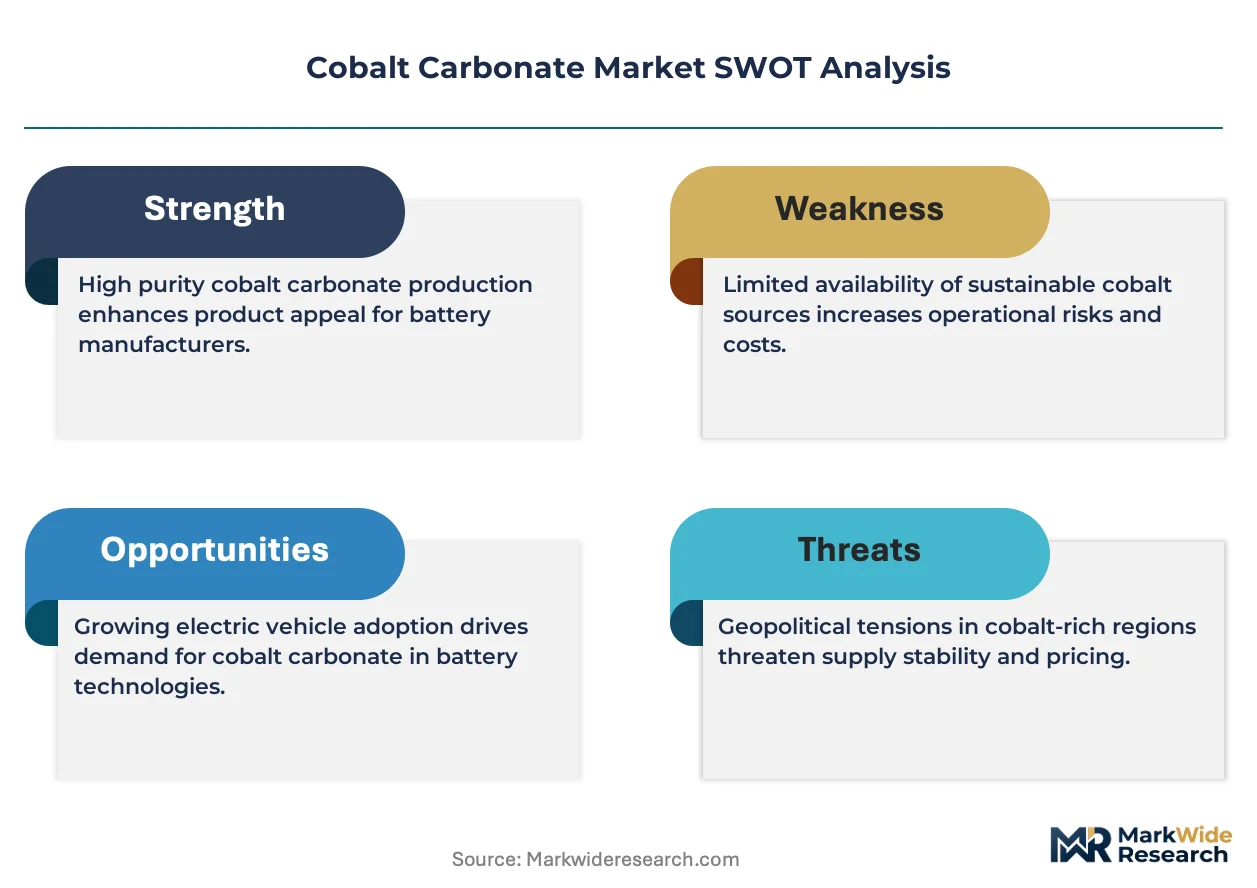
Premium-margin players sit above commodity-margin players across certification and traceability dimensions, with battery-grade qualification timelines creating defensive moats that technical-grade processors cannot breach. The market structure consolidates around integrated mine-refine operations and trader-producer hybrids that control feedstock origination. Three archetypes dominate: Congolese-integrated Chinese refiners, European closed-loop recyclers, and diversified mining conglomerates with cobalt by-product streams. Competitive moves center on long-term offtake contracting and geographic diversification of conversion assets to capture regulatory arbitrage.
Within the integrated refiner tier, Huayou Cobalt and China Molybdenum Co., Ltd. exemplify the Congolese-integrated Chinese archetype, leveraging upstream mine-site control to secure feedstock continuity. Glencore occupies a position as the trader-producer hybrid, anchoring procurement relationships through mine-site traceability systems. Umicore represents the European closed-loop recycling specialist, reducing virgin cobalt dependence through industrial symbiosis capabilities. These three entities illustrate the strategic divergence between upstream-integrated and recycling-focused competitive positioning.
| Leading Market Players |
|---|
| Jinchuan Group International Resources Co. Ltd. |
| Huayou Cobalt |
| Glencore |
| Sumitomo Metal Mining Co., Ltd. |
| GEM Co., Ltd. |
| China Molybdenum Co., Ltd. |
| Eurasian Resources Group |
| Freeport-McMoRan Inc. |
| Umicore |
| Others |
Supply Flow & Price Mechanics
Automotive OEM qualification protocols demanding eighteen-to-twenty-four month battery-grade purity certification cycles force merchant chemical processors to absorb extended working capital burdens, compressing margins and accelerating consolidation toward integrated mine-refine operations with captive feedstock security.
Pricing Analysis
Contract-based long-term offtake agreements dominate battery-grade transactions, with price differentiation anchored in certification tier and automotive OEM qualification status rather than spot-market volatility. Battery-grade material commands substantial premiums over technical-grade output due to GB standards compliance and traceability documentation burdens. Cost compression in mid-grade segments intensifies as Indonesian integrated operations expand technical-grade overflow capacity. Ceramics and pigment buyers exhibit highest price sensitivity, while automotive cathode manufacturers prioritize supply security over marginal cost differentials.
Supply Chain Analysis
Domestic content mandates embedded in the US IRA and Indonesia's downstream investment policies are rerouting carbonate conversion capacity toward free-trade agreement countries and integrated nickel-cobalt processing hubs. Supply concentrates in the Democratic Republic of Congo for ore feedstock, China for hydrometallurgical refining, and Indonesia for emerging downstream expansion. Production rests on sulfuric acid leaching reagents, sodium carbonate precipitation agents, and cobalt sulfate intermediate feedstock. Single-source vulnerability in DRC ore origination exposes processors to geopolitical disruption and ethical sourcing audit failures. Distribution runs through direct sales relationships with tier-one cathode manufacturers, bypassing intermediary channels for qualified battery-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cobalt carbonate market functions as a regulatory compounder where EU Battery Regulation recycled content thresholds and carbon footprint declaration mandates are restructuring procurement qualification requirements and accelerating demand for certified, traceable supply streams.
For Market Incumbents: Deepen backward integration into DRC mine-site assets and Indonesian hydrometallurgical hubs to secure feedstock continuity against merchant processor margin erosion. Invest in closed-loop recycling capabilities and blockchain-verified chain-of-custody systems to defend qualification status against emerging black mass recovery technologies threatening virgin carbonate demand. For New Entrants and Emerging Players: Automated solvent extraction circuits with machine learning feedback loops offer a technology-first wedge into quality-sensitive cathode precursor supply, bypassing eighteen-to-twenty-four month certification barriers through acquisition of distressed qualified assets. Target aerospace thermal insulation coating applications where defense procurement specifications favor domestic conversion sources and qualification protocols remain less congested than automotive battery-grade channels. For Investors and Strategic Acquirers: Asymmetric upside sits with European closed-loop recyclers possessing ECHA REACH registration and EU Battery Regulation compliance infrastructure, positioned to capture escalating recycled content premiums. Five-to-ten year viability hinges on cathode chemistry persistence against lithium iron phosphate substitution. Watch Korean cathode manufacturer qualification protocol changes as the inflection signal for recycled versus virgin carbonate demand balance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DRC Mining Assets | Huayou Cobalt and China Molybdenum demonstrate feedstock security through Kolwezi and Tenke Fungurume mine-site control. |
| Indonesian Hydrometallurgical Joint Venture | Korean and Chinese chemical producers capture Morowali industrial estate incentives to expand regional carbonate conversion capacity. |
| Closed-Loop Recycling Infrastructure Investment | Umicore's Hoboken facility reduces virgin cobalt dependence through industrial symbiosis aligned with EU Battery Regulation mandates. |
| Automotive OEM Direct Qualification Partnership | Tier-one cathode manufacturers bypass anonymous spot markets through blockchain-verified chain-of-custody contracting with integrated traders. |
| Aerospace Thermal Insulation Coating Certification | Defense procurement programs in NATO members provide stable offtake with limited price elasticity for high-temperature ceramic pigment applications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cathode manufacturer procurement directors, hydrometallurgical plant managers, automotive OEM sustainability officers, and chemical distribution channel partners with secondary validation from SEC 10-K filings, customs and trade data, MIIT GB standards documentation, and EU Battery Regulation implementation guidance. Bottom-up capacity and demand modeling triangulated against top-down market sizing from trade flow analysis.
Segment-weighting approaches distributed value and volume projections across purity grade tiers, end-use applications, and regional production hub configurations throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating electric vehicle production schedules, cathode chemistry persistence assumptions, and regulatory compliance timeline impacts. Industry-specific inputs included solvent extraction circuit capacity utilization rates and battery-grade certification pipeline backlogs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium iron phosphate substitution acceleration, DRC geopolitical instability, and direct recycling technology commercialization timelines. Assumptions reflect documented stakeholder input and disclosed regulatory frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Manganese Mining Market