
 Feed Supplements Market | 2026-2036
Feed Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Supplements Market Analysis
REACH compliance is rebalancing the cost-of-entry calculus for European feed additive manufacturers, forcing reformulation investments that smaller blenders cannot absorb. Cargill leverages its captive grain origination network to backward-integrate into premix production across multiple continents. BASF anchors its position through proprietary encapsulation technologies that protect vitamin stability during pelleting. DSM differentiates via its specialized algae-derived omega-3 platforms for aquaculture feed applications.
Feed supplements comprise nutritionally active substances including minerals, vitamins, amino acids, and probiotics that are incorporated into compound feeds or administered directly to livestock to correct dietary deficiencies, enhance feed conversion ratios, or support physiological functions such as immune response and reproductive performance. These inputs typically contain active concentrations ranging from trace levels in mineral premixes to major proportions in lysine or methionine supplements, and they are manufactured through fermentation, chemical synthesis, or extraction processes before blending into carrier matrices. Amino acids command the deepest margin pools among product types due to their indispensability in monogastric diets and limited synthetic substitution options. Probiotics represent the fastest-expanding category as antibiotic growth promoter bans in poultry and swine operations accelerate microbiome-focused alternatives. Powder and liquid forms dominate volume, though pelletized formats are gaining share in automated cattle feeding systems.
The European Food Safety Authority evaluates all novel feed additives through centralized scientific opinions, while the FDA's Center for Veterinary Medicine enforces Good Manufacturing Practice standards for medicated feeds in the United States. China's Ministry of Agriculture and Rural Affairs maintains a positive-list approach to feed additive approval, creating divergent market access conditions that multinational suppliers must navigate through separate registration pathways. Stakeholders should monitor how divergent regulatory timelines between jurisdictions affect product launch sequencing and inventory allocation across regional distribution networks.
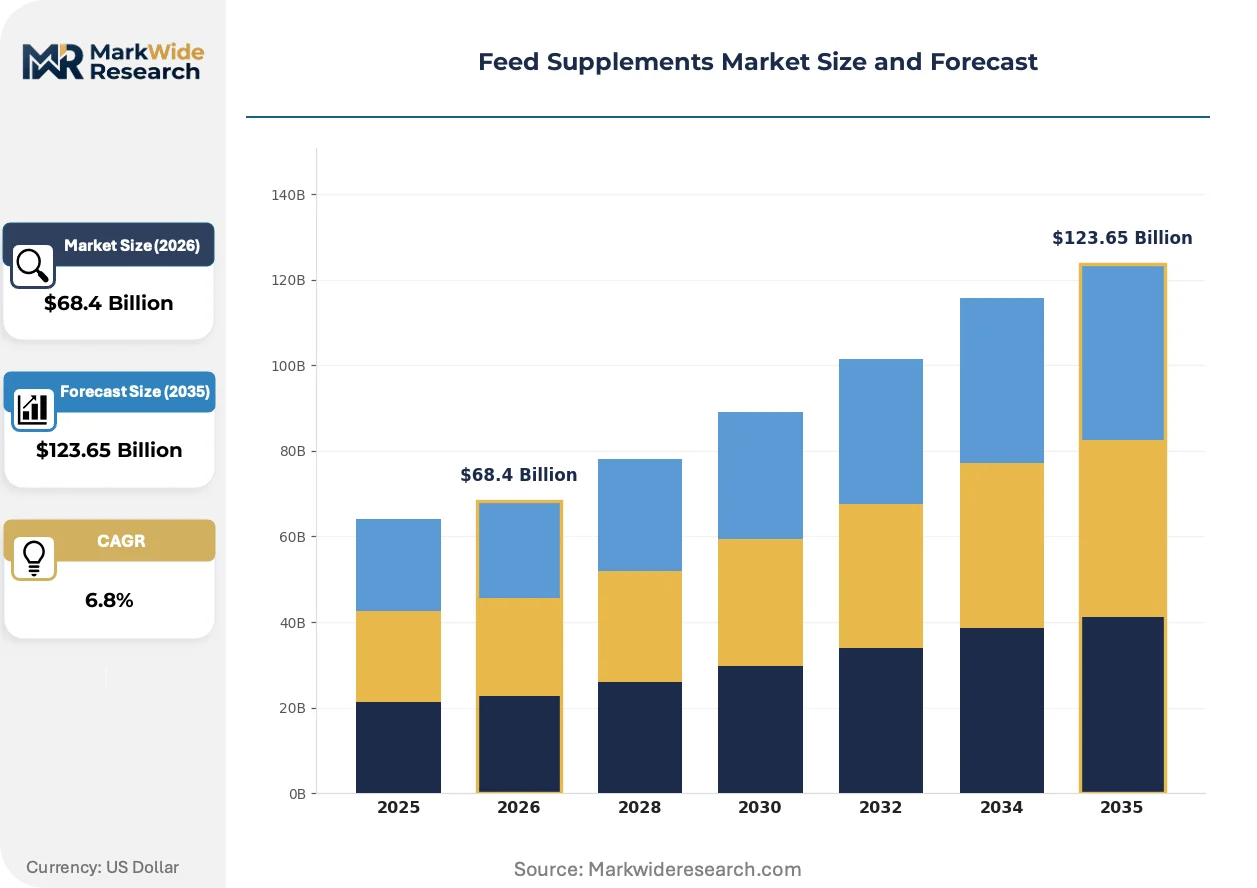
Market Dynamics
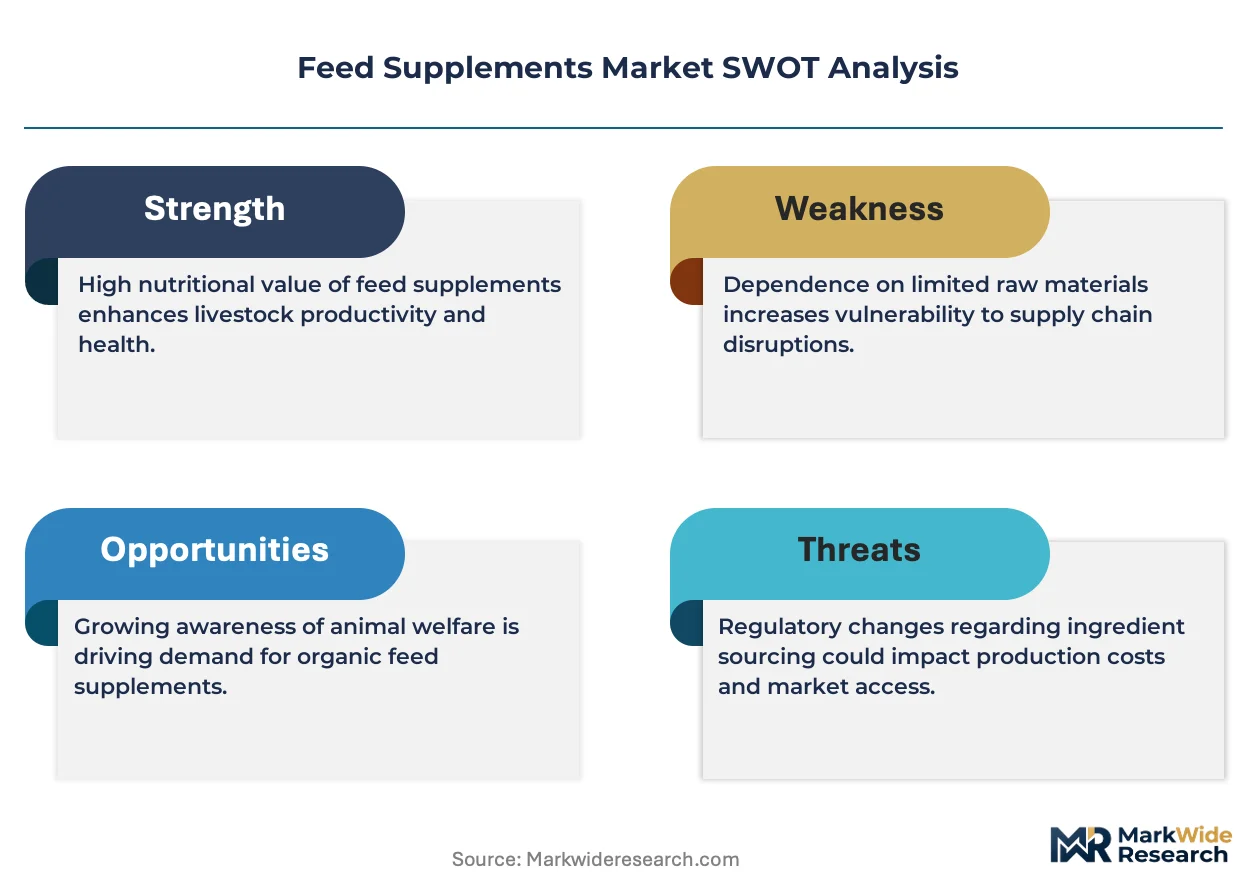
REACH compliance is rebalancing the cost-of-entry calculus for European feed additive manufacturers, forcing reformulation investments that smaller blenders cannot absorb while consolidating advantage among scale operators with captive R&D infrastructure.
Growth Catalysts
- EU Farm to Fork Strategy:Tightening permitted additive lists and residue thresholds accelerates demand for next-generation microbiome solutions in poultry and swine operations.
- Intensive feedlot expansion in Brazil's Mato Grosso:Bulk mineral and amino acid procurement concentrates as cattle finishing operations industrialize feed conversion optimization.
- Encapsulation technologies:Proprietary coating systems that protect vitamin stability during high-temperature pelleting unlock premium pricing for heat-sensitive micronutrient formulations.
Market Restraints
- Phosphate and trace mineral input volatility:Concentrated mining operations in Morocco and China expose premix manufacturers to supply disruption and margin compression.
- EFSA centralized scientific opinion timelines:Novel feed additive approvals face 18-24 month evaluation windows that delay product commercialization and tie up regulatory capital.
- Plant-based protein substitution:Fermented single-cell proteins and insect meal displace conventional amino acid supplementation in aquaculture and pet food formulations.
Strategic Opportunities
- Underpenetrated Vietnamese aquaculture:Shrimp and pangasius producers lack access to algae-derived omega-3 platforms that command premium positioning in export-certified feed.
- US dairy cattle micronutrient programs:Higher milk quality benchmarks create pull for precision-blended mineral premixes in expanding operations across Wisconsin and California.
- China's positive-list feed additive approval system:Separate registration pathways for multinational suppliers create first-mover advantages for firms with established MARA dossier capabilities.
Industry Challenges
- Fermentation scale-up talent scarcity:Microbiome engineering and bioprocess optimization expertise concentrates at a handful of academic-industry hubs, constraining probiotic manufacturing expansion.
- Legacy premix facility reconfiguration:Existing blending plants require capital-intensive clean-room upgrades and automated dosing systems to meet FDA Good Manufacturing Practice standards for medicated feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Supplements Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Amino Acids, Probiotics End User: Poultry, Cattle, Swine, Aquaculture Form: Powder, Granules, Liquid, Pellets Distribution Channel: Online, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Cargill, Archer Daniels Midland, BASF, DSM, Evonik Industries, Nutreco, Kemin Industries, Alltech, Adisseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Supplements Market Emerging Trajectories
Automation, regulatory stringency, and buyer consolidation are compressing traditional value chain configurations while opening specialized niches for precision-formulation capabilities.
Near-infrared spectroscopy coupled with robotic dosing systems is automating real-time premix quality verification and batch correction in high-throughput compound feed mills. Large integrators in US broiler operations deploy these systems to eliminate human sampling lag and reduce vitamin over-formulation safety margins. The technology is automating specification compliance while compressing the role of traditional quality-control laboratories.
China's Ministry of Agriculture and Rural Affairs maintains divergent approval timelines from EFSA and FDA pathways, forcing multinational suppliers to sequence product launches across jurisdictions rather than coordinating global rollouts. The regulatory friction most affects novel probiotic strains and enzyme preparations requiring extensive safety dossiers. Firms with established MARA registration infrastructure capture 12-18 month commercialization advantages over competitors dependent on third-party agents.
Buyer concentration among Brazilian protein integrators and North American dairy cooperatives is compressing distributor margins and forcing premix suppliers to negotiate direct formulation partnerships. Traditional independent feed dealers lose share to captive supply arrangements where processors specify micronutrient matrices. The shift is most visible in Mato Grosso feedlot corridors and California Central Valley dairy clusters where three buyers control sixty percent of amino acid procurement volume.
Feed Supplements Market Segmentation
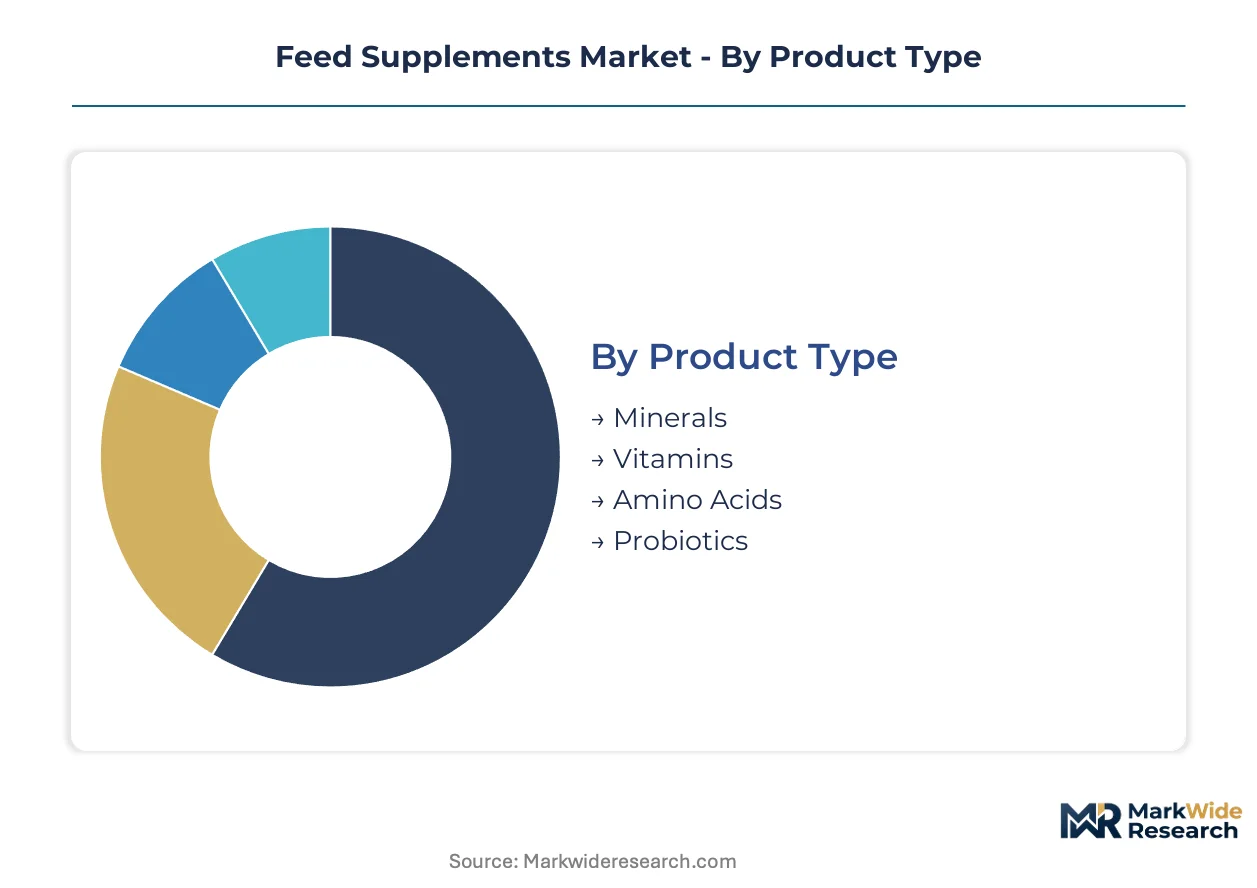
Feed supplement segmentation reveals divergent margin architectures across product chemistry, species physiology, and supply chain configuration. Each dimension carries distinct regulatory exposure and customer concentration profiles that reshape competitive positioning.
Product Type:
Volume concentration sits with commoditized mineral inputs, while premium capture flows to proprietary fermentation-derived categories.
- Amino Acids:Synthetic L-lysine and DL-methionine formulations command the deepest margin pools due to their indispensability in monogastric diets and limited substitution pathways. Demand concentrates in Brazil's Mato Grosso feedlot corridors where cattle finishing operations industrialize feed conversion optimization.
- Probiotics:Live microbial cultures including Lactobacillus and Bacillus strains represent the fastest-expanding trajectory as EFSA-enforced antibiotic growth promoter bans accelerate microbiome-focused alternatives across European poultry and swine operations.
- Minerals:Trace element premixes containing zinc, copper, and selenium correct dietary deficiencies at mass-market price points.
- Vitamins:Fat-soluble and water-soluble micronutrients require encapsulation technologies to survive high-temperature pelleting processes.
Today's leader: Amino Acids. Tomorrow's challenger: Probiotics.
End User:
Species-specific digestive physiology dictates formulation complexity and regulatory scrutiny intensity.
- Poultry:Intensive broiler operations drive the highest volume throughput for amino acid and enzyme supplementation, with near-infrared spectroscopy systems automating real-time premix verification in US integrator facilities.
- Cattle:Dairy operations in Wisconsin and California create pull for precision-blended mineral premixes as milk quality benchmarks tighten.
- Swine:Post-weaning diets rely heavily on acidifiers and zinc oxide alternatives facing REACH compliance reformulation pressures.
- Aquaculture:Shrimp and pangasius producers in Vietnam lack access to algae-derived omega-3 platforms that command premium positioning in export-certified feed.
Poultry maintains volume dominance. Aquaculture offers the steepest expansion trajectory for novel ingredient platforms.
Form:
Physical presentation determines manufacturing capital requirements and handling automation compatibility.
- Powder:Dominates volume through cost-efficient blending and broad compatibility with existing feed mill infrastructure.
- Liquid:Enables precise dosing in automated systems and superior bioavailability for certain organic trace minerals.
- Granules:Reduces dust exposure and improves flowability in mechanical handling equipment.
- Pellets:Gaining share in automated cattle feeding systems where uniform particle size prevents segregation and ensures consistent intake.
Powder leads current volume. Pelletized formats are climbing fastest in industrialized livestock corridors.
Distribution Channel:
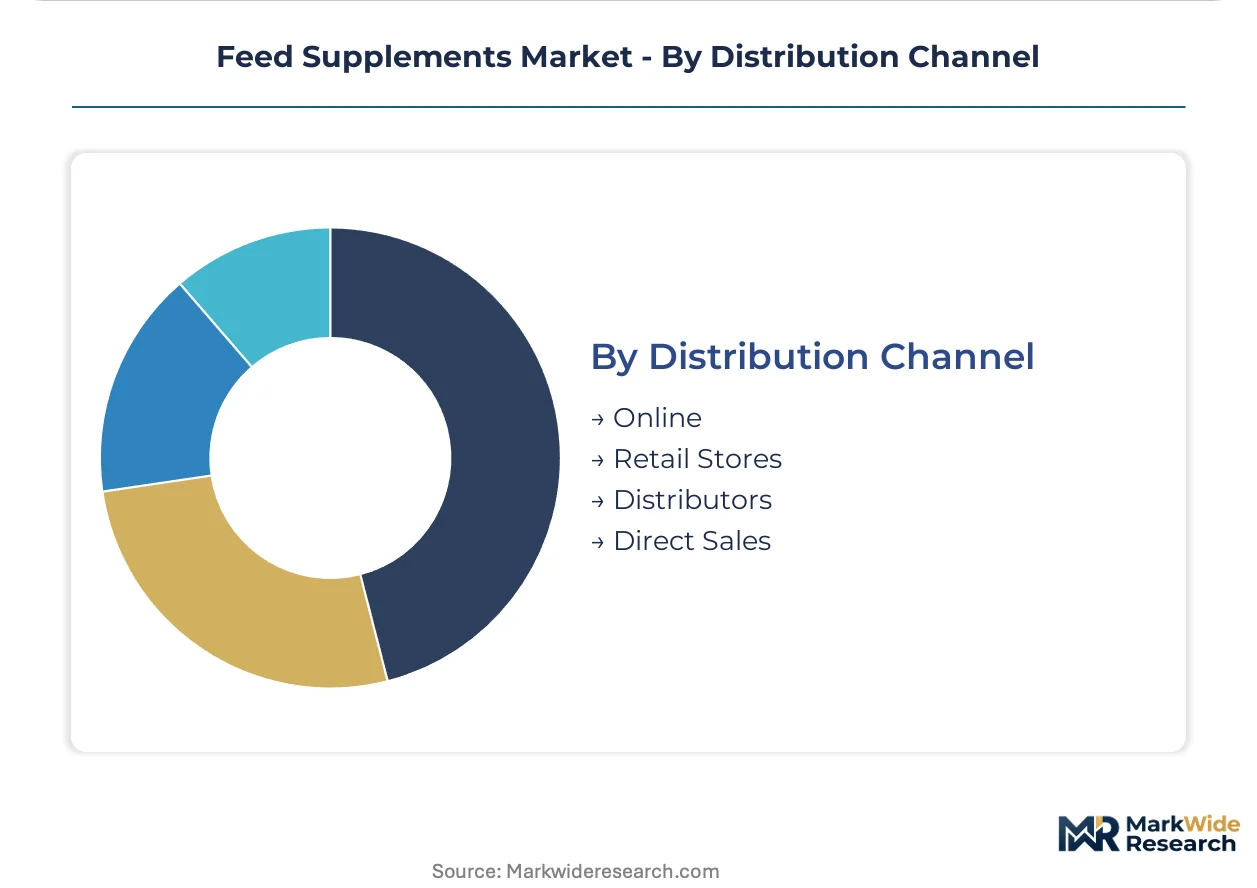
Channel selection reflects customer scale, technical service requirements, and geographic market maturity.
- Distributors:Independent feed dealers lose share to captive supply arrangements where Brazilian protein integrators and North American dairy cooperatives specify micronutrient matrices directly.
- Direct Sales:Large compound feed manufacturers negotiate formulation partnerships that compress traditional distributor margins.
- Retail Stores:Serves small-scale livestock operators and hobby farmers with packaged supplement solutions.
- Online:Emerging channel for specialty probiotic strains and traceability-certified organic mineral products.
Direct sales commands the premium tier. Distributor networks face structural compression from buyer consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed supplement formulation expertise clusters around veterinary science hubs in the Netherlands, Iowa, and São Paulo, with regulatory affairs specialists concentrating near EFSA in Parma and FDA in Rockville.
United States
Dairy cooperatives in Wisconsin and California drive precision mineral premix demand as milk quality benchmarks tighten. FDA's Center for Veterinary Medicine enforces Good Manufacturing Practice standards for medicated feeds. The California Central Valley dairy cluster sees three buyers controlling sixty percent of amino acid procurement volume through direct formulation partnerships.
Brazil
Intensive feedlot expansion in Mato Grosso concentrates bulk mineral and amino acid procurement as cattle finishing operations industrialize. ANVISA maintains residue threshold oversight for imported additive formulations. São Paulo-based protein integrators negotiate captive supply arrangements that compress traditional independent dealer margins across the cerrado feedlot corridor.
China
Aquaculture feed mills in Guangdong and Fujian provinces seek algae-derived omega-3 platforms for export-certified shrimp diets. The Ministry of Agriculture and Rural Affairs maintains a positive-list approach to feed additive approval with divergent timelines from Western regulators. Yangtze River Delta compound feed manufacturers automate premix verification through near-infrared spectroscopy systems.
Germany
REACH compliance forces reformulation investments among industrial premix blenders serving European poultry and swine operations. ECHA oversees chemical safety dossiers while EFSA evaluates novel probiotic strains through centralized scientific opinions. Lower Saxony's feed industry cluster hosts fermentation scale-up facilities for microbiome-focused antibiotic alternatives.
Vietnam
Shrimp and pangasius producers in the Mekong Delta lack access to premium omega-3 platforms that command positioning in EU and US export markets. The national agricultural regulator maintains evolving standards for aquaculture feed safety. Ho Chi Minh City-based feed mills concentrate procurement of conventional amino acid supplements while awaiting novel ingredient registrations.
Feed Supplements Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure consolidates around scale operators with captive R&D infrastructure and captive grain origination networks, while smaller blenders face absorption pressures from compliance costs. Three archetypes dominate: integrated agribusiness giants with backward integration into premix production, fermentation-focused biotechnology specialists, and regional blending operations serving niche species segments. Competitive moves center on strategic partnerships for distribution access and capacity expansion in high-growth aquaculture corridors.
Within the diversified agribusiness tier, Cargill and Archer Daniels Midland exemplify scale operators leveraging captive supply chain infrastructure across multiple continents. BASF and DSM occupy positions among specialty chemical and biotechnology-focused players, with the latter representing algae-derived platform specialists. Evonik Industries anchors the synthetic amino acid segment. These named entities illustrate how competitive positioning stratifies between volume-driven grain-integrated operations and premium-capture fermentation technology holders.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| BASF |
| DSM |
| Evonik Industries |
| Nutreco |
| Kemin Industries |
| Alltech |
| Adisseo |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap premix blenders across Europe's Lower Saxony cluster maintain pricing discipline through long-term offtake contracts with Moroccan phosphate miners, insulating formulated products from spot volatility while compressing margins for distributors lacking equivalent upstream anchoring.
Pricing Analysis
Bundled technical service contracts separate premium probiotic formulations from unbundled commodity mineral premixes sold on spot terms. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with EFSA-registered novel strains commanding substantial premiums over generic additive blends. Cost compression in standard-tier amino acids is intensifying because Brazilian protein integrators negotiate direct formulation partnerships that bypass traditional dealer markups. Small-scale livestock operators and hobby farmers exhibit highest price sensitivity, while large compound feed manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with concentrated phosphate mining operations in Morocco and China that expose premix manufacturers to supply disruption. Geographic supply concentration centers on China for fermentation-derived amino acids, the Netherlands for vitamin encapsulation technologies, and Brazil for regional mineral blending. Raw material dependencies rest on synthetic lysine and methionine feedstocks, algae-derived omega-3 biomass, and organic trace mineral chelates. Tariff exposure on Chinese fermentation imports presents structural risk. Distribution runs through direct sales channels for large integrators and compressed independent dealer networks for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as milk quality benchmarks in Wisconsin and California drive demand-shift toward precision-blended mineral premixes with verified micronutrient matrices.
For Market Incumbents: Extend encapsulation technology platforms into heat-sensitive probiotic categories before generic competitors replicate BASF's proprietary coating systems. Consolidate position through backward integration into captive algae cultivation for omega-3 platforms, defending against fermentation scale-up talent scarcity that constrains rapid competitor expansion. Prioritize MARA dossier capabilities in China to maintain 12-18 month commercialization advantages. For New Entrants and Emerging Players: The price-point gap between DSM's premium algae-derived omega-3 platforms and conventional fish oil alternatives opens viable entry space in Vietnamese aquaculture. Target shrimp and pangasius producers in the Mekong Delta lacking access to export-certified feed ingredients. Pursue white-space in automated pelletized mineral systems for Brazilian feedlot corridors. Anchor go-to-market through technical service partnerships with Ho Chi Minh City-based feed mills awaiting novel ingredient registrations. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blending operations serving niche species segments without captive R&D infrastructure. Long-term viability favors fermentation-focused biotechnology specialists with proprietary strain libraries over commoditized mineral premixers facing REACH compliance absorption pressures. Acquisition targets should demonstrate established regulatory affairs capabilities across EFSA, FDA, and MARA pathways. Watch EFSA centralized scientific opinion timelines as inflection indicator for probiotic category expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Proprietary coating systems unlock premium pricing for heat-sensitive vitamins during high-temperature pelleting. |
| MARA Registration Infrastructure Buildout | Established dossier capabilities in China capture 12-18 month commercialization advantages over agent-dependent competitors. |
| Algae Cultivation Capacity Expansion | In-house omega-3 biomass production secures supply for aquaculture export-certified feed formulations. |
| Near-Infrared Spectroscopy Integration | Automated premix verification eliminates human sampling lag in US broiler integrator facilities. |
| Direct Formulation Partnerships | Bypassing distributor networks captures margin compression from Brazilian protein integrator buyer consolidation. |
Methodological Framework
Bottom-up livestock operation modeling reconciled against top-down feed additive production tracking forms the analytical core of this study. Primary interviews with compound feed procurement directors, premix plant managers, regulatory affairs specialists at EFSA and MARA, and veterinary nutritionists at Brazilian protein integrators combined with secondary validation from customs records, SEC filings of diversified agribusiness conglomerates, EFSA scientific opinion databases, and MARA positive-list publications. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of amino acid and probiotic pricing trajectories informed projection frameworks across the modeling period. Segmentation dimensions modeled include product chemistry, species physiology, physical form, and distribution channel configuration. CAGRs were derived from fitted growth curves applied to verified baseline consumption data. Industry-specific forecast inputs incorporated EFSA evaluation pipeline backlogs, Mato Grosso feedlot expansion permits, and California dairy herd consolidation patterns.
Caveats apply where phosphate export restrictions, EFSA scientific opinion delays, or MARA approval timeline extensions could materially shift the outlook. Forecasts reflect assumptions about continued antibiotic growth promoter enforcement in European poultry and swine operations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Animal Digest Market