
 Wire Livestock Panels Market | 2026-2036
Wire Livestock Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Livestock Panels Market Analytics
The price-performance gap between premium welded-steel panels and commodity-grade wire mesh is hardening. Behlen Country leverages its Nebraska manufacturing footprint to sustain cost leadership in galvanized systems. Red Brand competes through vertical integration into wire drawing, while Gallagher differentiates via electrified containment integration.
Wire livestock panels are welded or woven grid structures, typically fabricated from gauge steel or galvanized wire with mesh openings between four and six inches, designed to confine cattle, equine, and small ruminants within paddocks, corrals, and handling facilities. High strength panels command the steepest price premiums due to reinforced frame tubing and continuous weld seams. Square panels anchor volume demand among commercial feedlots, whereas flexible panels represent the fastest-growing configuration for rotational grazing systems.
Farmers and ranchers navigate ASTM A641 galvanizing standards alongside state-level fencing ordinances that dictate minimum post depth and bracing requirements. The USDA Natural Resources Conservation Service cost-share programs shape procurement patterns by subsidizing perimeter containment upgrades. Stakeholders must weigh rising steel input volatility against the long replacement cycles that lock in brand loyalty across agricultural cooperatives.
Market Dynamics
ASTM A641 galvanizing standards and EPA corrosion-prevention mandates are hardening specification requirements across agricultural procurement, forcing fabricators to upgrade weld quality and coating thickness while ranchers face extended replacement cycles that lock in supplier relationships.
Growth Catalysts
- USDA NRCS cost-share programs:Conservation Service subsidies for perimeter containment upgrades accelerate replacement demand across Great Plains cattle operations.
- Rotational grazing systems:Flexible panel configurations enable paddock subdivision without permanent infrastructure, driving adoption among mid-scale ruminant producers.
- High-strength galvanized steel:Reinforced frame tubing with continuous weld seams commands premium positioning in commercial feedlot specifications.
Market Restraints
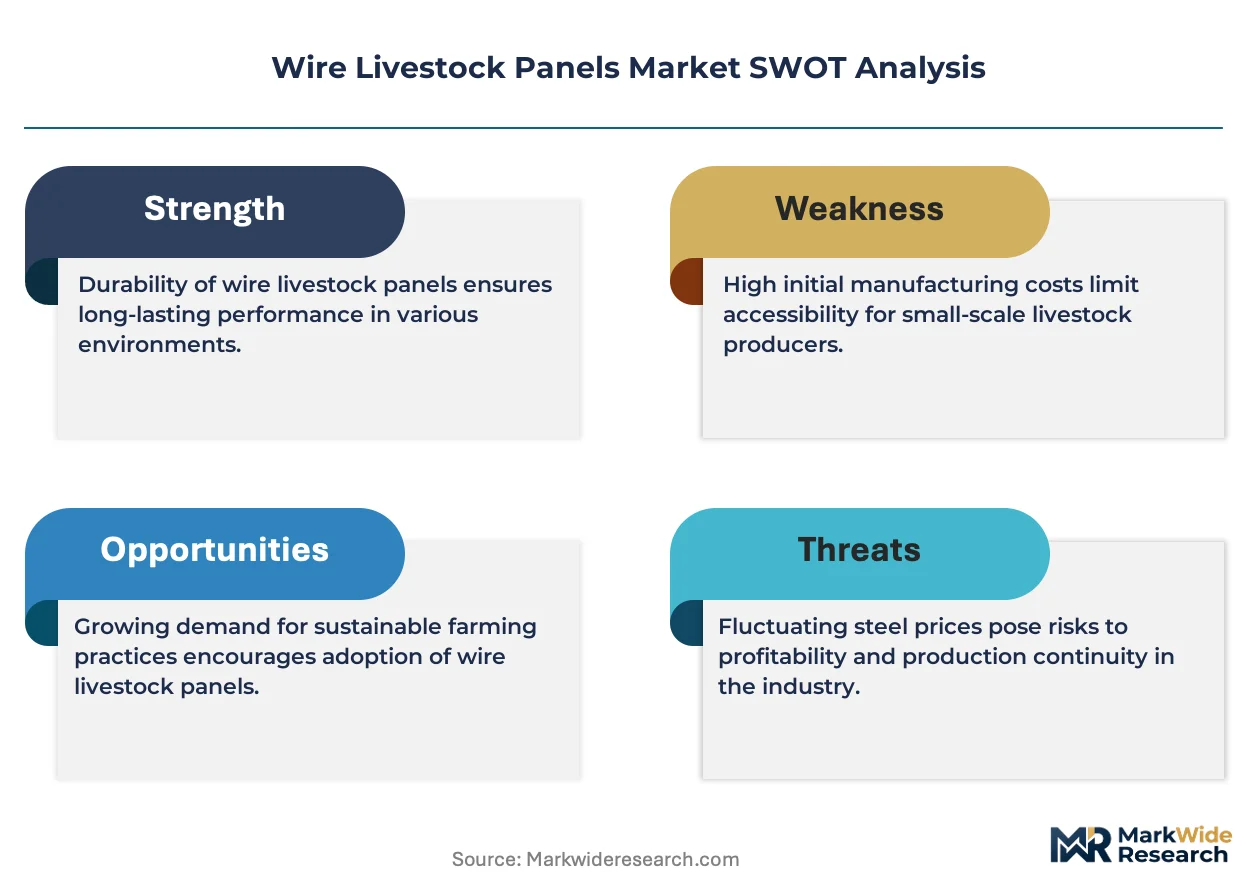
- Steel input volatility:Hot-rolled coil price swings compress fabrication margins and destabilize contract pricing for agricultural cooperatives.
- State-level fencing ordinances:Variable post depth and bracing requirements across jurisdictions fragment product standardization and increase compliance costs.
- Polymer composite substitutes:Lightweight plastic panel alternatives gain traction in equine and small ruminant containment, threatening wire mesh share in non-cattle segments.
Strategic Opportunities
- Electrified containment integration:Convergence of physical barrier panels with energizer systems opens premium positioning in predator-dense ranching regions.
- Texas Panhandle feedlot corridor:Concentrated cattle finishing operations present volume consolidation potential for panel suppliers with regional logistics scale.
- Canadian Prairie provinces:Underpenetrated bison and elk ranching sectors offer expansion vectors for heavy-duty welded systems beyond traditional cattle markets.
Industry Challenges
- Certified welder scarcity:Continuous seam welding requirements for high-strength panels outstrip qualified labor availability in rural fabrication hubs.
- Legacy handling facility retrofits:Integration of modern panel dimensions with existing corral infrastructure demands custom fabrication and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Livestock Panels Market |
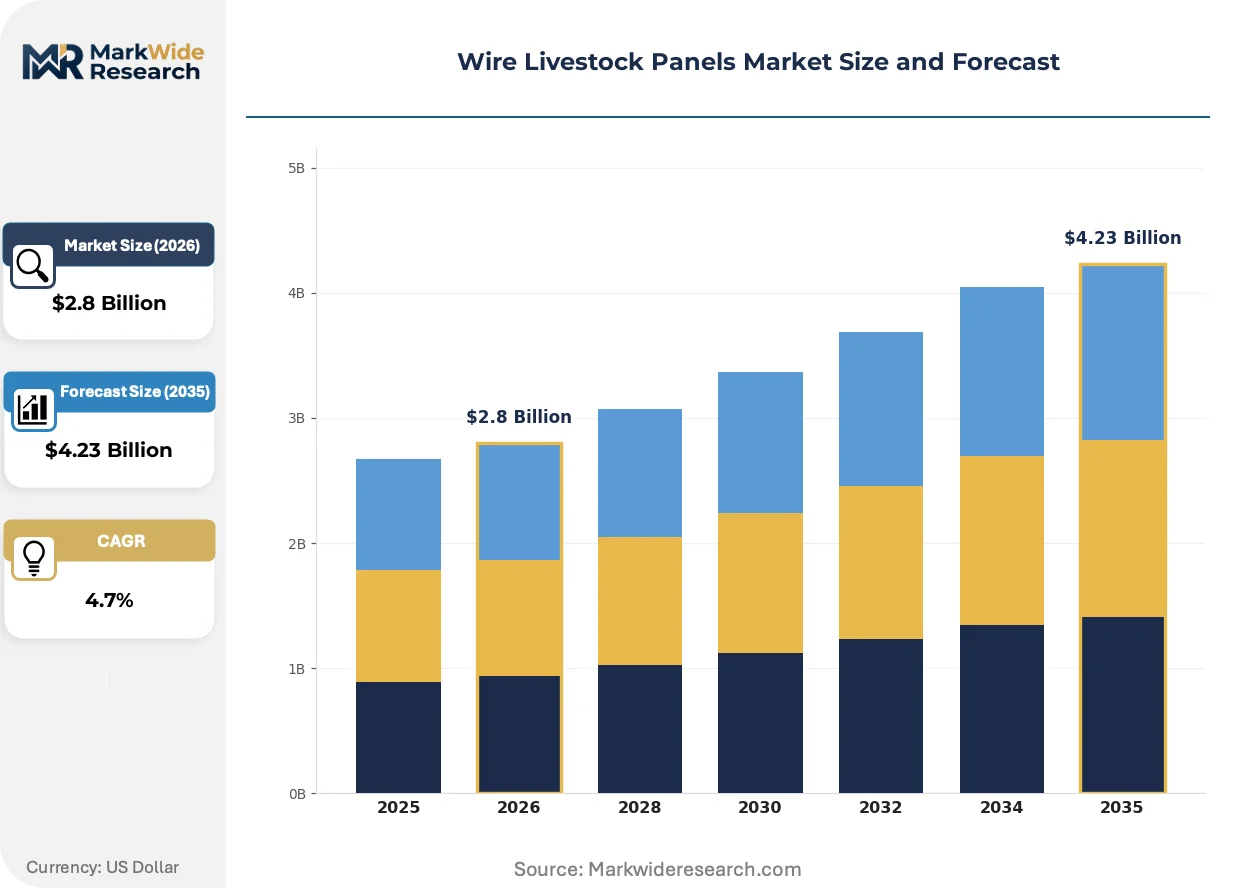
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Panels, Round Panels, Flexible Panels, High Strength Panels Material: Steel, Galvanized Wire, PVC Coated Wire, Aluminum End User: Farmers, Livestock Breeders, Agricultural Cooperatives, Ranchers Application: Fencing, Livestock Containment, Property Boundaries, Gardens |
| Companies Covered | Behlen Country, Red Brand, OK Brand, CK Manufacturing, Priefert, Tarter, Ramm Fence Systems, Gallagher, Red River Arenas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Livestock Panels Market Evolving Landscape
Robotic welding stations and precision galvanizing lines are compressing unit economics for high-specification panels while regulatory pressure on coating environmental performance intensifies. Three developments are restructuring competitive positioning.
Robotic MIG welding systems are automating seam consistency in high-volume panel production. Commercial feedlot suppliers in Nebraska and Kansas are retrofitting lines to capture ASTM A641 certification premiums. This automation is compressing the cost gap between premium welded systems and commodity-grade imports.
EPA corrosion-prevention rules are tightening volatile organic compound limits in galvanizing bath operations. Fabricators must install fume capture and wastewater treatment systems or face facility restrictions. Small Midwestern shops lacking capital access are consolidating into larger regional producers with compliant infrastructure.
Cooperative procurement pooling is displacing individual ranch purchases in the Northern Plains. Groups of 15-30 operations now negotiate panel specifications and delivery scheduling through agricultural extension networks. This concentration is most visible in Montana and Wyoming where dispersed geography previously favored fragmented buying.
Wire Livestock Panels Market Segmentation
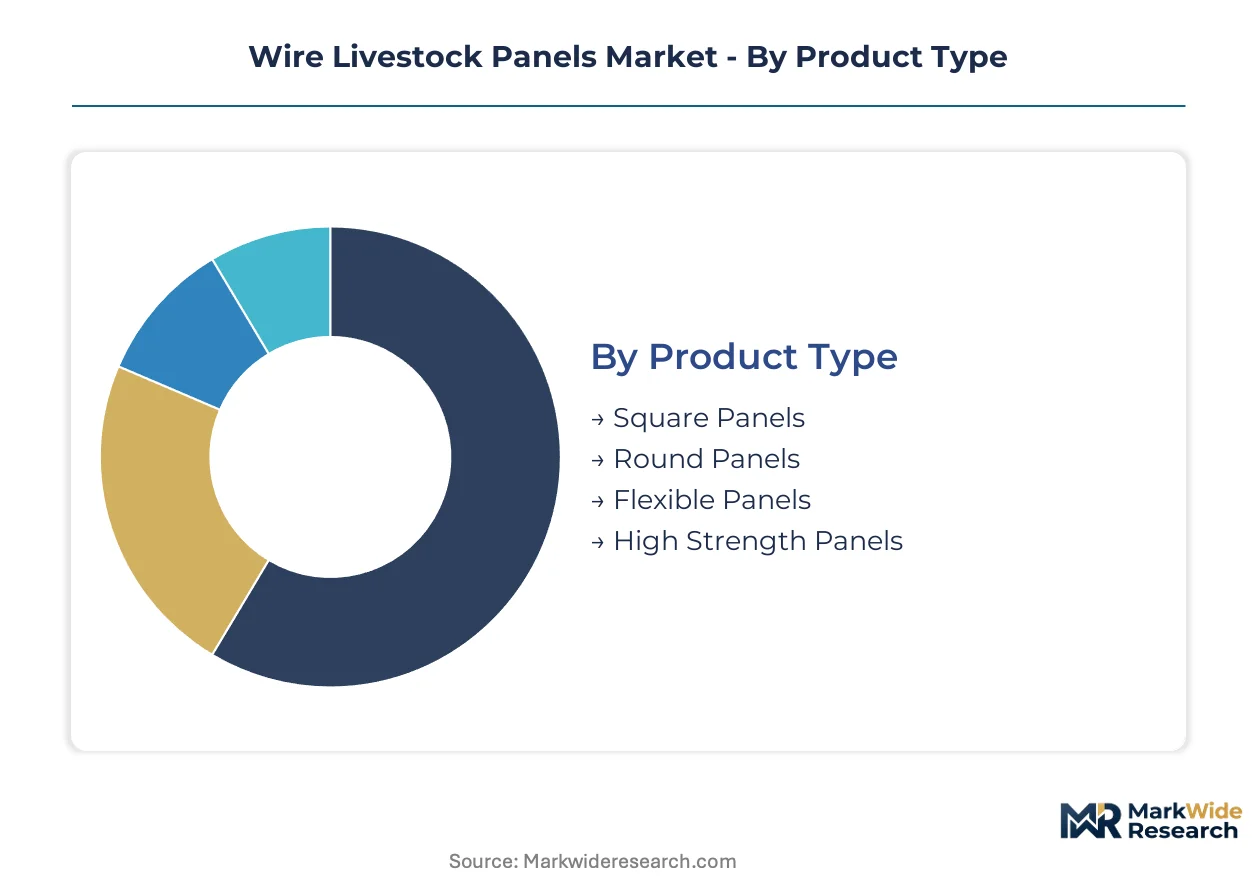
Product differentiation in wire livestock panels follows containment intensity and mobility requirements. Breeders prioritize panel specifications based on animal species, herd scale, and whether installations remain fixed or rotate across pasture.
Product Type:
Ranchers select panel geometry based on handling protocols and infrastructure permanence.
- Square Panels:Rigid four-sided frames with uniform mesh grids dominate commercial feedlot construction. Nebraska and Kansas feedlot operators specify these for permanent corral systems where ASTM A641 compliance is mandatory.
- Flexible Panels:Lightweight hinged or rollable configurations enable rapid paddock subdivision. Rotational grazing adopters in Montana and Wyoming drive demand as USDA NRCS cost-share programs subsidize portable infrastructure.
- Round Panels:Curved configurations suit crowding tubs and sweep systems in handling facilities.
- High Strength Panels:Reinforced tubing with continuous welds command premium positioning for bison and elk operations.
Square panels lead volumes today; flexible configurations are gaining share fastest.
Material:
Coating technology and base metal selection determine corrosion resistance and regulatory compliance costs.
- Galvanized Wire:Zinc-coated steel meeting ASTM A641 standards delivers the durability-to-cost ratio that Great Plains cattle operations require. EPA corrosion-prevention rules on galvanizing bath emissions are consolidating production toward larger fabricators with compliant infrastructure.
- PVC Coated Wire:Polyvinyl chloride over galvanized cores extends service life in high-moisture environments. Equine facilities in the Pacific Northwest specify these for reduced maintenance cycles despite 15-20% cost premiums.
- Steel:Uncoated or painted mild steel serves budget-conscious applications with shorter replacement horizons.
- Aluminum:Lightweight corrosion-resistant panels target portable systems where weight reduction justifies material cost premiums.
Galvanized wire dominates procurement volumes; PVC coated variants are climbing the fastest.
End User:
Buying power and technical specification authority vary sharply across customer types.
- Ranchers:Individual cattle operations in the Texas Panhandle and Great Plains drive replacement demand for high-strength welded systems. Direct relationships with Nebraska and Kansas fabricators lock in brand loyalty across multi-decade replacement cycles.
- Agricultural Cooperatives:Pooled procurement through extension networks concentrates negotiating leverage. Northern Plains cooperatives in Montana and North Dakota now specify delivery scheduling and quality audits collectively.
- Farmers:Mixed operations with secondary livestock containment needs prioritize cost efficiency over specification compliance.
- Livestock Breeders:Purebred and seedstock operations demand premium panel aesthetics and handling safety features for customer-facing facilities.
Ranchers anchor volume demand; agricultural cooperatives are expanding procurement share most rapidly.
Application:
Functional use cases determine mesh spacing, frame reinforcement, and electrification compatibility.
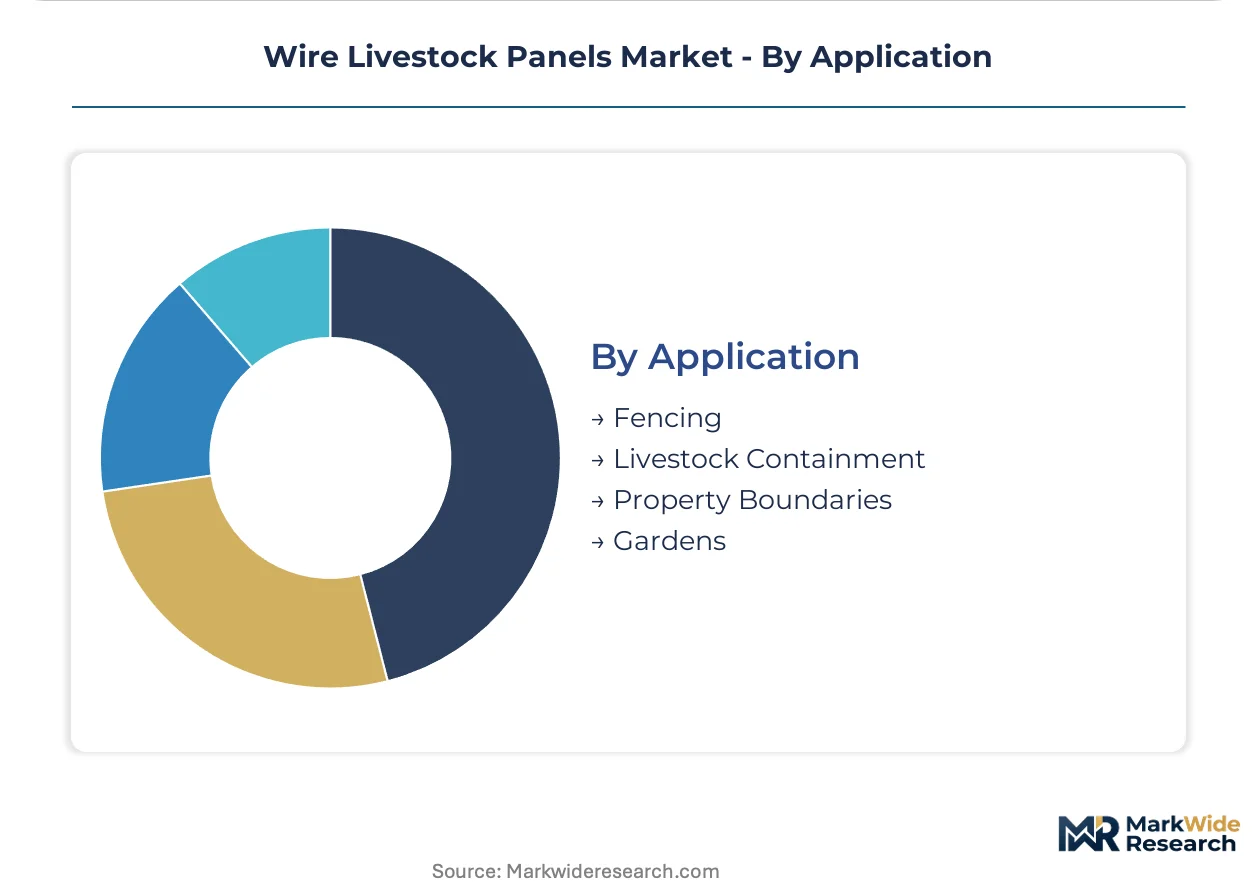
- Livestock Containment:Corrals, chutes, and handling systems require reinforced frames with four-inch mesh to prevent hoof entrapment. Commercial feedlots in the Texas Panhandle specify continuous weld seams for impact resistance under cattle pressure.
- Fencing:Perimeter installations combine wire panels with post systems to satisfy state-level fencing ordinances. USDA NRCS subsidies accelerate perimeter upgrades across Wyoming and Colorado rangeland.
- Property Boundaries:Demarcation applications prioritize visibility and durability over handling functionality.
- Gardens:Small-scale horticultural containment utilizes lighter gauge panels with wider mesh spacing.
Livestock containment leads application volumes; fencing applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates far greater wire livestock panel demand than Canada, though both markets operate under distinct regulatory frameworks that shape procurement patterns and product specifications across their respective agricultural corridors.
United States
The Great Plains cattle corridor from Texas through Nebraska and Kansas generates the heaviest panel consumption, with commercial feedlots specifying ASTM A641-compliant galvanized systems for permanent corral infrastructure. USDA Natural Resources Conservation Service cost-share programs accelerate perimeter containment upgrades across Wyoming and Colorado rangeland. Nebraska fabricators in the Omaha-Lincoln corridor leverage proximity to ranching operations to sustain regional supply dominance.
Canada
Prairie provinces in Alberta and Saskatchewan drive demand for heavy-duty welded systems serving bison and elk ranching sectors beyond traditional cattle markets. Canadian Food Inspection Agency regulations on livestock handling facility safety influence panel specification requirements for export-certified operations. Calgary-area distributors coordinate cross-border procurement pooling that captures economies of scale for dispersed northern ranching operations.
Mexico
Northern border states including Chihuahua and Sonora concentrate demand for cost-efficient containment systems serving export-oriented cattle finishing operations supplying US beef processors. Mexico's national agricultural regulator SADER oversees livestock infrastructure standards that align with US import requirements. Monterrey-based fabricators supply regional feedlots while competing with US imports across the border zone.
Brazil
Mato Grosso and Goiás states in the central-west cerrado region anchor South American demand for high-volume panel systems serving industrial-scale beef operations. Brazilian Ministry of Agriculture MAPA regulations on traceability infrastructure drive investment in permanent handling facilities. São Paulo-based agricultural equipment distributors coordinate nationwide logistics networks that extend panel supply deep into frontier ranching territories.
Australia
Queensland and New South Wales cattle stations generate demand for corrosion-resistant galvanized systems capable of withstanding extreme climate cycles across vast pastoral leases. Australian Pesticides and Veterinary Medicines Authority guidelines on livestock welfare infrastructure influence handling facility design standards. Toowoomba and Dubbo serve as fabrication and distribution hubs for the eastern seaboard beef industry.
Wire Livestock Panels Market Competitive Landscape
Top-tier vendors anchor the premium welded-steel segment, while commodity-grade wire mesh suppliers compete on price across budget-conscious ranching operations. The vendor base stratifies across three distinct tiers: integrated manufacturers with captive steel processing, regional fabricators serving agricultural cooperatives, and import-dependent distributors. Two strategic archetypes dominate competitive positioning—vertically integrated producers leveraging upstream control over wire drawing, and specialists in electrified containment convergence. Capacity expansion in robotic welding and strategic partnerships with agricultural extension networks represent the primary competitive moves reshaping supply relationships.
Among North American fabricators, Behlen Country exemplifies the integrated manufacturing archetype through its Nebraska-based production footprint, while Red Brand represents backward integration into wire drawing operations. Gallagher occupies a distinct position bridging physical barrier systems with electrified containment technology. These three companies collectively illustrate the competitive vectors—geographic concentration, upstream supply control, and technology convergence—that define strategic positioning across the market.
| Leading Market Players |
|---|
| Behlen Country |
| Red Brand |
| OK Brand |
| CK Manufacturing |
| Priefert |
| Tarter |
| Ramm Fence Systems |
| Gallagher |
| Red River Arenas |
| Others |
Value Network & Pricing Analysis
Hot-rolled coil steel pricing volatility cascades through fabrication tiers, compressing margins for Midwestern panel shops while rewarding integrated producers with captive galvanizing lines and long-term ranch supply contracts.
Pricing Analysis
Capacity additions in Nebraska and Kansas are reshaping price floors for ASTM A641-certified panels. Three-tier pricing structure across premium welded systems, standard galvanized grids, and economy-grade wire mesh separates certified feedlot specifications from portable rotational grazing units. Cost compression in the commodity tier stems from import competition, while ranchers in the Northern Plains demonstrate lowest price sensitivity due to NRCS subsidy coverage and multi-decade replacement cycles.
Supply Chain Analysis
Steel coil supply rests on domestic mill production in Indiana and Ohio alongside Canadian integrated producers. Zinc ingot sourcing draws from Australian and Peruvian mining operations, with coating chemical inputs anchored in Gulf Coast petrochemical corridors. Single-source vulnerability concentrates in qualified robotic welding equipment, where two German and Japanese vendors dominate agricultural fabrication lines. Distribution runs through agricultural cooperative pooling networks and direct ranch relationships across the Great Plains corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wire livestock panels function as a geographic-arbitrage play where Nebraska-Kansas fabrication proximity to the Texas Panhandle feedlot corridor captures logistics cost advantages against distant competitors facing elevated overland freight.
For Market Incumbents: Anticipate polymer composite substitution threats in equine and small ruminant segments by deepening captive galvanizing capabilities and securing NRCS pre-approval status for cooperative procurement pools. Reinforced frame tubing certification investments lock in specification authority for bison and elk ranching expansion in the Canadian Prairies. For New Entrants and Emerging Players: Agricultural extension networks offer the most penetrable channel for bypassing incumbent ranch relationships, particularly in Montana and Wyoming where dispersed geography previously fragmented buying. Target flexible panel configurations for rotational grazing adopters seeking NRCS-subsidized portable infrastructure without permanent corral investment. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing compliant EPA galvanizing infrastructure and robotic welding capacity. Long-term viability hinges on consolidation capture as small Midwestern shops face capital barriers to emission-control upgrades. Watch for NRCS program expansion announcements as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Welding Line Deployment | ASTM A641 certification premiums compress cost gaps with commodity imports for Nebraska-Kansas producers. |
| EPA Compliant Galvanizing Retrofit | Fume capture and wastewater investments consolidate production toward capital-rich regional fabricators. |
| Cooperative Procurement Partnership | Agricultural extension networks in Montana and Wyoming displace fragmented individual ranch purchasing. |
| Electrified Containment Integration | Convergence with Gallagher-style energizer systems opens premium positioning in predator-dense ranching regions. |
| Canadian Prairie Distribution Buildout | Calgary-area hubs capture bison and elk ranching demand beyond traditional cattle market saturation. |
Research Methodology
Bottom-up ranch and feedlot procurement modeling reconciled against top-down steel input and fabrication capacity tracking forms the analytical core. Primary interviews with cattle operation managers, agricultural cooperative procurement officers, Nebraska-Kansas fabricator plant managers, and USDA NRCS field staff combined with secondary validation from customs trade records, EPA facility compliance databases, SEC filings of integrated steel producers, and agricultural extension network reports. Triangulation across these sources isolates volume and specification trends.
Historical trendline analysis of replacement cycles, steel price correlation, and NRCS program enrollment patterns informed projection frameworks across the modeling period. Segmentation dimensions include panel geometry rigidity, coating technology tier, end-user buying structure, and application intensity. CAGRs derive from installed base aging curves and subsidy program trajectory assumptions, with feedlot construction permits and rotational grazing adoption rates serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel tariff regimes, EPA emission rule stringency, and NRCS funding authorization levels. Forecasts reflect documented assumptions about replacement cycle stability and cooperative procurement consolidation velocity. A small set of triggers—galvanizing bath emission enforcement actions, major feedlot bankruptcy events, and polymer composite breakthroughs in impact resistance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Cattle Supplies Market