
 Animal Probiotics Market | 2026-2036
Animal Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Probiotics Market Analysis
The gap between premium and commodity tiers is broadening in the Animal Probiotics Market as strain-specific formulations with genomic verification command pricing multiples over generic mixed-culture products. DSM-Firmenich leverages its dual nutrition and bioscience platforms to sustain R&D intensity in poultry-targeted solutions. Lallemand Inc. anchors its position through yeast and bacteria strain banks developed over decades of fermentation specialization. Cargill Animal Nutrition competes by integrating probiotic development directly into its global feed formulation services.
Animal probiotics comprise live microbial preparations, typically containing bacteria such as Lactobacillus, Bifidobacterium, or Bacillus species at concentrations measured in colony-forming units per gram, manufactured through controlled fermentation and stabilization processes to maintain viability through feed pelleting and gastric transit. These preparations serve primarily to modulate gastrointestinal microbiota, enhance nutrient digestibility, and reduce pathogen colonization in production animals. Powder formulations dominate volume due to compatibility with existing feed mill infrastructure and longer ambient stability, while liquid probiotics for aquaculture application represent the fastest-expanding format as recirculating systems intensify. Digestive health applications absorb the largest share of current demand, though immune support formulations targeting post-weaning stress in swine command superior margin pools.
The European Food Safety Authority (EFSA) evaluates strain-specific safety and efficacy claims under (EC) 1831/2003, creating a registration bottleneck that favors incumbents with dedicated regulatory affairs capacity. The FDA's Center for Veterinary Medicine exercises enforcement discretion for direct-fed microbials while maintaining GMP expectations that shape quality investment thresholds. China's Ministry of Agriculture and Rural Affairs (MARA) maintains an approved strain list that gates market access for imported products. Stakeholders must monitor evolving strain-level authorization requirements across jurisdictions to anticipate which product portfolios will retain commercial viability.
Market Dynamics
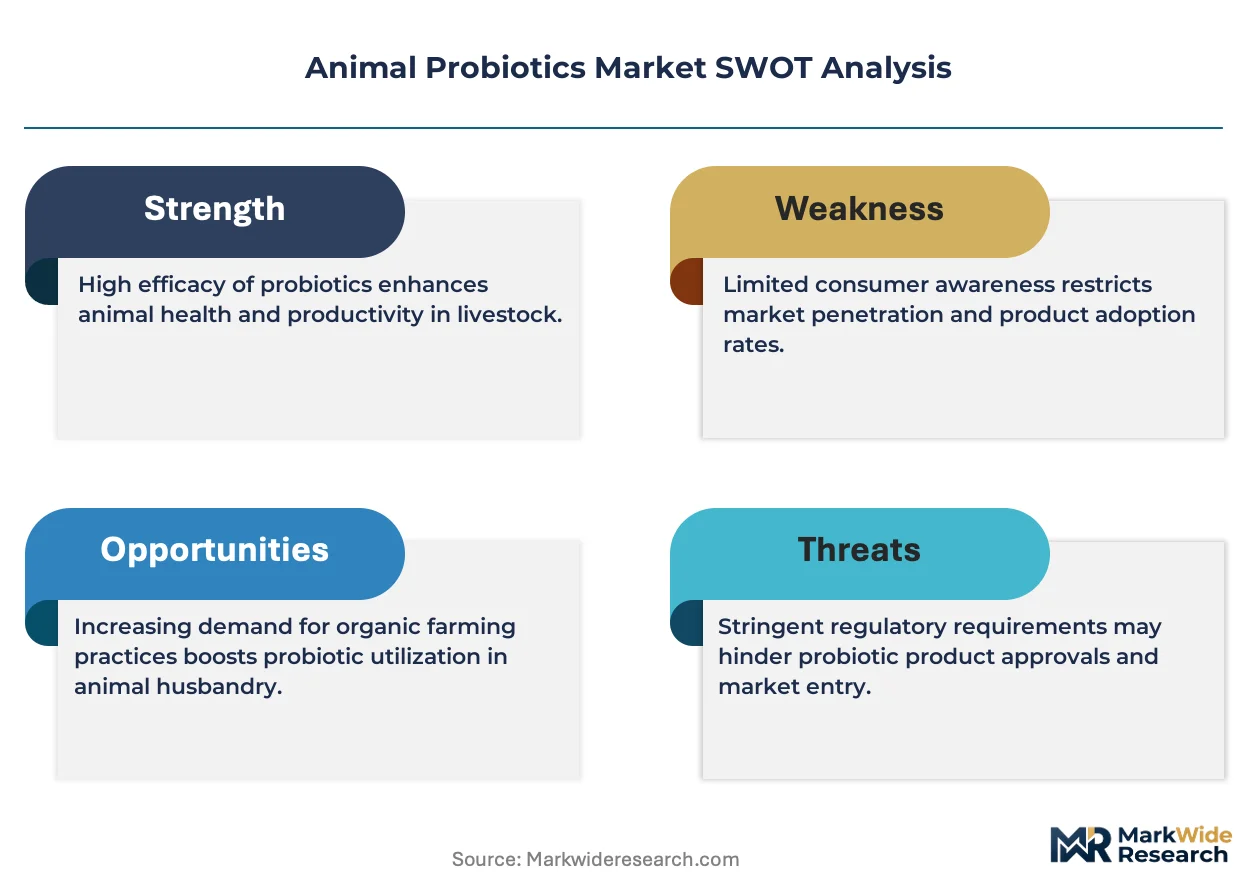
Strain-level regulatory authorization requirements under (EC) 1831/2003 and China's MARA approved strain list are concentrating competitive advantage among incumbents with dedicated regulatory affairs infrastructure and multi-decade strain banks.
Growth Catalysts
- Integrated pig farming in China:Large-scale operations in Sichuan and Henan provinces are standardizing probiotic inclusion in nursery diets to reduce post-weaning mortality and antibiotic dependency.
- EFSA authorization pathway:Strain-specific safety dossiers under (EC) 1831/2003 create durable competitive moats for firms with established regulatory capacity, discouraging commodity entrants.
- Recirculating aquaculture systems:Water quality management in intensive RAS facilities is driving liquid probiotic adoption for biofilter conditioning and pathogen suppression.
Market Restraints
- Strain stabilization costs:Maintaining colony-forming unit viability through feed pelleting temperatures above 85°C requires encapsulation technologies that add 15-25% to production cost.
- Single-source fermentation capacity:Contract manufacturing for thermotolerant Bacillus strains concentrates in a limited number of European and North American facilities.
- Regulatory fragmentation:Divergent strain approval lists between EFSA, FDA Center for Veterinary Medicine, and MARA force product portfolio duplication and jurisdiction-specific formulation.
Strategic Opportunities
- Thailand's broiler integration:Contract farming consolidation creates concentrated demand for performance-verified poultry probiotics with documented feed conversion improvements.
- Carbon accounting integration:EU Green Deal sustainability reporting requirements position microbiome modulation as a measurable methane reduction pathway in ruminant operations.
- Direct-to-farm digital channels:Veterinary telemedicine platforms and feed mill e-procurement portals are bypassing traditional distributor networks for probiotic sales.
Industry Challenges
- Genomic characterization expertise:Whole-genome sequencing for strain identity verification requires bioinformatics capabilities scarce among mid-tier manufacturers.
- Multi-year EFSA dossier timelines:Novel strain authorization under (EC) 1831/2003 demands 3-5 year investment before commercial return, compressing R&D portfolio flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Probiotics Market |
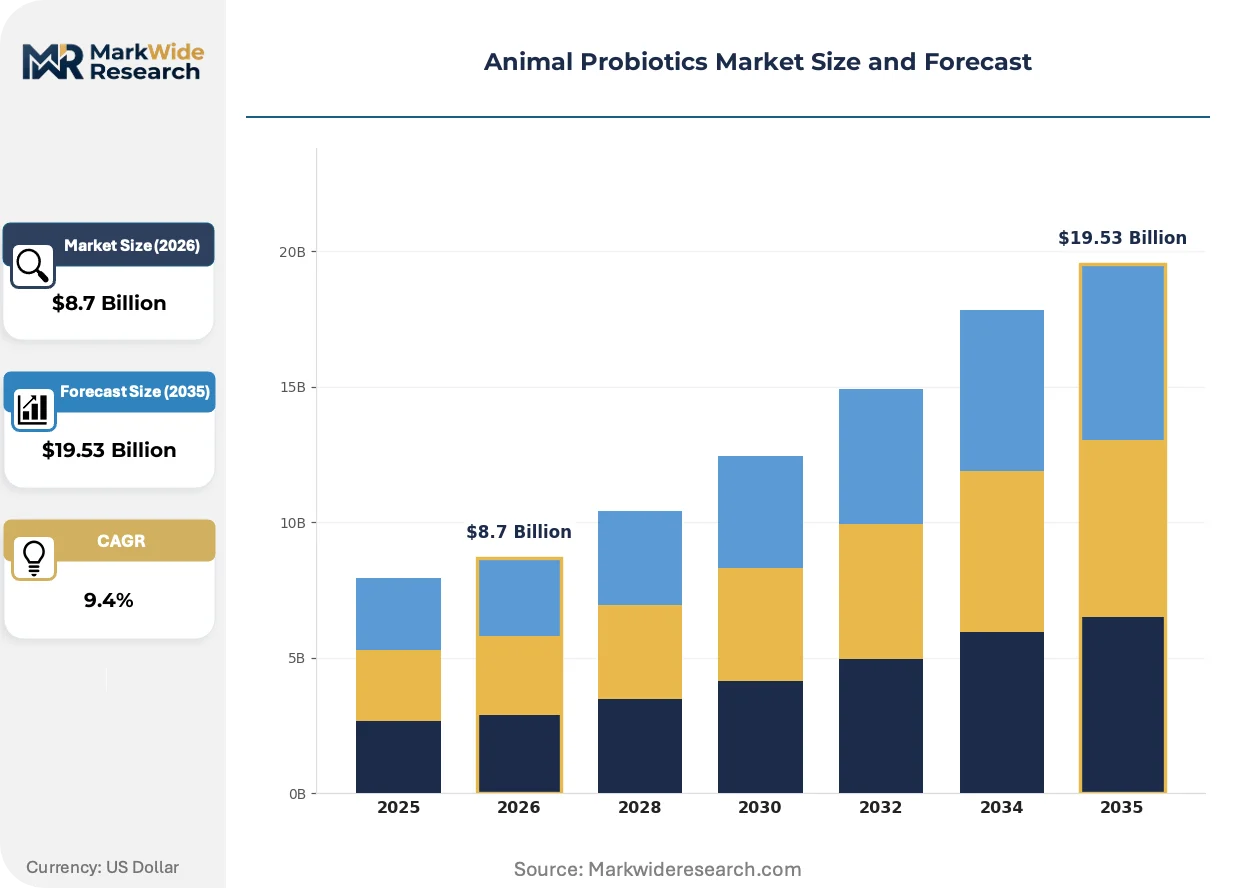
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Capsules Animal Type: Cattle, Poultry, Swine, Aquaculture Application: Digestive Health, Immune Support, Nutrient Absorption, Stress Relief Distribution Channel: Online, Retail, Veterinary Clinics, Distributors |
| Companies Covered | DSM-Firmenich, Evonik Industries AG, Novonesis, ADM, International Flavors & Fragrances Inc., Lallemand Inc., Cargill Animal Nutrition, Alltech, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Probiotics Market Emerging Trajectories
Microbiome sequencing and strain-specific formulation science are displacing generic mixed-culture products, while regulatory data requirements and buyer procurement sophistication accelerate capability gaps between premium and commodity tiers.
CRISPR-guided strain engineering is rewriting the technical foundation of probiotic development. Precision modifications to Lactobacillus and Bacillus genomes enhance gastric acid tolerance and bile salt resistance without antibiotic resistance markers. DSM-Firmenich and academic consortia in Denmark and the Netherlands are advancing edited strains through regulatory pre-submission. This capability is compressing the traditional fermentation optimization cycle from years to months.
EFSA's 2023 updated guidance on qualifying presumption of safety (QPS) status is tightening the evidentiary threshold for novel bacterial strains. The regulation now requires whole-genome sequence analysis for antimicrobial resistance genes and toxigenic potential. Yeast-based products face lighter scrutiny, tilting R&D investment toward Saccharomyces cerevisiae and Kluyveromyces marxianus platforms. European compound feed manufacturers are prioritizing QPS-listed strains to de-risk procurement compliance.
Large-scale poultry integrators in Brazil and Thailand are consolidating supplier relationships around single-source probiotic partnerships with guaranteed colony-forming unit stability claims. Long-term offtake agreements with performance bonuses tied to feed conversion ratios are displacing spot-market purchasing. This concentration is most visible in São Paulo state's vertically integrated broiler operations, where three processors account for the majority of live microbial additive procurement volume.
Animal Probiotics Market Segmentation
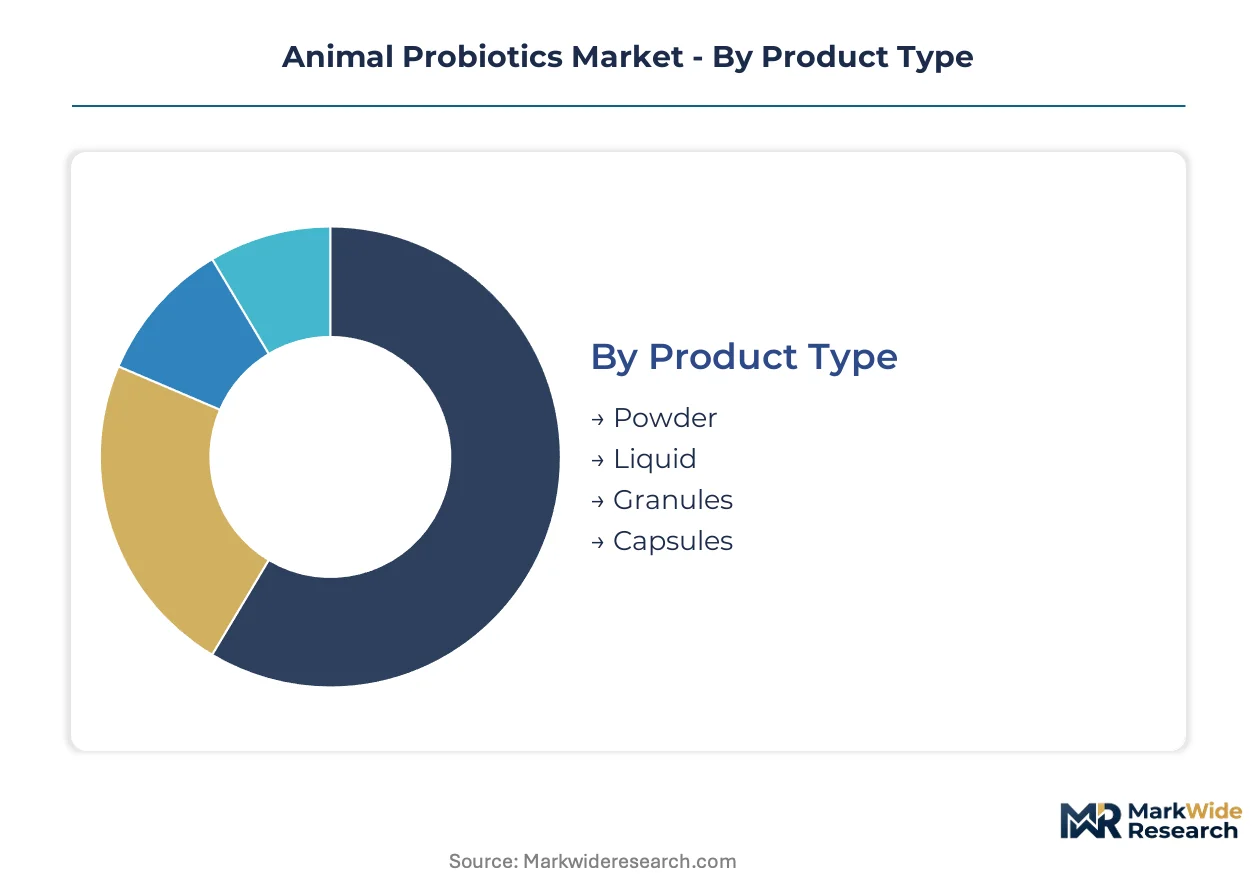
Strain-specific formulation science and regulatory strain authorization requirements are fragmenting the Animal Probiotics Market into distinct competitive tiers. Each segmentation dimension carries different margin profiles, technical barriers, and customer procurement behaviors.
Product Type:
Feed mill infrastructure compatibility and pelleting temperature tolerance determine upgrade cycles across formulation formats.
- Powder:Dry-blended preparations containing 10^9 to 10^11 colony-forming units per gram, manufactured through spray-drying or freeze-drying stabilization. Demand concentrates in Brazil's vertically integrated broiler operations where ambient storage stability and existing feed mill pneumatic handling systems minimize capital retrofit requirements.
- Liquid:Aqueous suspensions of live microbial cultures with shorter shelf life but superior dosing precision in automated drinking water systems. Recirculating aquaculture systems in Thailand and Vietnam are driving adoption for biofilter seeding and pathogen suppression in intensive shrimp and tilapia production.
- Granules:Agglomerated formulations with enhanced flowability for automated dispensing equipment. Poultry integrators in São Paulo state specify granule formats for reduced dust exposure during feed mill handling.
- Capsules:Gelatin or plant-based shell encapsulation protecting cultures from gastric acid in companion animal applications. Veterinary clinics in Germany and France stock capsule formats for targeted therapeutic dosing in high-value breeding stock.
Powder sits at the top of the volume ranking, with Liquid climbing the fastest.
Animal Type:
Production intensity and antibiotic reduction mandates reshape species-specific demand hierarchies.
- Poultry:Broiler and layer operations with short production cycles require rapid microbiome establishment. Thailand's contract farming consolidation is standardizing probiotic inclusion in starter diets to reduce necrotic enteritis incidence and improve feed conversion ratios.
- Swine:Post-weaning stress management in nursery pigs commands premium formulation pricing. China's integrated operations in Sichuan and Henan provinces are mandating probiotic protocols to replace antibiotic growth promoters under MARA's feed antibiotic restrictions.
- Cattle:Ruminant applications target methane mitigation and subacute ruminal acidosis prevention. EU Green Deal carbon accounting requirements are positioning microbiome modulation as a measurable emissions reduction pathway in Dutch and Danish dairy cooperatives.
- Aquaculture:Intensive recirculating systems and pond culture both drive liquid probiotic demand for water quality management. Vietnamese pangasius and shrimp producers are adopting bioaugmentation protocols to reduce chemical disinfectant dependency.
Poultry captures the largest volume share, while Aquaculture gains share fastest as intensive systems expand.
Application:
Clinical outcome measurability and margin capture potential stratify functional positioning.
- Digestive Health:Core applications targeting nutrient digestibility and pathogen competitive exclusion. Generic mixed-culture products dominate volume, though strain-specific formulations with genomic verification command pricing multiples in EFSA-regulated markets.
- Immune Support:Formulations targeting immunoglobulin modulation and post-weaning stress resilience. Swine producers in Denmark and the Netherlands pay premiums for documented reductions in veterinary antibiotic treatments.
- Nutrient Absorption:Phytase and carbohydrase-producing strains enhancing feed conversion efficiency. Brazil's broiler integrators specify enzyme-probiotic combinations in long-term offtake agreements with performance guarantees.
- Stress Relief:Cortisol reduction and behavioral stabilization in transport and handling contexts. Aquaculture operations in Thailand use stress-targeted formulations to reduce mortality during pond transfer and harvest.
Digestive Health anchors current volume, with Immune Support expanding most quickly as antibiotic replacement protocols mature.
Distribution Channel:
Procurement centralization and technical service requirements reshape channel economics.
- Distributors:Regional feed additive specialists providing formulation technical support and inventory financing. Traditional dominance persists in European compound feed manufacturing where mill-specific blending services retain value.
- Veterinary Clinics:Prescription and recommendation-driven sales for therapeutic and breeding stock applications. France's veterinary practice consolidation is concentrating probiotic recommendation authority in fewer clinical networks.
- Online:Direct-to-farm platforms and veterinary telemedicine portals bypassing traditional intermediaries. Chinese e-procurement platforms serving integrated pig farming operations are capturing share from provincial distributors.
- Retail:Farm supply stores and cooperatives serving smaller livestock operations. Limited growth as procurement concentrates in integrated production systems with direct manufacturer relationships.
Distributors maintain volume leadership, with Online channels showing the steepest expansion trajectory as digital procurement platforms penetrate integrated operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation scientists and regulatory affairs specialists cluster in Denmark and the Netherlands, anchoring European probiotic development. China's MARA-approved strain list has concentrated technical talent in Sichuan and Henan provinces. Brazil's São Paulo state attracts feed formulation engineers serving vertically integrated poultry operations.
China
Integrated pig farming in Sichuan and Henan provinces drives standardization of nursery diet protocols. MARA's approved strain list gates market access for imported live microbial preparations. Chengdu's feed additive corridor hosts formulation facilities supplying provincial integrators with thermotolerant Bacillus products.
Brazil
Vertically integrated broiler operations in São Paulo state consolidate supplier relationships around single-source partnerships. ANVISA's veterinary product registration framework shapes import requirements for European and North American suppliers. The Sorocaba feed manufacturing cluster processes the majority of live microbial additive volume for southeastern poultry processors.
United States
Specialized fermentation capacity for thermotolerant strains concentrates in Midwest contract manufacturing facilities. FDA Center for Veterinary Medicine maintains enforcement discretion for direct-fed microbials while imposing GMP compliance expectations. Iowa's feed production corridor integrates probiotic blending into existing mill infrastructure serving regional pork and poultry operations.
Thailand
Contract farming consolidation in the Central Plains creates concentrated demand for performance-verified poultry probiotics. The country's national agricultural regulator oversees feed additive safety assessments aligned with ASEAN harmonization initiatives. Bangkok's veterinary distribution networks channel liquid formulations to intensive aquaculture operations in Samut Sakhon and Chachoengsao provinces.
Germany
Dairy cooperatives in Lower Saxony and Bavaria pilot microbiome modulation for methane reduction under EU Green Deal reporting requirements. EFSA's QPS status evaluations under (EC) 1831/2003 create registration bottlenecks favoring established dossier capacity. Kassel's compound feed manufacturing hub prioritizes QPS-listed strains to de-risk procurement compliance for export-oriented livestock operations.
Animal Probiotics Market Vendor Landscape
Capital-heavy fermentation specialists compete with asset-light formulation designers for margin capture in strain-specific products. The vendor base stratifies across three tiers: genome-verified premium suppliers, QPS-listed standard providers, and generic mixed-culture commodity producers. Consolidation pressure intensifies as EFSA dossier timelines and stabilization technology costs raise entry barriers. Dominant competitive moves include backward integration into captive strain banking and geographic expansion through jurisdiction-specific regulatory approvals.
Among nutrition-bioscience conglomerates, DSM-Firmenich and ADM occupy positions spanning fermentation capacity and global feed formulation networks. Lallemand Inc. exemplifies the dedicated microbial specialist archetype with decades of yeast and bacteria strain collection. Cargill Animal Nutrition anchors the integrated agribusiness tier by embedding probiotic development within captive feed manufacturing services. These three organizational models represent the structural alternatives available to competitors navigating strain authorization requirements and customer procurement consolidation.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Evonik Industries AG |
| Novonesis |
| ADM |
| International Flavors & Fragrances Inc. |
| Lallemand Inc. |
| Cargill Animal Nutrition |
| Alltech |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Fermentation substrate indices for glucose and yeast extract feed directly into tiered pricing structures, with thermotolerant Bacillus strains commanding premium multiples over generic mixed-culture alternatives as stabilization costs cascade through contract manufacturing networks.
Pricing Analysis
Performance guarantees bundled into long-term offtake agreements separate premium strain-specific formulations from unbundled commodity spot purchases. Price differentiation rests on genomic verification certificates and EFSA QPS-listed status versus generic culture blends. Pricing pressure stems from Brazilian and Thai poultry integrators consolidating supplier relationships around single-source partnerships with documented feed conversion improvements. Contract farming operations show lowest price sensitivity due to mortality reduction value capture, while smaller independent feed mills face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Denmark, the Netherlands, and Germany anchor warehouse-distribution layers serving European compound feed manufacturers with QPS-compliant strain inventories. Thermotolerant Bacillus fermentation capacity concentrates in Denmark, the United States, and select Chinese facilities. Raw material dependencies include glucose feedstocks, nitrogen sources, and specialized encapsulation polymers for pelleting temperature protection. Single-source vulnerability runs through limited contract manufacturing sites for thermotolerant strains. Distribution runs through feed additive specialists providing mill-specific blending services and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal probiotics function as a stable compounder, with antibiotic replacement mandates across major livestock-producing jurisdictions providing durable demand tailwinds regardless of protein price cycles.
For Market Incumbents: Extend regulatory dossier capacity to capture strain authorization bottlenecks under EFSA and MARA frameworks. Deepen backward integration into captive strain banking to defend against CRISPR-edited strain entrants. Prioritize long-term offtake agreements with Brazilian and Thai poultry integrators to lock in volume commitments before procurement consolidation completes. For New Entrants and Emerging Players: Capture white-space in liquid probiotic formulations for Vietnamese pangasius and Thai shrimp recirculating systems, where technical service requirements have slowed incumbent penetration. Target direct-to-farm digital channels in China's Sichuan and Henan provinces, bypassing provincial distributor networks through veterinary telemedicine platforms and feed mill e-procurement portals. For Investors and Strategic Acquirers: Asymmetric upside sits with dedicated microbial specialists possessing multi-decade strain collections and established QPS dossier pipelines. Five-to-ten-year viability favors firms with in-house fermentation capacity rather than formulation designers dependent on contract manufacturing. Watch MARA strain list expansions as the signal for which product portfolios will retain Chinese market access.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Bank Acquisition | Captures decades of phenotypic characterization and regulatory pre-approval under EFSA frameworks. |
| CRISPR Strain Engineering Partnership | Compresses fermentation optimization cycles from years to months for gastric acid tolerance traits. |
| Direct-to-Farm Digital Channel Launch | Bypasses distributor networks in China's integrated pig farming provinces for margin capture. |
| EFSA Dossier Expansion | Creates durable competitive moats as novel strain authorization timelines extend to multi-year investments. |
| Aquaculture Liquid Formulation Scale-Up | Addresses fastest-expanding format demand in Thai and Vietnamese intensive recirculating systems. |
Methodological Framework
Direct dialogue with fermentation scientists, regulatory affairs specialists at EFSA and MARA, feed mill procurement managers, and veterinary practitioners grounded qualitative findings. Secondary validation drew from EFSA QPS opinions, FDA Center for Veterinary Medicine guidance documents, MARA approved strain list updates, and customs trade data for live microbial additive flows. Bottom-up strain-level demand modeling and top-down feed production correlation established triangulation anchors.
Bottom-up volume estimates by product format, animal species, and application function were stress-tested against top-down compound feed production and probiotic inclusion rate assumptions across the projection horizon. Segmentation dimensions modeled include formulation type, livestock species, functional application, and distribution channel. CAGRs were derived from historical growth pattern analysis and forward-looking regulatory mandate intensity. Forecast inputs incorporated antibiotic restriction timeline acceleration and carbon accounting integration under EU Green Deal frameworks.
Regulatory strain authorization delays, fermentation capacity constraints, and commodity feed price volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding MARA list expansion pace and EFSA QPS guidance evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market