
 Algeria Agriculture Market | 2026-2036
Algeria Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Agriculture Market Insights
Modular greenhouse kit bundling is pivoting buyer choice across Algeria's agriculture sector, as producers shift from standalone equipment purchases to integrated climate-control and irrigation packages. Baladna leverages its dairy-centric expertise to anchor livestock genetics and feed optimization partnerships in the Algerian market. Office de développement de l'agriculture industrielle en terres sahariennes sustains state-backed desert cultivation pilots through subsidized land concessions and technical assistance networks.
Algeria agriculture encompasses crop cultivation, animal husbandry, and agro-industrial processing within a Mediterranean-to-Sahara climatic gradient, where drip irrigation systems and soilless greenhouse substrates enable year-round tomato, pepper, and potato production in regions receiving under 200 mm annual rainfall. The cereals segment dominates planted area and state procurement volumes, though fruits and vegetables command stronger unit margins through direct retail and export channels. Livestock competes for fodder resources and pastoral land access, constraining near-term scaling despite rising domestic dairy and meat demand.
Office national des terres agricoles administers land allocation and tenure security, while CEA and national water authorities enforce irrigation efficiency standards and groundwater extraction limits that shape farm-level technology adoption. The country's national pharmaceutical regulator oversees veterinary product registration, affecting livestock input market access. Stakeholders must monitor groundwater depletion thresholds and land titling reform pace to calibrate long-term capacity commitments.
Market Dynamics
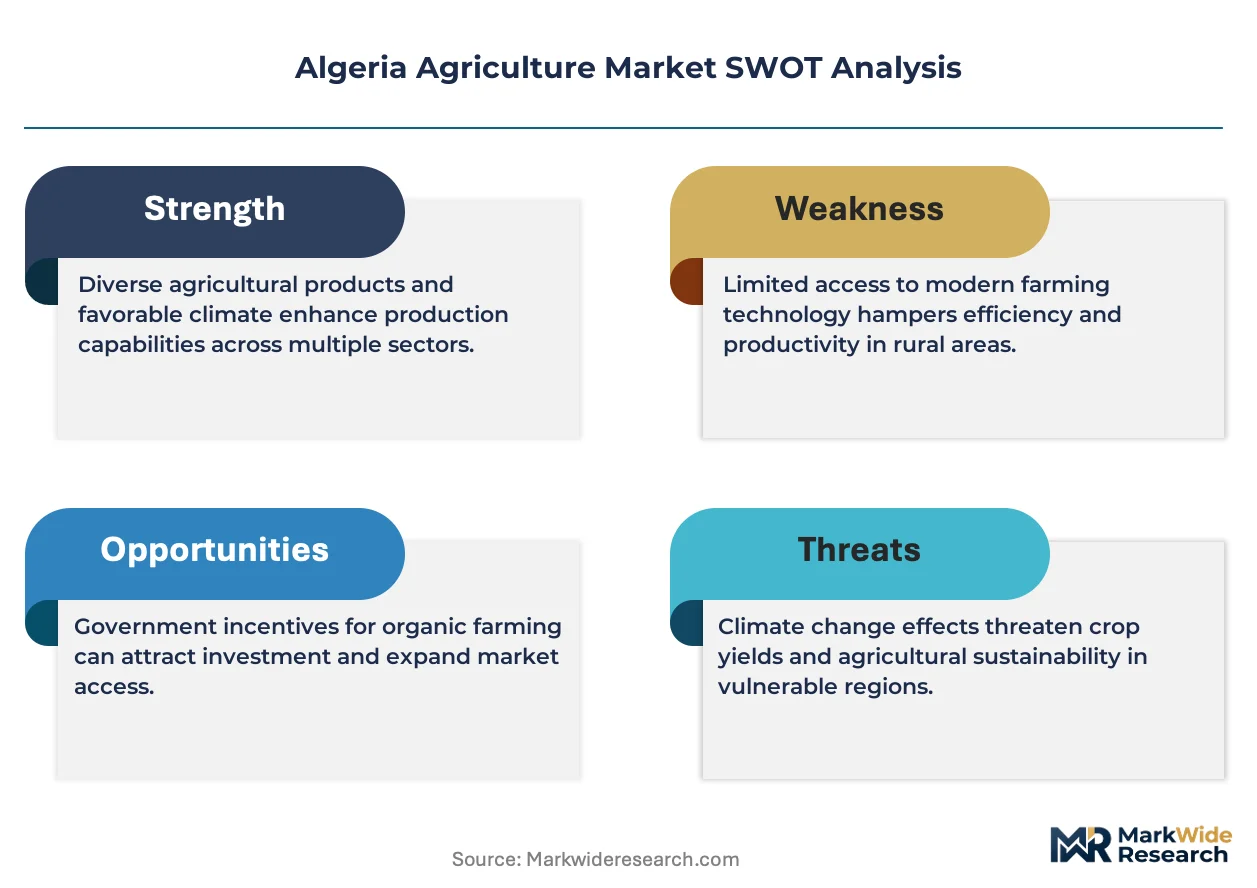
Algeria's agriculture sector faces acute groundwater depletion in the northern Tell Atlas aquifers, forcing state water authorities to tighten extraction permits and redirect investment toward Sahara-edge development zones with non-renewable fossil water reserves.
Growth Catalysts
- Subsidized drip irrigation programs:The national land reform framework funds precision water delivery infrastructure across Saharan perimeters, cutting unit water consumption by half while expanding cultivable hectares.
- Coastal peri-urban greenhouse clusters:Tomato and pepper producers near Algiers and Oran leverage soilless substrates to supply year-round fresh produce to urban retail networks.
- Domestic cereals procurement mandates:Food processing enterprises face state-directed sourcing quotas that redirect capital toward local grain cultivation and storage infrastructure.
Market Restraints
- Fossil groundwater depletion:The Intercalary Continental aquifer underlying southern development zones contains finite non-renewable reserves that constrain long-term irrigation security.
- Fodder resource competition:Livestock operators compete with cereal farmers for limited arable land and imported feed inputs, compressing herd expansion potential.
- Tenure insecurity in state-administered zones:Office national des terres agricoles maintains discretionary lease renewal authority that deters multi-year capital commitments from private operators.
Strategic Opportunities
- Modular greenhouse kit bundling:Integrated climate-control and irrigation packages replace standalone equipment sales, opening recurring service revenue streams for technology providers.
- Livestock genetics partnerships:Dairy and meat producers seek imported breeding stock and feed optimization protocols to close yield gaps with Mediterranean competitors.
- Sahara-edge land concessions:Office de développement de l'agriculture industrielle en terres sahariennes offers subsidized long-term leases with technical assistance networks for desert cultivation pilots.
Industry Challenges
- Veterinary product registration delays:The national pharmaceutical regulator maintains extended review timelines for livestock pharmaceuticals that stall input market access.
- Groundwater monitoring compliance costs:CEA-mandated extraction metering and reporting systems require capital investment beyond smallholder operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Agriculture Market |
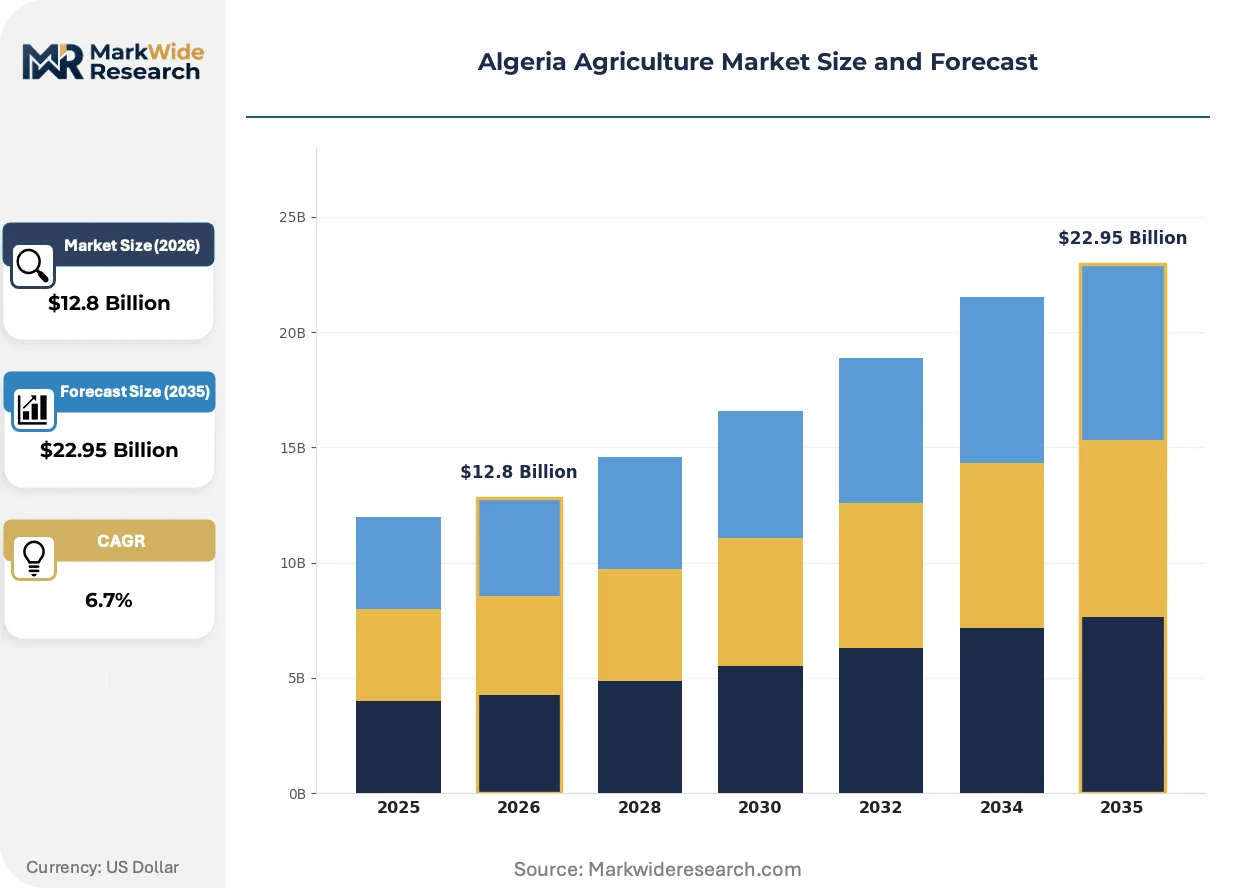
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Fruits, Vegetables, Livestock End Use Industry: Food Processing, Export, Local Consumption, Feed Production Distribution Channel: Wholesale, Retail, Online, Direct Sales Packaging Type: Bags, Bottles, Cartons, Bulk |
| Companies Covered | Algerian State Agricultural Enterprises, Qatari Agricultural Development Partners, Baladna, Solar-Powered Cold Chain Operators, Algerian Agri-Fintech Lending Platforms, Office de développement de l'agriculture industrielle en terres sahariennes, Italian Regenerative Agriculture Investors (Desert Operations), Greenhouse Cluster Developers (Coastal & Peri-Urban), Office national des terres agricoles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Agriculture Market Trends and Innovations
Technology convergence and procurement restructuring are reshaping how Algerian producers acquire and deploy agricultural assets, with bundled service models displacing transactional equipment sales.
Sensor-networked drip irrigation is integrating soil moisture telemetry with automated valve control across Saharan perimeter farms. Large-scale tomato and potato operators near Adrar and Ouargla deploy these systems to optimize water delivery timing. The technology is integrating previously separate hardware and software supply chains into single-vendor service contracts that lock in multi-year maintenance relationships.
The national water authority's extraction permit system now mandates flow metering and seasonal use caps for all commercial agricultural wells. CEA enforcement teams conduct unannounced audits that trigger permit suspensions for non-compliant operators. Greenhouse clusters in the Mitidja plain face the strictest monitoring given their proximity to urban water demand centers.
Direct contracting between food processors and farm cooperatives is compressing traditional wholesale market intermediation. Cereal and vegetable buyers in Algiers and Oran now negotiate volume commitments with producer associations that bypass state procurement auctions. This pattern concentrates most visibly in potato and pepper supply chains serving packaged food manufacturers.
Algeria Agriculture Market Segmentation
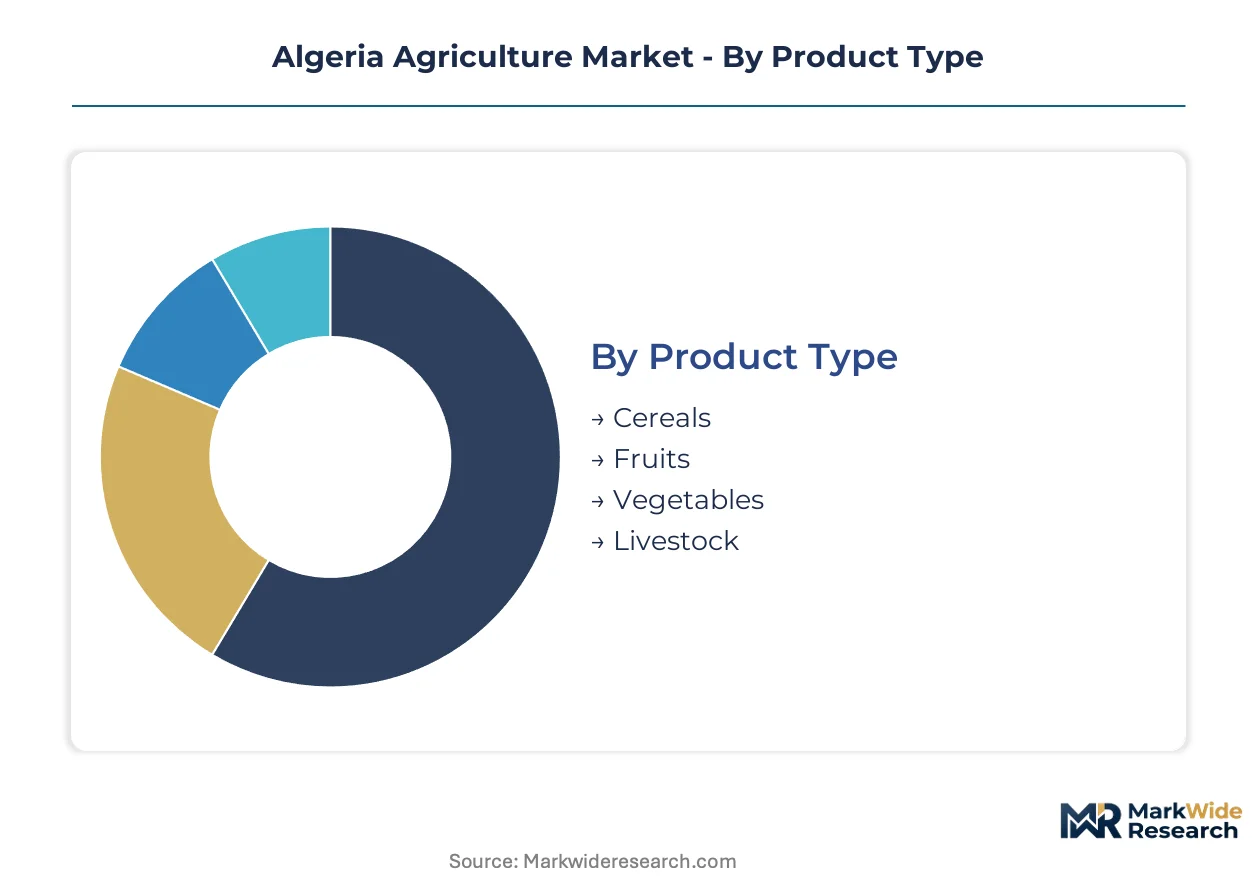
Algeria's agriculture market segments reveal divergent margin profiles and infrastructure requirements across product types and distribution pathways. Understanding these divisions clarifies where state subsidies concentrate versus where private capital deploys independently.
Product Type:
Water access and land tenure security differentiate buyers most sharply in this category, with Sahara-edge operators facing fundamentally different constraint sets than Tell Atlas farmers.
- Cereals:Wheat and barley cultivation occupies the largest planted area under state procurement mandates. Demand concentrates in northern rain-fed zones where Office national des terres agricoles administers lease allocations, though groundwater depletion is forcing marginal hectare abandonment.
- Vegetables:Tomato, pepper, and potato production leverages drip irrigation and soilless greenhouse substrates to achieve year-round harvests. Coastal peri-urban clusters near Algiers and Oran supply urban retail networks with the strongest unit margins in the sector.
- Fruits:Citrus and date palms dominate export-oriented cultivation, particularly in Saharan oases with fossil water access.
- Livestock:Dairy and meat operations compete with cereal farmers for fodder resources and pastoral land access, compressing herd expansion despite rising domestic demand.
Volume sits with Cereals; growth tilts toward Vegetables.
End Use Industry:
State intervention intensity varies dramatically by buyer type, from procurement quotas in processing to minimal oversight in local retail.
- Food Processing:Industrial buyers face mandatory domestic sourcing quotas for cereals and vegetables, redirecting capital toward local grain storage infrastructure. State-directed volume commitments dominate procurement patterns for packaged food manufacturers in Algiers.
- Local Consumption:Direct retail and traditional souk channels serve urban households with minimal regulatory intermediation. Mitidja plain greenhouse operators bypass wholesale markets to supply Algiers and Oran consumers.
- Export:Date and citrus shipments target European and West African markets, constrained by phytosanitary certification requirements.
- Feed Production:Compound feed mills compete for limited domestic grain supplies against food processors, driving import dependence for soy and corn.
Revenue concentrates in Food Processing; margin expansion is steepest in Export.
Distribution Channel:
Supply chain length and price transparency separate channels, with direct contracting eroding traditional wholesale intermediation.
- Direct Sales:Processor-farmer contracting bypasses state procurement auctions, concentrating in potato and pepper supply chains serving packaged food manufacturers. Producer associations negotiate volume commitments directly with Algiers-based buyers.
- Wholesale:Traditional aggregators dominate cereal and vegetable movement from farm gate to urban markets, though share is compressing under direct contracting pressure.
- Retail:Supermarket chains and neighborhood grocers source through consolidated distributors with cold-chain requirements.
- Online:Digital platforms remain nascent, limited by last-mile logistics gaps outside major urban centers.
Transaction volume flows through Wholesale; channel shift is accelerating toward Direct Sales.
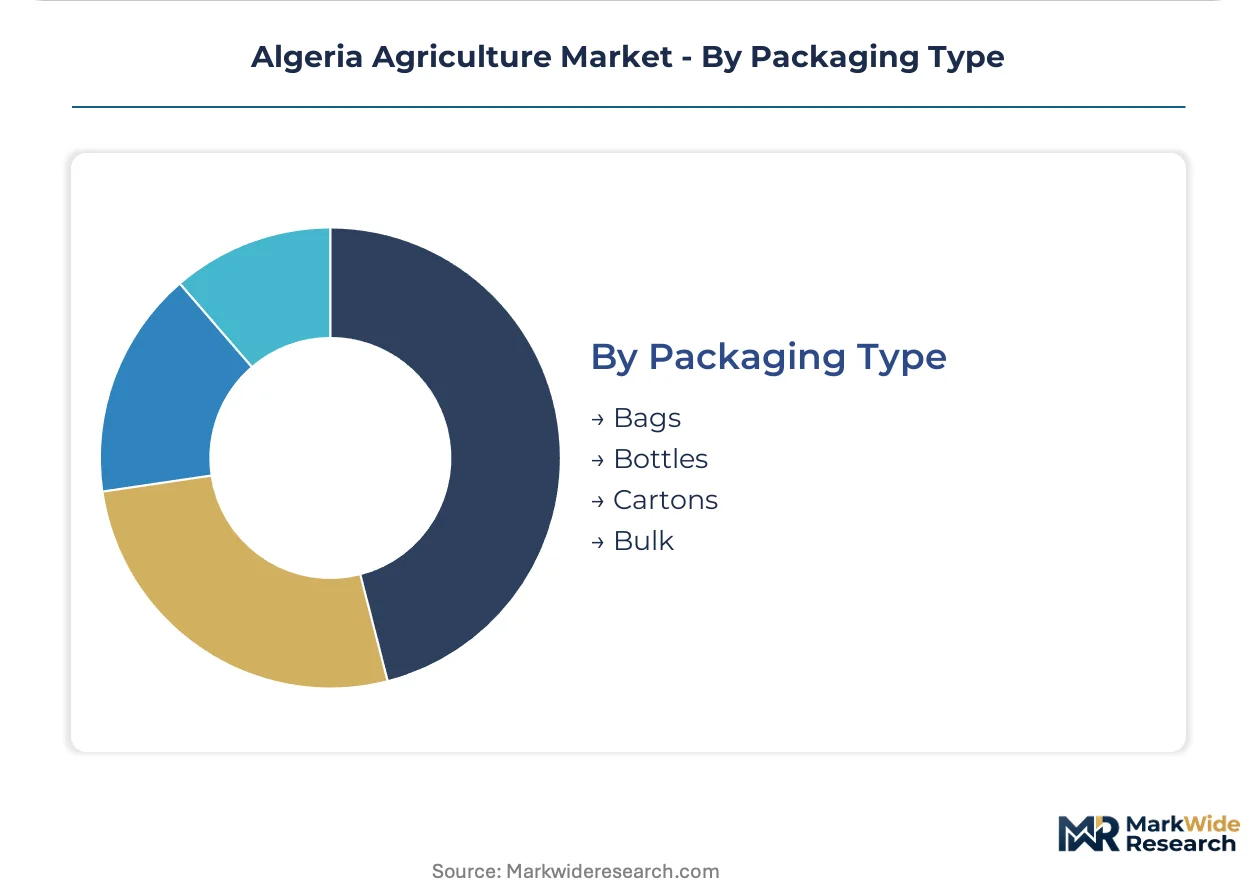
Packaging Type:
Export certification requirements and retail branding needs drive packaging differentiation, with bulk handling dominating commodity flows.
- Bulk:Unpackaged cereals and fodder move through state procurement silos and feed mill intakes with minimal handling costs. This format dominates inter-farm and processor-farm transactions across the Tell Atlas grain belt.
- Bags:Woven polypropylene sacks serve retail grain and legume distribution with printed branding for supermarket channels.
- Cartons:Fresh produce packaging for export citrus and domestic vegetable retail, requiring ventilation specifications for shelf-life extension.
- Bottles:Olive oil and dairy product containment for branded retail, constrained by domestic plastics manufacturing capacity.
Shipment weight concentrates in Bulk; value-added transition is sharpest toward Cartons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algeria's agricultural production concentrates along a narrow coastal belt while consumption demands pull toward major urban centers. The Sahara-edge development zones and northern Tell Atlas regions operate under divergent water security regimes. This geographic split shapes investment patterns and technology adoption across sub-regional markets.
Mitidja Plain
Greenhouse vegetable production for Algiers retail networks drives investment here. CEA-mandated groundwater extraction metering tightens operational compliance for tomato and pepper operators. Coastal peri-urban clusters near Blida and Boumerdès deploy soilless substrates to supply year-round fresh produce through direct contracting channels.
Tell Atlas Grain Belt
Wheat and barley cultivation dominates planted area under state procurement mandates. Office national des terres agricoles administers lease allocations across rain-fed northern zones where aquifer depletion forces marginal hectare abandonment. Cereal cooperatives near Tizi Ouzou and Sétif negotiate volume commitments directly with Algiers-based food processors.
Saharan Perimeter Zones
Date palm cultivation and desert agriculture pilots exploit fossil water reserves in Adrar and Ouargla governorates. Office de développement de l'agriculture industrielle en terres sahariennes offers subsidized long-term land concessions with technical assistance networks. Large-scale potato operators deploy sensor-networked drip irrigation to optimize delivery timing across non-renewable aquifer systems.
Oran Agricultural Corridor
Citrus export production and greenhouse vegetable supply to Algeria's second city shape regional demand. Phytosanitary certification requirements constrain European market access for coastal orchard operators. Peri-urban clusters near Mostaganem leverage drip irrigation infrastructure to serve packaged food manufacturers through direct sales channels.
High Plateaux Pastoral Zones
Livestock grazing competes with cereal farming for limited fodder resources across Djelfa and Laghouat steppe lands. State-administered pastoral land access constrains herd expansion despite rising domestic dairy demand. Feed mill operators in M'Sila compete for scarce domestic grain supplies against food processing procurement mandates.
Algeria Agriculture Market Competitive Landscape
The competitive structure tilts toward state-backed land development authorities and specialized technology providers rather than consolidated private agribusiness. Market participants cluster around three archetypes: desert cultivation concessionaires leveraging subsidized Sahara-edge leases, modular greenhouse system integrators bundling climate-control with irrigation packages, and livestock genetics partners importing breeding stock protocols. Dominant competitive moves center on strategic partnerships for technical assistance networks and capacity expansion through integrated kit deployment rather than standalone equipment sales.
Among state-affiliated development authorities, Office de développement de l'agriculture industrielle en terres sahariennes and Office national des terres agricoles anchor land allocation and tenure administration functions. Baladna represents the livestock genetics partnership archetype, leveraging dairy-centric expertise to anchor feed optimization relationships. Italian Regenerative Agriculture Investors exemplify foreign capital deployment into desert operations, occupying a position within the Sahara-edge concession tier alongside Qatari Agricultural Development Partners.
| Leading Market Players |
|---|
| Algerian State Agricultural Enterprises |
| Qatari Agricultural Development Partners |
| Baladna |
| Solar-Powered Cold Chain Operators |
| Algerian Agri-Fintech Lending Platforms |
| Office de développement de l'agriculture industrielle en terres sahariennes |
| Italian Regenerative Agriculture Investors (Desert Operations) |
| Greenhouse Cluster Developers (Coastal & Peri-Urban) |
| Office national des terres agricoles |
| Others |
Pricing and Supply Chain Analysis
Captive integration into greenhouse kit bundling anchors both supply security and margin capture for Algerian producers. Technology providers that merge climate-control hardware with irrigation software into single-vendor contracts lock in multi-year service relationships while insulating buyers from standalone equipment price volatility.
Pricing Analysis
Margin tightening in vegetable supply chains reflects CEA-mandated groundwater metering compliance costs that smallholders cannot absorb. Contract-based long-term offtake dominates processor-farmer direct sales, with price differentiation hinging on volume scale and phytosanitary certification grade. Cost-down pressure accelerates in cereal procurement as state quotas compress negotiating leverage. Food processing enterprises show least price sensitivity given mandatory domestic sourcing requirements, while independent greenhouse operators face acute margin compression from extraction permit fees.
Supply Chain Analysis
Refurbishment flows for drip irrigation components remain minimal given short equipment lifecycles in Saharan perimeter zones. Manufacturing concentrates in China, Italy, and Turkey for greenhouse structural materials and precision irrigation hardware. Raw material dependencies center on polypropylene for tubing, galvanized steel for framing, and semiconductor components for sensor networks. Single-source vulnerability runs through Chinese pump motor suppliers. Distribution runs through Office national des terres agricoles-sanctioned dealer networks with technical assistance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algeria's agriculture sector reads as a cost-of-compliance story where CEA groundwater extraction metering creates a regulatory moat favoring capitalized operators over smallholders.
For Market Incumbents: Deploy sensor-networked irrigation retrofits to preempt permit suspension risk from CEA audit teams. Deepen backward integration into soilless substrate production to capture margin from imported peat and coconut coir. Consolidate land lease portfolios through Office national des terres agricoles renewal negotiations before tenure reform accelerates. Threat substitution from modular greenhouse kit imports pressures standalone equipment vendors. For New Entrants and Emerging Players: Sensor-networked drip irrigation as-a-service offers a technology-first wedge into Sahara-edge development zones where technical assistance gaps persist. Target peri-urban greenhouse clusters near Oran with subscription-based maintenance contracts that bypass capital-intensive equipment purchases. Go-to-market through Office de développement de l'agriculture industrielle en terres sahariennes concession partnerships provides land access and state credibility. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by Gulf sovereign wealth vehicles seeking food security verticals. Long-term viability frames around fossil water reserve depletion curves and drip irrigation efficiency gains across the projection horizon. Acquisition targets should show integrated kit deployment capabilities and CEA compliance track records. Monitor groundwater extraction permit suspension rates as early inflection indicator for operational distress among incumbent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Greenhouse Kit Integration | Bundled climate-control and irrigation packages displace standalone equipment sales through Office de développement de l'agriculture industrielle en terres sahariennes concession networks. |
| CEA Compliance Infrastructure Investment | Extraction metering and reporting systems secure permit continuity under tightening groundwater monitoring enforcement. |
| Direct Processor Contracting | Volume commitments with Algiers-based food manufacturers bypass state procurement auction intermediation. |
| Livestock Genetics Partnership | Imported breeding stock protocols close yield gaps with Mediterranean competitors through Baladna-type technical assistance models. |
| Sahara-edge Land Concession Expansion | Subsidized long-term leases with fossil water access anchor desert cultivation pilots beyond Tell Atlas depletion zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with greenhouse cluster operators, drip irrigation system integrators, Office national des terres agricoles land allocation officers, CEA enforcement team members, and food processor procurement managers validated demand-side assumptions. Secondary sources included CEA groundwater extraction reports, customs records for agricultural equipment imports, and Office de développement de l'agriculture industrielle en terres sahariennes concession documentation. Bottom-up farm-level capacity estimates triangulated against top-down state procurement volume data.
Reconciling production surveys with consumption tracking data streams shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, distribution channel, and packaging format, with regional water security regime as an additional industry-specific layer. CAGRs derived from historical planted area trends, technology adoption curves for drip irrigation, and state subsidy allocation trajectories. Forecast inputs incorporated fossil aquifer depletion scenarios and land titling reform pace assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated groundwater extraction restrictions or tenure insecurity spikes. Practitioners should monitor CEA permit suspension announcements and Office national des terres agricoles lease renewal policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market