
 Global Animal Growth Promoters and Performance Enhancers Market | 2026-2036
Global Animal Growth Promoters and Performance Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Growth Promoters and Performance Enhancers Market Foresight
Precision fermentation for probiotic strain development is reshaping how animal growth promoters are manufactured, replacing traditional chemical synthesis with biologically active metabolites. Elanco Animal Health leverages its therapeutic heritage to anchor positions in regulated hormonal segments. Zoetis dominates microbiome research platforms, while Alltech specializes in yeast-derived nutritional supplements across ruminant channels.
Animal growth promoters and performance enhancers comprise biologically active substances administered to livestock to improve feed conversion efficiency, accelerate weight gain, or enhance reproductive performance, typically delivered through feed matrices at concentrations measured in parts per million. Their primary commercial purpose centers on reducing unit production costs for protein commodities in intensive farming systems. Non-hormonal additives now command expanding margin pools as regulatory pressure matures, while enzymes represent the fastest-growing product type driven by phytase and carbohydrase innovations in poultry nutrition. Antibiotic segments face structural contraction across most geographies, though residual demand persists in aquaculture applications where alternatives remain technically immature.
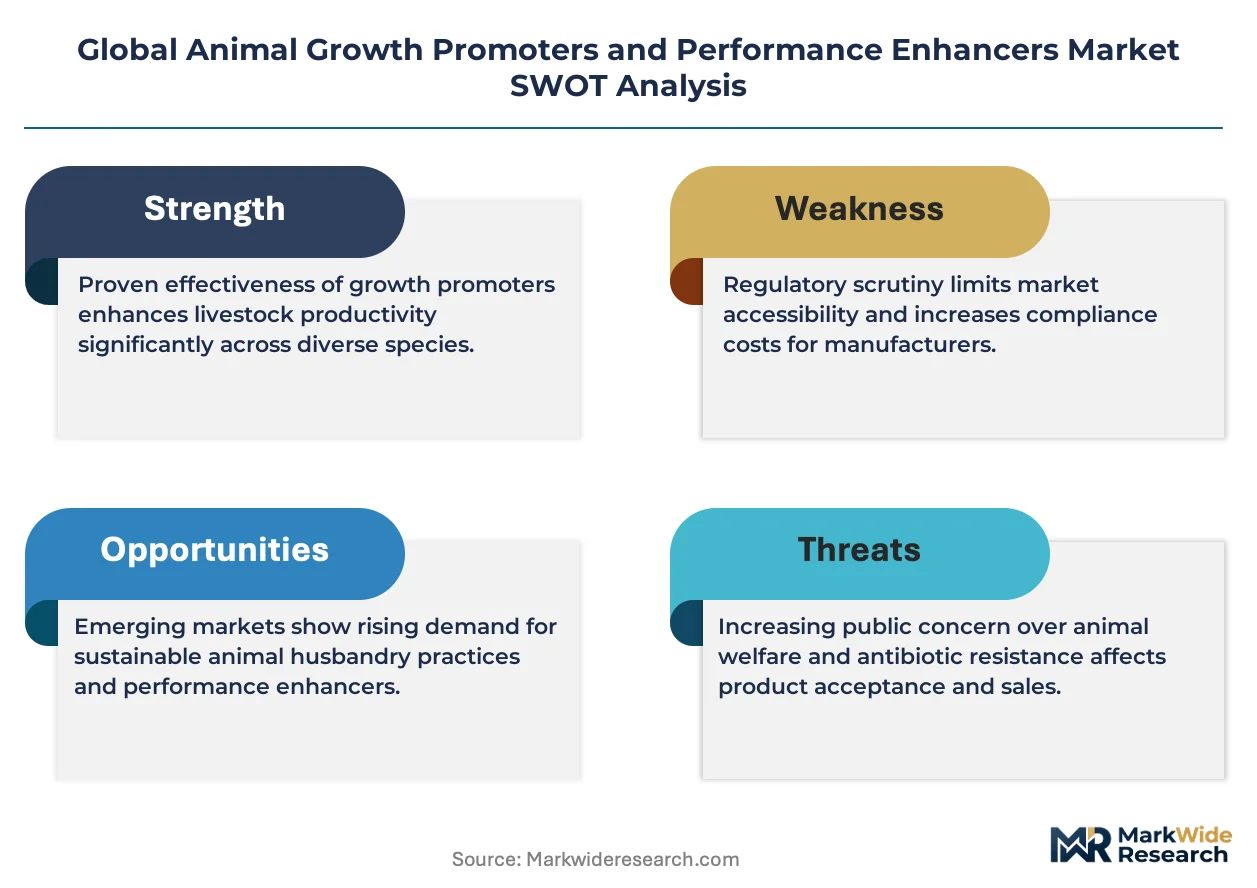
The FDA's Veterinary Feed Directive governs medically important antibiotics in US livestock feed, directly constraining product portfolios available to domestic feed manufacturers. EMA's guidance on hormonal residues in meat exports shapes formulation standards for EU-trading nations, while China's Ministry of Agriculture and Rural Affairs enforces GB standards for feed additive safety testing. Stakeholders must monitor divergence between residue tolerance thresholds set by OECD trading partners and emerging economy regulators, as misalignment threatens market access for cross-border protein suppliers.
Market Dynamics
The EU Green Deal's restrictions on antibiotic growth promoters in imported livestock products are forcing feed manufacturers to reconfigure additive portfolios across Southeast Asian supply chains. Precision fermentation technologies for probiotic strain development are simultaneously collapsing traditional chemical synthesis margins while opening new formulation categories.
Growth Catalysts
- Enzyme Innovation in Poultry Nutrition:Phytase and carbohydrase advances are improving feed conversion ratios in Brazil's integrated poultry sector, where export-oriented processors drive adoption of non-hormonal performance enhancers.
- EU Green Deal Compliance Pressure:The regulation's residue standards for imported meat products are compelling Asian feed manufacturers to expand procurement of microbiome-based alternatives to antibiotic growth promoters.
- Precision Fermentation Scale-Up:Biologically active metabolite production is replacing synthetic manufacturing routes, enabling novel probiotic formulations with enhanced stability in tropical feed storage conditions.
Market Restraints
- Regulatory Divergence Costs:Misalignment between OECD residue tolerance thresholds and emerging economy standards threatens market access for cross-border protein suppliers, forcing dual-formulation strategies.
- Technical Immaturity in Aquaculture:Antibiotic alternatives remain technically underdeveloped for shrimp and finfish applications, constraining segment transition timelines despite regulatory pressure.
- Input Concentration Risk:Specialized enzyme production concentrates among European and North American biotechnology suppliers, exposing Asian feed manufacturers to currency and logistics volatility.
Strategic Opportunities
- Ruminant Microbiome Platforms:Yeast-derived nutritional supplements for cattle represent underpenetrated white space, with Brazilian and Australian grazing operations seeking methane-reducing feed additives.
- Dual Carbon Policy Alignment:China's dual carbon goals are creating procurement incentives for low-emission feed additives that improve nitrogen retention and reduce enteric fermentation.
- Direct-to-Processor Distribution:Bypassing traditional feed compounder channels, additive manufacturers are building technical service relationships with integrated poultry and swine operations in Vietnam and Indonesia.
Industry Challenges
- Strain Characterization Expertise Gap:Probiotic formulation requires specialized microbiome sequencing capabilities that remain scarce among mid-sized Asian feed manufacturers, slowing product development cycles.
- Multi-Jurisdiction Registration Burden:Obtaining concurrent approvals from FDA's Veterinary Feed Directive, EMA's residue guidance, and China's GB standards extends commercialization timelines for novel additives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Growth Promoters and Performance Enhancers Market |
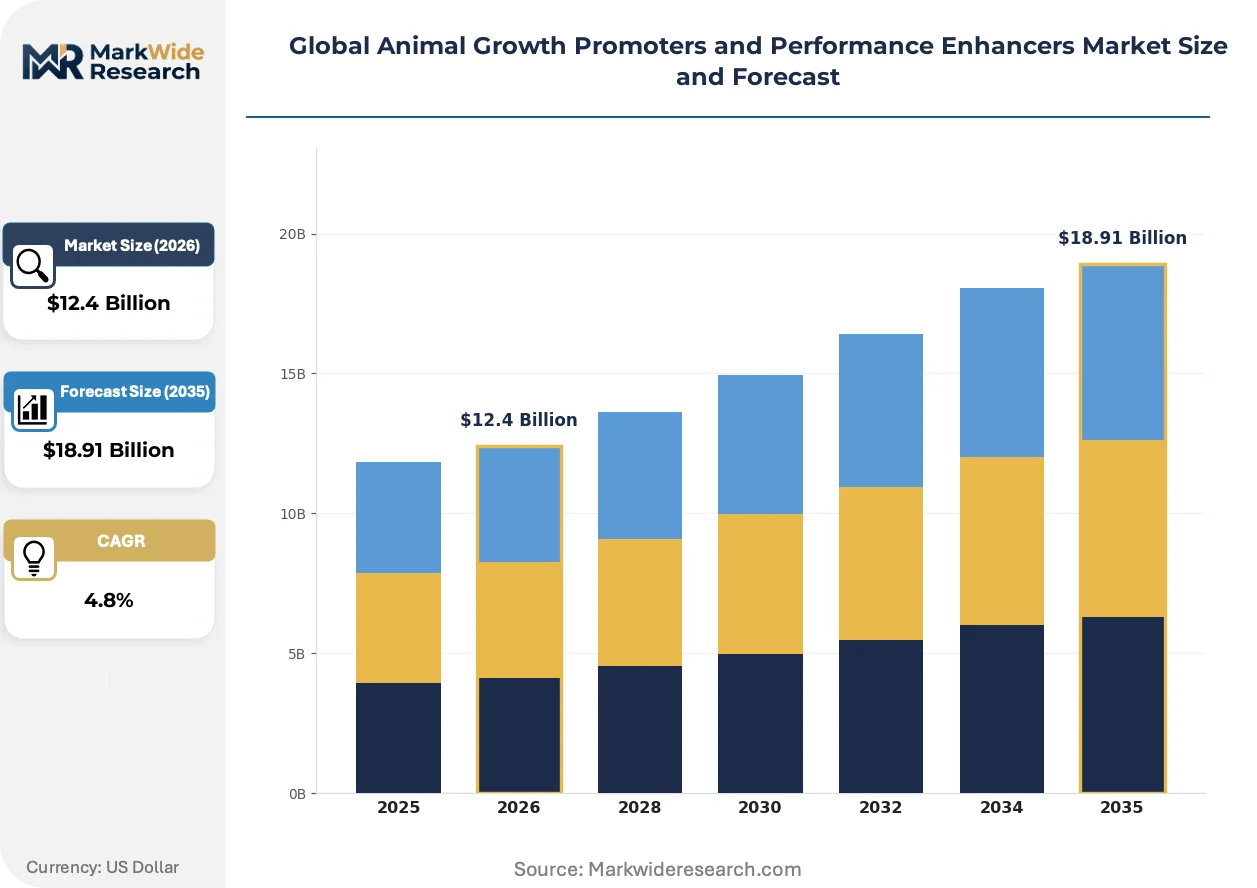
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Growth Promoters, Non-Hormonal Additives, Nutritional Supplements, Enzymes, Antibiotics Application: Poultry Nutrition, Aquaculture, Swine Feed, Ruminant Health, Pet Care End User: Feed Manufacturers, Livestock Farmers, Aquafarm Operators, Veterinary Clinics, Animal Breeders Distribution Channel: Direct Sales, Distributors, Online Platforms, Veterinary Supply Stores, Agricultural Cooperatives |
| Companies Covered | Elanco Animal Health, Zoetis, Boehringer Ingelheim, Merck Animal Health, Bayer Animal Health, Vetoquinol, Virbac, Ceva Sante Animale, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Growth Promoters and Performance Enhancers Market Shifts & Advancements
Biomanufacturing platforms are restructuring competitive boundaries between pharmaceutical heritage players and agricultural biotechnology specialists. Three concurrent developments are compressing traditional value capture models.
Precision fermentation for probiotic metabolite production is collapsing cost structures for traditionally synthesized growth promoters. Brazilian and Thai feed manufacturers are adopting these biologically active formulations at accelerating rates. The technology is collapsing the historical premium commanded by European chemical suppliers in tropical livestock markets.
EMA's guidance on hormonal residues in meat exports is reshaping formulation standards for EU-trading nations. The policy forces alignment between domestic tolerance thresholds and import destination requirements. Southeast Asian processors serving European retail channels are most affected, driving investment in enzyme-based and microbiome alternatives.
Integrated poultry and swine operations are consolidating procurement authority previously held by independent feed compounders. Technical service relationships with direct manufacturer teams are displacing distributor-mediated transactions in Brazil's Mato Grosso and Indonesia's Java clusters. This concentration is most visible in enzyme and probiotic categories where on-farm application expertise determines performance outcomes.
Global Animal Growth Promoters and Performance Enhancers Market Segmentation
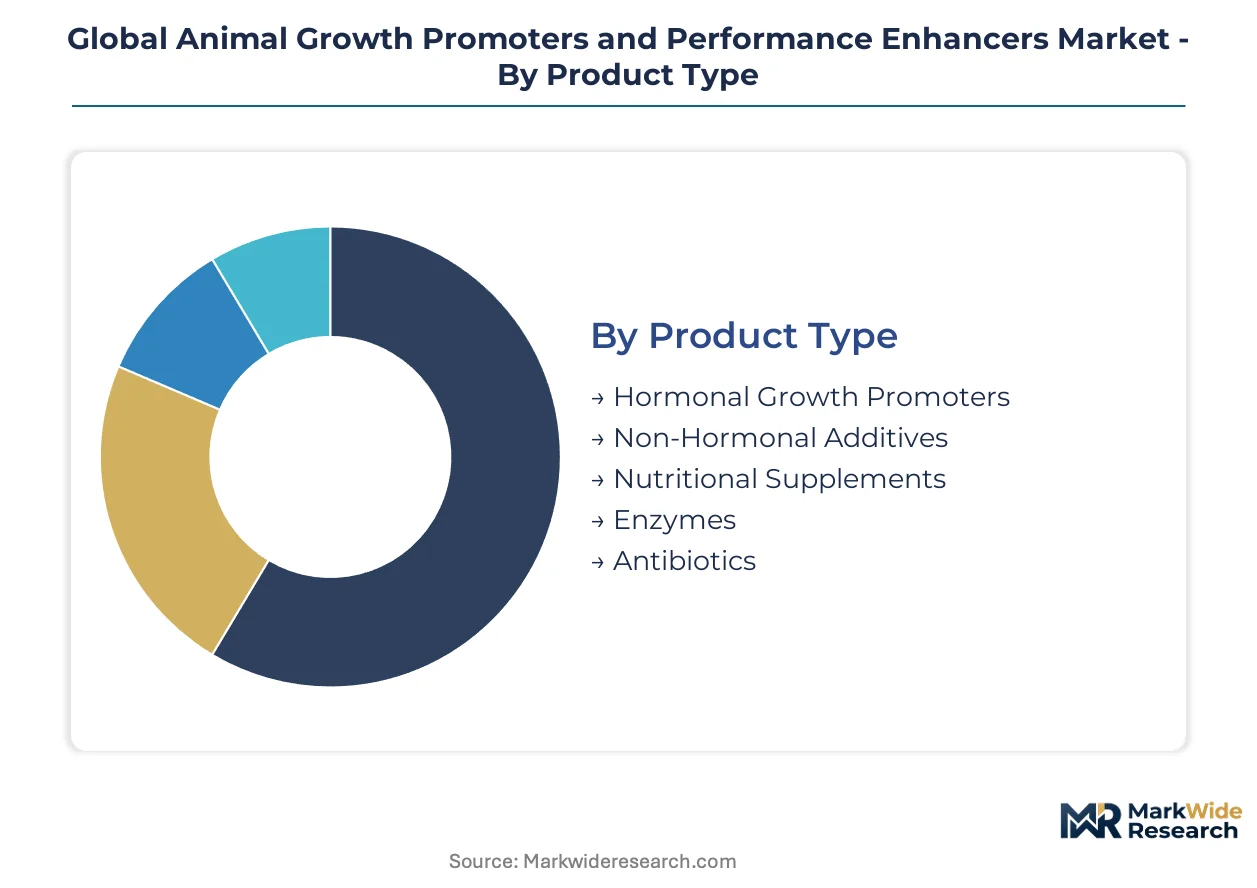
Segmentation in animal growth promoters reveals divergent regulatory tolerances and formulation economics across livestock species. Product type classifications separate mature hormonal segments from emerging biotechnological alternatives, while application splits expose poultry's volume dominance against aquaculture's technical lag.
Product Type:
Mature chemical synthesis categories face margin compression as biological manufacturing scales, while emerging precision fermentation platforms capture expanding formulation share.
- Enzymes:Phytase and carbohydrase formulations degrade anti-nutritional factors in plant-based feed matrices. Brazilian integrated poultry processors drive procurement concentration for these heat-stable variants in tropical storage conditions.
- Non-Hormonal Additives:Microbiome-based growth promoters include organic acids, prebiotics, and probiotic metabolites. Southeast Asian feed manufacturers expand procurement volumes to satisfy EU Green Deal residue standards for export-bound livestock products.
- Hormonal Growth Promoters:Synthetic steroid and peptide compounds remain restricted to specific regulatory jurisdictions with established residue monitoring infrastructure.
- Nutritional Supplements:Yeast-derived beta-glucans and nucleotides target immune modulation in ruminant and swine applications.
- Antibiotics:Medically important antimicrobial growth promoters face structural contraction across OECD markets, though residual demand persists in aquaculture where alternatives remain technically immature.
Enzymes retain volume leadership; non-hormonal additives hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity protein sectors with thin margins from specialized segments commanding premium formulation prices.
- Poultry Nutrition:Broiler and layer operations consume the largest additive volumes globally, with phytase adoption near-saturating intensive production systems. Export-oriented Brazilian processors specify enzyme inclusion rates exceeding domestic market baselines.
- Ruminant Health:Cattle feed additives target methane suppression and nitrogen retention. Australian grazing operations and Brazilian feedlot systems seek yeast-derived supplements that align with emerging carbon accounting frameworks.
- Swine Feed:Post-weaning diets incorporate acidifiers and zinc oxide alternatives as European antibiotic restrictions tighten.
- Aquaculture:Shrimp and finfish applications lag in probiotic efficacy validation, constraining transition timelines from antibiotic-dependent protocols.
- Pet Care:Companion animal formulations command premium pricing for human-grade ingredient specifications and specialized delivery formats.
Poultry nutrition dominates absolute consumption; ruminant health applications are climbing fastest on carbon policy alignment.
End User:
Customer type fragmentation concentrates procurement authority among integrated operations while dispersing transactional volumes across fragmented producer bases.
- Feed Manufacturers:Compound feed mills formulate additive premixes for distribution to independent livestock operations, facing margin pressure from direct-to-processor bypass strategies.
- Livestock Farmers:Integrated poultry and swine operations in Vietnam and Indonesia build technical service relationships directly with additive suppliers, displacing traditional distributor channels.
- Aquafarm Operators:Southeast Asian shrimp producers seek pathogen-specific probiotic solutions with documented survival benefits in high-density culture systems.
- Veterinary Clinics:Prescription-grade growth promoters and reproductive hormones require clinical administration and residue monitoring protocols.
- Animal Breeders:Genetic improvement programs utilize targeted nutritional interventions to optimize reproductive performance metrics.
Feed manufacturers retain transactional volume leadership; integrated livestock farmers are gaining share fastest through direct procurement consolidation.
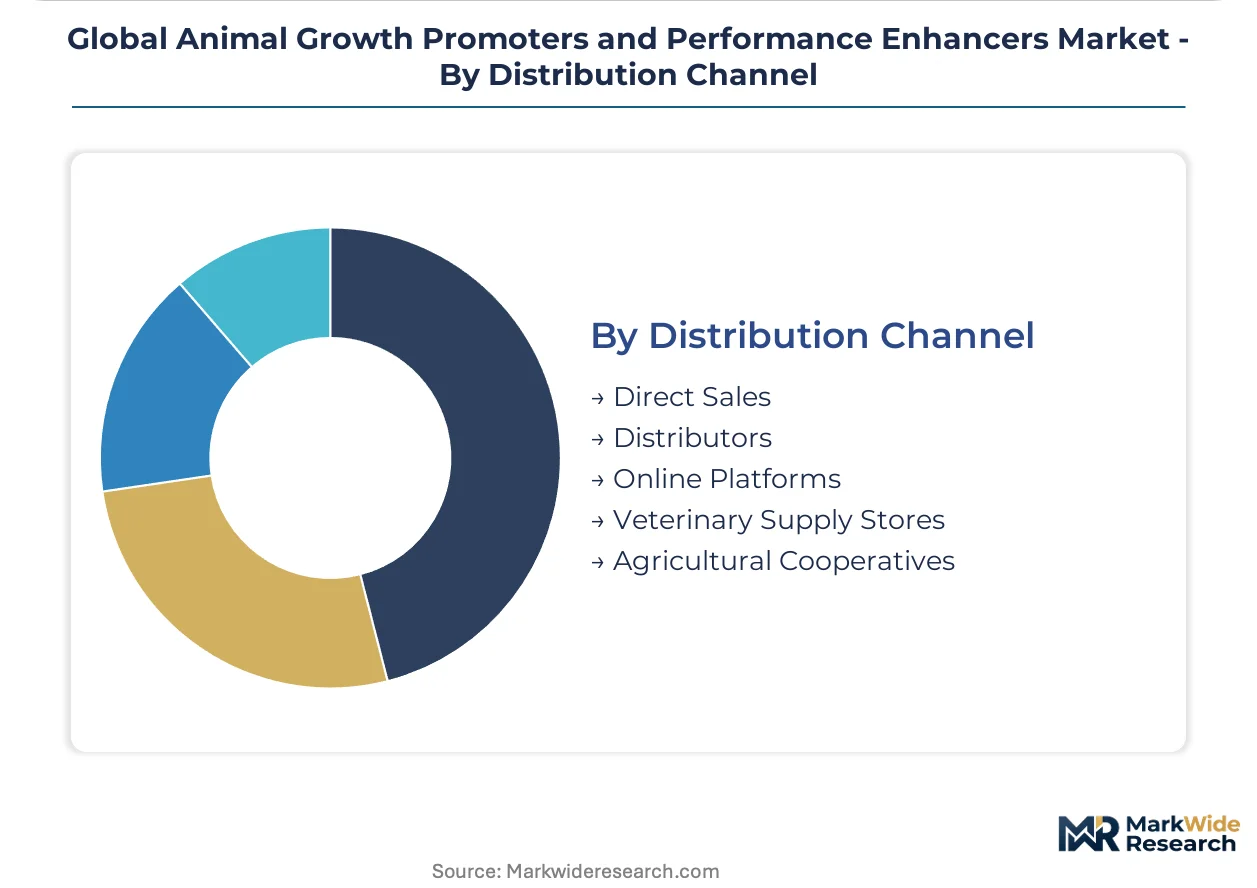
Distribution Channel:
Supply concentration in European and North American biotechnology producers shapes channel economics for Asian feed manufacturers exposed to currency and logistics volatility.
- Direct Sales:Technical service teams from specialized enzyme and probiotic suppliers establish on-farm relationships with large-scale integrated operations.
- Distributors:Regional feed additive distributors maintain inventory positions for mid-sized compounders lacking direct supplier contracts.
- Online Platforms:E-procurement channels expand for standardized nutritional supplements and commodity acidifiers with established specification profiles.
- Veterinary Supply Stores:Prescription hormonal products and therapeutic-grade additives require licensed veterinary dispensing.
- Agricultural Cooperatives:Producer-owned purchasing alliances aggregate demand for generic additive categories in fragmented farming regions.
Direct sales channels are expanding most quickly; distributor-mediated transactions retain residual volume in mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian poultry processors supply European retail channels under EU Green Deal residue standards, while Southeast Asian feed compounders reconfigure additive portfolios to maintain market access. This trade-flow dynamic concentrates investment in enzyme and probiotic manufacturing across tropical livestock zones.
United States
Integrated cattle feedlots in Texas and Kansas drive demand for hormonal growth promoters within FDA-regulated frameworks. The Veterinary Feed Directive governs medically important antibiotics in livestock feed, constraining product portfolios for domestic manufacturers. Omaha and Denver processing clusters specify residue-tested formulations for export-bound beef shipments.
Brazil
Export-oriented poultry processors in Mato Grosso and Paraná anchor regional enzyme consumption for phytase and carbohydrase applications. ANVISA monitors feed additive safety while EU import standards shape formulation specifications. São Paulo-based compounders build technical service relationships directly with integrated operations, bypassing traditional distribution channels.
China
Ministry of Agriculture and Rural Affairs enforces GB standards for feed additive safety testing across intensive swine and poultry operations. Dual carbon goals create procurement incentives for methane-reducing ruminant supplements in Inner Mongolian grazing zones. Shandong and Guangdong feed manufacturing clusters scale precision fermentation capacity for probiotic strain production.
Germany
EMA guidance on hormonal residues shapes formulation standards for EU-trading nations, with Bavarian compounders leading microbiome-based alternative development. REACH compliance requirements concentrate specialized enzyme sourcing among biotechnology suppliers in Baden-Württemberg. Cologne and Hamburg distribution hubs manage cross-border additive flows to Eastern European livestock operations.
Vietnam
Mekong Delta aquafarm operators seek pathogen-specific probiotic solutions as antibiotic alternatives remain technically immature for shrimp applications. National feed safety regulations align with EU Green Deal export requirements for seafood processors. Ho Chi Minh City technical teams from global suppliers establish direct relationships with integrated poultry operations in Dong Nai province.
Global Animal Growth Promoters and Performance Enhancers Market Competitive Landscape
On the supply side, the industry is consolidating around pharmaceutical heritage players with therapeutic expertise and agricultural biotechnology specialists with fermentation capabilities. Three archetypes dominate: integrated animal health conglomerates with regulatory navigation infrastructure, precision fermentation platforms with novel metabolite pipelines, and regional compounders with tropical formulation expertise. Competitive moves center on microbiome research partnerships and direct-to-processor distribution bypass strategies.
Within the pharmaceutical heritage tier, Elanco Animal Health and Zoetis exemplify regulatory-anchored positioning across hormonal and microbiome segments. Alltech occupies a distinct position as a yeast-derived nutritional supplement specialist with ruminant channel concentration. These three entities represent divergent strategic postures: therapeutic legacy integration, microbiome platform dominance, and fermentation-based nutritional innovation.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Zoetis |
| Boehringer Ingelheim |
| Merck Animal Health |
| Bayer Animal Health |
| Vetoquinol |
| Virbac |
| Ceva Sante Animale |
| Alltech |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's specialized enzyme production clusters concentrate global capacity for heat-stable phytase and carbohydrase formulations, granting European biotechnology suppliers outsized pricing leverage over Asian feed manufacturers exposed to euro-denominated procurement costs. This geographic concentration collapses margin buffers for tropical compounders when currency volatility strikes.
Pricing Analysis
Next-generation precision fermentation metabolites command 40-60% premiums over legacy chemical synthesis equivalents, while prior-generation antibiotic growth promoters face price erosion from regulatory phase-out schedules. Three-tier pricing structure across premium fermentation-derived, standard enzyme-based, and economy chemical additive levels stratifies the market. Pricing pressure stems from EU Green Deal compliance costs forcing Southeast Asian processors to absorb certification premiums for export-bound livestock. Integrated poultry operations in Brazil exhibit lowest price sensitivity due to export margin capture, while fragmented aquafarm operators in Vietnam face acute cost compression.
Supply Chain Analysis
DSM-Firmenich and Novozymes hold contract-manufacturing dominance for specialized feed enzymes, with production anchored in Germany, Denmark, and the Netherlands. Raw material dependencies span corn-derived fermentation substrates, specialized yeast strains, and pharmaceutical-grade peptide precursors. Single-source vulnerability concentrates in European fermentation capacity for probiotic metabolites, exposing Asian buyers to logistics chokepoints through Rotterdam and Hamburg distribution hubs. Distribution runs through direct technical service teams for integrated operations, with regional distributors retaining mid-market compounder relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up constitutes a high-growth disruption, with EU Green Deal residue standards forcing $12 billion in additive portfolio reconfiguration across export-dependent protein supply chains.
For Market Incumbents: Harden regulatory navigation infrastructure across FDA Veterinary Feed Directive, EMA residue guidance, and China's GB standards to defend formulation approvals from emerging biotechnology specialists. Consolidate precision fermentation capacity in Shandong and Guangdong clusters to offset European supply concentration risk. Deepen backward integration into yeast strain development to capture margin pools collapsing for chemical synthesis incumbents. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese and Indonesian direct-to-processor channels where technical service relationships displace traditional distributor networks. Target ruminant microbiome platforms for Australian and Brazilian carbon-aligned grazing operations as the most penetrable white space. Pursue white-label fermentation partnerships with Shandong manufacturing clusters to bypass multi-jurisdiction registration burdens. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical heritage players divesting non-core feed additive divisions as biological manufacturing displaces synthetic chemistry competencies. Long-term viability favors precision fermentation platforms with validated tropical stability profiles over legacy chemical synthesis assets. Monitor ANVISA and Ministry of Agriculture and Rural Affairs approval timelines as inflection indicators for market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biologically active metabolite production collapses synthetic manufacturing cost structures for probiotic formulations. |
| Direct-to-Processor Distribution | Technical service relationships with integrated Vietnamese poultry operations bypass traditional feed compounder channels. |
| Multi-Jurisdiction Registration | Concurrent FDA, EMA, and GB standard approvals extend commercialization timelines but lock out unresourced competitors. |
| Ruminant Microbiome Platform Development | Methane-reducing yeast-derived supplements align with Brazil's carbon accounting frameworks for export beef. |
| Backward Integration into Strain Development | In-house probiotic characterization capabilities reduce dependency on scarce Asian microbiome sequencing expertise. |
Research Methodology
Cross-validation between primary interviews with feed formulation directors, regulatory affairs leads at multinational animal health companies, procurement managers at Brazilian integrated processors, and technical directors at Southeast Asian compounders anchors the qualitative findings. Secondary validation draws from FDA Veterinary Feed Directive filings, EMA residue guidance documents, China's GB standards registry, and customs trade data for enzyme and probiotic additive flows. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Calibration against historical adoption curves for phytase and carbohydrase in Brazilian poultry, antibiotic phase-out timelines in EU-trading nations, and precision fermentation capacity buildouts in Shandong underpins the projection framework. Segmentation dimensions span product type, livestock application, end-user procurement authority, and regional regulatory cluster. CAGRs derive from elasticity-adjusted penetration modeling across enzyme, non-hormonal additive, and nutritional supplement categories. Forecast inputs incorporate EU Green Deal implementation pace and China's dual carbon procurement incentive structures.
Stress conditions across currency volatility for euro-denominated enzyme procurement, regulatory divergence between OECD and emerging economy residue thresholds, and technical validation timelines for aquaculture probiotics were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fermentation scale-up economics and trade flow reconfigurations. Quarterly review of ANVISA approval timelines, EMA guidance updates, and Shandong manufacturing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market