
 Organic Acids in Animal Nutrition Market | 2026-2036
Organic Acids in Animal Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Acids in Animal Nutrition Market Insights
Market Context
Buyer concentration among integrated poultry and pork processors is rebalancing procurement power toward large feed compounders. BASF SE leverages its backward integration into petrochemical feedstocks to control propionic acid cost positions across European livestock belts. Kemin Industries anchors its presence through microencapsulation technology that protects butyrate through upper-gut transit. Corbion competes on fermentation-derived platforms, differentiating its portfolio from petroleum-based rivals.
Technical Definition and Segment Structure
Organic acids in animal nutrition comprise short-chain carboxylic acids—primarily formic, acetic, propionic, and butyric—delivered as straight acids, salts, or esterified derivatives to acidify gastric contents, suppress gram-negative pathogens, and improve mineral chelation in monogastric species. Manufacturing proceeds via petrochemical oxidation or carbohydrate fermentation, with purity grades dictating suitability for feed versus pharmaceutical applications. Poultry feed applications dominate volume due to broiler gut health protocols, while aquaculture feed represents the fastest-expanding structural pocket as shrimp and salmon producers replace antibiotic growth promoters with acidifier blends. Liquid delivery modes capture the largest share of commodity acid sales, though granular and microencapsulated formats command premium positioning in young-animal diets where palatability and targeted release determine efficacy.
Regulatory Framework and Outlook
The European Food Safety Authority and European Chemicals Agency jointly constrain acidifier formulations through REACH substance evaluations and feed additive reauthorizations under Regulation 1831/2003. The U.S. Food and Drug Administration and China's Ministry of Agriculture and Rural Affairs maintain divergent approval pathways for novel acid salts, fragmenting product registration timelines across Atlantic and Pacific supply corridors. Stakeholders must monitor evolving maximum residue limits for acidifier metabolites in meat and milk, as these thresholds increasingly determine which chemistries gain formulary inclusion in export-oriented operations.
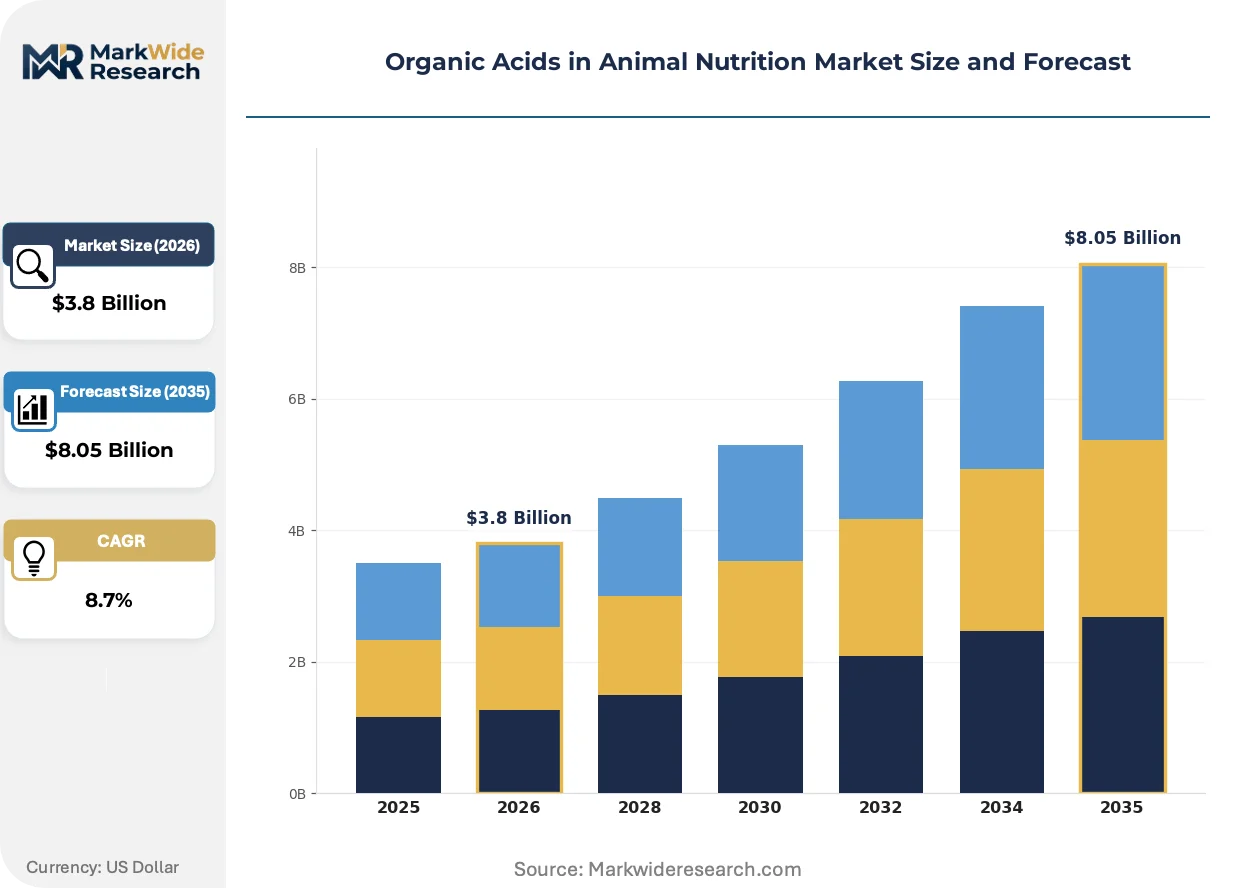
Market Dynamics
Integrated poultry and pork processors are consolidating procurement power, forcing compounders to absorb acidifier cost volatility while meeting tightening residue limits under EFSA and REACH frameworks.
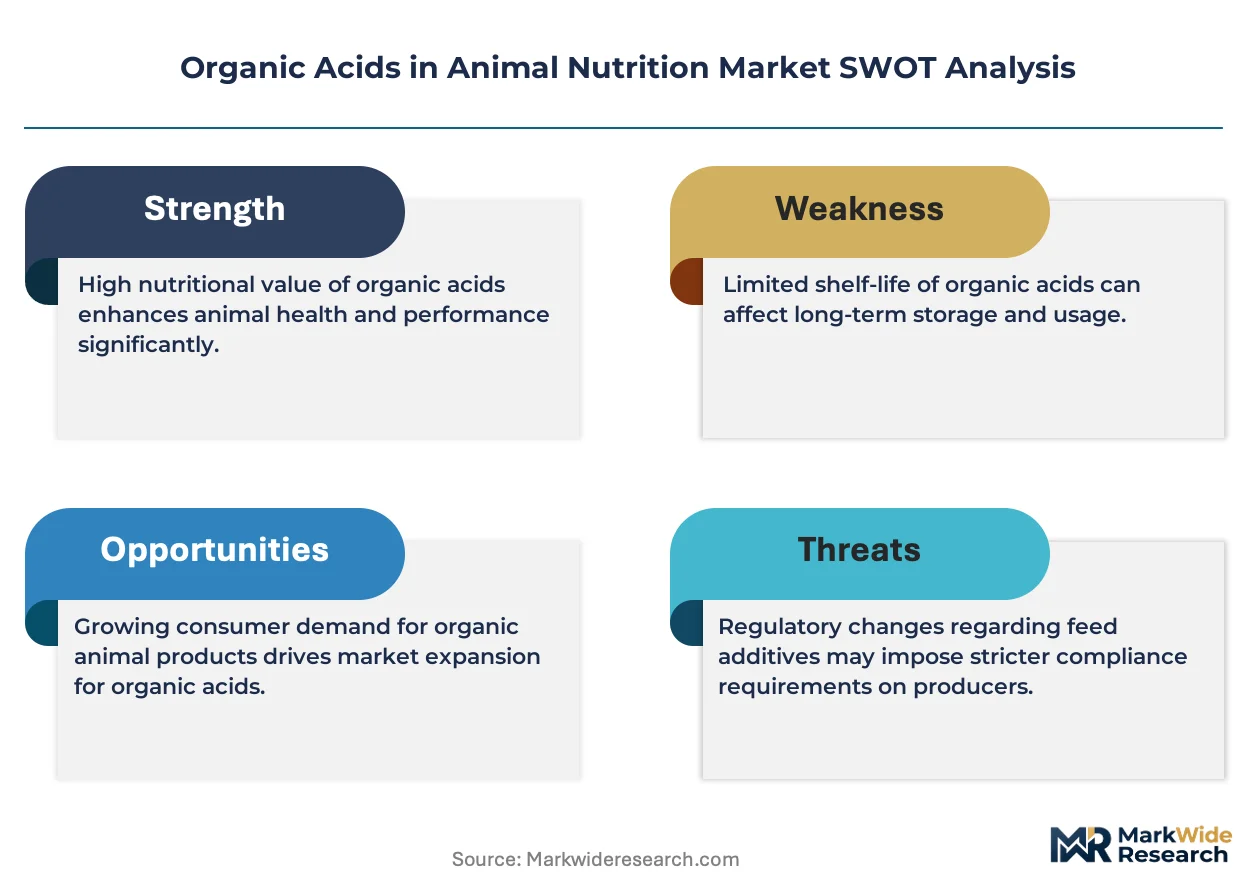
Growth Catalysts
- Antibiotic growth promoter bans:Brazil's MAPA enforcement and EU Regulation 1831/2003 reauthorizations are accelerating acidifier substitution in broiler and swine rations.
- Formic acid production scale-up:Petrochemical oxidation capacity expansion in the US Gulf Coast is lowering input costs for propionic and formic acid blends.
- Aquaculture feed conversion:Shrimp producers in Ecuador and Vietnam are adopting acidified premixes to replace prophylactic antibiotics in intensive pond systems.
Market Restraints
- Propionic acid feedstock volatility:Ethylene oxidation margins swing with crude oil benchmarks, compressing compounder margins during petrochemical upcycles.
- REACH substance evaluation timelines:ECHA's rolling re-evaluations of acid salts create 18-24 month registration delays, freezing formulary updates.
- Buffer technology substitution:Mineral acidifiers and phytogenic alternatives are capturing share in price-sensitive layer feed segments.
Strategic Opportunities
- Ruminant application white space:Beef feedlot operations in Australia and Argentina remain underpenetrated for acidified silage and total mixed ration programs.
- Microencapsulation-enzyme convergence:Combining butyrate protection with xylanase delivery is opening premium positioning in young piglet diets.
- Carbon border adjustment tailwinds:EU CBAM implementation favors fermentation-derived acids over petrochemical routes for export-oriented European compounders.
Industry Challenges
- Formulation chemist scarcity:The specialized skill set for acid-buffer compatibility testing is concentrated among legacy European compounders, constraining new entrant scale-up.
- Feed mill retrofit costs:Corrosion-resistant handling equipment for straight acid delivery requires capital outlays that fragment adoption between integrated and independent mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Acids in Animal Nutrition Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Formic Acid, Acetic Acid, Propionic Acid, Butyric Acid Application: Poultry Feed, Ruminant Feed, Swine Feed, Aquaculture Feed Delivery Mode: Liquid, Powder, Granular, Concentrate End User: Farmers, Feed Manufacturers, Veterinary Clinics, Research Institutions |
| Companies Covered | ADM, Perstorp, BASF SE, DSM, Kemin Industries, Corbion, Jungbunzlauer Suisse AG, Novus International, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Acids in Animal Nutrition Market Trends and Innovations
Formulation science is pivoting from commodity acid sales toward precision delivery systems that protect actives through upper-gut transit and enable species-specific dosing protocols.
Microencapsulated butyrate salts are electrifying young-animal nutrition by shielding sodium and calcium butyrate from gastric degradation until distal ileum release. Piglet starter feed compounders in Denmark and the Netherlands are adopting these formats at double-digit annual rates despite 40-60 percent premiums over straight acids. This technology is electrifying margin structures by converting commodity acid sales into high-value nutritional service contracts with guaranteed performance metrics.
EFSA's 2023 updated guidance on feed additive environmental risk assessments is forcing acidifier registrants to submit extended aquatic toxicity dossiers for metabolite discharge. The industrial consequence is a 12-18 month extension in reauthorization timelines for legacy formic acid salts. Aquaculture feed producers targeting EU export markets are responding by pivoting toward fermentation-derived acid blends with pre-submitted environmental fate data.
Compounders are consolidating acidifier procurement through multi-year toll manufacturing agreements rather than spot market purchases. Large integrators in Thailand and Indonesia are displacing traditional distributor networks with direct compounder relationships that bundle acidifiers, enzymes, and amino acids into single-source contracts. This concentration is most visible in vertically integrated shrimp operations where feed cost transparency has become a competitive weapon against independent hatcheries.
Organic Acids in Animal Nutrition Market Segmentation
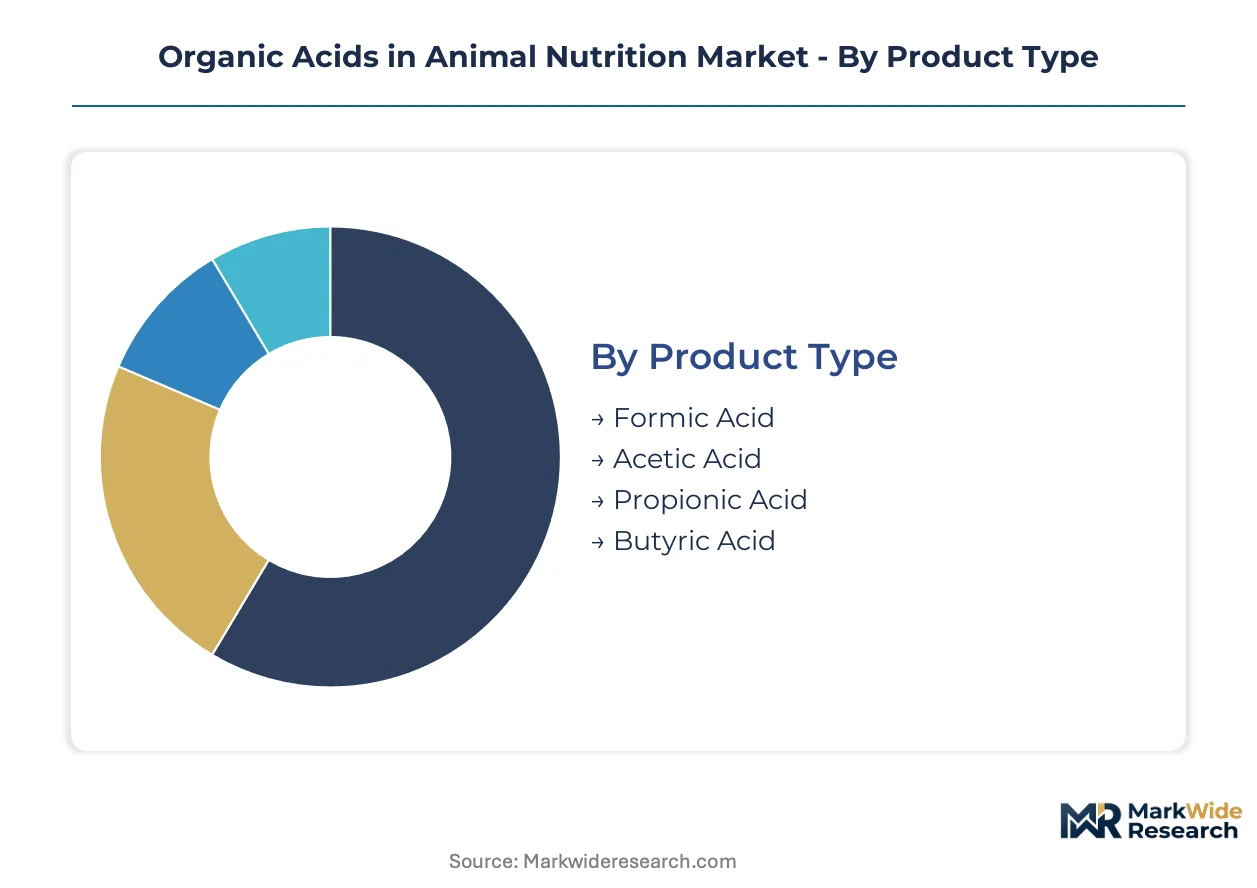
Organic acid procurement patterns diverge sharply across species-specific feed formulations, delivery technologies, and buyer sophistication tiers. Compounders must align acidifier portfolios with distinct gut physiology requirements, mill handling capabilities, and regulatory exposure profiles.
Product Type:
Cost sensitivity and pathogen suppression targets separate commodity acid buyers from premium formulation adopters.
- Formic Acid:The strongest acidifier by pKa value, formic acid dominates broiler and layer feed programs targeting Salmonella control. Integrated poultry operations in Brazil's Mato Grosso state specify formic-propionic blends for acidified premix programs serving export-oriented slaughterhouses.
- Propionic Acid:Fungistatic properties make propionic acid essential for feed preservation in humid climates. Southeast Asian shrimp feed mills rely on propionic acid blends to prevent mycotoxin contamination during tropical storage.
- Acetic Acid:Lower cost per unit acidity positions acetic acid in price-sensitive layer feed segments where moderate acidification suffices.
- Butyric Acid:Sodium and calcium butyrate salts command premium positioning in young-animal nutrition for intestinal villi development.
Formic acid leads volumes today; butyric acid is gaining share fastest.
Application:
Species gut physiology dictates acidifier selection, with monogastric applications commanding technology premiums over ruminant commodity sales.
- Poultry Feed:Broiler integrators deploy acidifier blends across starter, grower, and finisher phases to replace antibiotic growth promoters. EFSA's tightened residue limits under Regulation 1831/2003 are accelerating buffered acidifier adoption in Dutch and Danish compound feed.
- Swine Feed:Weaning stress protocols drive microencapsulated butyrate demand in piglet starter feeds. Danish compounders specify protected butyrate formats with guaranteed ileal release metrics.
- Aquaculture Feed:Shrimp producers in Ecuador and Vietnam are converting intensive pond systems to acidified premixes as antibiotic substitutes.
- Ruminant Feed:Beef feedlot operations in Australia and Argentina remain underpenetrated for acidified silage and total mixed ration programs.
Poultry feed absorbs the largest volume; aquaculture feed is climbing the fastest.
Delivery Mode:
Mill infrastructure investment separates liquid system adopters from dry format buyers seeking handling simplicity.
- Liquid:Straight acids in aqueous solution capture commodity volume through cost-efficient bulk delivery. US Gulf Coast petrochemical supply proximity lowers landed costs for North American compounders operating corrosion-resistant handling systems.
- Powder:Spray-dried acid salts suit independent mills lacking liquid storage infrastructure.
- Granular:Free-flowing granules enable precise dosing in automated batching systems.
- Concentrate:High-potency concentrates reduce freight costs for remote aquaculture feed operations.
Liquid delivery dominates tonnage; granular formats command the steepest price premiums.
End User:
Procurement scale and technical capability create four distinct buyer archetypes with diverging service requirements.
- Feed Manufacturers:Large compounders negotiate multi-year toll manufacturing agreements bundling acidifiers, enzymes, and amino acids. Thai and Indonesian integrators are displacing distributor networks with direct compounder relationships.
- Farmers:Smallholder operations purchase acidified premixes through cooperative procurement channels.
- Veterinary Clinics:Specialty acidifier formulations for therapeutic gut health protocols serve companion animal and high-value livestock segments.
- Research Institutions:Universities and feed trial centers drive novel acid salt evaluation for regulatory submission packages.
Feed manufacturers concentrate procurement volume; veterinary clinics represent the highest margin outlet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's integrated meat processors command acidifier procurement volumes that dwarf Argentina's fragmented feedlot sector, while Southeast Asian aquaculture expansion outpaces European poultry demand growth.
Brazil
Integrated pork and broiler operations in Mato Grosso and Paraná states have expanded acidified premix programs to meet export slaughterhouse specifications. MAPA enforcement of antibiotic growth promoter bans accelerates formic-propionic blend substitution. São Paulo-based compounders negotiate multi-year toll manufacturing agreements that bundle acidifiers with amino acids.
United States
Petrochemical oxidation capacity expansion along the US Gulf Coast lowers input costs for propionic and formic acid blends. FDA approval pathways for novel acid salts remain distinct from European frameworks, fragmenting product registration timelines. North Carolina and Arkansas poultry belts specify buffered acidifiers to manage Salmonella control costs.
Germany
EFSA and ECHA jointly constrain acidifier formulations through REACH substance evaluations and Regulation 1831/2003 reauthorizations. The F-Gas Regulation and tightening residue limits push compounders toward fermentation-derived platforms. Lower Saxony feed mills lead adoption of corrosion-resistant liquid handling systems for straight acid delivery.
China
The Ministry of Agriculture and Rural Affairs maintains divergent approval pathways that extend novel acid salt registration timelines. Dual carbon goals favor fermentation-derived production routes over petrochemical oxidation. Shandong Peninsula feed manufacturers consolidate procurement through direct compounder relationships displacing traditional distributor networks.
Vietnam
Shrimp producers in intensive pond systems adopt acidified premixes to replace prophylactic antibiotics for EU export compliance. Humid tropical storage conditions drive propionic acid demand for mycotoxin prevention. Mekong Delta feed mills rely on high-potency concentrates to reduce freight costs from remote supply points.
Organic Acids in Animal Nutrition Market Competitive Landscape
European producers anchor the premium formulation tier; North American specialists hold commodity acid positions through petrochemical feedstock proximity. The vendor base concentrates around backward-integrated chemical conglomerates and fermentation-platform innovators. Three archetypes dominate: petrochemical oxidation specialists, carbohydrate fermentation platforms, and microencapsulation technology providers. Capacity expansion in US Gulf Coast propionic acid production and multi-year toll manufacturing agreements represent the dominant competitive moves.
Within the fermentation-platform tier, Corbion and Jungbunzlauer Suisse AG exemplify carbohydrate-derived positioning distinct from petroleum-based rivals. Among petrochemical oxidation specialists, BASF SE occupies a position leveraging captive feedstock integration. Kemin Industries anchors the microencapsulation archetype through protected butyrate formats. DSM represents diversified nutritional ingredient portfolios that bundle acidifiers with enzyme and vitamin offerings.
| Leading Market Players |
|---|
| ADM |
| Perstorp |
| BASF SE |
| DSM |
| Kemin Industries |
| Corbion |
| Jungbunzlauer Suisse AG |
| Novus International |
| Cargill, Incorporated |
| Others |
Pricing and Supply Chain Analysis
Microencapsulated butyrate premiums diverge sharply from commodity acid spot markets, with sodium and calcium salt formats commanding 40-60 percent markups over straight acids while concentrating production among legacy European compounders with captive formulation chemists. This tier split feeds directly into procurement patterns: integrated poultry processors in Brazil's Mato Grosso state negotiate multi-year toll manufacturing agreements that bundle acidifiers with amino acids, whereas independent Southeast Asian shrimp feed mills purchase high-potency concentrates through distributor networks to circumvent capital-intensive liquid handling infrastructure.
Pricing Analysis
Capacity additions along the US Gulf Coast are reshaping price floors for propionic and formic acid blends, compressing margins for petrochemical oxidation specialists during ethylene upcycles. Contract-based long-term offtake dominates procurement among large integrators, with price differentiation hinging on certification grade under EFSA's Regulation 1831/2003 and volume scale. Cost compression in straight acid tiers is intensifying because Brazilian MAPA enforcement of antibiotic growth promoter bans has accelerated substitution demand. Smallholder cooperatives remain most price-sensitive, while Danish piglet starter feed compounders absorb premiums for guaranteed ileal release metrics.
Supply Chain Analysis
Single-source vulnerability sits with German fermentation-platform producers for carbohydrate-derived acids, while petrochemical oxidation capacity clusters in the United States and China. Raw material dependencies encompass ethylene feedstocks for oxidation routes, molasses and corn starch for fermentation, and specialized coating polymers for microencapsulation. Regulatory restriction risk looms through ECHA's rolling REACH re-evaluations, which freeze formulary updates for 18-24 month windows. Distribution runs through direct compounder relationships in Thailand and Indonesia, displacing traditional distributor networks among vertically integrated shrimp operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage favors fermentation-derived acid platforms in Europe as EU CBAM implementation penalizes petrochemical carbon intensity, while US Gulf Coast oxidation specialists capture feedstock proximity advantages in North American poultry belts.
For Market Incumbents: To counter mineral acidifier and phytogenic substitution in price-sensitive layer feed segments, BASF SE and Corbion should deepen backward integration into captive ethylene and carbohydrate feedstocks respectively. Certification investment under EFSA's updated environmental risk assessment protocols preserves formulary positioning for EU export-oriented compounders. For New Entrants and Emerging Players: Launch via aquaculture feed concentrate formats targeting Vietnamese shrimp producers seeking antibiotic replacement for EU compliance. Australia's beef feedlot sector offers underpenetrated white space for acidified silage programs, with go-to-market traction through direct relationships with Queensland and New South Wales integrators bypassing legacy distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with microencapsulation technology providers combining butyrate protection with enzyme delivery. Long-term viability over a multi-year horizon favors fermentation-platform assets with pre-submitted environmental fate data. Watch ECHA substance evaluation timelines as the inflection signal for formulary access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive ethylene or carbohydrate sourcing insulates margin volatility from crude oil benchmarks. |
| Microencapsulation-Enzyme Convergence | Combined butyrate-xylanase formats command premium positioning in Danish piglet starter protocols. |
| Fermentation Platform Scale-Up | Carbohydrate-derived routes gain EU CBAM preference over petrochemical oxidation for export compounders. |
| Direct Compounder Relationship Building | Thai and Indonesian integrators displace distributor networks with bundled acidifier-enzyme-amino acid contracts. |
| Environmental Fate Dossier Pre-Submission | Pre-submitted aquatic toxicity data accelerates EFSA reauthorization timelines for legacy acid salts. |
Research Methodology
Direct dialogue with feed mill procurement directors, compounder formulation chemists, regulatory affairs specialists at acidifier registrants, and aquaculture operations managers grounded this analysis in operational reality. Secondary validation drew from EFSA feed additive reauthorization databases, ECHA REACH substance evaluation records, US FDA approval pathway filings, and Brazilian MAPA enforcement circulars. Bottom-up volume estimates from species-specific feed formulation rates triangulated against top-down chemical industry capacity disclosures.
Bottom-up modeling segmented the market by acid type, species application, delivery technology, and buyer sophistication tier across the projection horizon. Top-down cross-checks referenced petrochemical oxidation capacity expansions and fermentation platform utilization rates. CAGRs derived from regression analysis against antibiotic growth promoter substitution elasticities and integrated processor procurement consolidation trajectories. Forecast inputs incorporated EFSA environmental risk assessment timeline extensions and EU CBAM carbon border adjustment implementation schedules.
Several conditions sit outside the modeled scope, including abrupt REACH substance evaluation accelerations, feed mill retrofit capital availability fluctuations, and ruminant application adoption rate deviations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Cattle Nutrition Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market