
 Cattle Nutrition Market | 2026-2036
Cattle Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Nutrition Market Insights
Veterinary nutrition expertise is bifurcating the competitive landscape as specialized formulation knowledge separates premium suppliers from commodity blenders. Cargill Inc. leverages its global grain origination network to secure cost-advantaged feedstock positions across multiple continents. Nutreco N.V. sustains R&D intensity through dedicated innovation centers focused on rumen-modulating additives. De Heus Animal Nutrition anchors its growth strategy in family-farm partnerships across Eastern Europe and Southeast Asia.
Cattle nutrition encompasses the science of formulating and delivering balanced dietary inputs—crude protein, energy, minerals, vitamins, and functional additives—to optimize rumen fermentation, growth rates, and reproductive performance in bovine herds. Precision formulation requires NDF (neutral detergent fiber) thresholds between 28-35% for high-producing dairy cows to maintain rumen pH above 6.0 and prevent subacute acidosis. Feed additives, particularly yeast cultures and ionophores, command disproportionate margins as producers seek methane mitigation and feed conversion efficiency gains. Pellet form dominates commercial channels due to reduced sorting behavior and uniform nutrient delivery, though block formulations retain share in extensive grazing systems where labor availability limits daily feeding frequency.
The EPA regulates feed manufacturing under the Clean Air Act, while the FDA oversees medicated feed additives through its Veterinary Feed Directive, reshaping product registration timelines and label claims for antibiotic alternatives. BIS feed quality standards in India and GB standards under SAMR in China create divergent compliance pathways for multinational suppliers seeking market access. Stakeholders must monitor evolving carbon accounting methodologies for Scope 3 agricultural emissions, as downstream protein buyers begin imposing feed-linked climate disclosure requirements on their supply bases.
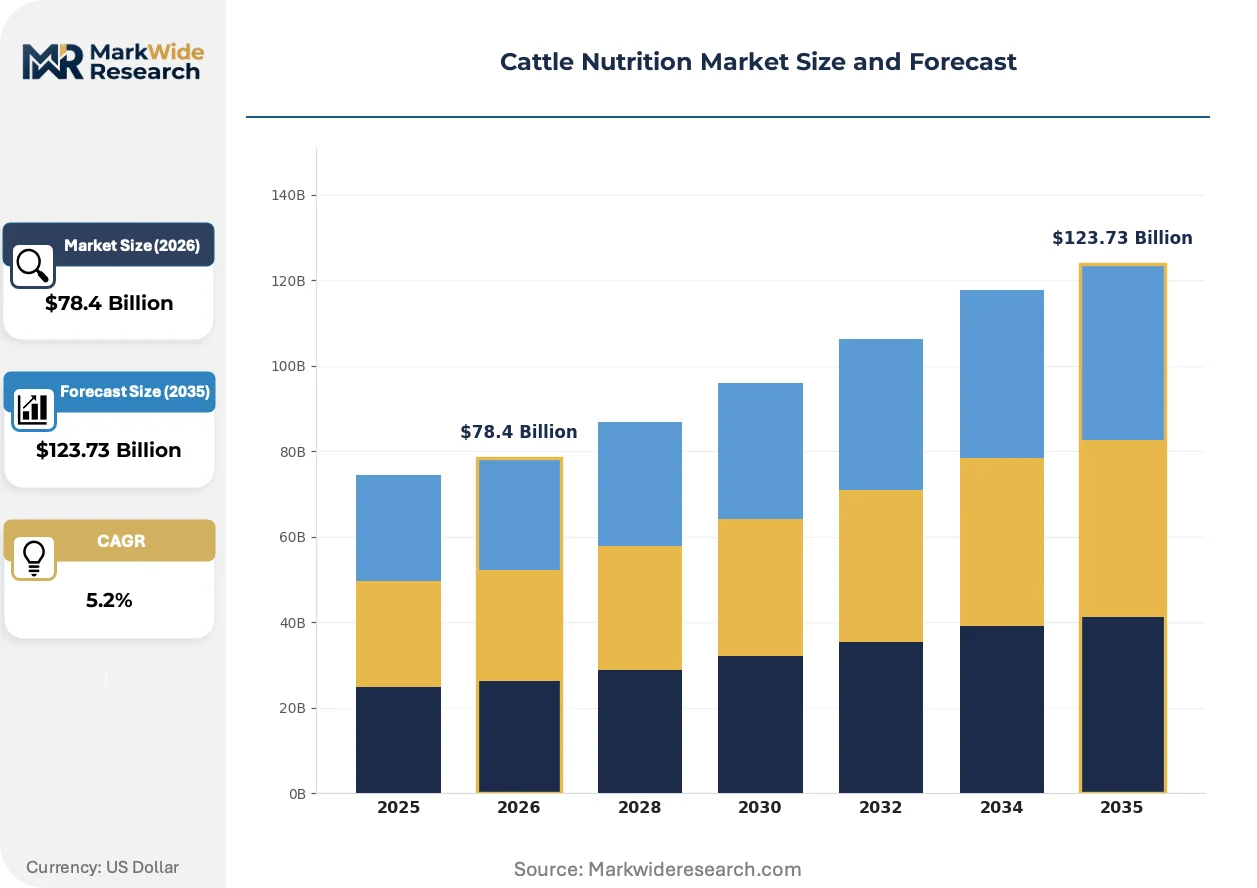
Market Dynamics
Precision feeding systems and methane-mitigation mandates are restructuring procurement priorities across cattle operations, forcing nutrition suppliers to reformulate around rumen-modulating additives and carbon-accounting traceability.
Growth Catalysts
- EU F-Gas Regulation:Tightening emissions standards for livestock operations are accelerating demand for low-carbon feed formulations that reduce enteric methane output.
- Integrated Brazilian feedlots:Expanding beef export capacity across Brazil's central-west cattle belt is driving premium nutrition adoption in confined finishing systems.
- Yeast culture additives:Rumen-modulating technologies are capturing disproportionate margins as producers prioritize feed conversion efficiency and herd health metrics.
Market Restraints
- Grain price volatility:Global origination networks face margin compression when corn and soybean meal markets spike, squeezing formulation economics.
- FDA Veterinary Feed Directive:Antibiotic restriction protocols are extending product registration timelines and complicating label claims for medicated additives.
- Regional supply concentration:Premium additive manufacturing clusters in Western Europe create logistics vulnerability for Asian and Latin American distributors.
Strategic Opportunities
- India's BIS feed standards:Compliance pathway divergence creates first-mover advantage for suppliers establishing local formulation facilities ahead of enforcement tightening.
- Block formulation channels:Extensive grazing systems with labor constraints present underserved demand for self-fed mineral and protein supplementation.
- Carbon disclosure mandates:Downstream protein buyers imposing Scope 3 agricultural emissions tracking are creating subscription revenue streams for feed-linked climate data services.
Industry Challenges
- Rumen microbiology expertise:Veterinary nutrition specialization is bifurcating the talent pool, with premium suppliers competing for scarce formulation scientists.
- Legacy system integration:Precision feeding software deployment faces friction from farm-level data infrastructure gaps and operator training requirements.
- Cross-border certification timelines:Divergent GB standards under China's SAMR versus BIS protocols in India are fragmenting product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Nutrition Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Feed Additives, Protein Supplements Form: Powder, Liquid, Block, Pellets End User: Dairy Farms, Beef Cattle Producers, Feedlots, Veterinary Clinics Distribution Channel: Online Retail, Direct Sales, Distributors, Agro Vets |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Nutreco N.V., ForFarmers N.V., Land O'Lakes Inc., Alltech Inc., De Heus Animal Nutrition, Charoen Pokphand Foods Group, Kemin Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Nutrition Market Trends and Innovations
Active fermentation monitoring and real-time ration adjustment are transforming how nutrition programs align with individual animal metabolic status, compressing the gap between research formulations and field performance.
Precision rumen pH sensors paired with automated concentrate dispensers are displacing manual feeding schedules in high-producing dairy herds. Large-scale operations in the Netherlands and Denmark are deploying these systems at commercial scale. The technology is displacing nutritionist-dependent ration balancing with algorithm-driven daily adjustments that prevent subacute acidosis.
The EU Green Deal's farm-to-fork strategy is mandating 50% pesticide reduction and binding climate targets for agricultural inputs. Feed manufacturers must now document lifecycle emissions across ingredient sourcing and processing stages. Dairy cooperatives in Northern Europe are responding by consolidating procurement around certified low-carbon premix suppliers.
Direct contracting between beef processors and feed mills is compressing traditional distributor layers in Brazil's Mato Grosso and Goiás production zones. Vertically integrated protein exporters are capturing margin by controlling nutrition inputs through captive blending facilities. This channel consolidation is most visible among export-oriented feedlots serving Middle Eastern and Asian markets.
Cattle Nutrition Market Segmentation
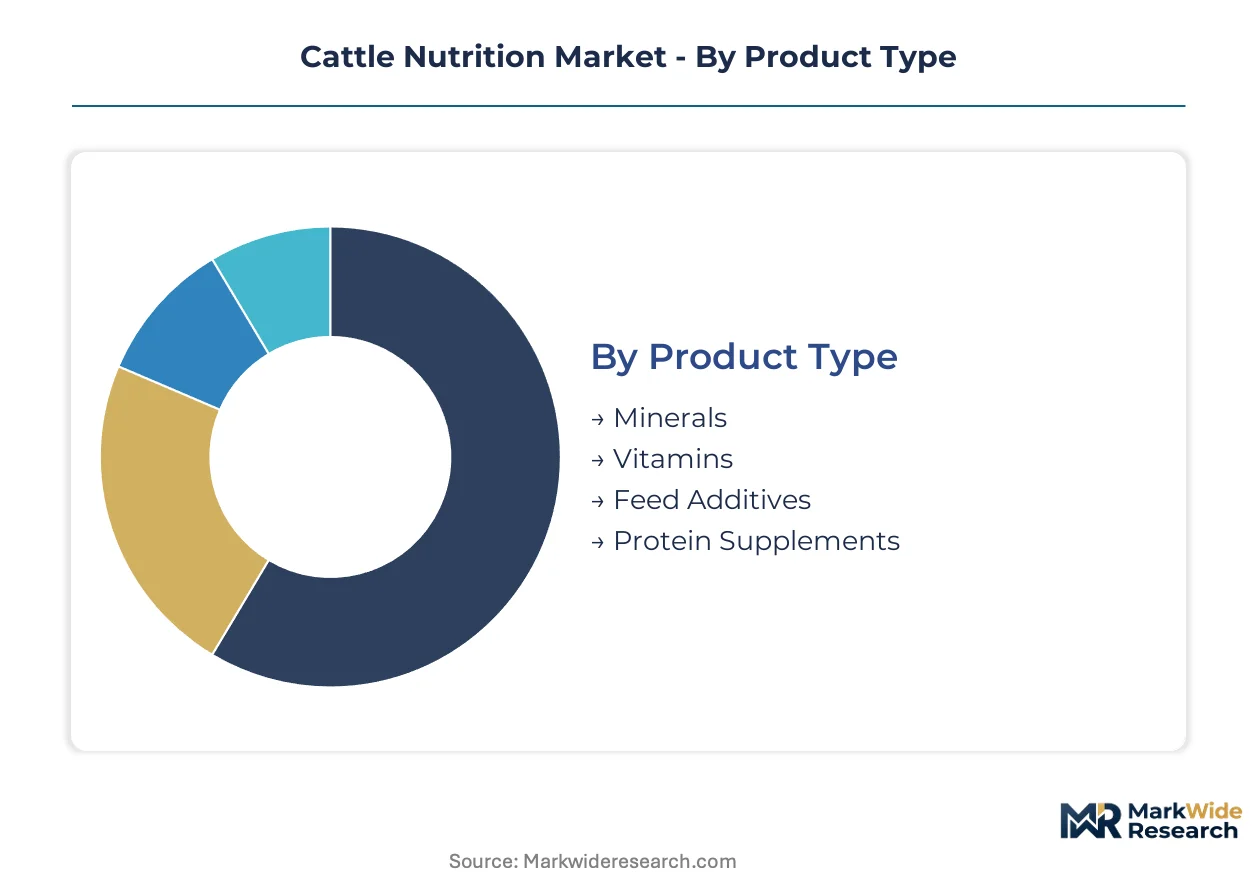
Cattle nutrition suppliers configure product portfolios around four distinct segmentation axes. Each dimension reflects divergent cost structures, delivery logistics, and buyer procurement sophistication across domestic and export-oriented operations.
Product Type:
Domestic consumption concentrates in mineral and vitamin premixes, while feed additives and protein supplements flow disproportionately toward export-led dairy and beef operations.
- Minerals:Macro and trace mineral premixes provide calcium, phosphorus, magnesium, and selenium to prevent metabolic disorders. Demand clusters in intensive dairy regions of the Netherlands and Denmark where herd productivity thresholds mandate precise mineral balancing. Sourcing complexity for chelated trace minerals elevates pricing power among specialized blenders.
- Feed Additives:Yeast cultures, ionophores, and rumen buffers modulate fermentation efficiency and methane output. Brazilian integrated feedlots in Mato Grosso and Goiás are scaling additive inclusion rates to meet EU import standards for low-carbon beef. Regulatory pressure under the EU F-Gas Regulation is accelerating reformulation toward methane-inhibiting compounds.
- Vitamins:Fat-soluble and water-soluble vitamin premixes prevent deficiency syndromes in high-producing herds.
- Protein Supplements:Urea, bypass protein, and oilseed meals correct rumen-degradable protein deficits in forage-based diets.
Minerals command the established base. The steepest expansion runs through feed additives.
Form:
Cost tier stratification separates labor-intensive powders and liquids from premium-priced blocks and pellets that reduce daily handling requirements.
- Pellets:Compressed formulations eliminate sorting behavior and ensure uniform nutrient delivery across the herd. Large-scale dairy operations in Denmark and the Netherlands deploy automated feeding systems optimized for pellet flow characteristics. Pellet durability specifications above 95% reduce fines generation during pneumatic conveying.
- Block:Self-fed mineral and protein blocks address labor constraints in extensive grazing systems. Australian and Argentine pastoral operations rely on block formulations where daily feeding frequency is impractical. Weather-resistant binding technologies extend block integrity through seasonal exposure.
- Powder:Dry premixes offer formulation flexibility for on-farm blending operations.
- Liquid:Molasses-based suspensions and emulsified fat supplements integrate into total mixed rations.
Pellets anchor volume leadership in intensive systems. Block formulations are gaining share fastest in pastoral zones with labor scarcity.
End User:
Application intensity varies sharply between high-frequency dairy nutrition programs and seasonal beef finishing cycles.
- Dairy Farms:Continuous feeding regimens demand precise ration balancing to sustain milk yield and reproductive performance. Precision feeding technology penetration is highest among cooperative-affiliated herds in Northern Europe. Real-time rumen pH monitoring justifies premium additive spending in herds exceeding 10,000 liters annual production.
- Feedlots:Confined finishing systems concentrate feed conversion efficiency optimization in the final 90-120 days. Brazilian central-west feedlots serving Middle Eastern export markets are consolidating procurement around captive blending facilities. Direct processor-mill contracting is displacing traditional distributor layers.
- Beef Cattle Producers:Cow-calf and stocker operations prioritize cost-efficient mineral supplementation.
- Veterinary Clinics:Clinical nutrition services address metabolic disorder recovery and transition cow management.
Dairy farms represent the most stable demand base. Feedlot operations are climbing the fastest as Brazilian export capacity expands.
Distribution Channel:
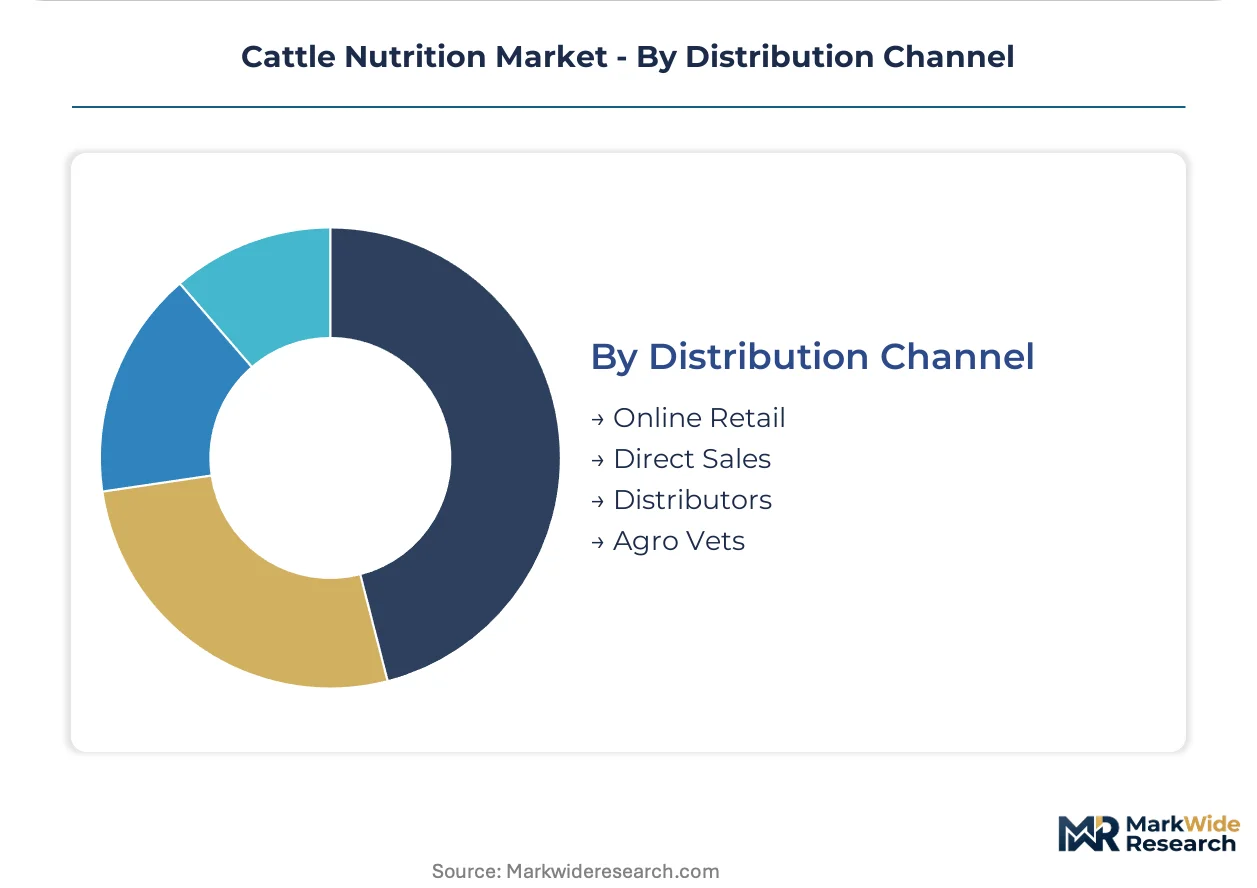
Customer type and procurement scale determine channel selection, with large operations bypassing intermediaries while smaller farms rely on technical advisory services.
- Direct Sales:Major nutrition suppliers deploy technical sales teams to large integrated operations and cooperative procurement groups. Cargill and Nutreco maintain dedicated account management for feedlot chains exceeding 50,000 head capacity. Contract structures increasingly incorporate carbon accounting data services.
- Agro Vets:Veterinary-pharmacy hybrids provide formulation advice alongside product distribution. De Heus leverages agro-vet partnerships to penetrate family-farm segments across Eastern Europe and Southeast Asia. Technical credibility differentiates advisory-intensive channels from commodity traders.
- Distributors:Regional wholesalers aggregate fragmented demand across smaller operations.
- Online Retail:E-commerce platforms serve hobby farms and specialty additive purchasers.
Direct sales capture the premium tier. Agro-vet networks are expanding most quickly in emerging markets with veterinary advisory gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed additive consumption patterns diverge sharply between intensive dairy zones and extensive grazing belts, with Northern European herds prioritizing rumen-modulating technologies while Brazilian operations emphasize export-compliant finishing formulations.
United States
Large-scale feedlots in the Texas Panhandle and Kansas are deploying precision methane-monitoring systems to preempt EPA enforcement actions under evolving Clean Air Act interpretations. The FDA's Veterinary Feed Directive continues reshaping antibiotic alternative registration timelines. Nebraska's Platte River Valley concentrates premix manufacturing capacity serving the Corn Belt dairy corridor.
Brazil
Integrated beef processors in Mato Grosso and Goiás are consolidating nutrition procurement through captive blending facilities to meet EU F-Gas Regulation compliance for export shipments. ANVISA feed additive protocols are tightening documentation requirements for ionophore imports. The central-west cattle belt now hosts the densest concentration of automated feed mill investments outside North America.
Netherlands
Cooperative dairy herds exceeding 10,000 liters annual production are standardizing real-time rumen pH monitoring under EU Green Deal farm-to-fork binding targets. EFSA novel feed additive approvals are accelerating yeast culture formulations with documented methane reduction coefficients. Friesland's precision feeding technology cluster supplies retrofit packages across Northern European cooperative networks.
India
Domestic dairy cooperatives in Gujarat and Maharashtra are expanding bypass protein supplementation as BIS feed quality standards enforcement intensifies ahead of 2025 compliance deadlines. FSSAI coordination with state dairy federations is harmonizing mineral premix specifications. The Anand milk shed anchors formulation R&D partnerships between multinational suppliers and indigenous cooperatives.
China
Large-scale dairy operations in Hebei and Shandong provinces are adopting SAMR-certified low-carbon premixes under dual carbon goals pressure from downstream protein processors. GB standards for feed additive residue limits are diverging from Codex Alimentarius benchmarks, fragmenting import approval pathways. The Yangtze River Delta concentrates domestic yeast culture manufacturing serving premium herd segments.
Cattle Nutrition Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding grain origination economies and the lower layer competing on rumen microbiology expertise. The market structure rewards backward integration into feedstock procurement and forward integration into precision feeding data services. Three archetypes dominate: global grain traders with nutrition divisions, dedicated animal nutrition pure-plays, and cooperative-affiliated regional blenders. Competitive intensity concentrates on M&A-driven geographic expansion and technology licensing for methane-mitigation additives.
Within the global grain-trader archetype, Cargill Inc. and Archer Daniels Midland Company exemplify scale-driven positioning anchored in multi-continent origination networks. Nutreco N.V. occupies the dedicated nutrition pure-play tier, while De Heus Animal Nutrition represents cooperative-rooted regional expansion. These three patterns illustrate how supplier configuration maps to buyer procurement sophistication across dairy cooperative, integrated feedlot, and family-farm segments.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| ForFarmers N.V. |
| Land O'Lakes Inc. |
| Alltech Inc. |
| De Heus Animal Nutrition |
| Charoen Pokphand Foods Group |
| Kemin Industries Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Brazilian integrated feedlots and premix suppliers lock in corn and soybean meal access while anchoring price visibility through the EU F-Gas Regulation compliance cycle. These arrangements insulate buyers from spot grain volatility while committing suppliers to methane-reducing additive volumes.
Pricing Analysis
Contract-based long-term offtake dominates large dairy cooperatives and export-oriented feedlots, with spot markets serving fragmented family farms. Price differentiation hinges on certification tier—EU Green Deal-aligned low-carbon premixes command substantial premiums over standard formulations—and volume scale, where herds exceeding 10,000 liters annual production secure preferential terms. Cost compression in commodity mineral blends is intensifying because Brazilian grain origination networks face margin pressure during corn price spikes. Family-farm segments exhibit highest price sensitivity, while Northern European dairy cooperatives prioritize methane-accounting traceability over unit economics.
Supply Chain Analysis
Brazil, the United States, and the Netherlands anchor global premix and additive manufacturing, with Brazil's central-west cattle belt hosting the densest automated feed mill investments outside North America. Formulation draws from chelated trace minerals sourced through specialized Western European blenders, yeast cultures manufactured in the Yangtze River Delta, and oilseed meals from Argentine crushing facilities. Single-source vulnerability concentrates in ionophore additive production clusters located in Western Europe, exposing Asian and Latin American distributors to logistics disruption. Distribution runs through direct technical sales teams for integrated operations exceeding 50,000 head capacity, while agro-vet hybrids penetrate family-farm segments across Eastern Europe and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-accounting data services represent a service-attach opportunity expanding faster than hardware, as downstream protein buyers impose Scope 3 agricultural emissions tracking on feed suppliers.
For Market Incumbents: Consolidate around captive blending facilities in Brazil's Mato Grosso and Goiás production zones to preempt channel disintermediation by vertically integrated beef processors. Secure backward integration into yeast culture manufacturing to reduce dependency on Yangtze River Delta supply clusters. Lock in long-term offtake contracts with Northern European dairy cooperatives before EFSA novel feed additive approvals commoditize methane-inhibiting formulations. For New Entrants and Emerging Players: Differentiate on block formulation specialization for extensive grazing systems in Australia and Argentina where labor constraints limit daily feeding frequency. Target India's Gujarat and Maharashtra dairy cooperatives ahead of BIS feed quality standards enforcement tightening. Penetrate through agro-vet partnerships that combine mineral premix distribution with veterinary advisory services, replicating De Heus's Eastern Europe model. For Investors and Strategic Acquirers: Capital is best deployed toward rumen-modulation additive specialists with documented methane reduction coefficients and EFSA approval pathways. The five-to-ten year viability window favors suppliers integrating precision feeding software with hardware-enabled subscription revenue. Watch for inflection when EU carbon border adjustment mechanisms begin pricing enteric methane into import tariffs on Brazilian beef.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Culture Manufacturing | Captive supply of rumen-modulating additives reduces Western European single-source vulnerability for Brazilian feedlots. |
| Precision Feeding Software Subscription Launch | Real-time rumen pH monitoring services generate recurring revenue from Dutch cooperative herds exceeding 10,000 liters production. |
| Carbon Accounting Data Platform Partnership | Feed-linked emissions tracking aligns with EU Green Deal farm-to-fork binding targets for Scope 3 disclosure. |
| Local Formulation Facility in India | BIS compliance pathway divergence creates first-mover positioning ahead of 2025 enforcement deadlines in Gujarat. |
| Direct Processor Contracting in Brazil | Long-term offtake agreements with Mato Grosso feedlots preempt distributor layer compression by integrated beef exporters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with dairy cooperative procurement directors, feedlot nutrition managers, premix formulation scientists, agro-vet channel partners, and regulatory affairs specialists at multinational suppliers. Secondary validation incorporated FDA Veterinary Feed Directive filings, EFSA novel feed additive approval databases, ANVISA import documentation, BIS feed quality standards drafts, and customs data on yeast culture trade flows. Bottom-up herd-level consumption estimates were triangulated against top-down premix manufacturing capacity assessments.
Across the analysis window, the forecasting framework modeled product type segmentation—minerals, feed additives, vitamins, and protein supplements—alongside form factor, end-user application intensity, and distribution channel procurement sophistication. CAGRs were derived from elasticity-adjusted consumption trajectories tied to dairy productivity thresholds and Brazilian beef export capacity expansion. Rumen-modulating additive adoption curves and precision feeding technology penetration rates served as industry-specific forecast inputs.
Material uncertainties—grain price volatility, regulatory approval timelines for methane-inhibiting compounds, and carbon accounting methodology standardization—sit outside the modeled envelope. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement intensity and Brazilian integrated feedlot consolidation pace. Recalibration cycles align with material shifts in downstream protein buyer Scope 3 disclosure requirements and EFSA novel feed additive approval decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
South America Eubiotics Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Animal Feed Phytase Market