
 Agricultural Unit Heaters Market | 2026-2036
Agricultural Unit Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Unit Heaters Market Insights
Large-scale agribusiness firms is unwinding the historical dominance of small farm operations as the primary buyer archetype for agricultural unit heaters. Rheem Manufacturing leverages its distribution network across rural supply cooperatives to sustain volume leadership in gas-fired equipment. Daikin Industries anchors its position through advanced heat exchanger technology optimized for corrosive barn environments. Bosch Thermotechnology competes on efficiency ratings that appeal to energy-conscious plantation estates managing heating costs across multiple facilities.
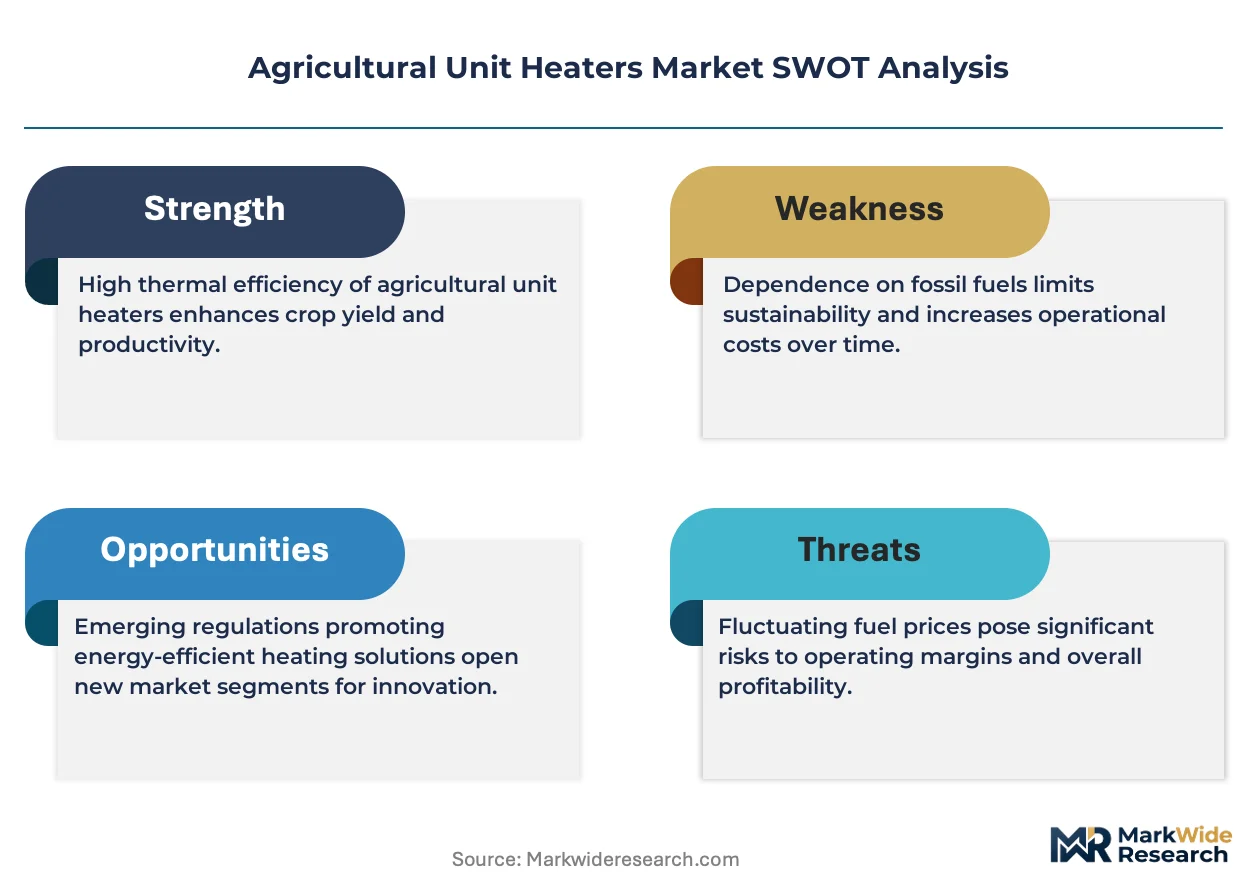
Agricultural unit heaters are self-contained heating appliances designed to maintain thermal conditions in livestock housing, crop storage, and controlled-environment agriculture, typically rated between 50,000 and 400,000 BTU per hour with corrosion-resistant housings for ammonia-rich atmospheres. Their primary purpose is preventing livestock mortality, ensuring germination rates, and protecting harvested commodities from moisture damage in cold-climate operations. Gas heaters occupy the largest installed base due to lower operating costs where pipeline or bulk propane infrastructure exists, while infrared heaters command premium positioning in poultry houses where draft-free radiant warmth reduces bird stress and improves feed conversion. Electric heaters lead in greenhouse applications where zero-emission heating aligns with organic certification requirements, though operating expense limits expansion beyond regions with favorable utility rates.
EPA New Source Performance Standards and OSHA ventilation requirements shape product design by mandating sealed combustion and minimum air-exchange rates in confined animal feeding operations. CE marking under the EU Ecodesign Directive restricts market access for imported units failing efficiency benchmarks, while USDA conservation programs incentivize energy-efficient heater retrofits through cost-share arrangements. Stakeholders must monitor evolving state-level carbon pricing proposals and decide whether to prioritize low-carbon electric portfolios or invest in advanced gas combustion technologies that preserve existing infrastructure.
Market Dynamics
EPA New Source Performance Standards are forcing sealed combustion architectures across livestock confinement heating systems, compressing margins for manufacturers lacking certified product portfolios while advantaging incumbents with established testing relationships.
Growth Catalysts
- USDA Conservation Programs:Cost-share arrangements for energy-efficient retrofits accelerate replacement cycles in Midwest grain and livestock operations.
- Controlled-Environment Agriculture:Commercial greenhouse operators in the Netherlands and Canada expand heated acreage for year-round vegetable production.
- Infrared Radiant Technology:Poultry integrators adopt draft-free warming systems to reduce bird stress and improve feed conversion metrics.
Market Restraints
- Steel and Aluminum Input Volatility:Heat exchanger fabrication costs fluctuate with commodity pricing, pressuring margin stability for corrosion-resistant component suppliers.
- CE Marking Compliance Burden:EU Ecodesign Directive efficiency benchmarks restrict market access for imported units lacking certified test data.
- Electric Resistance Substitution Ceiling:Operating expense barriers limit electric heater penetration beyond regions with favorable utility rate structures.
Strategic Opportunities
- Sub-Saharan Livestock Modernization:Commercial dairy and poultry ventures in Kenya and Nigeria require climate-controlled housing infrastructure.
- Biogas-Fired Heating Convergence:On-farm anaerobic digesters supply methane for captive heating, pairing waste management with thermal energy.
- Rural Cooperative Distribution Channels:Direct supply relationships with agricultural supply cooperatives bypass traditional HVAC wholesale networks.
Industry Challenges
- Combustion Engineering Talent Scarcity:Specialized expertise in ammonia-resistant burner design concentrates among legacy equipment manufacturers.
- Multi-Jurisdiction Certification Timelines:Parallel EPA, OSHA, and state-level air quality approvals extend product launch cycles by 12-18 months.
- Legacy Barn Infrastructure Integration:Retrofit installations accommodate uneven concrete pads, irregular ventilation patterns, and obsolete fuel delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Unit Heaters Market |
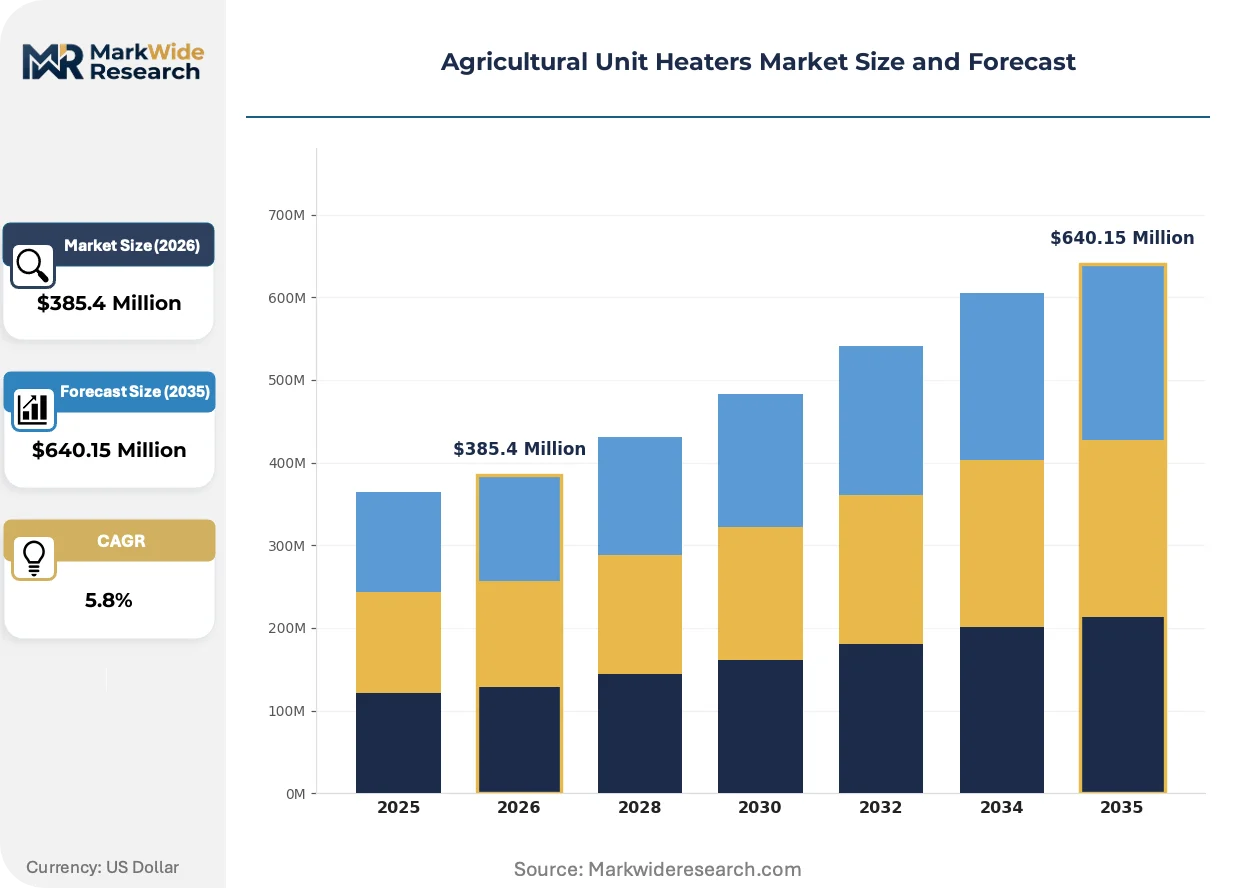
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
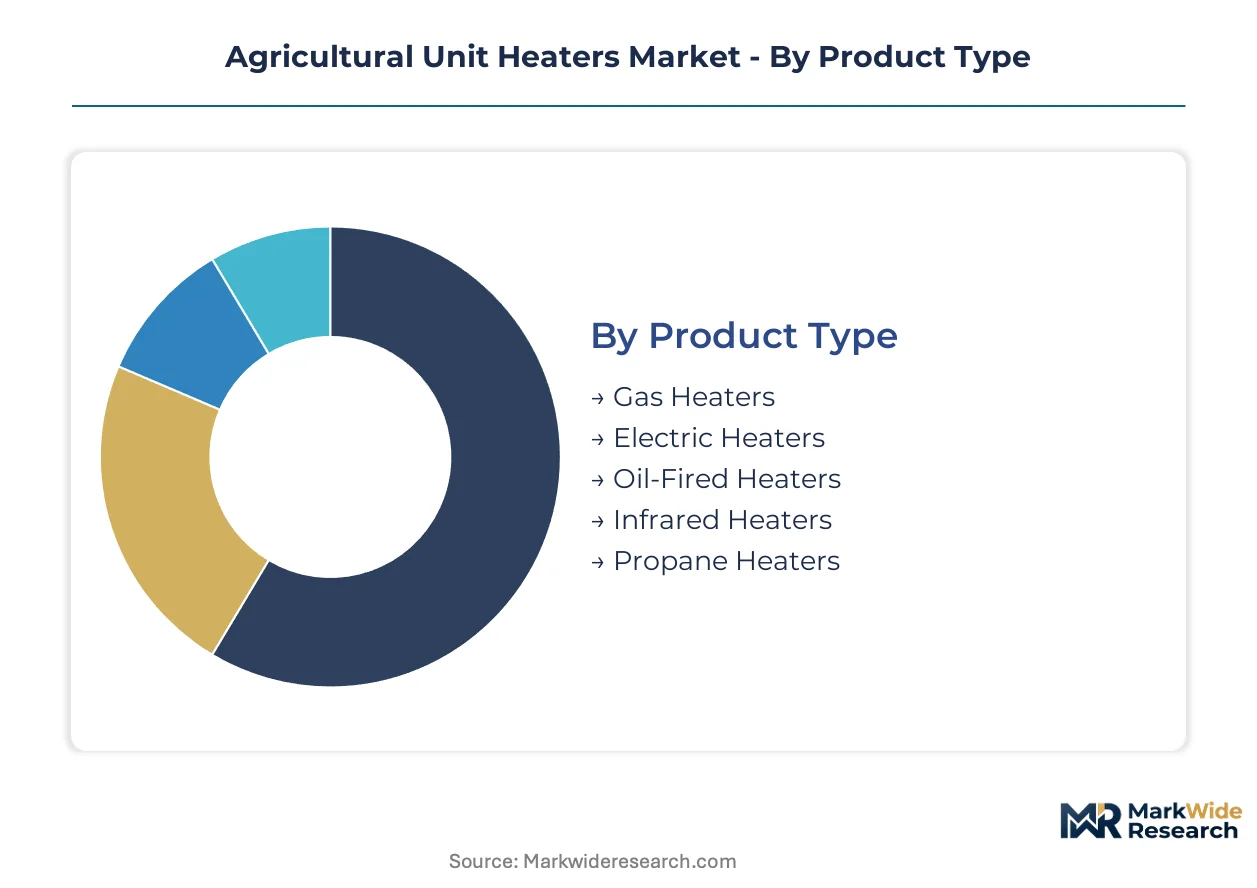
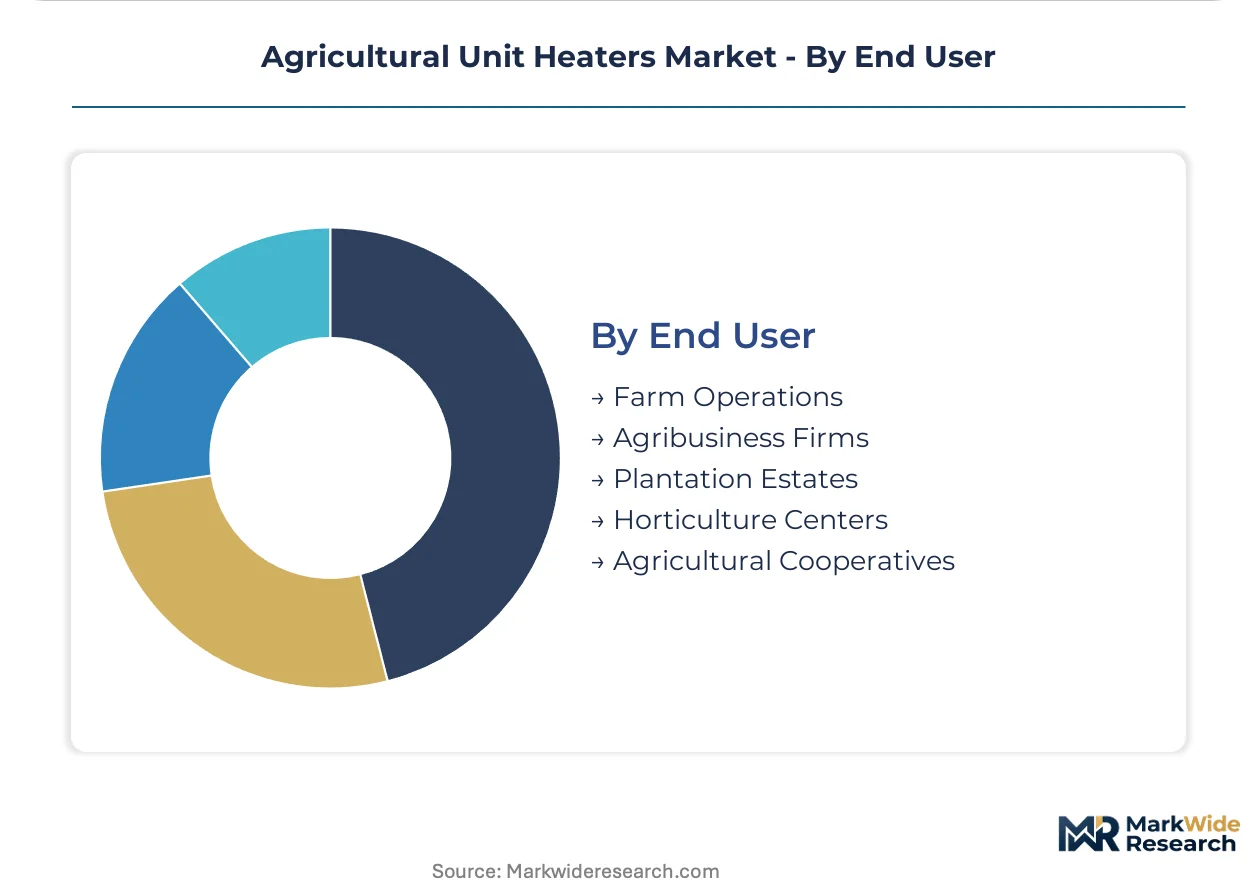
| Segmentation | Product Type: Gas Heaters, Electric Heaters, Oil-Fired Heaters, Infrared Heaters, Propane Heaters Technology: Direct Fired, Indirect Fired, Convection, Radiant, Forced Air Application: Livestock Barns, Crop Drying, Greenhouses, Poultry Houses, Warehouses End User: Farm Operations, Agribusiness Firms, Plantation Estates, Horticulture Centers, Agricultural Cooperatives |
| Companies Covered | Rheem Manufacturing, Sterling HVAC, Daikin Industries, Johnson Controls, Stelpro, Carrier Global, Bosch Thermotechnology, Lennox International, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Unit Heaters Market Trends and Innovations
Product architecture is splitting between premium sealed-combustion systems for regulated environments and cost-optimized atmospheric units for exempt agricultural structures. This divergence reshapes R&D allocation and manufacturing footprint decisions across the supply base.
Condensing heat exchanger technology is bifurcating the product hierarchy. These systems capture latent heat from exhaust gases to achieve efficiency ratings above 90%. Large-scale hog and dairy operations in Denmark and the Netherlands specify condensing units to meet carbon accounting requirements. The technology is compressing demand for conventional atmospheric heaters in premium segments while leaving price-sensitive buyers with widening performance gaps.
EPA emissions certification timelines are tightening product development cycles. Manufacturers must submit test data under revised New Source Performance Standards before market entry. Livestock confinement applications face the strictest scrutiny due to ammonia-rich atmospheres and continuous operation profiles. Firms with established EPA testing relationships accelerate certification, while smaller competitors face backlog delays at approved laboratories.
Buying behavior is consolidating through agricultural supply cooperatives and direct manufacturer relationships. Traditional HVAC distribution channels lose share as large integrators negotiate volume contracts for multi-facility deployments. This channel compression is most visible in the US Midwest, where livestock operators manage heating standardization across dozens of confinement sites.
Agricultural Unit Heaters Market Segmentation
Heater specification varies sharply across agricultural subsectors. Thermal load calculations, fuel infrastructure access, and species-specific comfort requirements drive distinct procurement patterns that manufacturers must address through targeted product portfolios.
Product Type:
Margin pools concentrate in gas-fired equipment where replacement cycles and parts revenue sustain aftermarket profitability.
- Gas Heaters:Atmospheric and power-vented units rated 50,000-400,000 BTU/hour dominate Midwest grain and livestock operations. Pipeline natural gas access in Iowa, Illinois, and Nebraska locks in operating cost advantages that resist electric conversion despite efficiency gaps.
- Electric Heaters:Resistance and heat pump configurations serve greenhouse operators pursuing organic certification where zero-emission heating satisfies audit requirements. Favorable utility rates in Pacific Northwest hydroelectric zones and Quebec enable operating cost parity with combustion alternatives.
- Oil-Fired Heaters:Diesel and fuel oil units persist in remote Canadian prairie farms lacking gas pipeline infrastructure.
- Infrared Heaters:Radiant tube and plaque systems command premium positioning in poultry integrator specifications.
- Propane Heaters:Bulk tank configurations serve transitional zones between natural gas grids and fully electrified regions.
Gas heaters hold installed capacity. Infrared heaters are rotating up the share rankings.
Technology:
Volume concentrates in forced-air and convection systems where manufacturing scale and installation simplicity compress unit economics.
- Direct Fired:Open-flame combustion introduces moisture and combustion byproducts directly into conditioned spaces. Swine farrowing operations in Denmark and the Netherlands specify direct-fired units for rapid temperature recovery after ventilation cycles, accepting humidity trade-offs for capital cost savings.
- Indirect Fired:Sealed combustion chambers with heat exchangers isolate exhaust gases from conditioned air. EPA New Source Performance Standards mandate this architecture for new livestock confinement construction, adding heat exchanger cost and maintenance burden.
- Convection:Natural airflow circulation suits low-ceiling crop storage facilities with minimal ventilation requirements.
- Radiant:Infrared energy transfer creates zoned warmth without air movement, critical for draft-sensitive poultry and calf housing.
- Forced Air:Fan-driven distribution achieves rapid temperature uniformity across large floor plates in machinery storage and packing sheds.
Forced air dominates shipment volumes. Indirect fired is climbing the fastest as regulatory compliance tightens.
Application:
Customer concentration varies by heating season length and facility capital intensity.
- Livestock Barns:Continuous heating demand for swine, dairy, and beef cattle housing drives premium equipment specifications. Mortality risk from cold stress justifies redundant heating capacity and 24-hour service contracts.
- Greenhouses:Seasonal and diurnal temperature swings require modulation capability and integration with shading and ventilation systems. Dutch Venlo-style glasshouse operators specify condensing boilers with heat storage for load shifting.
- Crop Drying:Batch-process heating for grain moisture reduction operates at extreme temperature differentials with abrasive dust exposure.
- Poultry Houses:Broiler and layer operations demand precise temperature gradients across brooding, growing, and laying zones.
- Warehouses:Equipment and commodity storage requires freeze protection rather than comfort conditioning, permitting simpler control strategies.
Livestock barns anchor replacement demand. Greenhouses are gaining share fastest through controlled-environment agriculture expansion.
End User:
Procurement sophistication stratifies sharply by operation scale and technical staffing.
- Agribusiness Firms:Integrated pork and poultry producers standardize equipment across multi-state facility portfolios. Volume contracts with national manufacturers bypass distribution markups and lock in parts availability commitments.
- Farm Operations:Family-owned grain and livestock enterprises rely on agricultural supply cooperatives for equipment selection guidance and installation referrals. Price sensitivity limits specification to proven atmospheric heater designs.
- Plantation Estates:Large-scale specialty crop operations in California's Central Valley and Florida's citrus belt manage heating costs across dispersed facilities, prioritizing efficiency ratings in capital allocation decisions.
- Horticulture Centers:Nursery and floriculture operations require precise humidity and temperature control for propagation success.
- Agricultural Cooperatives:Member-owned supply organizations aggregate purchasing power for input standardization across patron operations.
Agribusiness firms command specification influence. Farm operations retain volume leadership in unit shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat exchanger fabrication and sealed-combustion engineering concentrate among North American and Western European manufacturing bases. These regions anchor supply chains for corrosion-resistant components while regulatory divergence shapes product certification requirements across destination markets.
United States
Midwest livestock confinement operations in Iowa, Illinois, and Nebraska drive replacement cycles for gas-fired equipment. EPA New Source Performance Standards mandate sealed combustion architectures for new construction, compressing margins for uncertified suppliers. The Minnesota-Wisconsin dairy corridor hosts concentrated demand for ammonia-resistant heating systems in large-scale hog and cattle facilities.
Canada
Prairie grain operations and remote livestock farms lacking pipeline infrastructure sustain demand for propane and oil-fired alternatives. Natural Resources Canada's energy efficiency regulations align with provincial carbon pricing schemes in British Columbia and Quebec. The Red River Valley greenhouse cluster near Winnipeg expands heated acreage for vegetable production under favorable hydroelectric rates.
Netherlands
Venlo-style glasshouse operators specify condensing boilers with heat storage systems to meet carbon accounting requirements under EU Ecodesign Directive benchmarks. The Westland horticulture district drives premium equipment specifications for year-round tomato and pepper cultivation. CE marking compliance creates certification barriers for non-European manufacturers lacking established testing relationships.
China
Shandong and Henan provinces host expanding livestock confinement capacity requiring winter heating systems for swine and poultry operations. GB standards for agricultural equipment safety shape product design for domestic manufacturers. The Yangtze River Delta greenhouse belt adopts electric heating configurations where grid infrastructure supports load management.
Brazil
Commercial poultry integrators in São Paulo and Paraná states deploy radiant heating systems to optimize feed conversion in broiler operations. ANVISA veterinary facility regulations intersect with state-level environmental licensing for concentrated animal feeding operations. The southern livestock belt experiences seasonal heating demand spikes that stress equipment reliability standards.
Agricultural Unit Heaters Market Competitive Landscape
Concentration sits with diversified HVAC conglomerates and specialized agricultural equipment fabricators. The vendor base stratifies between premium sealed-combustion specialists and cost-optimized atmospheric unit producers. Two strategic archetypes dominate: integrated heating system providers leveraging distribution scale, and corrosion-engineering specialists commanding technical premiums. Competitive moves center on EPA certification acceleration and cooperative distribution channel capture.
Among North American diversified manufacturers, Rheem Manufacturing and Carrier Global represent scale-driven archetypes with established rural supply relationships. Daikin Industries and Bosch Thermotechnology exemplify technology-forward positioning through heat exchanger specialization. Johnson Controls occupies a position bridging commercial HVAC expertise with agricultural application adaptation. These named entities anchor competitive dynamics without exhausting the participant universe.
| Leading Market Players |
|---|
| Rheem Manufacturing |
| Sterling HVAC |
| Daikin Industries |
| Johnson Controls |
| Stelpro |
| Carrier Global |
| Bosch Thermotechnology |
| Lennox International |
| Trane Technologies |
| Others |
Pricing and Supply Chain Analysis
Heat exchanger fabrication scale economies in Ohio and Michigan concentrate corrosion-resistant component supply among legacy equipment manufacturers, compressing price floors for sealed-combustion architectures while elevating procurement leverage for volume buyers negotiating multi-facility contracts across Midwest livestock operations.
Pricing Analysis
Volume-discount tiering structures separate agribusiness integrators securing national account pricing from family farm operations purchasing through agricultural supply cooperatives at standard list rates. Price differentiation hinges on EPA certification status and after-sales service bundling, with sealed-combustion units commanding premiums due to testing compliance costs. Cost compression in atmospheric heater tiers is intensifying because commodity steel and aluminum volatility erodes margin buffers. Agribusiness firms exhibit lowest price sensitivity given mortality-risk mitigation priorities, while small grain operations in Nebraska and Kansas remain most responsive to capital cost differentials.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane elevates inbound logistics costs for heat exchanger alloys and electronic control modules sourced from East Asian manufacturing bases. Geographic supply concentration centers on the United States, Germany, and China for corrosion-resistant burner assemblies and precision-formed steel housings. Raw material dependencies draw from galvanized steel, aluminum extrusions, and ceramic radiant plaques. Single-source vulnerability concentrates in specialized ammonia-resistant coating chemistries. Distribution runs through agricultural supply cooperatives and direct manufacturer relationships, bypassing traditional HVAC wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution defense imperatives as heat pump configurations and biogas-fired systems displace conventional gas combustion in carbon-accounting-sensitive operations. Electric resistance and heat pump technologies threaten core revenue streams where grid infrastructure supports load management.
For Market Incumbents: Fortify certification portfolios by accelerating EPA New Source Performance Standards testing relationships, compressing launch cycles for sealed-combustion architectures before regulatory deadlines tighten. Anchor aftermarket profitability through captive parts supply and 24-hour service contracts with large integrators, defending against corrosion-engineering specialists capturing premium positioning in poultry and dairy specifications.
For New Entrants and Emerging Players: Remote diagnostic and predictive maintenance capabilities represent a service-layer gap where incumbents under-serve family farm operations lacking technical staffing. Target Sub-Saharan livestock modernization in Kenya and Nigeria, where commercial dairy and poultry ventures require climate-controlled housing infrastructure absent established supplier relationships. Pursue rural cooperative distribution partnerships to bypass entrenched national account structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors corrosion-engineering specialists with established heat exchanger intellectual property and EPA testing relationships over diversified HVAC conglomerates facing portfolio rationalization pressures. Long-term viability rests on condensing technology adoption curves and carbon pricing trajectory across Midwest agricultural states. Watch state-level carbon pricing proposals as inflection indicators for electric portfolio prioritization versus advanced gas combustion investment.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA Certification Acceleration | Sealed-combustion testing relationships compress product launch cycles before regulatory deadlines. |
| Backward Integration into Heat Exchanger Fabrication | Captive corrosion-resistant component supply defends margin buffers against steel volatility. |
| Rural Cooperative Channel Capture | Direct supply relationships with agricultural cooperatives bypass traditional HVAC wholesale markups. |
| Biogas-Fired Heating Convergence | On-farm anaerobic digester integration pairs waste management with captive thermal energy supply. |
| Condensing Technology Portfolio Expansion | Efficiency ratings above 90% satisfy carbon accounting requirements in Dutch and Danish operations. |
Research Methodology
Operator-level perspectives from livestock facility managers, greenhouse operations directors, agricultural cooperative procurement leads, and EPA compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from USDA conservation program databases, EPA New Source Performance Standards filings, and equipment shipment records from agricultural supply cooperatives. Bottom-up installation tracking across Midwest farm belt counties triangulated against top-down manufacturer revenue analysis.
Sensitivity analysis tested demand elasticity under utility rate volatility scenarios and regulatory acceleration cases across the projection horizon. Segmentation dimensions modeled include heater product type, combustion technology architecture, agricultural application, and end-user scale tier. CAGRs derived from replacement cycle analysis, heated acreage expansion rates, and livestock confinement capacity additions. Industry-specific inputs incorporated USDA cost-share program participation rates and state-level carbon pricing proposal tracking.
Forecasts assume regulatory continuity in EPA New Source Performance Standards and EU Ecodesign Directive regimes; material policy shifts would require re-modeling. Specific risk factors include commodity steel and aluminum price spikes, multi-jurisdiction certification timeline extensions, and electric utility rate restructuring that alters operating cost parity calculations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Agricultural Tractor Market