
 UAE Ophthalmic Devices Market | 2026-2036
UAE Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Ophthalmic Devices Market Analytics
The hospital procurement channel is narrowing as UAE health authorities consolidate purchasing through centralized tenders. Alcon Inc. leverages its cataract surgery portfolio to sustain dominant placement in Ministry of Health contracts. Carl Zeiss Meditec AG competes through diagnostic imaging platforms that anchor premium positioning in private eye care centers. Johnson & Johnson Vision Care differentiates via disposable surgical consumables that reduce infection control burdens for hospital buyers.
Ophthalmic devices encompass instruments, implants, and diagnostic systems engineered for vision correction, disease detection, and surgical intervention, with intraocular lenses typically manufactured from hydrophobic or hydrophilic acrylic materials featuring square-edge designs to inhibit posterior capsule opacification. These devices serve the primary commercial purpose of restoring or preserving visual function across clinical settings. Diagnostic equipment leads product type revenue as optical coherence tomography systems command replacement cycles tied to software upgrade pathways, while laser technologies within the technology segment capture margin pools from refractive surgery demand among younger demographics seeking spectacle independence. Vision care products represent a mature, high-volume category where distribution economics favor scale operators.
The UAE Ministry of Health and Prevention regulates medical device registration through its Drug Registration and Control Department, requiring conformity with recognized international standards for market authorization. MOHAP's framework shapes demand by mandating clinical evidence packages that filter out lower-tier suppliers and elevate product quality thresholds for ophthalmic implants. The Emirates Authority for Standardization and Metrology (ESMA) administers UAE-specific labeling and post-market surveillance protocols that extend compliance obligations across the product lifecycle. Stakeholders must monitor how MOHAP's anticipated alignment with EU Medical Device Regulation technical documentation requirements will reshape supplier qualification timelines and competitive access.
Market Dynamics
Centralized procurement consolidation by UAE health authorities is compressing vendor margins while elevating technical compliance thresholds for ophthalmic device suppliers seeking Ministry of Health contracts.
Growth Catalysts
- Diabetes Prevalence:The Emirates' elevated diabetic population generates sustained procedural volume for cataract and retinal interventions across Dubai and Abu Dhabi hospital networks.
- MOHAP Registration Standards:Tightened conformity requirements for intraocular lenses filter out lower-tier competitors and elevate average selling prices for qualified suppliers.
- Medical Tourism Infrastructure:Private hospital chains in Dubai Healthcare City and Abu Dhabi are expanding dedicated ophthalmology wings to capture regional patient flows from Gulf Cooperation Council states.
Market Restraints
- Import Dependency:The UAE lacks domestic manufacturing capacity for premium intraocular lenses and optical coherence tomography systems, exposing buyers to currency fluctuation and shipping disruption risks.
- MOHAP Documentation Burden:Clinical evidence packages required for device registration extend qualification timelines and freeze smaller European and Asian suppliers from tender participation.
- Acrylic Material Cost Volatility:Hydrophobic and hydrophilic acrylic feedstock prices track petrochemical indices, compressing gross margins for implant manufacturers serving the Emirates.
Strategic Opportunities
- Northern Emirates Penetration:Ras Al Khaimah and Fujairah present underdeveloped ophthalmology infrastructure with government hospital modernization programs creating first-mover access.
- Tele-ophthalmology Integration:Remote diagnostic platforms combining artificial intelligence screening with cloud-based image transmission address specialist scarcity in peripheral Emirates.
- ESMA Harmonization Pathways:Anticipated alignment between Emirates Authority for Standardization and Metrology protocols and EU Medical Device Regulation technical documentation will accelerate multi-market registration for prepared suppliers.
Industry Challenges
- Corneal Specialist Scarcity:The UAE faces acute shortages of fellowship-trained corneal surgeons capable of performing advanced lamellar transplantation procedures, limiting adoption of premium endothelial keratoplasty devices.
- Legacy Equipment Integration:Private eye centers in Dubai operate mixed fleets of diagnostic platforms spanning multiple generations, complicating software interoperability and maintenance contract standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Ophthalmic Devices Market |
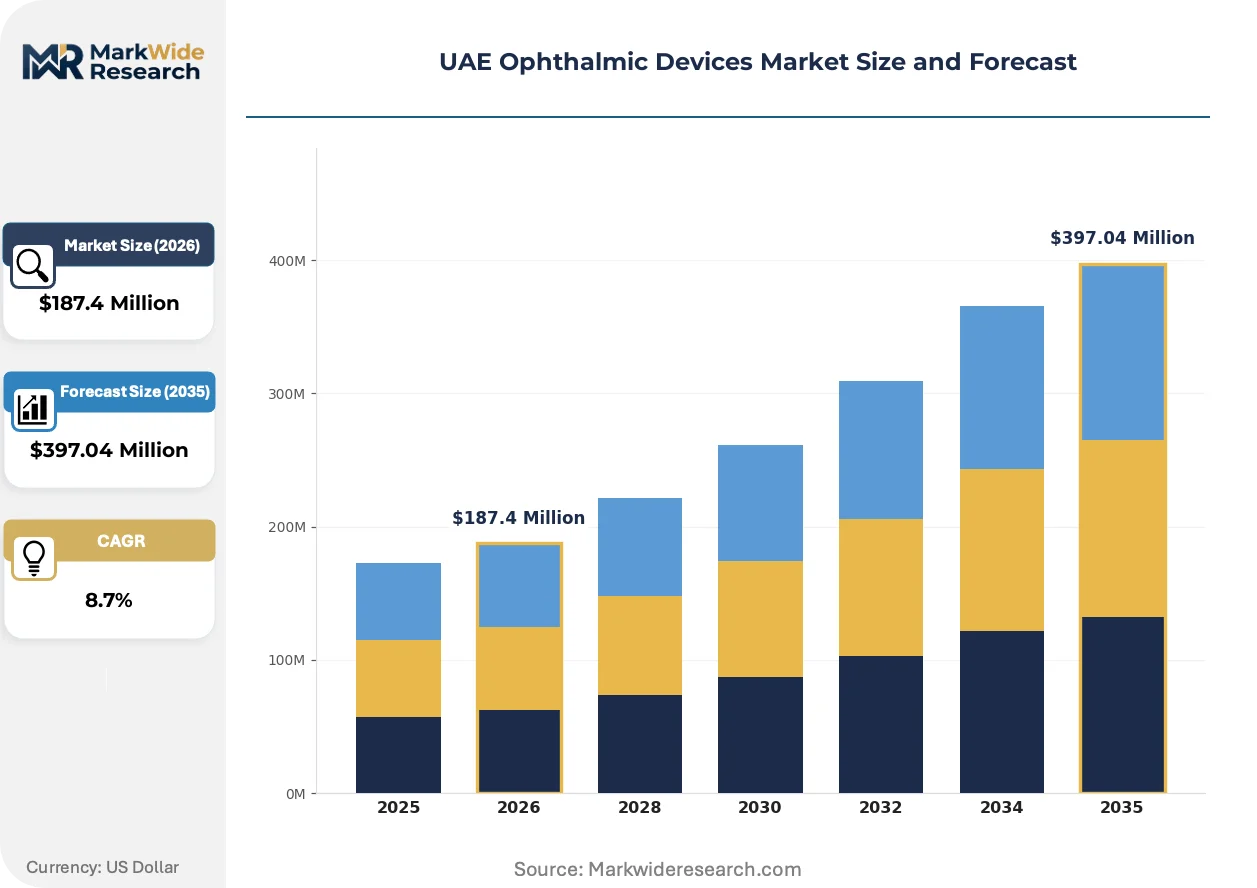
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Diagnostic Equipment, Surgical Instruments, Vision Care Products End User: Hospitals, Clinics, Eye Care Centers, Research Institutes Technology: Laser Technologies, Optical Coherence Tomography, Phacoemulsification, Retinal Imaging Application: Cataract Surgery, Refractive Surgery, Glaucoma Treatment, Retinal Disorders |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, EssilorLuxottica SA, Johnson & Johnson Vision Care, Bausch + Lomb Corporation, Topcon, Nidek, HOYA, HAAG-Streit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Ophthalmic Devices Market Evolving Landscape
Digital diagnostic workflows and regulatory convergence are restructuring how ophthalmic devices reach clinical deployment in the Emirates, with software-defined capabilities displacing hardware-centric purchasing criteria.
Femtosecond laser platforms for cataract surgery are migrating from premium-tier private hospitals in Dubai toward mid-tier facilities in Sharjah and Ajman as equipment financing models and refurbished device channels expand access. Adoption velocity accelerates among surgeon-owners seeking differentiation from Ministry of Health facilities. This technology migration is compressing conventional phacoemulsification equipment replacement cycles and fragmenting vendor service revenue streams across installation bases.
MOHAP's anticipated technical documentation alignment with EU Medical Device Regulation requirements is elevating clinical evidence thresholds for intraocular lens registration. Suppliers must now submit post-market surveillance data and biocompatibility testing protocols that exceed prior UAE-specific standards. Premium hydrophobic acrylic lens portfolios face compressed approval timelines relative to economy-tier competitors lacking European notified body certifications.
Hospital procurement departments in Abu Dhabi are unbundling diagnostic equipment purchases from mandatory multi-year service contracts, a pattern spreading to Dubai's private hospital groups. Buyers now negotiate software subscription tiers and remote technical support separately from capital hardware acquisition. This disaggregation is most visible among optical coherence tomography system purchases, where replacement decisions increasingly hinge on upgrade pathway pricing rather than initial capital expenditure.
UAE Ophthalmic Devices Market Segmentation
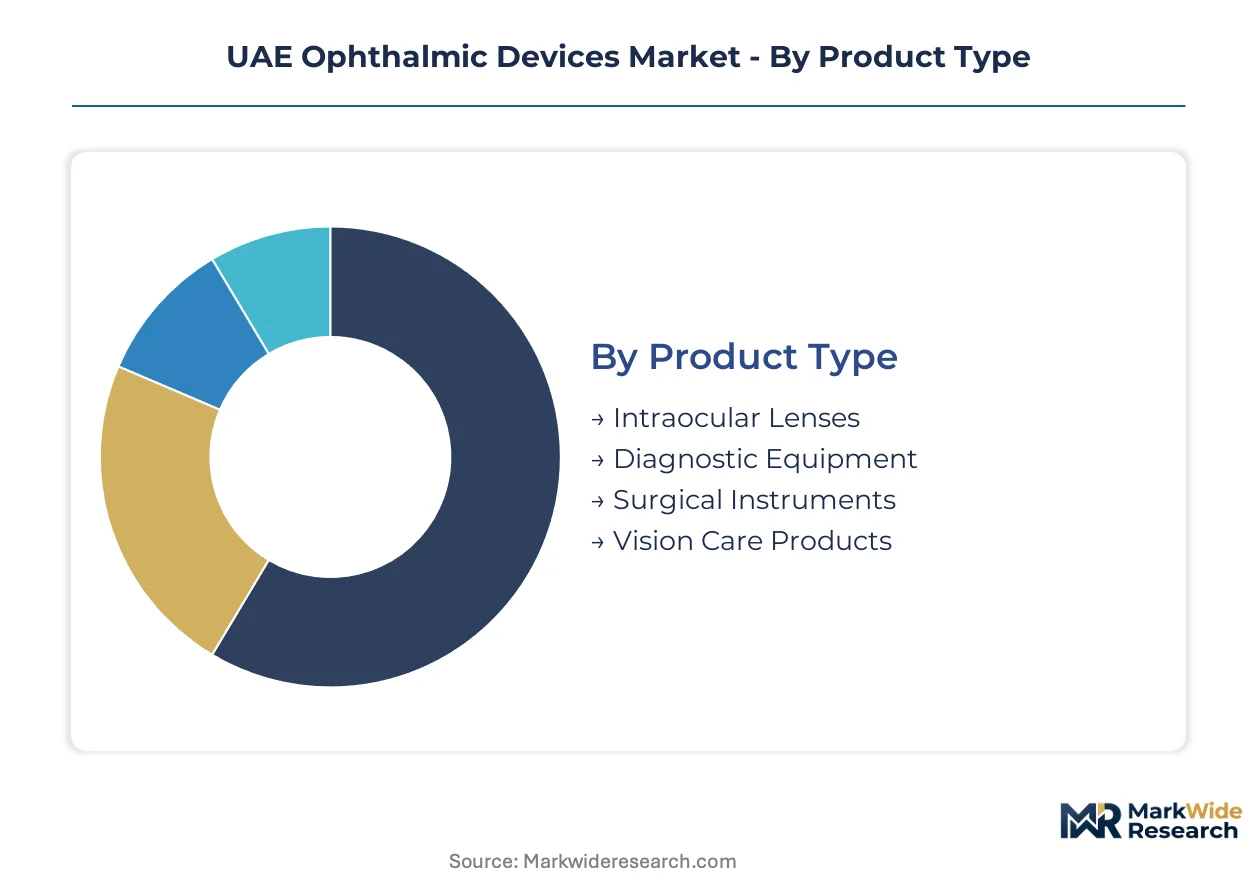
Segmentation reveals how procurement consolidation and technology migration reshape competitive positioning across the Emirates. Understanding category boundaries clarifies where suppliers must adapt compliance strategies versus where volume concentration offers scale advantages.
Product Type:
Mature categories dominate revenue concentration while emerging segments reshape margin structures.
- Intraocular Lenses:Hydrophobic and hydrophilic acrylic implants with square-edge geometries inhibit posterior capsule opacification. Dubai's private hospital chains drive demand for premium multifocal designs as medical tourism patients seek spectacle independence post-cataract surgery.
- Diagnostic Equipment:Optical coherence tomography systems and fundus cameras anchor capital expenditure cycles. Abu Dhabi's Ministry of Health facilities prioritize replacement decisions based on software upgrade pathway pricing rather than hardware acquisition costs alone.
- Surgical Instruments:Phacoemulsification handpieces and femtosecond laser interfaces constitute reusable and disposable toolsets.
- Vision Care Products:Contact lenses and lens care solutions represent high-volume, low-margin distribution economics.
Diagnostic Equipment retains volume leadership; Intraocular Lenses holds the steepest expansion curve.
End User:
Customer concentration varies sharply between centralized procurement channels and fragmented private practice networks.
- Hospitals:Ministry of Health facilities and private chains in Dubai Healthcare City execute bulk tenders for implant and equipment portfolios. Centralized purchasing compresses vendor margins while elevating technical documentation requirements for contract eligibility.
- Eye Care Centers:Specialized private clinics in Jumeirah and Al Ain pursue premium positioning through diagnostic imaging investments. These facilities drive adoption of femtosecond laser platforms as surgeon-owners seek differentiation from public sector competitors.
- Clinics:General medical practices with ophthalmology departments serve routine screening and referral functions.
- Research Institutes:Academic medical centers in Abu Dhabi and Dubai support clinical trial infrastructure for device registration.
Hospitals command procurement volume concentration; Eye Care Centers generate the fastest technology upgrade cycles.
Technology:
Cost tier stratification separates capital-intensive platforms from procedure-linked consumable systems.
- Optical Coherence Tomography:Non-invasive cross-sectional imaging systems dominate diagnostic capital budgets. Replacement demand concentrates in Dubai's private centers where software-defined capabilities displace hardware-centric purchasing criteria.
- Laser Technologies:Femtosecond and excimer platforms serve refractive and cataract surgical applications. Equipment financing models and refurbished channels are expanding access from premium Dubai facilities toward mid-tier Sharjah and Ajman hospitals.
- Phacoemulsification:Ultrasound-based cataract extraction systems represent mature installed bases requiring consumable replenishment.
- Retinal Imaging:Wide-field fundus photography and angiography systems address diabetic retinopathy screening demand.
Optical Coherence Tomography anchors diagnostic spending; Laser Technologies are climbing the fastest as financing democratizes access.
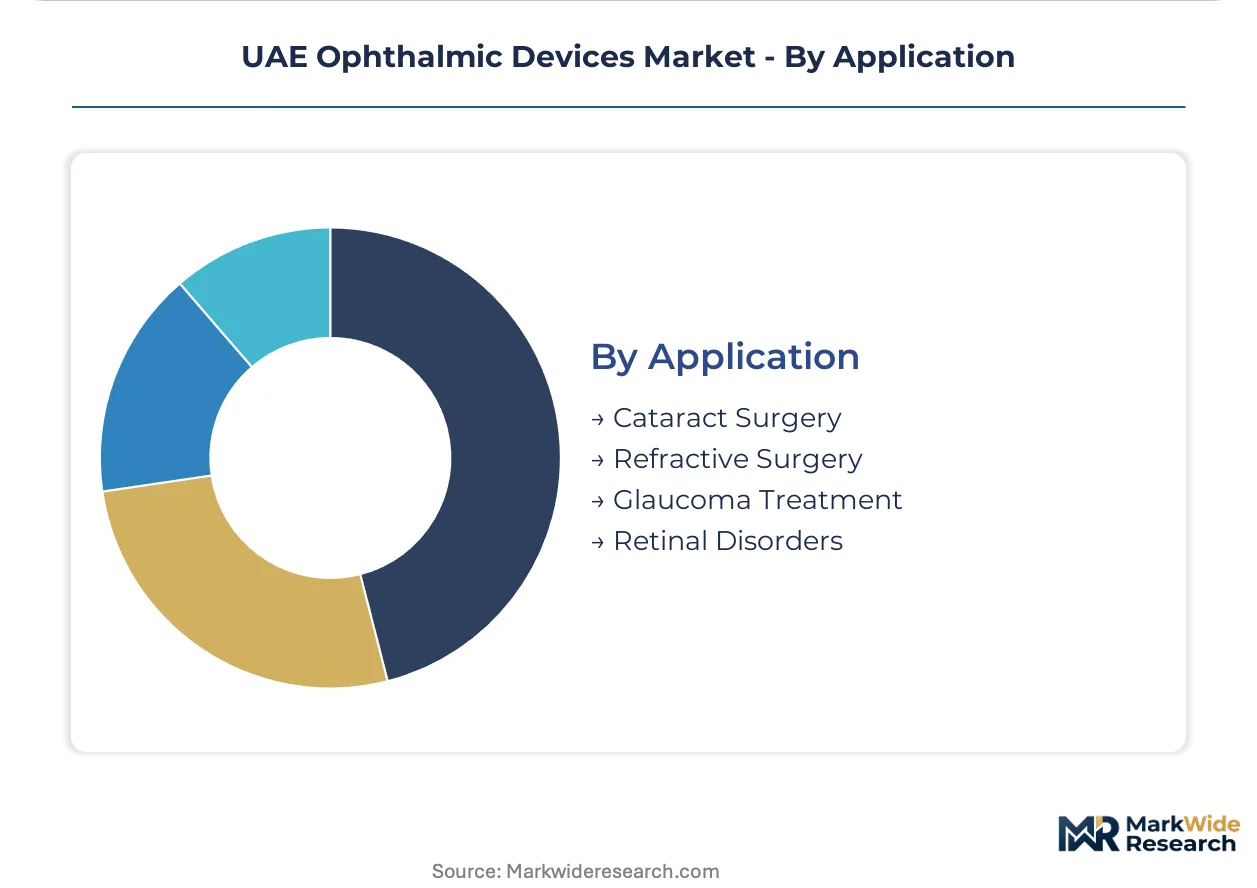
Application:
Procedure volume distribution reflects demographic disease burden and medical tourism targeting.
- Cataract Surgery:The Emirates' aging population and elevated diabetes prevalence sustain procedural volume across all emirates. MOHAP's tightened intraocular lens registration standards filter supplier pools and elevate average selling prices for qualified entrants.
- Refractive Surgery:LASIK and SMILE procedures attract GCC medical tourism flows to Dubai's private centers. Younger demographics seeking spectacle independence drive femtosecond laser platform utilization rates.
- Glaucoma Treatment:Minimally invasive surgical devices and drainage implants address progressive optic nerve pathology.
- Retinal Disorders:Diabetic macular edema and age-related macular degeneration interventions utilize intravitreal injection and laser photocoagulation systems.
Cataract Surgery retains procedural volume leadership; Refractive Surgery holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's pharmaceutical and medical device free zone infrastructure underwrites Dubai's distribution dominance across Gulf ophthalmic supply chains. Khalifa Port's adjacent KIZAD industrial zone anchors Abu Dhabi's procurement consolidation for Northern Emirates feeder markets.
Dubai
Dubai Healthcare City and Dubai Silicon Oasis concentrate private hospital chains expanding dedicated ophthalmology wings for GCC medical tourism flows. MOHAP's Drug Registration and Control Department operates its primary device approval hub here, filtering supplier pools through tightened intraocular lens conformity requirements. Jumeirah and Al Barsha districts host premium eye care centers driving femtosecond laser platform adoption.
Abu Dhabi
Sheikh Khalifa Medical City and Cleveland Clinic Abu Dhabi anchor Ministry of Health procurement consolidation for cataract surgery volume. The Department of Health Abu Dhabi mandates clinical evidence packages that exceed prior federal standards, accelerating multi-hospital tender standardization. Yas Island and Al Maryah Island clusters concentrate diagnostic imaging investments tied to software upgrade pathway negotiations.
Sharjah
University Hospital Sharjah and private chains in Al Nahda district are capturing femtosecond laser platform migration from premium Dubai facilities through equipment financing models. The Sharjah Health Authority's alignment with federal MOHAP standards streamlines device registration for mid-tier hospital buyers. Industrial zones near Sharjah International Airport support refurbished device channel distribution to Ajman and Umm Al Quwain.
Northern Emirates
Ras Al Khaimah's Saqr Hospital and Fujairah's Dibba Hospital modernization programs create first-mover access for suppliers addressing underdeveloped ophthalmology infrastructure. Federal Ministry of Health procurement budgets for these emirates remain fragmented relative to Dubai-Abu Dhabi centralization. Tele-ophthalmology platforms combining AI screening with cloud transmission address specialist scarcity in these peripheral markets.
UAE Ophthalmic Devices Market Competitive Landscape
On the supply side, the industry is consolidating around multinational ophthalmic portfolios capable of satisfying MOHAP's elevated technical documentation requirements. Three archetypes dominate: diversified surgical implant manufacturers with cataract surgery breadth, specialized diagnostic imaging platform vendors, and disposable consumables suppliers reducing infection control burdens. Competitive moves concentrate on Ministry of Health contract defense through localized regulatory affairs teams and diagnostic equipment purchase unbundling from service contracts.
Within the diversified surgical implant tier, Alcon Inc. and Johnson & Johnson Vision Care exemplify multinational scale advantages in centralized UAE tender participation. Carl Zeiss Meditec AG occupies a distinct position among diagnostic imaging specialists leveraging European notified body certifications to compress MOHAP approval timelines. These three entities anchor the competitive structure through differentiated compliance capabilities and procurement channel access.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| EssilorLuxottica SA |
| Johnson & Johnson Vision Care |
| Bausch + Lomb Corporation |
| Topcon |
| Nidek |
| HOYA |
| HAAG-Streit |
| Others |
Value Network & Pricing Analysis
Jebel Ali Port's pharmaceutical free zone freight corridors concentrate ophthalmic device import volumes, compressing logistics costs for Dubai-based distributors while amplifying price differentiation between Ministry of Health tender winners and peripheral market suppliers. This corridor dynamic concentrates procurement power among hospital chains that leverage volume scale against vendors, while smaller eye care centers in Northern Emirates absorb elevated landed costs that stratify end-user pricing tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates intraocular lens procurement, with hydrophobic acrylic multifocal designs commanding certification-grade premiums from Dubai's medical tourism hospitals. Price differentiation hinges on MOHAP registration status and software upgrade bundling for diagnostic platforms. Cost compression in economy-tier phacoemulsification consumables is intensifying because Sharjah's mid-tier hospitals negotiate unbundled service contracts. Ministry of Health facilities exhibit lowest price sensitivity due to centralized tender volumes, while independent eye care centers in Ras Al Khaimah face acute budget constraints.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Jebel Ali distributors enable smaller UAE hospitals to acquire femtosecond laser platforms without upfront capital outlay. Manufacturing concentration rests on Germany, Switzerland, and the USA for premium diagnostic imaging systems, while hydrophobic acrylic feedstock draws from petrochemical suppliers in Saudi Arabia and Singapore. Single-source vulnerability permeates optical coherence tomography component supply, with specialized optical sensors manufactured exclusively in Japan. Distribution runs through Dubai Healthcare City warehousing hubs that serve Northern Emirates via Sharjah International Airport feeder routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE ophthalmic devices market exhibits cyclical recovery characteristics as deferred cataract surgery volumes from regional healthcare disruptions return to procedural baselines. Medical tourism infrastructure investments in Dubai Healthcare City and Abu Dhabi anchor this cyclical rebound through sustained GCC patient inflows.
For Market Incumbents: Pre-empt margin erosion in phacoemulsification consumables by securing backward integration into hydrophobic acrylic polymer supply through Saudi petrochemical partnerships. Alcon and Johnson & Johnson Vision Care must defend Ministry of Health contract positioning against emerging Asian suppliers by accelerating MOHAP registration dossiers ahead of EU MDR alignment deadlines. Diagnostic imaging incumbents should unbundle software subscription tiers from hardware sales to match Abu Dhabi procurement department negotiation patterns.
For New Entrants and Emerging Players: Northern Emirates government hospital modernization programs represent the most penetrable entry point for qualified intraocular lens suppliers lacking Dubai-Abu Dhabi contract history. Tele-ophthalmology diagnostic platforms targeting Ras Al Khaimah and Fujairah specialist scarcity offer white-space access without competing against entrenched capital equipment vendors. A go-to-market angle emphasizing AI-enabled remote screening compliance with MOHAP data sovereignty requirements differentiates from legacy device distributors.
For Investors and Strategic Acquirers: European diagnostic imaging specialists holding notified body certifications under EU MDR command acquisition premium potential as MOHAP technical documentation alignment accelerates their UAE market access timelines. Long-term viability in this market rests on regulatory affairs capabilities that compress multi-market registration cycles. The signal to watch is MOHAP's publication of harmonized technical documentation requirements, which would trigger accelerated consolidation among suppliers lacking European certification pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Dossier Enhancement | Accelerated approval timelines filter competitor pools for intraocular lens tenders. |
| Software Subscription Unbundling | Abu Dhabi procurement departments now negotiate OCT upgrades separately from hardware. |
| Tele-ophthalmology Platform Launch | AI screening addresses specialist scarcity in Ras Al Khaimah and Fujairah markets. |
| EU MDR Certification Pathway Investment | Notified body approvals compress MOHAP technical documentation review periods. |
| Refurbished Device Channel Development | Sharjah financing models democratize femtosecond laser access from mid-tier hospitals. |
Research Methodology
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings on MOHAP registration pathway evolution. Primary interviews with biomedical engineers, GPO contracts managers, ophthalmology department heads, and medical device regulatory affairs specialists informed tender participation barriers and technology adoption timelines. Secondary sources encompassed MOHAP Drug Registration and Control Department guidance documents, ESMA labeling protocols, EU MDR technical documentation frameworks, and hospital capital expenditure disclosures. Bottom-up procedural volume estimates and top-down market sizing triangulated across these input streams.
Calibration against historical replacement cycles for optical coherence tomography systems and intraocular lens implant volumes shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, end-user channel, technology tier, and application procedure category. CAGRs derived from installed base growth rates, software upgrade pathway pricing elasticity, and medical tourism patient flow projections. Forecast inputs incorporated diabetes prevalence trajectories, cataract surgery age-adjusted incidence rates, and femtosecond laser financing penetration assumptions.
Practitioners should monitor MOHAP technical documentation alignment announcements and EU MDR implementation pace for early signals of competitive access restructuring. Forecasts reflect assumptions on procurement centralization continuity, acrylic feedstock price stability, and GCC medical tourism policy support. Macroeconomic currency fluctuation, regulatory restriction tightening, or tele-ophthalmology reimbursement exclusion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Macular Edema Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market