
 Hemorrhagic Stroke Treatment Market | 2026-2036
Hemorrhagic Stroke Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemorrhagic Stroke Treatment Market Analysis
Minimally invasive intervention standards is bifurcating the competitive landscape between premium catheter-based platforms and conventional surgical portfolios. Medtronic leverages its integrated neurovascular pipeline to dominate endovascular hemorrhage control across North American stroke centers. Penumbra, Inc. specializes in aspiration thrombectomy and hemorrhage access systems, anchoring its position in high-volume comprehensive stroke centers. Stryker competes through sustained R&D intensity in stent retriever and flow diversion technologies for complex aneurysm presentations.
Hemorrhagic stroke treatment encompasses acute interventions to arrest bleeding, reduce intracranial pressure, and prevent rebleeding in subarachnoid and intracerebral hemorrhage, typically involving catheter-delivered embolic agents, surgical clip application, or ventricular drainage with target blood pressure control below 140 mmHg systolic. The primary purpose is mortality reduction and functional outcome preservation through rapid hemorrhage source control. Clot management devices and neurovascular stents command the deepest margin pools as hospitals prioritize catheter-based intervention capacity over conservative medical management. Endovascular therapy as a delivery mode is displacing open surgical approaches in eligible aneurysm presentations, while rehabilitation centers represent the fastest-growing end user segment as payers mandate post-acute functional recovery metrics.
FDA breakthrough device pathways and Japan's PMDA Sakigake designation compress regulatory timelines for novel neurointerventional platforms, directly shaping R&D allocation and clinical trial geography. EU MDR requirements for neurovascular implantables are elevating post-market surveillance costs, favoring manufacturers with established quality management systems. Stakeholders must monitor reimbursement divergence between endovascular and surgical intervention codes as health technology assessment bodies in Germany, France, and the United States recalibrate episode-based payment models.
Market Dynamics
Endovascular therapy is displacing open surgical intervention as the default protocol for eligible aneurysm presentations, compressing hospital infrastructure requirements and redistributing margin pools toward catheter-based platform manufacturers. This structural shift concentrates purchasing power within comprehensive stroke centers capable of maintaining 24/7 neurointerventional coverage.
Growth Catalysts
- FDA breakthrough device designation:The pathway accelerates commercialization timelines for novel neurointerventional platforms, compressing the gap between clinical validation and hospital procurement in tertiary stroke centers across the United States.
- Japan's PMDA Sakigake fast-track:This regulatory framework reduces review periods for hemorrhage access systems, enabling earlier revenue recognition for manufacturers targeting the Asia-Pacific's aging stroke population.
- Comprehensive stroke center certification:State-level mandates for 24/7 neurointerventional coverage drive capital allocation toward endovascular suites, creating installed base expansion for catheter-delivered embolic agents.
Market Restraints
- Platinum coil input volatility:Price fluctuations in this critical raw material for embolic devices compress gross margins for manufacturers without long-term supply agreements.
- EU MDR post-market surveillance:Elevated clinical follow-up requirements for neurovascular implantables increase compliance costs, favoring established quality management systems over emerging entrants.
- Conservative medical management:Blood pressure control protocols below 140 mmHg systolic remain the default in resource-constrained settings, limiting addressable patient populations for interventional devices.
Strategic Opportunities
- Rehabilitation center channel expansion:Post-acute functional recovery mandates from United States payers create procurement pull for hemorrhage monitoring devices outside traditional hospital settings.
- Germany episode-based payment recalibration:Health technology assessment body reconfiguration of intervention reimbursement codes may elevate endovascular procedure economics relative to surgical alternatives.
- Flow diversion and aspiration convergence:Integration of stent retriever technology with hemorrhage access systems enables single-platform treatment of complex aneurysm presentations.
Industry Challenges
- Neurointerventionalist workforce scarcity:Fellowship-trained specialists capable of 24/7 hemorrhage intervention coverage remain concentrated in urban academic medical centers, limiting protocol standardization.
- EU MDR technical documentation:Extended conformity assessment timelines for novel neurovascular implantables delay product launches and compress competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemorrhagic Stroke Treatment Market |
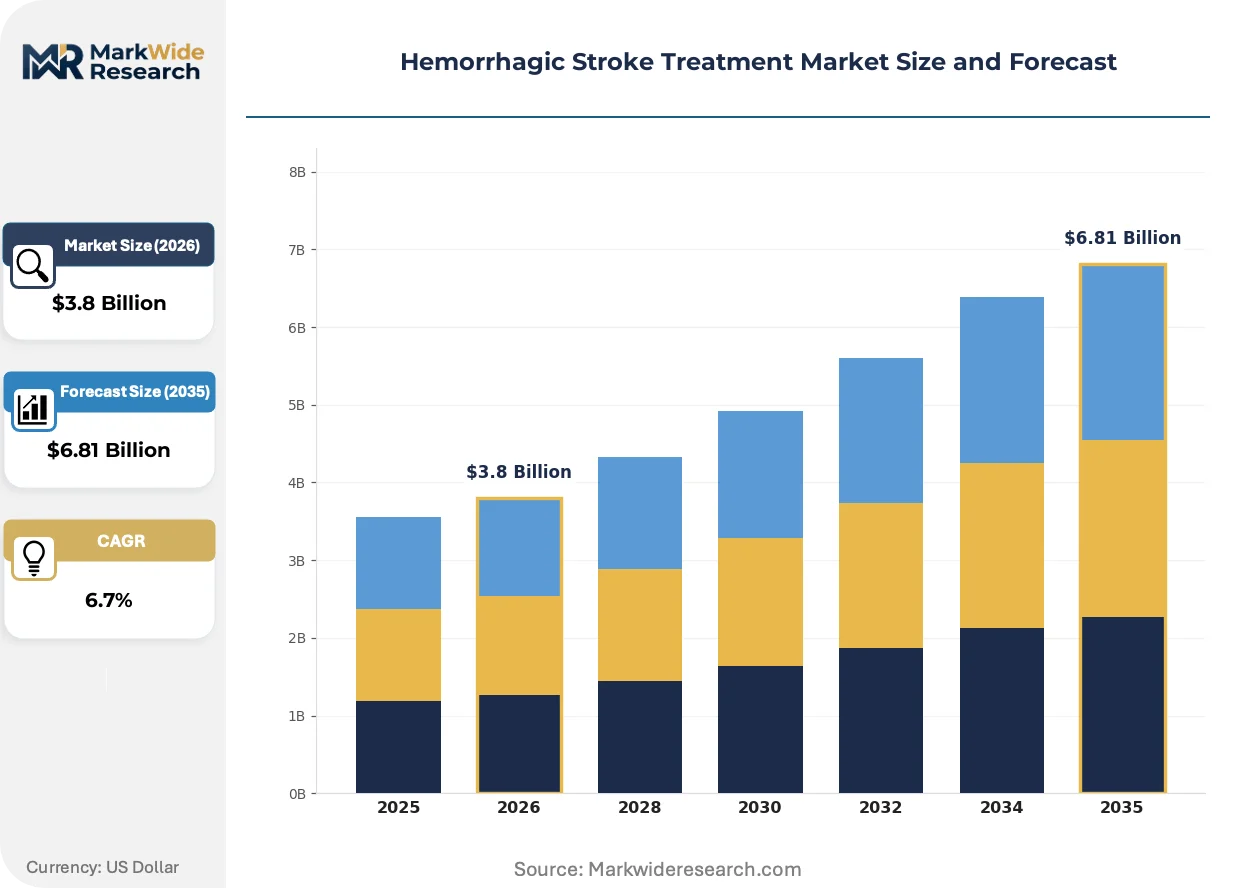
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clot Management Devices, Surgical Instruments, Neurovascular Stents, Hemostatic Agents Delivery Mode: Intravenous Administration, Intra-arterial Administration, Oral Administration, Endovascular Therapy End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers, Neurology Clinics Treatment Strategy: Medical Management, Surgical Intervention, Conservative Care, Follow-up Monitoring |
| Companies Covered | Medtronic, B. Braun Melsungen AG, Novartis AG, Pfizer Inc, Abbott, Penumbra, Inc., Stryker, Boston Scientific Corporation, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemorrhagic Stroke Treatment Market Emerging Trajectories
Catheter-based hemorrhage control is reshaping competitive positioning across the neurovascular intervention landscape, with technology convergence and regulatory acceleration compressing traditional development cycles. Three distinct forces are restructuring how treatments reach eligible patients.
Mechanical thrombectomy platforms with integrated aspiration capability are displacing standalone coil embolization systems in high-volume comprehensive stroke centers. Tertiary hospitals in the United States and Germany are prioritizing dual-function devices that address both ischemic and hemorrhagic presentations within single catheter lab investments. This convergence is displacing single-purpose inventory and forcing manufacturers to consolidate R&D spending toward multifunctional platforms.
Japan's PMDA Sakigake designation is compressing regulatory timelines for hemorrhage access innovations, enabling earlier commercialization in the Asia-Pacific's most lucrative neurovascular market. The framework's priority review status reduces pre-market approval periods, accelerating revenue recognition for breakthrough device submissions. European manufacturers are responding by front-loading clinical trial geography toward Japanese sites to capture this regulatory tailwind.
Episode-based reimbursement models in Germany and France are elevating post-acute functional outcome metrics above procedural volume in purchasing decisions. Hospital procurement committees now weight rehabilitation cost avoidance more heavily than device acquisition price, favoring technologies with demonstrated disability reduction. This behavioral shift is most visible in French university hospital systems, where bundled payment pilots have already reconfigured supplier evaluation criteria.
Hemorrhagic Stroke Treatment Market Segmentation
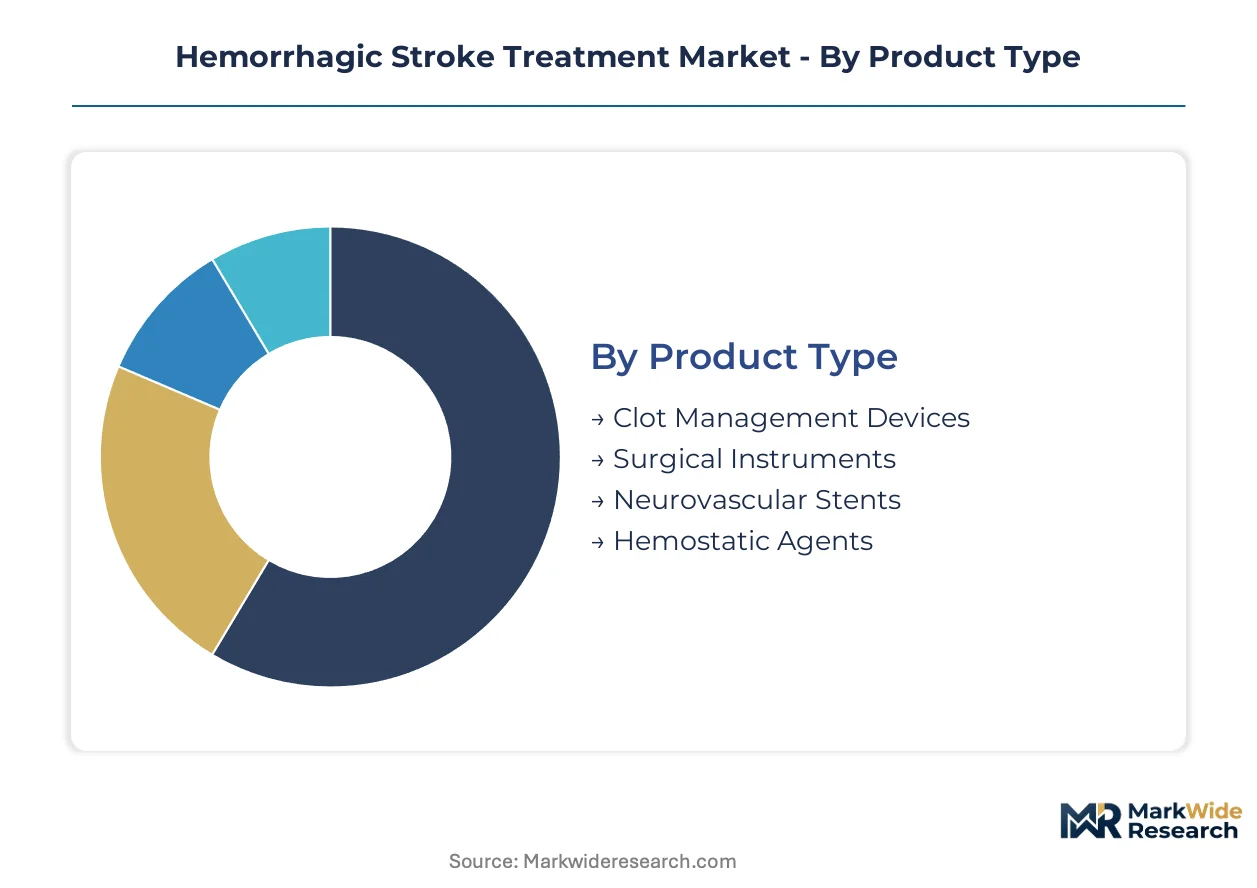
Segmentation in hemorrhagic stroke treatment reveals how regulatory pathways and reimbursement structures fragment purchasing decisions across acute and post-acute settings. Product classification directly determines FDA breakthrough eligibility and EU MDR conformity assessment timelines.
Product Type:
FDA breakthrough device pathways apply differentially across implantable versus non-implantable categories, compressing commercialization timelines for catheter-delivered platforms while extending scrutiny for permanent implants.
- Clot Management Devices:Aspiration thrombectomy systems and suction catheters designed for intracranial hemorrhage evacuation. Demand concentrates in United States comprehensive stroke centers where 24/7 neurointerventional coverage mandates dual-function platforms addressing both ischemic and hemorrhagic presentations.
- Surgical Instruments:Craniotomy kits, aneurysm clips, and ventricular drainage systems for open hemorrhage control. Adoption is contracting in Germany and Japan as endovascular protocols displace open surgical approaches in eligible aneurysm presentations.
- Neurovascular Stents:Flow diverters and intracranial stent systems for complex aneurysm reconstruction.
- Hemostatic Agents:Topical and injectable agents for surgical field bleeding control.
Established volume favors Clot Management Devices; emerging adoption favors Neurovascular Stents.
Delivery Mode:
Cost tier differentiation separates capital-intensive catheter lab procedures from pharmaceutical administration, with reimbursement codes increasingly bundling device and procedure costs.
- Endovascular Therapy:Catheter-delivered embolization, coiling, and flow diversion performed in angiography suites. Tertiary stroke centers in the United States and Japan are prioritizing this delivery mode as default protocol for eligible aneurysm presentations, displacing open surgical alternatives.
- Intra-arterial Administration:Targeted drug delivery via femoral or radial artery access for thrombolysis or vasospasm management. Concentrated in high-volume academic medical centers with interventional neuroradiology fellowship programs.
- Intravenous Administration:Systemic blood pressure control and coagulation management.
- Oral Administration:Antihypertensive and anticoagulation reversal protocols.
Procedure economics favor Endovascular Therapy; access expansion favors Intravenous Administration.
End User:
Customer type segmentation tracks the post-acute migration of hemorrhage monitoring and functional recovery services outside traditional hospital settings.
- Rehabilitation Centers:Post-acute facilities delivering hemorrhage recovery protocols and disability reduction programs. United States payers are mandating functional outcome metrics that elevate procurement pull for hemorrhage monitoring devices in this channel, creating the steepest expansion trajectory across end user categories.
- Hospitals:Comprehensive stroke centers and academic medical centers with 24/7 neurointerventional coverage. Remain the dominant revenue channel for acute hemorrhage intervention devices, though share is shifting toward post-acute settings.
- Ambulatory Surgical Centers:Limited application for hemorrhagic stroke given acute care requirements.
- Neurology Clinics:Outpatient follow-up and secondary prevention services.
Acute revenue concentrates in Hospitals; growth velocity favors Rehabilitation Centers.
Treatment Strategy:
Maturity stratification separates established conservative protocols from emerging interventional standards, with health technology assessment bodies recalibrating episode-based payment models.
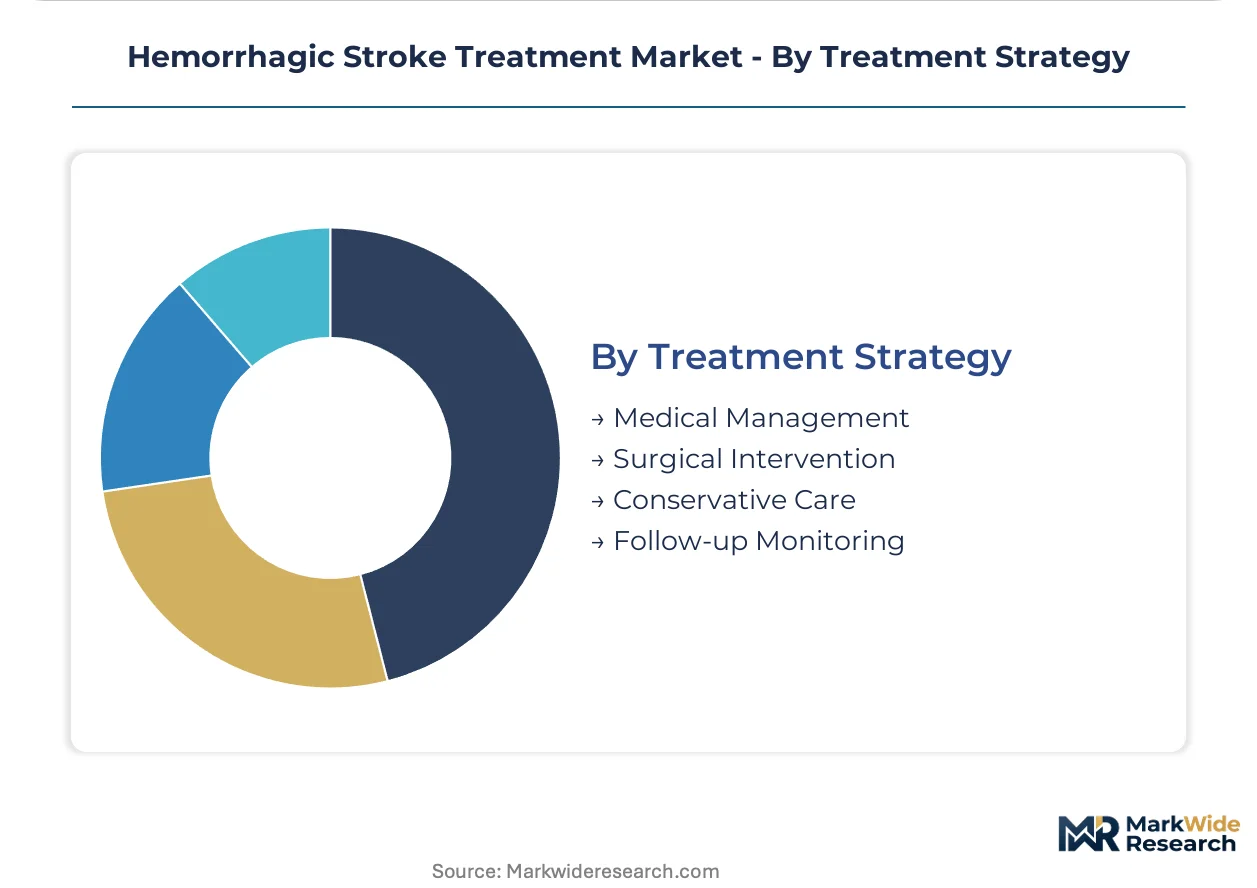
- Medical Management:Blood pressure control below 140 mmHg systolic, coagulation reversal, and intracranial pressure monitoring. Default protocol in resource-constrained settings and for patients ineligible for intervention, limiting addressable populations for device manufacturers.
- Surgical Intervention:Craniotomy, aneurysm clipping, and hematoma evacuation. Volume is contracting in France and Germany as endovascular alternatives capture eligible presentations.
- Conservative Care:Supportive management without active hemorrhage source control.
- Follow-up Monitoring:Surveillance imaging and secondary prevention protocols.
Current volume favors Medical Management; protocol evolution favors Surgical Intervention contraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for platinum coils and neurovascular catheters shapes procurement strategies across major markets, with specialized manufacturers in Germany and Japan serving as critical suppliers to stroke centers in the United States and France.
United States
FDA breakthrough device designations compress commercialization timelines for catheter-based hemorrhage control platforms. Comprehensive stroke center certification mandates in 46 states drive capital allocation toward 24/7 neurointerventional coverage. The Cleveland Clinic and Mayo Clinic stroke networks anchor demand concentration in the Midwest.
Germany
Episode-based reimbursement recalibration by the Institute for Quality and Efficiency in Health Care elevates post-acute functional outcomes in procurement decisions. EU MDR conformity assessment requirements extend launch timelines for novel neurovascular implantables. The Rhine-Ruhr metropolitan region hosts the densest concentration of certified comprehensive stroke centers in Europe.
Japan
PMDA Sakigake fast-track pathways reduce pre-market approval periods for hemorrhage access systems by 50%. An aging stroke population expands addressable patient volumes for endovascular interventions. Tokyo and Osaka academic medical centers serve as primary clinical trial sites for Asia-Pacific neurovascular device launches.
France
ANSM post-market surveillance requirements align with EU MDR clinical follow-up mandates for permanent implants. Bundled payment pilots in university hospital systems reconfigure supplier evaluation criteria toward disability reduction metrics. The Paris-Saclay cluster concentrates neurointerventional research capacity and tertiary referral volumes.
United Kingdom
NICE technology appraisals determine reimbursement eligibility for novel hemorrhage intervention devices within the National Health Service. NHS England stroke service specifications mandate hyperacute unit coverage within 30 minutes for 95% of the population. Greater Manchester and London stroke networks drive procurement standardization across integrated care systems.
Hemorrhagic Stroke Treatment Market Vendor Landscape
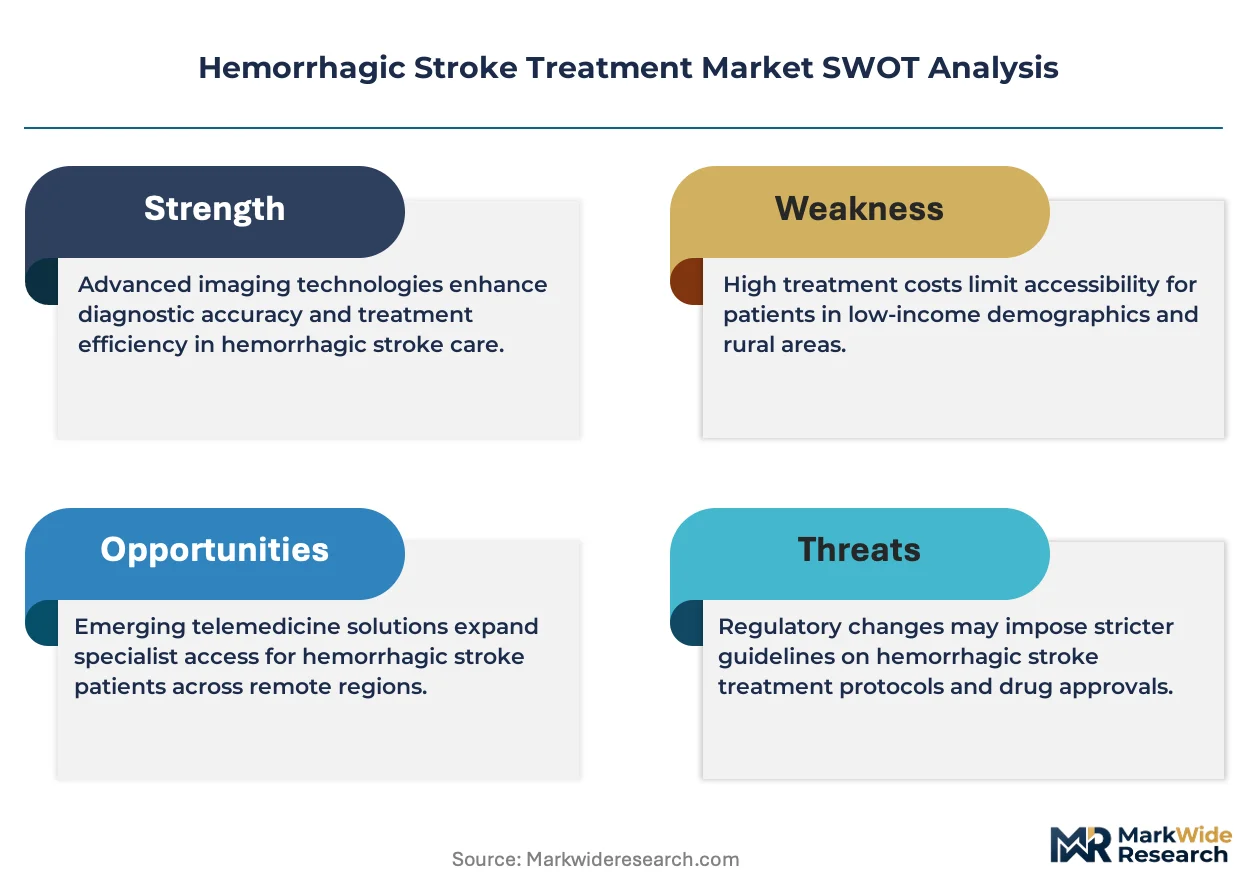
Listed leaders compete with private specialists across integrated neurovascular portfolios versus focused hemorrhage access platforms. Market structure concentrates around three tiers: diversified medical technology conglomerates with stroke care divisions, pure-play neurovascular device manufacturers, and pharmaceutical firms with hemostatic agent portfolios. Dominant competitive moves include regulatory pathway optimization for breakthrough device submissions and strategic partnerships with comprehensive stroke centers for clinical validation.
Within the diversified technology tier, Medtronic and Stryker occupy positions spanning catheter-based intervention and surgical hemorrhage control. Penumbra, Inc. exemplifies the pure-play neurovascular specialist archetype with focused aspiration and access system development. These three entities anchor competitive dynamics across tertiary stroke center procurement committees in the United States, Germany, and Japan.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| Novartis AG |
| Pfizer Inc |
| Abbott |
| Penumbra, Inc. |
| Stryker |
| Boston Scientific Corporation |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply Flow & Price Mechanics
Catheter lab utilization rates above 70 percent in United States comprehensive stroke centers create scale economies that compress per-procedure device costs while elevating minimum viable production volumes for manufacturers. This capacity concentration simultaneously hardens price floors for platinum coil-dependent embolic devices and forces supply chain rationalization toward single-source agreements with German and Japanese precision component suppliers.
Pricing Analysis
Hospital purchasing committees anchor catheter-delivered hemorrhage control pricing through three-tier structures across premium flow diverters, standard coil systems, and economy aspiration platforms. Price differentiation rests on FDA breakthrough designation status and 24/7 technical support bundling rather than raw device specifications alone. Cost compression in economy tiers is intensifying because Japanese PMDA fast-track entrants are undercutting established EU MDR-certified portfolios. Academic medical centers exhibit lowest price sensitivity due to episode-based reimbursement insulation, while community hospitals facing bundled payment pressure drive hardest bargain negotiations.
Supply Chain Analysis
Port congestion at Rotterdam and Yokohama elevates inbound logistics costs for platinum alloy coils and nitinol catheter components sourced from German precision metalworkers and Japanese shape-memory alloy specialists. Manufacturing concentration in Ireland, Switzerland, and Costa Rica for final device assembly creates single-source vulnerability during EU MDR technical documentation delays. Raw material dependencies center on South African platinum group metals, United States medical-grade polymers, and Chinese rare-earth processing for catheter sensor integration. Distribution runs through hospital GPO contracts with Cardinal Health and Medline rather than direct manufacturer sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device pathways and Japan's PMDA Sakigake designation are compressing commercialization timelines from validation to revenue, creating a regulatory arbitrage window that rewards fastest-moving platform developers.
For Market Incumbents: Shield installed base positions in United States comprehensive stroke centers by locking 24/7 service contracts before PMDA fast-track competitors achieve FDA parallel submissions. Prioritize backward integration into platinum coil supply through long-term offtake agreements with South African refiners, neutralizing raw material volatility that threatens gross margins. Counter emerging aspiration-convergence platforms by accelerating flow diverter software companion development for procedure outcome documentation. For New Entrants and Emerging Players: Japan's PMDA Sakigake fast-track offers the most penetrable regulatory pathway for hemorrhage access system launches, compressing pre-market approval periods relative to EU MDR timelines. Target rehabilitation center channel expansion in United States markets where payer functional outcome mandates create procurement pull outside traditional hospital settings. Lead go-to-market with disposable monitoring device subscriptions rather than capital equipment sales to bypass comprehensive stroke center certification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among catheter-delivered platform manufacturers with installed base service contracts spanning device replenishment and software updates. Five-to-ten year viability favors pure-play neurovascular specialists with PMDA Sakigake designations already secured over diversified conglomerates facing EU MDR compliance cost inflation. Monitor FDA breakthrough device designation announcements as inflection indicators for revenue acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses commercialization timelines for novel hemorrhage access platforms in tertiary stroke centers. |
| PMDA Sakigake Fast-Track Pursuit | Reduces review periods by 50 percent for Asia-Pacific market entry ahead of EU MDR competitors. |
| Comprehensive Stroke Center Partnership | Locks 24/7 neurointerventional coverage requirements into exclusive device procurement agreements. |
| Rehabilitation Center Channel Development | Captures post-acute functional recovery spending mandated by United States payer outcome metrics. |
| Platinum Coil Supply Integration | Neutralizes raw material volatility through captive offtake from South African refinery operations. |
Methodological Framework
Desk research of FDA 510(k) and PMA filings, PMDA approval databases, and hospital GPO contract disclosures preceded structured interviews with interventional neuroradiologists, comprehensive stroke center purchasing committee chairs, and neurovascular device regulatory affairs directors. Secondary validation drew from EU MDR technical documentation summaries, CMS Medicare procedure volume data, and Japanese Ministry of Health stroke registry statistics. Bottom-up device shipment estimates triangulated against top-down hospital capital expenditure surveys across the analysis window.
Variance decomposition across product type, delivery mode, end user, and treatment strategy segmentation dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from procedure volume elasticity models incorporating aging stroke population demographics and regulatory pathway acceleration effects. Industry-specific forecast inputs included comprehensive stroke center certification mandates by United States state and PMDA Sakigake designation success rates.
Decision-makers should treat outputs as directional under assumptions of sustained FDA breakthrough pathway utilization and stable platinum group metal pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions of gradual EU MDR timeline normalization and stable Japan PMDA staffing capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Eisenmenger Complex Management Market