
 Asia-Pacific Wearable Medical Devices Market | 2026-2036
Asia-Pacific Wearable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wearable Medical Devices Market Outlook
Remote patient monitoring revenue is rewriting profit distribution across the Asia-Pacific wearable medical devices landscape. Samsung Electronics leverages its semiconductor supply chain to control component costs for biosensor modules. Omron Corporation anchors its position through specialized blood pressure monitoring wearables with clinical-grade validation. Xiaomi competes aggressively on manufacturing scale, flooding entry-level fitness tracker segments across Southeast Asian retail channels.
Asia-Pacific wearable medical devices comprise sensor-embedded garments, wrist-worn units, and patch-based monitors that collect physiological data through photoplethysmography, accelerometry, or bioimpedance analysis for continuous health surveillance outside clinical settings. Smartwatches dominate current revenue pools due to multipurpose health tracking and consumer familiarity, while wearable ECG monitors represent the fastest-expanding category as cardiac outpatient programs proliferate across the region. Biosensor technology underpins margin concentration, with wireless connectivity and cloud computing layers becoming commoditized infrastructure elements.
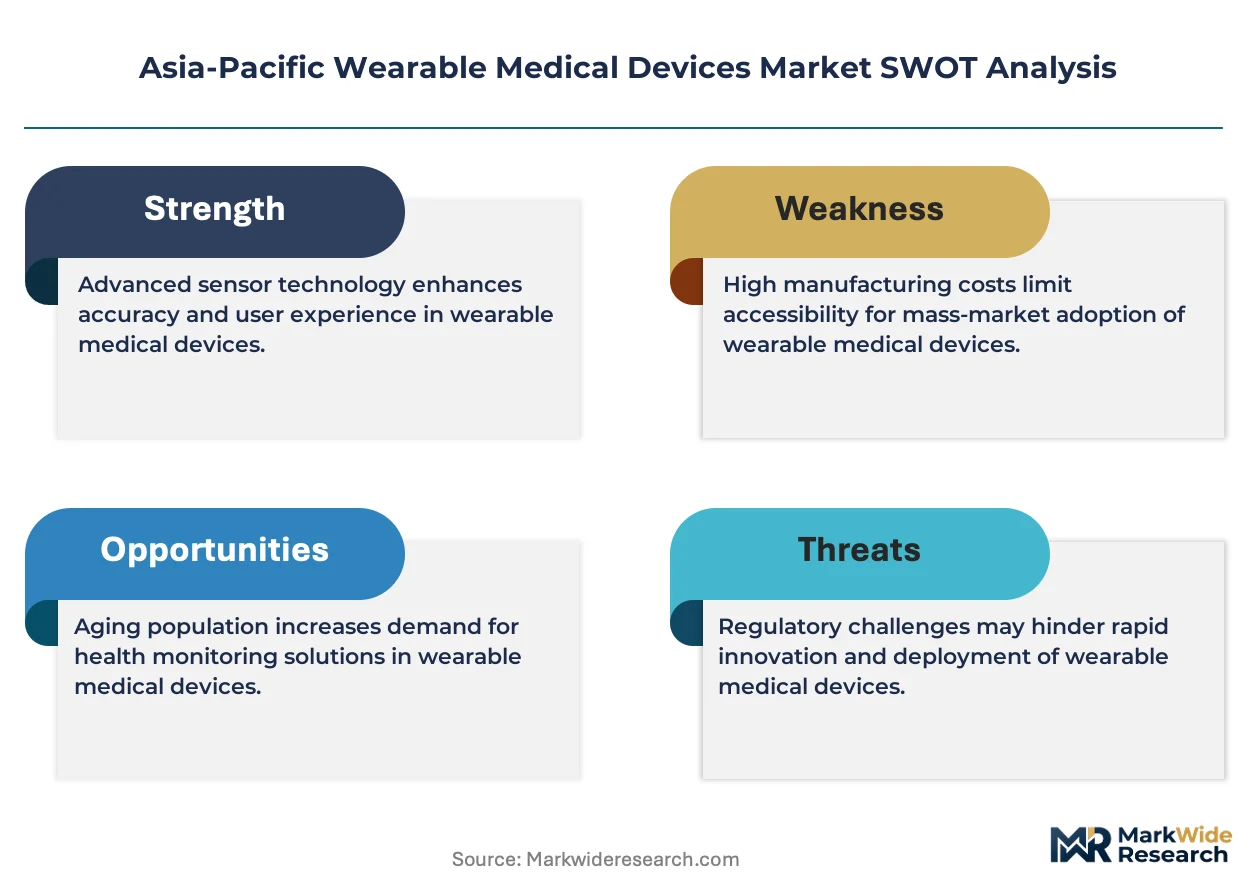
Japan's PMDA and China's NMPA enforce divergent clinical evidence requirements for Class II and III wearable devices, fragmenting registration timelines and compliance costs for manufacturers serving multiple markets. India's CDSCO has aligned with ISO 13485 quality management standards while introducing accelerated review tracks for software-as-medical-device applications. Stakeholders must monitor regulatory harmonization negotiations between ASEAN member states, as mutual recognition agreements would reshape market access strategies for device makers currently maintaining separate quality systems per country.
Market Dynamics
Hospital-at-home reimbursement frameworks across China and Japan are collapsing the traditional boundary between acute care and ambulatory monitoring, forcing device manufacturers to redesign validation protocols for continuous-use scenarios.
Growth Catalysts
- Japan's PMDA accelerated approval tracks:Reduced review timelines for Class II wearable ECG monitors enable faster commercialization of cardiac outpatient devices.
- Photoplethysmography sensor miniaturization:Smaller optical modules allow integration into ring and earbud form factors previously constrained by size.
- China's hospital-at-home procurement mandates:Provincial health commissions in Guangdong and Jiangsu now require remote monitoring capability for discharged cardiac patients.
Market Restraints
- GaAs photodetector supply concentration:Taiwan and South Korean foundries control 70% of medical-grade optical sensor wafer supply, exposing manufacturers to single-source risk.
- PMDA-NMPA evidence divergence:Japan requires 12-month continuous-use studies while China accepts 6-month data, forcing duplicate clinical trials for multi-market registration.
- Smartphone-based health apps:Consumer-grade heart rate and sleep tracking reduces willingness to pay for dedicated medical wearables among healthy demographics.
Strategic Opportunities
- Indonesia's underpenetrated diabetes management:World's fourth-largest diabetic population lacks continuous glucose monitor penetration, creating first-mover advantage for patch-based biosensors.
- Software-as-medical-device pathways:India's CDSCO accelerated review for algorithm-driven diagnostic features enables faster updates than hardware-locked competitors.
- Insurer wellness incentive integration:Japan's health insurance societies now subsidize wearable purchases tied to verified activity targets, creating institutional procurement channel.
Industry Challenges
- Bioimpedance calibration expertise scarcity:Few Asia-Pacific engineering programs train specialists in body composition sensor validation, constraining product development timelines.
- ISO 13485 quality system maintenance:Separate audits required for each national subsidiary multiply compliance overhead for manufacturers serving China, Japan, and India simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wearable Medical Devices Market |
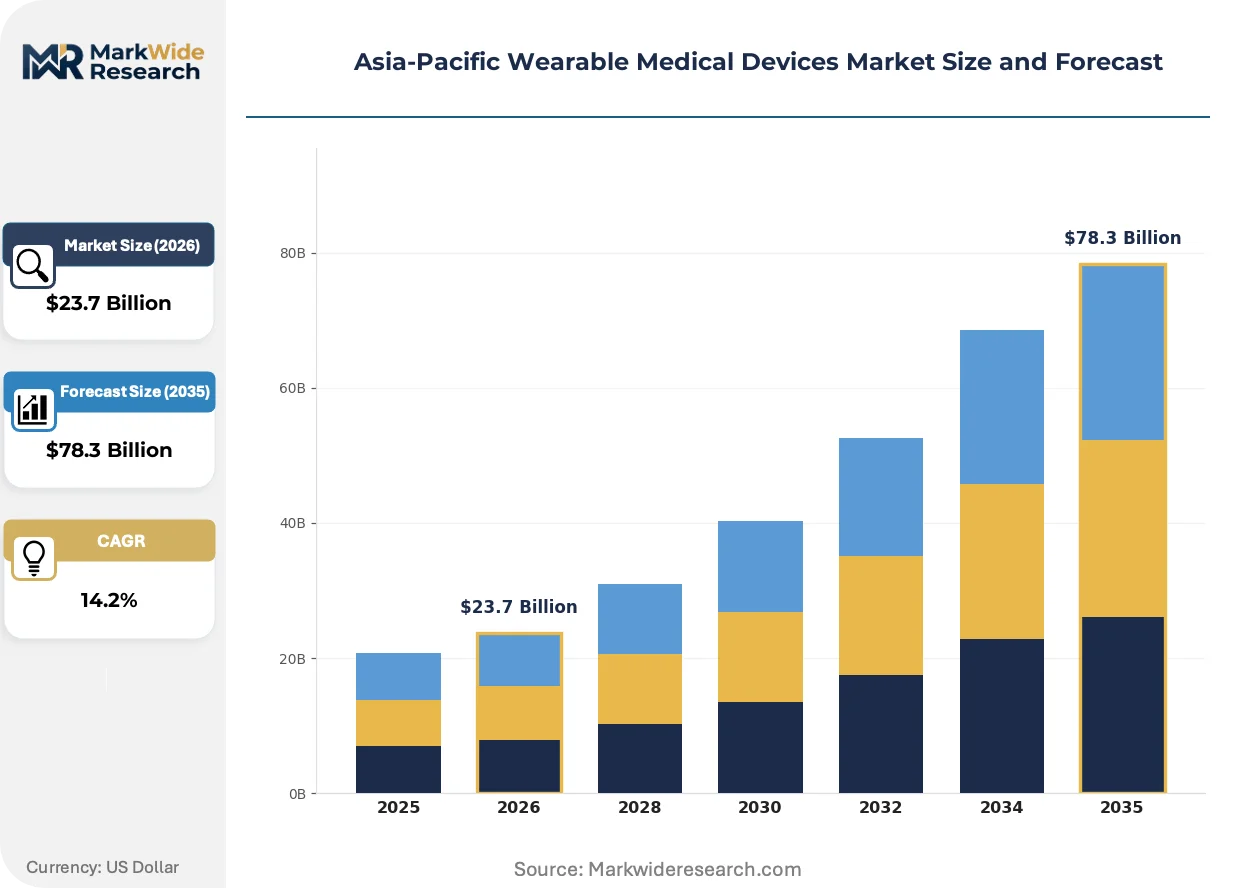
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Health Monitors, Wearable ECG Monitors Technology: Biosensors, Mobile Health Applications, Wireless Connectivity, Cloud Computing End User: Patients, Healthcare Professionals, Fitness Enthusiasts, Researchers Application: Chronic Disease Management, Fitness Monitoring, Emergency Alerts, Rehabilitation |
| Companies Covered | Apple Inc., Samsung Electronics, Fitbit Inc., Garmin Ltd., Omron Corporation, Xiaomi Corporation, Huawei Technologies Co., Ltd., Philips Healthcare, Medtronic plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wearable Medical Devices Market Strategic Shifts
Continuous glucose monitoring technology is migrating from dedicated patch devices to multi-sensor wrist-worn platforms, compressing the addressable market for single-purpose diabetes hardware.
Photoplethysmography is collapsing the distinction between consumer fitness tracking and clinical-grade arrhythmia detection. Samsung and Apple now embed FDA-cleared atrial fibrillation algorithms in mass-market smartwatches. Japanese cardiac centers are integrating these consumer device outputs into electronic health records, bypassing traditional Holter monitor procurement.
China's NMPA 2023 software-as-medical-device guidance requires cloud-based algorithm updates to undergo pre-market review, treating each model revision as a new registration event. Wearable manufacturers serving the Chinese market must now maintain frozen algorithm versions or absorb 90-day review cycles. Cardiac monitoring applications face the strictest scrutiny given diagnostic consequence.
Hospital procurement departments in Australia and South Korea are unbundling device hardware from data platform subscriptions, forcing vendors to compete on sensor cost alone. This purchasing pattern shift favors semiconductor-integrated manufacturers with captive component supply over pure-play device assemblers. Japanese university hospitals pioneered this split-contract model, with Seoul National University Hospital and Royal Melbourne Hospital now following suit.
Asia-Pacific Wearable Medical Devices Market Segmentation
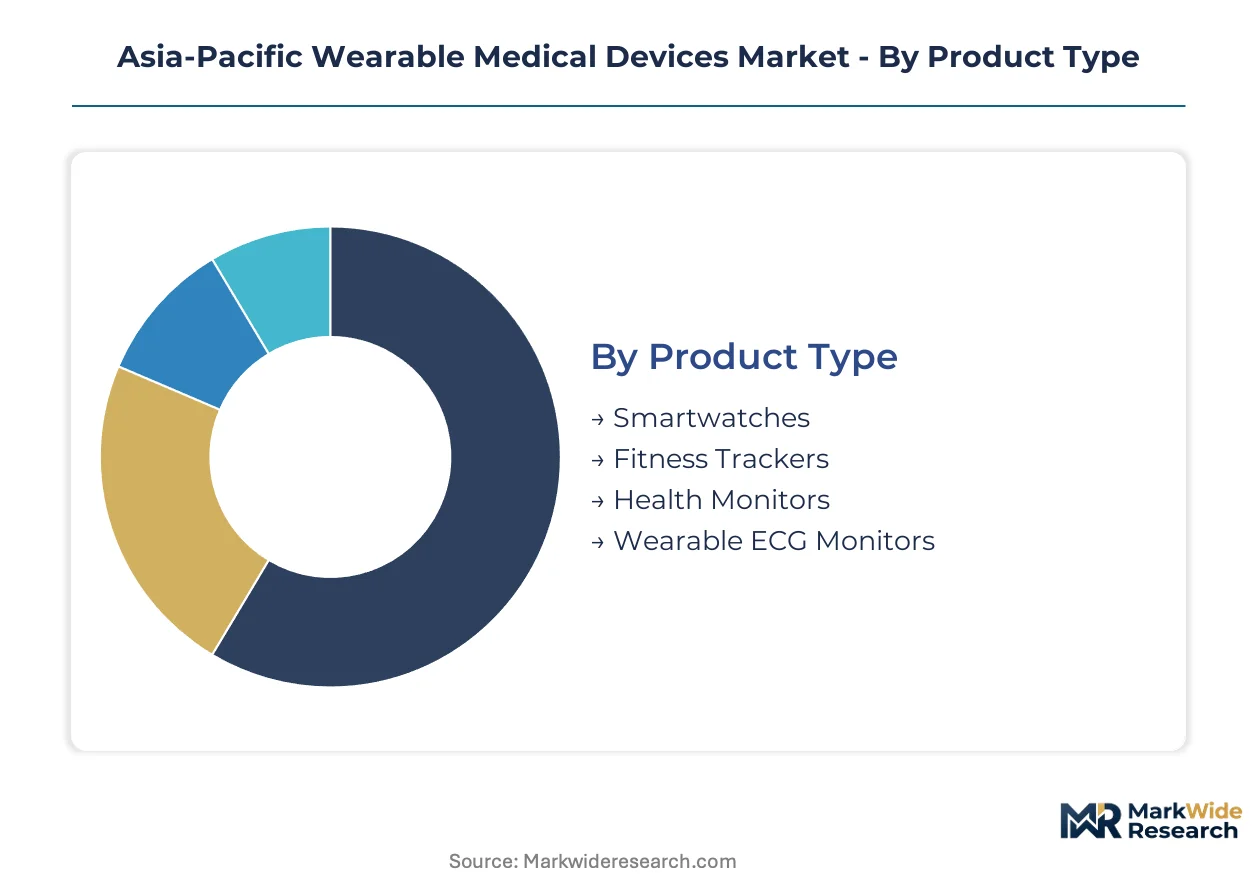
Segmentation across the Asia-Pacific wearable medical devices market reveals divergent margin profiles and regulatory pathways. Product form factors, sensing technologies, and end-user workflows each impose distinct validation requirements and procurement channels across China, Japan, and India.
Product Type:
Mature wrist-worn categories dominate current revenue pools while emerging patch-based formats capture hospital-at-home procurement mandates.
- Smartwatches:Multipurpose health tracking platforms integrate photoplethysmography, accelerometry, and bioimpedance sensors into familiar consumer form factors. China's provincial health commissions in Guangdong and Jiangsu now require remote monitoring capability for discharged cardiac patients, expanding institutional procurement beyond retail channels.
- Wearable ECG Monitors:Dedicated cardiac monitoring patches and chest straps deliver continuous arrhythmia detection with clinical-grade validation. Japan's PMDA accelerated approval tracks for Class II devices enable faster commercialization, while cardiac outpatient programs proliferate across Tokyo and Osaka metropolitan areas.
- Fitness Trackers:Entry-level wrist-worn units concentrate in Southeast Asian retail channels with aggressive manufacturing scale.
- Health Monitors:Specialized devices for blood pressure, blood glucose, and sleep apnea target aging populations with chronic conditions.
Smartwatches handle the majority of throughput; wearable ECG monitors are gaining share fastest as cardiac outpatient programs expand.
Technology:
Cost tier stratification separates premium biosensor modules from commoditized connectivity infrastructure.
- Biosensors:Photoplethysmography, bioimpedance, and electrochemical sensing layers determine clinical accuracy and margin concentration. Taiwan and South Korean foundries control medical-grade optical sensor wafer supply, exposing manufacturers to single-source risk.
- Wireless Connectivity:Bluetooth Low Energy and NFC protocols enable device-to-smartphone data transmission with minimal power draw.
- Cloud Computing:Data aggregation platforms face unbundling pressure from hospital procurement departments in Australia and South Korea.
- Mobile Health Applications:Algorithm-driven diagnostic features trigger software-as-medical-device regulatory pathways under India's CDSCO and China's NMPA.
Biosensors command premium pricing; mobile health applications are climbing the fastest as regulatory frameworks mature for algorithm-based diagnostics.
End User:
Customer type segmentation aligns device complexity with clinical oversight requirements and reimbursement eligibility.
- Patients:Home-based chronic disease management drives demand for continuous glucose monitors, blood pressure wearables, and sleep tracking devices. Japan's health insurance societies now subsidize wearable purchases tied to verified activity targets.
- Healthcare Professionals:Hospital-at-home programs and cardiac outpatient centers require devices with electronic health record integration and clinical-grade validation protocols.
- Fitness Enthusiasts:Consumer-grade heart rate and sleep tracking reduces willingness to pay for dedicated medical wearables among healthy demographics.
- Researchers:Clinical trial applications demand raw data export capabilities and compliance with ISO 14155 medical device clinical investigation standards.
Patients absorb the largest volume; healthcare professionals are expanding most quickly as hospital-at-home reimbursement frameworks mature.
Application:
Application scope determines regulatory classification and evidence requirements across PMDA, NMPA, and CDSCO jurisdictions.
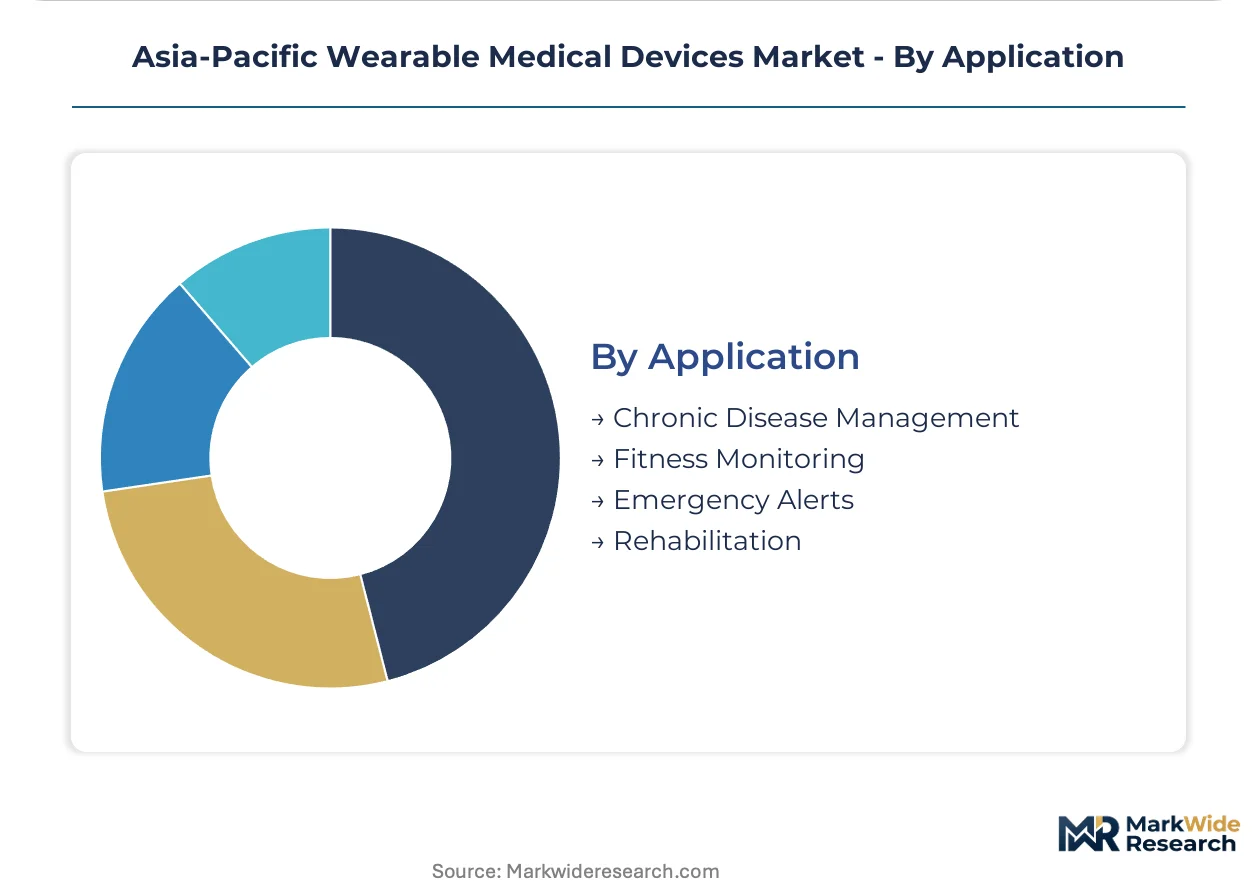
- Chronic Disease Management:Diabetes, hypertension, and cardiac arrhythmia monitoring applications face the strictest regulatory scrutiny given diagnostic consequence. Indonesia's underpenetrated diabetes management market lacks continuous glucose monitor penetration.
- Fitness Monitoring:Activity tracking and sleep analysis occupy the boundary between consumer wellness and regulated medical claims.
- Emergency Alerts:Fall detection and automated emergency response systems integrate with aged care infrastructure across Japan and Australia.
- Rehabilitation:Post-surgical mobility monitoring and physical therapy compliance tracking serve orthopedic and cardiac recovery protocols.
Chronic disease management generates the highest average selling prices; emergency alerts are gaining traction fastest as aged care infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and Japan deploy wearable medical devices primarily for cardiac outpatient monitoring under hospital-at-home reimbursement, while India and Indonesia concentrate procurement on diabetes management and fitness-linked insurance incentives.
China
Provincial health commissions in Guangdong and Jiangsu mandate remote monitoring capability for discharged cardiac patients, expanding institutional procurement beyond retail channels. The NMPA's 2023 software-as-medical-device guidance requires 90-day pre-market review for cloud-based algorithm updates. Device manufacturers cluster in Shenzhen's electronics corridor, where semiconductor-integrated producers control biosensor module costs.
Japan
Health insurance societies subsidize wearable purchases tied to verified activity targets, creating an institutional procurement channel distinct from consumer retail. The PMDA maintains accelerated approval tracks for Class II wearable ECG monitors with 12-month continuous-use evidence requirements. Tokyo and Osaka metropolitan areas anchor cardiac outpatient program expansion, with university hospitals pioneering split-contract procurement models.
India
The CDSCO's alignment with ISO 13485 quality management standards coincides with accelerated review tracks for software-as-medical-device applications. Maharashtra and Karnataka host the primary engineering talent pools for bioimpedance calibration and algorithm development. Hospital-at-home programs remain nascent, concentrating demand in chronic disease management for diabetes and hypertension.
South Korea
Seoul National University Hospital and affiliated cardiac centers unbundle device hardware from data platform subscriptions, forcing vendors to compete on sensor cost alone. The MFDS enforces clinical evidence requirements for Class II and III wearables that partially diverge from PMDA standards. Busan-Ulsan manufacturing corridors supply GaAs photodetector wafers, exposing regional device makers to single-source concentration risk.
Indonesia
The world's fourth-largest diabetic population lacks continuous glucose monitor penetration, creating first-mover positioning for patch-based biosensor entrants. National health system reimbursement for remote monitoring remains limited, channeling demand through private insurer wellness programs. Jakarta and Surabaya concentrate distribution infrastructure for Southeast Asian market access.
Asia-Pacific Wearable Medical Devices Market Competitive Environment
Capability concentration sits with semiconductor-integrated conglomerates controlling biosensor module design; scale advantage sits with consumer electronics manufacturers flooding entry-level segments. The vendor base stratifies across three tiers: clinical-grade specialists with regulatory validation depth, platform-integrated technology conglomerates with captive component supply, and manufacturing-scale assemblers competing on unit economics. Dominant competitive moves include backward integration into optical sensor wafer production and geographic expansion through insurer-backed wellness incentive partnerships.
Within the clinical-grade specialist tier, Omron Corporation anchors blood pressure monitoring validation protocols. Samsung Electronics and Xiaomi Corporation occupy opposing positions on the capability-scale spectrum, with the former exemplifying semiconductor-integrated supply chain control and the latter representing manufacturing-scale penetration of Southeast Asian retail channels. Apple Inc. sits within the platform-integrated tier, leveraging algorithm-driven diagnostic features across multi-sensor wrist-worn form factors.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Fitbit Inc. |
| Garmin Ltd. |
| Omron Corporation |
| Xiaomi Corporation |
| Huawei Technologies Co., Ltd. |
| Philips Healthcare |
| Medtronic plc |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's electronics corridor anchors biosensor module production capacity, concentrating cost-control leverage among semiconductor-integrated manufacturers while fragmenting pricing power for pure-play device assemblers serving hospital procurement channels.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement through Japan's health insurance societies and China's provincial health commissions, while spot-market transactions concentrate in Southeast Asian retail channels for fitness trackers. Price differentiation rests on clinical-grade validation tiers—PMDA Class II certification commands premium positioning against uncertified consumer alternatives. Cost compression in entry-level segments intensifies as Xiaomi's manufacturing scale floods Indonesian and Vietnamese retail networks. Hospital purchasing committees exhibit lowest price sensitivity given reimbursement-backed procurement mandates, whereas fitness enthusiasts demonstrate highest elasticity as smartphone health apps substitute dedicated devices.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk planning for GaAs photodetector procurement, with medical-grade optical sensor wafers drawing from Taiwanese and South Korean foundries. Raw material dependencies center on gallium arsenide substrates, lithium-polymer cells, and medical-grade silicone encapsulants. Single-source vulnerability concentrates in photodetector wafer supply, where two foundries control critical capacity. Distribution runs through hospital GPO contracts in Japan and Australia, direct-to-consumer retail in Southeast Asia, and insurer-subsidized channels in Japanese metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific wearable medical devices sit in early-cycle expansion as hospital-at-home reimbursement frameworks collapse acute-ambulatory boundaries and create institutional procurement channels previously absent from consumer-dominated markets.
For Market Incumbents: Pre-empt algorithm commoditization by embedding FDA-cleared and PMDA-validated diagnostic features into multi-sensor platforms before pure-play cardiac monitor specialists achieve scale. Backward integration into optical sensor wafer production defends margin position against Taiwan foundry concentration. Accelerate software-as-medical-device regulatory investments under India's CDSCO accelerated review tracks to lock in update-cycle advantages over hardware-locked competitors. For New Entrants and Emerging Players: Build out patch-based continuous glucose monitoring capabilities for Indonesia's underpenetrated diabetic population before established diabetes hardware manufacturers migrate to multi-sensor wrist platforms. Target private insurer wellness incentive channels in Jakarta and Surabaya as reimbursement infrastructure matures. Pursue software-first market entry under India's CDSCO framework to bypass capital-intensive hardware manufacturing scale requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because clinical validation depth and multi-jurisdictional approval portfolios compound defensibility against consumer electronics entrants. Acquisition targets should concentrate on semiconductor-integrated device makers with captive biosensor module design and existing PMDA-NMPA dual registration. Monitor ASEAN mutual recognition agreement negotiations as inflection signal—harmonized quality systems would collapse compliance overhead advantages currently held by multi-market specialists.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Class II Accelerated Approval | Reduced review timelines enable faster commercialization of cardiac outpatient devices in Tokyo-Osaka corridors. |
| Software-as-Medical-Device Pathway | CDSCO accelerated review tracks enable algorithm-driven diagnostic updates without hardware revision cycles. |
| Hospital System Partnership | Split-contract procurement models at Seoul National University Hospital and Royal Melbourne Hospital unbundle hardware from platform subscriptions. |
| Backward Integration into Optical Sensors | Captive GaAs photodetector wafer supply mitigates single-source concentration risk from Taiwanese foundries. |
| Insurer Wellness Incentive Integration | Japan's health insurance societies subsidize wearable purchases tied to verified activity targets, creating institutional channel access. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at PMDA and NMPA; and secondary validation through FDA 510(k) filings, PMDA approval databases, hospital procurement records, and customs trade data for biosensor component flows. Bottom-up triangulation across device shipment estimates and top-down reconciliation against reimbursement expenditure data anchored market sizing.
Forecast inputs considered product form factor adoption curves, regulatory pathway timelines across PMDA-NMPA-CDSCO jurisdictions, and hospital-at-home reimbursement expansion rates. Segmentation modeling spanned sensing technology tiers, end-user clinical oversight requirements, and application-specific evidence standards. CAGRs derived from fitted adoption curves against chronic disease prevalence projections and insurer incentive program rollouts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated technology conglomerates or unexpected ASEAN regulatory harmonization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Kiosk Market
Medical Devices
Neurotech Devices Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Global Medical Drones Market
Medical Devices
Creatinine Meter Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Transilluminators Market
Medical Devices
Thyroid Ablation Devices Market