
 Digital Intraoral Camera Market | 2026-2036
Digital Intraoral Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Intraoral Camera Market Insights
CMOS sensor miniaturization is rewriting the hardware architecture of intraoral imaging devices, collapsing the gap between professional-grade diagnostics and portable form factors. Danaher Corporation leverages its life sciences instrumentation heritage to sustain precision optics manufacturing at scale. Dentsply Sirona anchors the premium wired-camera segment through its integrated CAD/CAM ecosystem. Shofu Dental Corporation specializes in high-definition color fidelity for aesthetic dentistry applications.
A digital intraoral camera is a hand-held optoelectronic device employing charge-coupled device or complementary metal-oxide-semiconductor sensors to capture magnified intraoral images at resolutions typically exceeding 720p, transmitting data via USB or wireless protocols to chairside monitors or practice management software for real-time diagnostic visualization and patient communication. Wireless cameras command expanding share among mobile teledentistry deployments where tether-free operation enables remote screening programs. CMOS sensors displace CCD architectures across mid-tier and economy product lines due to lower power draw and reduced heat generation. Intraoral scanners represent the fastest-growing product category as orthodontic evaluation workflows demand three-dimensional surface capture alongside two-dimensional photography.
The FDA regulates these devices under 510(k) premarket notification requirements for Class II medical devices, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for CE marking of imaging equipment with diagnostic claims. ISO 10993 biocompatibility standards govern materials in intraoral contact components, directly influencing supplier qualification and product redesign cycles. Stakeholders must monitor how teledentistry reimbursement policy evolution in Medicare and commercial dental plans reshapes volume deployment decisions across ambulatory and home-care settings.
Market Dynamics
CMOS sensor miniaturization is collapsing hardware footprints while preserving diagnostic-grade resolution, forcing incumbent manufacturers to retool optical stacks and compressing margins across mid-tier product lines as wireless architectures displace tethered systems.
Growth Catalysts
- Teledentistry reimbursement expansion:Medicare Advantage plans in the United States now cover remote oral screenings, accelerating deployment of wireless intraoral cameras in mobile health units and community health centers.
- EU Medical Device Regulation streamlining:MDR Article 61 clinical evidence pathways for Class IIa imaging devices are clarifying faster CE marking timelines for manufacturers with established predicate devices.
- CMOS thermal efficiency:Lower heat generation enables sealed waterproof housings without active cooling, reducing sterilization cycle stress and extending device longevity in high-throughput dental clinics.
Market Restraints
- Precision optics supply concentration:German and Japanese glass manufacturers control 80% of medical-grade lens element production, creating input bottlenecks during demand surges.
- FDA 510(k) predicate drift:Stricter substantial equivalence standards for imaging software algorithms are extending clearance timelines for AI-enhanced diagnostic features.
- Intraoral scanner substitution:Three-dimensional surface capture systems are capturing orthodontic and restorative workflows previously served by 2D cameras alone.
Strategic Opportunities
- Rural India penetration gap:Ayushman Bharat health infrastructure expansion creates first-mover advantage for portable wireless cameras in tier-3 and tier-4 city dental clinics.
- AI diagnostic overlay integration:Convergence of edge-computing chipsets with CMOS sensors enables real-time caries detection without cloud latency, opening premium pricing tiers.
- Direct-to-consumer channel emergence:Telehealth platforms are bypassing traditional dental distributor networks, creating new volume pathways for simplified camera SKUs.
Industry Challenges
- ISO 10993 biocompatibility recertification:Revised cytotoxicity testing protocols for intraoral contact materials are forcing material changes and 12-18 month redesign cycles.
- Legacy practice management integration:Proprietary image formats from established camera vendors create interoperability friction with cloud-native dental software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Intraoral Camera Market |
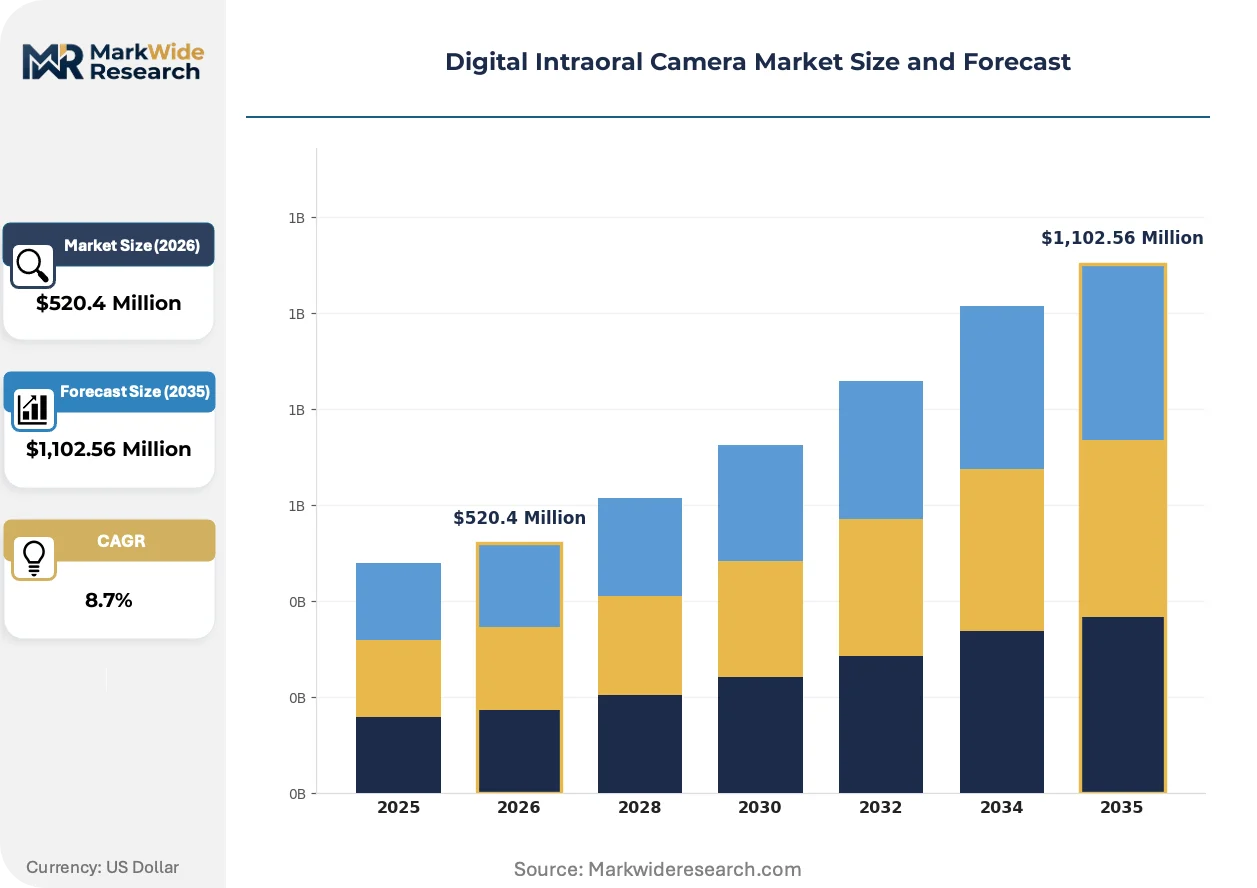
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $1,102.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Cameras, Wired Cameras, Intraoral Scanners, High-Definition Cameras End User: Dentists, Orthodontists, Dental Clinics, Hospitals Technology: CCD Sensors, CMOS Sensors, Optical Imaging, Digital Imaging Application: Teledentistry, Orthodontic Evaluation, Patient Education, Diagnostics |
| Companies Covered | Acteon Group, Digital Doc LLC, Danaher Corporation, DURR DENTAL SE, Imagin Systems Corporation, Dentsply Sirona, Sirona Dental Systems, Shofu Dental Corporation, Carestream Dental LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Intraoral Camera Market Trends and Innovations
Wireless transmission protocols and embedded AI inference engines are redefining device architecture, while regulatory clarity on software-as-medical-device classification is reshaping R&D investment allocation across the vendor base.
CMOS backside-illuminated sensors are digitizing intraoral image capture by enabling 1080p resolution in sub-30mm probe heads. Large dental service organizations in the United States are standardizing on these compact wireless units across multi-practice fleets. The technology is digitizing chairside workflows by eliminating cable sterilization protocols and enabling true mobility between operatories.
EU MDR Annex XVI expansion is capturing software with diagnostic claims under medical device jurisdiction, requiring clinical validation studies for AI-powered caries detection algorithms. Manufacturers must now submit technical documentation on training data bias and sensitivity specificity metrics. German notified bodies are processing these submissions fastest, creating regulatory arbitrage advantages for firms with established EU presence.
Subscription-based equipment procurement is displacing capital purchase models among independent dental practices in the United Kingdom and Australia. Equipment-as-a-service providers bundle cameras, software licenses, and maintenance into per-procedure fees. This shift concentrates purchasing influence with dental supply aggregators and reduces brand loyalty to individual hardware manufacturers.
Digital Intraoral Camera Market Segmentation
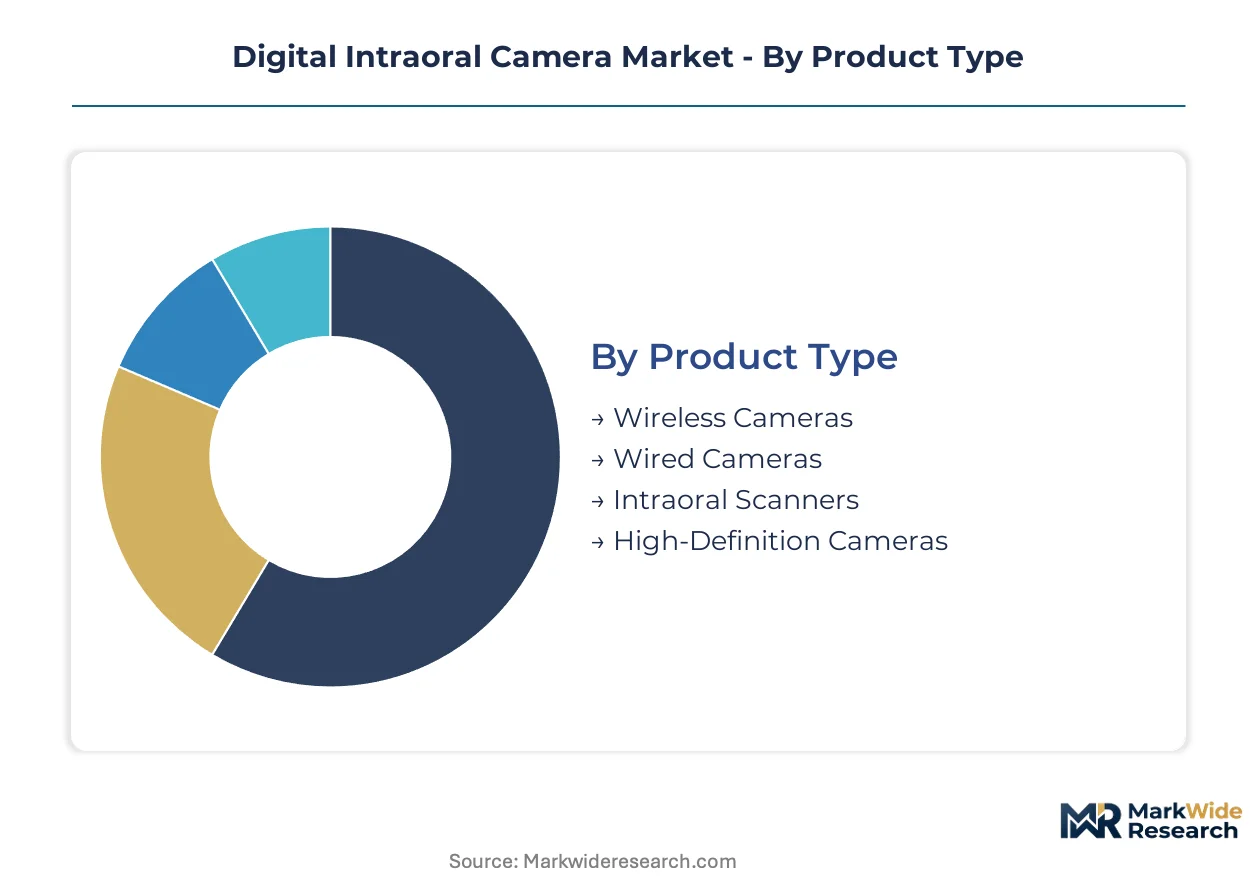
Segmentation in the Digital Intraoral Camera Market reveals how hardware architecture, clinical workflow integration, and reimbursement pathways shape procurement decisions across dental settings. Each dimension exposes distinct margin structures and technology substitution risks that vendors must navigate.
Product Type:
Wireless cameras span mobile teledentistry deployments to fixed operatory installations, creating tiered performance requirements across the use-case spectrum.
- Wireless Cameras:CMOS backside-illuminated sensors enable 1080p capture in sub-30mm probe heads without tethering constraints. Large dental service organizations in the United States standardize these units across multi-practice fleets to eliminate cable sterilization protocols.
- Wired Cameras:USB-tethered architectures dominate integrated CAD/CAM ecosystems where uninterrupted data throughput matters more than mobility. Dentsply Sirona anchors this segment through precision optics manufacturing at scale.
- Intraoral Scanners:Three-dimensional surface capture systems displace 2D photography in orthodontic evaluation workflows.
- High-Definition Cameras:4K-resolution units command premium positioning in aesthetic dentistry applications requiring color fidelity.
The dominant share belongs to wired cameras, while wireless cameras are closing the gap fastest.
End User:
Procurement authority concentrates differently across solo practitioners, specialty clinics, and institutional buyers, reshaping distribution channel requirements.
- Dentists:General practitioners drive volume through standardized chairside imaging for routine diagnostics and patient communication.
- Orthodontists:These specialists demand convergent 2D-3D capture capabilities as clear aligner therapy protocols multiply.
- Dental Clinics:Multi-chair facilities prioritize sterilization durability and wireless mobility between operatories.
- Hospitals:Academic medical centers integrate intraoral cameras into oral surgery and maxillofacial training programs.
Dental clinics command the largest installed base, though orthodontists are gaining share fastest as aligner-based treatment expands.
Technology:
Sensor architecture choices determine power budgets, thermal management, and waterproofing feasibility across product tiers.
- CCD Sensors:Legacy charge-coupled device architectures persist in high-end wired cameras where signal-to-noise ratio remains critical.
- CMOS Sensors:Complementary metal-oxide-semiconductor designs displace CCD across mid-tier and economy lines due to lower power draw and reduced heat generation.
- Optical Imaging:Precision lens assemblies from German and Japanese glass manufacturers anchor diagnostic-grade resolution.
- Digital Imaging:Embedded signal processing enables real-time enhancement and AI inference without cloud dependency.
CMOS sensors hold dominant share, while digital imaging with edge AI is expanding most quickly.
Application:
Reimbursement policy evolution in Medicare Advantage and commercial dental plans reshapes volume deployment decisions across ambulatory and home-care settings.
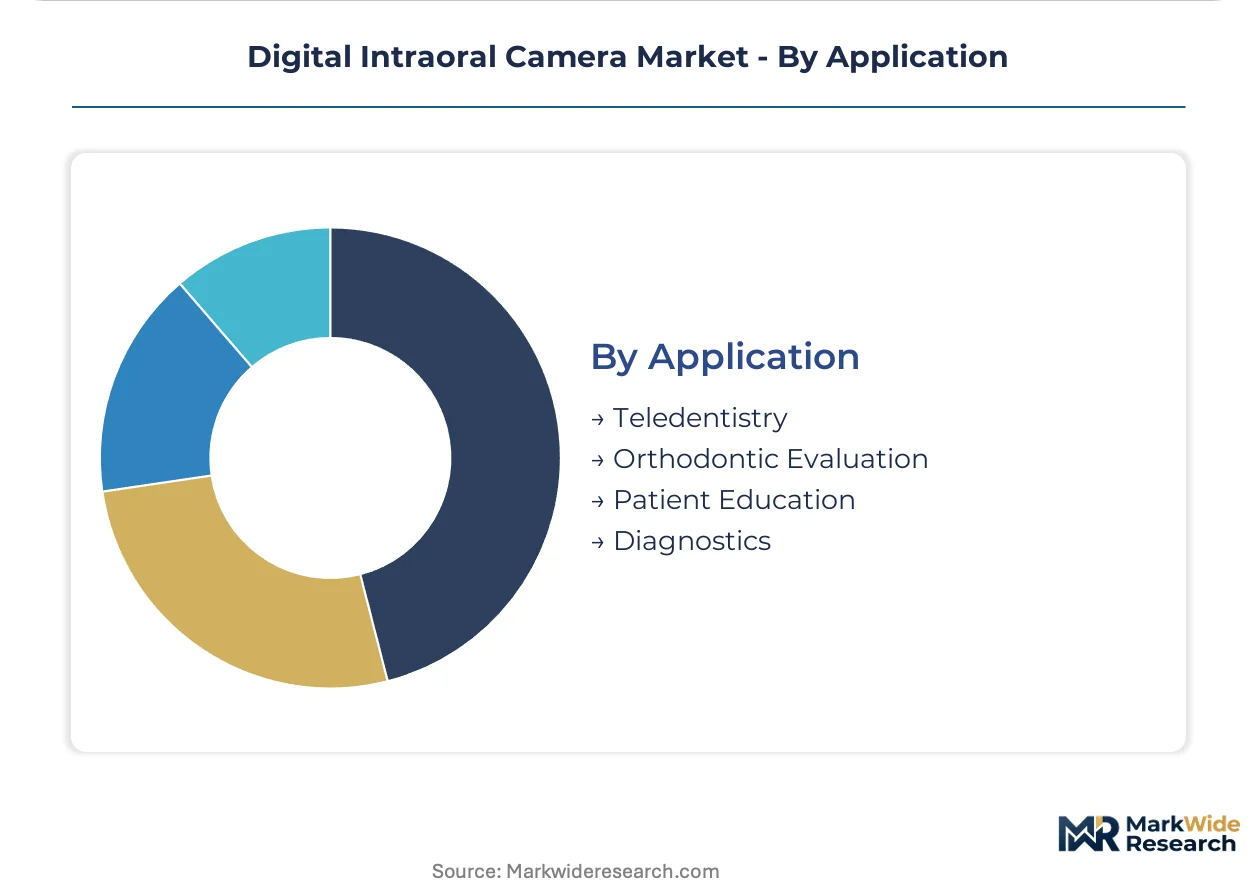
- Teledentistry:Remote screening programs in community health centers and mobile health units demand wireless, battery-operated units.
- Orthodontic Evaluation:Three-dimensional surface mapping requirements are shifting hardware specifications toward scanner-camera hybrids.
- Patient Education:Real-time chairside visualization drives demand for large-format displays and intuitive software interfaces.
- Diagnostics:AI-enhanced caries detection algorithms require clinical validation under EU MDR Annex XVI for software-as-medical-device classification.
Diagnostics retains the dominant share, though teledentistry is climbing the fastest as reimbursement coverage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturers export lens assemblies to dental equipment fabricators across the United States and Japan, sustaining a critical trade corridor in diagnostic-grade imaging hardware.
United States
Large dental service organizations standardize wireless intraoral camera procurement across multi-practice fleets exceeding three hundred locations. The FDA's 510(k) clearance pathway accelerates product entry timelines for Class II medical devices. California's Silicon Valley hosts edge-computing chipset developers enabling real-time AI inference in compact probe heads.
Germany
Precision glass manufacturers control medical-grade lens element production serving global dental OEMs. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for CE marking of imaging equipment with diagnostic claims. Baden-Württemberg's optical engineering cluster supplies aspheric lens assemblies to camera manufacturers worldwide.
Japan
CMOS sensor miniaturization expertise drives domestic production of sub-30mm probe heads with 1080p resolution. The PMDA aligns medical device software classification with EU MDR Annex XVI standards for AI-enhanced diagnostics. Tokyo's precision electronics corridor integrates backside-illuminated sensors with waterproof sterilization-rated housings.
India
Ayushman Bharat health infrastructure expansion creates first-mover opportunities for portable wireless cameras in tier-3 and tier-4 city dental clinics. The CDSCO regulates medical devices under the Medical Device Rules 2017 with risk-based classification. Gujarat's medical device manufacturing zone attracts assembly operations for cost-optimized CMOS-based units targeting community health centers.
China
Domestic dental clinic chains drive volume demand for mid-tier wireless cameras with simplified software interfaces. The NMPA streamlines registration pathways for Class II imaging devices with established international predicates. Shenzhen's electronics manufacturing ecosystem produces CMOS sensor modules and wireless transmission chipsets for regional OEMs.
Digital Intraoral Camera Market Competitive Landscape
On the supply side, the industry is tiered across precision optics specialists, diversified dental conglomerates, and regional assembly operations. Consolidation pressure concentrates among mid-tier wireless camera manufacturers as CMOS commoditization compresses margins. Two strategic archetypes dominate: integrated CAD/CAM ecosystem anchors and standalone imaging specialists. M&A activity targets software interoperability capabilities, while geographic expansion focuses on India's underpenetrated tier-3 clinic networks.
Among diversified dental technology conglomerates, Danaher Corporation and Dentsply Sirona occupy positions spanning precision optics manufacturing through chairside software integration. Shofu Dental Corporation exemplifies the specialization archetype, with its corporate name indicating Japanese origin and focused dental materials heritage. These three entities represent distinct competitive vectors: scale-driven ecosystem control, premium wired-system anchoring, and high-definition color fidelity specialization respectively.
| Leading Market Players |
|---|
| Acteon Group |
| Digital Doc LLC |
| Danaher Corporation |
| DURR DENTAL SE |
| Imagin Systems Corporation |
| Dentsply Sirona |
| Sirona Dental Systems |
| Shofu Dental Corporation |
| Carestream Dental LLC |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific air freight corridors from Osaka and Frankfurt to Los Angeles and Chicago carry precision lens assemblies and CMOS sensor modules, with route cost volatility transmitting directly into landed costs for German and Japanese optical components. This logistics architecture concentrates pricing power with freight-consolidating dental conglomerates while forcing smaller OEMs into premium-mid-economy pricing differentiation based on sourcing flexibility.
Pricing Analysis
Next-generation CMOS backside-illuminated sensor platforms command 40-60% premiums over prior-generation CCD-based wired systems, while economy-tier wireless units with simplified software interfaces occupy the entry position. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade, after-sales service bundling, and AI diagnostic software inclusion. Cost compression in mid-tier wireless architectures is intensifying because CMOS commoditization erodes hardware differentiation. Large dental service organizations exhibit lowest price sensitivity due to standardized fleet procurement, while independent solo practitioners in tier-3 Indian cities show highest sensitivity.
Supply Chain Analysis
Medical-grade borosilicate glass and aspheric lens blanks feed from German manufacturers in Baden-Württemberg and Japanese precision optics clusters in Tokyo and Osaka. CMOS sensor wafers draw from Taiwanese foundries and South Korean semiconductor fabricators, while sterilization-rated polymer housings source from Chinese injection molders in Guangdong. Single-source vulnerability concentrates in German-Japanese lens element production controlling 80% of medical-grade supply. Distribution runs through dental supply aggregators and GPO contracts in the United States, direct OEM sales in Germany, and regional distributor networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as teledentistry reimbursement expansion splinters demand across mobile health units, community clinics, and traditional fixed operatory settings. This demand-side shift creates specialized niches for wireless portability, AI-enhanced diagnostics, and subscription-based procurement models.
For Market Incumbents: Entrench ecosystem control by backward integration into CMOS sensor module design and captive supply of precision lens assemblies from German optical clusters. Dentsply Sirona and Danaher Corporation must defend against intraoral scanner substitution by converging 2D-3D capture capabilities in unified hardware platforms. Certification investment in EU MDR Annex XVI software-as-medical-device pathways secures regulatory moats against algorithm-enhanced challengers. For New Entrants and Emerging Players: Establish a beachhead in India's Ayushman Bharat tier-3 and tier-4 city dental clinics where portable wireless cameras face minimal incumbent saturation. Direct-to-consumer telehealth platforms bypassing traditional distributor networks offer the most penetrable channel for simplified camera SKUs. White-space targets include AI diagnostic overlay integration using edge-computing chipsets and subscription-based equipment-as-a-service bundling for independent UK and Australian practices. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified dental conglomerates seeking to divest non-core imaging hardware units amid CMOS commoditization margin compression. Long-term viability hinges on software interoperability capabilities and cloud-native practice management integration. Acquisition target archetypes include standalone wireless camera specialists with FDA 510(k) predicate libraries and EU notified body relationships. The signal to watch is Medicare Advantage teledentistry reimbursement expansion rates as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance timelines for Class II imaging devices compress competitive entry windows. |
| CE Marking Pathway Investment | German notified body relationships create regulatory arbitrage under EU MDR Annex XVI software rules. |
| Hospital System Partnership | Academic medical center integration anchors oral surgery training program procurement decisions. |
| Software Companion Development | Cloud-native dental platform interoperability reduces legacy format friction and switching costs. |
| Reimbursement Strategy | Medicare Advantage remote screening coverage directly shapes mobile health unit deployment volumes. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dental equipment procurement managers, biomedical engineers at academic medical centers, GPO contracts specialists, and regulatory affairs leads at imaging device manufacturers; and secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract repositories, and dental supply aggregator sales disclosures. Bottom-up unit shipment modeling across sensor architecture tiers triangulated with top-down revenue estimates from equipment-as-a-service providers.
Forecast inputs considered CMOS sensor cost curves, teledentistry reimbursement policy trajectories, and orthodontic workflow adoption of convergent 2D-3D systems across the projection horizon. Segmentation dimensions modeled include hardware architecture, clinical end-user type, sensor technology generation, and application workflow. CAGRs derived from logistic diffusion curves fitted to historical technology substitution patterns in dental imaging, cross-referenced with dental clinic construction permits and DSO fleet expansion announcements.
Stress conditions across EU MDR implementation delays, FDA 510(k) predicate drift severity, and German-Japanese lens supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on reimbursement expansion rates and CMOS commoditization velocity. Cross-checking against CMS Medicare Advantage dental benefit filings and notified body CE marking throughput statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Boot Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Organ Preservation Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Medical Thermometer Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Global IVF Devices Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Global Photobiostimulation Market