
 Reusable Medical Battery Market | 2026-2036
Reusable Medical Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Medical Battery Market Insights
Aftermarket battery refurbishment and recertification revenue is reconfiguring margin pools away from virgin cell manufacturing. Ultralife Corporation leverages its military-grade lithium heritage to dominate hospital-grade power architectures. EnerSys sustains broad manufacturing scale across nickel-metal hydride and lithium-ion chemistries for surgical tool OEMs. Integer Holdings Corporation anchors its position through deep integration into portable monitor supply chains.
Reusable medical batteries are electrochemical energy storage devices engineered for multiple charge-discharge cycles in clinical environments, typically specified for 500–1,000 cycles with stable voltage output across sterilization temperatures. Their primary purpose is to eliminate single-use battery waste while ensuring uninterrupted power for life-supporting and surgical equipment. Lithium-ion cells capture the dominant share of new platform design due to energy density advantages in compact surgical tools and infusion pumps. Nickel-metal hydride retains relevance in legacy portable monitors where cost sensitivity outweighs performance demands. Smart battery technology with embedded energy management circuits represents the fastest-expanding segment as hospitals prioritize predictive maintenance and cycle-count transparency.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements shape product validation pathways and market access timelines for reusable medical battery suppliers. ISO 13485 certification and IEC 62133 safety standards further constrain which manufacturers can serve regulated clinical end users. Stakeholders must monitor evolving EU battery sustainability rules and FDA guidance on wireless charging interoperability as these frameworks will determine which technology platforms qualify for institutional procurement contracts.
Market Dynamics
Surgical tool electrification is compressing replacement cycles while FDA and EU MDR safety mandates force validated recharge protocols onto all new platform designs. This dual pressure is restructuring margin pools away from virgin cell manufacturing toward aftermarket refurbishment and recertification services.
Growth Catalysts
- EU MDR Technical Documentation:Mandatory validated recharge protocols for reusable medical batteries create compliance-driven replacement demand across European hospital procurement networks.
- Surgical Tool Electrification:Advanced electrosurgical instruments and robotic platforms require higher-cycle lithium-ion architectures that obsolete legacy nickel-metal hydride systems.
- Germany-Japan-US Hospital Procurement Standards:Institutional certification requirements in these three markets concentrate demand for FDA-cleared and CE-marked reusable battery platforms.
Market Restraints
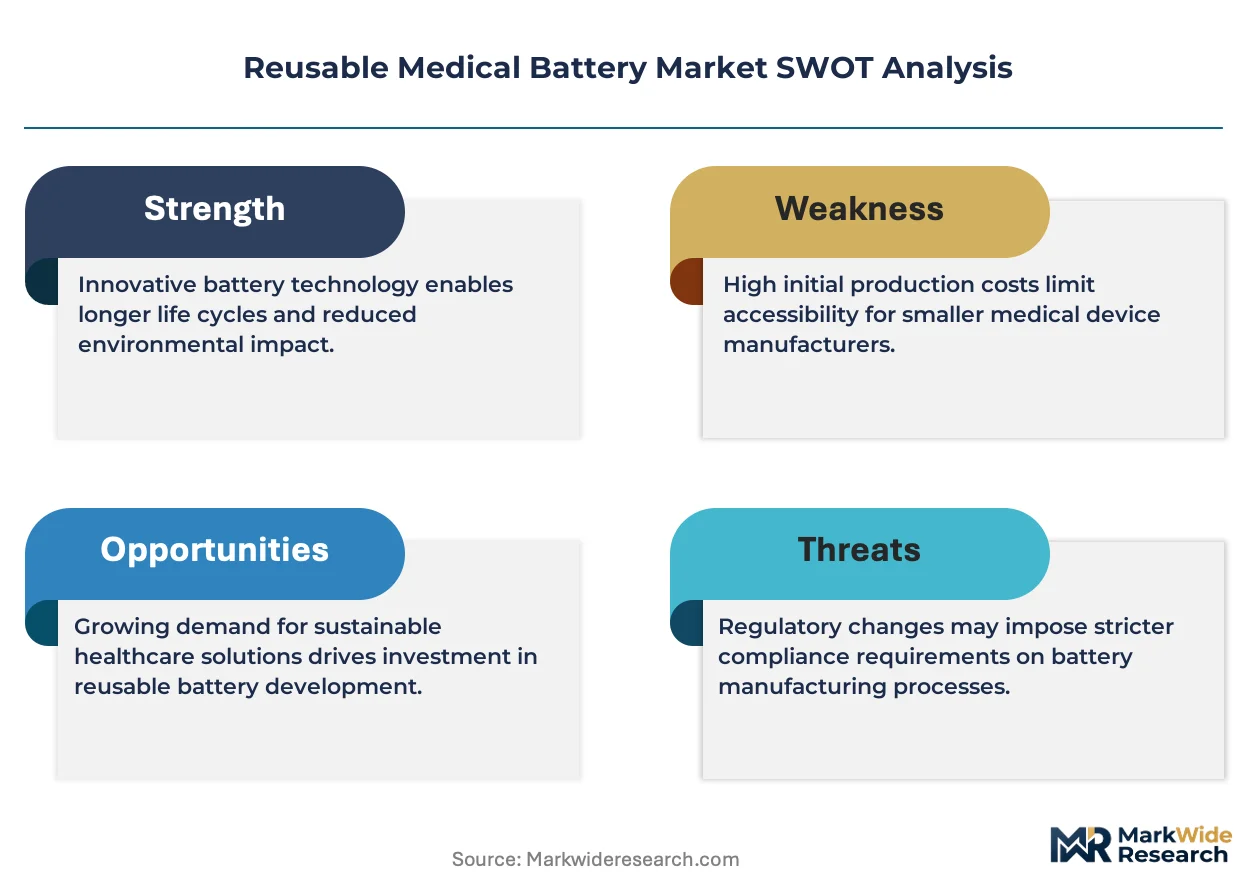
- Lithium Cobalt Oxide Input Volatility:Cathode material cost swings constrain margin stability for manufacturers dependent on spot-market cobalt supply from Central African mining operations.
- East Asian Cell Concentration:Over 70 percent of medical-grade lithium-ion cell fabrication concentrates in South Korea and China, creating geopolitical supply vulnerability for Western OEMs.
- IEC 62133 Certification Friction:Extended safety testing timelines for secondary cell chemistries delay product launches by 12-18 months versus consumer electronics benchmarks.
Strategic Opportunities
- Indian Hospital Modernization:CDSCO regulatory alignment with international standards opens procurement pathways for certified reusable battery suppliers in tertiary care expansion.
- Wireless Charging Convergence:Integration of resonant inductive power transfer with embedded battery management circuits eliminates contact-point sterilization failures in operating theaters.
- EU Battery Sustainability Rules:Mandatory carbon footprint disclosure and recycled content thresholds create first-mover advantage for closed-loop refurbishment operators.
Industry Challenges
- Electrochemical Engineer Scarcity:Specialized talent in medical-grade cell chemistry and sterilization-compatible encapsulation commands premium compensation and extends hiring timelines.
- ISO 13485 Quality System Capex:Cleanroom manufacturing infrastructure and traceability systems require substantial capital deployment before first commercial shipments.
- Legacy Monitor Integration Complexity:Backward compatibility demands for nickel-metal hydride architectures in installed portable monitor bases fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Medical Battery Market |
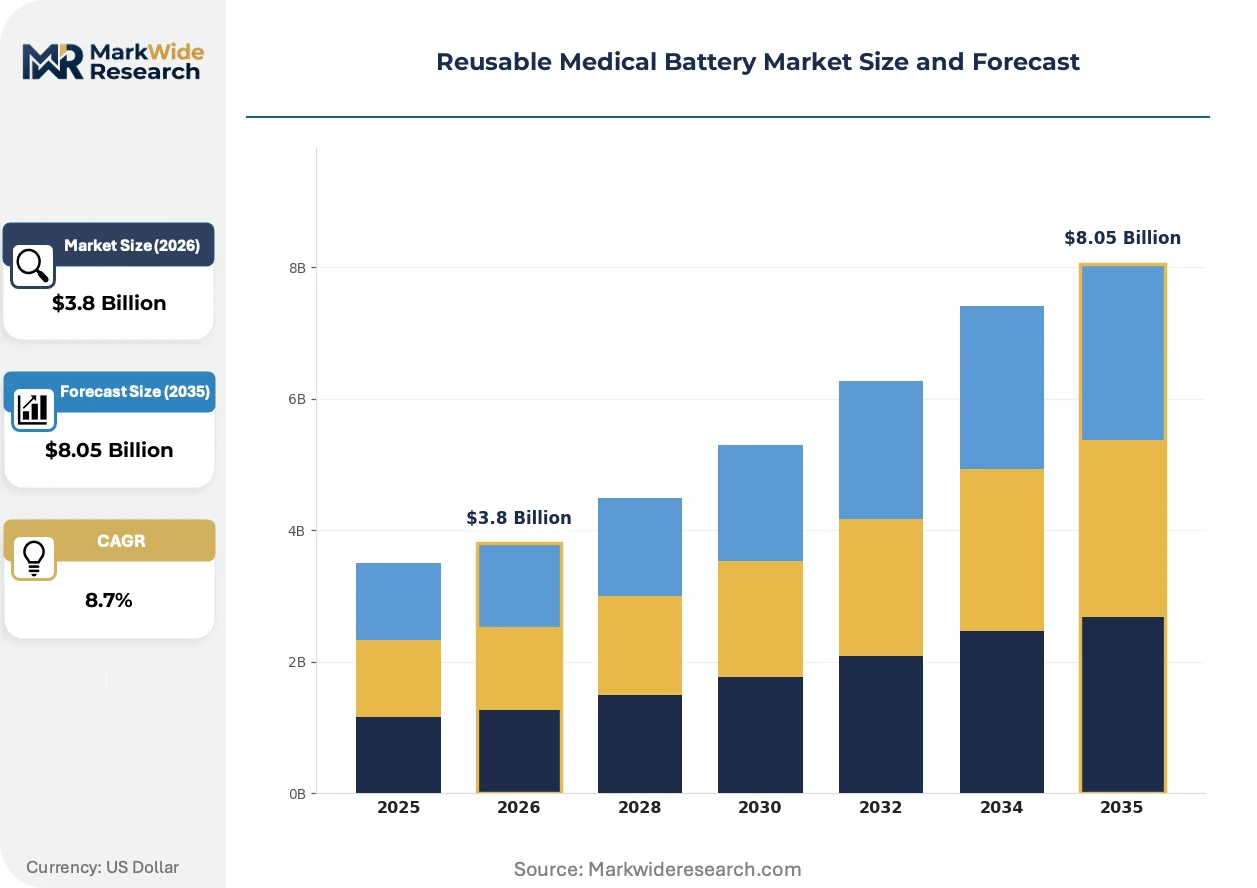
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Polymer Application: Pacemakers, Surgical Tools, Portable Monitors, Infusion Pumps End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Technology: Rechargeable Systems, Energy Management, Wireless Charging, Smart Batteries |
| Companies Covered | Ultralife Corporation, Saft Groupe, EaglePicher Technologies, EnerSys, Integer Holdings Corporation, Electrochem Solutions, Bytec Healthcare, KAYO Battery, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Medical Battery Market Trends and Innovations
Smart battery architectures with embedded fuel gauging and predictive analytics are displacing passive electrochemical cells across premium surgical tool segments. This intelligence layer is redefining competitive differentiation and service revenue models.
Solid-state lithium-polymer technology is migrating from defense-aerospace applications into compact surgical instruments requiring sterilization tolerance beyond 134 degrees Celsius. ENT microdebriders and arthroscopic shaver manufacturers in Germany and Japan are piloting these platforms for 2027 product launches. The shift is compressing conventional liquid electrolyte cell qualification timelines as OEMs prioritize thermal stability over proven field data.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for battery-powered active implantable accessories, extending validation pathways for infusion pump and ventilator power systems. Manufacturers must demonstrate biocompatibility of encapsulation materials under repeated sterilization cycles. Class IIa and IIb device suppliers in the Netherlands and Ireland are restructuring regulatory affairs teams to manage parallel FDA 510(k) and CE marking submissions.
Hospital materials management departments are consolidating supplier contracts around full-service battery lifecycle agreements that bundle cells, chargers, and refurbishment services under single-source frameworks. This displaces spot purchasing of replacement batteries through distributor channels. Integrated delivery networks in the United States and National Health Service trusts in England are piloting these arrangements for high-volume surgical tool fleets.
Reusable Medical Battery Market Segmentation
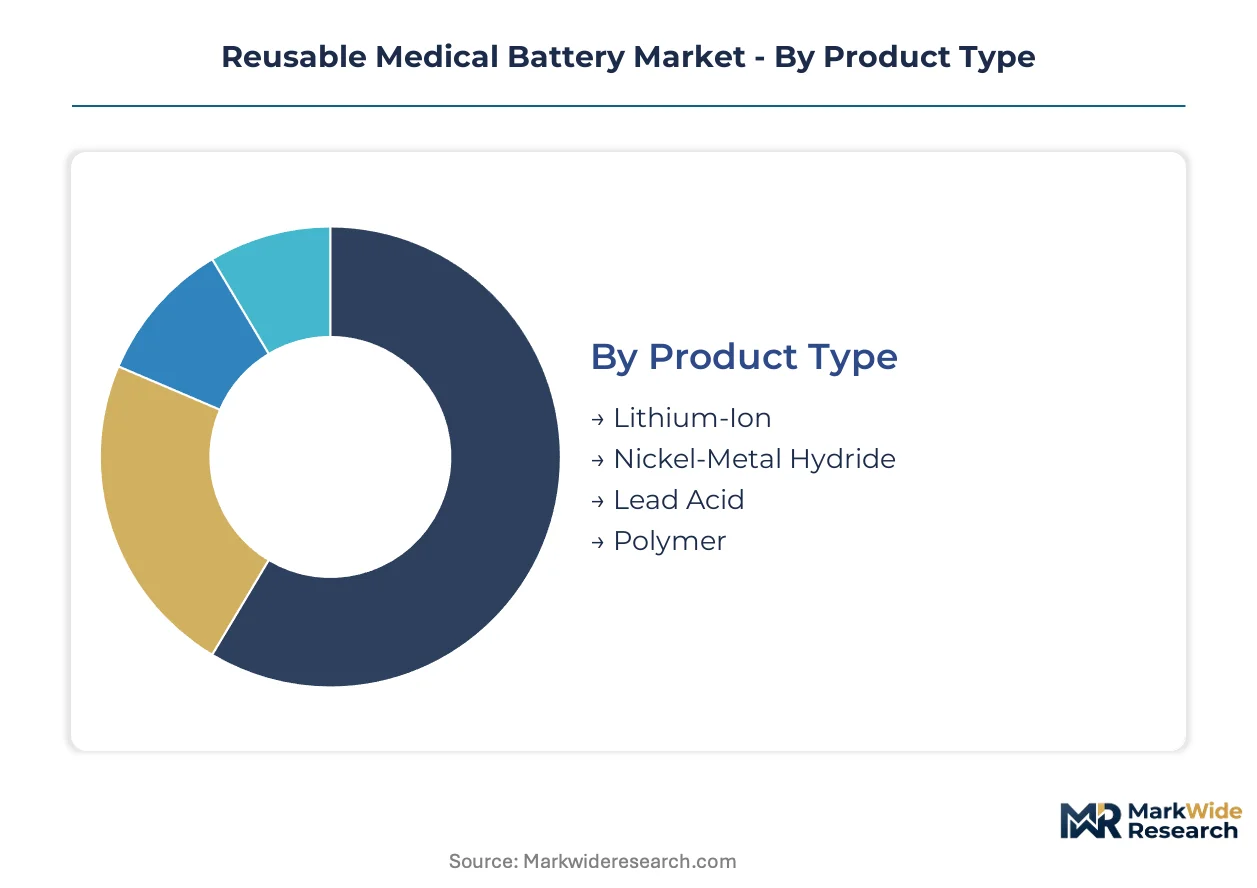
Reusable medical battery segmentation reflects competing priorities across energy density, sterilization tolerance, and procurement compliance. Hospital materials managers select chemistries and technologies based on specific device power signatures and regulatory certification requirements.
Product Type:
Mature nickel-metal hydride platforms coexist with emerging solid-state lithium architectures as OEMs balance proven field data against thermal performance demands.
- Lithium-Ion:Cobalt-oxide and iron-phosphate cathode formulations deliver 150-200 Wh/kg energy density for compact surgical tools. Demand concentrates in Germany and Japan where robotic instrument manufacturers specify IEC 62133-validated cells for 500+ cycle lifespans under autoclave conditions.
- Nickel-Metal Hydride:Metal hydride anode chemistry tolerates moderate sterilization cycles with lower thermal runaway risk than lithium systems. Legacy portable monitor fleets in United States hospitals sustain procurement volume despite declining share in new platform designs.
- Lead Acid:Absorbed glass mat construction supports backup power for stationary ventilator systems where weight constraints are secondary to cost predictability.
- Polymer:Gel electrolyte lithium-polymer pouches enable form-factor flexibility in wearable infusion pumps requiring conformal battery geometries.
Lithium-ion handles the majority of throughput; polymer configurations are climbing the fastest on share as wearable drug delivery platforms expand.
Application:
Application segmentation tracks electrification intensity across device categories, from passive implantable power to active surgical instrumentation.
- Surgical Tools:Robotic graspers, electrosurgical pencils, and battery-powered scalpels demand 10-20A pulse discharge capability with instantaneous voltage recovery. German ENT microdebrider OEMs pilot solid-state cells for 134°C sterilization tolerance.
- Portable Monitors:Multi-parameter bedside and transport monitors prioritize 8-12 hour continuous operation with hot-swappable battery architectures. United States hospital procurement contracts specify FDA 510(k)-cleared power systems for crash cart deployments.
- Pacemakers:Implantable cardiac rhythm management devices require hermetic sealing and 10-year service life from primary lithium-iodine cells, limiting rechargeable adoption.
- Infusion Pumps:Ambulatory insulin and analgesic delivery systems balance compact form factors against IEC 60601-1 electrical safety compliance for patient-connected equipment.
Portable monitors sustain the largest installed base; surgical tools are expanding most quickly on share as electrification accelerates replacement cycles.
End User:
End user segmentation reveals divergent procurement authority and lifecycle management sophistication across care delivery settings.
- Hospitals:Integrated delivery networks in the United States and National Health Service trusts in England consolidate supplier contracts around full-service battery lifecycle agreements bundling cells, chargers, and refurbishment services.
- Ambulatory Surgical Centers:Freestanding outpatient facilities prioritize capital efficiency and favor certified refurbished battery packs over virgin cell purchases for instrument fleets under 50 units.
- Clinics:Primary and specialty care practices rely on distributor channel purchasing with limited in-house technical support for battery management system calibration.
- Homecare:Patient-operated portable oxygen concentrators and ventilators require consumer-grade charging interfaces with clinical-grade cell safety validation.
Hospitals command the dominant procurement volume; ambulatory surgical centers are gaining share fastest as surgical migration accelerates.
Technology:
Technology segmentation captures the shift from passive electrochemical storage to intelligent power systems with embedded diagnostics and connectivity.
- Smart Batteries:Integrated fuel gauging ICs and predictive analytics firmware enable cycle-count transparency and scheduled replacement before clinical failure. FDA guidance on wireless charging interoperability is accelerating embedded communication module adoption.
- Energy Management:Active cell balancing and thermal monitoring circuits extend cycle life 15-25% versus passive protection architectures in high-duty surgical tool applications.
- Rechargeable Systems:Conventional cabled charging docks dominate installed bases, though contact-point sterilization failures drive interest in alternative architectures.
- Wireless Charging:Resonant inductive power transfer eliminates galvanic connectors in operating theaters, reducing sterilization protocol complexity for sealed instrument enclosures.
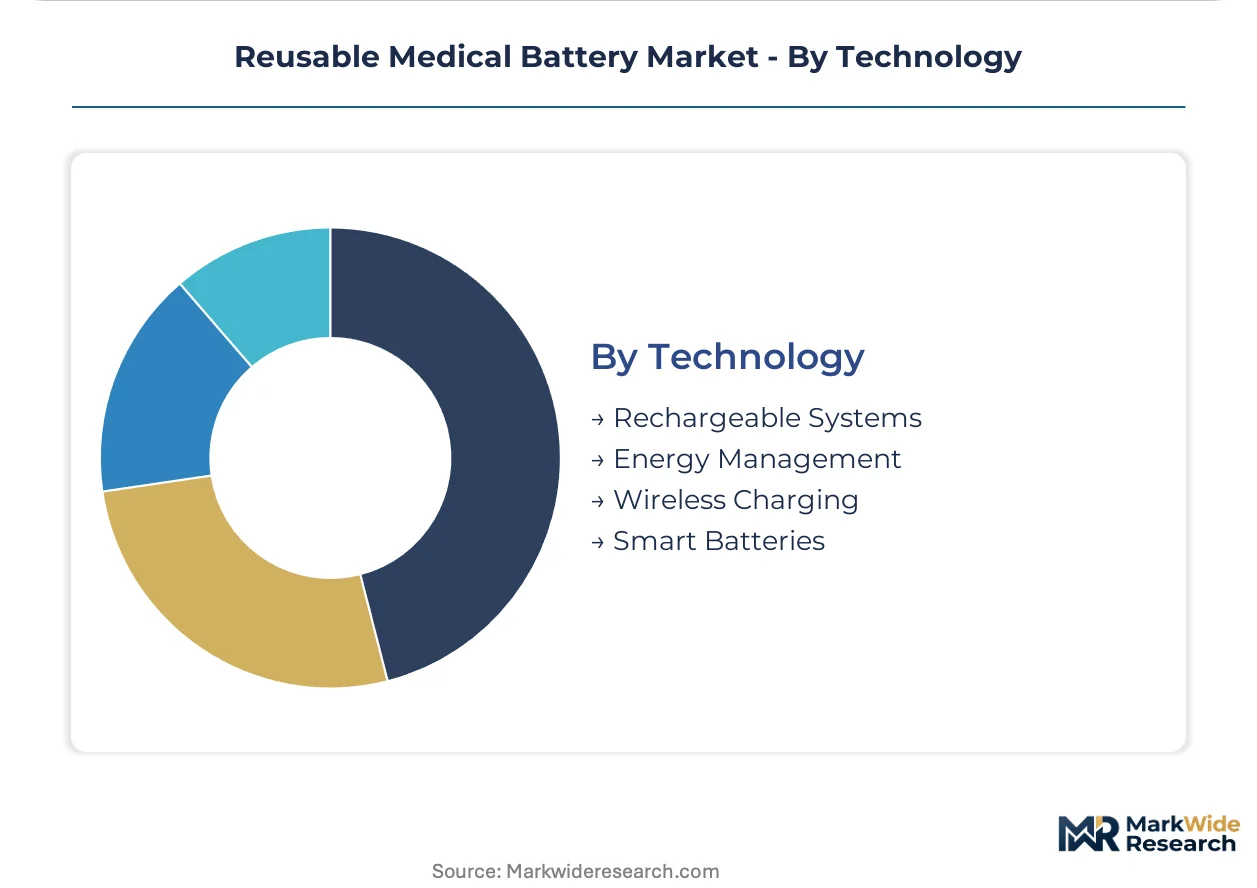
Rechargeable systems maintain the largest installed footprint; smart batteries are expanding most quickly on share as predictive maintenance priorities reshape procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement standards in Germany and Japan show minimal price elasticity, while ambulatory surgical centers in the United States and India exhibit acute cost sensitivity that favors refurbished battery platforms over virgin cell purchases.
United States
FDA 510(k) clearance requirements for rechargeable medical power systems sustain premium pricing for certified suppliers serving integrated delivery networks. The Inflation Reduction Act's domestic manufacturing incentives are reshaping cell sourcing strategies for hospital procurement officers. Boston's medical device corridor anchors refurbishment service capacity for surgical tool battery fleets.
Germany
EU MDR technical documentation mandates for validated recharge protocols are accelerating replacement demand across university hospital procurement networks. The country's national pharmaceutical regulator enforces strict biocompatibility standards for encapsulation materials under repeated sterilization. Baden-Württemberg's precision engineering clusters host solid-state lithium-polymer pilot programs for ENT microdebrider manufacturers.
Japan
METI's industrial standards for medical-grade lithium-ion cells concentrate demand among domestic OEMs specifying 500-plus cycle lifespans. PMDA guidance on active implantable accessories extends validation timelines for infusion pump power systems. The Kansai region's Osaka-based surgical instrument manufacturers are piloting wireless charging architectures for robotic platforms.
India
CDSCO regulatory alignment with international standards is opening procurement pathways for certified suppliers in tertiary care expansion. The country's central drug regulator now recognizes IEC 62133 safety certifications for imported medical batteries. Maharashtra's Mumbai-Pune corridor is emerging as a refurbishment hub serving cost-conscious ambulatory surgical centers.
China
NMPA medical device registration requirements for rechargeable power systems are tightening market access for domestic and foreign cell suppliers. The Ministry of Industry and Information Technology's dual carbon goals are pressuring manufacturers toward closed-loop battery recycling. The Yangtze River Delta's Shanghai-Suzhou cluster concentrates medical-grade lithium-ion cell fabrication for export markets.
Reusable Medical Battery Market Competitive Landscape
Military-heritage specialists and diversified industrial battery manufacturers split the market between premium surgical tool architectures and broad-scale hospital supply contracts. The vendor base organizes around three strategic archetypes: defense-aerospace heritage suppliers with sterilization-tolerant cell expertise, diversified energy storage conglomerates spanning multiple chemistries, and integrated medical device component suppliers with deep OEM relationships. Capacity expansion in solid-state cell fabrication and strategic partnerships for wireless charging module integration represent the dominant competitive moves reshaping positioning.
Within the defense-heritage tier, Ultralife Corporation and EaglePicher Technologies exemplify suppliers leveraging military-grade lithium expertise for hospital-grade power architectures. EnerSys occupies a position as the diversified industrial battery manufacturer sustaining broad manufacturing scale across nickel-metal hydride and lithium-ion chemistries. Integer Holdings Corporation anchors the integrated medical device component supplier archetype through captive battery operations serving portable monitor supply chains. These three company types collectively represent the competitive structure governing procurement relationships with German surgical tool OEMs, United States integrated delivery networks, and Japanese robotic instrument manufacturers.
| Leading Market Players |
|---|
| Ultralife Corporation |
| Saft Groupe |
| EaglePicher Technologies |
| EnerSys |
| Integer Holdings Corporation |
| Electrochem Solutions |
| Bytec Healthcare |
| KAYO Battery |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
South Korean and Chinese lithium-ion cell fabrication dominance concentrates upstream margin capture among East Asian cathode and electrolyte suppliers, forcing Western OEMs and hospital procurement networks to absorb volatility through long-term offtake contracts and certified refurbishment service bundling.
Pricing Analysis
Aftermarket refurbishment and recertification revenue streams now drive lifetime value capture for certified suppliers serving hospital integrated delivery networks. Three-tier pricing structure across FDA-cleared premium, CE-marked standard, and refurbished economy levels separates virgin cell procurement from validated reuse programs. Cost compression in economy-tier refurbished packs is intensifying because CDSCO-aligned Indian importers are undercutting Western certification overhead. Ambulatory surgical centers exhibit acute price sensitivity, while German university hospitals show minimal elasticity for sterilization-validated premium architectures.
Supply Chain Analysis
Cathode active material feedstock draws from cobalt concentrate operations in the Democratic Republic of Congo and lithium carbonate processing in Chile and Australia. Cell fabrication rests on separator membranes from Japan, electrolyte salts from Chinese chemical complexes, and precision current collectors from South Korean metallurgy plants. Single-source vulnerability concentrates in cobalt sulfate purification capacity. Distribution runs through GPO-contracted medical device distributors and direct hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical engineers with medical-grade sterilization encapsulation expertise command premium compensation and extend hiring timelines beyond eighteen months, constraining capacity expansion for OEMs and refurbishment operators alike.
For Market Incumbents: Pre-empt solid-state lithium-polymer qualification timelines by locking Baden-Württemberg precision engineering clusters for pilot production partnerships before 2027 product launches. Vertical integration into captive cell balancing and thermal monitoring IC design protects margin pools from semiconductor supply volatility. Defend hospital system relationships by embedding predictive analytics firmware ahead of FDA wireless charging interoperability guidance finalization. For New Entrants and Emerging Players: Maharashtra's Mumbai-Pune corridor offers underpenetrated refurbishment hub capacity serving cost-conscious Indian ambulatory surgical centers with CDSCO-recognized IEC 62133 certification pathways. Target tertiary care expansion in Indian states with centralized procurement standardization. Partner with established German surgical tool OEMs for private-label solid-state cell supply rather than direct hospital sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with defense-aerospace heritage suppliers possessing sterilization-tolerant lithium expertise but limited hospital channel access. Five-to-ten year viability hinges on regulatory certification moats rather than manufacturing scale alone. Watch for EU battery sustainability rule implementation timing as the inflection signal for closed-loop refurbishment operator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Article 10 technical documentation requirements extend validation timelines for infusion pump power systems. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate supplier contracts around full-service battery lifecycle agreements. |
| Wireless Charging Module Integration | FDA guidance on resonant inductive power transfer interoperability accelerates embedded communication module adoption. |
| Solid-State Cell Capacity Buildout | German ENT microdebrider OEMs pilot thermal-tolerant architectures for 134°C sterilization tolerance requirements. |
| Refurbishment Service Expansion | EU battery sustainability rules mandate carbon footprint disclosure and recycled content thresholds for closed-loop operators. |
Research Methodology
The analysis maps lithium-ion, nickel-metal hydride, and solid-state lithium-polymer sub-sectors, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and surgical tool OEM product directors. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation registries, CDSCO import certification records, and METI industrial standard filings. Bottom-up cell chemistry demand modeling and top-down hospital capital equipment procurement surveys triangulate volume estimates.
Assumptions held fixed include EU MDR enforcement timelines and FDA wireless charging guidance trajectory, while lithium cobalt oxide input volatility and CDSCO regulatory alignment pace were varied across sensitivity scenarios. Segmentation dimensions span chemistry type, application intensity, end-user procurement sophistication, and embedded intelligence tier. CAGRs derive from installed base replacement cycle compression and electrification penetration curves. Forecast inputs include surgical tool OEM production schedules and hospital materials management department consolidation patterns.
Practitioners should monitor lithium carbonate spot market movements and EU battery sustainability rule implementation timing for early signals of margin pool redistribution. Forecasts reflect these documented assumptions regarding regulatory enforcement and technology migration. Cross-checking against hospital procurement database contract values and GPO pricing benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Walking Assist Devices Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Posture Correction Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Oxygen Generator Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Memory Implants Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Veterinary Ventilators Market