
 Sweet Potato Chips Market | 2026-2036
Sweet Potato Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Potato Chips Market Insights
EU Green Deal sustainability targets for food production are expanding procurement criteria for snack manufacturers sourcing root vegetable inputs. PepsiCo leverages its global agricultural partnerships to secure non-GMO sweet potato supply chains across multiple continents. Kettle Brand anchors its competitive stance through small-batch kettle-cooking methods that preserve fiber content and mineral density. Calbee dominates Japanese and Asian export markets with specialized frying techniques that reduce oil absorption rates.
Sweet potato chips are thin-sliced tuber pieces fried, baked, or vacuum-cooked to achieve crisp texture, typically containing 30-40% less fat than conventional potato chips while delivering higher vitamin A and dietary fiber content. The product serves retail consumers seeking nutrient-dense convenience foods and food service operators requiring premium garnish or side-dish components. Plain and salted varieties sustain the largest revenue share due to broad demographic acceptance, while spicy and barbecue segments attract younger consumers seeking flavor intensity. Supermarkets and online channels capture the fastest volume growth as direct-to-consumer subscription models and grocery delivery platforms reshape snack purchasing patterns.
The FDA enforces Nutrition Facts panel requirements and allergen labeling standards that influence packaging claims and ingredient transparency for sweet potato chip producers. EFSA acrylamide monitoring protocols and EU MDR-aligned food contact material rules constrain frying temperatures and packaging substrate selection. USDA organic certification and Non-GMO Project verification create tiered market access thresholds that differentiate premium positioning from conventional offerings. Stakeholders must monitor evolving clean-label requirements and carbon footprint disclosure mandates that will determine supplier qualification and retail shelf access.
Market Dynamics
Clean-label regulatory mandates and acrylamide reduction protocols are forcing manufacturers to reengineer frying temperatures, oil selection, and packaging substrates across the sweet potato chip supply chain.
Growth Catalysts
- FDA Nutrition Facts modernization:Updated labeling requirements for added sugars and serving sizes push brands toward simpler ingredient decks that resonate with wellness-focused retail buyers.
- EU EFSA acrylamide benchmarks:Strict monitoring protocols for processed potato products accelerate adoption of vacuum-frying and lower-temperature cooking methods that preserve nutrient density.
- Millennial and Gen Z snack substitution:Younger demographics in the United States systematically replace conventional potato chips with root vegetable alternatives perceived as functional foods.
Market Restraints
- Input cost volatility:Sweet potato harvest sensitivity to drought conditions in North Carolina and California generates raw material price instability that compresses processor margins.
- Supply concentration risk:Premium non-GMO tuber sourcing clusters among a limited network of contract growers in the southeastern United States, creating bottleneck vulnerability.
- Technical limitation:Achieving shelf-stable crispness without synthetic preservatives remains challenging for clean-label formulations targeting extended retail distribution.
Strategic Opportunities
- Underpenetrated European markets:Germany and the Netherlands show nascent demand for kettle-cooked root vegetable snacks, with specialty retail channels actively seeking import partnerships.
- Direct-to-consumer subscription models:Curated snack boxes and grocery delivery platforms enable premium positioning bypassing traditional supermarket slotting fee structures.
- EU Green Deal procurement incentives:Sustainability-linked sourcing criteria favor manufacturers demonstrating carbon footprint transparency and regenerative agricultural partnerships.
Industry Challenges
- Specialized equipment capex:Vacuum-frying and continuous kettle systems require seven-figure capital commitments that strain mid-tier processor expansion timelines.
- USDA organic certification complexity:Multi-year transition periods for contracted acreage and dual-crop handling protocols delay premium product line launches.
- Acrylamide testing protocol standardization:Inconsistent laboratory methodologies across jurisdictions create compliance documentation friction for export-oriented facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Potato Chips Market |
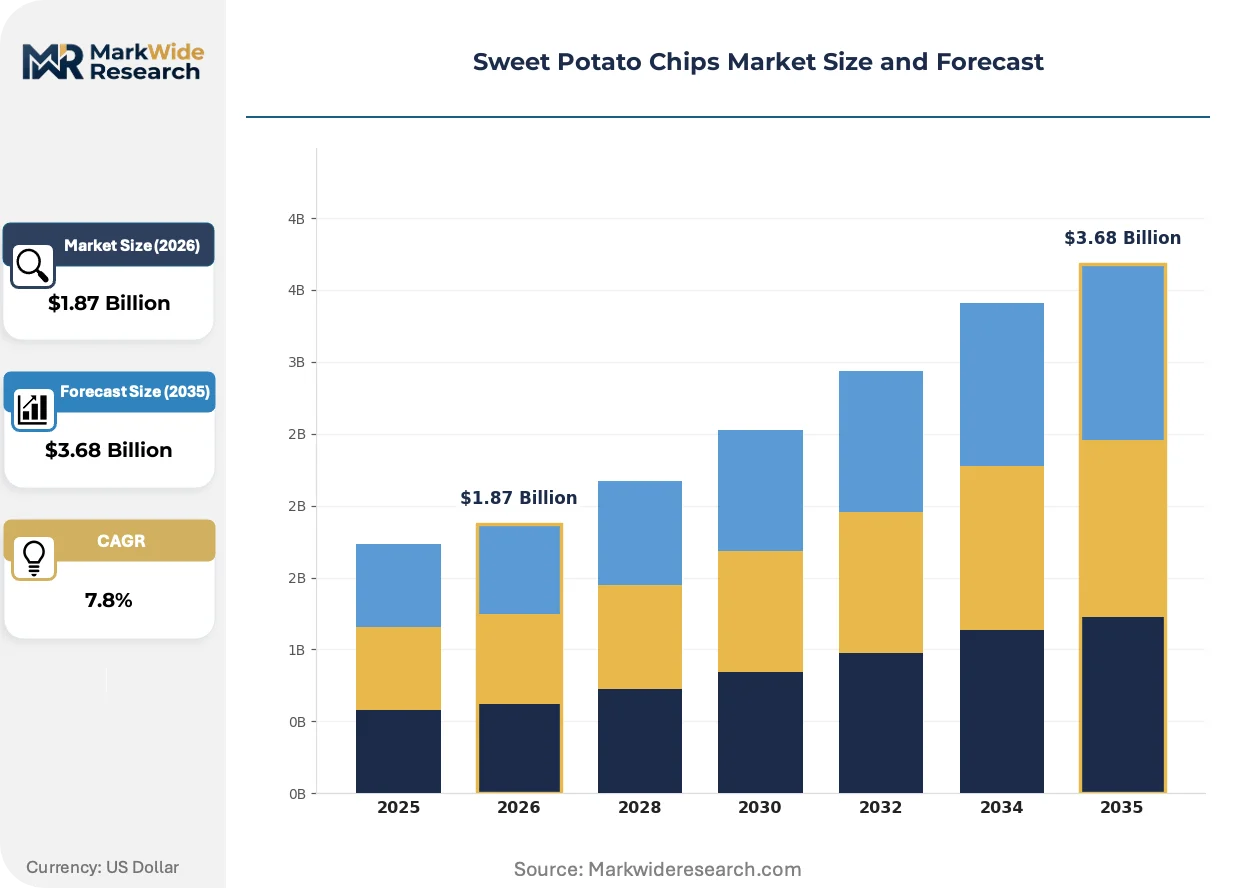
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Spicy, Barbecue, Salted Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores Packaging Type: Bag, Box, Pouch, Canister End User: Retail Consumers, Food Service, Restaurants, Snack Manufacturers |
| Companies Covered | PepsiCo, Kettle Brand, Utz Quality Foods, Shearer's, Calbee, Hain Celestial, Terra, Cape Cod, Pringles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Potato Chips Market Trends and Innovations
Processing technology convergence and regulatory pressure on thermal cooking methods are accelerating equipment upgrades and formulation science investment across the sector.
Vacuum-frying technology operates at reduced atmospheric pressure to lower oil boiling points, enabling crisp texture development at temperatures that minimize acrylamide formation. Premium snack producers in Japan and South Korea have pioneered commercial-scale deployment, and this method is expanding into North American contract manufacturing facilities serving private-label retailers.
EU EFSA acrylamide monitoring protocols now enforce benchmark levels for potato-based snacks sold in member states, with non-compliant batches subject to recall and public disclosure requirements. Manufacturers are responding by retrofitting production lines with real-time temperature monitoring and rapid cooling systems, particularly affecting high-volume exporters targeting German and French retail chains.
Subscription-based snack curation has displaced impulse purchasing as the primary customer acquisition channel for emerging brands, with millennial households in urban United States markets prioritizing discovery and convenience over traditional grocery aisle browsing. Direct-to-consumer platforms now capture disproportionate growth in spicy and barbecue flavor segments where trial risk is lower through curated sampling.
Sweet Potato Chips Market Segmentation
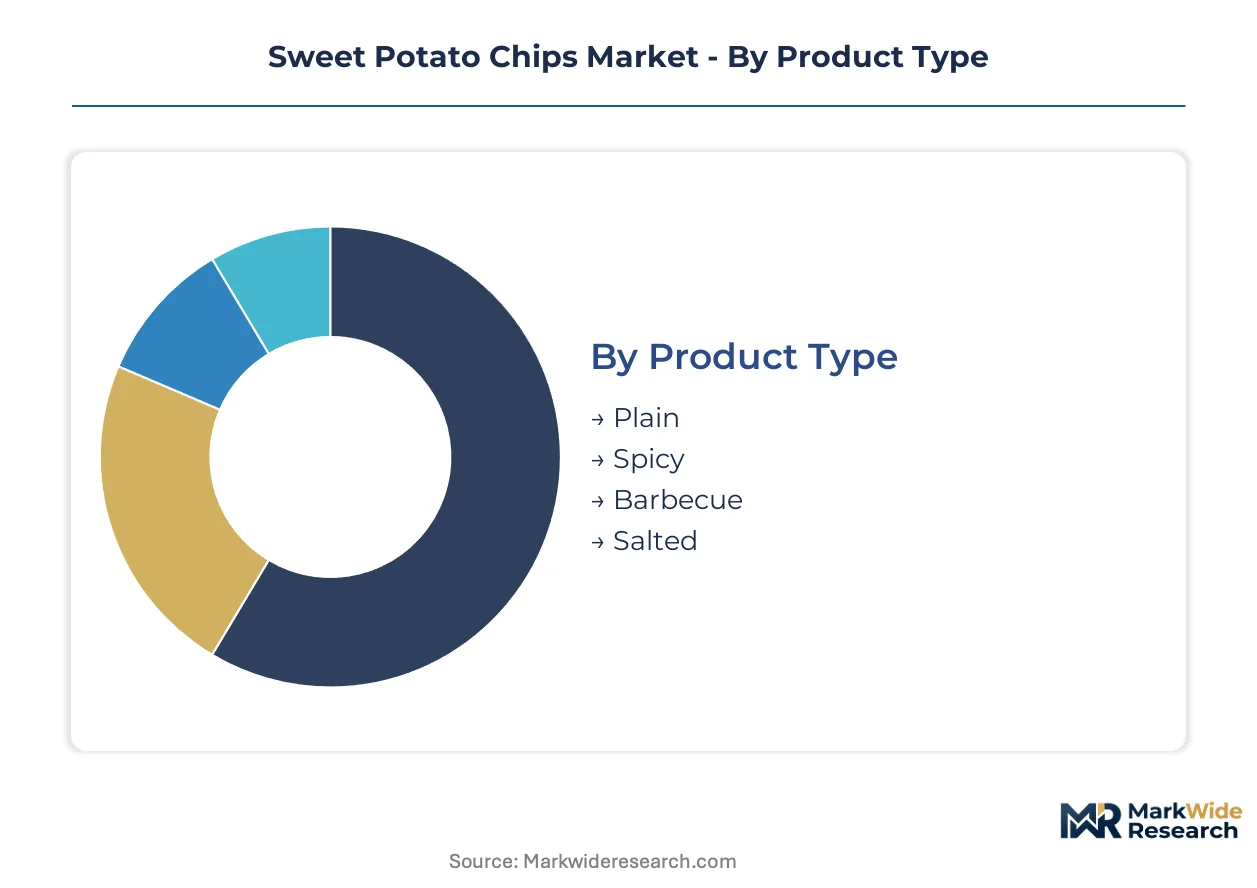
Sweet potato chip producers calibrate equipment, formulation, and channel strategy against distinct segment requirements. Capital allocation decisions diverge sharply across product types, packaging formats, and end-user specifications.
Product Type:
Capital intensity peaks in flavored varieties requiring additional processing lines for seasoning application and quality control.
- Plain:Single-ingredient formulations minimize processing complexity and maximize production throughput. Mass-market retail buyers in the United States favor this variety for its clean-label positioning and lower price point, though margin compression limits reinvestment capacity.
- Salted:Light sodium application adds minimal equipment overhead while broadening demographic appeal. German and Dutch retail chains prioritize this segment for private-label programs targeting health-conscious snack substitution.
- Spicy:Chili and pepper coatings demand dedicated blending systems and allergen-control protocols. Younger consumers in urban United States markets drive trial through direct-to-consumer subscription channels.
- Barbecue:Complex seasoning matrices require precision coating drums and extended drying tunnels. Flavor innovation in this segment attracts venture-backed emerging brands seeking differentiation in crowded snack aisles.
Plain absorbs the bulk of installed capacity; Barbecue is expanding most quickly.
Distribution Channel:
Customer acquisition economics vary dramatically between physical retail slotting fees and digital marketing spend.
- Supermarkets:National chains command placement fees exceeding six figures per SKU, favoring established processors with balance sheet capacity. United States grocery consolidation into regional megachains intensifies negotiation leverage.
- Online:Subscription models and grocery delivery platforms enable premium pricing without slotting fee burden. Millennial households in metropolitan United States areas show highest repeat purchase rates for kettle-cooked varieties.
- Specialty Stores:Curated assortments in natural food retailers reward organic certification and transparent sourcing narratives. Japanese import specialists in European urban centers create niche demand for vacuum-fried products.
- Convenience Stores:Impulse-driven purchasing favors single-serve packaging and prominent shelf positioning. California and Texas fuel station networks represent concentrated volume opportunity for salted and plain varieties.
Supermarkets retain the greatest share of volume throughput; Online channels are climbing the fastest.
Packaging Type:
Material selection and shelf-life engineering drive differentiated machinery investments across format types.
- Bag:Flexible film structures dominate retail shelf presence with lowest unit cost. Multi-layer barrier requirements for oil oxidation control complicate recycling compliance under EU packaging regulations.
- Pouch:Stand-up configurations with resealable zippers command premium placement in specialty retail. Japanese convenience store operators favor this format for portion-controlled snacking occasions.
- Canister:Rigid paperboard cylinders protect product integrity through extended distribution cycles. Food service operators in United States casual dining chains specify this format for back-of-house storage efficiency.
- Box:Corrugated secondary packaging enables bulk shipment to subscription fulfillment centers. Direct-to-consumer brands in Netherlands and Germany utilize this format for carbon footprint disclosure marketing.
Bag formats account for the majority of production line configuration; Pouch specifications are gaining share fastest.
End User:
Specification requirements diverge between retail-ready packaging and industrial-scale ingredient supply.
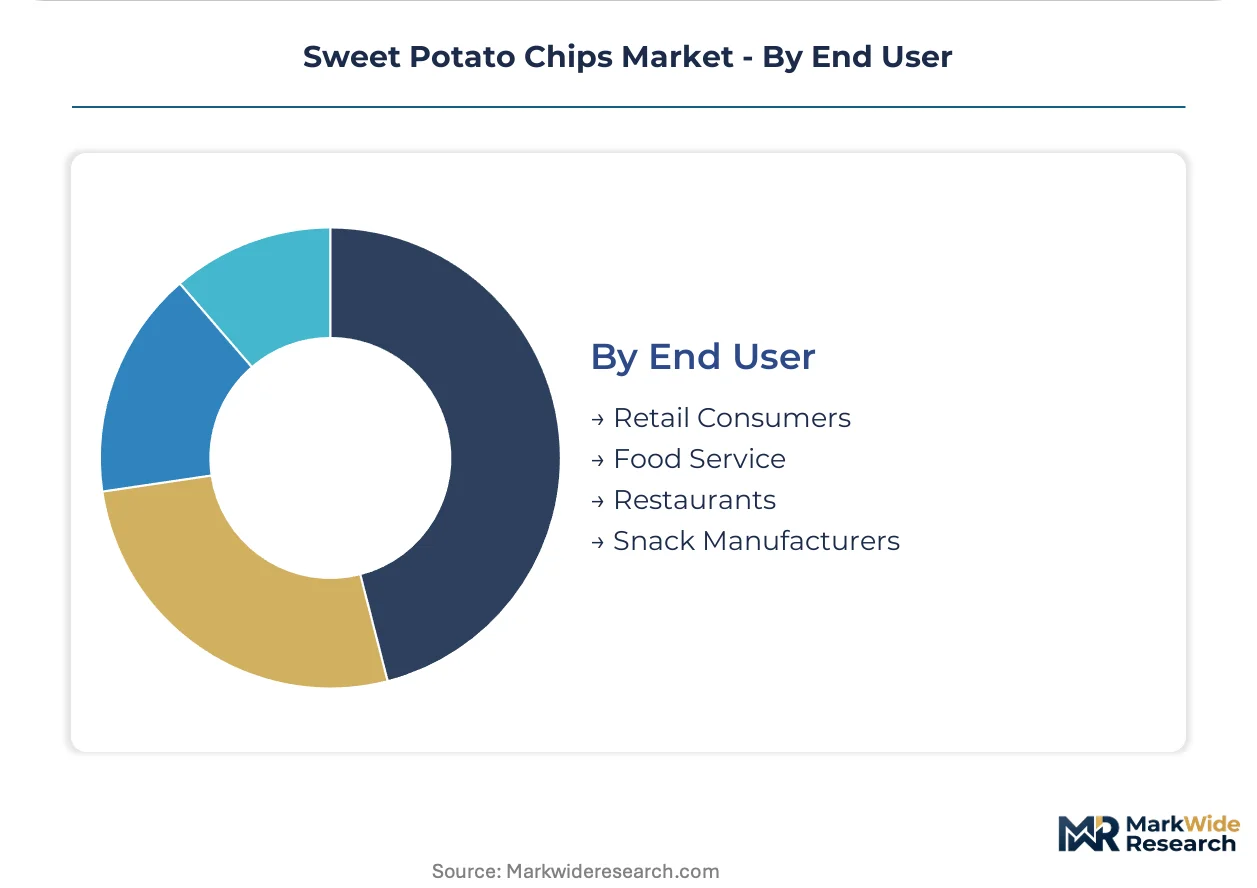
- Retail Consumers:Individual portion sizes and nutritional panel transparency dominate purchasing criteria. Clean-label claims and Non-GMO Project verification unlock placement in United States natural food channels.
- Restaurants:Bulk formats and extended holding stability support garnish and side-dish applications. Fast-casual chains in California specify precise slice thickness for plate presentation consistency.
- Food Service:Institutional distributors demand case-quantities with uniform seasoning coverage. School nutrition programs in the United States increasingly specify lower-sodium formulations for compliance with federal guidelines.
- Snack Manufacturers:Ingredient-grade supply for co-manufacturing and private-label assembly requires bulk density optimization. European contract manufacturers source vacuum-fried inputs for premium product line extensions.
Retail Consumers represent the largest addressable base; Restaurants are seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Carolina's Research Triangle corridor anchors North American sweet potato chip processing, with contract farming networks extending through the coastal plain toward Greenville and New Bern.
United States
Millennial households in Austin and Denver drive direct-to-consumer subscription volume for spicy and barbecue varieties. FDA Nutrition Facts modernization mandates cleaner ingredient decks that favor kettle-cooked production methods. California's Central Valley processors retrofit lines with vacuum-frying equipment to meet export acrylamide standards.
Japan
Urban convenience store operators in Tokyo and Osaka specify pouch-format portion control for commuter snacking occasions. METI guidelines on processed food safety shape domestic frying temperature protocols. Calbee's Chiba Prefecture facilities supply vacuum-fried inputs to European contract manufacturers seeking premium line extensions.
Germany
Natural food retailers in Berlin and Hamburg actively source organic-certified root vegetable snacks for private-label programs. EU EFSA acrylamide monitoring protocols enforce benchmark levels that disqualify high-temperature fried imports. Bavarian distributors negotiate sustainability-linked procurement contracts tied to EU Green Deal carbon disclosure requirements.
Netherlands
Amsterdam-based subscription fulfillment centers handle bulk corrugated shipments for curated snack boxes targeting Belgian and French buyers. Dutch agricultural cooperatives pilot regenerative sweet potato cultivation to qualify for EU Green Deal incentives. Rotterdam port logistics clusters enable re-export of Japanese vacuum-fried products to German retail chains.
United Kingdom
London specialty grocers demand transparent sourcing narratives and Non-GMO Project verification for premium shelf placement. Post-Brexit import documentation friction complicates EU-sourced chip shipments through Dover-Calais corridors. Midlands-based co-manufacturers invest in continuous kettle systems to serve supermarket private-label programs.
Sweet Potato Chips Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with organic and non-GMO verification commanding placement in natural food channels while conventional formulations compete on price in mass retail. The vendor base spans multinational snack conglomerates with agricultural partnerships, regional kettle-cooking specialists, and Asian export-oriented processors with proprietary frying technologies. Three archetypes dominate: diversified CPG portfolios leveraging global supply chains, craft-scale operators emphasizing small-batch production narratives, and equipment-integrated manufacturers controlling frying process patents. Capacity expansion and sustainability certification partnerships represent the dominant competitive moves reshaping supplier qualification thresholds.
Among diversified CPG portfolios, PepsiCo and Hain Celestial exemplify scale-driven archetypes with balance sheet capacity for six-figure supermarket slotting fees and multi-continental agricultural contracting. Kettle Brand occupies a position within the craft-scale tier, anchoring competitive differentiation through small-batch production narratives that resonate with clean-label retail buyers. Calbee represents the equipment-integrated Asian export model, with proprietary frying technologies reducing oil absorption rates for premium positioning in European and North American specialty channels.
| Leading Market Players |
|---|
| PepsiCo |
| Kettle Brand |
| Utz Quality Foods |
| Shearer's |
| Calbee |
| Hain Celestial |
| Terra |
| Cape Cod |
| Pringles |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap processors in North Carolina and California anchor supply-side discipline through multi-generational agricultural contracting that buffers spot-market volatility and sustains premium pricing power against private-label commoditization.
Pricing Analysis
Value-based pricing anchored to clean-label certification tiers stratifies the market across premium organic, standard non-GMO, and conventional economy levels. USDA organic and Non-GMO Project verification command shelf-price premiums of 40-60% above conventional equivalents, while mass-market private-label programs compete on volume scale with minimal brand markup. Pricing pressure stems from drought-driven input cost volatility in southeastern U.S. growing regions, compressing processor margins most acutely in the conventional tier. Food service operators and institutional buyers exhibit highest price sensitivity due to standardized procurement protocols, whereas direct-to-consumer subscription channels absorb premium positioning with lower elasticity.
Supply Chain Analysis
Certification gating through USDA organic transition periods and EU EFSA acrylamide compliance documentation constrains supplier qualification and creates tiered market access. Raw material sourcing concentrates in the United States, Japan, and the Netherlands, with specialized vacuum-frying equipment dependencies resting on Japanese and South Korean manufacturing bases. Sweet potato tuber supply draws from contract farming networks in North Carolina and California, exposing processors to climate-driven yield variability and concentrated geographic risk. Distribution runs through supermarket retail chains commanding six-figure slotting fees, direct-to-consumer subscription fulfillment centers, and food service institutional distributors serving restaurant and school nutrition programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum-frying technology is displacing legacy high-temperature kettle methods as the dominant production paradigm, reshaping capital allocation priorities and supplier qualification thresholds across the sector.
For Market Incumbents: Lock in regenerative agricultural partnerships with southeastern U.S. contract growers to secure non-GMO supply chains against climate volatility and emerging competitor sourcing. Prioritize retrofitting production lines with real-time temperature monitoring systems to meet EU EFSA acrylamide benchmarks and maintain export access to German and French retail channels. Certification investment in USDA organic and EU organic equivalence represents the critical lever for defending premium shelf positioning against private-label encroachment. For New Entrants and Emerging Players: Capture underpenetrated demand in German and Dutch specialty retail channels where organic-certified root vegetable snacks face limited domestic supply and active importer recruitment. The direct-to-consumer subscription segment offers lowest customer acquisition friction for spicy and barbecue flavor varieties, enabling trial-based market entry without six-figure supermarket slotting fee burdens. A curated sourcing narrative emphasizing transparent agricultural partnerships unlocks placement in natural food retailers and urban millennial households. For Investors and Strategic Acquirers: Distressed-cycle entries favor equipment-integrated processors with proprietary vacuum-frying patents in Japan and South Korea, where technology licensing revenue streams diversify beyond commodity snack margins. Long-term viability over a multi-year horizon hinges on sustainability-linked procurement contracts tied to EU Green Deal carbon disclosure requirements and regenerative agricultural verification. The signal to watch is accelerating supermarket consolidation into regional megachains, which will intensify slotting fee negotiation leverage and favor balance-sheet-heavy incumbents capable of absorbing placement cost inflation.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Frying Equipment Deployment | Lower-temperature processing preserves nutrient density while meeting EU EFSA acrylamide monitoring protocols. |
| Regenerative Agricultural Partnerships | Carbon footprint transparency unlocks EU Green Deal procurement incentives and sustainability-linked retail contracts. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass supermarket slotting fees and enable premium pricing for flavored varieties. |
| Organic Certification Investment | USDA organic and Non-GMO Project verification differentiate placement in natural food retail channels. |
| European Import Partnership Development | German and Dutch specialty retailers actively seek vacuum-fried root vegetable snacks for private-label programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with snack brand managers, category buyers at supermarket chains, sweet potato processors, agricultural cooperative directors, and food service procurement officers. FDA Nutrition Facts modernization documentation, EU EFSA acrylamide monitoring protocols, and USDA organic certification databases provided regulatory boundary conditions. Bottom-up production capacity modeling triangulated against top-down retail audit data from Nielsen and Circana to validate volume estimates.
Granularity-level modeling operated at product-type, distribution-channel, packaging-format, and end-user dimensions, with geographic disaggregation to country-level for the United States, Japan, Germany, Netherlands, and United Kingdom. CAGRs across the analysis window derived from segment-specific volume trajectories and price-index movements, incorporating vacuum-frying equipment adoption curves and EU Green Deal procurement incentive timelines as technology-transition inputs.
The model holds under sustained regulatory enforcement of acrylamide benchmarks and clean-label disclosure requirements; deviation in FDA or EFSA protocol relaxation would shift competitive advantage toward conventional high-temperature processors. Forecasts reflect assumptions regarding drought frequency in southeastern U.S. growing regions and subscription channel growth sustainability. A model refresh is warranted upon material change in EU packaging recycling regulations or supermarket consolidation patterns affecting slotting fee structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Snack Products Market
Snacks
Plant-Based Snacks Market
Snacks
Crackers Market
Snacks
Refrigerated Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Organic Snack Food Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
No Fat Snacks Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Spain Energy Bar Market
Snacks
Fruit and Vegetable Chips Market
Snacks
North America Baked Savory Snacks Market
Snacks
Global Vegetable Chips Market
Snacks
Low Calorie Crackers Market