
 Europe Extruded Snack Food Market | 2026-2036
Europe Extruded Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Extruded Snack Food Market Intelligence
Premium clean-label specifications is unwinding commodity-grade volume dominance across European extruded snack aisles. Mondelez International Inc. leverages its pan-European distribution infrastructure to sustain shelf-space priority in multiple countries. Orkla ASA anchors Nordic private-label supply with backward integration into seasoning and coating operations. PepsiCo Inc. competes through direct-to-retailer analytics partnerships that optimize replenishment cycles for high-velocity SKUs.
Extruded snack food denotes products manufactured by forcing moistened cereal or starch-based dough through a die under elevated temperature and pressure, then expanding upon exit to create a porous, crunchy texture with bulk densities typically below 0.15 g/cm³. The process enables precise control of oil absorption, structural integrity, and flavor retention for shelf-stable consumption. Potato snacks and corn snacks occupy mature volume positions with established margin pools tied to commodity input hedging, while rice snacks and multigrain snacks attract reformulation investment as EFSA-guided nutritional profiling reshapes permissible health claims. End-user segmentation shows retail consumers commanding baseline throughput, whereas food service and nutritional programs represent faster-growing channels where portion control and fortified formulations command price premiums.
EFSA nutritional labeling standards, EU Green Deal packaging directives, and national trans-fat caps under EFSA coordination collectively constrain permissible ingredient palettes and mandate recyclable or compostable packaging transitions by specified deadlines. REACH chemical compliance and RoHS-adjacent material standards further govern equipment coatings and processing aids entering food-contact surfaces. Stakeholders must monitor evolving EFSA sodium reduction benchmarks and extended producer responsibility schemes to anticipate reformulation timelines and capital allocation for extrusion line upgrades.
Market Dynamics
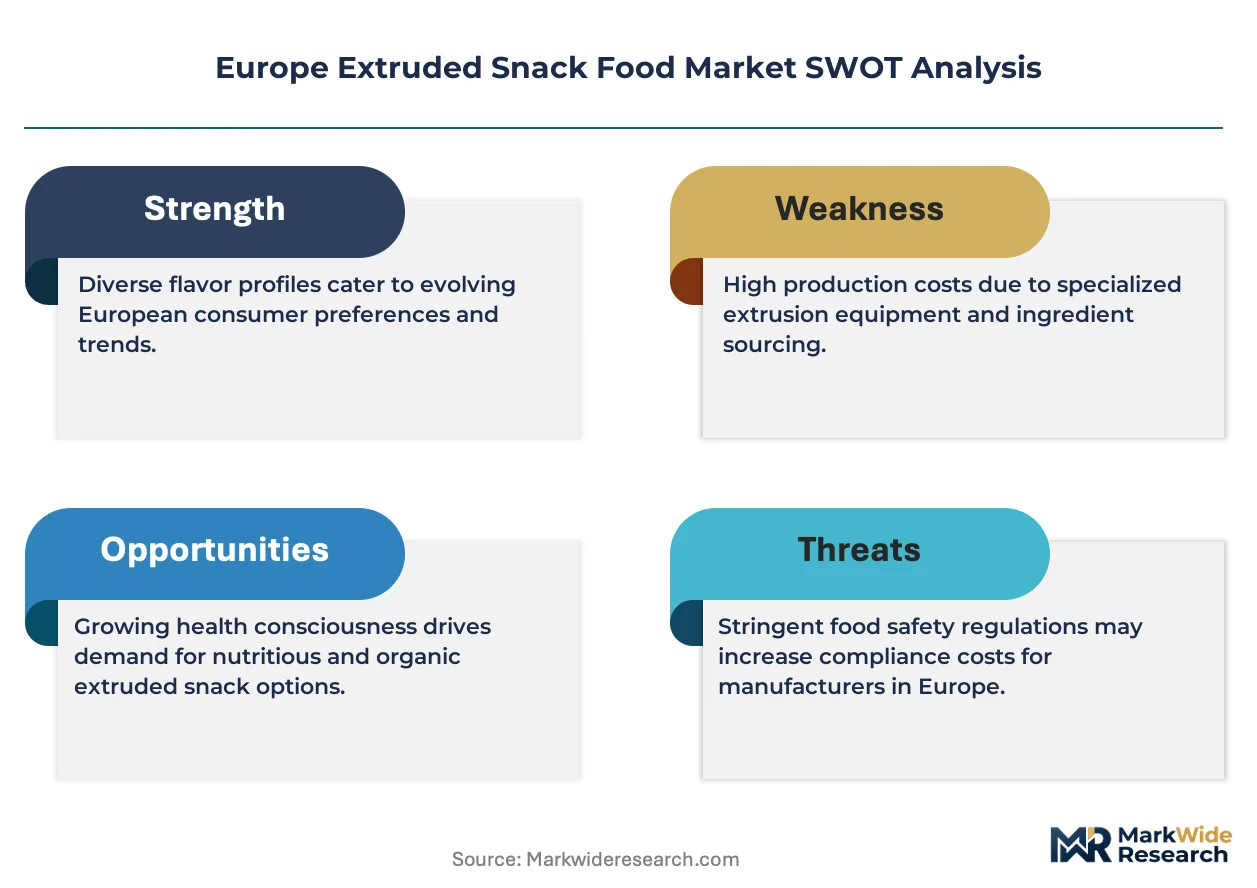
EFSA sodium reduction benchmarks and EU Green Deal packaging mandates are compressing formulation flexibility while forcing capital redeployment into extrusion line upgrades and sustainable material transitions across European manufacturing footprints.
Growth Catalysts
- EFSA nutritional profiling:Permissible health claims for reformulated multigrain and rice snack variants are expanding addressable shelf space in premium retail channels.
- Germany's discount retail channel:Aldi and Lidl's private-label expansion is sustaining volume throughput for high-velocity potato and corn snack SKUs with optimized replenishment cycles.
- Extrusion precision technology:Advanced die designs enabling oil absorption control below 15% are unlocking clean-label positioning previously unattainable with commodity processes.
Market Restraints
- Palm oil price volatility:Input cost swings for the primary frying medium are compressing margin pools in mass-market potato snack categories where hedging coverage remains incomplete.
- Packaging material concentration:Dependence on a narrow supplier base for compostable film laminates compliant with EU Green Deal deadlines creates bottleneck risk for Q4 2025 transitions.
- REACH compliance friction:Seasoning and coating additive approvals are extending reformulation timelines by 12-18 months for novel flavor introductions.
Strategic Opportunities
- France's artisan-positioned segment:Premium clean-label specifications in Parisian and Lyon retail clusters command 40-60% price premiums over standard extruded products.
- Food service portion control:Single-serve fortified formats for institutional nutrition programs represent underexploited volume with higher per-unit economics than retail.
- Extended Producer Responsibility schemes:Early compliance with national packaging fee structures in the Netherlands and Belgium is creating first-mover shelf access advantages.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized process optimization expertise for low-bulk-density texture control is concentrated among retiring cohorts in northern Italy and southern Germany.
- Legacy equipment retrofit complexity:Integrating recyclable packaging handling into existing high-speed lines requires 18-24 month downtime windows that disrupt seasonal production planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Extruded Snack Food Market |
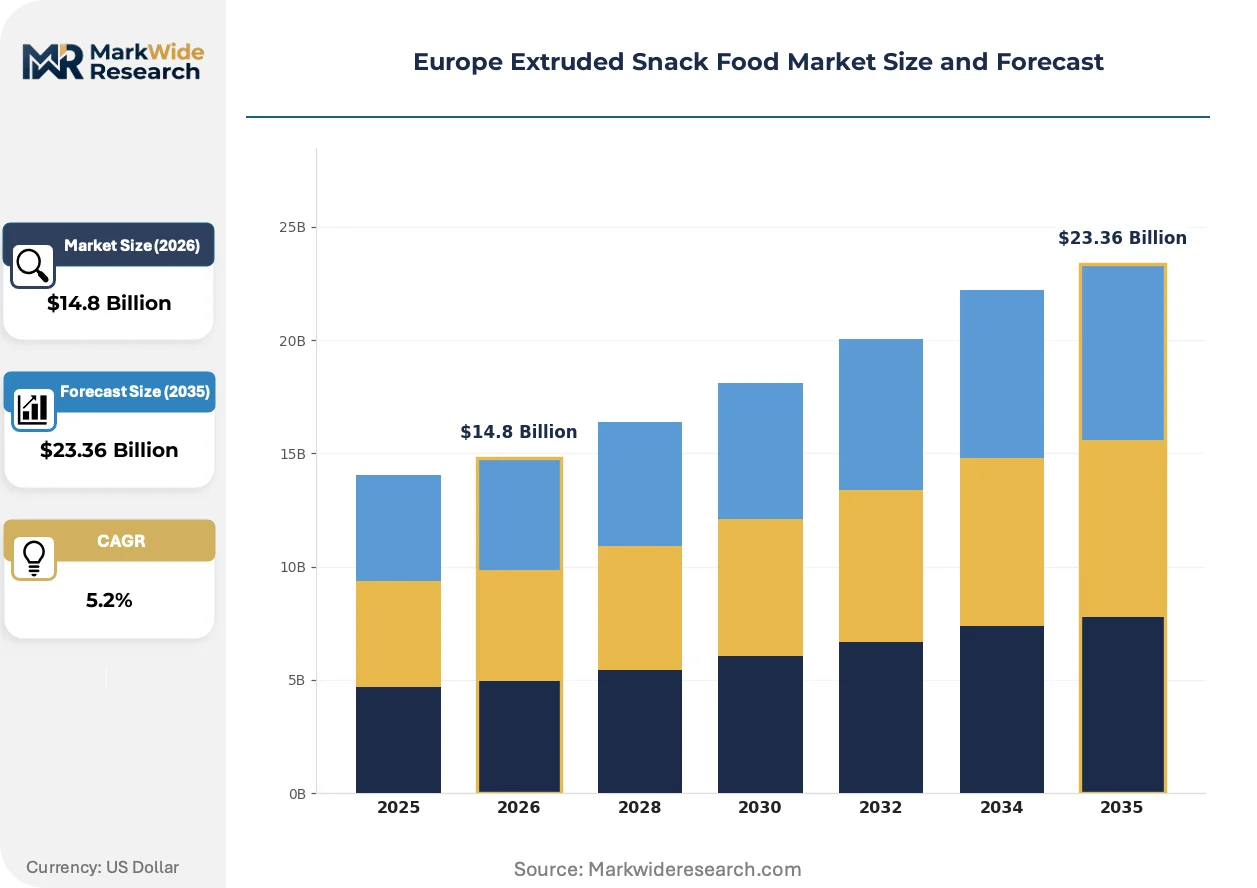
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Snacks, Corn Snacks, Rice Snacks, Multigrain Snacks End User: Retail Consumers, Food Service, Online Buyers, Nutritional Programs Packaging Type: Bags, Pouches, Boxes, Bulk Packaging Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Specialty Stores |
| Companies Covered | Mondelez International Inc., Orkla ASA, PepsiCo Inc., Estrella Maarud AS, Walkers Snack Foods Ltd., Intersnack Group GmbH & Co. KG, Lorenz Snack-World GmbH, Zweifel Pomy-Chips AG, Kellanov (formerly Kellogg Company), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Extruded Snack Food Market Strategic Shifts & Innovations
Clean-label reformulation and sustainable packaging transitions are redrawing competitive boundaries between commodity volume players and premium-positioned specialists across European extruded snack aisles.
Twin-screw extrusion with in-barrel flavor injection is bifurcating the technology landscape between high-flexibility batch systems and continuous high-output lines. Mid-tier manufacturers in Poland and Spain are adopting hybrid configurations to bridge both production modes. This capability spread is compressing the middle market as specialists defend premium positioning while scale players consolidate commodity volume.
EU Green Deal packaging directives mandating recyclable or compostable materials by specified deadlines are eliminating multi-layer plastic laminates from permissible food-contact applications. German and French retailers are accelerating compliance verification through third-party certification requirements. Rice snack and multigrain categories face the tightest reformulation windows due to higher moisture sensitivity in sustainable film structures.
Direct-to-retailer data partnerships are displacing traditional distributor-led replenishment in high-velocity channels. PepsiCo's analytics collaborations with Tesco and Carrefour are compressing order cycles from weekly to daily intervals. This pattern is most visible in the UK and Netherlands where grocery e-commerce penetration has crossed threshold levels for dynamic inventory management.
Europe Extruded Snack Food Market Segmentation
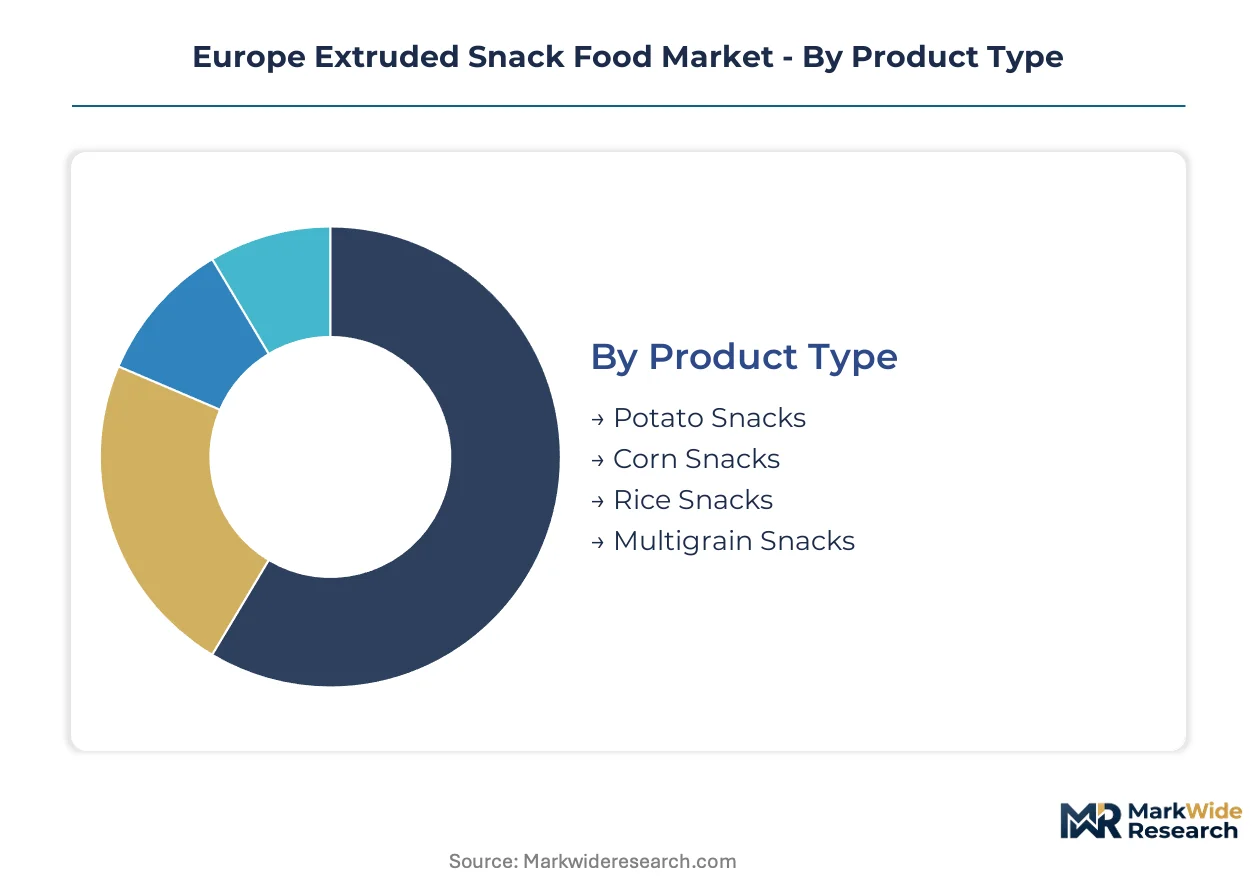
Segmentation in Europe's extruded snack food market reveals how EFSA nutritional profiling and EU Green Deal mandates are reshaping competitive boundaries across product formulations, distribution channels, and end-user applications. Understanding these divisions exposes where reformulation investments concentrate and which packaging transitions face the tightest compliance windows.
Product Type:
Substitute pressure from clean-label alternatives and nutritional reformulation is most acute in legacy starch categories where commodity positioning dominates shelf space.
- Potato Snacks:These products rely on dehydrated potato flake or fresh potato dough extrusion with bulk densities typically reaching 0.08-0.12 g/cm³. Germany's discount retail channel sustains volume throughput for these SKUs through Aldi and Lidl private-label programs with optimized replenishment cycles.
- Corn Snacks:Maize-based formulations permit the lowest oil absorption profiles in commodity extrusion, typically 12-18% fat content. France's premium artisan-positioned segment is absorbing reformulated corn variants with heritage grain positioning that commands substantial price premiums over standard offerings.
- Rice Snacks:Higher moisture sensitivity in sustainable film structures is compressing reformulation timelines for this category.
- Multigrain Snacks:EFSA-guided nutritional profiling is expanding permissible health claims for these variants in premium retail channels.
Potato snacks anchor the volume base while multigrain snacks gain share at the steepest rate.
End User:
Margin tier differentiation separates institutional procurement with fortified specifications from mass retail velocity plays.
- Retail Consumers:Baseline throughput depends on convenience-oriented purchasing across Germany, France, and the UK with on-the-go format expansion driving SKU proliferation.
- Food Service:Single-serve fortified formats for institutional nutrition programs command higher per-unit economics than retail equivalents. Portion control specifications and nutrient fortification requirements in French and Belgian school feeding contracts are creating dedicated supply relationships.
- Online Buyers:Grocery e-commerce penetration in the UK and Netherlands has crossed threshold levels for dynamic inventory management with daily replenishment intervals.
- Nutritional Programs:Public health procurement in Nordic countries is mandating sodium reduction benchmarks ahead of EFSA timelines.
Retail consumers anchor the volume base while food service gains share at the steepest rate.
Packaging Type:
Supply concentration in compostable film laminates is creating bottleneck risk for Q4 transitions across multiple format categories.
- Bags:Multi-layer plastic laminates are being eliminated from permissible food-contact applications under EU Green Deal deadlines. German and French retailers are accelerating compliance verification through third-party certification requirements.
- Pouches:Stand-up flexible formats face the tightest reformulation windows due to moisture barrier requirements in sustainable film structures. Rice snack and multigrain categories are particularly exposed to shelf-life compression during this transition.
- Boxes:Secondary packaging for premium assortments is shifting toward recycled cardboard with reduced plastic windowing.
- Bulk Packaging:Food service and institutional channels are adopting returnable container systems in the Netherlands and Belgium under extended producer responsibility schemes.
Bags anchor the volume base while pouches gain share at the steepest rate.
Distribution Channel:
Customer type concentration in discount retail is compressing margin pools while specialty channels defend premium positioning.
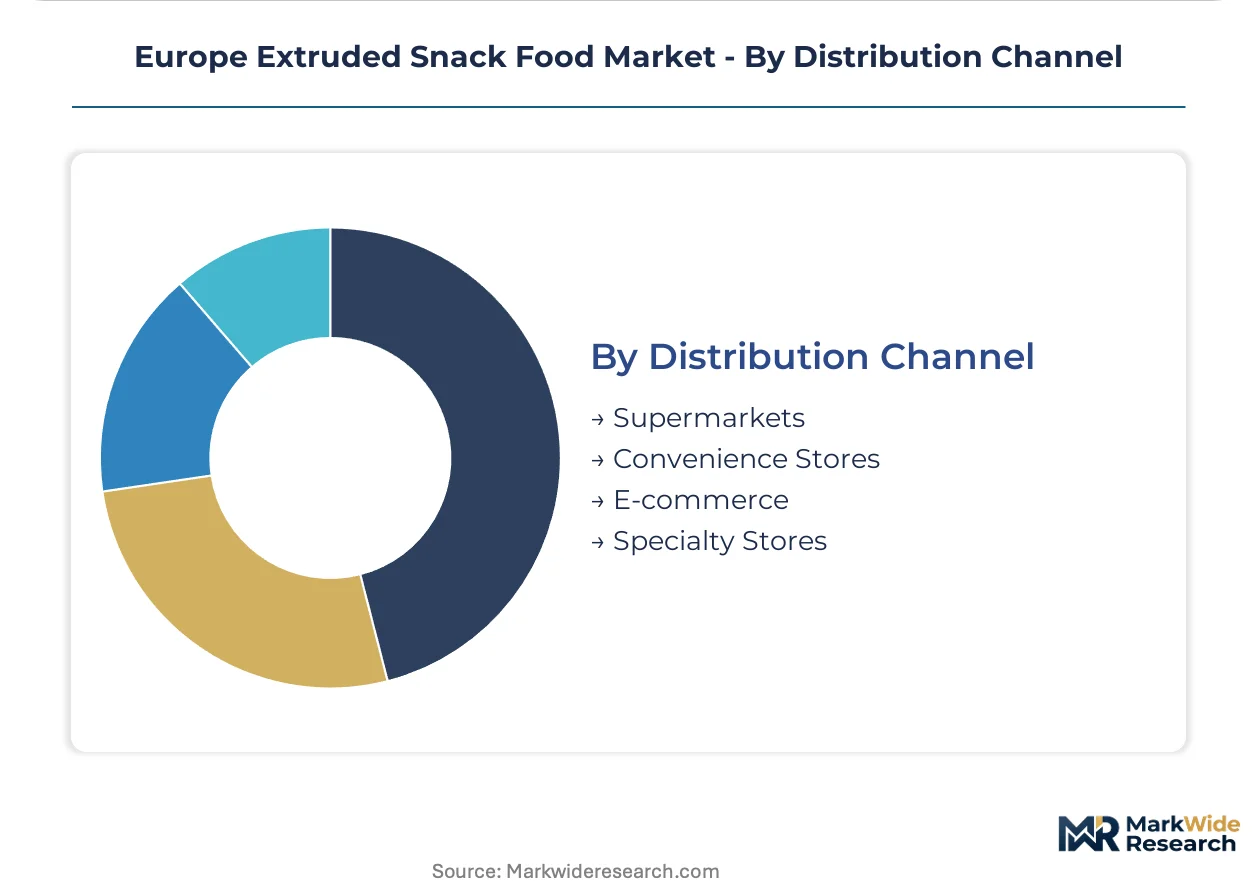
- Supermarkets:Tesco and Carrefour analytics partnerships are compressing order cycles from weekly to daily intervals through direct-to-retailer data collaborations. This pattern is most visible in the UK and Netherlands where inventory management systems have integrated dynamic replenishment.
- Convenience Stores:On-the-go format expansion across Germany, France, and the UK is sustaining high-velocity SKU placement with space-constrained ranging decisions favoring established brands.
- E-commerce:Grocery platform penetration has enabled daily replenishment cycles that displace traditional distributor-led inventory management.
- Specialty Stores:Parisian and Lyon retail clusters command substantial price premiums for clean-label specifications in artisan-positioned segments.
Supermarkets anchor the volume base while e-commerce gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity clusters across northern Italy and southern Germany where specialized engineering expertise for low-bulk-density texture control has concentrated for decades. This geographic pattern shapes where reformulation investments and packaging line upgrades receive priority allocation.
Germany
Aldi and Lidl's private-label expansion sustains volume throughput for high-velocity potato and corn snack SKUs through optimized replenishment cycles. EFSA sodium reduction benchmarks are compressing formulation flexibility for mass-market offerings. The Munich-Stuttgart corridor hosts the densest concentration of extrusion engineering specialists retiring from active workforce participation.
France
Parisian and Lyon retail clusters command 40-60% price premiums for clean-label specifications in artisan-positioned segments. ANSM nutritional claim verification extends reformulation timelines for novel multigrain introductions. The Auvergne-Rhône-Alpes region anchors heritage grain sourcing networks supplying premium corn snack variants.
United Kingdom
Tesco and Carrefour analytics partnerships compress order cycles from weekly to daily intervals through direct-to-retailer data collaborations. Extended producer responsibility schemes in England and Wales are mandating packaging fee structures ahead of continental deadlines. The Midlands manufacturing belt faces legacy equipment retrofit complexity requiring 18-24 month downtime windows.
Netherlands
Early compliance with national packaging fee structures is creating first-mover shelf access advantages for sustainable film transitions. Dutch grocery e-commerce penetration has crossed threshold levels for dynamic inventory management with daily replenishment intervals. The Randstad logistics hub enables rapid distribution across Benelux retail networks.
Italy
Specialized process optimization expertise for low-bulk-density texture control concentrates among retiring cohorts in northern Italian extrusion engineering firms. REACH chemical compliance friction extends seasoning and coating additive approvals by 12-18 months. The Emilia-Romagna food processing cluster integrates twin-screw extrusion with in-barrel flavor injection capabilities.
Europe Extruded Snack Food Market Key Industry Players
Concentration sits with pan-European scale players and Nordic private-label specialists. Three tiers structure competitive positioning: multinational CPG conglomerates with direct-to-retailer analytics partnerships, regional private-label anchors with backward integration into seasoning operations, and mid-tier hybrid manufacturers bridging batch flexibility with continuous output. Dominant competitive moves include strategic partnerships for inventory management optimization and portfolio diversification into clean-label multigrain variants.
Among scale-driven conglomerates, Mondelez International Inc. and PepsiCo Inc. occupy positions exemplifying pan-European distribution infrastructure and data-driven retailer collaboration respectively. Orkla ASA anchors Nordic private-label supply archetypes with integrated seasoning capabilities. These three entities represent the structural poles around which mid-tier specialists in Poland and Spain configure hybrid production systems.
| Leading Market Players |
|---|
| Mondelez International Inc. |
| Orkla ASA |
| PepsiCo Inc. |
| Estrella Maarud AS |
| Walkers Snack Foods Ltd. |
| Intersnack Group GmbH & Co. KG |
| Lorenz Snack-World GmbH |
| Zweifel Pomy-Chips AG |
| Kellanov (formerly Kellogg Company) |
| Others |
Cost & Logistics Intelligence
Forty-five-day inventory cycles for sustainable film laminates concentrate purchasing power among German and French retailers while compressing margin pools for mid-tier manufacturers lacking direct-to-retailer analytics partnerships. This lead-time band ties shelf-access fees to EFSA sodium reduction compliance timelines, reshaping how extrusion capacity allocates across premium and commodity tiers.
Pricing Analysis
EFSA nutritional profiling dictates the pricing tier structure across European extruded snack aisles. Three-tier pricing separates heritage-grain artisan variants from standard multigrain offerings and economy potato SKUs, with certification level and volume scale as primary differentiation drivers. Pricing pressure stems from palm oil input volatility, which is intensifying margin compression in mass-market categories where Aldi and Lidl private-label buyers exhibit highest price sensitivity.
Supply Chain Analysis
Germany and France anchor extrusion manufacturing for low-bulk-density texture control, while the Netherlands concentrates compostable film laminate supply under EU Green Deal deadlines. Raw material dependencies draw from palm oil trading hubs, heritage grain networks in Auvergne-Rhône-Alpes, and seasoning additive suppliers facing REACH compliance friction. Single-source vulnerability in sustainable packaging creates bottleneck risk as distribution runs through Randstad logistics hubs and direct-to-retailer data partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as EFSA reformulation timelines force capital redeployment into extrusion line upgrades, creating replacement demand for precision-engineered equipment.
For Market Incumbents: Secure backward integration into seasoning and coating operations to offset REACH compliance friction extending novel flavor timelines. Lock direct-to-retailer analytics partnerships in UK and Netherlands grocery e-commerce channels before mid-tier competitors bridge batch-flexibility gaps. Channel control through daily replenishment cycles defends shelf space against private-label expansion. For New Entrants and Emerging Players: Differentiate on clean-label multigrain variants targeting France's artisan-positioned segment where 40-60% price premiums persist. Food service portion control for institutional nutrition programs offers the most penetrable white space, with fortified single-serve formats commanding superior per-unit economics. Go-to-market leverage should center on third-party EFSA health claim certification to bypass incumbent brand equity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-tier hybrid manufacturers in Poland and Spain face technology bifurcation pressure between batch-flexibility and continuous-output systems. Target acquisition archetypes are regional private-label anchors with captive seasoning capabilities and established Aldi or Lidl supply relationships. The signal to watch is extrusion engineering talent scarcity in northern Italy and southern Germany, which will accelerate capability premiums for firms with retained specialist cohorts.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA health claim expansion unlocks premium shelf space in Parisian retail clusters. |
| Sustainable Packaging Transition | EU Green Deal compliance creates first-mover advantage in Dutch extended producer responsibility schemes. |
| Direct-to-Retailer Analytics Partnership | Tesco and Carrefour data collaborations compress replenishment cycles from weekly to daily intervals. |
| Backward Integration into Seasoning | Orkla ASA model reduces REACH compliance friction for novel flavor introductions. |
| Food Service Portion Control Expansion | Fortified single-serve formats for French school feeding contracts command price premiums over retail. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with extrusion engineering directors, retail category buyers, and EFSA regulatory affairs specialists; and secondary validation through EU customs trade records, EFSA additive approval databases, and Nielsen retail audit data. Bottom-up capacity modeling triangulated against top-down expenditure flows from pan-European CPG conglomerates.
Across the analysis window, forecasts employed product-type segmentation by bulk density and oil absorption profiles, end-user splits between retail and food service procurement, and packaging format transitions under EU Green Deal mandates. CAGRs derived from volume trajectory modeling incorporating EFSA sodium reduction benchmark timelines and sustainable packaging compliance deadlines. Industry-specific inputs included twin-screw extrusion adoption rates and direct-to-retailer partnership penetration in UK and Netherlands grocery e-commerce.
Material uncertainties — palm oil price volatility, REACH seasoning additive approval delays, and compostable film laminate supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions about EFSA benchmark implementation pacing and retailer third-party certification requirements. Recalibration cycles align with material shifts in regulatory enforcement timelines and extrusion engineering labor market dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Organic Snacks Market
Snacks
Snack Pellets Market
Snacks
Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
Vegan Snacks Market
Snacks
Premium Snacks Market
Snacks
UAE Cereal Bar Market
Snacks
Indonesia Snack Bar Market
Snacks
Low Sodium Snacks Market
Snacks
Seaweed Snacks Market
Snacks
Europe Snack Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Cheese Snacks Market
Snacks
Asia Pacific Snack Food Market
Snacks
No-Fat Peanut Butter Market
Snacks
North America Baked Savory Snacks Market