
 South Africa Snack Bar Market | 2026-2036
South Africa Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Snack Bar Market Analytics
The Department of Health's proposed front-of-pack labeling regulation is expanding compliance costs for new entrants while rewarding incumbents with established R&D infrastructure. Tiger Brands Ltd. leverages its integrated supply chain to absorb these regulatory costs without margin erosion. Nestlé SA sustains category leadership through specialized nutrition science capabilities. Mondelez International Inc. competes via brand equity built on global snack portfolios adapted to local taste profiles.
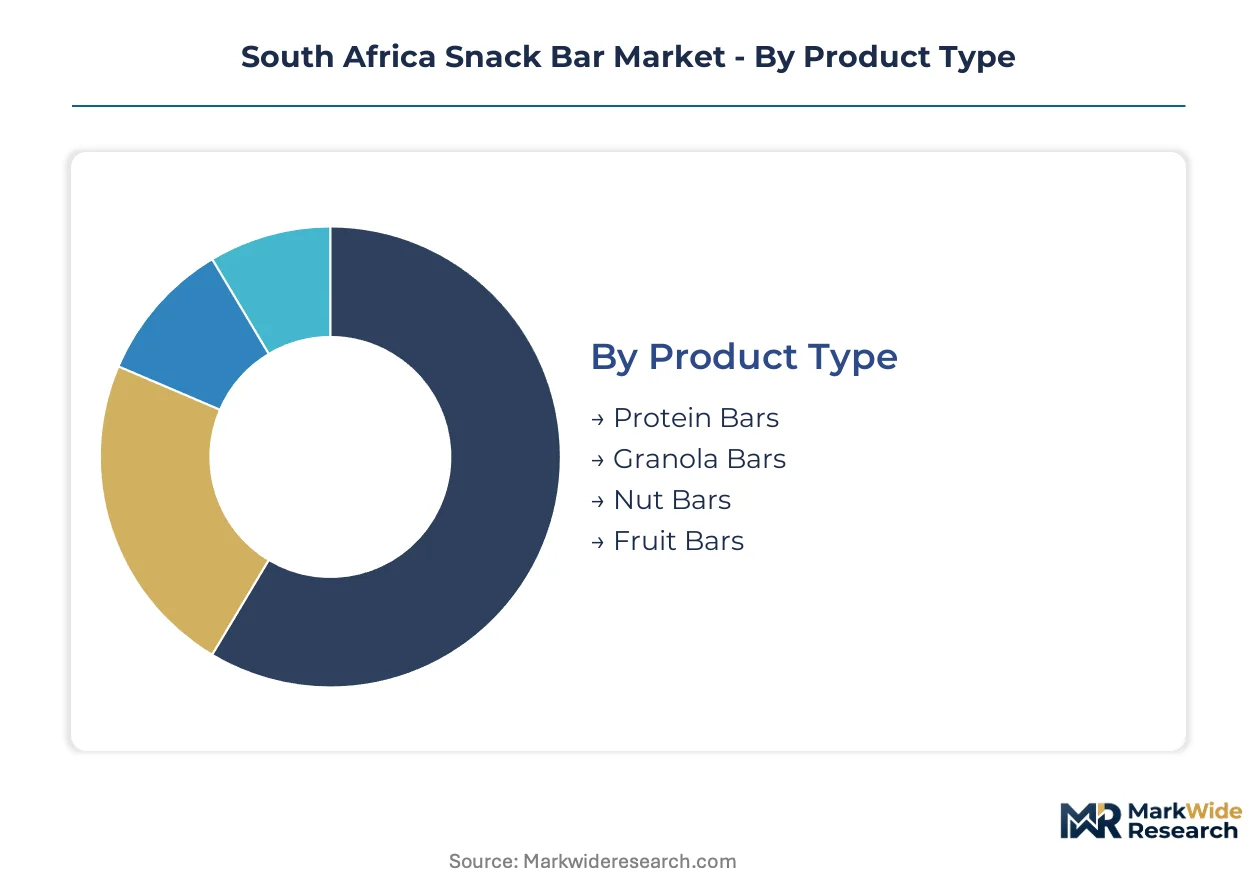
A snack bar is a shelf-stable, extruded or cold-pressed food unit typically comprising cereals, proteins, binders, and functional additives, manufactured through continuous slab-forming or enrobing processes to deliver portion-controlled energy delivery. Protein bars dominate value capture due to premium positioning among athletes and gym-goers, while granola bars anchor volume through supermarket penetration. Nut bars represent the fastest-growing segment as plant-based protein demand concentrates among health conscious consumers. Fruit bars occupy a mature niche with thinner margins but stable convenience store distribution.
The National Regulator for Compulsory Specifications enforces packaging and food safety standards, while the Advertising Regulatory Board governs health claims that shape consumer trust and purchase decisions. The Consumer Protection Act further constrains labeling practices, forcing reformulation investments across the competitive set. Stakeholders must monitor pending sugar taxation proposals and front-of-pack labeling implementation timelines to calibrate portfolio and pricing strategies ahead of enforcement.
Market Dynamics
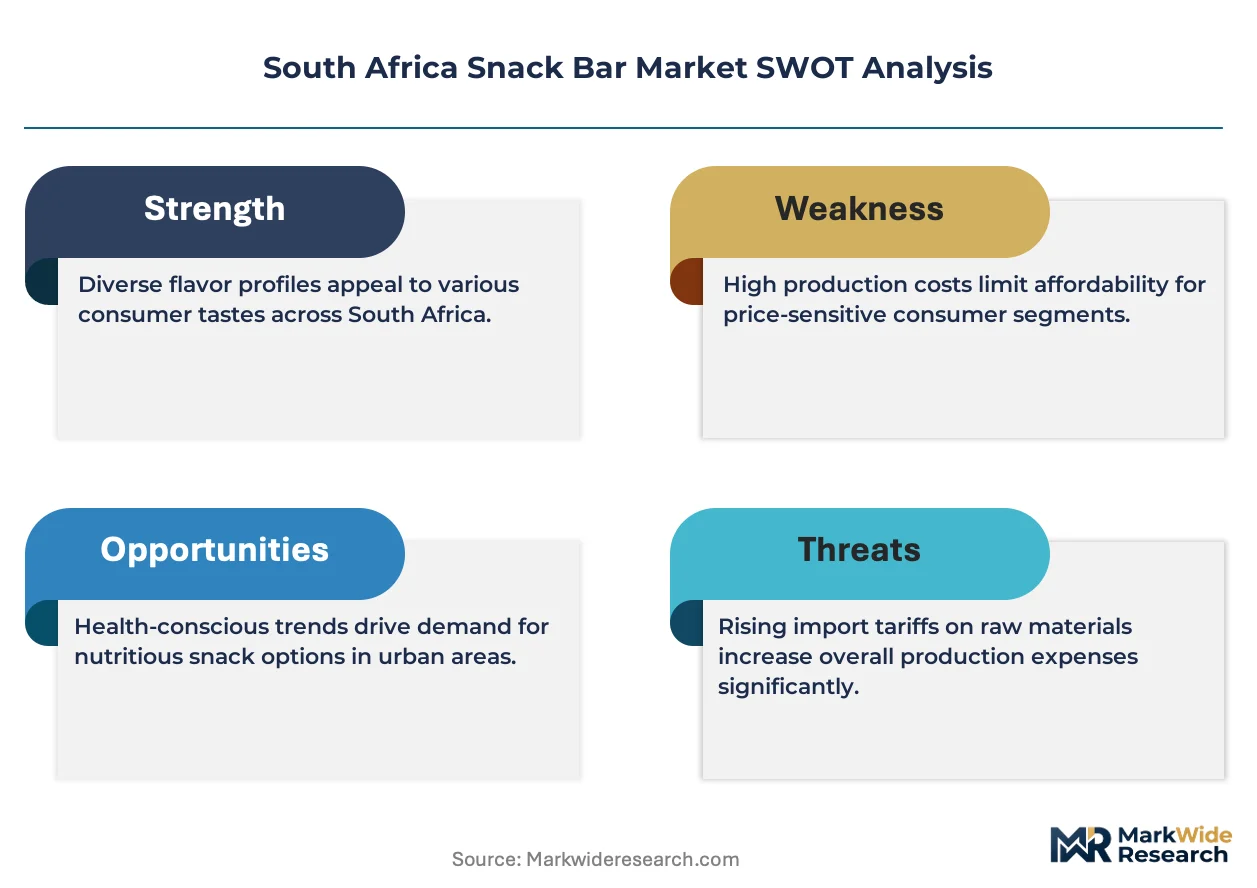
The Department of Health's proposed front-of-pack labeling regulations are forcing reformulation investments across South African snack bar portfolios, compressing margins for smaller operators while entrenching scale advantages for incumbents with captive R&D infrastructure.
Growth Catalysts
- Protein-fortified innovation:Health-conscious consumers in Gauteng and the Western Cape are pulling demand for functional formats, creating premium price real estate for manufacturers with specialized nutrition science capabilities.
- Plant-based protein migration:Nut bars are capturing accelerated interest as consumers reduce animal-derived ingredients, opening formulation white space for cold-pressed and extruded alternatives with clean-label positioning.
- Supermarket channel expansion:Granola bars anchor volume through modern retail penetration in urban centers, with shelf-stable logistics enabling distribution reach into secondary cities.
Market Restraints
- Input cost volatility:Almond and cashew prices fluctuate with rainfall patterns in Mozambique and Kenya, squeezing gross margins for nut-dependent SKUs without long-term supply contracts.
- Regulatory compliance burden:The Consumer Protection Act and pending sugar taxation proposals force simultaneous label redesign and reformulation, diverting capital from brand building.
- Substitution pressure:Fresh fruit and unpackaged traditional snacks compete on perceived naturalness and price in informal retail channels.
Strategic Opportunities
- Underserved rural distribution:Spaza shops and informal traders in Eastern Cape and Limpopo represent volume expansion potential for portion-controlled, low-unit-price formats.
- Sports nutrition convergence:Collaboration with gym chains and fitness apps creates direct-to-consumer pathways for protein bar trial outside conventional retail.
- Export corridor development:SADC trade agreements enable tariff-advantaged access into Botswana, Namibia, and Zimbabwe for compliant South African manufacturers.
Industry Challenges
- Front-of-pack labeling implementation:The National Regulator for Compulsory Specifications enforcement timeline remains uncertain, complicating production planning and inventory management.
- Cold chain limitations:Enrobed and chocolate-coated variants face spoilage risk in summer distribution, constraining product architecture for mass-market penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Snack Bar Market |
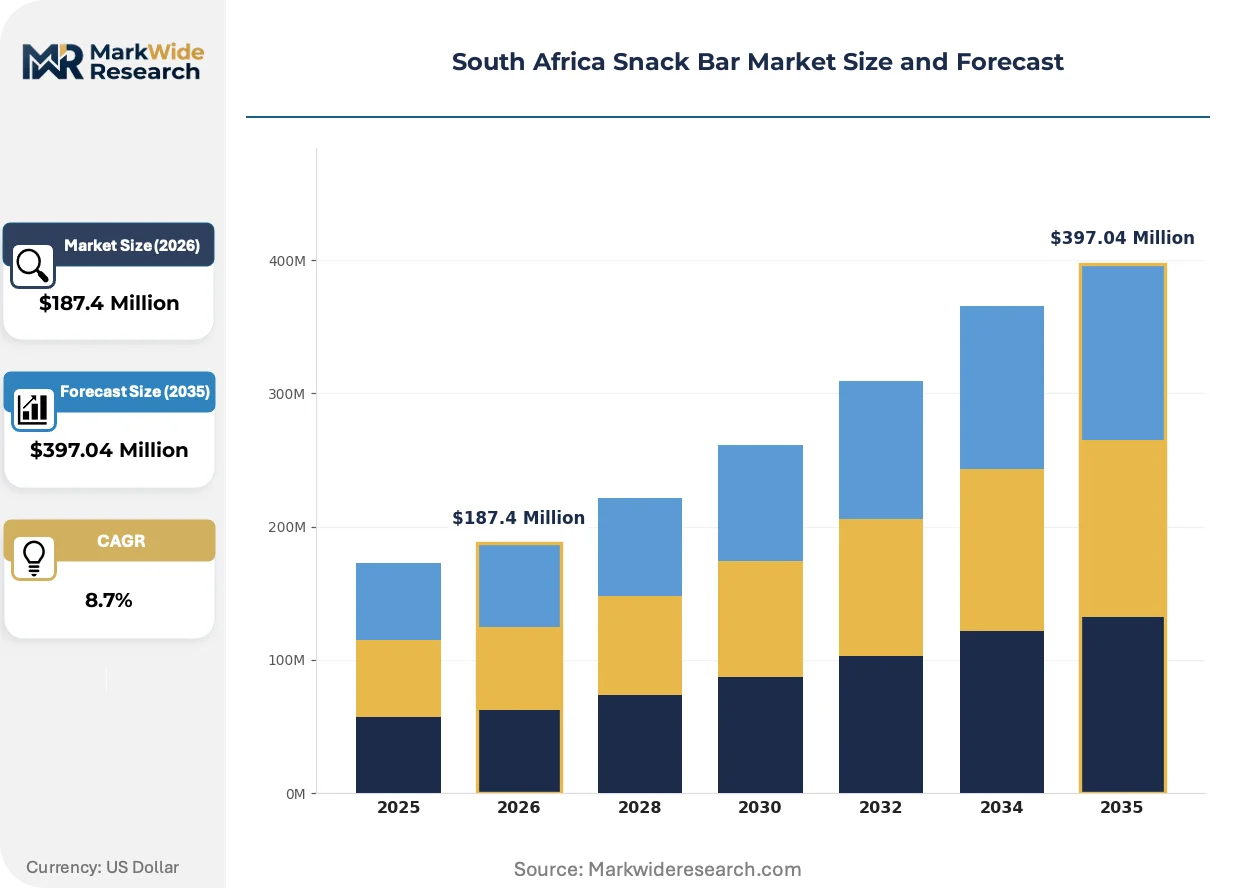
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Nut Bars, Fruit Bars Customer Type: Health Conscious Consumers, Busy Professionals, Athletes, Students Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Shops Packaging Type: Single-Serve Packets, Multi-Pack Boxes, Resealable Bags, Bulk Packaging |
| Companies Covered | Tiger Brands Ltd., General Mills Inc., Nestlé SA, Post Holdings Inc., The Kellogg Company, Mondelez International Inc., Ultimate Sports Nutrition (USN), Quest Nutrition LLC, Kellanova, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Snack Bar Market Evolving Landscape
Automation and regulatory precision are compressing production economics while consumer preference fragmentation forces portfolio diversification beyond traditional format boundaries.
Cold-pressing technology is automating nutrient retention in plant-protein bars, preserving enzymatic activity and flavor compounds that thermal extrusion degrades. Mid-tier manufacturers in Cape Town and Durban are retrofitting slab-forming lines with servo-controlled compression systems to capture this quality tier. The shift is automating batch consistency and reducing labor dependency in high-mix production environments.
The Advertising Regulatory Board's tightening guidance on health claims is constraining permissible language around energy, protein, and functional benefits. Manufacturers must now substantiate assertions through clinical documentation or reformulate marketing to focus on ingredient provenance. Protein bar segments targeting athletes face the steepest compliance burden, with several brands pivoting toward taste-forward positioning.
Gym-goers and weekend athletes are consolidating purchase decisions around subscription and bundled formats, displacing single-unit impulse buying. E-commerce platforms and specialized nutrition retailers are capturing this behavioral shift through auto-replenishment models. This pattern concentrates in Gauteng's metropolitan nodes where fitness club density and digital payment penetration overlap.
South Africa Snack Bar Market Segmentation
Snack bar purchase decisions in South Africa diverge sharply across consumption occasions, from post-workout recovery to desk-bound meal replacement. Manufacturers must align formulation density, portion architecture, and channel presence with distinct buyer workflows rather than treating the category as uniform.
Product Type:
Premium positioning and functional claims separate winners from commodity players in this dimension.
- Protein Bars:Extruded or cold-pressed formats delivering 15-25g protein per serving through whey, casein, or plant isolates. Demand concentrates among Gauteng gym-goers and CrossFit communities where recovery nutrition commands price premiums. The Advertising Regulatory Board's tightening health claim enforcement forces reformulation of label language.
- Granola Bars:Baked oat and honey matrices with lower protein density but higher carbohydrate fuel for sustained energy. Supermarket penetration in Cape Town and Durban suburban nodes anchors volume through family-pack formats and school lunchbox positioning.
- Nut Bars:Cold-pressed almond, cashew, or macadamia bases with minimal processing and clean-label positioning. Plant-based protein migration accelerates interest among Western Cape health-conscious consumers reducing animal-derived intake.
- Fruit Bars:Dehydrated fruit purees and pulp matrices with natural sugar profiles and fiber retention. Convenience store distribution in transport hubs and fuel station networks sustains this mature segment.
Volume sits with granola bars through supermarket reach; growth tilts toward nut bars as plant protein preference steepens.
Customer Type:
Occasion-based usage patterns determine packaging format and channel strategy more than demographic labels alone.
- Health Conscious Consumers:Buyers prioritizing ingredient transparency, low glycemic index, and absence of artificial additives. Western Cape and Gauteng metropolitan clusters drive premium SKU uptake through health food shop and online direct channels.
- Busy Professionals:Time-constrained urban workers seeking meal replacement in transit. Johannesburg and Pretoria CBD convenience stores capture this segment through single-serve placement at checkout and office building proximity.
- Athletes:Structured training populations with peri-workout nutrition protocols. Sports nutrition convergence with gym chains and fitness apps creates subscription pathways outside conventional retail.
- Students:Price-sensitive younger buyers in secondary cities and university towns. Eastern Cape and Limpopo campus-adjacent spaza shops represent volume expansion potential for low-unit-price formats.
Health conscious consumers anchor premium pricing; athletes are expanding most quickly through subscription and bundled formats.
Distribution Channel:
Cold chain capabilities and payment infrastructure shape feasible product architecture by route-to-market.
- Supermarkets:Modern retail with climate-controlled environments enabling chocolate-coated and enrobed variants. Shelf-stable logistics extend reach into secondary cities beyond primary metros.
- Online Retailers:E-commerce platforms and specialized nutrition sites capturing auto-replenishment behavior. Gauteng metropolitan nodes with digital payment penetration concentrate this channel.
- Convenience Stores:High-frequency impulse purchase locations in transport corridors and fuel stations. Fruit bars and single-serve granola formats dominate this channel.
- Health Food Shops:Curated assortments with educated staff and premium positioning. Cape Town and Durban mid-tier manufacturers leverage this channel for cold-pressed nut bar trial.
Supermarkets hold volume through modern retail penetration; online retailers gain share fastest as subscription models consolidate athlete purchasing.
Packaging Type:
Unit economics and consumption occasion alignment determine margin structure in this dimension.
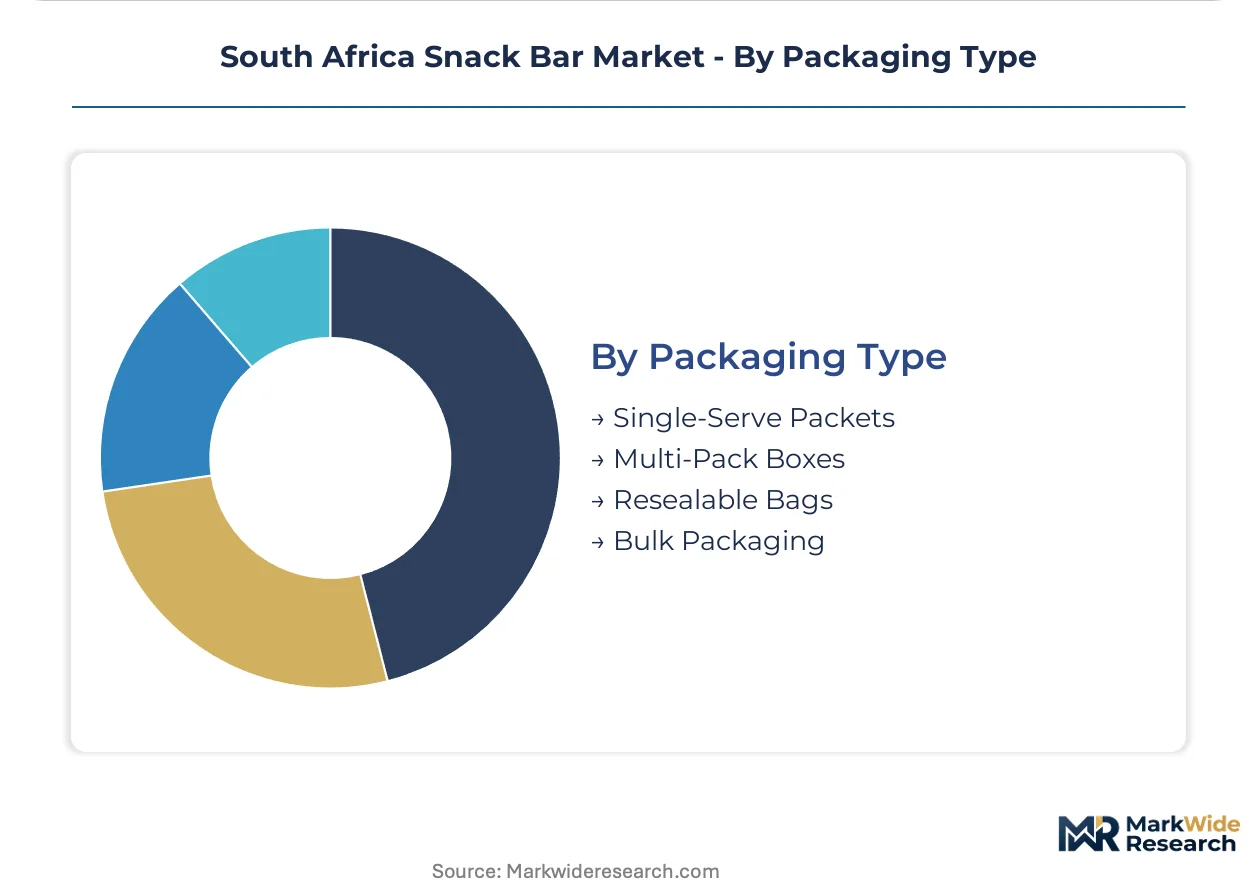
- Single-Serve Packets:Individual 40-60g wrappers for immediate consumption and impulse purchase. Convenience stores and transport hubs favor this format for portion control and portability.
- Multi-Pack Boxes:Aggregated 5-6 count cartons for household pantry stocking and school lunch preparation. Supermarket promotional cycles and family budgeting drive this format.
- Resealable Bags:Flexible pouches with zip-lock closures for portion-controlled access over multiple days. Health food shops and online channels favor this for premium nut and granola variants.
- Bulk Packaging:Large-format bags or boxes for institutional buyers, gyms, and corporate wellness programs. Direct procurement relationships bypass retail markup.
Single-serve packets dominate transaction frequency; multi-pack boxes capture the steepest expansion trajectory as household pantry stocking consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Special Economic Zone in the Coega Industrial Development Zone near Gqeberha accelerates snack bar manufacturing concentration through tax incentives and customs facilitation for export-oriented producers.
Gauteng Province
Johannesburg and Pretoria metropolitan clusters drive premium protein bar uptake through dense gym chain networks and fitness app subscriptions. The Consumer Protection Act enforcement tightens label compliance timelines for manufacturers distributing through modern retail. Midrand logistics hubs enable cold-pressed nut bar distribution into secondary cities.
Western Cape
Cape Town health food shops and Atlantic Seaboard consumers anchor clean-label demand for plant-based protein formats. The Department of Health's proposed front-of-pack labeling regulations force reformulation investments among Stellenbosch-area manufacturers. Somerset West production facilities specialize in cold-pressed technology for enzymatic preservation.
KwaZulu-Natal
Durban port access facilitates almond and cashew importation from Mozambique and Kenya for nut-dependent SKUs. The National Regulator for Compulsory Specifications audits packaging facilities in Pinetown industrial corridors. Umhlanga Ridge retail nodes concentrate convenience store distribution for single-serve formats.
Eastern Cape
Gqeberha and Port Elizabeth spaza shop networks represent volume expansion potential for low-unit-price granola formats. Pending sugar taxation proposals complicate pricing architecture for mass-market penetration. Buffalo City campus-adjacent retailers capture student segment demand through portion-controlled packaging.
South Africa Snack Bar Market Competitive Landscape
South African producers anchor the domestic supply tier; multinational specialists hold premium nutrition science positions. The market exhibits moderate consolidation around integrated food conglomerates with captive R&D infrastructure, while mid-tier cold-press specialists fragment the plant-based protein niche. Three archetypes dominate: scale-driven FMCG conglomerates with supermarket channel control, nutrition science specialists with sports distribution partnerships, and agile cold-press artisans with health food shop penetration. Competitive dynamics center on regulatory compliance absorption and supermarket shelf-space negotiation.
Within the scale-driven tier, Tiger Brands Ltd. and Nestlé SA exemplify incumbents with integrated supply chains that distribute compliance costs across diversified portfolios. Mondelez International Inc. occupies a position bridging global snack equity with local taste adaptation. These three represent the dominant competitive anchors against which mid-tier specialists and artisanal entrants define differentiation strategies.
| Leading Market Players |
|---|
| Tiger Brands Ltd. |
| General Mills Inc. |
| Nestlé SA |
| Post Holdings Inc. |
| The Kellogg Company |
| Mondelez International Inc. |
| Ultimate Sports Nutrition (USN) |
| Quest Nutrition LLC |
| Kellanova |
| Others |
Value Network & Pricing Analysis
Athlete and gym-goer subscription consolidation in Gauteng metropolitan clusters anchors premium pricing for protein-fortified formats, while spaza shop penetration in Eastern Cape and Limpopo drives low-unit-price architecture for granola and fruit bars. The Department of Health's pending front-of-pack labeling regulations compress margins through simultaneous reformulation and label redesign investments, forcing portfolio segmentation between compliance-absorbing incumbents and margin-vulnerable mid-tier operators.
Pricing Analysis
Short lead-time premiums for cold-pressed nut bars with enzymatic preservation command price premiums in Cape Town health food shops, while spot inventory discounts move through supermarket promotional cycles for standard granola formats. Three-tier pricing structure across premium protein bars, standard granola bars, and economy fruit bars reflects formulation density and channel positioning. Pricing pressure stems from almond and cashew input cost volatility tied to Mozambique and Kenya rainfall patterns, compressing gross margins for nut-dependent SKUs without long-term supply contracts. Students in campus-adjacent spaza shops exhibit highest price sensitivity, while health-conscious Atlantic Seaboard consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Direct-to-gym-chain channels handle athlete subscription demand through auto-replenishment models, while supermarket distribution networks anchor volume for family-pack granola formats. Raw nut sourcing concentrates in Mozambique and Kenya for almond and cashew inputs, with whey protein isolates drawing from established dairy processing infrastructure. Single-source vulnerability in regional nut harvests creates margin volatility for cold-pressed specialists dependent on specific origin grades. Distribution runs through Midrand logistics hubs enabling secondary city penetration, with Durban port access facilitating importation for nut-dependent SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive cold-pressing technology and specialized nutrition science capabilities defines competitive positioning, as manufacturers race to internalize enzymatic preservation expertise and sports nutrition distribution partnerships before regulatory enforcement tightens.
For Market Incumbents: Acquire cold-press manufacturing assets in Western Cape production corridors to internalize enzymatic preservation capabilities and defend against mid-tier artisanal entrants. Consolidate supermarket shelf-space through multi-pack box promotional cycles while absorbing front-of-pack labeling compliance costs across diversified portfolios. Threat substitution from fresh fruit and unpackaged traditional snacks in informal channels demands fortified spaza shop penetration with portion-controlled formats. For New Entrants and Emerging Players: The Department of Health's proposed front-of-pack labeling regulations in South Africa opens a window for clean-label positioning that sidesteps reformulation burdens falling on established portfolios. Target Eastern Cape and Limpopo spaza shop networks with low-unit-price granola formats as the most penetrable geography. Pursue direct-to-consumer trial through fitness app partnerships and gym chain subscriptions as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-tier cold-press specialists with health food shop penetration and proprietary enzymatic preservation technology. Long-term viability hinges on regulatory compliance infrastructure and captive R&D capabilities over a 5-10 year horizon. Watch for National Regulator for Compulsory Specifications enforcement timeline clarity as the signal for portfolio revaluation and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Technology Acquisition | Internalizes enzymatic preservation capabilities that thermal extrusion degrades, capturing Western Cape clean-label demand. |
| Gym Chain Distribution Partnership | Creates subscription pathways for protein bar trial outside conventional retail through Gauteng fitness club networks. |
| Front-of-Pack Labeling Compliance Investment | Absorbs regulatory costs that compress margins for smaller operators without captive R&D infrastructure. |
| Spaza Shop Network Penetration | Captures volume expansion in Eastern Cape and Limpopo through portion-controlled, low-unit-price format placement. |
| SADC Export Corridor Development | Leverages trade agreements for tariff-advantaged access into Botswana, Namibia, and Zimbabwe markets. |
Research Methodology
Independent corroboration across brand manager interviews, category buyer discussions at supermarket chains, and supply planner consultations at nut importers underwrites the qualitative findings. Secondary validation drew from Nielsen retail audit data, customs import records for almond and cashew shipments, and National Regulator for Compulsory Specifications enforcement documentation. Bottom-up channel volume estimates and top-down category value assessments were reconciled through iterative triangulation.
Comparable historical periods anchored the projection framework to pre-regulatory announcement baselines and post-implementation analogs from comparable markets. Segmentation modeling spanned product type, customer archetype, distribution channel, and packaging format dimensions across the analysis window. CAGRs were derived from fitted growth curves calibrated to protein-fortified innovation velocity and plant-based protein migration rates. Forecast inputs included supermarket expansion trajectories in secondary cities and cold chain infrastructure development timelines.
Caveats apply where front-of-pack labeling enforcement timing, sugar taxation proposal passage, or Mozambique and Kenya rainfall volatility could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation pace and consumer preference migration speed. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Cheese Snacks Market
Snacks
South Korea Snack Bar Market
Snacks
South America Protein Bar Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Trail Mix Market
Snacks
North America Snack Bar Market
Snacks
Jerky Snacks Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Fruit Jerky Market
Snacks
Organic Snack Food Market
Snacks
South East Asia Snack Bar Market
Snacks
Meat Snacks Market
Snacks
United States Popcorn Market
Snacks
Europe Snacks Market
Snacks
Saudi Arabia French Fries Market