
 Reduced Fat Peanut Butter Market | 2026-2036
Reduced Fat Peanut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Fat Peanut Butter Market Analytics
FDA nutrition-labeling mandates are restructuring the cost-of-entry calculus for reduced fat peanut butter formulations, forcing manufacturers to invest in reformulation labs and third-party certification. The J.M. Smucker Company leverages its vertically integrated peanut sourcing to sustain margin stability across conventional and natural retail channels. Hormel Foods Corporation anchors its position through protein-centric brand positioning that competes directly with full-fat spreads. Conagra Brands differentiates via private-label manufacturing scale that controls shelf placement economics for discount-oriented retail banners.
Reduced fat peanut butter denotes a spreadable food product wherein a portion of peanut oil is mechanically or chemically reduced and partially replaced with stabilizers, yielding a fat content typically 25 percent lower than standard peanut butter while maintaining protein density above 20 percent by weight; commercial production employs high-shear milling and hydrogenated vegetable oil blending to achieve shelf-stable emulsion. Creamy variants dominate volume shipments due to their versatility in baking and sandwich applications, while organic spreads capture disproportionate margin pools through certified supply chains and health food shop premiums. Jars remain the primary packaging format for mainstream supermarkets, though pouches are gaining traction in convenience stores and on-the-go consumption occasions.
The FDA governs allergen labeling and fat-content claim thresholds under the Federal Food, Drug, and Cosmetic Act, while USDA grading standards influence peanut quality benchmarks that cascade into reduced fat input costs. State-level nutrition disclosure laws in California and New York add compliance layers that smaller entrants struggle to navigate. Stakeholders must monitor evolving clean-label expectations and regulator scrutiny of reduced-fat claims against actual nutritional profiles to anticipate reformulation cycles and avoid enforcement actions.
Market Dynamics
FDA's updated Nutrition Facts labeling requirements for added sugars and fat content disclosures are compelling manufacturers to restructure formulation labs and accelerate third-party certification investments, fundamentally altering the cost structure for reduced fat peanut butter market entry.
Growth Catalysts
- FDA Labeling Mandates:The Federal Food, Drug, and Cosmetic Act's disclosure thresholds force manufacturers to clarify nutritional claims, driving reformulation investment and premium positioning opportunities for compliant producers.
- Fitness Segment Demand:Health-conscious consumers pursuing weight management programs are adopting reduced fat spreads as pantry staples, creating sustained volume pull through conventional and natural grocery channels.
- High-Shear Milling Technology:Advanced emulsion processing enables shelf-stable products with 25 percent fat reduction while maintaining protein density above 20 percent by weight, expanding addressable use cases.
Market Restraints
- Peanut Oil Volatility:Input cost fluctuations for mechanically extracted peanut oil and hydrogenated vegetable oil stabilizers compress margin predictability for reformulation-intensive producers.
- California and New York Compliance Layers:State-level nutrition disclosure laws add regulatory friction that smaller entrants struggle to navigate, consolidating shelf access around established manufacturers.
- Full-Fat Spread Substitution:Standard peanut butter retains price advantage and taste preference among non-health-conscious households, limiting category expansion beyond wellness-oriented demographics.
Strategic Opportunities
- Pouch Packaging Innovation:Convenience stores and on-the-go consumption occasions are shifting toward flexible pouches, opening channel diversification beyond jar-dependent mainstream supermarkets.
- Organic Certification Premiums:Certified supply chains and health food shop positioning capture disproportionate margin pools through verified clean-label credentials.
- USDA Grading Alignment:Peanut quality benchmarks cascading into reduced fat input costs create differentiation pathways for producers meeting superior grade specifications.
Industry Challenges
- Reformulation Timeline Compression:Accelerated FDA compliance deadlines strain R&D capacity, forcing simultaneous label redesign, emulsion testing, and stability validation.
- Clean-Label Expectation Divergence:Consumer scrutiny of reduced-fat claims against actual nutritional profiles demands continuous monitoring to anticipate enforcement exposure and avoid regulatory actions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Fat Peanut Butter Market |
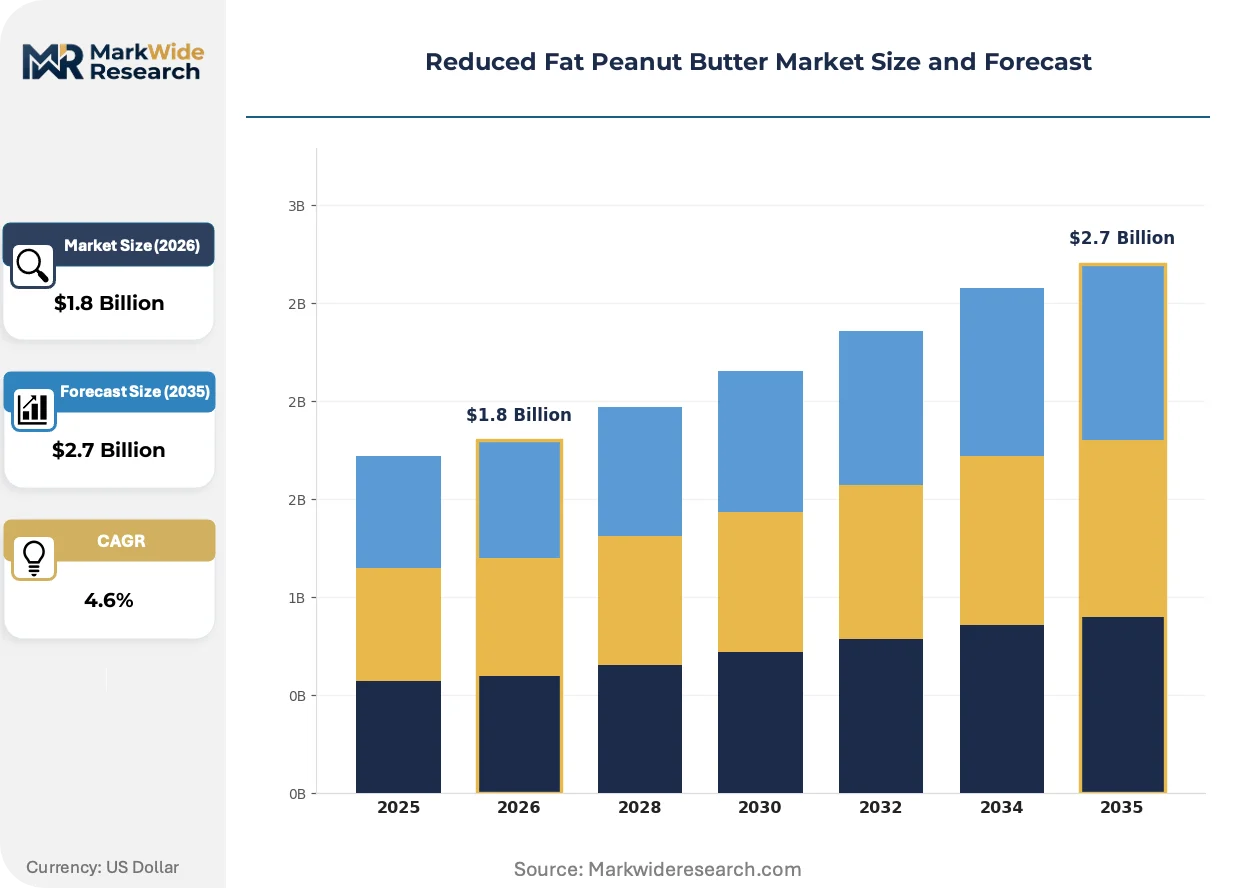
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Crunchy, Creamy, Organic Ingredient Type: Peanuts, Almonds, Cashews, Soy Packaging Type: Tubs, Jars, Pouches, Sachets Distribution Channel: Supermarkets, Online, Convenience Stores, Health Food Shops |
| Companies Covered | The J.M. Smucker Company, Hormel Foods Corporation, Conagra Brands, Unilever, Kraft Heinz, Procter & Gamble, Algood Food Company Inc., Kraft Canada Inc., Del Monte Food Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Fat Peanut Butter Market Evolving Landscape
Automation in emulsion processing and packaging lines is compressing unit economics while regulatory disclosure requirements and shifting retail formats are restructuring how reduced fat peanut butter reaches end consumers.
High-shear milling systems paired with hydrogenated vegetable oil blending technology is automating the production of shelf-stable emulsions at commercial scale. Natural grocery chains and private-label manufacturers are adopting these systems to maintain protein density thresholds while achieving consistent texture profiles. This automation is compressing batch-to-batch variation and reducing manual quality intervention, enabling smaller production runs for specialty formulations.
The FDA's Federal Food, Drug, and Cosmetic Act enforcement of allergen labeling and fat-content claim thresholds is restructuring competitive positioning around documentation rigor. Manufacturers must now maintain detailed reformulation records and third-party verification to support reduced-fat assertions on packaging. Natural and organic segments face the steepest compliance burden, responding by consolidating supplier relationships and investing in captive certification capacity.
Retail procurement patterns are fragmenting across channel-specific packaging requirements, with convenience stores and fitness-focused direct-to-consumer platforms demanding portion-controlled formats distinct from conventional supermarket jars. Club stores and discount banners are replacing traditional grocery as volume anchors, unbundling historical shelf placement economics. This channel rotation is most visible in the United States, where private-label reduced fat varieties are capturing incremental space in natural grocery and value-oriented retail banners simultaneously.
Reduced Fat Peanut Butter Market Segmentation
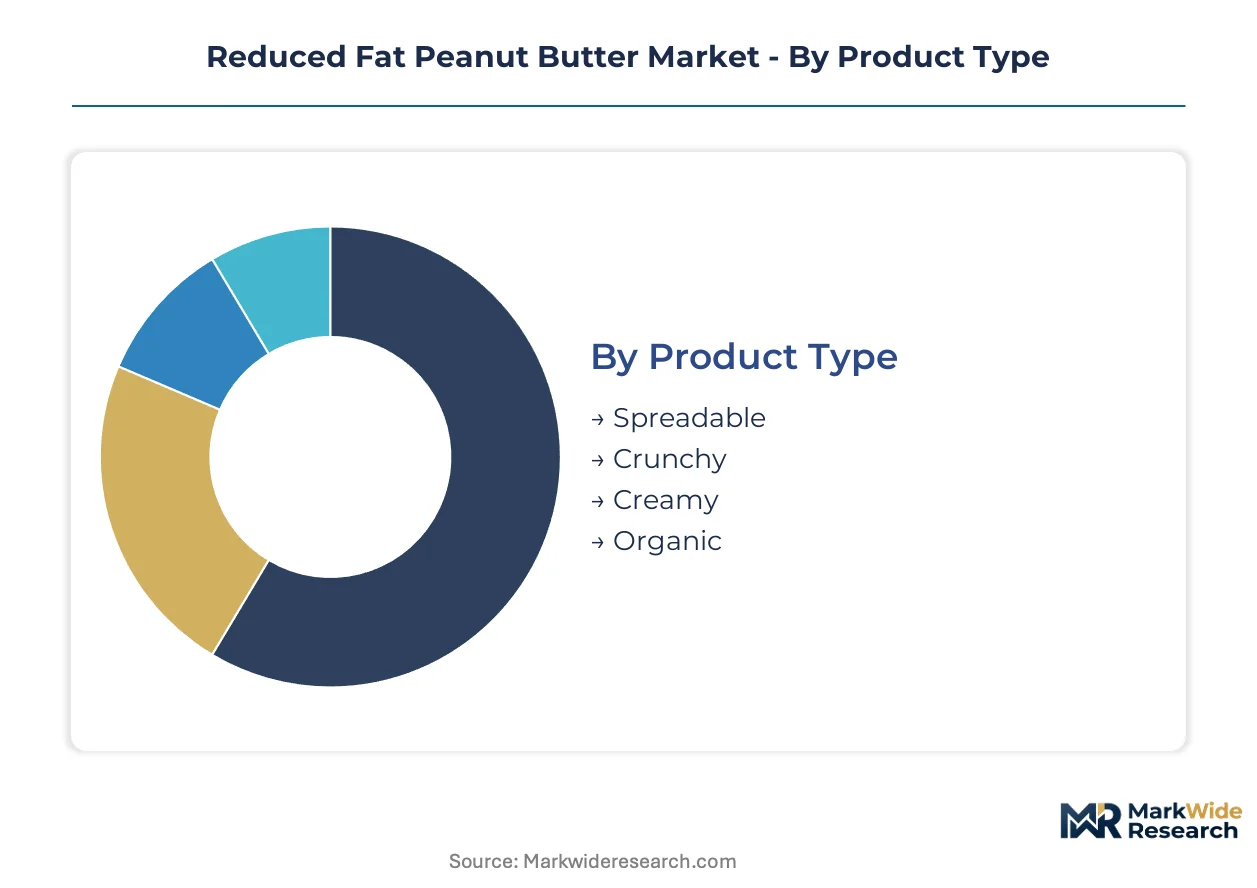
Reduced fat peanut butter manufacturers must align formulation investments with distinct consumption occasions and channel economics. Segmentation reveals where protein density requirements, portability demands, and clean-label premiums command pricing power.
Product Type:
Texture preferences drive pantry stocking decisions across baking, sandwich, and snacking use cases.
- Creamy:High-shear milling produces uniform emulsion with 25 percent fat reduction while maintaining protein density above 20 percent by weight. Sandwich applications and baking recipes in United States conventional grocery channels concentrate volume demand for this spreadable consistency.
- Crunchy:Partial peanut fragment retention adds textural contrast that appeals to adult snackers seeking satiety cues. Health food shops and natural grocery chains in fitness-oriented metropolitan areas disproportionately stock this variant for its perceived wholesomeness.
- Spreadable:Stabilizer-enhanced formulations optimize for knife-spread consistency at refrigerated temperatures. Food service accounts and institutional buyers prioritize this specification for portion control and handling efficiency.
- Organic:Certified supply chains exclude synthetic pesticides and hydrogenated oils, commanding shelf space premiums in natural retail channels.
Volume sits with Creamy; growth tilts toward Organic.
Ingredient Type:
Base nut selection determines allergen labeling obligations and protein profile positioning against full-fat alternatives.
- Peanuts:Mechanically extracted peanut oil reduction yields the standard reduced fat profile with partial replacement by hydrogenated vegetable oil stabilizers. United States production clusters in Georgia and Alabama supply conventional and private-label manufacturers with grade-compliant runner varieties.
- Almonds:Higher monounsaturated fat content and distinct flavor profile attract premium positioning in health food shops and specialty retailers. California Central Valley sourcing commands traceability documentation that supports clean-label claims.
- Cashews:Creamier mouthfeel and lower allergen prevalence expand addressable households beyond peanut-restricted environments.
- Soy:Plant-protein fortification targets vegan and dairy-free consumer segments with complete amino acid profiles.
Ingredient sourcing concentrates in Peanut varieties; Almond formulations are climbing the fastest.
Packaging Type:
Channel-specific format requirements separate mainstream grocery economics from convenience and on-the-go consumption.
- Jars:Glass and plastic containers dominate mainstream supermarket shelf sets with standard 16-18 ounce capacities supporting family pantry replenishment cycles. Conventional retail banners and club stores anchor volume procurement around this format's established handling infrastructure.
- Pouches:Flexible single-serve and multi-serve formats penetrate convenience stores, fitness centers, and direct-to-consumer platforms where portability commands premium pricing. On-the-go consumption occasions in urban United States markets are expanding addressable use cases beyond traditional meal preparation.
- Tubs:Wide-mouth plastic containers optimize for food service scooping and institutional portion control.
- Sachets:Single-serve foil packets serve airline, hospitality, and sampling programs with minimal waste profiles.
Jar formats retain volume dominance; pouch packaging is gaining share fastest.
Distribution Channel:
Retail format selection determines margin structure and compliance burden for nutritional claim verification.
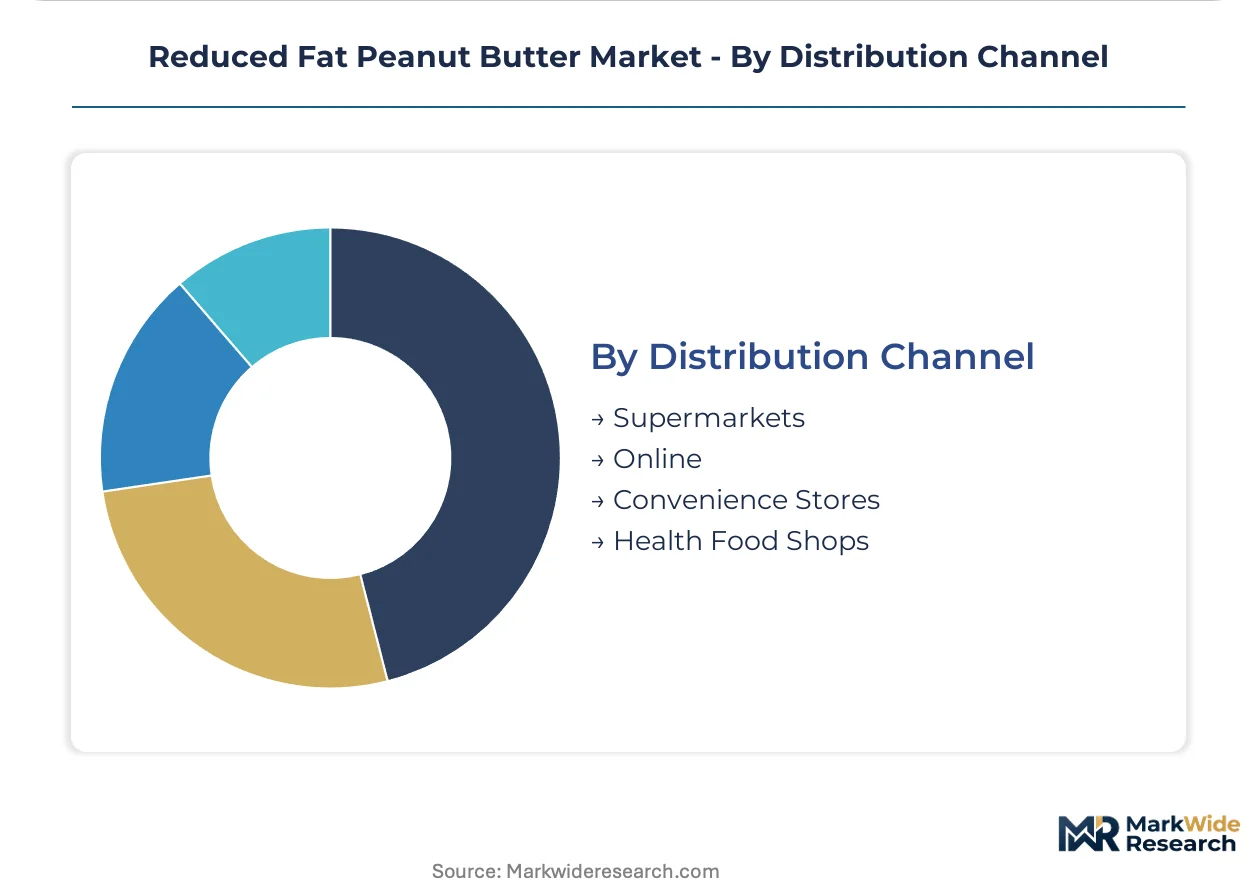
- Supermarkets:Conventional grocery chains and natural food banners provide primary shelf access for branded and private-label reduced fat varieties. United States conventional retail channels concentrate volume through established slotting fee structures and promotional calendar coordination.
- Health Food Shops:Independent natural retailers and cooperative grocery networks prioritize certified organic and clean-label formulations with verified supply chain documentation. Premium positioning in this channel supports margin pools that offset smaller case volumes.
- Online:Direct-to-consumer platforms and third-party marketplaces enable subscription replenishment and flavor variety bundling.
- Convenience Stores:Grab-and-go locations favor pouch and single-serve formats for immediate consumption occasions.
Supermarket channels anchor volume; Health Food Shops are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Georgia's peanut belt qualifies as a federal opportunity zone, concentrating shelling and processing infrastructure that feeds reduced fat formulation facilities. This tax-advantaged clustering lowers capital costs for manufacturers expanding emulsion capacity.
United States
Fitness-focused metropolitan consumers in Denver and Austin drive pouch-format adoption for on-the-go protein consumption. The FDA's updated Nutrition Facts labeling mandates compel reformulation investments across Georgia and Alabama processing corridors. Runner peanut varieties from the Southeast shelling cluster supply conventional and private-label manufacturers with grade-compliant inputs.
Canada
Health food shop networks in Toronto and Vancouver prioritize certified organic reduced fat spreads with clean-label credentials. Health Canada's allergen disclosure requirements under the Food and Drugs Act add compliance layers distinct from US FDA thresholds. Quebec-based private-label manufacturers leverage bilingual packaging regulations to capture cross-border shelf placement economics.
Germany
Discounter penetration in Berlin and Munich retail banners concentrates volume procurement around private-label reduced fat varieties. The EU's Food Information to Consumers Regulation mandates strict fat-content claim verification that exceeds US disclosure thresholds. Bavarian food technology clusters supply high-shear milling equipment to domestic and export-oriented producers.
United Kingdom
Natural grocery chains in London and Manchester expand shelf space for organic certified spreads commanding premium positioning. The Food Standards Agency enforces allergen labeling protocols that influence reformulation decisions for export-bound manufacturers. Midlands-based co-manufacturers serve both domestic supermarkets and Irish cross-channel distribution.
Australia
Metropolitan fitness centers in Sydney and Melbourne drive single-serve pouch demand for post-workout protein consumption. Food Standards Australia New Zealand governs nutrition content claims with thresholds that limit reduced-fat assertions to verified formulations. Queensland peanut growing regions supply domestic processors while Victorian food tech clusters develop stabilizer alternatives.
Reduced Fat Peanut Butter Market Competitive Landscape
United States producers anchor one tier; European and Canadian specialists hold differentiated positions in premium organic segments. The vendor base organizes around three strategic archetypes: vertically integrated agricultural processors controlling upstream peanut supply, branded consumer goods conglomerates with multi-category scale, and private-label specialists optimizing manufacturing throughput for retail banners. Competitive moves concentrate on reformulation R&D acceleration and third-party certification investments to satisfy disclosure mandates.
Within the branded conglomerate tier, The J.M. Smucker Company and Hormel Foods Corporation occupy positions exemplifying divergent positioning strategies. Unilever and Kraft Heinz represent European and North American multinational scale archetypes with cross-category leverage. Conagra Brands anchors the private-label manufacturing specialist position, while Algood Food Company Inc. exemplifies regional co-manufacturing scale.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Hormel Foods Corporation |
| Conagra Brands |
| Unilever |
| Kraft Heinz |
| Procter & Gamble |
| Algood Food Company Inc. |
| Kraft Canada Inc. |
| Del Monte Food Inc. |
| Others |
Value Network & Pricing Analysis
Clean-label certification mandates gate both qualified peanut supply and premium-tier pricing access, as USDA grading alignment and third-party organic verification create dual thresholds that manufacturers must clear to command shelf space in natural grocery channels. FDA disclosure requirements for fat-content claims add compliance layers that compress margin predictability for non-compliant producers while rewarding documented reformulation investment with pricing power in health-conscious segments.
Pricing Analysis
Short lead-time premiums for certified organic runner peanuts from Georgia shelling facilities command 15-20 percent markups over conventional spot inventory, with contract-based long-term offtake agreements dominating procurement between established manufacturers and Southeast agricultural processors. Price differentiation separates USDA Grade A certified supply from standard commercial grades, with brand premiums for verified clean-label credentials further stratifying the landscape. Cost compression in private-label tiers is intensifying due to peanut oil volatility and hydrogenated stabilizer input fluctuations. Discount-oriented retail banners exhibit highest price sensitivity, while health food shops and fitness-focused direct-to-consumer platforms absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for glass jar returns and flexible pouch recycling are emerging cost centers as sustainability mandates penetrate retail procurement criteria, with manufacturers consolidating packaging partnerships to manage circular-economy compliance. Geographic supply concentrates in the United States, specifically Georgia and Alabama peanut belts, with secondary sourcing from Argentina and China for conventional oil inputs. Raw material dependencies include mechanically extracted peanut oil, hydrogenated vegetable oil stabilizers, and high-protein runner varieties. Single-source vulnerability in Southeast shelling infrastructure creates concentration risk during harvest volatility periods. Distribution runs through conventional supermarket slotting-fee structures, club store volume anchors, and expanding convenience store pouch formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reduced fat peanut butter market functions as a cost-of-compliance story, with FDA's updated Nutrition Facts labeling mandates creating a barrier-to-entry moat that consolidates shelf access around manufacturers with captive reformulation labs and third-party certification capacity.
For Market Incumbents: Lock in upstream supply security through backward integration into Georgia and Alabama shelling infrastructure, securing grade-compliant runner peanut streams that insulate against harvest volatility and input cost spikes. Accelerate captive organic certification capacity to defend margin position against private-label specialists encroaching on natural grocery channels. Prioritize R&D investment in stabilizer alternatives that anticipate clean-label enforcement exposure. For New Entrants and Emerging Players: Fitness-focused direct-to-consumer subscription platforms represent an underserved buyer archetype with minimal incumbent penetration and tolerance for premium pricing. White-space targets include portion-controlled pouch formats for post-workout consumption occasions and certified organic spreads for health food shop networks in metropolitan markets. The most penetrable segment is convenience store single-serve distribution, where established players maintain limited presence. Deploy influencer-backed digital sampling as the primary go-to-market angle to bypass slotting-fee barriers. For Investors and Strategic Acquirers: Accelerated FDA compliance deadline extensions or enforcement actions against reduced-fat claim discrepancies are the leading indicator that consolidation momentum is shifting toward documented reformulation leaders. Long-term viability across the projection horizon rests on manufacturers with vertically integrated agricultural processing and demonstrated certification throughput. Acquisition target archetype: mid-scale co-manufacturers with USDA-aligned quality systems and underutilized emulsion capacity. Monitor state-level nutrition disclosure law expansions beyond California and New York as the critical inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Lab Investment | FDA disclosure mandates force documented emulsion testing that compliant producers leverage for shelf placement. |
| Organic Certification Capacity | USDA organic verification captures margin premiums in natural grocery channels and health food shop networks. |
| Pouch Packaging Expansion | Convenience store and fitness center penetration diversifies revenue beyond jar-dependent supermarket economics. |
| Backward Integration into Shelling | Georgia and Alabama peanut belt control secures grade-compliant input streams against harvest volatility. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models bypass slotting fees and capture post-workout consumption occasions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with peanut processing facility managers, natural grocery category buyers, food service procurement directors, and reformulation R&D leads at spread manufacturers. FDA enforcement documentation, USDA grading standards, and state-level nutrition disclosure statutes provided regulatory boundary conditions. Bottom-up shipment data from shelling cooperatives and top-down retail audit information were reconciled through iterative triangulation.
Data-stream reconciliation across production volume, trade flow, and point-of-sale records enabled segmentation modeling by texture variant, ingredient base, packaging format, and distribution channel throughout the forecast period. CAGRs were derived from trend extrapolation adjusted for regulatory compliance cost trajectories and channel shift elasticity. Industry-specific forecast inputs included peanut harvest yield projections and hydrogenated oil stabilizer price indices.
Revisions become necessary when FDA enforcement intensity escalates, peanut oil input volatility exceeds historical bands, or state-level disclosure mandates proliferate beyond current jurisdictions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and consumer clean-label preference stability. Practitioners should monitor USDA grade specification changes and third-party certification backlog durations for early signals of supply constraint or compliance bottleneck formation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
Cashew Nut Butter Market