
 Kale Chips Market | 2026-2036
Kale Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Kale Chips Market Outlook
Avocado oil is restructuring cost and flavor profiles across premium kale chip lines as brands abandon sunflower and canola bases. BRAD'S PLANT BASED, LLC leverages its Los Angeles manufacturing footprint to control West Coast distribution. The Kale Factory anchors its model on small-batch dehydration, sustaining higher price points through limited production runs. Vermont Kale Chips competes through direct-to-consumer subscription channels that bypass conventional retail slotting fees.
Kale chips are dehydrated or baked leaf vegetable snacks produced from Brassica oleracea var. sabellica, typically seasoned and dried at temperatures between 105°F and 140°F to preserve enzymatic activity and nutrient density. The finished product serves as a shelf-stable, nutrient-dense alternative to conventional potato and corn snacks in the better-for-you snack category. Organic ingredient positioning commands the deepest margin pools as consumers pay premiums for certified supply chains, while gluten-free claims function as table stakes rather than differentiators across most retail channels. Pouch packaging dominates unit economics through lighter shipping weights and reduced shelf space requirements compared to rigid canisters.
FDA nutrition labeling requirements and USDA organic certification standards govern product claims and market access across the United States, with enforcement actions rising against unsubstantiated superfood marketing. State-level cottage food laws in Vermont and California create parallel regulatory pathways for small producers entering retail. Stakeholders must monitor evolving EPA guidance on commercial dehydration emissions as thermal processing scales to meet forecast volume expansion.
Market Dynamics
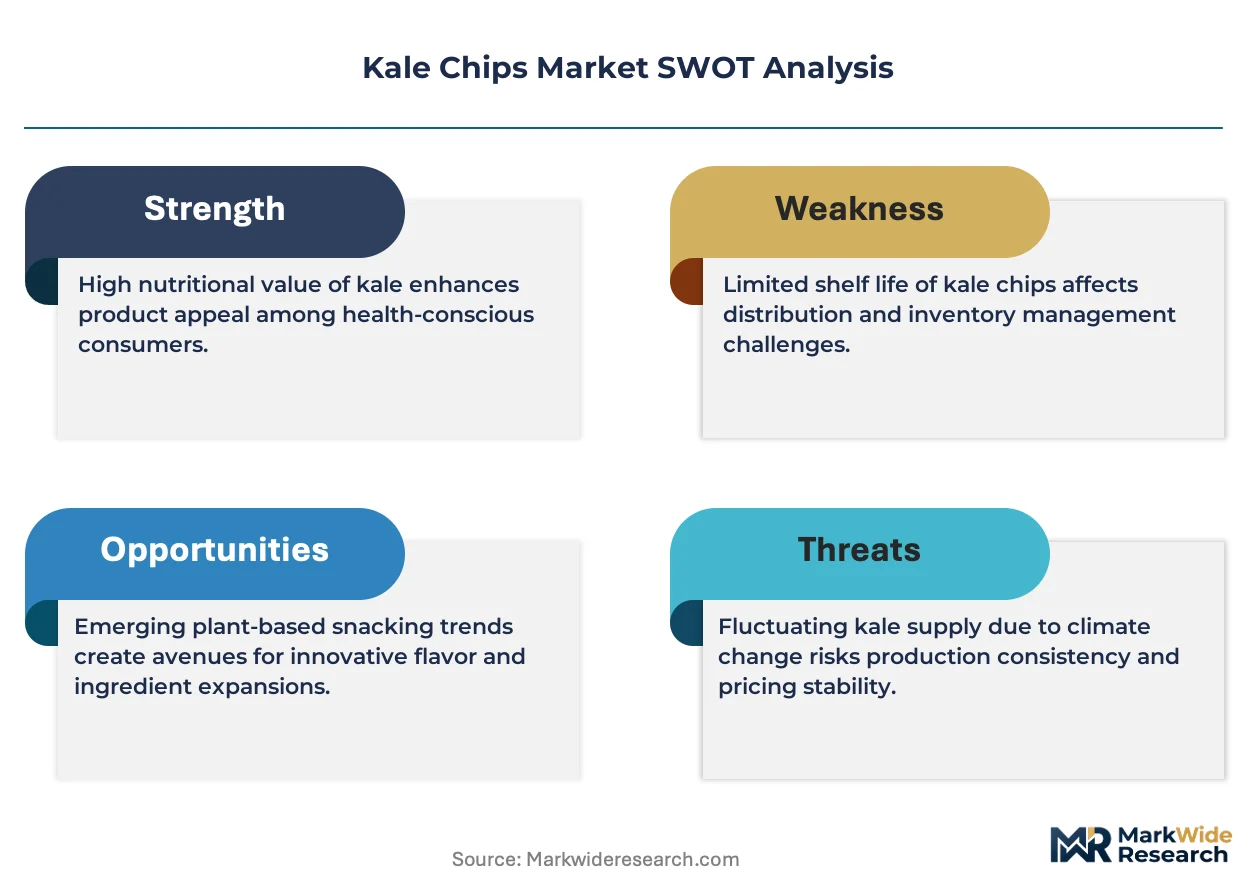
Clean-label ingredient mandates from FDA and EFSA are forcing kale chip manufacturers to reformulate away from synthetic preservatives and flavor enhancers, compressing formulation flexibility while opening premium positioning for compliant brands.
Growth Catalysts
- Gen Z snack substitution:Younger consumers in coastal United States cities are displacing conventional potato chip consumption with vegetable-based alternatives, creating volume pull through specialty retail channels.
- REACH additive restrictions:European chemical regulations are banning titanium dioxide and certain artificial colorants, advantaging brands with pre-certified clean-label supply chains.
- Dehydration efficiency gains:Low-temperature vacuum drying technology is reducing energy input per kilogram of finished product, improving unit economics for mid-scale producers.
Market Restraints
- Organic kale input concentration:Certified organic brassica supply concentrates in California's Central Valley and Mexico's Baja region, creating weather-dependent price volatility.
- Moisture barrier limitations:Compostable packaging films lack the oxygen transmission rates of conventional multilayer plastics, shortening shelf life and constraining distribution radius.
- Savory snack substitution:Seaweed crisps and mushroom jerky occupy similar price-positioning and nutrient-density profiles, fragmenting shelf space allocation.
Strategic Opportunities
- Direct-to-consumer subscription:Brands bypassing conventional retail slotting fees through recurring delivery models capture margin otherwise lost to distributor markups.
- School nutrition programs:USDA Smart Snacks in School standards create institutional procurement channels for low-sodium, whole-food alternatives meeting competitive food guidelines.
- Upcycled stem inclusion:Processing technology enabling edible use of kale stalks otherwise discarded reduces raw material waste and input cost per unit.
Industry Challenges
- Thermal processing emissions compliance:EPA commercial dehydrator emission thresholds require capital expenditure on scrubber systems or facility relocation for scaling producers.
- Organic certification timeline:Three-year land transition requirements and annual audit costs delay market entry for new farm suppliers, constraining raw material expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kale Chips Market |
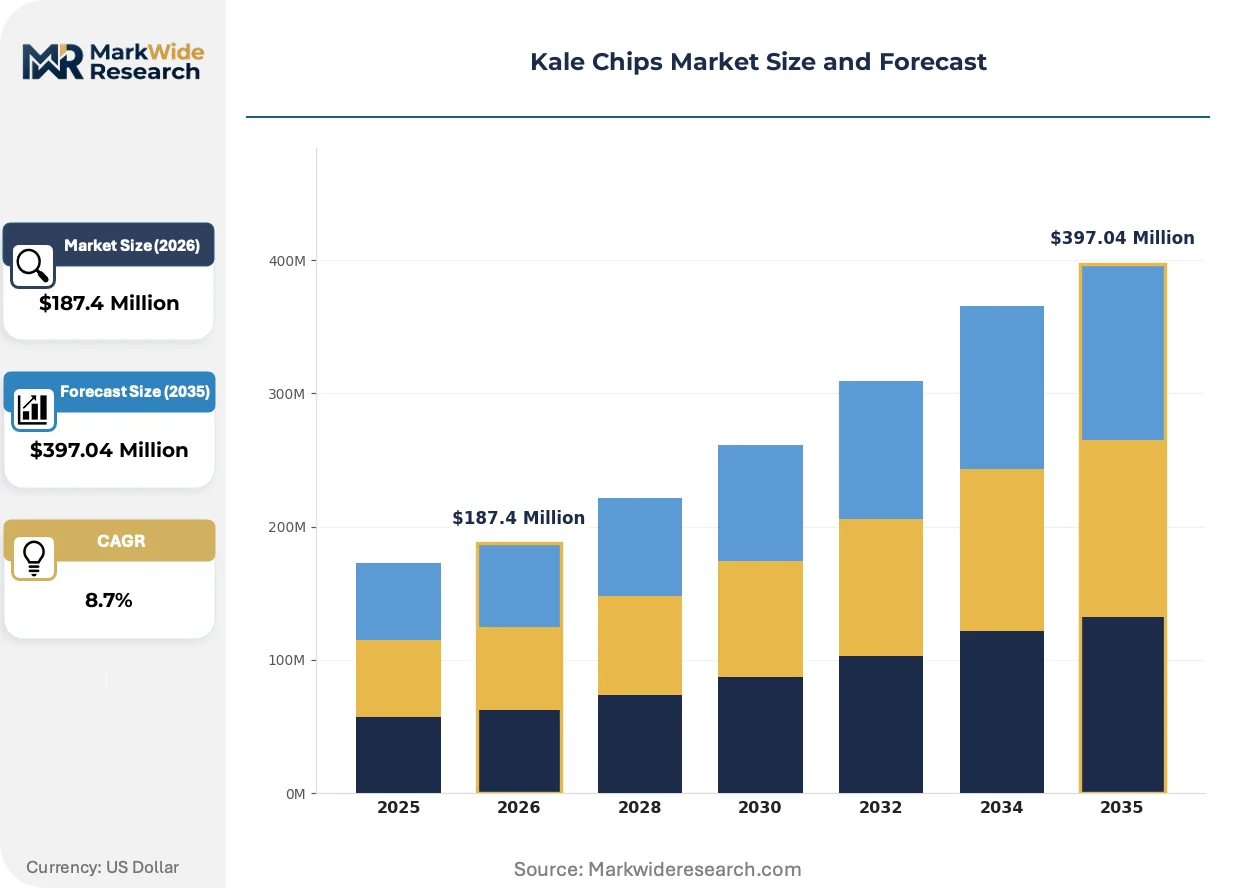
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Spicy, Cheesy, Barbecue Ingredient Type: Organic, Non-GMO, Gluten-Free, Vegan Package Type: Bag, Box, Canister, Pouch Distribution Channel: Online, Supermarket, Health Food Stores, Specialty Stores |
| Companies Covered | BRAD'S PLANT BASED, LLC, The Kale Factory, Vermont Kale Chips, Simply 7 Snacks, Healthy Crunch, Nagano Prefecture, The Angel Kale Company, Chicago Kale Chip Co., Takebayashi WB Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kale Chips Market Strategic Shifts
Avocado oil is displacing legacy seed oils as the dominant lipid substrate, while dehydration automation and packaging material science converge to extend shelf stability without synthetic preservatives.
Low-temperature vacuum dehydration is consolidating control over premium segment production economics. This technology preserves heat-sensitive glucosinolates and chlorophyll content that conventional air-drying degrades. West Coast contract manufacturers are adopting these systems to serve private-label clients demanding nutrient-retention claims. The capital intensity of this equipment is consolidating premium production among facilities with sufficient throughput to amortize investment.
EFSA's 2021 reclassification of titanium dioxide as a food additive no longer considered safe is reshaping European formulation standards. Brands exporting to EU markets must eliminate whitening agents from seasoning blends and find mineral-based alternatives. United States manufacturers with established clean-label positioning are capturing shelf space from legacy brands requiring reformulation cycles.
Retail buyer consolidation is compressing supplier negotiation leverage. Natural food cooperative distributors and regional grocery chains are merging procurement functions, reducing the number of discrete buyers a brand must reach for national coverage. Pacific Northwest and Northeast metropolitan clusters show the earliest concentration of buyer power, with independent retailers forming purchasing alliances to match chain-scale terms.
Kale Chips Market Segmentation
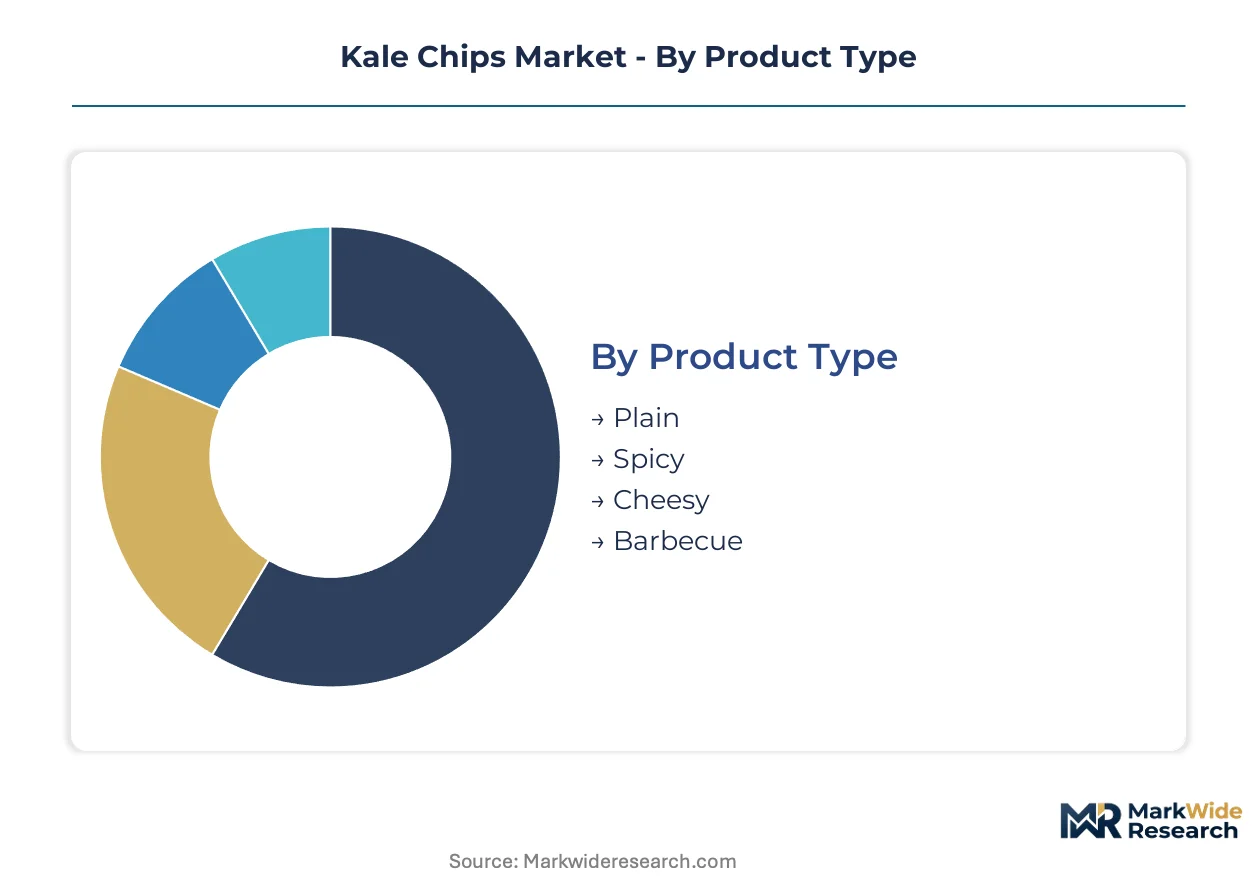
Kale chip manufacturers navigate distinct demand profiles across flavor preferences, ingredient certifications, packaging formats, and retail channels. Each dimension carries different margin structures and regulatory exposure that shape portfolio prioritization.
Product Type:
Flavor differentiation separates impulse purchasers from habitual buyers, with heat tolerance and familiarity driving repeat rates.
- Plain:Unseasoned dehydrated kale leaves with minimal processing retain the highest glucosinolate content. Coastal United States consumers in Los Angeles and Seattle metro areas favor this format for clean-label adherence and recipe versatility.
- Spicy:Cayenne, jalapeño, or habanero-based seasonings create sensory distinction in crowded snack aisles. Heat-forward profiles command premium shelf placement in Texas and Arizona markets where Latin flavor influence runs deep.
- Cheesy:Nutritional yeast and cashew-based coatings replicate dairy flavor without animal ingredients. This segment attracts flexitarian households seeking indulgence cues without lactose content.
- Barbecue:Smoked paprika and molasses-forward seasoning blends target conventional chip switchers. Midwestern United States consumers show strongest affinity for this familiar flavor bridge.
Volume sits with Plain; growth tilts toward Spicy.
Ingredient Type:
Certification depth determines price positioning and distributor access, with organic commanding the steepest premium multiples.
- Organic:USDA-certified supply chains require three-year land transition and annual third-party audit. California Central Valley and Mexico Baja sourcing regions concentrate production, creating weather-dependent input volatility.
- Non-GMO:Verified absence of bioengineered ingredients through supply chain documentation. This claim functions as baseline expectation rather than differentiator in natural food channels.
- Gluten-Free:Third-party tested assurance against cross-contamination for celiac-sensitive consumers. FDA labeling enforcement has elevated testing rigor, compressing margins for non-compliant entrants.
- Vegan:Absence of animal derivatives including honey, dairy, and egg-based seasonings. Gen Z and millennial buyers in urban coastal markets prioritize this attribute above other certifications.
Organic captures the deepest margin pools; Vegan shows the steepest expansion trajectory.
Package Type:
Format selection trades shelf stability against shipping economics and retail space constraints.
- Bag:Flexible multilayer plastic with nitrogen flush extends shelf life to 9-12 months. Dominates club store and mass retail channels where volume throughput matters.
- Box:Paperboard secondary packaging with inner film barrier supports gift-oriented and subscription box positioning. Higher per-unit cost limits penetration beyond premium channels.
- Canister:Rigid paper or plastic cylinders with resealable lids. Favored by consumers prioritizing pantry organization and portion control; shipping weight disadvantages constrain e-commerce adoption.
- Pouch:Lightweight flexible packaging with zip closure dominates unit economics through reduced dimensional weight. Stand-up formats secure prime shelf placement in grab-and-go retail zones.
Pouch leads unit volume; Box climbs fastest in direct-to-consumer channels.
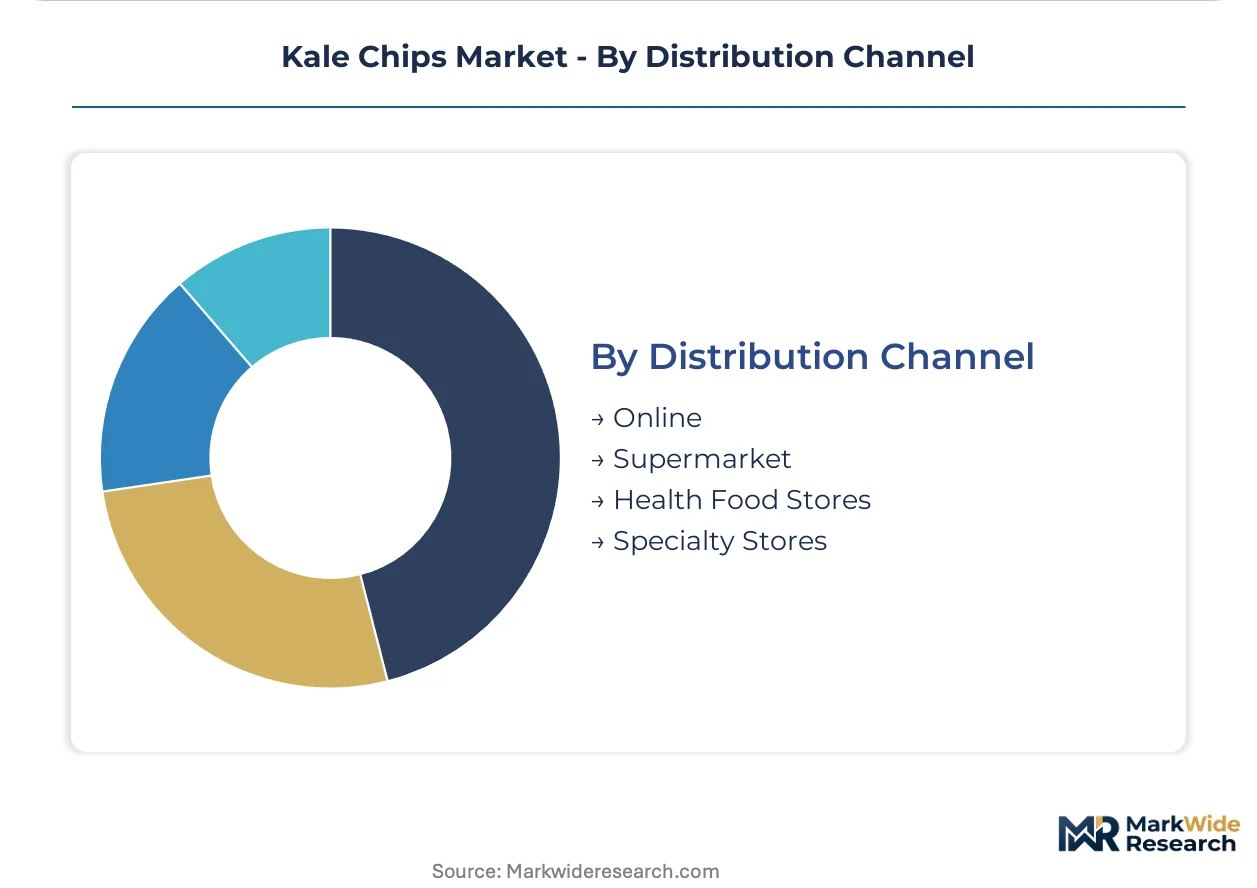
Distribution Channel:
Channel mix determines margin capture versus brand control, with slotting fee structures varying dramatically.
- Online:Brand-controlled storefronts and third-party marketplace presence. Subscription models bypass distributor markups, though customer acquisition costs pressure unit economics.
- Supermarket:Conventional grocery placement requires slotting fee investment and promotional fund commitments. National chain buyers consolidate leverage, compressing supplier negotiation position.
- Health Food Stores:Regional natural food cooperatives and independent retailers. Pacific Northwest and Northeast clusters show earliest buyer alliance formation to match chain-scale procurement terms.
- Specialty Stores:Gourmet food boutiques and fitness center retail. Highest per-square-foot velocity for premium-positioned lines; limited geographic reach constrains scale.
Supermarket anchors volume share; Online expands most quickly as brands circumvent retail gatekeepers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley agricultural enterprise zones concentrate organic brassica cultivation, drawing kale chip manufacturers to co-locate dehydration facilities near certified organic feedstock sources.
United States
Coastal urban consumers in Los Angeles and Seattle metro areas displace conventional snack consumption with vegetable-based alternatives. FDA nutrition labeling requirements and USDA organic certification standards govern product claims and market access. Pacific Northwest metropolitan clusters show the earliest concentration of natural food cooperative purchasing alliances.
Germany
REACH additive restrictions from ECHA are banning titanium dioxide and certain artificial colorants, advantaging brands with pre-certified clean-label supply chains. EFSA reclassification of whitening agents is reshaping European formulation standards. Berlin and Hamburg anchor distribution networks serving private-label clients demanding nutrient-retention claims.
Japan
Health-conscious metropolitan consumers in Tokyo and Osaka prioritize certified organic supply chains for enzymatic activity preservation. METI guidance on commercial food processing emissions influences thermal dehydration facility siting decisions. Nagano Prefecture hosts concentrated small-batch producers leveraging regional vegetable cultivation heritage.
Canada
Health Canada and PMRA enforcement actions are rising against unsubstantiated superfood marketing claims in the better-for-you snack category. Provincial organic certification programs create parallel regulatory pathways for cross-border suppliers. British Columbia and Ontario metropolitan markets concentrate specialty retail channel penetration.
United Kingdom
EFSA clean-label mandates are compressing formulation flexibility while opening premium positioning for compliant brands. London and Southeast England clusters show strongest affinity for vegan-certified positioning among Gen Z and millennial buyers. Independent retailers in metropolitan areas are forming purchasing alliances to match chain-scale procurement terms.
Kale Chips Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium-positioned lines consolidating around small-batch dehydration capabilities and mass-market volumes flowing through West Coast contract manufacturing facilities. The competitive set organizes into three strategic archetypes: vertically integrated farm-to-bag operators, regional craft specialists leveraging direct-to-consumer subscription channels, and private-label manufacturers serving retail buyer consolidation. Dominant competitive moves include facility relocation to evade EPA commercial dehydrator emission thresholds and backward integration into certified organic brassica cultivation to secure input supply.
Within the farm-to-bag archetype, BRAD'S PLANT BASED, LLC exemplifies West Coast manufacturing footprint control, while The Kale Factory occupies a position anchored on small-batch dehydration economics. Vermont Kale Chips represents the direct-to-consumer subscription model, bypassing conventional retail slotting fees through recurring delivery infrastructure.
| Leading Market Players |
|---|
| BRAD'S PLANT BASED, LLC |
| The Kale Factory |
| Vermont Kale Chips |
| Simply 7 Snacks |
| Healthy Crunch |
| Nagano Prefecture |
| The Angel Kale Company |
| Chicago Kale Chip Co. |
| Takebayashi WB Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive supply of certified organic brassica feedstock anchors both the supply position and the pricing power for premium kale chip manufacturers, with California Central Valley and Mexico Baja cultivation zones concentrating input control among vertically integrated operators who bypass commodity spot volatility.
Pricing Analysis
Volume sits with mass-market pouch formats while margins concentrate in small-batch organic lines. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic SKUs from non-GMO verified and conventional alternatives. Pricing pressure stems from compostable packaging film premiums and organic input cost volatility. Price-sensitive conventional grocery buyers drive standard-tier negotiations, while direct-to-consumer subscribers absorb premium-tier markups with minimal elasticity.
Supply Chain Analysis
Domestic-content mandates in USDA school nutrition programs are reshaping sourcing toward United States-certified organic acreage, pressuring brands with Mexico-dependent supply chains. Raw material flows draw from California Central Valley, Mexico Baja, and emerging Arizona cultivation zones. Dehydration equipment and nitrogen-flush packaging films rest on concentrated supplier bases. Single-source vulnerability runs through organic seed stock and low-temperature vacuum dryer fabrication. Distribution runs through natural food cooperative networks and direct-to-consumer subscription infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification backlog functions as the binding capacity constraint, propping pricing premiums as three-year land transition requirements throttle new farm supplier entry.
For Market Incumbents: Deploy dehydration automation to compress unit costs as seaweed crisps and mushroom jerky fragment savory snack shelf space. Secure captive supply of Arizona-certified organic acreage ahead of climate volatility in California Central Valley. Deepen backward integration into seed breeding programs to reduce single-source germplasm risk. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer the lowest customer acquisition friction against incumbent slotting fee advantages. Target Pacific Northwest metropolitan clusters where natural food cooperative purchasing alliances concentrate buyer access. Exploit upcycled stem processing technology to undercut conventional feedstock costs by fifteen to twenty percent. For Investors and Strategic Acquirers: Exit pathways concentrate in farm-to-bag vertical integration plays with certified organic land assets and established direct-to-consumer infrastructure. Five-to-ten-year viability hinges on climate-adaptive cultivation geography and EPA emission compliance positioning. Monitor organic certification application backlogs as the inflection signal for input cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive supply of California Central Valley and Arizona acreage insulates against Mexico Baja weather volatility. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models bypass supermarket slotting fees and capture margin lost to distributor markups. |
| Low-Temperature Vacuum Dehydration Adoption | Glucosinolate preservation technology commands premium shelf placement in EFSA-compliant European export channels. |
| Upcycled Stem Processing Scale-Up | Edible stalk inclusion reduces raw material waste and compresses per-unit feedstock costs for mid-tier positioning. |
| Compostable Packaging Film Transition | Oxygen barrier limitations in bio-based films constrain distribution radius but satisfy REACH-driven clean-label mandates. |
Study Parameters
Multi-period observation of organic certification timelines, dehydration capacity buildouts, and retail buyer consolidation anchored the trend analysis, supplemented by interviews with brand managers at kale chip manufacturers, category buyers at natural food cooperatives, supply planners at organic brassica distributors, and regulatory affairs leads at USDA-accredited certification bodies. Secondary validation drew from FDA nutrition labeling guidance documents, EPA commercial dehydrator emission thresholds, EFSA additive reclassifications, Nielsen retail audit data for better-for-you snacks, and organic acreage reports from California Department of Food and Agriculture. Bottom-up production capacity estimates triangulated against top-down retail velocity data.
Segment-weighting across flavor profiles, ingredient certifications, packaging formats, and distribution channels shaped the analytical framework over the projection horizon. Modeled dimensions included organic versus conventional supply chains, small-batch versus mass-production dehydration economics, and direct-to-consumer versus conventional retail channel mix. CAGRs were derived from trend extrapolation of volume and value indicators across the analysis window, incorporating dehydration efficiency gain curves and organic input cost trajectories as industry-specific forecast inputs.
Inputs from certification body disclosure filings and cooperative procurement alliance announcements were available through the study window; gaps in real-time organic acreage transition data and private-label contract terms introduce uncertainty bands around supply-side capacity estimates. Forecasts reflect documented assumptions regarding EPA emission threshold enforcement timing and EFSA clean-label mandate adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Potato Chips Market
Snacks
Fiber Bars Market
Snacks
Global Tortilla Chips Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Nutritional Bar Market
Snacks
North America Savory Snacks Market
Snacks
Meat Snacks Market
Snacks
Seaweed Snacks Market
Snacks
Refrigerated Snacks Market
Snacks
UAE Cereal Bar Market
Snacks
Fat Free Snacks Market
Snacks
Europe Snacks Market
Snacks
Baked Chips Market
Snacks
Cereal Bars Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
North America Fruit Snacks Market