
 North America Peanut Butter Market | 2026-2036
North America Peanut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Peanut Butter Market Intelligence
Multi-source procurement from domestic and Argentine peanut suppliers is pivoting as North American processors seek supply resilience against climate volatility. The J.M. Smucker Company leverages its vertically integrated roasting and grinding infrastructure to sustain cost advantages across conventional and natural product lines. Hormel Foods Corporation anchors its position through private-label manufacturing scale, while Conagra Brands differentiates via SKU proliferation in on-trend flavor extensions and portion-controlled formats.
North America peanut butter is a shelf-stable spread produced by grinding roasted peanuts to a paste consistency, typically containing 90 percent or more peanut content with optional stabilizers, sweeteners, and salt to control oil separation and extend shelf life. Its primary commercial purpose spans retail table spreads, food-service ingredient applications, and industrial inputs for confectionery and nutrition-bar manufacturing. Creamy and crunchy product types dominate volume, though organic claims command disproportionate margin pools as health food stores and online retail channels expand shelf space for certified-clean-label offerings. Jar packaging retains household penetration leadership, while pouch and pump dispenser formats gain traction in food-service and fitness-oriented end-user segments where portability and portion control drive purchase decisions.
The FDA governs peanut butter identity standards through minimum peanut content thresholds and allergen labeling mandates under the Food Allergen Labeling and Consumer Protection Act, while USDA organic certification requirements shape premium-tier product development and channel access. Health Canada enforces parallel allergen regulations and bilingual labeling standards that condition cross-border product formulation and packaging investments. Stakeholders must monitor evolving added-sugar disclosure thresholds and front-of-pack labeling proposals across both jurisdictions, as these regulatory trajectories will determine reformulation costs and competitive positioning in health-claim-eligible segments.
Market Dynamics
The FDA's added-sugar disclosure mandate and Health Canada's bilingual labeling requirements are forcing simultaneous reformulation and packaging redesign across North American processors, compressing margin structures while opening premium positioning for compliant clean-label portfolios.
Growth Catalysts
- Protein-forward snacking:Fitness enthusiasts and meal-prep consumers are integrating peanut butter into portable nutrition formats, expanding consumption occasions beyond traditional breakfast spreads.
- USDA organic certification:Premium-tier channel access through health food retailers and e-commerce platforms rewards processors who meet stringent supply chain traceability standards.
- Club-channel velocity:Warehouse retailers in the United States are driving volume through bulk-format private-label offerings that capture household pantry stocking behavior.
Market Restraints
- Argentine supply concentration:Climate volatility in South American growing regions creates input cost instability for processors dependent on imported peanut stocks.
- Allergen labeling mandates:The Food Allergen Labeling and Consumer Protection Act imposes strict facility segregation requirements that elevate manufacturing overhead.
- Seed oil substitutes:Sunflower and soy-based spreads are capturing price-sensitive consumers in conventional retail channels.
Strategic Opportunities
- Canadian retail underpenetration:Private-label penetration and club-channel development lag US benchmarks, presenting expansion headroom for format innovators.
- Food-service pump dispensers:Portion-controlled dispensing systems are displacing jar formats in fitness centers and workplace cafeterias.
- Industrial confectionery inputs:Nutrition bar manufacturers are sourcing certified peanut paste for clean-label protein fortification.
Industry Challenges
- Roasting technician scarcity:Precision temperature control expertise for flavor profile consistency is concentrated among aging workforce cohorts.
- Dual-jurisdiction compliance:Simultaneous FDA and Health Canada reformulation timelines compress product development cycles.
- Legacy grinding infrastructure:Stone mill and steel cutter maintenance requires specialized mechanical knowledge that suppliers are retiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Peanut Butter Market |
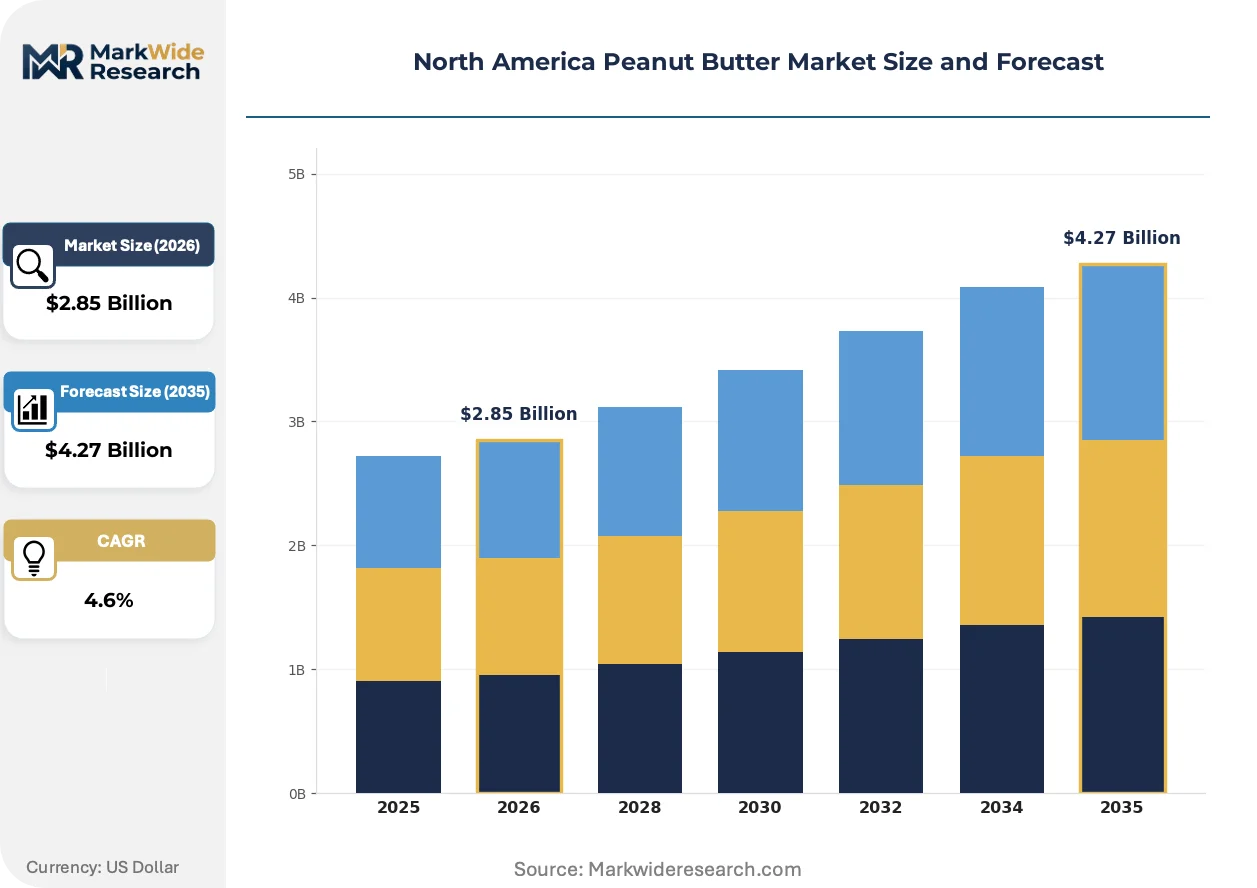
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.27 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Crunchy, Creamy Packaging Type: Tub, Jar, Pouch, Pump Dispenser Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores End User: Households, Food Service, Manufacturers, Fitness Enthusiasts |
| Companies Covered | Procter & Gamble, Boulder Brands, The J.M. Smucker Company, Algood Food Company, Kraft Canada, Hormel Foods Corporation, Unilever, The Hershey Company, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Peanut Butter Market Strategic Shifts & Innovations
Formulation science and packaging engineering are converging to address oil separation and portability constraints that have historically limited peanut butter's addressable occasions. Processors are investing in stabilizer alternatives and portion-control formats that align with regulatory disclosure mandates and on-the-go consumption patterns.
High-pressure processing technology is modularizing clean-label manufacturing by eliminating thermal degradation of peanut flavor compounds while achieving commercial sterility without synthetic preservatives. Natural and organic processors in the United States are adopting HPP systems at accelerating rates. This capability compression allows smaller facilities to compete with conventional roasting infrastructure on shelf-stability claims.
The FDA's updated Nutrition Facts labeling requirements are mandating added-sugar line-item disclosure that exposes sweetened conventional formulations to consumer scrutiny. Reformulation costs are concentrating among mid-tier processors lacking R&D scale. The natural segment is responding by marketing zero-added-sugar certifications as competitive differentiators in health-claim-eligible retail placements.
Direct-to-subscription models are displacing conventional grocery replenishment cycles among fitness-oriented households. Online specialty retailers are capturing recurring revenue through curated protein-forward assortments. This channel pivot is most visible in United States metropolitan markets where delivery density supports economically viable fulfillment networks.
North America Peanut Butter Market Segmentation
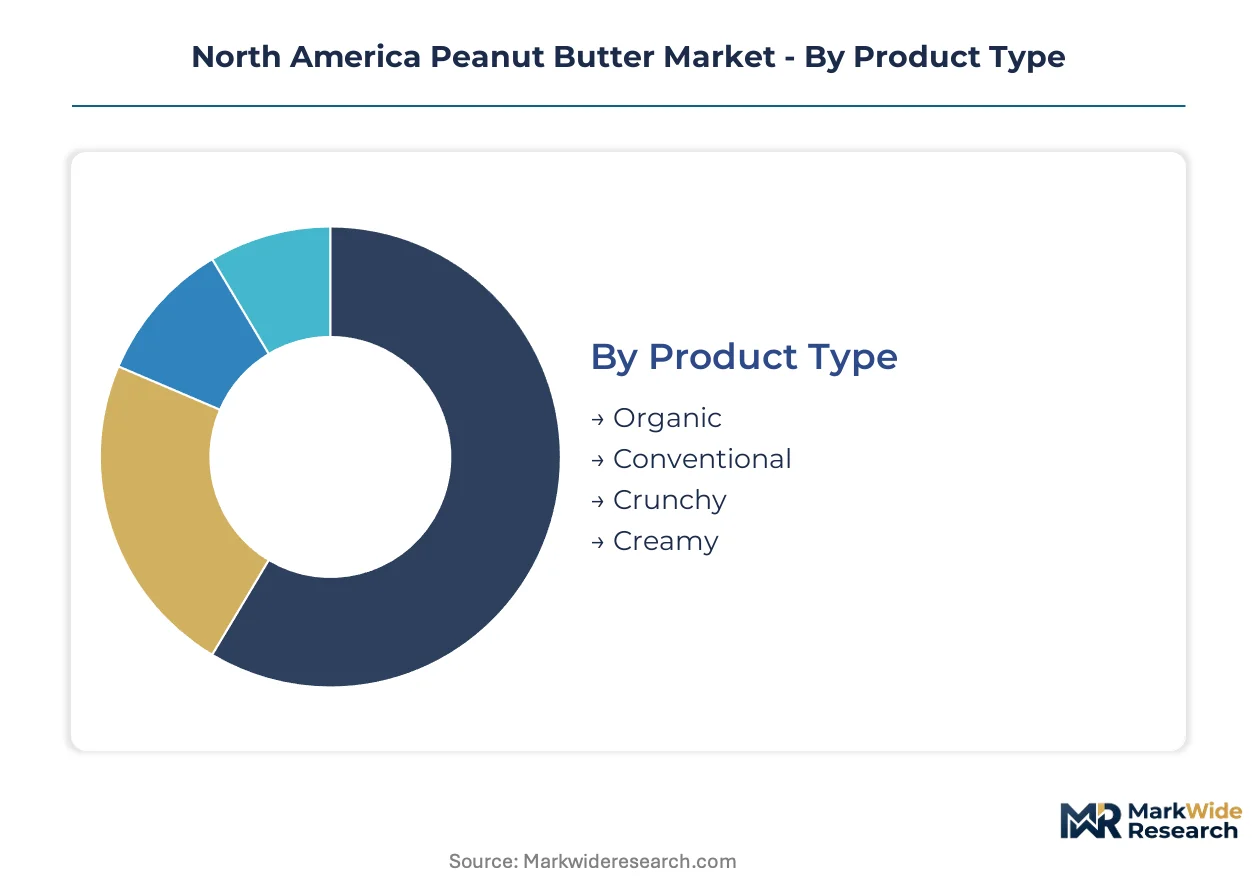
Segmentation in North American peanut butter reveals how supply chain configuration, regulatory exposure, and channel economics concentrate margin capture across distinct product and packaging tiers. Processors align formulation investments with the specific compliance burdens and velocity requirements of each segment.
Product Type:
Supply concentration in roasted peanut procurement favors processors with multi-origin sourcing capabilities that can flex between domestic and Argentine stocks.
- Creamy:Achieved through finer grinding mesh sizes that reduce particle suspension and improve spreadability. Household demand in the United States concentrates this segment, where club-channel bulk purchasing and private-label velocity sustain volume leadership despite thinner per-unit margins.
- Organic:Requires USDA certification and supply chain traceability from shelling through retail. Health food stores and online specialty retailers reward compliant processors with premium shelf placement and recurring subscription revenue.
- Conventional:Standard formulations with stabilizers and added sweeteners dominate conventional retail shelf space. FDA added-sugar disclosure mandates are elevating reformulation costs for mid-tier processors lacking R&D scale.
- Crunchy:Incorporates peanut fragment inclusions that require modified grinding sequences and particle size control. Regional brand loyalty in the southeastern United States sustains niche positioning against creamy dominance.
Creamy absorbs the bulk of installed capacity; Organic is expanding most quickly.
Packaging Type:
Cost tier differentiation separates commodity jar formats from engineered dispensing systems that command price premiums in institutional channels.
- Jar:Glass and PET containers retain household penetration leadership through established retail shelf sets and pantry storage compatibility. Supermarket and club-channel velocity in the United States reinforces this format's volume concentration despite higher shipping cube costs.
- Pump Dispenser:Portion-controlled systems with calibrated dose mechanisms displace traditional formats in food-service and fitness center applications. Workplace cafeteria contracts and gym chain procurement specifications are accelerating adoption.
- Pouch:Flexible film structures with tear-notch and spout configurations target portable consumption occasions. Online retail fulfillment economics favor lighter shipping weights for direct-to-consumer subscription models.
- Tub:Wide-mouth polypropylene containers serve industrial confectionery and nutrition bar manufacturing inputs. Bulk purchasing by contract manufacturers concentrates demand in Midwestern processing clusters.
Jar retains the largest production footprint; Pump Dispenser is climbing the fastest.
Distribution Channel:
Volume throughput separates high-velocity club and supermarket formats from specialty channels where certification claims command margin premiums.
- Supermarkets:Conventional grocery retail maintains the broadest SKU assortment and promotional frequency. Private-label penetration in the United States compresses branded pricing power while sustaining category household penetration.
- Online Retail:Direct-to-subscription models and curated protein-forward assortments capture recurring revenue from fitness-oriented households. Metropolitan delivery density in the United States supports economically viable fulfillment networks.
- Health Food Stores:Certified organic and clean-label SKUs receive disproportionate shelf space and promotional support. USDA organic certification requirements condition channel access and supplier qualification.
- Convenience Stores:Single-serve and portable formats target immediate consumption occasions. Grab-and-go placement in travel corridors and urban centers sustains incremental volume.
Supermarkets absorb the bulk of throughput capacity; Online Retail is gaining share fastest.
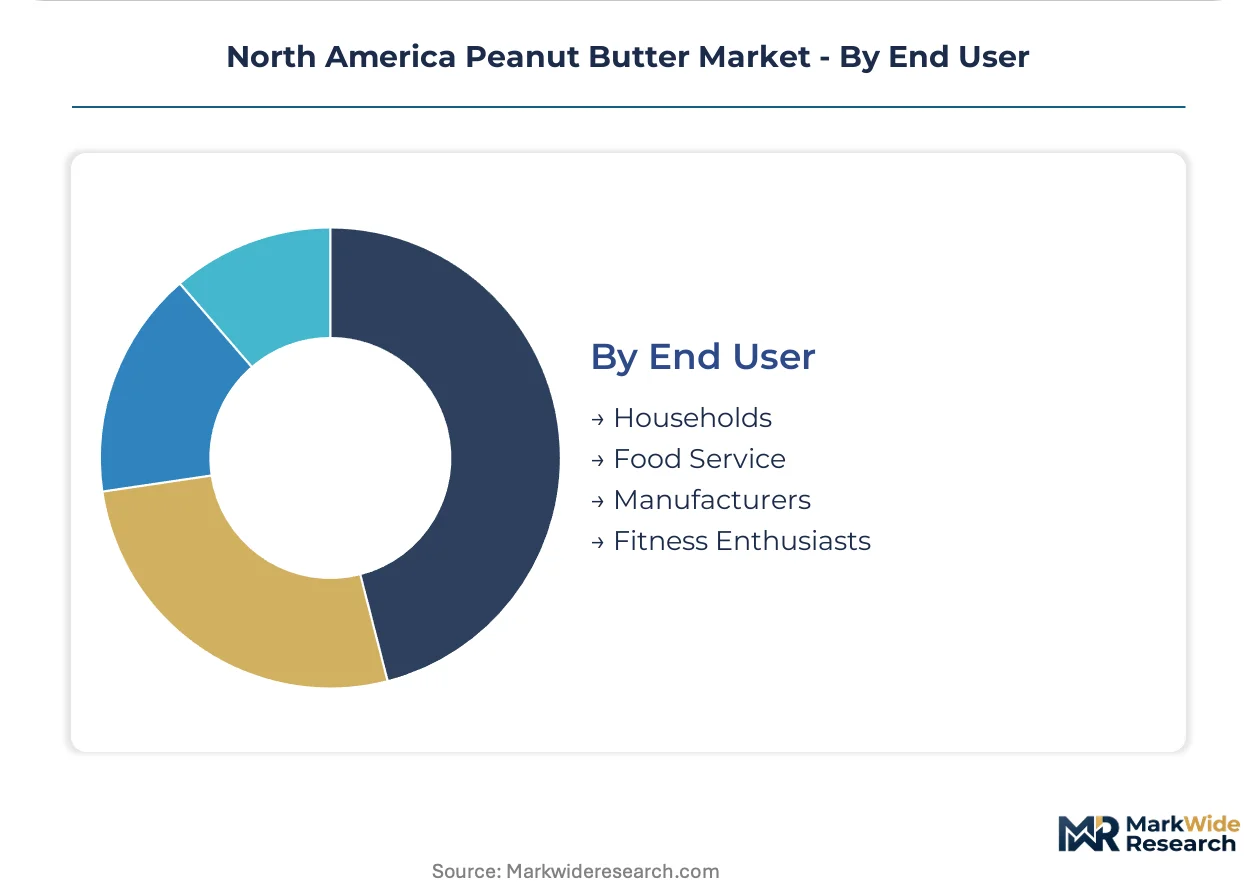
End User:
Application requirements separate household table-spread consumption from ingredient-grade specifications that industrial buyers enforce.
- Households:Retail consumers purchasing for pantry stocking and meal preparation drive conventional and natural segment volume. Club-channel bulk purchasing behavior in the United States concentrates demand in multi-pack jar formats.
- Manufacturers:Industrial confectionery and nutrition bar producers source certified peanut paste with specified particle size and microbiological standards. Clean-label protein fortification requirements are elevating organic input demand.
- Food Service:Institutional kitchens and restaurant chains specify pump dispenser compatibility and portion control for back-of-house efficiency. Health Canada bilingual labeling requirements condition cross-border contract specifications.
- Fitness Enthusiasts:Protein-forward snacking integration drives pouch format adoption and subscription replenishment cycles. Direct-to-consumer channels capture this segment with curated assortments and delivery convenience.
Households retain the largest demand base; Manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households concentrate the bulk of North American peanut butter consumption, with club-channel bulk purchasing and private-label velocity sustaining volume leadership. Canadian retail development and Mexican ingredient-grade demand create secondary growth poles with distinct regulatory and channel characteristics.
United States
Fitness-oriented protein snacking and direct-to-subscription e-commerce models are expanding consumption occasions beyond traditional breakfast spreads. FDA added-sugar disclosure mandates under updated Nutrition Facts labeling are forcing reformulation across conventional product lines. Georgia and Alabama shelling clusters supply domestic roasting infrastructure, while Texas and Oklahoma growing regions anchor multi-origin procurement flexibility.
Canada
Private-label penetration and club-channel development lag US benchmarks, presenting expansion headroom for format innovators targeting metropolitan Toronto and Vancouver households. Health Canada bilingual labeling requirements and parallel allergen regulations condition cross-border packaging investments and product qualification timelines. Quebec and Ontario retail corridors concentrate demand for certified organic SKUs through health food store networks.
Mexico
Industrial confectionery and nutrition bar manufacturers in Monterrey and Guadalajara are sourcing certified peanut paste for clean-label protein fortification applications. Mexican food safety authority COFEPRIS enforces allergen labeling standards that align with USMCA trade facilitation protocols. Bajío Region agribusiness clusters are developing shelling capacity to reduce import dependency for domestic processing facilities.
North America Peanut Butter Market Key Industry Players
Portfolio diversification dominates the current landscape as processors balance conventional volume segments against premium-tier certification requirements. The vendor base concentrates around three strategic archetypes: vertically integrated roasters with captive peanut supply, contract manufacturers serving private-label retail programs, and natural-specialty processors leveraging organic certification for channel access. M&A activity and capacity expansion in high-pressure processing technology represent the dominant competitive moves reshaping manufacturing capabilities.
Among established North American processors, The J.M. Smucker Company and Hormel Foods Corporation exemplify scale-driven archetypes with integrated manufacturing footprints, while Conagra Brands occupies a position emphasizing SKU proliferation and flavor innovation. These entities represent contrasting approaches to navigating simultaneous FDA and Health Canada compliance burdens while capturing divergent channel economics across club retail, food service, and direct-to-consumer segments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Boulder Brands |
| The J.M. Smucker Company |
| Algood Food Company |
| Kraft Canada |
| Hormel Foods Corporation |
| Unilever |
| The Hershey Company |
| Conagra Brands |
| Others |
Cost & Logistics Intelligence
Captive roasting and grinding infrastructure at J.M. Smucker anchors supply position and pricing power across both conventional and natural product lines, while mid-tier processors lacking backward integration into peanut procurement face margin compression from Argentine supply volatility and simultaneous FDA reformulation mandates.
Pricing Analysis
Service bundling separates club-channel private-label velocity from premium-tier organic certification plays, with the former unbundling R&D and brand marketing costs to hit price points below branded equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA organic certification, club-channel volume scale, and conventional retail placement. Pricing pressure stems from seed oil substitutes capturing price-sensitive consumers in conventional channels. Food-service buyers exhibit highest price sensitivity due to pump dispenser commoditization, while fitness enthusiasts show lowest sensitivity for subscription-model organic pouches.
Supply Chain Analysis
Direct-to-club-channel distribution handles hyperscale household pantry stocking demand in the United States, while food-service pump dispensers and online retail fulfillment operate through specialized logistics networks. Raw material sourcing draws from Georgia-Alabama domestic shelling clusters and Argentine import stocks, with grinding infrastructure resting on steel cutter and stone mill maintenance expertise concentrated among aging workforce cohorts. Single-source vulnerability in Argentine peanut supply creates input cost instability during South American climate shocks. Distribution runs through warehouse retailer consolidation centers, supermarket distribution networks, and direct-to-consumer fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around processors with captive supply chains and reformulation scale, as FDA added-sugar disclosure mandates and Health Canada bilingual requirements force weaker mid-tier players toward acquisition or exit.
For Market Incumbents: Cement position by deepening backward integration into domestic and Argentine peanut procurement to buffer climate volatility, while expanding high-pressure processing capacity to capture clean-label shelf-stability claims without synthetic preservatives. Threat from seed oil substitutes demands certification investment in USDA organic and zero-added-sugar positioning to defend premium channel access. For New Entrants and Emerging Players: Begin with Canadian retail underpenetration in private-label and club-channel formats, where metropolitan Toronto and Vancouver households lag US benchmarks for bulk purchasing behavior. Food-service pump dispenser contracts present white-space opportunity given workplace cafeteria and fitness center procurement specifications. Go-to-market angle: portion-controlled dispensing systems with bilingual labeling compliance for cross-border contract eligibility. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated roasters seeking regional capacity expansion or natural-specialty processors requiring organic certification infrastructure. Long-term viability favors entities with multi-origin sourcing flexibility and HPP technology deployment. Signal to watch: Argentine climate volatility frequency as indicator of input cost stress and consolidation pressure on import-dependent processors.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | HPP systems eliminate synthetic preservatives while achieving commercial sterility, opening clean-label channel access for smaller facilities. |
| Backward Integration into Peanut Procurement | Captive supply from Georgia-Alabama shelling clusters and Argentine contracts buffers climate-driven input cost volatility. |
| Zero-Added-Sugar Certification Investment | FDA disclosure mandates expose sweetened formulations to consumer scrutiny, rewarding compliant processors with health-claim-eligible placement. |
| Pump Dispenser Format Development | Portion-controlled systems displace jar formats in food-service and fitness center channels where back-of-house efficiency drives procurement. |
| Direct-to-Subscription Channel Launch | Online specialty retailers capture recurring revenue from fitness-oriented households through curated protein-forward assortments. |
Research Approach
Document review covered FDA regulatory filings, USDA organic certification databases, and customs trade records, complemented by interviews with peanut processing plant managers, club-channel category buyers, health food store procurement leads, and food-service distribution specialists. Secondary validation drew from SEC 10-K disclosures, Nielsen retail audit data, and Argentine agricultural export statistics. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Value and volume projections across the modeling period reflect segmentation by product type, packaging format, distribution channel, and end-user application, with CAGRs derived from historical velocity trends and regulatory impact assessment. Forecast inputs incorporated FDA reformulation timeline assumptions, Health Canada bilingual labeling implementation schedules, and high-pressure processing adoption curves among natural-specialty processors.
Underlying measurement precision varies by segment; club-channel velocity and supermarket private-label data carry tighter precision than emerging online retail and food-service pump dispenser categories. Forecasts reflect documented assumptions regarding Argentine supply stability and regulatory compliance cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Pecans Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Strawberry Seed Oil Market
Nuts and Seeds
Macadamia Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Carob Extract Market