
 Australia Snack Bar Market | 2026-2036
Australia Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Snack Bar Market Analysis
Asset-light contract manufacturing and third-party co-packing arrangements is rewriting competitive entry dynamics in the Australia snack bar sector. Nestlé S.A. leverages its global procurement scale to secure cost advantages on nut and dairy inputs. The Sanitarium Health and Wellbeing Company anchors its position through heritage brand equity and dominance in whole-grain and plant-based formulations. Carmen's Fine Foods Pty Ltd differentiates via premium positioning and localized supply chain control over Australian-grown ingredients.
An Australia snack bar is a shelf-stable, ready-to-eat confectionery or cereal-based bar, typically comprising grains, nuts, dried fruits, protein isolates, and binding syrups, formed through extrusion or cold-press processing and packaged for single-serve consumption. These products serve as meal replacements, sports nutrition aids, or convenience snacks for time-constrained consumers seeking portable energy. Protein bars command the strongest margin pools due to premium pricing and sports nutrition alignment, while granola bars sustain volume leadership through household pantry penetration. The ingredient-type dimension shows organic and low-sugar variants outpacing conventional formats as FSANZ labeling transparency and consumer wellness priorities reshape purchase criteria.
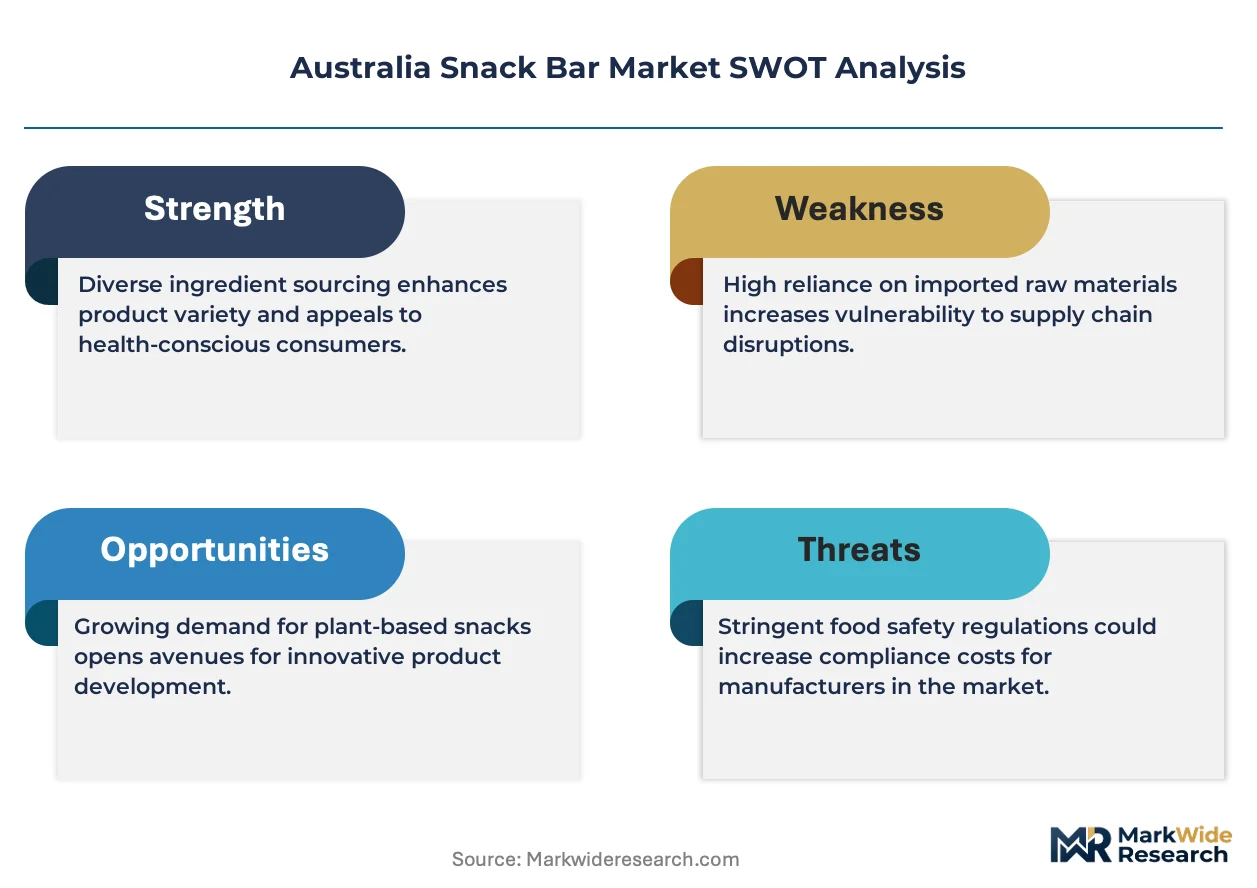
FSANZ mandates strict allergen declaration and nutrition content standards that directly influence product formulation and packaging design across Australian snack bar lines. The Health Star Rating system and Australian Competition and Consumer Commission enforcement on health claims create compliance thresholds that favor established players with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving front-of-pack labeling requirements and state-level container deposit schemes that are reshaping packaging material selection and sustainability credentials.
Market Dynamics
FSANZ labeling mandates and the Health Star Rating system are compressing formulation freedom, forcing manufacturers to rebuild recipes around cleaner ingredient decks and transparent nutrition declarations that favor established regulatory affairs capabilities.
Growth Catalysts
- Protein-enriched formats:Fitness enthusiasts and health-conscious millennials in Sydney and Melbourne are pulling demand toward sports nutrition bars with elevated protein isolates and amino acid profiles.
- Health Star Rating system:Front-of-pack scoring is rewarding reformulated products with reduced sugar and sodium, creating competitive advantage for compliant manufacturers.
- Urban center concentration:New South Wales and Victoria account for disproportionate premium and organic snack bar penetration, concentrating marketing spend and distribution investment.
Market Restraints
- Almond and whey input volatility:Australian-grown nut costs fluctuate with irrigation water allocation cycles, compressing margin stability for mid-tier producers.
- Co-packer capacity bottlenecks:Asset-light contract manufacturing concentration in Melbourne and Brisbane creates queue delays for new entrants seeking production slots.
- Substitution by fresh convenience:Ready-to-eat salad bowls and protein pots in 7-Eleven and petrol station channels capture overlapping meal-replacement occasions.
Strategic Opportunities
- Queensland and Western Australia underpenetration:Premium snack bar household penetration trails Victoria by double digits, offering whitespace for regional distribution buildouts.
- Container deposit scheme alignment:State-level packaging return programs create incentive for recyclable film and paperboard innovation that commands shelf preference.
- Plant-protein fermentation:Precision fermentation of pea and fava protein isolates is converging with extrusion technology to enable cleaner-label vegan bars.
Industry Challenges
- Allergen segregation protocols:FSANZ cross-contamination standards demand dedicated production lines or extensive changeover sanitation, elevating capital intensity for multi-SKU facilities.
- Nutrition claim substantiation:Australian Competition and Consumer Commission enforcement on "high protein" and "natural" descriptors requires clinical validation and legal review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Snack Bar Market |
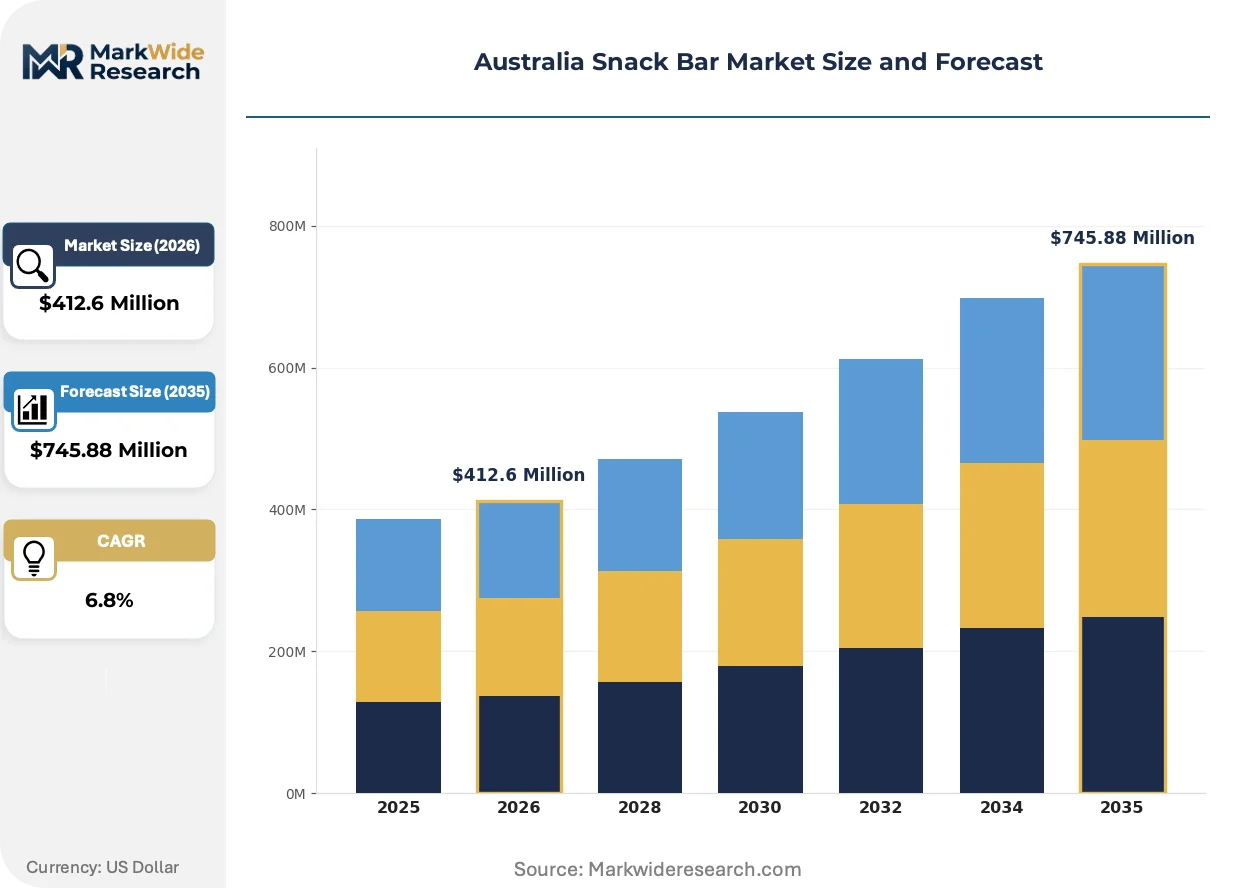
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Energy Bars, Fruit Bars Ingredient Type: Nut-Based, Whole Grain, Organic, Low Sugar Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Packaging Type: Single Serve, Multi-Packs, Eco-Friendly, Resealable |
| Companies Covered | Nestlé S.A., Mars, Incorporated, Mondelēz International, Inc., The Simply Good Foods Company, The Sanitarium Health and Wellbeing Company, Vitaco Holdings Ltd, Carmen's Fine Foods Pty Ltd, Tasti Products Ltd, Kellogg Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Snack Bar Market Emerging Trajectories
Clean-label ingredient sourcing and processing transparency are redefining competitive positioning, with manufacturers racing to eliminate synthetic additives and establish provenance narratives that resonate with skeptical urban consumers.
Cold-press forming technology is migrating from artisan granola specialists to mainstream contract manufacturers. Equipment suppliers in Melbourne report 18-month order backlogs as co-packers retrofit lines to preserve heat-sensitive probiotics and vitamins. This migration is compressing the shelf-life advantage previously held by baked extrusion formats, forcing legacy producers to accelerate capital deployment or cede premium positioning.
FSANZ is tightening enforcement on "no added sugar" claims through revised Food Standards Code Schedule 23 provisions. Manufacturers must now substantiate implicit sweetness from date paste and rice syrup against quantitative thresholds. Protein bar SKUs with fruit-based binding systems face the steepest reformulation burden, with several Victorian producers already adjusting front-of-pack messaging to avoid compliance action.
Direct-to-subscription models are displacing supermarket-centric distribution for premium and functional bar brands. Melbourne-based fitness communities and corporate wellness programs are piloting curated monthly boxes that bypass Coles and Woolworths slotting fees. This channel rotation is most visible in Victoria, where boutique operators report customer acquisition costs 40% below conventional retail launch economics.
Australia Snack Bar Market Segmentation
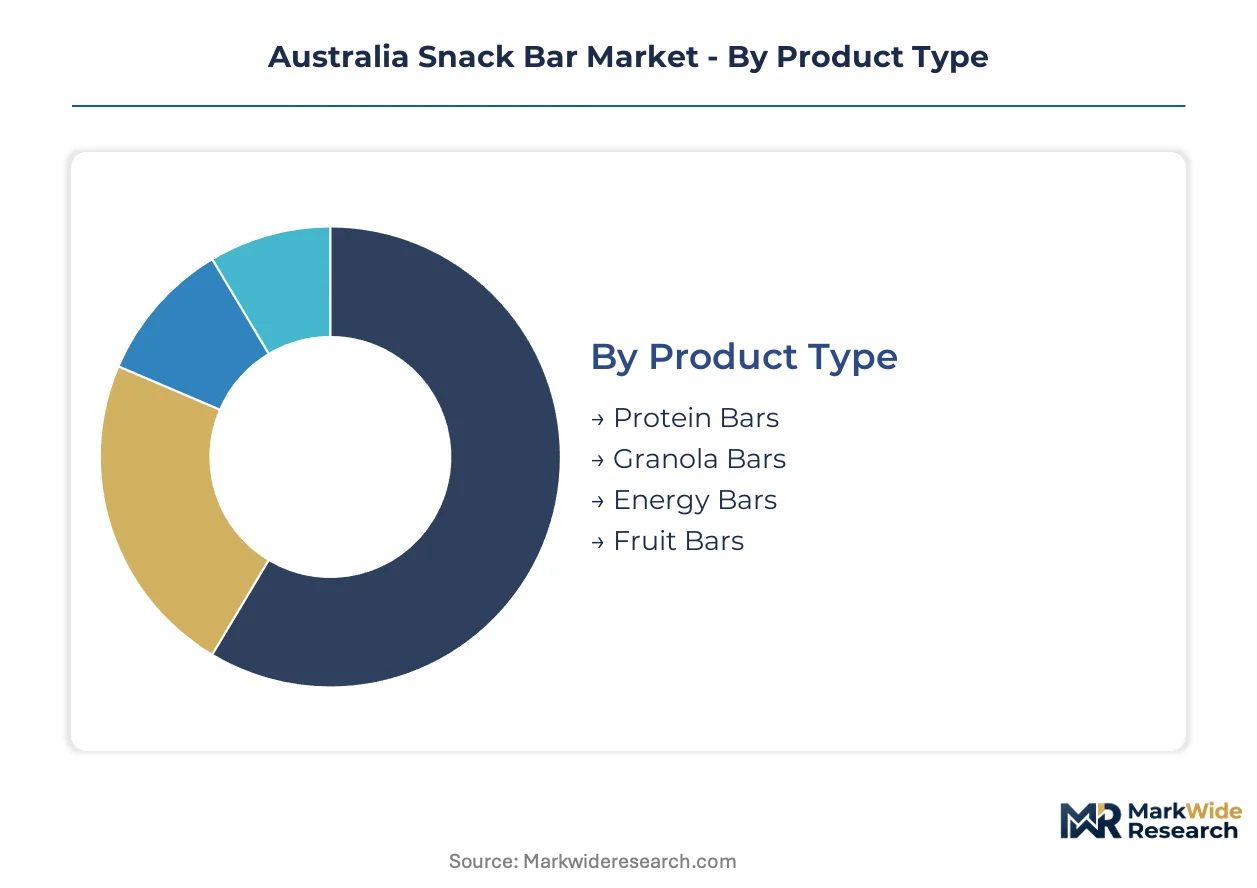
Australia's snack bar manufacturers engineer product portfolios around distinct consumption occasions and channel economics. Segment boundaries increasingly blur as protein enrichment migrates across traditional format lines and FSANZ labeling rules compress formulation differentiation.
Product Type:
After-sales intensity concentrates in protein bars, where sports nutrition consumers demand batch-traceable amino acid profiles and responsive customer service on formulation queries.
- Protein Bars:These bars incorporate whey, casein, or plant isolates with 15-25g protein per serve, bound by maltitol or fiber syrups. Sydney and Melbourne fitness communities pull demand toward clinically validated amino acid ratios. FSANZ substantiation requirements on "high protein" claims elevate compliance costs for new entrants.
- Granola Bars:Rolled oat and honey-based formats dominate household pantry penetration across Victoria and New South Wales. Breakfast replacement occasions sustain volume leadership despite slower growth pace than functional alternatives.
- Energy Bars:Carbohydrate-dense formulations target endurance athletes with rapid glycemic delivery. Queensland cycling and triathlon clubs represent concentrated demand pockets outside major metropolitan centers.
- Fruit Bars:Date and dried fruit compacts serve clean-label seekers avoiding synthetic binders. South Australian dried fruit processors supply upstream inputs to Victorian contract manufacturers.
By volume, granola bars lead. By growth pace, protein bars are expanding most quickly.
Ingredient Type:
Cost tier stratification separates premium-positioned organic and low-sugar lines from commodity nut-based and whole-grain alternatives.
- Low Sugar:Reformulated bars leveraging allulose, monk fruit, or fiber-based sweetness systems command shelf price premiums. FSANZ Schedule 23 enforcement on implicit sugar claims forces meticulous front-of-pack recalibration.
- Organic:Certified inputs from Australian Organic–accredited suppliers enable provenance narratives for export-oriented brands. New South Wales Riverina nut growers anchor supply security for premium SKUs.
- Nut-Based:Almond, macadamia, and cashew-dominant bars face irrigation water allocation volatility compressing margin stability. Western Australian orchard expansion offers geographic diversification.
- Whole Grain:Heritage grain formulations from Sanitarium and established players sustain volume through school canteen and institutional channels. Tasmanian oat millers provide regional supply concentration.
By household penetration, whole grain leads. By margin expansion, low sugar commands the steepest trajectory.
Distribution Channel:
Customer type bifurcation separates supermarket-dependent mass market from health food shop and online retail premium seekers.
- Supermarkets:Coles and Woolworths slotting fees and promotional calendars dictate cash flow timing for national brand portfolios. Victorian producers concentrate trade marketing investment here.
- Online Retail:Direct-to-subscription models bypass retail margin stacking for functional and boutique brands. Melbourne corporate wellness programs pilot curated monthly boxes with customer acquisition economics below conventional launch costs.
- Convenience Stores:7-Eleven and petrol station channels capture impulse and meal-replacement occasions competing with fresh protein pots. Queensland motorway corridors show strongest per-outlet velocity.
- Health Food Shops:Independent retailers in Byron Bay and Noosa provide brand-building platforms before supermarket scale-up. Staff recommendation influence sustains premium pricing tolerance.
By revenue concentration, supermarkets dominate. By channel margin, online retail offers the most favorable unit economics.
Packaging Type:
Supply concentration in Melbourne and Brisbane co-packer networks shapes format availability and minimum order quantities.
- Eco-Friendly:Compostable films and paperboard structures align with state-level container deposit scheme incentives. New South Wales and Victorian consumers show measurable shelf preference for recyclable formats.
- Single Serve:Individual wrapper formats sustain trial and impulse purchase occasions across all channels. Barrier property requirements for shelf stability limit material innovation freedom.
- Multi-Packs:Six-to-ten count cartons reduce per-unit packaging cost for pantry stock-up occasions. Queensland and Western Australia underpenetration creates whitespace for household penetration buildouts.
- Resealable:Zip-lock and adhesive strip closures target portion-controlled consumption. Equipment retrofit costs delay adoption among smaller contract manufacturers.
By shipment volume, single serve leads. By innovation priority, eco-friendly formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian snack bar production flows predominantly toward domestic consumption, with limited export volumes directed at New Zealand and select Asian markets. Import penetration remains minimal given established local manufacturing capacity and FSANZ regulatory alignment requirements.
New South Wales
Sydney's fitness culture and corporate wellness programs pull demand toward protein-enriched formats with elevated amino acid profiles. The state's container deposit scheme incentivizes recyclable packaging innovation across manufacturing facilities. Co-packer networks in Western Sydney concentrate production capacity serving both domestic supermarket channels and direct-to-subscription startups.
Victoria
Melbourne's health-conscious millennials drive premium and organic snack bar penetration at rates exceeding national averages. FSANZ headquarters proximity enables rapid regulatory compliance consultation for reformulating products around Health Star Rating optimization. Cold-press equipment suppliers in the city's northern suburbs report sustained order backlogs as contract manufacturers retrofit lines.
Queensland
Brisbane's co-packer capacity bottlenecks create queue delays for new entrants seeking production slots despite trailing household penetration versus southern states. The state's motorway corridors concentrate convenience store velocity for energy bar formats targeting endurance athletes. Regional distribution buildouts offer whitespace opportunity given double-digit penetration gaps relative to Victoria.
Western Australia
Perth's geographic isolation sustains higher transport costs that compress margin structures for imported interstate brands. The state's almond orchard expansion offers geographic diversification against irrigation water allocation volatility affecting eastern nut supplies. Local contract manufacturing capacity remains underdeveloped relative to demand growth trajectories.
South Australia
Adelaide's dried fruit processors supply upstream inputs to Victorian contract manufacturers specializing in fruit-based binding systems. The state's agricultural base anchors clean-label provenance narratives for organic-certified snack bar lines. Limited local co-packer infrastructure necessitates interstate production arrangements for finished goods.
Australia Snack Bar Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with ingredient and equipment supply. The Australia snack bar sector exhibits moderate consolidation around heritage food manufacturers and global FMCG platforms, with mid-tier private label and boutique operators occupying fragmented niches. Three archetypes dominate: multinational nutrition platforms leveraging global procurement scale, domestic heritage brands with whole-grain and plant-based formulation depth, and asset-light contract manufacturers enabling rapid private label entry. Competitive moves concentrate on co-packer capacity acquisition and direct-to-consumer channel bypass of supermarket slotting fee structures.
Among heritage Australian manufacturers, The Sanitarium Health and Wellbeing Company and Carmen's Fine Foods Pty Ltd occupy positions exemplifying domestic brand equity leverage and localized supply chain control. Nestlé S.A. represents the multinational platform archetype with procurement scale advantages on nut and dairy inputs. These three anchors illustrate the competitive tension between global sourcing efficiency and regional provenance marketing.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Mars, Incorporated |
| Mondelēz International, Inc. |
| The Simply Good Foods Company |
| The Sanitarium Health and Wellbeing Company |
| Vitaco Holdings Ltd |
| Carmen's Fine Foods Pty Ltd |
| Tasti Products Ltd |
| Kellogg Co. |
| Others |
Supply Flow & Price Mechanics
Australian almond and macadamia orchard concentration in the Riverina and Western Australia anchors upstream supply security, directing margin pools toward brands with locked-in grower contracts and bypassing spot-market volatility that compresses mid-tier producers.
Pricing Analysis
Health-conscious millennials anchor a three-tier pricing structure across premium, standard, and economy levels in the Australia snack bar sector. Price differentiation separates organic-certified lines with Australian-grown provenance from conventional nut-based formats and private-label economy tiers. Cost compression in the standard tier is intensifying because FSANZ labeling compliance elevates reformulation expenses. Corporate wellness programs show least price sensitivity, while petrol station impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Melbourne co-packers to South Australian dried fruit processors are stabilizing working capital for seasonal input procurement. Australian almond growers, Tasmanian oat millers, and Victorian cold-press equipment suppliers anchor geographic supply concentration. Formulation draws from whey isolates, pea protein, and date paste binding systems. Single-source vulnerability sits with Melbourne co-packer queue bottlenecks. Distribution runs through Coles and Woolworths supermarket networks with direct-to-subscription bypass emerging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as direct-to-subscription models displace supermarket-centric distribution, creating niches for boutique operators to capture corporate wellness and fitness community demand without slotting fee burdens.
For Market Incumbents: Build regulatory affairs moats through dedicated FSANZ compliance capabilities that new entrants cannot replicate quickly. Secure long-term grower contracts in the Riverina to lock in almond supply against irrigation allocation volatility. Expand cold-press capacity in Victoria before equipment order backlogs worsen. Channel control through direct-to-subscription pilot programs with Sydney corporate wellness providers offers defensive positioning against supermarket margin compression. For New Entrants and Emerging Players: Build out Queensland and Western Australia distribution infrastructure where premium snack bar household penetration trails Victoria by double digits. Target energy bar formats in Brisbane motorway corridors and Perth fitness communities as the most penetrable white-space. Bypass Coles and Woolworths slotting fees through curated monthly subscription boxes piloted with Melbourne corporate wellness programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-press manufacturing as 18-month equipment backlogs elevate facility deployment costs. Long-term viability favors asset-light contract manufacturers with locked co-packer capacity over greenfield production investments. Acquisition target archetype: Victorian boutique brands with established direct-to-subscription customer bases and Health Star Rating-optimized formulations. Watch cold-press equipment supplier order books as inflection indicator for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Bypasses Coles and Woolworths slotting fees while capturing Melbourne fitness community demand. |
| Backward Integration into Almond Supply | Locks in Riverina grower contracts against irrigation water allocation volatility compressing margins. |
| Health Star Rating Optimization | Aligns front-of-pack scoring with FSANZ enforcement trends rewarding reduced sugar formulations. |
| Queensland Distribution Expansion | Captures whitespace in motorway corridor convenience channels where energy bar velocity concentrates. |
| Sustainability Repositioning | Aligns packaging with New South Wales and Victorian container deposit scheme incentives. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the Australia snack bar sector. Primary interviews captured brand managers at heritage manufacturers, category buyers at Coles and Woolworths, procurement leads at Victorian co-packers, and supply planners at nut processing facilities. Secondary validation drew from FSANZ Food Standards Code provisions, Health Star Rating database filings, Australian Bureau of Agricultural and Resource Economics trade data, and supermarket promotional calendar disclosures. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates.
Calibration anchored volume and value outputs to observed production capacity at Melbourne and Brisbane co-packer networks across the projection horizon. Segmentation dimensions modeled include product type, ingredient certification tier, distribution channel economics, and packaging format compliance with state-level container deposit schemes. CAGRs were derived from trend extrapolation of protein-enriched format uptake and organic penetration rates. Forecast inputs incorporated almond irrigation water allocation cycles and cold-press equipment supplier order backlogs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational nutrition platforms or private equity-backed contract manufacturing roll-ups would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia-Pacific Snack Bar Market
Snacks
Meat Snacks Market
Snacks
France Energy Bar Market
Snacks
Meat Protein Chips Market
Snacks
US Potato Chips Market
Snacks
Europe Extruded Snack Food Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Popcorn Market
Snacks
Europe Snack Pellets Market
Snacks
India Snack Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Roasted Snacks Market
Snacks
Italy Snack Bar Market
Snacks
Forti Flakes Market