
 Kids Snacks Market | 2026-2036
Kids Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Snacks Market Analysis
The EU Green Deal's sustainable food packaging targets is pivoting European retailers toward recyclable pouch and resealable bag formats for children's snack portfolios. Nestlé leverages its R&D network to reformulate sodium and sugar profiles ahead of evolving WHO guidelines. General Mills anchors North American distribution through deep penetration in club stores and school breakfast programs. PepsiCo competes aggressively on flavor innovation, extending its salty snack expertise into fruit-based and protein-enhanced lines for younger demographics.
Kids snacks comprise shelf-stable, portion-controlled food products formulated with modified textures, fortified micronutrients, and allergen-managed ingredient decks for consumers aged two to twelve years. Manufacturing employs extrusion, baking, or freeze-drying processes to achieve moisture levels below 0.6 water activity for ambient stability without preservatives. Granola bars and fruit snacks occupy the premium margin tier where clean-label claims command price premiums, while chips and cookies sustain volume leadership through impulse-channel placement and licensed character marketing. Pouch packaging is displacing rigid formats in on-the-go consumption occasions, particularly in online retail and convenience store channels where single-serve portability drives basket size.
FDA nutrition labeling rules and USDA Smart Snacks in School standards constrain permissible fat, sugar, and sodium thresholds for products targeting institutional channels. EFSA additive evaluations and EU F-Gas Regulation indirectly shape manufacturing equipment choices and cold-chain requirements for dairy-inclusive offerings. REACH compliance on packaging substrates adds formulation complexity for brands exporting into European supermarkets. Stakeholders must monitor evolving school nutrition mandates and packaging waste directives to anticipate channel access restrictions and reformulation timelines.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are compressing permissible ingredient decks while school nutrition programs simultaneously tighten procurement specifications for sodium, sugar, and fat thresholds.
Growth Catalysts
- USDA Smart Snacks in School standards:Federal compliance requirements are institutionalizing portion-controlled formats across North American school districts, creating predictable demand for qualifying products.
- Extrusion technology advancement:Twin-screw extrusion systems now achieve protein fortification at industrial scale without texture degradation, opening formulation possibilities previously limited to premium tiers.
- Club store channel expansion:Costco and Sam's Club are dedicating expanded shelf space to bulk children's snack assortments, driving volume commitments from reformulated clean-label suppliers.
Market Restraints
- Palm oil price volatility:Reformulated clean-label recipes depend on specialty lipid systems whose input costs fluctuate with Malaysian and Indonesian palm kernel export quotas.
- Freeze-drying equipment concentration:European and Chinese OEMs control over seventy percent of industrial freeze-dryer supply, creating capex bottlenecks for North American fruit snack expansion.
- EFSA additive re-evaluation cycles:Pending titanium dioxide and artificial colorant bans force contingency reformulation investments before final rulings.
Strategic Opportunities
- Indian FSSAI fortification mandates:Government-mandated micronutrient enrichment in school feeding programs creates first-mover advantage for exporters with pre-certified formulations.
- Resealable pouch recyclability:Mono-material polyethylene developments compatible with existing store-dropoff infrastructure unlock premium positioning in European retail.
- Probiotic strain stabilization:Advances in ambient-stable Bacillus coagulans encapsulation are converging with dairy-free base formulations to create shelf-stable functional snacks without refrigeration.
Industry Challenges
- Food technologist specialization gap:Clean-label reformulation requires rare expertise in natural preservation and texture modulation that outpaces current university pipeline output.
- Dual certification timeline compression:Simultaneous USDA Organic and Non-GMO Project verification processes extend go-to-market schedules by eight to fourteen months.
- Legacy ERP integration:Batch-level allergen tracking requirements exceed capabilities of incumbent manufacturing execution systems at mid-tier co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Snacks Market |
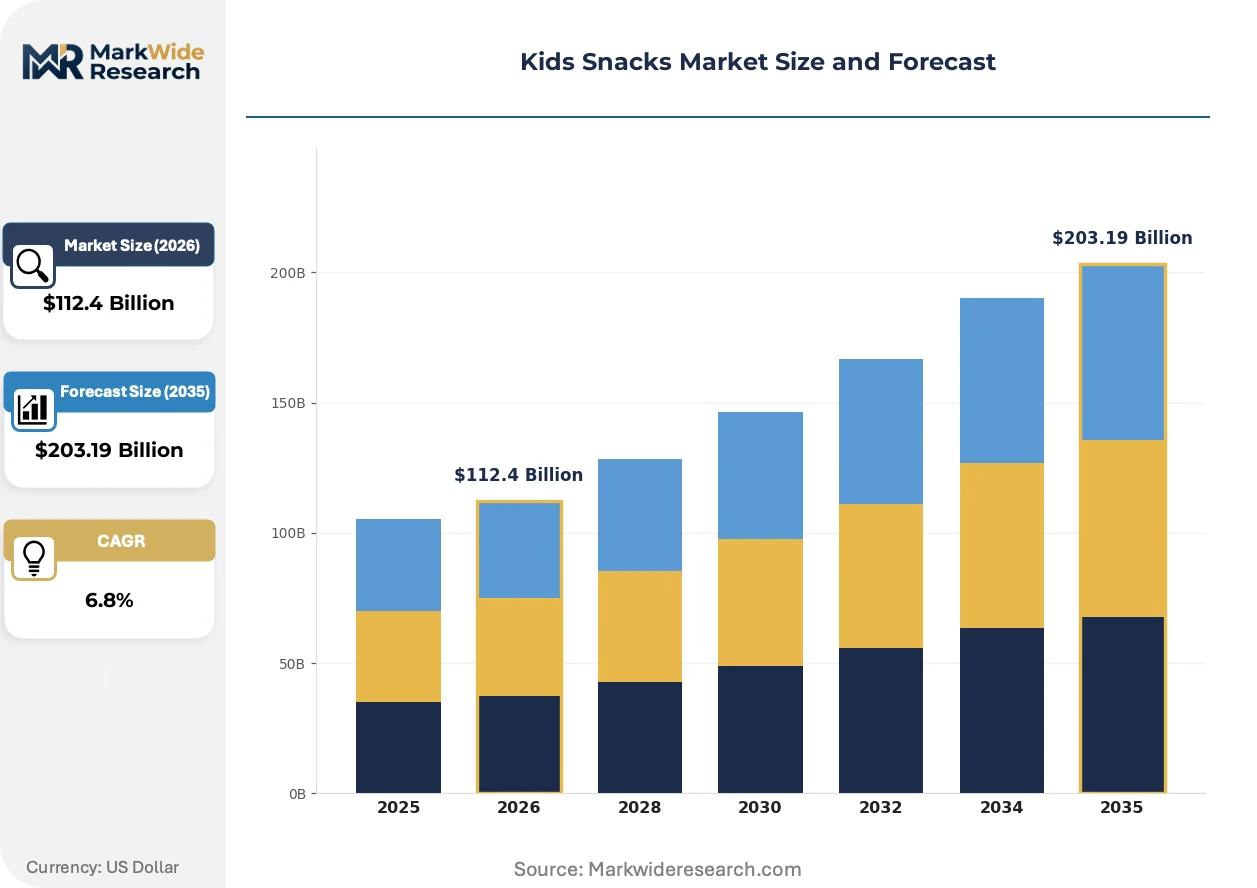
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Fruit Snacks, Chips, Cookies Flavor: Chocolate, Strawberry, Cheese, Sour Packaging Type: Snack Packs, Resealable Bags, Boxes, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Dollar Stores |
| Companies Covered | Kellogg Company, Tyson Foods, General Mills, The Hain Celestial Group, KIND, Mondelēz International, PepsiCo, Hormel Foods Corporation, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Snacks Market Emerging Trajectories
Reformulation science and packaging material innovation are compressing the gap between shelf-stable convenience and fresh-perception claims that previously required refrigerated distribution.
High-pressure processing is expanding into ambient-stable fruit puree pouches by eliminating pathogens without thermal degradation of vitamin C and polyphenols. Premium private-label buyers at Target and Whole Foods Market are adopting HPP-treated lines at triple-digit annual rates. This technology is expanding into categories previously dominated by aseptic hot-fill, compressing the price premium between refrigerated and shelf-stable nutrition claims.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration equipment replacement cycles at dairy-inclusive snack facilities. Manufacturers face stranded asset risk in cold-chain dependent production lines as hydrofluorocarbon servicing costs escalate. European operators are responding with accelerated investment in thermally processed shelf-stable alternatives that eliminate refrigeration entirely.
Parental purchasing patterns are fragmenting across channel-specific mission types rather than consolidating around single-retailer loyalty. Convenience store grab-and-go occasions now favor single-serve pouches while club store stock-up trips demand multi-count variety packs. This bifurcation is most visible in United States suburban markets where dual-income households maintain parallel shopping lists for immediate consumption versus planned pantry loading.
Kids Snacks Market Segmentation
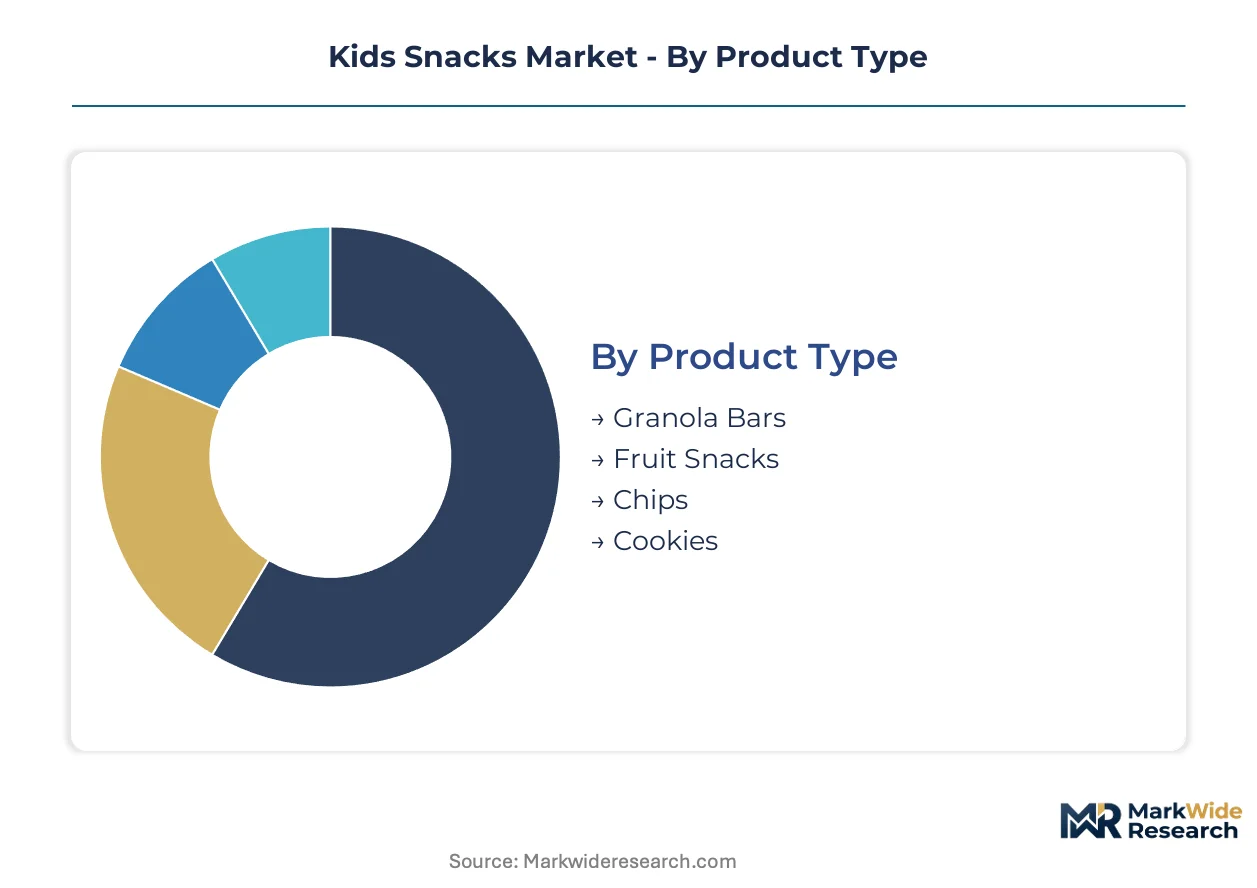
Segmentation in the kids snacks market reveals how parental purchasing decisions fragment across consumption occasions, nutritional priorities, and channel accessibility. Manufacturers must align formulation, packaging, and pricing architectures to distinct buyer missions rather than treating the category as uniform.
Product Type:
Parents select product types based on perceived nutritional density versus permissibility trade-offs, with texture and portability shaping repeat purchase rates.
- Granola Bars:Composite oat-and-nut matrices with binding syrups achieve moisture stability below 0.6 water activity for ambient shelf life. Demand concentrates in club store channels where bulk variety packs serve planned pantry stocking for suburban dual-income households.
- Fruit Snacks:Gelatin or pectin-based confections with fruit puree content ranging from 10% to 100% deliver chewy textures without refrigeration. Clean-label reformulations using concentrated apple or pear bases are gaining share fastest in premium supermarket sets as EFSA additive scrutiny intensifies.
- Chips:Extruded or kettle-cooked starch matrices with sodium profiles constrained by USDA Smart Snacks thresholds.
- Cookies:Baked wheat or gluten-free flour bases with reduced sugar claims targeting permissible treat positioning.
Chips lead on scale through impulse channel penetration; fruit snacks lead on momentum through clean-label premiumization.
Flavor:
Flavor selection reflects developmental taste preference windows, with younger children favoring basic profiles and older demographics accepting complex or challenging notes.
- Chocolate:Cocoa-derived coatings and inclusions in compound or tempered forms deliver familiar palatability across all age brackets. Demand concentrates in back-to-school promotional periods when permissible treat positioning peaks for lunchbox inclusion.
- Strawberry:Natural or nature-identical flavor systems with anthocyanin coloration meet parental clean-label expectations. European retail buyers are expanding shelf space for strawberry profiles as artificial colorant bans under EFSA review reshape formulation pipelines.
- Cheese:Cheddar or parmesan powder coatings on extruded bases delivering umami without refrigeration dependency.
- Sour:Citric or malic acid coatings creating salivary response popular among 8-12 year old demographics.
Chocolate dominates absolute volume; sour profiles exhibit steepest expansion trajectory among older children.
Packaging Type:
Packaging selection hinges on consumption occasion architecture, with single-serve portability competing against multi-serve value propositions across channel contexts.
- Snack Packs:Pre-portioned multi-pouch configurations with 90-120 calorie per-unit specifications satisfy institutional procurement requirements. School nutrition programs across the United States mandate this format for USDA Smart Snacks compliance.
- Resealable Bags:Zipper-equipped flexible films with oxygen barrier properties extending shelf life post-opening. EU Green Deal packaging waste directives are accelerating mono-material polyethylene conversions for store-dropoff recyclability.
- Boxes:Paperboard secondary packaging with primary film overwrap for shelf stability and graphic billboard space.
- Pouches:Spouted or tear-notch flexible formats for puree or semi-liquid products enabling mess-free consumption.
Snack packs lead on institutional volume; resealable bags lead on sustainability-driven retail momentum.
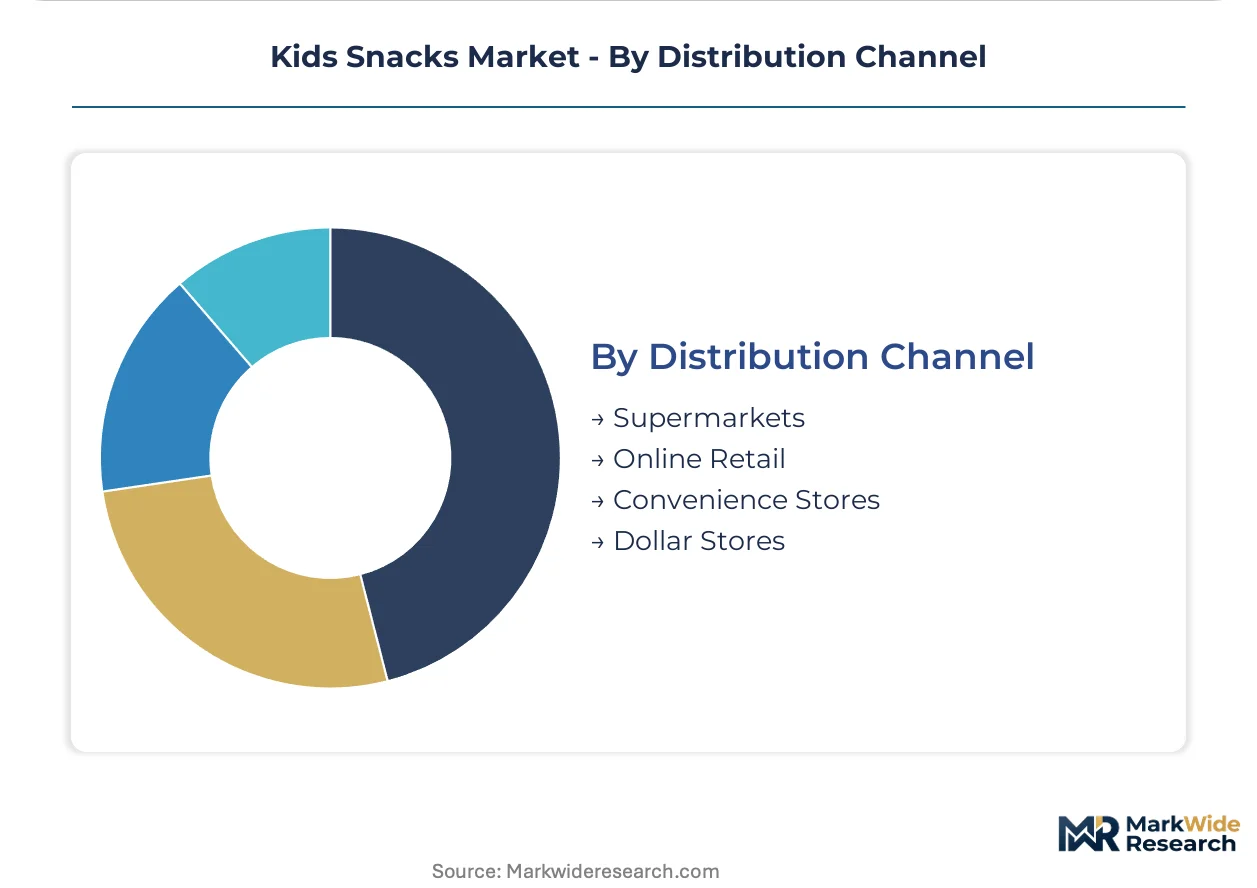
Distribution Channel:
Channel selection determines pricing architecture, promotional cadence, and assortment breadth requirements, with each channel serving distinct shopper missions.
- Supermarkets:Full-category assortments with 20-40 linear feet dedicated to kids snacks, combining national brands with private-label tiering. Clean-label private-label lines at Target and Whole Foods Market are expanding at triple-digit rates.
- Online Retail:Subscription and bulk formats with direct-to-home replenishment for planned consumption. Amazon's subscribe-and-save mechanics capture pantry-loading missions with 15-20% price discounts against brick-and-mortar.
- Convenience Stores:High-velocity single-serve placement at checkout with licensed character marketing driving impulse conversion.
- Dollar Stores:Value-tier assortments with simplified ingredient decks and reduced package sizes for budget-constrained households.
Supermarkets anchor absolute revenue; online retail demonstrates sharpest volume acceleration through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The kids snacks industry traces its modern scale to post-war United States food processing innovations, with subsequent European and Asian markets adapting formulations to local taste profiles and regulatory frameworks.
United States
Club store channels and school nutrition programs drive procurement volume for portion-controlled formats. USDA Smart Snacks in School standards constrain permissible fat and sodium thresholds for institutional suppliers. Chicago and Minneapolis anchor R&D clusters where reformulation labs adapt clean-label recipes to federal compliance timelines.
Germany
Retail buyers prioritize recyclable mono-material packaging compatible with store-dropoff infrastructure under EU Green Deal targets. EFSA additive re-evaluations force contingency planning for titanium dioxide and artificial colorant phase-outs. Cologne and Hamburg host formulation centers developing natural preservation systems for ambient-stable fruit snacks.
China
Middle-class urban households generate demand for imported premium organic lines through cross-border e-commerce channels. SAMR nutrition labeling rules and GB standards on food additives shape permissible ingredient decks for domestic manufacturing. Shanghai and Guangzhou concentrate distribution hubs serving tier-one city retail networks.
India
FSSAI-mandated micronutrient fortification in government school feeding programs creates procurement opportunities for exporters with pre-certified formulations. DGFT import regulations and local packaging requirements complicate direct market entry. Mumbai and Bengaluru host co-manufacturing facilities adapting international recipes to regional palate preferences.
Brazil
ANVISA registration requirements for imported processed foods extend go-to-market timelines for foreign brands. Urban convenience store expansion drives single-serve pouch demand in São Paulo and Rio de Janeiro metropolitan corridors. Local palm oil supply chains offer cost advantages for reformulated clean-label lipid systems.
Kids Snacks Market Vendor Landscape
Premium-margin players sit above commodity-margin players across clean-label certification and channel access dimensions, with the market consolidating around three tiers: multinational CPG conglomerates with school program compliance expertise, mid-tier organic specialists with Non-GMO Project verification, and private-label suppliers serving club store volume commitments. Strategic moves concentrate on M&A for R&D capabilities and capacity expansion for extrusion-based protein fortification.
Among diversified food conglomerates, Nestlé, General Mills, and PepsiCo exemplify distinct competitive archetypes. Nestlé occupies a position emphasizing sodium and sugar reformulation ahead of evolving WHO guidelines. General Mills anchors North American institutional channel penetration through USDA-compliant portfolio breadth. PepsiCo represents flavor innovation velocity extending salty snack expertise into fruit-based and protein-enhanced lines.
| Leading Market Players |
|---|
| Kellogg Company |
| Tyson Foods |
| General Mills |
| The Hain Celestial Group |
| KIND |
| Mondelēz International |
| PepsiCo |
| Hormel Foods Corporation |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
Clean-label certification bifurcation separates premium organic lines from commodity-tier products, creating divergent margin structures that reshape both procurement economics and supplier qualification protocols. USDA Organic and Non-GMO Project verification tiers command shelf-space allowances at Target and Whole Foods Market, while unverified suppliers compete on unit economics for dollar-store and institutional contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the category, with certification grade and volume scale as primary differentiation drivers. Premium tiers capture price multiples through dual USDA Organic and clean-label positioning, while commodity chips and cookies face downward pressure from private-label expansion at Costco and Sam's Club. School nutrition programs exhibit highest price sensitivity due to fixed federal reimbursement rates, whereas convenience store impulse buyers show lowest sensitivity for licensed-character single-serve packs.
Supply Chain Analysis
Certification gating through USDA Organic and Non-GMO Project verification concentrates qualified supply among mid-tier co-manufacturers with legacy ERP systems capable of batch-level allergen tracking. Raw material sourcing draws from Malaysian and Indonesian palm kernel markets for clean-label lipid systems, concentrated apple and pear bases for fruit snack reformulations, and domestic oat and nut suppliers for granola bar matrices. Palm oil export quota volatility poses structural risk to reformulated recipes dependent on specialty lipid alternatives. Distribution runs through club store consolidation centers, supermarket regional DCs, and direct-to-warehouse e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU Green Deal packaging compliance costs and US school nutrition program volume commitments, with European sustainability mandates accelerating equipment replacement cycles that strand North American competitors.
For Market Incumbents: Cement institutional channel control through preemptive USDA Smart Snacks reformulation ahead of threshold tightening, while acquiring freeze-drying equipment capacity to bypass European and Chinese OEM bottlenecks. Threats from probiotic strain stabilization technologies and ambient-stable functional claims require R&D investment in Bacillus coagulans encapsulation partnerships. For New Entrants and Emerging Players: High-pressure processing technology for ambient-stable fruit puree pouches offers white-space entry against aseptic hot-fill incumbents. Target Indian FSSAI pre-certification for government school feeding program procurement, leveraging Mumbai and Bengaluru co-manufacturing relationships for regional palate adaptation. For Investors and Strategic Acquirers: Consolidation pressure builds where clean-label reformulation expertise outpaces university pipeline output for food technologist specialization. Mid-tier organic specialists with Non-GMO Project verification and club store volume commitments represent viable acquisition targets. Signal to watch: EFSA final rulings on titanium dioxide and artificial colorant bans triggering contingency reformulation investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | USDA Smart Snacks compliance ahead of federal threshold revisions secures institutional channel access. |
| Mono-Material Packaging Conversion | EU Green Deal store-dropoff compatibility unlocks premium positioning at German and French retail buyers. |
| Probiotic Strain Stabilization Partnership | Bacillus coagulans encapsulation advances enable shelf-stable functional claims without refrigeration dependency. |
| High-Pressure Processing Capacity Addition | HPP-treated fruit puree lines capture triple-digit growth at Target and Whole Foods Market private-label programs. |
| Indian FSSAI Pre-Certification | Government-mandated micronutrient fortification creates first-mover advantage in school feeding program procurement. |
Methodological Framework
Multiple input streams — executive interviews with brand managers and category buyers, supply chain conversations with co-manufacturing facility directors, and regulatory tracking through FDA and EFSA filing databases — were reconciled against Nielsen retail audit data, customs import records, and SEC 10-K disclosures from diversified food conglomerates. Bottom-up volume modeling across product type, flavor, packaging format, and distribution channel segments was triangulated with top-down macroeconomic validation.
Data-stream reconciliation anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type, flavor profile, packaging technology, and regional regulatory cluster. CAGRs were derived from historical trajectory analysis and forward-looking procurement commitment tracking, incorporating school nutrition program budget allocations, club store shelf-space expansion plans, and e-commerce subscription growth mechanics as industry-specific inputs.
The model holds under stable regulatory enforcement timelines and intact palm oil supply chains; deviation in EFSA additive ban acceleration or Malaysian export quota restrictions would shift volume and value trajectories. A model refresh is warranted upon material change in USDA Smart Snacks threshold revisions or EU F-Gas Regulation phase-down schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
On-The-Go Healthy Snacks Market
Snacks
Snack Products Market
Snacks
Forti Flakes Market
Snacks
Marshmallow Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Salty Puffed Snacks Market
Snacks
Cereal Bars Market
Snacks
Plant-Based Snacks Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Low Fat Granola Market
Snacks
North America Snack Food Market
Snacks
North America Snack Bar Market
Snacks
Popcorn Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Savoury Biscuits Market