
 Low Calorie Cookies Market | 2026-2036
Low Calorie Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Cookies Market Foresight
Alternative sweetener blends is decoupling low-calorie cookie production from traditional sugar economics, compressing input costs while preserving taste profiles. Mondelez International leverages its global procurement network to secure stevia and monk fruit supplies at scale. Nestlé anchors its portfolio reformulation around proprietary fiber-fat matrices that replicate mouthfeel without caloric load. Quest Nutrition specializes in protein-fortified variants that compete directly with conventional indulgence cookies on sensory metrics.
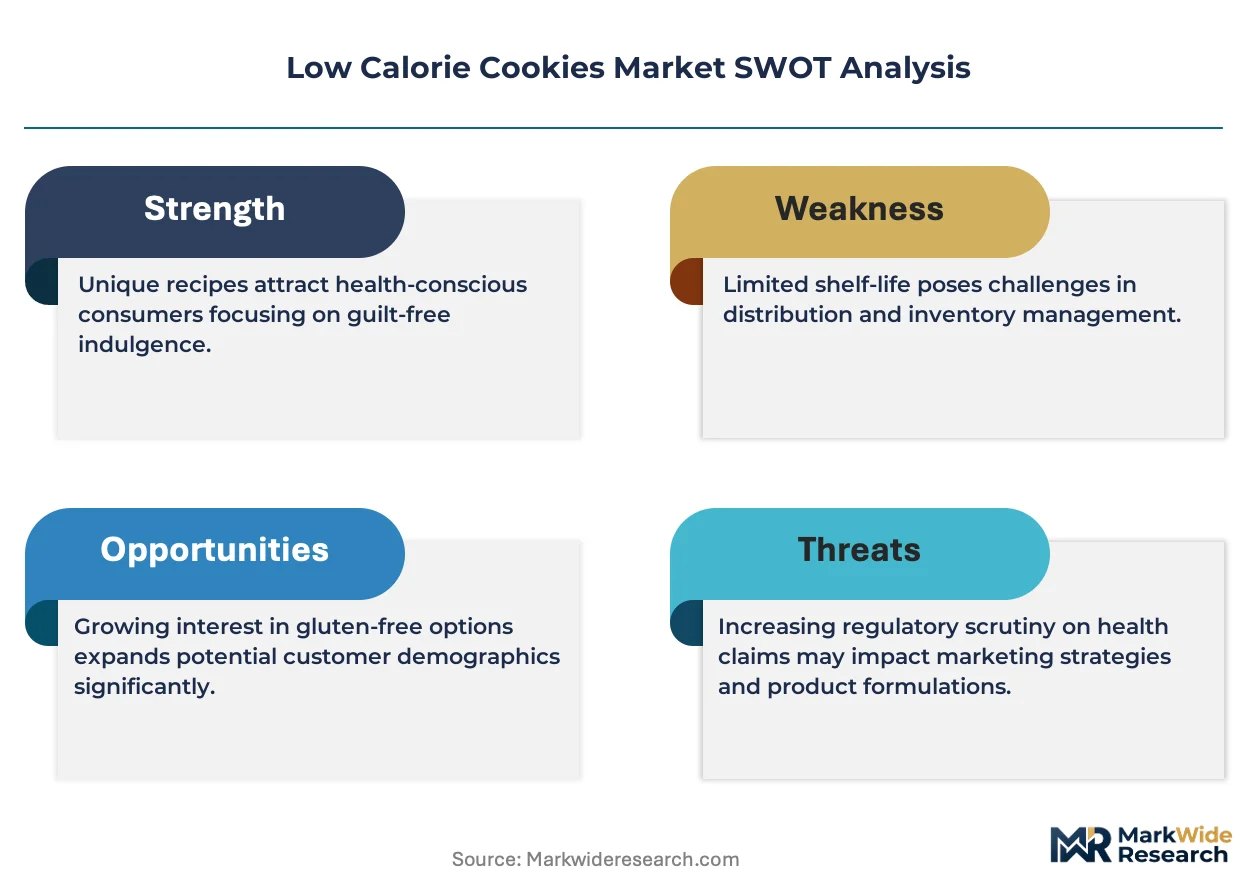
Low calorie cookies are baked goods formulated with reduced caloric density through substitution of refined sugars with non-nutritive sweeteners, partial replacement of wheat flour with resistant starches or soluble fibers, and controlled fat content typically below 25% by weight, designed to deliver portion-controlled snacking for consumers monitoring energy intake. Soft baked formats command premium shelf positioning in North American supermarkets due to their perceived freshness and higher moisture content that masks alternative sweetener aftertaste. Sugar-free ingredient claims attract the fastest-growing consumer cohort among fitness enthusiasts seeking ketogenic-compatible options, while gluten-free formulations occupy a mature niche with stable but slower velocity in specialty retail channels.
FDA nutrition labeling requirements and EU health claims regulations under EFSA jurisdiction compel manufacturers to substantiate reduced-calorie assertions through validated analytical methods, raising formulation transparency and reformulation costs for market entrants. The USDA organic certification and Non-GMO Project verification create parallel compliance tracks that segment margin pools across conventional and premium-positioned product lines. Stakeholders must monitor evolving sweetener safety assessments from EFSA and FDA as novel polyol blends and rare sugar formulations advance through novel food approval pathways.
Market Dynamics
Alternative sweetener supply concentration and FDA nutritional labeling enforcement are compressing margins for reformulation laggards while rewarding scaled procurement networks. The shift from sucrose to stevia-monk fruit blends has restructured ingredient sourcing economics across the category.
Growth Catalysts
- Ketogenic diet expansion:Fitness enthusiasts in the United States are adopting sugar-free cookie formats as permissible indulgences within strict macronutrient protocols, expanding addressable demand beyond traditional weight-loss segments.
- EFSA health claims harmonization:Validated reduced-calorie assertions under EU Regulation 1924/2006 enable cross-border marketing with substantiated nutritional positioning, lowering regulatory friction for compliant manufacturers.
- Fiber-fat matrix advances:Proprietary texturizing systems replicate conventional cookie mouthfeel without caloric density, resolving the historical taste-quality barrier that constrained category penetration.
Market Restraints
- Stevia leaf supply volatility:Agricultural concentration in China and Paraguay exposes processors to climate-driven harvest fluctuations and input cost spikes.
- Polyol gastrointestinal tolerance thresholds:Erythritol and maltitol consumption limits restrict formulation flexibility for sugar-free variants targeting mass-market palates.
- Organic certification backlog:USDA organic verification timelines extending 12-18 months delay premium product launches and tie up working capital.
Strategic Opportunities
- Direct-to-consumer subscription channels:Replenishment models bypass slotting fee barriers in consolidated US retail, capturing full margin and consumer data.
- India functional snacking emergence:Urban middle-class dietary transition creates first-mover positioning for protein-fortified formats adapted to local sweetness preferences.
- EU Green Deal packaging mandates:Compostable wrapper requirements favor early movers with integrated sustainable supply chains, creating differentiation in environmentally conscious European markets.
Industry Challenges
- Sensory scientist scarcity:Formulation expertise bridging alternative sweetener chemistry and traditional baking science commands premium compensation, constraining R&D expansion for mid-tier producers.
- Novel food approval timelines:Rare sugar submissions through EFSA and FDA pathways require 18-24 month toxicology dossiers, delaying next-generation ingredient adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Cookies Market |
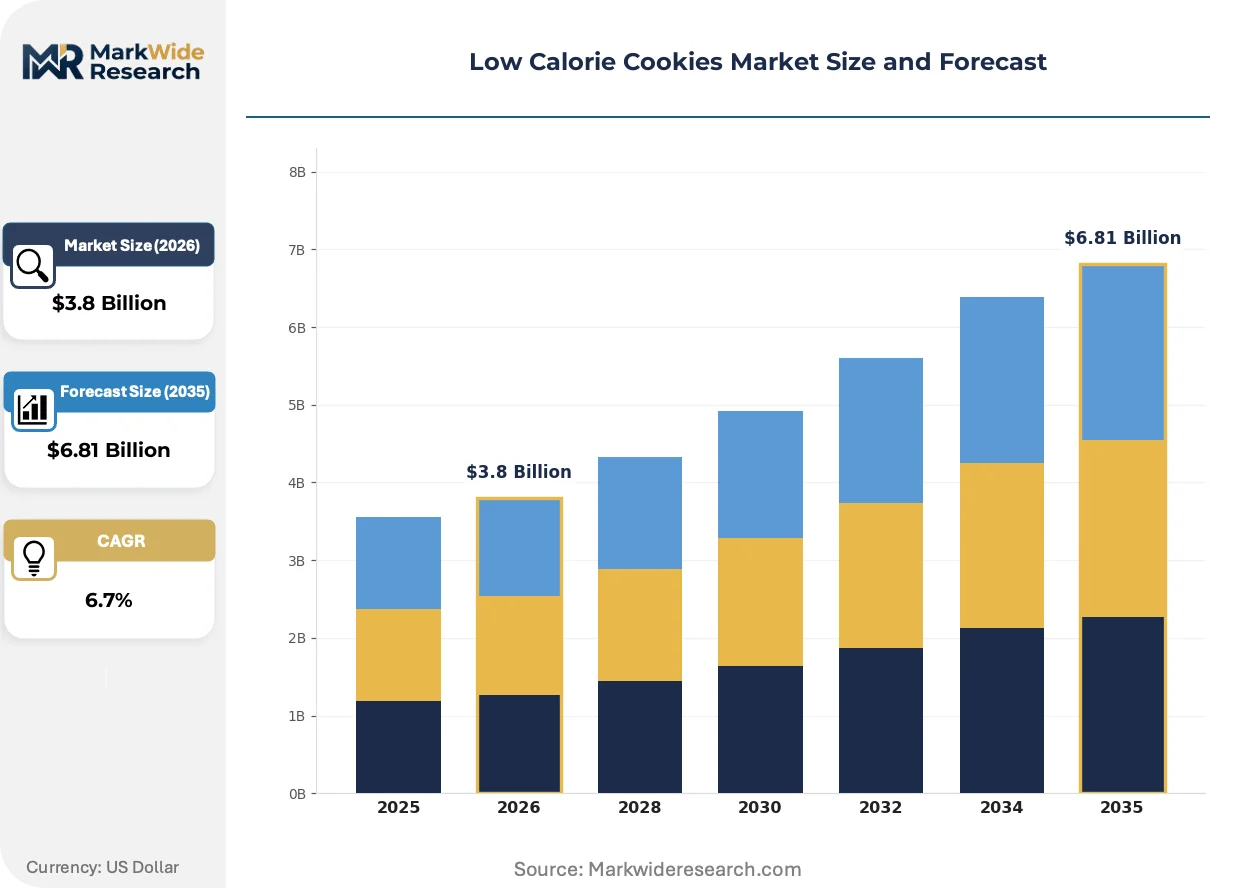
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Baked, Crunchy, Sandwich, Bite-Sized Ingredient Type: Gluten-Free, Whole Grain, Organic, Sugar-Free Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Food Shops Consumer Type: Weight Watchers, Fitness Enthusiasts, Health-Conscious Individuals, Snackers |
| Companies Covered | Mondelez International, Nestlé, Kraft Heinz, General Mills, Lenny and Larry's, Quest Nutrition, Kellogg Company, Pepperidge Farm, Nature Valley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Cookies Market Shifts & Advancements
Precision fermentation and AI-driven flavor mapping are compressing development cycles for clean-label reformulations. These technologies enable rapid prototyping of sweetness profiles that mask alternative ingredient off-notes.
Precision fermentation of rare sugars is automating the production of allulose and tagatose at commercial scale previously constrained by agricultural extraction economics. Contract manufacturers in North America are integrating these platforms to serve mid-sized brands lacking captive biotechnology capacity. This automation is compressing the cost differential between conventional and next-generation sweeteners, enabling mass-market price parity.
EFSA's 2023 updated guidance on health claims substantiation requires randomized controlled trials for reduced-calorie assertions, raising evidentiary standards above historical compositional analysis. Manufacturers must now invest in clinical endpoint studies to maintain EU market positioning. Protein-fortified cookie segments face the steepest compliance burden given the intersection of multiple nutrient claims.
Retailer private-label consolidation is displacing national brand shelf presence in European supermarkets, concentrating volume with chains controlling their own reformulation pipelines. Aldi and Lidl in Germany and the United Kingdom are accelerating in-house low-calorie cookie development, compressing branded manufacturer negotiation leverage. This channel shift is most pronounced in value-oriented segments where price elasticity exceeds brand loyalty.
Low Calorie Cookies Market Segmentation
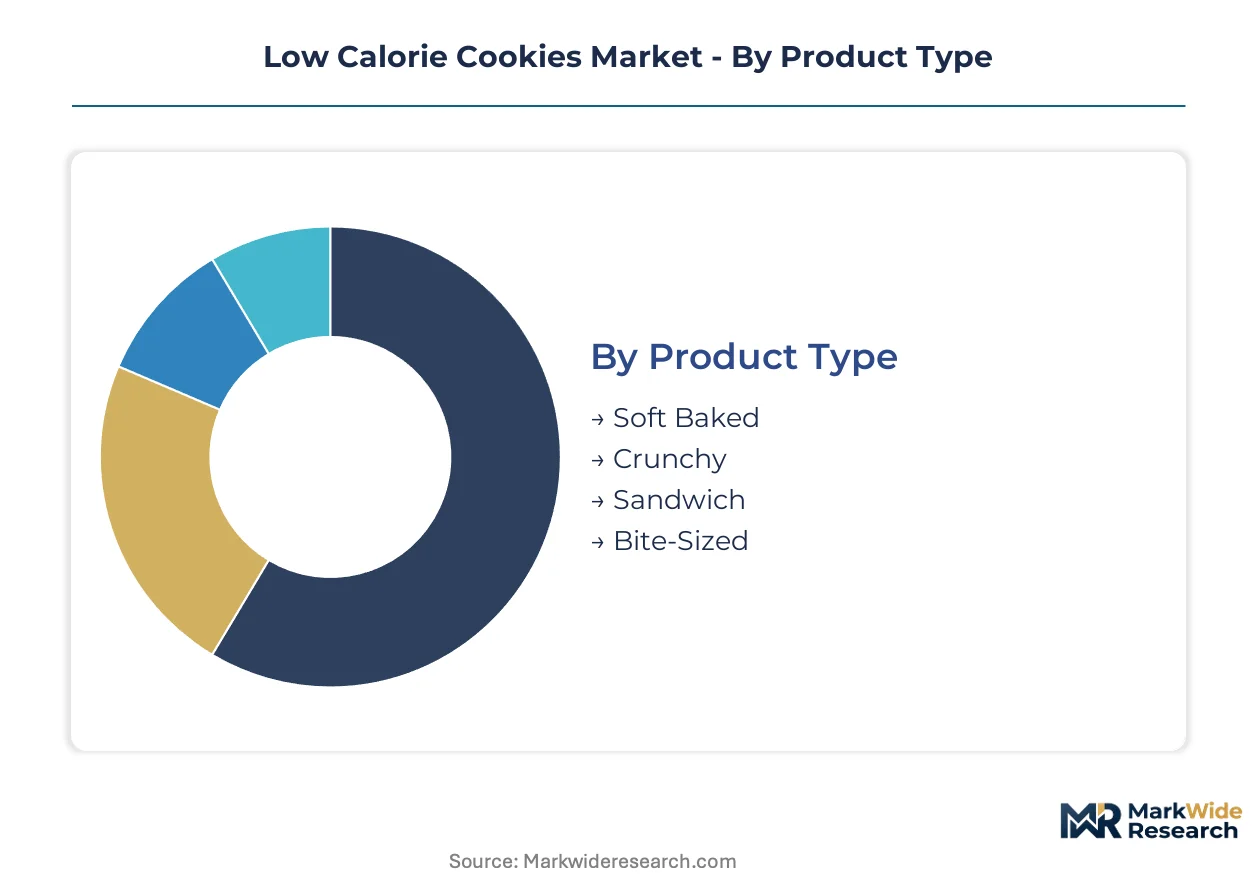
Low-calorie cookie manufacturers must navigate divergent compliance burdens across product formats and ingredient certifications. Segmentation strategy determines which USDA organic verification, FDA nutrition labeling, or EU health claims pathways each SKU must traverse.
Product Type:
USDA organic certification and FDA moisture content standards impose distinct testing protocols on each format, with soft baked variants facing the most stringent shelf-stability documentation.
- Soft Baked:High moisture content above 15% masks alternative sweetener aftertaste through texture engineering. Demand concentrates in United States supermarkets where refrigerated distribution preserves perceived freshness. FDA labeling for moisture-adjusted serving sizes adds compliance complexity.
- Crunchy:Low water activity below 0.6 enables ambient distribution without preservatives. European markets favor this format for clean-label positioning under EFSA health claims regulations, though brittle texture amplifies any off-notes from stevia blends.
- Sandwich:Dual-component structure with cream filling requires separate fat-content verification for filling and cookie base.
- Bite-Sized:Portion-controlled formats align with single-serve packaging mandates in EU Green Deal circular economy frameworks.
Soft Baked sits at the top of the volume ranking, with Bite-Sized climbing the fastest.
Ingredient Type:
Margin stratification follows certification tier, with organic and sugar-free variants commanding shelf-space premiums that offset USDA and Non-GMO Project verification costs.
- Gluten-Free:Rice flour and tapioca starch blends replace wheat protein matrices, requiring separate allergen-control protocols under FDA Food Safety Modernization Act rules. Mature niche with stable velocity in United States specialty retail channels.
- Whole Grain:Resistant starch content above 12% by weight delivers fiber claims without caloric density increase. Fastest-expanding segment among health-conscious consumers seeking satiety signaling in portion-controlled formats.
- Organic:USDA certification timelines extending 12-18 months delay launches and tie up working capital for reformulation pipelines.
- Sugar-Free:Erythritol and allulose formulations target ketogenic diet adherents with net-carb calculations below 3g per serving.
Whole Grain leads volume contribution, while Sugar-Free gains share fastest among fitness-focused cohorts.
Distribution Channel:
Channel selection dictates margin capture, with direct-to-consumer platforms bypassing slotting fees that erode profitability in consolidated retail.
- Supermarkets:Slotting fee structures exceeding $25,000 per SKU in top United States chains concentrate volume with Mondelez and Nestlé procurement scale. Planogram positioning requires annual renegotiation.
- Online Retail:Subscription replenishment models capture full margin and first-party consumer data, though cold-chain shipping constraints limit soft-baked format penetration.
- Specialty Stores:Curated assortments favor gluten-free and organic certifications with higher tolerance for premium price points.
- Health Food Shops:Staff education requirements favor brands with clinical substantiation for reduced-calorie claims.
Supermarkets dominate volume throughput, with Online Retail expanding most quickly as fulfillment infrastructure matures.
Consumer Type:
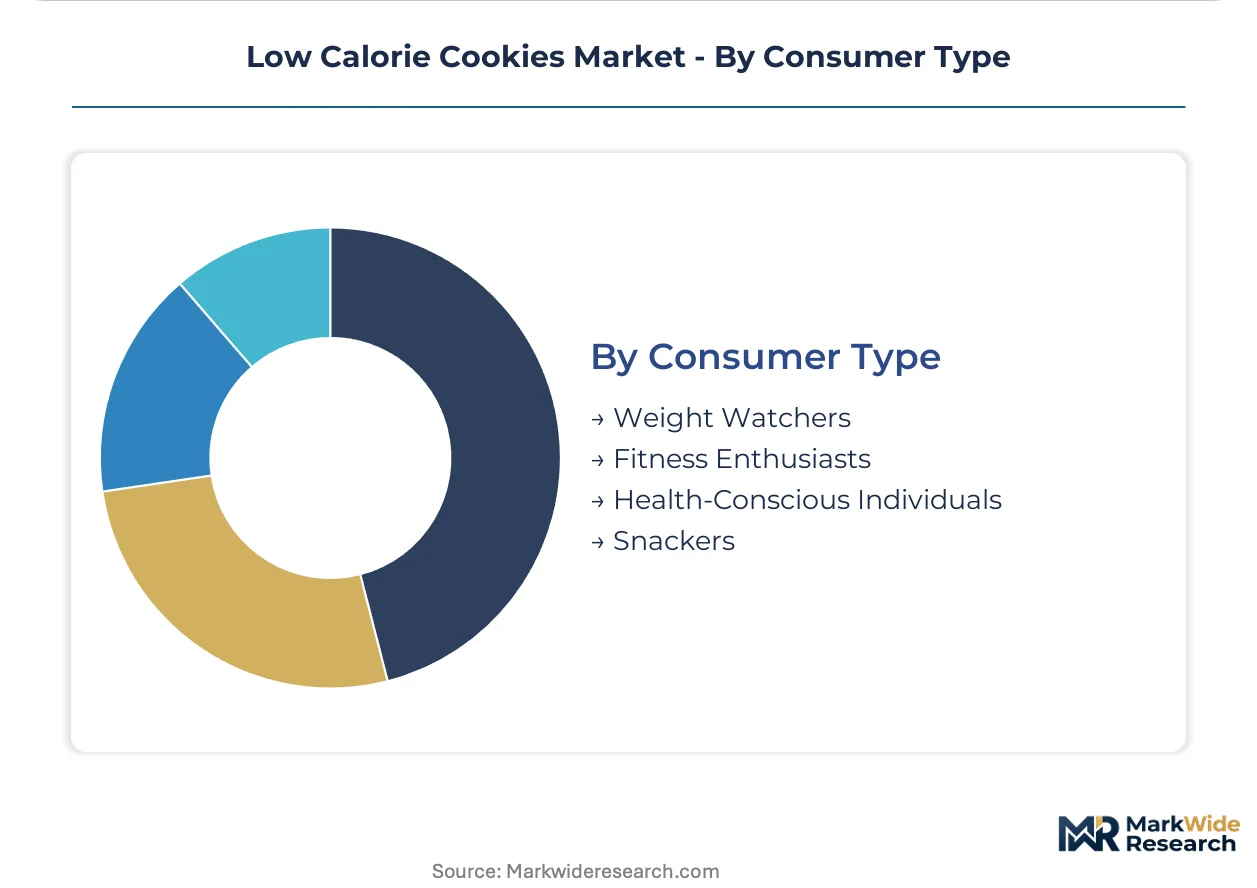
Customer segmentation aligns formulation intensity with behavioral commitment to macronutrient tracking.
- Weight Watchers:Point-system compatibility drives demand for precise calorie disclosure and portion-controlled packaging formats.
- Fitness Enthusiasts:Protein-fortified variants above 10g per serving compete with conventional indulgence cookies on sensory metrics. United States gym-channel distribution concentrates demand for Quest Nutrition and similar performance-positioned brands.
- Health-Conscious Individuals:Clean-label preference prioritizes ingredient list brevity over specific macronutrient targets.
- Snackers:Occasional consumption tolerates higher price elasticity for convenience and taste optimization.
Fitness Enthusiasts anchor premium pricing power, with Health-Conscious Individuals showing the steepest expansion trajectory as clean-label preference broadens beyond core wellness demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American low-calorie cookie manufacturing through Mondelez International's R&D campus and pilot production facilities. FDA nutritional labeling enforcement and USDA organic certification pipelines concentrate technical expertise in this metropolitan cluster. Fitness-focused demand in California and Texas drives regional formulation specialization toward protein-fortified and ketogenic-compatible formats.
United States
Fitness enthusiasts in California and Texas drive ketogenic cookie adoption through gym-channel distribution and direct-to-consumer subscription models. FDA nutrition labeling requirements under the 2016 updated rules mandate validated analytical methods for reduced-calorie assertions, raising compliance costs for market entrants. Chicago's industrial corridor concentrates Mondelez and Kellogg reformulation laboratories, with pilot facilities testing fiber-fat matrix advances for mass-market sensory parity.
Germany
Health-conscious consumers in Bavaria and North Rhine-Westphalia favor clean-label crunchy formats with EFSA-substantiated reduced-calorie claims under EU Regulation 1924/2006. Aldi and Lidl private-label consolidation displaces branded shelf presence, compressing manufacturer negotiation leverage in value-oriented segments. Hamburg's food technology cluster hosts precision fermentation startups supplying allulose to contract manufacturers serving mid-sized European brands.
United Kingdom
Urban professionals in London and Manchester adopt soft-baked formats through premium supermarket channels, tolerating price premiums for perceived freshness and moisture-engineered taste masking. EU Green Deal packaging mandates favor early movers with compostable wrapper supply chains, creating differentiation in environmentally conscious retail segments. Cambridge's biotechnology corridor advances AI-driven flavor mapping for clean-label reformulation acceleration.
India
Maharashtra's urban middle-class in Mumbai and Pune drives first-mover demand for protein-fortified cookies adapted to local sweetness preferences through lower erythritol concentrations. FSSAI labeling requirements for functional food claims create compliance pathways distinct from Western regulatory frameworks, requiring localized substantiation studies. Gujarat's food processing belt attracts contract manufacturing investment for export-oriented low-calorie biscuit production.
Japan
Aging consumers in Tokyo and Osaka prioritize portion-controlled bite-sized formats aligned with metabolic health management and physician-recommended snacking protocols. METI standards for functional food labeling enable specific health claim categories unavailable in Western jurisdictions, rewarding clinical substantiation investment. Nagoya's confectionery equipment manufacturers supply precision baking technology for alternative sweetener formulations with minimized thermal degradation.
Low Calorie Cookies Market Competitive Landscape
Portfolio diversification dominates the current landscape as multinational food conglomerates and specialized nutrition brands reposition around functional snacking segments. The market structure concentrates volume among three to five integrated players with global procurement networks for stevia and monk fruit, while mid-tier producers face margin compression from reformulation lag. Strategic archetypes span multinational packaged food conglomerates with captive R&D infrastructure, performance-nutrition specialists with gym-channel distribution, and private-label manufacturers serving retailer consolidation. Dominant competitive moves include M&A targeting clean-label capability acquisition and capacity expansion into precision fermentation platforms for rare sugar production.
Within the multinational conglomerate tier, Mondelez International and Nestlé occupy positions defined by global ingredient sourcing scale and proprietary texturizing systems. Quest Nutrition exemplifies the performance-nutrition specialist archetype through protein-fortified format development. Among diversified food manufacturers, General Mills and Kellogg Company represent legacy players adapting portfolio composition toward reduced-calorie segments through reformulation investment.
| Leading Market Players |
|---|
| Mondelez International |
| Nestlé |
| Kraft Heinz |
| General Mills |
| Lenny and Larry's |
| Quest Nutrition |
| Kellogg Company |
| Pepperidge Farm |
| Nature Valley |
| Others |
Supply & Pricing Matrix
Sensory scientist concentration in Chicago and Hamburg compresses R&D labor-cost differentials into pricing-tier spreads, with premium soft-baked formats absorbing specialist compensation premiums while economy crunchy variants source formulation expertise from contract manufacturers in lower-cost jurisdictions.
Pricing Analysis
Input-cost pass-through from stevia leaf and monk fruit concentrate volatility flows unevenly across certification tiers. Three-tier pricing structure across premium organic, standard clean-label, and economy conventional levels reflects USDA verification timelines and EFSA health claims substantiation burdens. Pricing pressure stems from Aldi and Lidl private-label consolidation in European value segments. Price differentiation separates fitness enthusiasts tolerating premium protein fortification from snackers gravitating toward lowest unit-cost formats in supermarket planogram battles.
Supply Chain Analysis
Dual-sourcing requirements for alternative sweeteners mandate multi-supplier qualification across China and Paraguay for stevia leaf, with secondary qualification in India for emerging allulose fermentation capacity. Raw material dependencies center on erythritol fermentation feedstocks, soluble fiber resistant starches, and precision-fermented rare sugars. Single-source vulnerability concentrates in Chinese agricultural stevia concentration exposed to climate-driven harvest fluctuation. Distribution runs through refrigerated supermarket networks for soft-baked formats and ambient retail for crunchy variants, with direct-to-consumer subscription bypassing slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie cookies market functions as a stable compounder anchored by persistent fitness-culture penetration and reformulation-driven replacement cycles in conventional indulgence categories.
For Market Incumbents: Anchor procurement scale advantages through captive stevia-monk fruit supply agreements and precision fermentation partnerships for allulose cost parity. Defend against private-label displacement by accelerating fiber-fat matrix proprietary differentiation and securing exclusive refrigerated distribution slots in top United States supermarket chains. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel architecture, bypassing slotting fee barriers that erode profitability for unscaled brands. Target protein-fortified formats in India urban middle-class segments where local sweetness preference adaptation creates first-mover positioning. Pursue gym-channel distribution partnerships with performance-nutrition retailers to establish credibility before retail expansion. For Investors and Strategic Acquirers: Packaged food conglomerates with captive R&D infrastructure represent the most active acquirer category in this space, seeking clean-label capability and precision fermentation capacity. Long-term viability over a five-to-ten year window rests on rare sugar cost convergence and EFSA health claims harmonization execution. Watch EFSA novel food approval timelines for allulose and tagatose as inflection indicators for next-generation ingredient adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Allulose production cost compression enables mass-market price parity with conventional sugar economics. |
| Direct-to-Consumer Channel Launch | Subscription replenishment captures full margin and first-party consumer data outside consolidated retail. |
| EFSA Health Claims Substantiation | Clinical endpoint investment secures cross-border marketing rights under EU Regulation 1924/2006. |
| Organic Certification Pipeline Investment | USDA verification capacity expansion reduces 12-18 month launch delays for premium SKUs. |
| Compostable Packaging Integration | EU Green Deal compliance creates differentiation in environmentally conscious European supermarket segments. |
Research Methodology
Multiple input streams — regulatory filing analysis, retail audit databases, and procurement cost indices — were reconciled through bottom-up and top-down triangulation. Primary interviews with brand managers, category buyers at retailers, sensory R&D directors, and contract manufacturing executives were cross-validated against secondary sources including FDA nutrition labeling guidance documents, EFSA health claims registers, Nielsen retail measurement data, and USDA organic certification records.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across product format, ingredient certification, distribution channel, and consumer behavioral commitment dimensions. CAGRs were derived from segmented growth rate reconciliation with macroeconomic consumption elasticity assumptions. Forecast inputs incorporated ketogenic diet adoption curves, precision fermentation capacity buildout schedules, and retailer private-label consolidation velocity.
Revisions become necessary when EFSA or FDA sweetener safety assessments shift, stevia harvest volatility exceeds historical bands, or Aldi and Lidl private-label acceleration compresses branded manufacturer shelf presence faster than modeled. Deviation in alternative sweetener cost convergence timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Cereal Bar Market
Snacks
Oat-Based Snacks Market
Snacks
Roasted Snacks Market
Snacks
United States Children's Snack Bar Market
Snacks
North America Potato Chips Market
Snacks
Crackers Market
Snacks
Global Rice Snacks Market
Snacks
UAE Cereal Bar Market
Snacks
Dried Fruit Snacks Market
Snacks
Low Fat Granola Market
Snacks
Australia Snack Bar Market
Snacks
Low Calorie Biscuits Market
Snacks
Grass-Fed Jerkies Market
Snacks
Saudi Arabia French Fries Market
Snacks
Granola Bars Market
Snacks
Latin America Extruded Snack Food Market