
 Super Low Calorie Snacks Market | 2026-2036
Super Low Calorie Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Super Low Calorie Snacks Market Analytics
North American production capacity for super low calorie snacks is rewriting supply chain expectations as co-manufacturers expand clean-label facilities across the United States and Canada. General Mills leverages its cereal-to-snack ingredient synergies to control input costs on high-protein formulations. Nestle S.A. anchors European R&D expertise while competing aggressively in North American retail channels. Mondelez International differentiates through its global procurement scale for natural sweeteners and low-calorie flavorings.
Super low calorie snacks are formulated food products typically containing fewer than 100 calories per serving, achieved through controlled carbohydrate content, sugar alcohol substitution, and air-puffed or dehydrated processing techniques that reduce caloric density without sacrificing portion volume. These products serve consumers managing weight, blood glucose, or macronutrient targets across retail and foodservice channels. Protein bars dominate current shelf space and margin capture due to established consumer willingness to pay for functional satiety claims. Seaweed snacks represent the fastest-growing product type as Asian flavor profiles penetrate Western markets and brands exploit minimal processing narratives. Single-serve packs command premium pricing while resealable bags sustain household penetration and repeat purchase frequency.
The FDA's Nutrition Facts panel mandates and the USDA's organic certification requirements shape formulation choices and label claims across the American market, while Health Canada's front-of-package labeling regulations for high-sugar products create parallel compliance obligations for cross-border suppliers. The EPA's emerging scrutiny of food packaging per- and polyfluoroalkyl substances introduces additional reformulation pressure for brands reliant on conventional barrier films. Stakeholders must monitor how evolving federal and state-level sugar taxation proposals intersect with clean-label consumer expectations to determine portfolio prioritization and geographic manufacturing investments.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars and serving sizes are compelling manufacturers to reformulate with natural sweeteners and high-protein ingredients, compressing R&D timelines and reshaping competitive positioning.
Growth Catalysts
- Millennial and Gen Z Health Consciousness:Corporate wellness programs in the United States are accelerating adoption of portion-controlled snack formats among younger demographics seeking macronutrient control.
- USDA Organic Certification:Clean-label consumer expectations are driving producers toward certified organic ingredient sourcing and transparent supply chain documentation.
- Air-Puffed Processing Technology:Advanced dehydration techniques enable caloric density reduction without sacrificing portion volume, expanding addressable use cases for weight management consumers.
Market Restraints
- Natural Sweetener Cost Volatility:Stevia and monk fruit extract prices fluctuate with agricultural yields in Southeast Asia, squeezing margin structures for mid-tier producers.
- Co-Manufacturer Concentration:Clean-label facility expansion remains concentrated among a handful of United States and Canadian contract manufacturers, creating bottleneck risks.
- Sugar Alcohol Digestive Tolerance:Erythritol and allulose consumption limits restrict formulation flexibility for products targeting mass-market penetration.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:United States households demonstrate willingness to commit to recurring deliveries of personalized low-calorie snack assortments.
- Asian Flavor Profile Penetration:Seaweed snack formats exploiting minimal processing narratives are capturing new consumer segments in Western retail channels.
- State-Level Sugar Taxation Proposals:Emerging fiscal policies in California and New York jurisdictions create preemptive formulation incentives for reduced-sugar portfolios.
Industry Challenges
- Packaging Chemist Talent Scarcity:EPA scrutiny of per- and polyfluoroalkyl substances in barrier films demands specialized expertise that outpaces current workforce supply.
- Cross-Border Label Harmonization:Health Canada's front-of-package high-sugar labeling regulations create parallel compliance burdens for suppliers serving both Canadian and American markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Low Calorie Snacks Market |
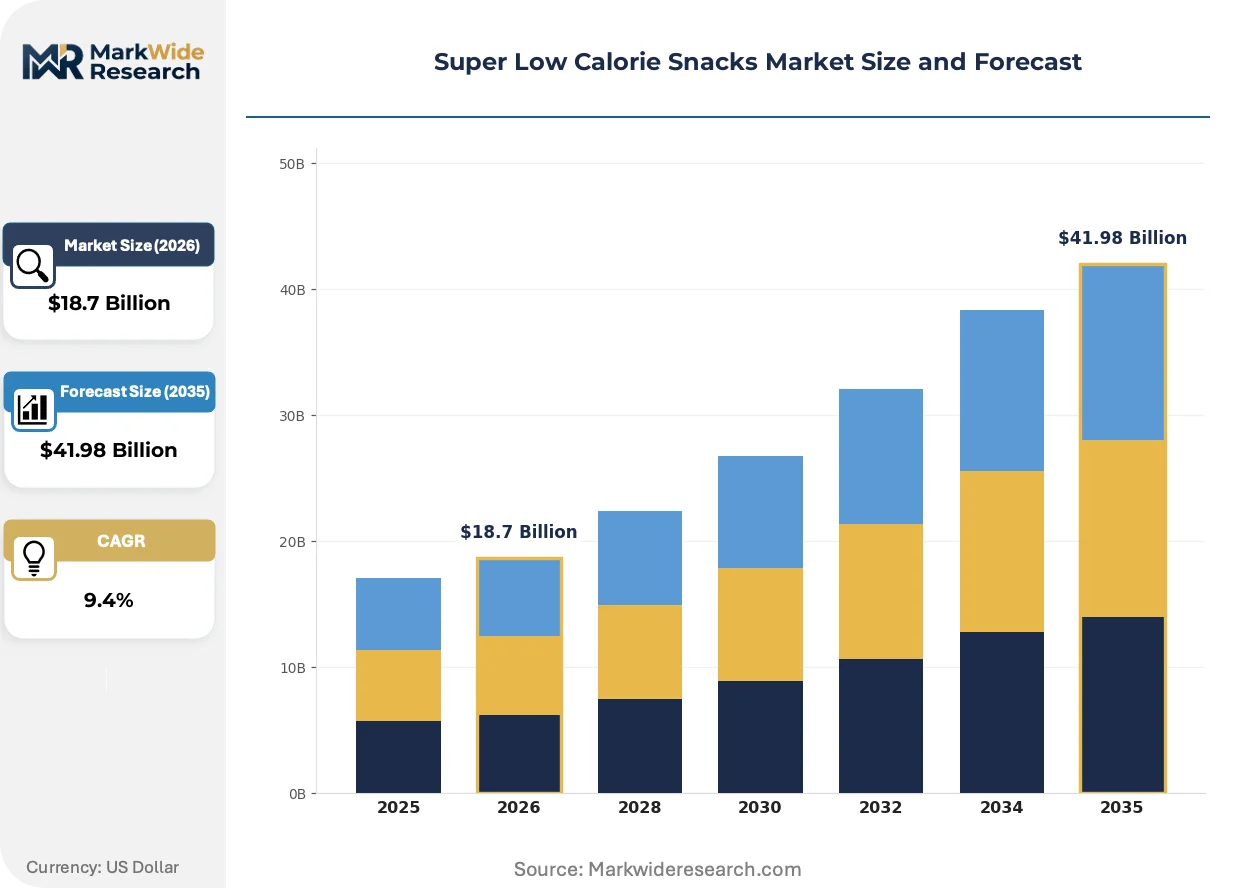
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Rice Cakes, Seaweed Snacks, Veggie Chips Ingredient Type: Natural Sweeteners, High-Protein Ingredients, Fiber, Low-Calorie Flavorings Packaging Type: Single-Serve Packs, Resealable Bags, Bulk Containers, Snack Boxes Distribution Channel: Online Retail, Health Food Stores, Supermarkets, Convenience Stores |
| Companies Covered | General Mills, Inc, Conagra Brands, Inc, Cargill, Incorporated, Nestle S.A., Mondelez International, The Kraft Heinz Company, Archer Daniels Midland Company, Danone, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Low Calorie Snacks Market Evolving Landscape
Reformulation science and distribution model experimentation are converging to redefine how low-calorie snacks reach end consumers and justify price premiums.
Extrusion-based protein texturization is collapsing the cost gap between animal-derived and plant-based satiety claims. Sports nutrition buyers in the United States are adopting these formulations at accelerating velocity. The technology is collapsing legacy protein bar margin structures and enabling private-label parity with established functional brands.
REACH regulations in Europe are tightening scrutiny of food contact materials and novel ingredient safety dossiers. Manufacturers exporting to EU member states must now compile extensive migration testing data for alternative barrier coatings. Snack brands with pan-European ambitions are responding by consolidating formulation platforms to reduce regulatory surface area.
Corporate procurement departments are unbundling after-sales service from product supply, instead negotiating direct relationships with co-manufacturers for custom formulation development. Foodservice distributors in the United States are losing intermediation power as large employers build captive low-calorie snack programs. This behavior is most visible among technology sector employers with centralized wellness budget authority.
Super Low Calorie Snacks Market Segmentation
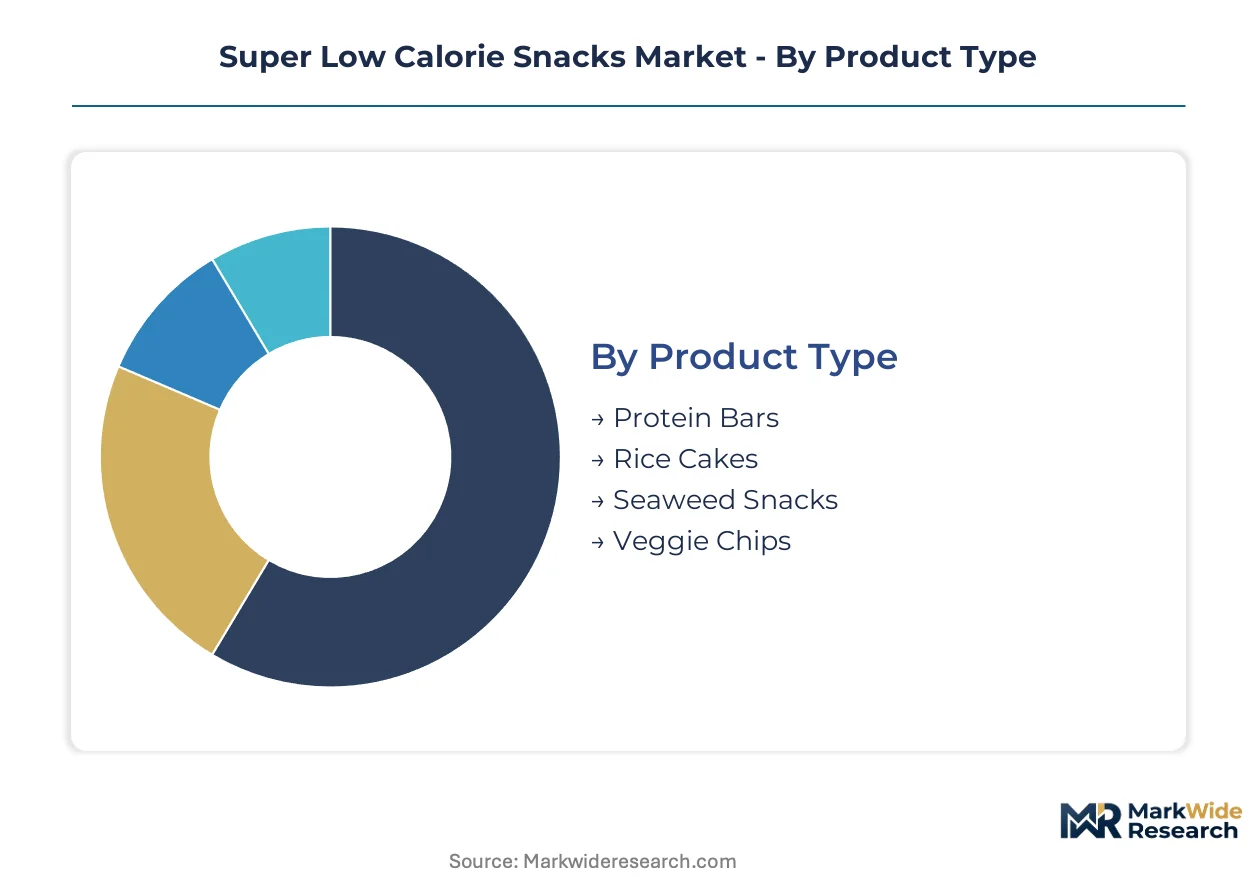
Segmentation in super low calorie snacks reveals how formulation science, packaging engineering, and channel economics intersect to capture distinct consumer willingness-to-pay thresholds. Manufacturers calibrate ingredient costs against portion control expectations to optimize margin capture across divergent usage occasions.
Product Type:
Mature formats dominate shelf space while emerging categories exploit minimal processing narratives to command premium positioning.
- Protein Bars:Dense formulations combining whey or plant protein isolates with sugar alcohol binding systems achieve sub-200 calorie targets while delivering 15-20g protein claims. Corporate wellness procurement in the United States concentrates demand here, though extrusion technology is collapsing legacy margin structures through private-label parity.
- Seaweed Snacks:Thin-sheet roasted or air-dried laminaria species deliver sub-50 calorie servings through minimal oil processing and umami-forward seasoning. Asian flavor profiles penetrating Western retail channels in California and New York metro areas are accelerating adoption among Gen Z consumers seeking authentic ethnic credentials.
- Rice Cakes:Puffed whole grain discs leveraging air-expansion processing to achieve volume without caloric density, positioned as vehicle foods for nut butter or avocado toppings in household pantry rotation.
- Veggie Chips:Dehydrated root vegetable slices marketed as potato chip alternatives, facing formulation challenges around oil absorption rates that threaten clean-label positioning.
Protein bars retain volume leadership; seaweed snacks hold the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates commodity inputs from specialty extracts with supply concentration risks in Southeast Asian agricultural zones.
- Natural Sweeteners:Stevia rebaudiana and monk fruit extracts replace sucrose at 200-400x sweetness intensity, enabling dramatic carbohydrate reduction. FDA added sugar labeling mandates are compressing reformulation timelines for manufacturers serving American retail.
- High-Protein Ingredients:Whey isolates, pea protein concentrates, and emerging fungal fermentation platforms deliver satiety claims that justify 40-60% price premiums over conventional snacks. Sports nutrition buyers in United States metropolitan markets are adopting plant-forward formulations at accelerating velocity.
- Fiber:Soluble corn fiber and chicory root inulin provide bulk and mouthfeel compensation in reduced-calorie matrices, though digestive tolerance limits restrict inclusion rates in mass-market SKUs.
- Low-Calorie Flavorings:Natural and nature-identical volatile compounds synthesized through biotech fermentation or solvent extraction, subject to EPA scrutiny on processing residue profiles.
High-protein ingredients dominate margin capture; natural sweeteners face the most acute supply volatility exposure.
Packaging Type:
Application context determines format selection, with portion control requirements in corporate settings diverging from household pantry economics.
- Single-Serve Packs:Pre-portioned 0.5-1.0 ounce units commanding 25-35% unit price premiums, preferred by workplace wellness coordinators managing per-employee snack budgets in United States technology sector employers.
- Resealable Bags:Multi-serve pouches with zip-lock or adhesive closure systems sustaining repeat purchase frequency through pantry visibility and freshness preservation claims.
- Bulk Containers:Foodservice-scale formats serving hospitality and institutional channels where portion control responsibility shifts to the operator.
- Snack Boxes:Curated assortments in subscription and gift configurations, exploiting direct-to-consumer delivery economics to bypass retail slotting fee structures.
Single-serve packs command the highest unit economics; snack boxes are gaining share fastest through subscription model adoption.
Distribution Channel:
Customer type segmentation separates health-motivated seekers from convenience-driven purchasers with divergent information processing behaviors.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling personalized assortment curation and subscription commitment, capturing United States households willing to prepay for recurring low-calorie snack deliveries.
- Health Food Stores:Specialty retailers with trained staff delivering ingredient education and clean-label verification, anchoring premium price realization for certified organic and non-GMO positioned SKUs.
- Supermarkets:Mass retail channels where private-label expansion is reshaping competitive dynamics through price-architecture pressure on branded incumbents.
- Convenience Stores:Impulse-oriented locations where portion-controlled formats compete against conventional candy and chip sets on immediate gratification metrics.
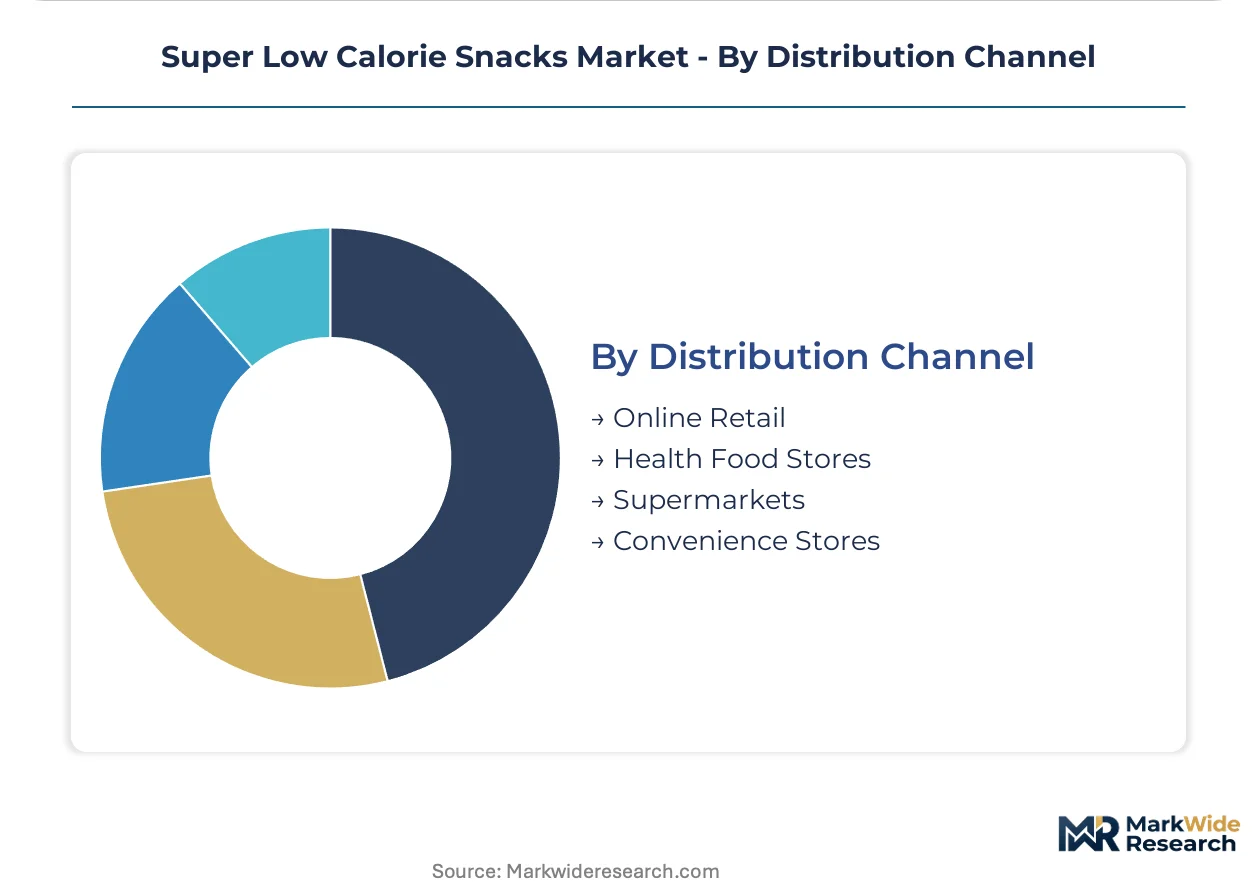
Supermarkets retain volume leadership; online retail holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Co-manufacturer capacity expansion clusters in the United States and Canada, while Asian flavor-profile adoption creates secondary demand nodes in Western Europe and Australia. FDA labeling mandates and Health Canada front-of-package regulations are forcing simultaneous reformulation cycles across North American supply chains.
United States
Corporate wellness procurement from technology sector employers drives single-serve pack demand in California and New York metro corridors. The FDA's updated Nutrition Facts requirements for added sugars are compressing R&D timelines for manufacturers reformulating with stevia and monk fruit extracts. Chicago and Minneapolis host expanding clean-label co-manufacturing facilities serving branded and private-label clients.
Canada
Health-conscious millennials in Toronto and Vancouver accelerate adoption of portion-controlled seaweed snacks and air-puffed formats. Health Canada's front-of-package high-sugar labeling regulations create parallel compliance obligations for cross-border suppliers serving American and Canadian retail channels simultaneously. Montreal-area food technology clusters are developing alternative barrier coatings in response to EPA scrutiny of per- and polyfluoroalkyl substances.
Germany
REACH regulations tighten scrutiny of food contact materials and novel ingredient safety dossiers for manufacturers exporting across EU member states. Munich and Frankfurt metropolitan areas concentrate R&D investment in extrusion-based protein texturization technologies collapsing cost gaps between animal-derived and plant-based formulations. German retailers are unbundling after-sales service from product supply, negotiating direct co-manufacturer relationships.
United Kingdom
London-based direct-to-consumer subscription platforms capture recurring delivery commitments from households seeking personalized low-calorie snack assortments. The UK's departure from EU regulatory alignment creates divergent compliance pathways for brands serving British versus continental European markets. Birmingham and Manchester distribution hubs are consolidating subscription fulfillment infrastructure.
Australia
Sydney and Melbourne consumers demonstrate accelerating willingness to pay for functional satiety claims in protein-forward formats. The Therapeutic Goods Administration's emerging scrutiny of novel food ingredients intersects with clean-label expectations to determine portfolio prioritization for brands entering Australian retail. Queensland agricultural zones supply stevia rebaudiana cultivation with yield volatility exposure to Southeast Asian climate patterns.
Super Low Calorie Snacks Market Competitive Landscape
Multinational food conglomerates and specialized health-nutrition players split the market through divergent route-to-market strategies. Cereal-to-snack ingredient synergies and global procurement scale for natural sweeteners represent the dominant competitive vectors. Two archetypes dominate: diversified packaged food corporations leveraging cross-category R&D infrastructure, and focused functional nutrition specialists exploiting direct-to-consumer subscription economics. Capacity expansion in United States and Canadian clean-label facilities and technology licensing for air-puffed processing are reshaping competitive positioning.
Within the diversified conglomerate tier, General Mills, Nestle S.A., and Mondelez International exemplify archetypal positioning. General Mills occupies a position leveraging cereal-to-snack ingredient synergies for high-protein formulation cost control. Nestle S.A. anchors European R&D expertise while competing aggressively in North American retail channels. Mondelez International sits within the global procurement scale archetype for natural sweeteners and low-calorie flavorings. These three entities represent how cross-category infrastructure and geographic diversification determine competitive posture in reformulation-intensive segments.
| Leading Market Players |
|---|
| General Mills, Inc |
| Conagra Brands, Inc |
| Cargill, Incorporated |
| Nestle S.A. |
| Mondelez International |
| The Kraft Heinz Company |
| Archer Daniels Midland Company |
| Danone |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Intermodal freight corridors connecting Southeast Asian agricultural zones to North American processing hubs transmit stevia and monk fruit extract cost volatility directly into manufacturer margin structures, while FDA labeling mandates compress reformulation timelines and intensify downstream price differentiation between certified organic and conventional product tiers.
Pricing Analysis
FDA Nutrition Facts panel mandates dictate the pricing tier structure across the super low calorie snacks market, separating USDA-certified organic SKUs from conventional formulations through ingredient sourcing transparency requirements. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label certification intensity, with single-serve workplace packs commanding the highest premiums. Cost compression in mid-tier protein bars is intensifying because extrusion technology enables private-label parity with legacy functional brands. Corporate wellness procurement coordinators demonstrate lowest price sensitivity, while convenience store impulse purchasers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for natural sweetener inputs, compelling manufacturers to diversify sourcing toward Vietnamese and Thai agricultural processing zones. Raw material dependencies center on stevia rebaudiana cultivation, monk fruit extract concentration, and air-puffed processing equipment components. Single-source vulnerability concentrates in Canadian clean-label co-manufacturing facilities serving cross-border American and Canadian retail channels. Distribution runs through direct-to-consumer subscription platforms, health food specialty retailers, and mass supermarket channels with diverging margin expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among technology sector corporate wellness procurement departments with centralized budget authority, fragmenting traditional foodservice distributor intermediation and reshaping vendor negotiation leverage across the super low calorie snacks market.
For Market Incumbents: Pre-empt private-label erosion by securing captive stevia and monk fruit supply through backward integration into Southeast Asian agricultural zones, while accelerating air-puffed processing technology licensing to maintain formulation differentiation against extrusion-based protein bar commoditization. For New Entrants and Emerging Players: Establish a beachhead in seaweed snack formats exploiting minimal processing narratives and Asian flavor profile authenticity gaps in California and New York metro corridors, leveraging direct-to-consumer subscription economics to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaged food conglomerates seeking to divest reformulation-intensive snack portfolios with compressed R&D timelines, with long-term viability hinging on clean-label facility capacity expansion velocity. Monitor EPA per- and polyfluoroalkyl substance enforcement patterns as packaging chemistry inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Facility Expansion | Chicago and Minneapolis co-manufacturing clusters capture branded and private-label demand from FDA-mandated reformulation cycles. |
| Natural Sweetener Supply Agreement | Long-term offtake contracts with Vietnamese and Thai agricultural processors hedge against Southeast Asian yield volatility. |
| Direct-to-Consumer Platform Launch | Subscription economics bypass supermarket slotting fees while capturing recurring revenue from wellness-motivated households. |
| Air-Puffed Technology Licensing | Equipment partnerships enable caloric density reduction without sacrificing portion volume claims in weight management segments. |
| Organic Certification Investment | USDA certification unlocks premium pricing in health food retail channels with trained staff delivering ingredient education. |
Research Methodology
The analysis maps protein bar, seaweed snack, rice cake, and veggie chip sub-sectors, each validated through formulation scientists, co-manufacturing facility managers, corporate wellness procurement directors, and health food retail category buyers. Primary interview insights triangulate against FDA filing databases, USDA organic certification registries, Nielsen retail audit data, and customs import records for natural sweetener inputs. Bottom-up segment sizing and top-down macro validation ensure cross-check consistency across the analysis window.
Assumption sets hold FDA labeling enforcement intensity and Health Canada front-of-package regulation implementation fixed, while varying stevia agricultural yield scenarios and corporate wellness program adoption curves. Segmentation dimensions include product type, ingredient category, packaging format, and distribution channel, with CAGRs derived from trend extrapolation against historical volume inflection points. Air-puffed processing technology diffusion rates and extrusion-based protein texturization cost curves inform forward projections.
Sensitivities concentrate around Southeast Asian climate disruption impacts on natural sweetener supply, EPA enforcement escalation on food contact materials, and state-level sugar taxation proposal progression in California and New York jurisdictions. Forecasts embed documented assumptions about regulatory trajectory and consumer clean-label preference stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Snack Bar Market
Snacks
Snack Food Packaging Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
North America Cereal Bar Market
Snacks
North America Energy Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
Spain Energy Bar Market
Snacks
Europe Frozen Snacks Market
Snacks
Allergy-Free Snacks Market
Snacks
Cereal Bars Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
No-Fat Peanut Butter Market
Snacks
Energy Bar Market
Snacks
Savory Snack Products Market
Snacks
Asia Pacific Tortilla Market