
 Medical Image Analysis Software Market | 2026-2036
Medical Image Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Image Analysis Software Market Intelligence
The capability gap between large-scale platform providers and niche algorithm specialists is unwinding the traditional software licensing model. Major imaging hardware vendors like Siemens Healthineers leverage their vast installed base to bundle software solutions. GE Healthcare competes by offering integrated diagnostic workflow platforms across hospital networks. In contrast, specialists such as MIM Software, Inc. differentiate through deep expertise in specific modalities like radiation oncology planning.
Medical image analysis software employs computational algorithms to quantify and visualize features from medical imaging data like MRI, CT, and PET scans. These tools utilize techniques such as segmentation and registration to extract clinically meaningful information, supporting diagnostic decisions and treatment planning. Oncology applications represent the largest segment due to the high volume of imaging required for cancer diagnosis and monitoring. The rapid adoption of cloud-based deployment models is transforming access, enabling more flexible and scalable solutions compared to legacy on-premise systems.
Regulatory oversight for software as a medical device (SaMD) is a critical market factor, governed by bodies like the US FDA and through Europe's Medical Device Regulation (MDR). Approvals from China's NMPA are also essential for market access in that key geography. These frameworks mandate rigorous validation of algorithm performance and cybersecurity. Future success depends on vendors' ability to navigate evolving data privacy laws, such as GDPR, while scaling AI models across international healthcare systems.
Market Dynamics
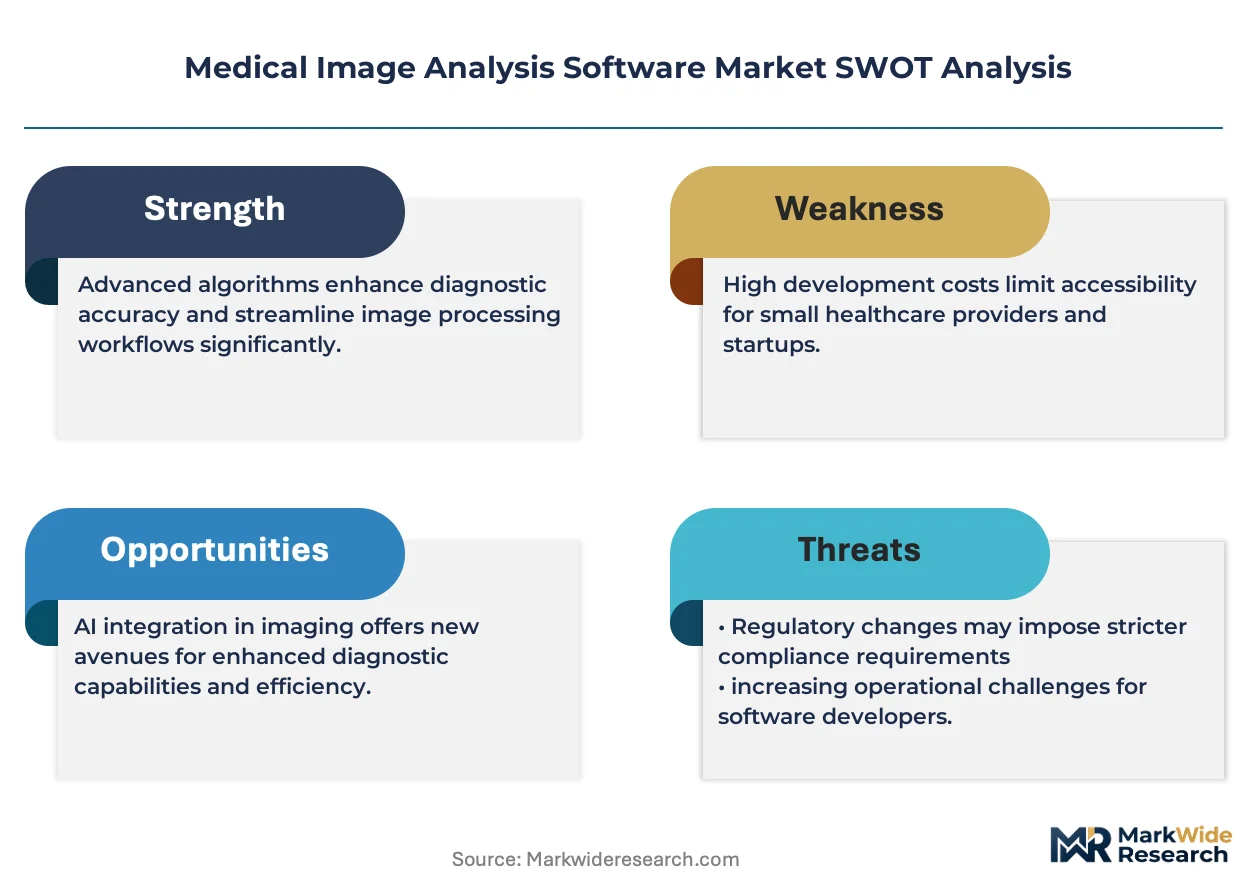
The central tension between integrated platform providers and niche algorithm specialists is reshaping the medical image analysis software market. This dynamic forces a strategic choice between comprehensive workflow integration offered by major hardware vendors and the deep, modality-specific expertise from specialized software firms.
Growth Catalysts
- Precision Medicine Initiatives:National strategies prioritizing precision medicine, particularly in the United States and Germany, drive demand for advanced imaging analytics to tailor patient treatments in oncology and neurology.
- Cloud Deployment Models:The adoption of cloud-based SaaS platforms enables scalable, cost-effective access to powerful analysis tools for a wider range of healthcare providers, bypassing large upfront capital investments.
- Advanced AI Algorithms:The integration of deep learning and machine learning algorithms significantly enhances the accuracy and speed of image segmentation, registration, and quantification, unlocking new diagnostic capabilities.
Market Restraints
- Stringent Regulatory Hurdles:Navigating complex and lengthy approval processes for Software as a Medical Device (SaMD) from bodies like the US FDA and under Europe's MDR framework delays market entry and increases development costs.
- High System Costs:The substantial cost of advanced software licenses, coupled with the need for high-performance computing infrastructure and compatible imaging hardware, limits adoption in budget-constrained healthcare facilities.
- Data Interoperability Issues:A lack of universal standards for medical imaging data and communication protocols creates significant challenges in integrating new software with existing hospital picture archiving and communication systems (PACS) and EHRs.
Strategic Opportunities
- Expansion into Neurology and Cardiology:Vendors have an opportunity to adapt proven oncology analysis techniques for other data-intensive fields like Alzheimer's disease progression monitoring and cardiovascular functional assessment.
- Federated Learning Models:Developing AI models using federated learning allows for training on diverse, multi-institutional datasets without violating patient data privacy regulations like GDPR, improving algorithm robustness and generalizability.
- Untapped Emerging Markets:As healthcare infrastructure modernizes in regions like Southeast Asia and Latin America, there is significant white space for vendors offering cost-effective and scalable imaging analysis solutions.
Industry Challenges
- Talent Scarcity:A persistent shortage of professionals with dual expertise in clinical medicine and data science hinders the development, validation, and clinical implementation of sophisticated AI-based imaging tools.
- Data Annotation Bottlenecks:The operational challenge of acquiring and accurately annotating large, high-quality medical imaging datasets for AI model training remains a significant and costly bottleneck for algorithm developers.
- Cybersecurity Vulnerabilities:The increasing connectivity of medical devices and the use of cloud platforms expose sensitive patient data to greater cybersecurity risks, requiring vendors to implement rigorous security measures mandated by frameworks like HIPAA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Image Analysis Software Market |
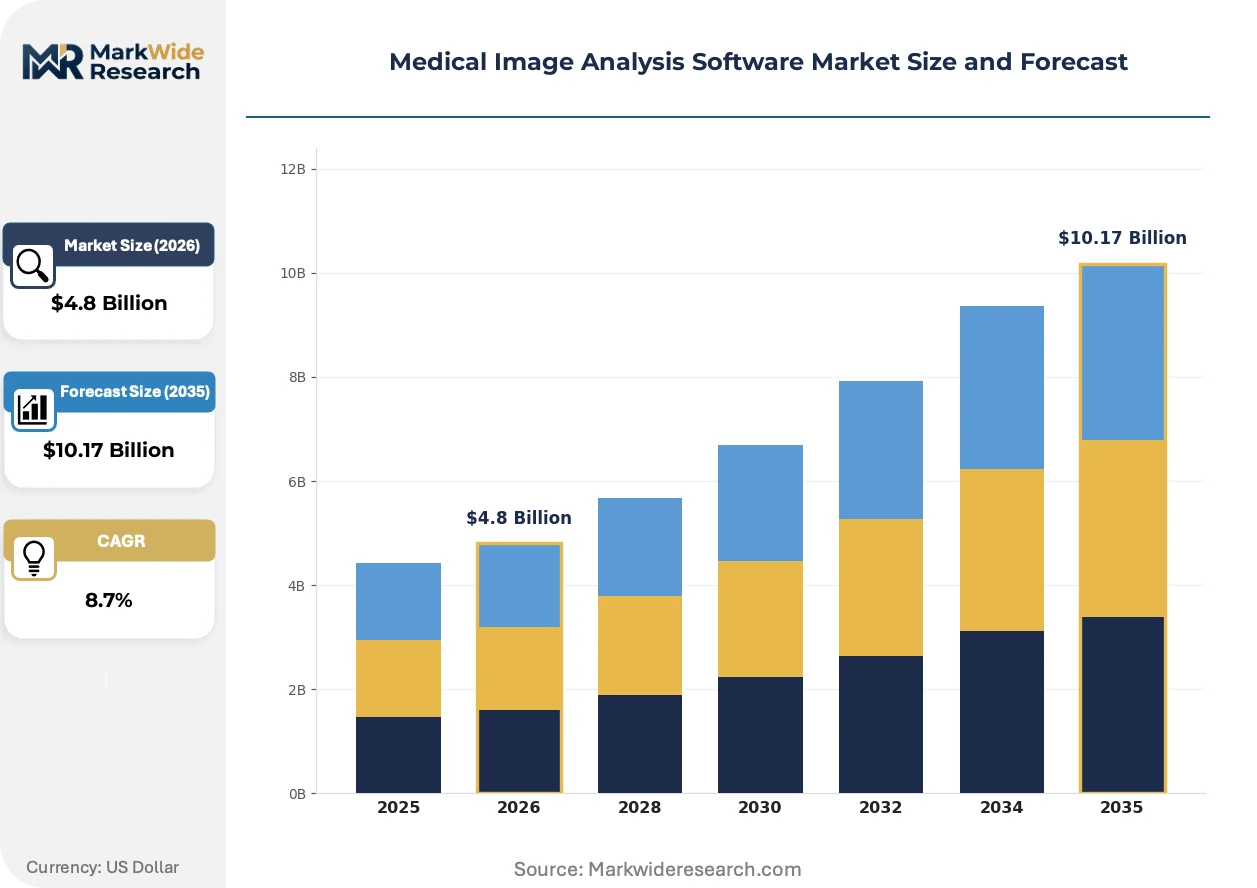
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD Software, Visualization Software, 3D Reconstruction, Archiving Solutions, Workflow Management Application: Oncology, Neurology, Cardiology, Orthopedics, Dermatology End User: Hospitals, Diagnostic Centers, Research Institutes, Imaging Centers, Academic Centers Deployment: On-premise, Cloud-based, Hybrid, SaaS, Private Cloud |
| Companies Covered | Siemens Healthineers, Koninklijke Philips N.V., GE Healthcare, Canon Medical Systems, Agfa-Gevaert Group, Bruker, MIM Software, Inc., Carestream Health, Esaote S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Image Analysis Software Market Strategic Shifts & Innovations
The convergence of advanced computational methods with the clinical need for quantitative, reproducible diagnostics is defining the next generation of medical image analysis tools. This evolution is driven by innovations in AI, evolving regulatory frameworks, and fundamental shifts in how healthcare providers procure and deploy software.
Generative AI models provide the ability to synthesize high-fidelity medical images for data augmentation. Research institutions and specialized AI developers are rapidly adopting these methods to overcome the scarcity of well-annotated training data. This development is fragmenting the competitive landscape by enabling smaller firms to build powerful, specialized algorithms without needing access to massive, proprietary clinical data archives previously controlled by incumbent vendors.
Europe's Medical Device Regulation (MDR) imposes a rigorous, risk-based compliance structure on software. This framework mandates extensive clinical evidence and post-market surveillance for SaMD, increasing the burden of proof for vendors. The diagnostic software segment is most affected, as companies must now invest heavily in transparent, explainable AI (XAI) and robust quality management systems to secure and maintain CE marking for market access.
A clear migration from perpetual licensing to subscription-based and pay-per-use models is altering software acquisition. This trend disrupts traditional, capital-intensive procurement cycles, enabling individual hospital departments to adopt specialized tools via cloud marketplaces without lengthy enterprise-level approvals. This shift is most pronounced in large, multi-site hospital networks in North America and Western Europe seeking greater budgetary flexibility and technological agility.
Medical Image Analysis Software Market Segmentation
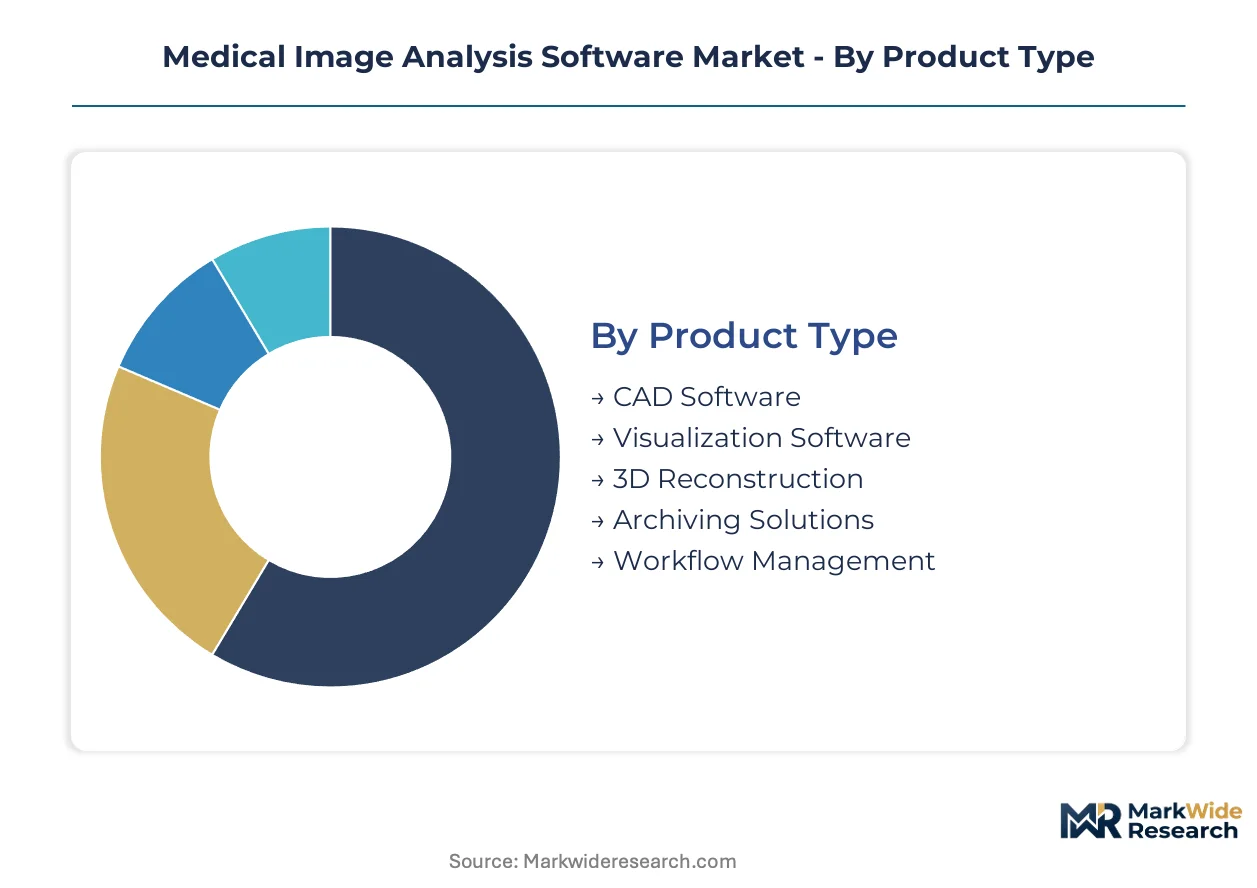
Understanding the segmentation of the medical image analysis software market is crucial for identifying areas of concentrated demand and technological specialization. This granular view reveals how different product types, applications, end-users, and deployment models cater to varied clinical and research needs across global healthcare systems.
Product Type:
The geographic spread of product type adoption often reflects regional healthcare priorities and technological maturity, with advanced solutions seeing higher penetration in developed markets.
- CAD Software:Computer-aided detection software employs algorithms to highlight potential abnormalities in medical images, assisting clinicians in identifying lesions or diseases. Demand for CAD software is particularly high in the United States and Germany, driven by national screening programs and precision oncology initiatives.
- Visualization Software:This software creates 2D and 3D representations of anatomical structures and pathological findings from imaging data, facilitating easier interpretation. Visualization tools form a foundational component across most imaging departments, with widespread adoption in hospitals and diagnostic centers globally.
- 3D Reconstruction:These tools generate comprehensive three-dimensional models from cross-sectional imaging data, enabling detailed anatomical and pathological assessment for surgical planning.
- Archiving Solutions:Software designed for secure, long-term storage and retrieval of medical images, ensuring data integrity and regulatory compliance.
- Workflow Management:Solutions that optimize the entire imaging process from acquisition to reporting, enhancing efficiency and reducing administrative burdens for healthcare providers.
Visualization Software commands the established base. The steepest expansion runs through CAD Software.
Application:
Application segments are distinguished by the specific clinical challenges they address, each requiring tailored computational approaches and data interpretation.
- Oncology:This segment involves the analysis of imaging data for cancer detection, staging, treatment planning, and monitoring, often utilizing advanced quantification and segmentation algorithms. Oncology applications represent the largest segment due to the high volume of imaging required for cancer diagnosis and surveillance.
- Neurology:Software solutions for analyzing brain and spinal cord images to diagnose conditions like Alzheimer's disease, stroke, and multiple sclerosis, often focusing on volumetric analysis and lesion tracking. Precision medicine initiatives in countries like the United States and Japan are driving demand for advanced neurological imaging analytics.
- Cardiology:Tools for assessing heart function, vascular structures, and blood flow from cardiac MRI, CT, and ultrasound images, supporting the diagnosis of cardiovascular diseases.
- Orthopedics:Software used for analyzing bone and joint imaging, aiding in fracture detection, surgical planning, and the assessment of degenerative conditions.
- Dermatology:Emerging applications focus on analyzing skin lesions from dermatoscopic images, supporting the early detection of skin cancer and other dermatological conditions.
Oncology applications dominate current demand. Neurology and Cardiology applications show significant future potential.
End User:
End-user categories reflect distinct operational needs and procurement patterns, influencing software feature sets and integration requirements.
- Hospitals:Large-scale healthcare institutions that require comprehensive, integrated imaging analysis platforms capable of handling high patient volumes across multiple specialties. Hospitals in Germany and the United States frequently seek solutions that integrate seamlessly with existing electronic health records and picture archiving and communication systems.
- Diagnostic Centers:Specialized facilities focused primarily on imaging diagnostics, prioritizing efficiency, rapid turnaround times, and high-quality image interpretation. These centers often adopt cloud-based solutions for scalability and cost-effectiveness.
- Research Institutes:Academic and commercial organizations engaged in medical research, requiring advanced analytical tools for experimental design, data analysis, and algorithm development.
- Imaging Centers:Standalone facilities offering a range of medical imaging services, where software solutions enhance diagnostic accuracy and operational workflow.
- Academic Centers:Educational institutions that use medical image analysis software for teaching, training, and collaborative research projects.
Hospitals represent the primary consumer base for these solutions. Research Institutes are increasingly influencing advanced algorithm development.
Deployment:
Deployment models are shaped by considerations of cost, scalability, data security, and IT infrastructure capabilities within healthcare organizations.
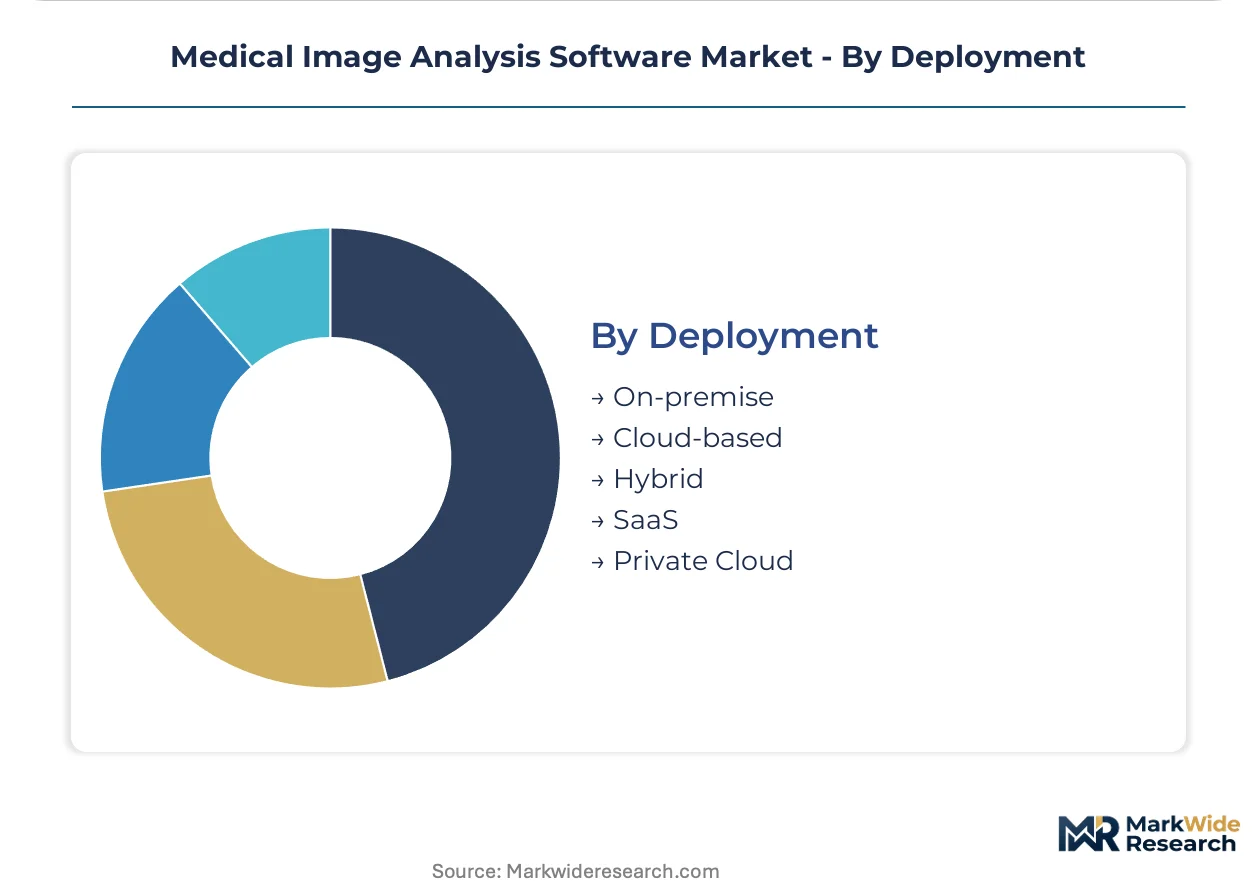
- Cloud-based:Software hosted on remote servers and accessed over the internet, offering flexibility, scalability, and reduced upfront capital expenditure. Cloud-based solutions are gaining traction in North America and Western Europe due to their agility and lower maintenance requirements.
- On-premise:Software installed and run on local servers within the healthcare facility, providing direct control over data and systems. Many larger hospitals in Japan and Germany still prefer on-premise deployments for perceived data security and compliance reasons.
- Hybrid:A combination of on-premise and cloud-based solutions, allowing organizations to leverage the benefits of both models based on specific data and application needs.
- SaaS:Software as a Service, a subscription-based model where software is centrally hosted and licensed on a pay-per-use basis, often delivered via the cloud.
- Private Cloud:Cloud infrastructure dedicated to a single organization, offering enhanced security and control while retaining some scalability benefits of cloud computing.
Traditional on-premise installations still hold significant share. Cloud-based models are rapidly gaining traction due to their flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for medical image analysis software varies significantly across developed and emerging healthcare systems. Countries with established precision medicine initiatives demonstrate lower price sensitivity for advanced solutions, while budget-constrained markets prioritize cost-effective, scalable cloud-based deployments.
United States
National strategies prioritizing precision medicine drive strong demand for advanced imaging analytics in oncology and neurology. The US FDA's rigorous SaMD approval process shapes product development and market entry. Major medical technology clusters in Boston and California foster innovation in AI-driven diagnostic tools.
Germany
Germany's robust healthcare infrastructure and focus on early cancer detection fuel demand for CAD software and advanced visualization tools. Europe's Medical Device Regulation (MDR) mandates extensive clinical evidence for market access, impacting development cycles. Research institutions in cities like Heidelberg and Berlin actively collaborate on AI model validation.
Japan
Precision medicine initiatives in Japan drive adoption of advanced neurological and oncology imaging analytics. Approvals from the Pharmaceuticals and Medical Devices Agency (PMDA) are crucial for market entry, ensuring product quality. Major medical device manufacturers in Tokyo and Osaka integrate software solutions into their hardware offerings.
China
The modernization of healthcare infrastructure and increasing cancer screening programs generate substantial demand for medical image analysis software. Approvals from China's NMPA are essential for market access, requiring local clinical trials. Technology hubs in Shenzhen and Shanghai are developing localized AI solutions for diagnostic imaging.
Medical Image Analysis Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the medical image analysis software market. The market structure exhibits a tiered consolidation, with large platform providers alongside specialized algorithm developers. Strategic partnerships and portfolio diversification represent dominant competitive moves for market participants.
Large-scale platform providers, such as Siemens Healthineers and GE Healthcare, exemplify comprehensive workflow integration across hospital networks. These companies leverage their vast installed bases to bundle software solutions with imaging hardware. Niche algorithm specialists, including MIM Software, Inc., differentiate through deep expertise in specific modalities like radiation oncology planning.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Canon Medical Systems |
| Agfa-Gevaert Group |
| Bruker |
| MIM Software, Inc. |
| Carestream Health |
| Esaote S.p.A. |
Cost & Logistics Intelligence
A 12-month development lead time for advanced AI algorithms in medical image analysis software significantly influences the supply chain structure and vendor pricing power. This extended development cycle necessitates substantial R&D investment, often recovered through premium pricing for innovative solutions and long-term service contracts.
Pricing Analysis
After-sales service contracts and recurring software subscriptions drive significant lifetime value for medical image analysis software vendors. The dominant pricing model is subscription-based SaaS, offering tiered access based on features and user volume. Price differentiation stems from the level of AI algorithm sophistication and the depth of integration with existing hospital systems. Pricing softness runs through basic visualization tools due to increasing commoditization, while advanced CAD software retains premium pricing. Diagnostic centers are more price-sensitive than large research institutes seeking cutting-edge capabilities.
Supply Chain Analysis
The scarcity of dual-expertise talent in clinical medicine and data science represents a critical chokepoint in the medical image analysis software supply chain. Software development concentrates in the United States, Germany, and Japan due to established healthcare ecosystems and research capabilities. Key dependencies include access to large, well-annotated medical imaging datasets and high-performance computing infrastructure. A structural risk is cybersecurity vulnerabilities, demanding continuous investment in robust security protocols. Distribution runs through direct sales channels to large hospital networks and increasingly via cloud marketplaces for smaller diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical image analysis software market is experiencing a cyclical recovery, driven by renewed post-pandemic investment in digital health infrastructure and precision medicine initiatives.
For Market Incumbents:Shield market share by deepening integration with existing PACS and EHR systems, leveraging vast installed hardware bases. Invest heavily in explainable AI (XAI) to build trust and navigate evolving regulatory frameworks like Europe's MDR. Expand cloud-based offerings to counter niche SaaS competitors, focusing on hybrid models for data-sensitive clients. A persistent threat comes from specialized algorithm developers offering point solutions.
For New Entrants and Emerging Players:Accelerated regulatory certification pathways, particularly for specific SaMD applications, present a significant opportunity. Target underpenetrated application areas such as dermatology or specific sub-segments within neurology with highly specialized, cost-effective AI algorithms delivered via cloud SaaS. A focused go-to-market strategy on diagnostic centers or smaller imaging facilities can bypass the lengthy enterprise sales cycles of large hospital networks.
For Investors and Strategic Acquirers:Long-term, this sits as an essential infrastructure play because advanced imaging analytics are becoming fundamental to precision medicine and efficient healthcare delivery. Acquisition targets should include specialized AI algorithm developers with strong intellectual property in specific modalities, or firms possessing regulatory expertise in navigating SaMD approvals. The signal to watch is the widespread adoption of federated learning models, indicating scalable data access without privacy breaches.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate advanced AI algorithms | Enhances diagnostic accuracy and treatment planning, improving clinical outcomes for patients. |
| Expand cloud-based SaaS offerings | Increases accessibility for smaller healthcare providers and reduces upfront capital expenditures. |
| Pursue SaMD regulatory approvals | Ensures market access in key geographies and builds clinical credibility for software solutions. |
| Develop federated learning capabilities | Enables AI model training on diverse datasets while adhering to stringent data privacy regulations. |
| Form strategic partnerships with hardware vendors | Leverages existing installed bases for wider distribution and integrated workflow solutions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to triangulate market dynamics and validate quantitative models. Primary interviews included radiologists, hospital IT managers, software developers, and regulatory affairs specialists. Secondary data sources comprised FDA and MDR guidelines, medical journal databases, and industry association reports, ensuring comprehensive market understanding. This approach combined bottom-up data aggregation with top-down market sizing for robust estimates.
The analytical framework projects market growth across the analysis window by segmenting revenue streams by product type, application, end-user, and deployment model. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and validated against future technology adoption curves. Key forecast inputs included healthcare expenditure trends and the pace of AI algorithm development in medical imaging, influencing market expansion.
Decision-makers should treat outputs as directional under current technological and regulatory landscapes; material deviation would warrant model refresh. Forecasts reflect assumptions regarding continued investment in precision medicine and digital health infrastructure. Practitioners should keep alternative scenarios live as data privacy regulations and AI integration challenges evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Contrast Media Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
North America Nuclear Medicine Market